
 Free-From Food Market | 2026-2036
Free-From Food Market Size, Share, and Industry Trends Forecast 2026-2036
Free-From Food Market Intelligence
Premium clean-label certification is rotating toward the center of competitive strategy in free-from food. General Mills leverages its manufacturing scale to anchor gluten-free portfolio expansion across conventional retail channels. Nestlé competes through R&D intensity in dairy-free alternative formulations. The Hain Celestial Group specializes in organic-certified free-from lines that command shelf positioning in health-focused retail.
Free-from food denotes formulated products excluding specific allergens or ingredients—gluten, dairy, nuts, or eggs—through controlled ingredient sourcing, dedicated production lines, and validated testing protocols below detectable threshold limits. These products serve consumers with diagnosed allergies, intolerances, or elective dietary exclusions requiring verified safety and transparent composition disclosure. Gluten-free product types dominate volume as established retail penetration sustains baseline revenue, while dairy-free alternatives capture accelerated growth from flexitarian dietary shifts. Online retailers within distribution channels represent the fastest-expanding access point, though supermarkets retain the deepest margin pools through private-label expansion and slotting fee structures.
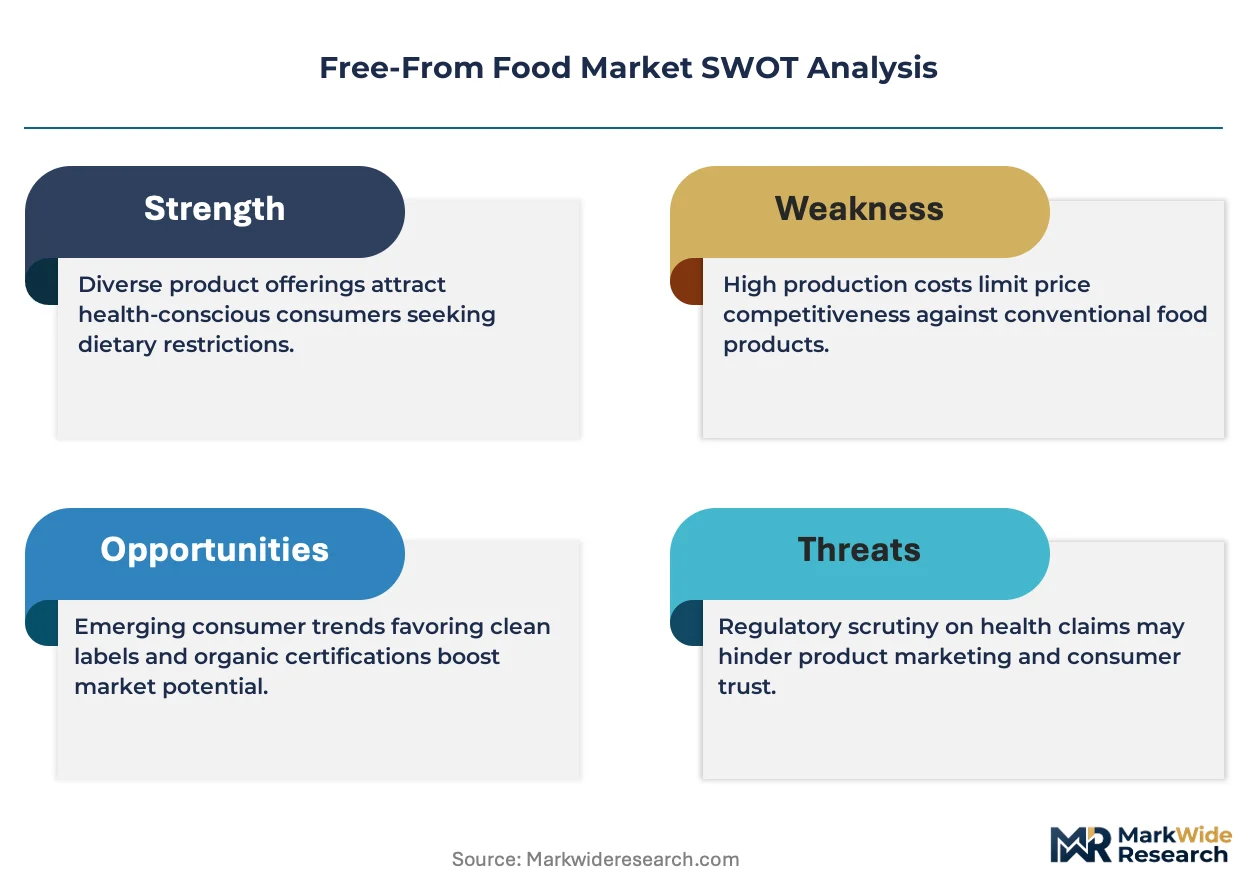
FDA enforcement of Food Allergen Labeling and Consumer Protection Act standards shapes domestic market access requirements, while EFSA scientific opinions on allergen thresholds influence European formulation benchmarks and cross-border trade compliance. USDA organic certification and Non-GMO Project verification add layered compliance costs that filter smaller entrants from premium shelf positions. Stakeholders must monitor evolving regulator positions on precautionary allergen labeling and emerging protein alternatives to anticipate reformulation cycles and certification investments.
Market Dynamics
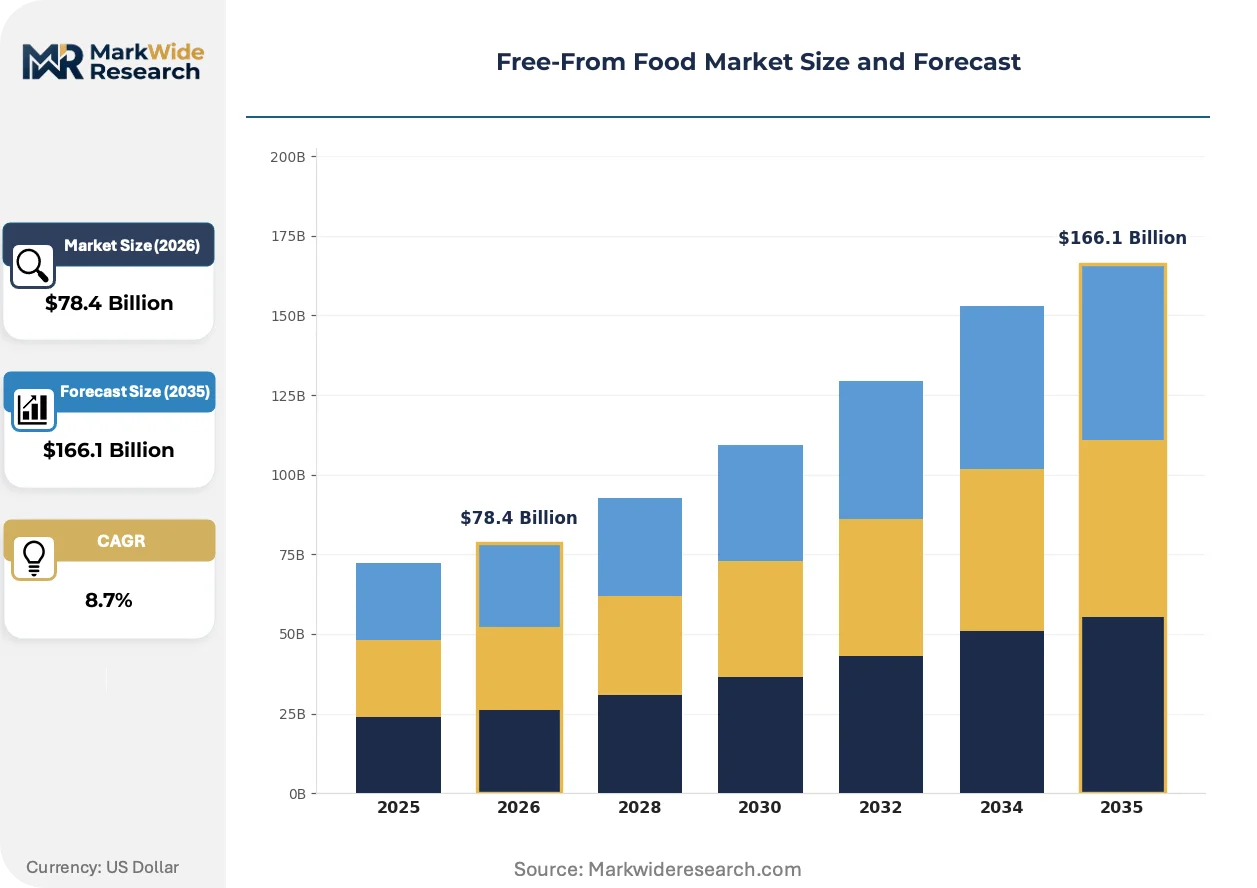
Clean-label certification requirements are compressing formulation timelines as manufacturers race to meet stacked USDA organic, Non-GMO Project, and allergen-free validations simultaneously. This credential layering is reshaping supplier qualification protocols and capital allocation across production networks.
Growth Catalysts
- FDA Allergen Labeling Mandates:Enforcement of Food Allergen Labeling and Consumer Protection Act standards compels reformulation investment, expanding addressable product portfolios for compliant manufacturers.
- Flexitarian Dietary Migration:Dairy-free alternatives capture volume from consumers reducing animal protein intake without diagnosed intolerance, broadening beyond the allergy-core segment.
- United States Retail Density:Conventional supermarket channel expansion of dedicated free-from shelf sets normalizes accessibility beyond specialty health stores.
Market Restraints
- Input Cost Volatility:Certified gluten-free oat and almond protein prices swing with climate-impacted harvest yields, squeezing margin stability for mid-tier producers.
- Production Line Dedication:Segregated allergen-free manufacturing infrastructure requires capital intensity that filters smaller entrants from premium positioning.
- Threshold Validation Complexity:EFSA scientific opinions on detectable allergen limits create cross-border formulation friction between European and North American product specifications.
Strategic Opportunities
- Germany Retail Channel Development:Discounter and drugstore expansion of private-label free-from lines presents white-space positioning for certified organic entrants.
- Precautionary Allergen Labeling Evolution:Anticipated FDA guidance on voluntary advisory statements creates first-mover advantage for brands investing in below-threshold testing protocols.
- Direct-to-Consumer Subscription Models:Online retailers bypass slotting fee structures to capture margin pools unavailable through conventional supermarket negotiation.
Industry Challenges
- Cross-Contamination Control Expertise:Validated cleaning protocol engineering and environmental monitoring talent scarcity constrains production scale-up timelines.
- Stacked Certification Timelines:Simultaneous USDA organic and allergen-free validation processes extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Free-From Food Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $166.1 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free, Dairy-Free, Nut-Free, Egg-Free End User: Health-Conscious Consumers, Allergic Individuals, Dietary Restriction Followers, Vegans Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Shops Certification: Non-GMO, Organic, Vegan, Kosher |
| Companies Covered | General Mills, Conagra Brands, Nestlé, Mondelēz International, The Hain Celestial Group, Danone, The Kraft Heinz Company, Kellogg Company, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Free-From Food Market Strategic Shifts & Innovations
Mass spectrometry and PCR-based allergen detection methods are compressing testing turnaround from batch release to real-time production monitoring. This capability shift is enabling preventive control architectures that reduce hold-and-release inventory carrying costs.
Enzymatic gluten degradation technology is bifurcating the gluten-free segment between native gluten-free grain formulations and processed wheat starch treatments. Celiac disease patient associations and clean-label purists are diverging in adoption preference, with the former prioritizing sensory fidelity and the latter demanding ingredient simplicity. This split is forcing parallel product architecture investments that strain R&D bandwidth.
EFSA precautionary allergen labeling opinions are harmonizing with FDA enforcement discretion to create transatlantic regulatory convergence pressure. Manufacturers serving both markets face consolidated reformulation cycles as threshold science advances. Dairy-free alternative formulations experience the most acute compliance friction given divergent casein and whey detection methodologies.
Health-focused retail procurement is consolidating supplier bases around vertically integrated manufacturers with captive certified ingredient supply. Smaller brands face exclusion from planogram resets as shelf-space productivity metrics tighten. United States natural channel buyers are demanding supplier-funded in-store education programming as a condition of distribution access.
Free-From Food Market Segmentation
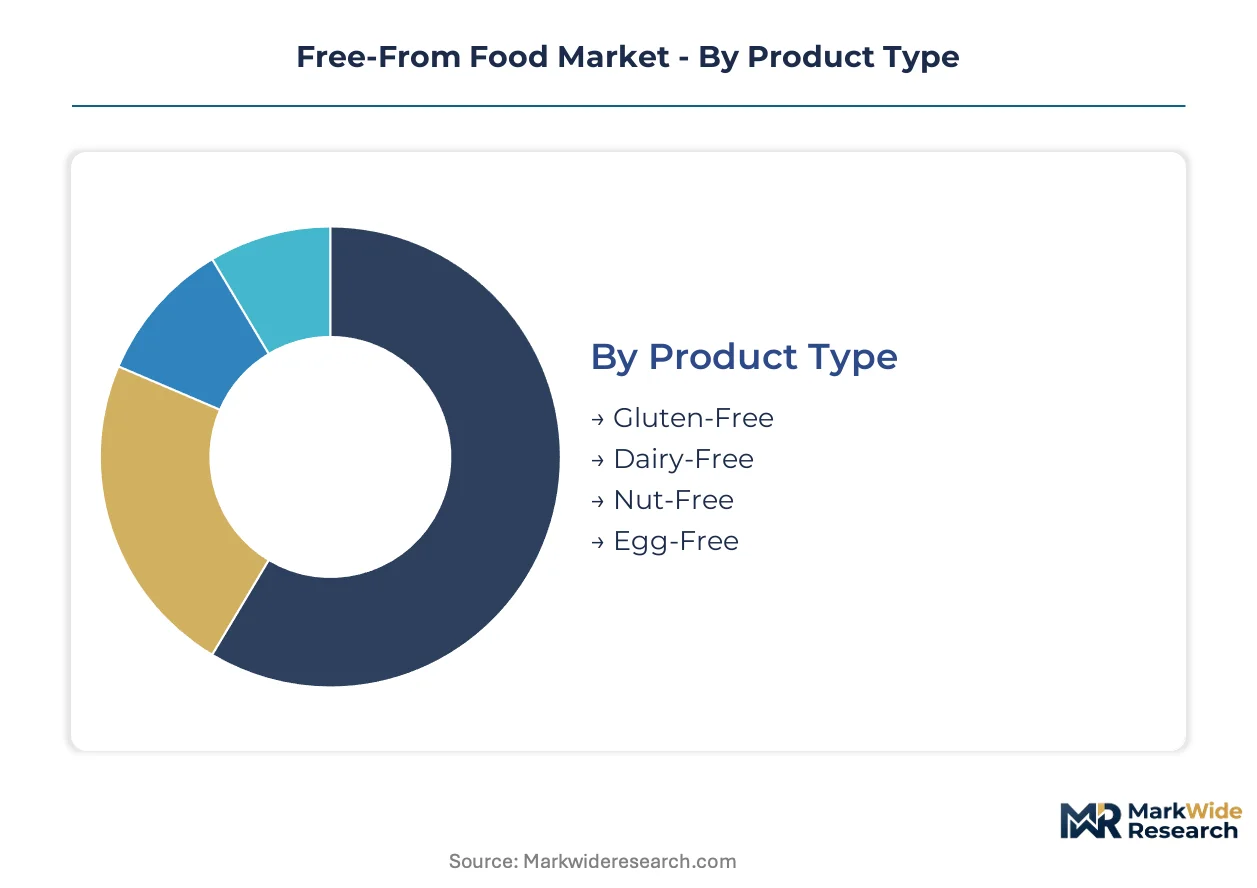
Free-from food manufacturers must navigate four intersecting segmentation dimensions where channel strategy, consumer motivation, and certification stacking determine margin capture. Each dimension reshapes formulation investment, supplier qualification, and shelf-positioning economics differently.
Product Type:
Supermarket buyers source gluten-free and dairy-free through centralized procurement, while health food stores and online retailers concentrate nut-free and egg-free in specialty assortments with higher certification requirements.
- Gluten-Free:Formulated products exclude wheat, barley, and rye through dedicated grain sourcing or enzymatic wheat starch treatment. United States conventional retail channels sustain volume leadership as celiac disease diagnosis rates and elective grain-avoidance diets converge. FDA gluten-free labeling standards mandate below 20 ppm detectable threshold, filtering non-compliant imports from shelf sets.
- Dairy-Free:Plant-based alternatives replace milk, cheese, and butter using oat, almond, soy, or coconut protein bases. Germany and United States flexitarian consumers drive expansion beyond the lactose-intolerance core, with EFSA and FDA diverging on casein detection methodologies creating cross-border formulation friction.
- Nut-Free:Excludes peanuts and tree nuts through segregated supply chains and validated cleaning protocols. School nutrition programs and pediatric allergen management concentrate demand in North American institutional channels.
- Egg-Free:Baked goods and prepared foods substitute binding and leavening functions with plant-based hydrocolloids. Vegan certification alignment broadens addressable consumer base beyond egg allergy patients.
Gluten-free dominates installed base. Dairy-free is where expansion concentrates.
End User:
Cost tier stratification separates premium-positioned allergic individuals from price-sensitive health-conscious mainstream consumers, with margin structure varying accordingly.
- Health-Conscious Consumers:Elective dietary exclusion without diagnosed medical need. United States supermarket private-label penetration captures this volume-driven segment at lower per-unit margin.
- Allergic Individuals:Medically diagnosed IgE-mediated or celiac conditions requiring validated below-threshold safety. Premium pricing tolerance supports stacked organic and Non-GMO Project certification investments.
- Dietary Restriction Followers:Religious, ethical, or wellness-motivated exclusions spanning kosher, halal, or elimination protocols. Specialty shops and online subscription models concentrate this fragmented demand.
- Vegans:Complete animal product avoidance extending beyond dairy and eggs to honey and gelatin. Health-focused retail procurement demands supplier-funded in-store education programming as distribution condition.
Allergic individuals anchor premium tier pricing. Health-conscious consumers drive volume scaling.
Distribution Channel:
Volume concentration in supermarkets contrasts with margin concentration in direct-to-consumer online models, reshaping capital allocation between slotting fees and fulfillment infrastructure.
- Supermarkets:Conventional retail shelf sets with dedicated free-from sections. United States channel density accelerates as Kroger, Albertsons, and regional chains expand private-label lines.
- Health Food Stores:Curated assortments emphasizing organic and local sourcing. Germany's DM and Rossmann drugstore chains are expanding certified free-from private-label positioning.
- Online Retailers:Subscription and direct-to-consumer models bypass slotting fee structures. Fastest-expanding access point capturing margin pools unavailable through conventional negotiation.
- Specialty Shops:Independent retailers with educated staff and localized supplier relationships. Celiac disease patient associations often recommend specific local outlets.
Supermarkets dominate installed base. Online retailers represent the steepest expansion trajectory.
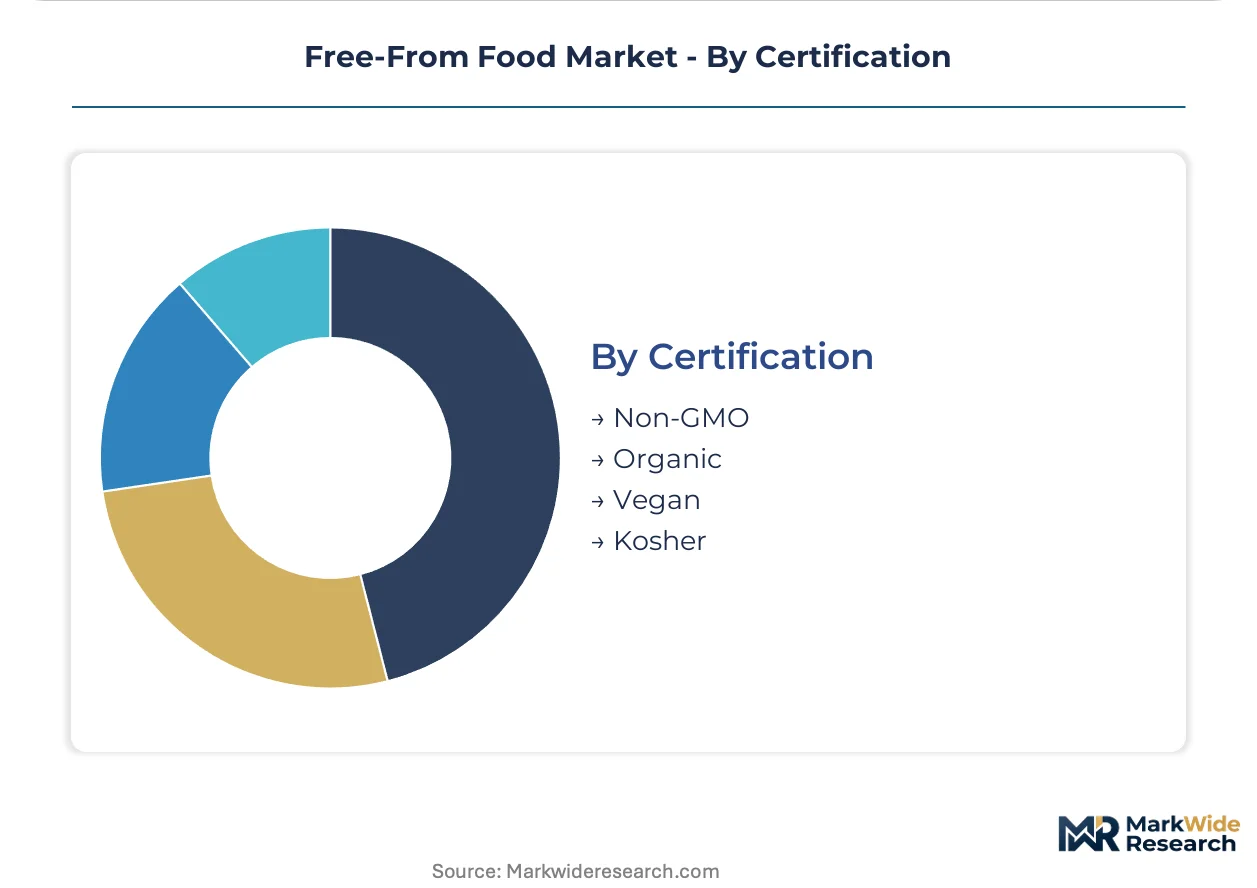
Certification:
Application-driven stacking requirements compress formulation timelines as manufacturers race to meet multiple validations simultaneously.
- Non-GMO:Third-party verification excluding genetically modified ingredients through supply chain audit and testing. Project verification adds 6-12 months to supplier qualification timelines.
- Organic:USDA or equivalent national standards mandating synthetic input prohibition and soil health practices. EU organic regulation equivalence agreements facilitate cross-border trade compliance.
- Vegan:Animal product and testing exclusion verified through supply chain documentation. Leaping Bunny and PETA alternatives create competing standard fragmentation.
- Kosher:Rabbinical supervision of ingredient sourcing and production equipment. Passover-specific certification commands additional production line dedication and cleaning validation.
Organic dominates installed base. Vegan is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-from food trade flows concentrate in import-dependent developed markets where domestic manufacturing cannot match formulation complexity. The United States and Germany absorb premium certified volumes while exporting nations compete on oat, almond, and rice protein commodity supply.
United States
FDA enforcement of Food Allergen Labeling and Consumer Protection Act standards compels domestic reformulation investment. Celiac disease diagnosis rates and flexitarian dietary shifts sustain supermarket channel expansion. Greater Chicago anchors gluten-free manufacturing clusters where dedicated production line infrastructure concentrates.
Germany
DM and Rossmann drugstore chains expand private-label free-from positioning at price points below organic specialty stores. EFSA scientific opinions on allergen thresholds shape formulation benchmarks for cross-border EU trade. Bavaria hosts certified oat processing facilities supplying pan-European gluten-free brands.
United Kingdom
Health-conscious consumers in London and Southeast England drive demand for stacked organic and vegan certifications. Trading relationships with EU suppliers face post-Brexit regulatory friction on precautionary allergen labeling alignment. Midlands manufacturing clusters specialize in nut-free baked goods for school nutrition programs.
Canada
Health Canada allergen labeling requirements parallel FDA standards, facilitating US product line extensions. Prairie provinces supply certified gluten-free oat and pulse proteins to North American formulators. Toronto and Vancouver retail channels concentrate premium-positioned imported European brands.
Australia
FSANZ allergen standards and growing diagnosed food allergy prevalence expand retail shelf sets. New South Wales and Victoria host dedicated allergen-free manufacturing facilities serving domestic and Asia-Pacific export markets. Sydney procurement offices source almond and coconut bases from Southeast Asian suppliers.
Free-From Food Market Key Industry Players
Listed leaders compete with private specialists across certification stacking and channel access dimensions. The market structure tiers between multinational CPG conglomerates with manufacturing scale and mid-cap organic specialists with health-focused retail relationships. Strategic archetypes include scale-driven portfolio diversifiers, organic-certified pure-plays, and private-label contract manufacturers. Dominant competitive moves center on backward integration into certified ingredient supply and supplier-funded in-store education programming as distribution conditions.
Within the scale-driven tier, General Mills and Nestlé exemplify multinational CPG archetypes with manufacturing infrastructure spanning conventional retail channels. The Hain Celestial Group occupies a position among organic-certified specialists targeting health-focused retail procurement. These three anchors represent divergent capital allocation strategies between R&D intensity in alternative formulations and captive supply chain control.
| Leading Market Players |
|---|
| General Mills |
| Conagra Brands |
| Nestlé |
| Mondelēz International |
| The Hain Celestial Group |
| Danone |
| The Kraft Heinz Company |
| Kellogg Company |
| Unilever |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts for certified gluten-free oat and almond protein lock in supply access and price visibility for manufacturers serving United States and Germany retail channels. These arrangements compress working capital requirements while exposing buyers to climate-impacted harvest yield volatility that transfers into margin pressure.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in free-from food procurement. Price differentiation rests on USDA organic certification tier and dedicated production line validation status. Cost compression in the economy tier is intensifying because supermarket private-label expansion squeezes mid-tier branded positioning. Health-conscious mainstream consumers exhibit highest price sensitivity while diagnosed allergic individuals tolerate premium positioning for below-threshold safety assurance.
Supply Chain Analysis
Segregated allergen-free grain processing facilities in Canada, Australia, and the United States create supply chokepoints for certified ingredient sourcing. Raw material dependencies center on gluten-free oat, almond protein, and rice flour inputs. Single-source vulnerability concentrates in Prairie provinces oat milling capacity where dedicated cleaning validation infrastructure limits expansion speed. Distribution runs through supermarket centralized procurement with health food stores and online retailers capturing residual premium volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Free-from food demand cycles track celiac disease diagnosis rate expansion and flexitarian dietary migration waves, positioning the market for recovery as health-conscious consumer spending normalizes post-correction.
For Market Incumbents: Fortify backward integration into certified ingredient supply to offset input cost volatility from climate-impacted harvest yields. Expand dedicated production line infrastructure in Greater Chicago and Bavaria manufacturing clusters to defend against emerging contract manufacturers winning health-focused retail procurement through supplier-funded in-store education programming. For New Entrants and Emerging Players: Differentiate on stacked vegan and organic certification positioning to access white-space shelf sets in Germany's DM and Rossmann drugstore expansion. Target direct-to-consumer subscription models bypassing supermarket slotting fee structures where margin pools concentrate. Lead with below-threshold testing protocol transparency to capture precautionary allergen labeling first-mover advantage. For Investors and Strategic Acquirers: Mid-cap organic-certified specialists with captive supply chain control represent compelling acquisition targets as health-focused retail procurement consolidates supplier bases. Long-term viability hinges on certification stacking capability and vertical integration depth across the five-to-ten year window. Monitor FDA guidance evolution on voluntary advisory statements as inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Ingredient Supply | Captive oat and almond protein sourcing insulates margins from climate-driven harvest volatility. |
| Direct-to-Consumer Subscription Launch | Online retailer models bypass Kroger and Albertsons slotting fee structures to capture premium margin pools. |
| Below-Threshold Testing Protocol Investment | Mass spectrometry and PCR-based detection capabilities enable real-time production monitoring reducing inventory carry costs. |
| Supplier-Funded In-Store Education Programming | Health-focused retail procurement demands educational investment as condition of distribution access in United States natural channels. |
| Precautionary Allergen Labeling Compliance Preparation | Anticipated FDA guidance convergence with EFSA opinions creates transatlantic regulatory positioning advantage. |
Research Approach
Initial hypotheses were tested against primary input from brand managers, category buyers at Kroger and Albertsons, supply planners at certified oat processors, and health-focused retail procurement directors and refined through secondary validation. FDA gluten-free labeling standards, EFSA scientific opinions on allergen thresholds, USDA organic certification databases, and Nielsen retail audit data anchored quantitative baselines. Bottom-up volume builds across product type and certification segments triangulated against top-down market sizing from trade flow analysis.
Variance decomposition across product type, end user motivation, distribution channel, and certification stacking dimensions structured the analytical framework throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation with macroeconomic consumption indicators. Enzymatic gluten degradation technology adoption curves and flexitarian dietary migration rates served as industry-specific demand drivers in the projection model.
Material uncertainties — regulatory threshold revisions, climate-impacted harvest yields, and precautionary allergen labeling guidance evolution — sit outside the modeled envelope. Forecasts reflect documented assumptions on certification timeline compression and retail channel expansion rates. Practitioners should keep alternative scenarios live as EFSA-FDA regulatory convergence and stacked validation cost trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Low Fat Hummus Market
Specialty Foods
GCC Halal Food Market
Specialty Foods
Wet Grain-Free Pet Food Market
Specialty Foods
Liquid Mushroom Market
Specialty Foods
North America Popping Boba/Juice Balls Market
Specialty Foods
Thai Cuisine Market
Specialty Foods
Middle East and Africa Yerba Mate Market
Specialty Foods
Global Freeze-Dried Pet Food Market
Specialty Foods
Military Forces Ready to Eat Meals Market
Specialty Foods
Huoxiangzhengqi Market
Specialty Foods
Global Truffle Market
Specialty Foods
Kosher Food Market
Specialty Foods
Algeria Couscous Market
Specialty Foods
Low Calorie Diet Meal Plan Market
Specialty Foods
Germany Barbeque Grill Market
Specialty Foods
Postbiotic Pet Food Market