
 GNSS Devices Market | 2026-2036
GNSS Devices Market Size, Share, and Industry Trends Forecast 2026-2036
GNSS Devices Market Foresight
Multi-sourcing of GNSS chipsets is consolidating as device manufacturers reduce dependency on single-constellation suppliers. Trimble Inc. leverages its dominance in precision agriculture receivers to sustain premium positioning across North American farming operations. Hexagon AB anchors its portfolio through deep specialization in surveying equipment and geospatial software integration. u-blox competes aggressively in the automotive tier-one supply chain with compact multi-band receiver modules.
Global Navigation Satellite System devices are electronic receivers that process radio signals from orbiting satellite constellations to determine precise geographic position, velocity, and timing; modern units integrate multi-frequency front ends capable of tracking GPS, GLONASS, Galileo, and BeiDou signals simultaneously for sub-meter accuracy in challenging environments. Their primary commercial purpose spans navigation, surveying, asset tracking, and synchronization of critical infrastructure networks. Automotive navigation systems lead product-type revenue pools due to embedded OEM contracts and fleet telematics mandates, while wearable devices represent the fastest-expanding category driven by consumer fitness and outdoor recreation applications. Geospatial mapping applications command the deepest margins among professional use cases, whereas fleet management adoption scales most rapidly across logistics and ride-hailing platforms.
EU radio equipment directives and CE marking requirements under the EU AI Act are tightening electromagnetic compatibility and cybersecurity standards for connected GNSS receivers. The US FAA mandates specific integrity levels for aviation-grade equipment, while China's MIIT enforces domestic BeiDou compatibility in critical infrastructure deployments. Stakeholders must monitor constellation modernization timelines and frequency allocation disputes that could disrupt receiver compatibility and certification pathways.
Market Dynamics
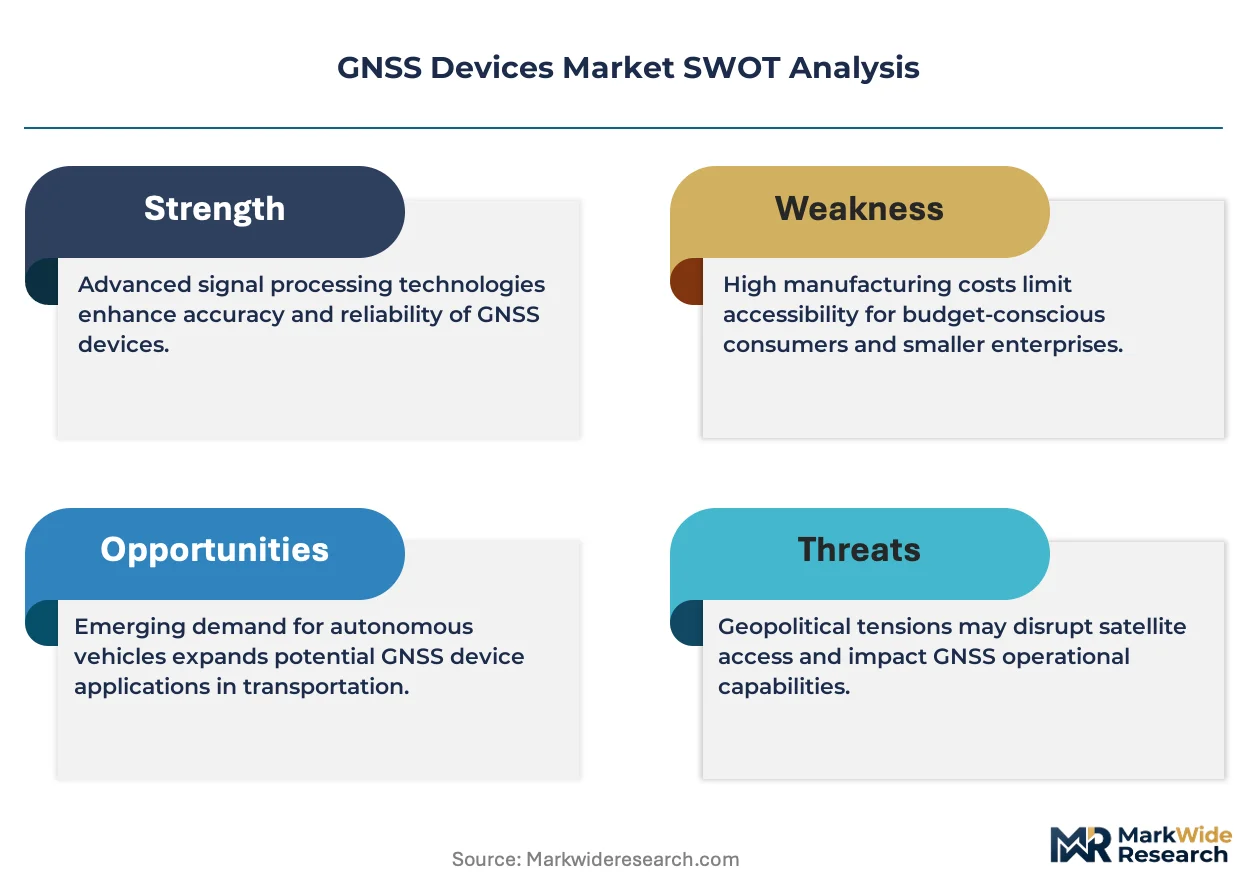
Multi-constellation receiver mandates are compressing certification timelines while fragmenting chipset supply chains, forcing device manufacturers to redesign RF front ends for simultaneous GPS, Galileo, BeiDou, and GLONASS tracking.
Growth Catalysts
- EU Radio Equipment Directive:CE marking requirements for multi-band compatibility are compelling fleet operators across Germany and France to replace single-constellation hardware ahead of compliance deadlines.
- Autonomous vehicle testing corridors:China's MIIT-designated zones around Beijing and Shanghai are generating concentrated demand for centimeter-accuracy receivers in lidar fusion systems.
- Precision agriculture:Large-scale farming operations in Brazil's Mato Grosso and the United States Corn Belt are adopting RTK-guided tractors to reduce input overlap and fuel consumption.
Market Restraints
- Semiconductor supply concentration:Advanced RF front-end fabrication depends on a limited number of foundries in Taiwan and South Korea, creating vulnerability to geopolitical disruption.
- BeiDou compatibility mandates:China's MIIT requires domestic constellation priority in critical infrastructure, forcing foreign suppliers to maintain parallel certification tracks.
- Multi-frequency antenna costs:Ceramic patch and helical antennas capable of L1/L2/L5 reception carry 3-4x material cost premiums versus legacy single-band components.
Strategic Opportunities
- India's PLI scheme for electronics:Production-linked incentives for semiconductor assembly and testing are attracting module manufacturers to establish localized packaging operations.
- Wearable fitness integration:Consumer brands are embedding multi-GNSS chips into smartwatches for backcountry navigation, opening volume markets outside traditional automotive and surveying segments.
- EU AI Act cybersecurity requirements:New connected device standards create first-mover advantage for suppliers offering secure boot and encrypted positioning pipelines.
Industry Challenges
- RF engineering talent scarcity:Design of low-noise amplifiers and interference-resistant correlators requires specialized expertise concentrated among legacy defense contractors.
- Aviation certification timelines:FAA TSO-C145 approval for certified aviation receivers spans 18-24 months, freezing product roadmaps and delaying revenue recognition.
- Legacy fleet integration:Retrofitting existing telematics hardware with multi-constellation capability demands backward-compatible firmware architectures that strain engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GNSS Devices Market |
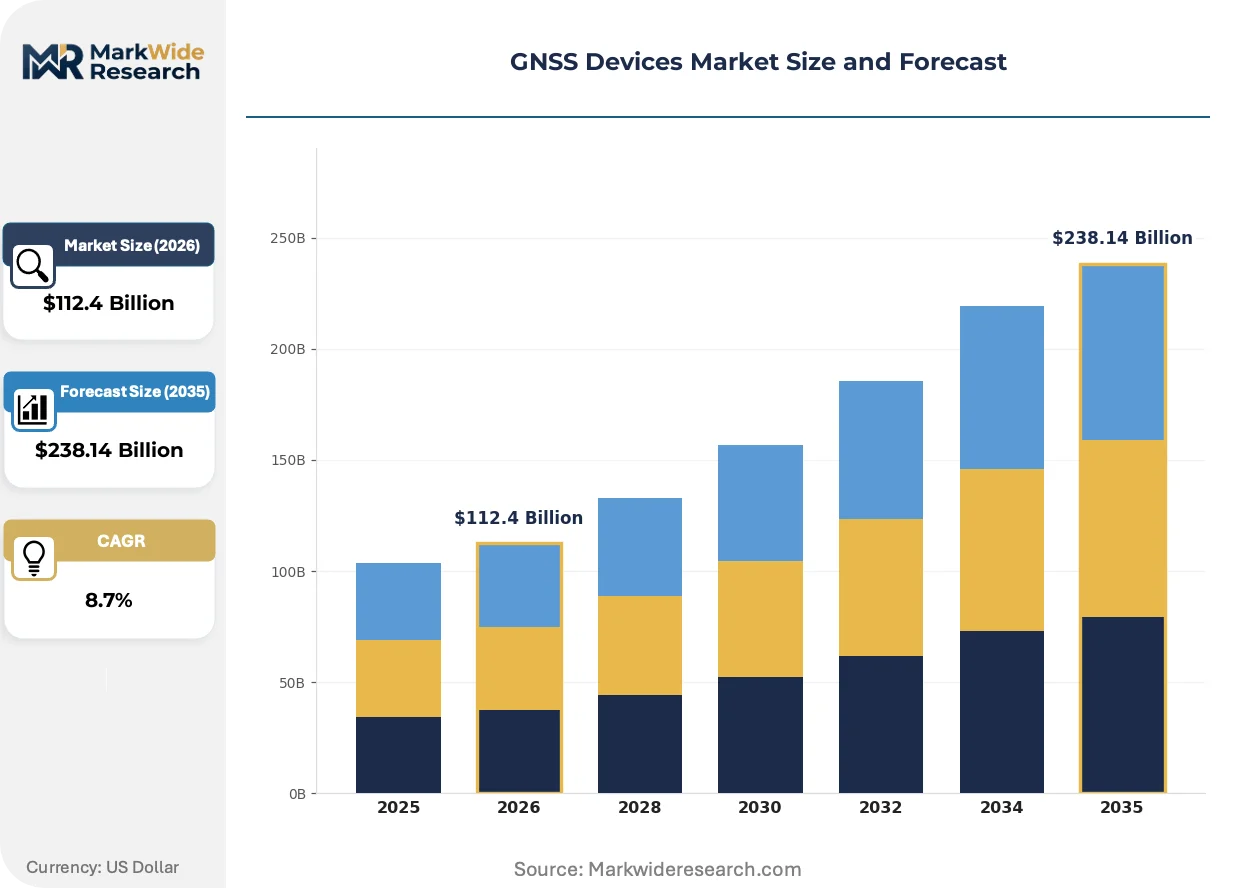
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $238.14 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Receivers, Automotive Navigation, Surveying Equipment, Wearable Devices Application: Geospatial Mapping, Fleet Management, Agriculture, Disaster Recovery End User: Aerospace, Construction, Transportation, Marine Technology: GPS, GLONASS, Galileo, BeiDou |
| Companies Covered | Trimble Inc., Hexagon AB, Topcon Positioning Systems, Inc., Garmin Ltd., u-blox, Qualcomm Inc., Texas Instruments Inc., Broadcom Inc., Furuno Electric Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GNSS Devices Market Shifts & Advancements
Receiver architectures are bifurcating between ultra-low-power consumer modules and high-integrity professional systems, with middleware software layers emerging as the primary differentiation battleground.
Dual-frequency L1/L5 reception is overtaking legacy L1-only designs in automotive OEM specifications. Tier-one suppliers in Germany and Japan are mandating ionospheric correction capability for highway autonomous driving programs. This shift is compressing margins for single-frequency chipset vendors while rewarding those with multi-band RF intellectual property.
REACH restrictions on persistent organic pollutants are forcing antenna substrate material changes across European supply chains. Ceramic manufacturers are reformulating dielectric compositions to eliminate restricted flame retardants without degrading phase-center stability. Surveying equipment producers in Switzerland and Germany face the steepest reformulation costs due to precision requirements.
Fleet operators are unbundling hardware procurement from data service contracts, treating GNSS modules as commodity inputs rather than integrated solutions. Logistics platforms in the United States and Brazil are sourcing receivers separately from telematics software, pressuring bundled pricing models. This disintermediation favors chipset suppliers with direct API documentation and open NMEA output standards.
GNSS Devices Market Segmentation
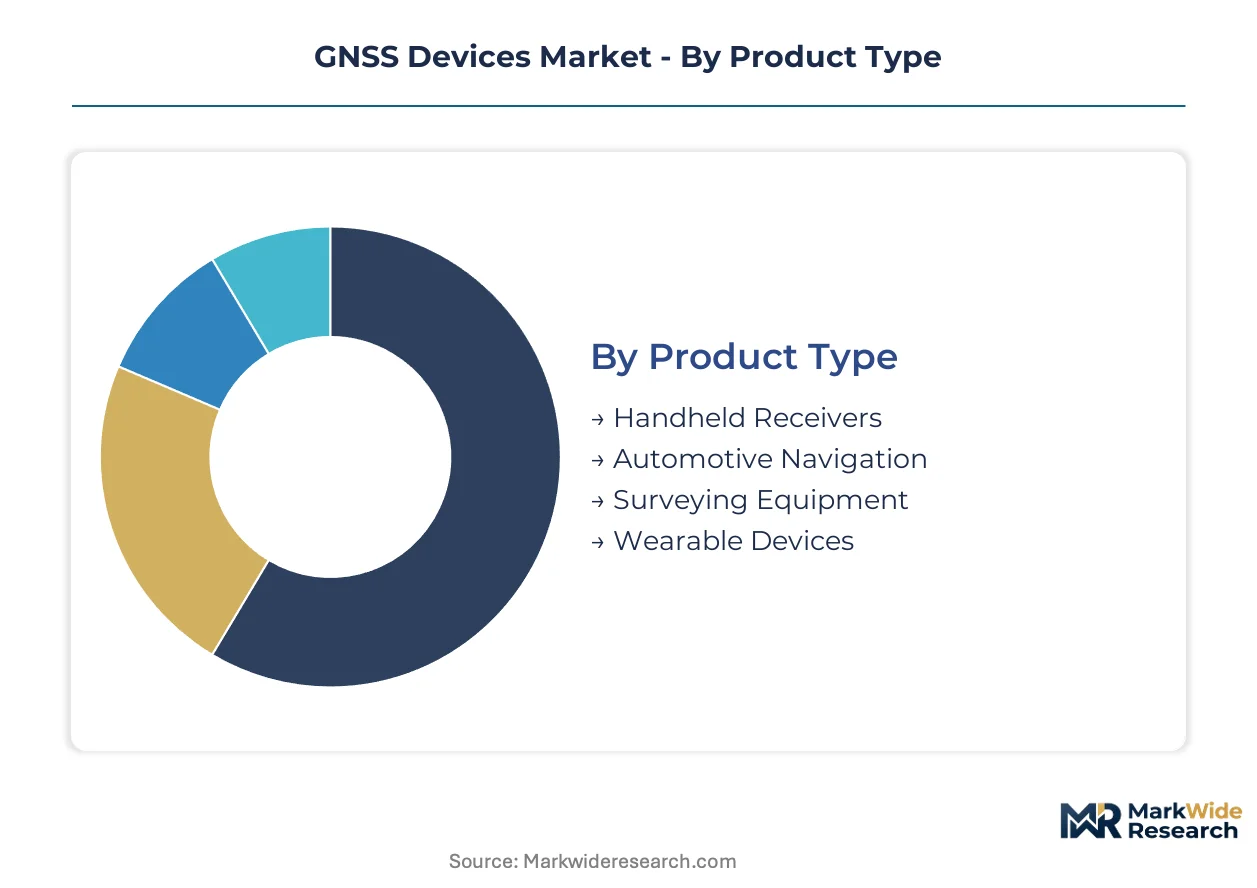
GNSS device architectures vary sharply in RF front-end complexity, certification burden, and software integration requirements. Capital allocation across these segments determines competitive positioning in precision agriculture, autonomous mobility, and professional surveying verticals.
Product Type:
Automotive navigation and surveying equipment demand the heaviest upfront investment in multi-frequency RF design, safety certification, and firmware development.
- Automotive Navigation:Embedded OEM receivers integrate L1/L2/L5 bands with functional safety ISO 26262 compliance. Tier-one contracts with German and Japanese manufacturers concentrate demand for highway autonomous driving programs.
- Surveying Equipment:RTK-capable units require centimeter-accuracy algorithms, ruggedized enclosures, and multi-constellation tracking engines. Swiss and German geomatics firms anchor professional demand for construction staking and cadastral mapping.
- Handheld Receivers:Portable units serve forestry, utility inspection, and recreational navigation with simplified antenna arrays and lower power budgets.
- Wearable Devices:Ultra-compact modules integrate into smartwatches and fitness trackers for backcountry positioning, sacrificing accuracy for battery life and form factor.
Most installed capacity flows through Automotive Navigation. Expansion is steepest in Wearable Devices.
Application:
Margin profiles diverge sharply between professional geospatial workflows and high-volume fleet tracking deployments.
- Fleet Management:Telematics platforms across United States logistics and Brazilian agribusiness drive volume procurement of compact modules with cellular backhaul integration.
- Geospatial Mapping:Aerial LiDAR fusion and mobile mapping systems command premium pricing for sub-decimeter accuracy in urban corridor digitization projects.
- Agriculture:RTK-guided tractors and variable-rate applicators reduce input overlap in Brazil's Mato Grosso and United States Corn Belt operations.
- Disaster Recovery:Rapid-deployment units enable coordinate reference system re-establishment following seismic events and infrastructure failures.
Geospatial Mapping captures the deepest margins. Fleet Management scales most rapidly across emerging logistics networks.
End User:
Certification timelines and procurement authority structures fragment demand across infrastructure verticals.
- Aerospace:FAA TSO-C145 mandates 18-24 month approval cycles for aviation-grade receivers with integrity monitoring and fault detection.
- Transportation:Rail signaling and highway tolling systems require synchronized timing distribution across distributed sensor networks.
- Construction:Machine control systems on excavators and graders demand real-time kinematic corrections for automated blade and bucket positioning.
- Marine:SOLAS-compliant receivers support bridge navigation with differential corrections for port approach and offshore positioning.
Aerospace absorbs the longest development cycles. Construction offers the broadest addressable equipment base.
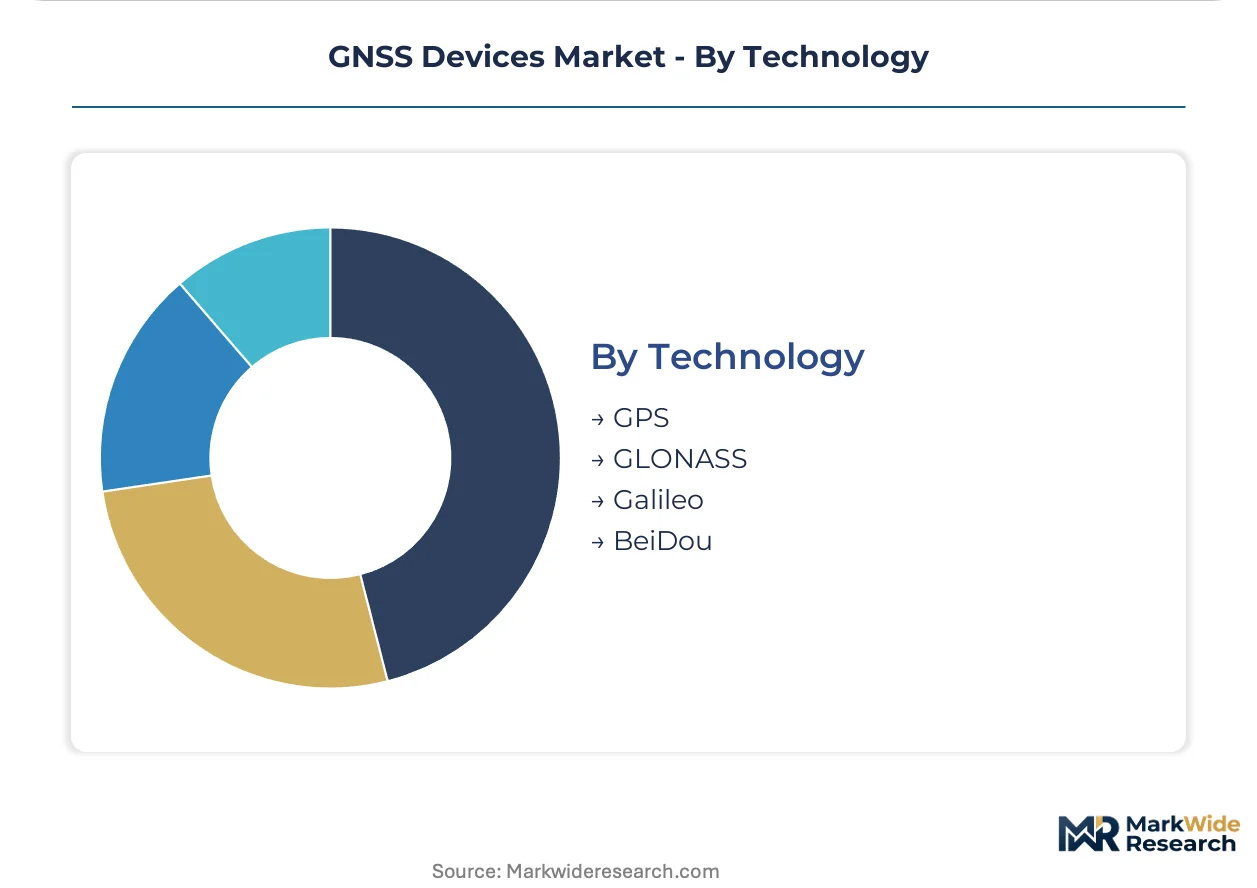
Technology:
Constellation diversification strategies reshape RF intellectual property requirements and certification pathway complexity.
- GPS:Legacy L1 C/A signal remains the baseline compatibility layer across consumer and professional equipment, though modern designs prioritize L5 for ionospheric correction.
- Galileo:EU radio equipment directives mandate Open Service and Commercial Service reception for CE marking eligibility in German and French fleet deployments.
- BeiDou:China's MIIT requires domestic constellation priority in critical infrastructure, forcing parallel certification tracks for foreign suppliers.
- GLONASS:Russian FDMA signals complement CDMA constellations for cold-start sensitivity in urban canyon environments.
GPS maintains the widest installed base. Galileo is gaining regulatory momentum across European procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beijing-Tianjin-Hebei anchors the largest concentration of autonomous vehicle testing infrastructure, with MIIT-designated corridors driving centimeter-accuracy receiver procurement for lidar fusion systems.
United States
Large-scale farming operations across the Corn Belt and logistics platforms in the Midwest are replacing single-constellation telematics hardware. FAA mandates specific integrity levels for aviation-grade equipment through TSO-C145 certification. Silicon Valley and Austin host receiver module design centers serving automotive OEMs.
Germany
Tier-one automotive suppliers mandate dual-frequency L1/L5 reception for highway autonomous driving programs. CE marking requirements under EU radio equipment directives compel fleet operators to upgrade multi-band compatible hardware. Stuttgart and Munich concentrate RF front-end engineering for safety-critical automotive integration.
China
MIIT enforces BeiDou priority in critical infrastructure deployments across designated autonomous vehicle zones. Domestic constellation compatibility mandates force parallel certification tracks for foreign suppliers. Shanghai and Shenzhen module packaging operations serve both automotive and surveying equipment producers.
Brazil
RTK-guided tractors reduce input overlap across Mato Grosso soybean operations. ANVISA-equivalent telecommunications regulators enforce electromagnetic compatibility standards for connected agricultural machinery. São Paulo logistics corridors drive fleet telematics module procurement for agribusiness exporters.
Switzerland
REACH restrictions on persistent organic pollutants force antenna substrate material reformulation for precision surveying equipment. Swissmedic-equivalent certification bodies coordinate with EU CE marking for cross-border equipment sales. Geneva and Zurich anchor geomatics firms specializing in construction staking and cadastral mapping.
GNSS Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in wearable fitness and drone navigation. The vendor base stratifies across defense-heritage RF specialists, automotive tier-one integrated suppliers, and commoditized consumer module producers. Three archetypes dominate: multi-constellation chipset licensors, precision agriculture receiver integrators, and compact module packagers for fleet telematics. Consolidation pressures concentrate around RF intellectual property acquisition and automotive safety certification capacity.
Within the precision agriculture tier, Trimble Inc. and Hexagon AB exemplify integrated solution providers combining hardware with geospatial software layers. u-blox occupies a position among compact module specialists serving automotive supply chains with multi-band receiver architectures. These three anchors represent distinct competitive vectors: field-proven farming automation, surveying equipment specialization, and tier-one automotive integration.
| Leading Market Players |
|---|
| Trimble Inc. |
| Hexagon AB |
| Topcon Positioning Systems, Inc. |
| Garmin Ltd. |
| u-blox |
| Qualcomm Inc. |
| Texas Instruments Inc. |
| Broadcom Inc. |
| Furuno Electric Co., Ltd. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up RF specialists in Taiwan and South Korea anchor advanced foundry capacity, translating wafer-level scarcity into sustained pricing power for multi-frequency front-end components while compressing margins for downstream module assemblers.
Pricing Analysis
Input-cost pass-through from ceramic substrate and RF silicon shortages intensifies margin pressure at the module-packaging tier. Three-tier pricing structure across aviation-certified, automotive-grade, and consumer-level receivers separates buyers by functional safety requirements and constellation-tracking capability. Pricing pressure stems from fleet operators unbundling hardware from data services and sourcing GNSS modules as commodity inputs. Logistics platforms in Brazil and the United States exhibit the highest price sensitivity, whereas aerospace integrators absorbing FAA TSO-C145 certification costs show the least.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan Semiconductor Manufacturing and South Korean foundries for sub-40nm RF mixed-signal fabrication. Advanced GNSS receiver production draws from Taiwanese wafer foundries, South Korean memory suppliers, and Japanese ceramic substrate manufacturers. Raw material dependencies center on high-purity alumina for antenna substrates, gallium arsenide for low-noise amplifiers, and rare-earth elements for precision oscillators. Tariff exposure on Chinese-assembled modules creates supply chain risk as MIIT mandates reshape procurement patterns. Distribution runs through tier-one automotive suppliers in Germany and Japan, direct OEM contracts for precision agriculture, and open-channel electronics distributors for consumer wearables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as autonomous vehicle corridors and precision agriculture operations shift procurement specifications toward centimeter-accuracy, multi-constellation receivers with embedded functional safety.
For Market Incumbents: Lock in multi-constellation RF intellectual property through targeted acquisition of defense-heritage correlator design teams. Secure captive supply of ceramic patch antennas by backward integration into Japanese substrate manufacturers or long-term offtake agreements. Fortify against emerging compact-module specialists by accelerating FAA TSO-C145 certification pipelines for aviation-grade product lines. For New Entrants and Emerging Players: Capture wearable fitness integration opportunities by embedding ultra-low-power multi-GNSS chips into smartwatch reference designs for backcountry navigation brands. Target India's PLI scheme for semiconductor assembly and testing to establish localized packaging operations serving domestic automotive and surveying equipment producers. Lead with open API documentation and encrypted positioning pipelines to differentiate against bundled legacy solutions. For Investors and Strategic Acquirers: Valuations sit cheapest among commoditized consumer module producers facing disintermediation from fleet operator unbundling trends. Long-term viability favors suppliers with automotive safety certification capacity and multi-constellation RF patent estates. Monitor constellation modernization timelines and frequency allocation disputes as the primary signal for receiver compatibility disruption and certification pathway revision.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Constellation RF IP Acquisition | Defense-heritage correlator teams in Israel and the United States anchor next-generation interference-resistant designs. |
| Automotive Safety Certification Investment | FAA TSO-C145 and ISO 26262 compliance unlock tier-one contracts with German and Japanese OEMs. |
| India PLI Localization | Production-linked incentives for semiconductor assembly attract module packaging operations serving domestic surveying demand. |
| Encrypted Positioning Pipeline Development | EU AI Act cybersecurity requirements create first-mover advantage for secure boot and encrypted NMEA output standards. |
| Ceramic Substrate Backward Integration | Japanese alumina suppliers face REACH reformulation costs that favor captive supply arrangements with Swiss antenna manufacturers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with RF front-end engineering directors, tier-one automotive procurement managers, precision agriculture fleet operators, and geomatics firm technical leads with secondary validation. Primary fieldwork drew from semiconductor foundry supply planners, European telematics platform executives, and Indian electronics manufacturing service providers. Secondary sources encompassed FAA TSO certification databases, EU radio equipment directive filings, MIIT autonomous vehicle corridor designations, and customs records for GNSS module trade flows. Bottom-up unit shipment modeling and top-down value aggregation triangulated across these inputs.
Historical reference periods spanning constellation modernization cycles and regulatory compliance deadlines anchored the forecast window to observable adoption patterns. Segmentation dimensions modeled include product architecture, application workflow, end-user certification burden, and constellation-tracking technology. CAGRs derived from fitted growth curves calibrated to replacement cycle timing for single-constellation hardware and penetration rates for RTK-guided agricultural equipment. Industry-specific forecast inputs incorporated MIIT-designated autonomous vehicle testing corridor expansion timelines and EU CE marking enforcement schedules for multi-band compatibility.
Constellation frequency allocation disputes, geopolitical disruption of Taiwan and South Korean foundry operations, and unanticipated delays in aviation certification timelines are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about regulatory compliance deadlines and replacement cycle elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Photoelectric Sensor Market
Sensors and Controls
Glucose Sensor Market
Sensors and Controls
Global Fluid Management and Visualization Systems Market
Sensors and Controls
Digital Barometer Market
Sensors and Controls
Vacuum Pressure Sensors Market
Sensors and Controls
Piezoelectric Materials Market
Sensors and Controls
DCT Mechatronic Control Unit Market
Sensors and Controls
IoT Sensor Market
Sensors and Controls
Environmental Sensing and Monitoring Technologies Market
Sensors and Controls
United States Gas Sensors Market
Sensors and Controls
Asia-Pacific Water Detection Sensors Market
Sensors and Controls
Smartphone Biometric Sensors Market
Sensors and Controls
Factory Automation Sensor Market
Sensors and Controls
Oxygen Sensor Market
Sensors and Controls
Smart Hydrophone Market
Sensors and Controls
Gesture Control Market