
 Environmental Sensing and Monitoring Technologies Market | 2026-2036
Environmental Sensing and Monitoring Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Environmental Sensing and Monitoring Technologies Market Analysis
Silicon photonics is decoupling environmental sensor performance from legacy electrochemical cost structures. Danaher Corporation leverages life-science instrumentation expertise to anchor premium water-quality segments. Bosch Sensortec GmbH dominates compact MEMS gas-sensing modules for consumer and industrial IoT endpoints. Sensirion AG specializes in calibrated multi-gas sensing packages that compete on drift stability rather than price alone.
Environmental sensing and monitoring technologies encompass instrument systems that detect, quantify, and transmit data on physical, chemical, and biological parameters across air, water, and soil matrices, typically operating at detection thresholds from parts-per-billion to ambient concentration ranges with sampling frequencies from continuous to campaign-based deployments. Their primary commercial purpose is to enable regulatory compliance verification, operational risk management, and resource optimization for industrial, municipal, and agricultural clients. Air quality monitors and water quality sensors together occupy the deepest margin pools, while IoT Solutions within the technology dimension represents the fastest-expanding deployment mode as edge-computing architectures reduce backhaul costs. Agricultural Monitoring application demand is accelerating fastest where precision-irrigation subsidies intersect with soil-moisture sensor commoditization.
EPA National Ambient Air Quality Standards enforcement and EU Green Deal binding emissions targets together shape product certification requirements and procurement specifications across OECD markets. FDA and EMA frameworks for environmental monitoring in pharmaceutical manufacturing further tighten validation protocols for particulate and microbial detection systems. Stakeholders must monitor how emerging PFAS maximum contaminant level rules in the United States and REACH substance restrictions in Europe redirect R&D spending toward novel chemosensor and mass-spectrometry detection modalities.
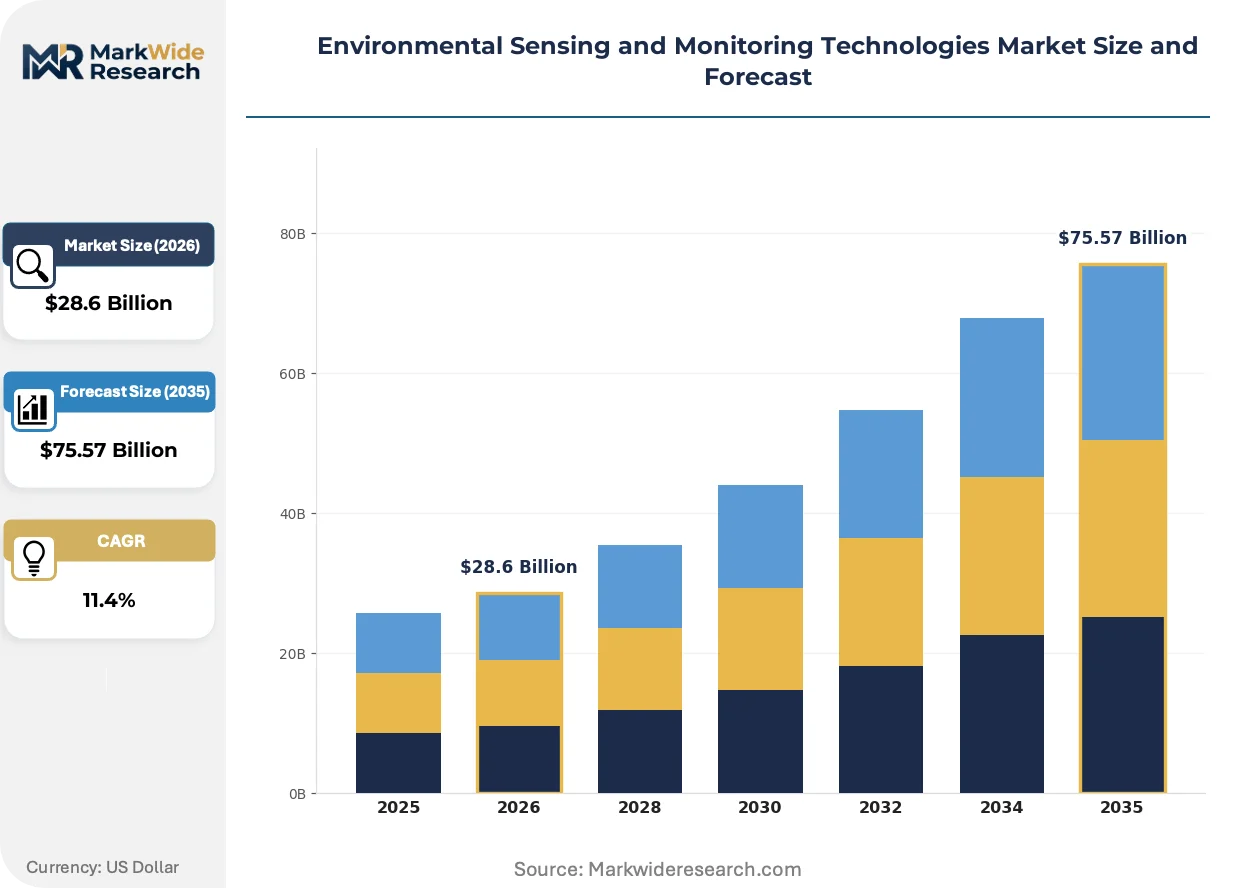
Market Dynamics
Silicon photonics integration is decoupling sensor performance from legacy electrochemical cost structures, enabling MEMS foundries to compress unit economics for distributed networks while EPA and EU Green Deal mandates accelerate procurement velocity.
Growth Catalysts
- EPA discharge mandates:Water utilities across the United States face tightening National Pollutant Discharge Elimination System requirements, forcing sensor deployments at treatment outfalls.
- EU Green Deal binding targets:Industrial clusters in Germany confront compliance deadlines that redirect capital toward continuous emissions monitoring systems.
- Precision-irrigation subsidies:Agricultural districts in California and Spain deploy soil-moisture sensor arrays where commoditized hardware intersects with drought-response funding.
Market Restraints
- MEMS fabrication concentration:Advanced foundry capacity for environmental-grade sensors concentrates in Taiwan and South Korea, exposing procurement timelines to geopolitical friction.
- Calibration gas supply volatility:Specialty reference gas mixtures for sensor validation face input cost swings tied to rare gas extraction rates.
- Electrochemical drift limitations:Legacy dissolved-oxygen and pH sensors require frequent recalibration cycles that inflate total cost of ownership in remote deployments.
Strategic Opportunities
- India air-quality networks:National Clean Air Programme mandates in Delhi, Mumbai, and Bangalore drive demand for low-cost particulate monitors with cellular backhaul.
- Silicon photonics-LiDAR convergence:Atmospheric sensing platforms integrate chip-scale spectrometers with optical ranging for precision agriculture and emissions verification.
- REACH substance restrictions:Novel chemosensor R&D redirects toward PFAS and heavy-metal detection modalities as substance bans expand candidate lists.
Industry Challenges
- Multi-physics simulation talent scarcity:Sensor design teams lack expertise coupling fluid dynamics, thermal, and electromagnetic domains in single-package optimization.
- FDA validation timelines:Pharmaceutical environmental monitoring systems face extended 21 CFR Part 11 compliance certification cycles that delay revenue recognition.
- Legacy SCADA integration friction:New IoT sensor architectures encounter protocol mismatches with decades-old municipal control systems requiring gateway middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Environmental Sensing and Monitoring Technologies Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Quality Monitors, Water Quality Sensors, Soil Moisture Sensors, Remote Sensing Devices Technology: Optical Sensors, Chemical Sensors, Acoustic Sensors, IoT Solutions Application: Agricultural Monitoring, Urban Air Quality, Industrial Emissions, Disaster Management End User: Government Agencies, Environmental Consultants, Research Institutions, Agricultural Producers |
| Companies Covered | Honeywell International Inc., Danaher Corporation, Thermo Fisher Scientific Inc., Agilent Technologies Inc., PerkinElmer, Teledyne Technologies Incorporated, Siemens AG, Bosch Sensortec GmbH, Sensirion AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Environmental Sensing and Monitoring Technologies Market Emerging Trajectories
Edge-computing architectures are compressing backhaul costs and enabling real-time anomaly detection at the sensing node, rewriting deployment economics for distributed environmental networks.
Photonic integrated circuits are rewriting the cost-performance tradeoff for gas and particulate detection. Municipal air-quality authorities in the Netherlands and South Korea adopt chip-scale spectrometers for urban monitoring grids. The technology compresses calibration overhead while expanding analyte coverage beyond electrochemical limits.
REACH substance restrictions and emerging PFAS maximum contaminant level rules in the United States redirect R&D spending toward novel detection modalities. Industrial laboratories face expanded analytical requirements for per- and polyfluoroalkyl substances in wastewater and soil matrices. Mass-spectrometry and advanced chemosensor suppliers in Germany and Massachusetts scale production to meet compliance-driven procurement.
Sensor-as-a-service contracting is displacing capital purchase models in municipal water utilities. Dutch and Australian utilities now procure continuous water-quality data streams rather than owning hardware, transferring calibration and maintenance liability to instrumentation vendors. The shift concentrates vendor risk while accelerating technology refresh cycles.
Environmental Sensing and Monitoring Technologies Market Segmentation
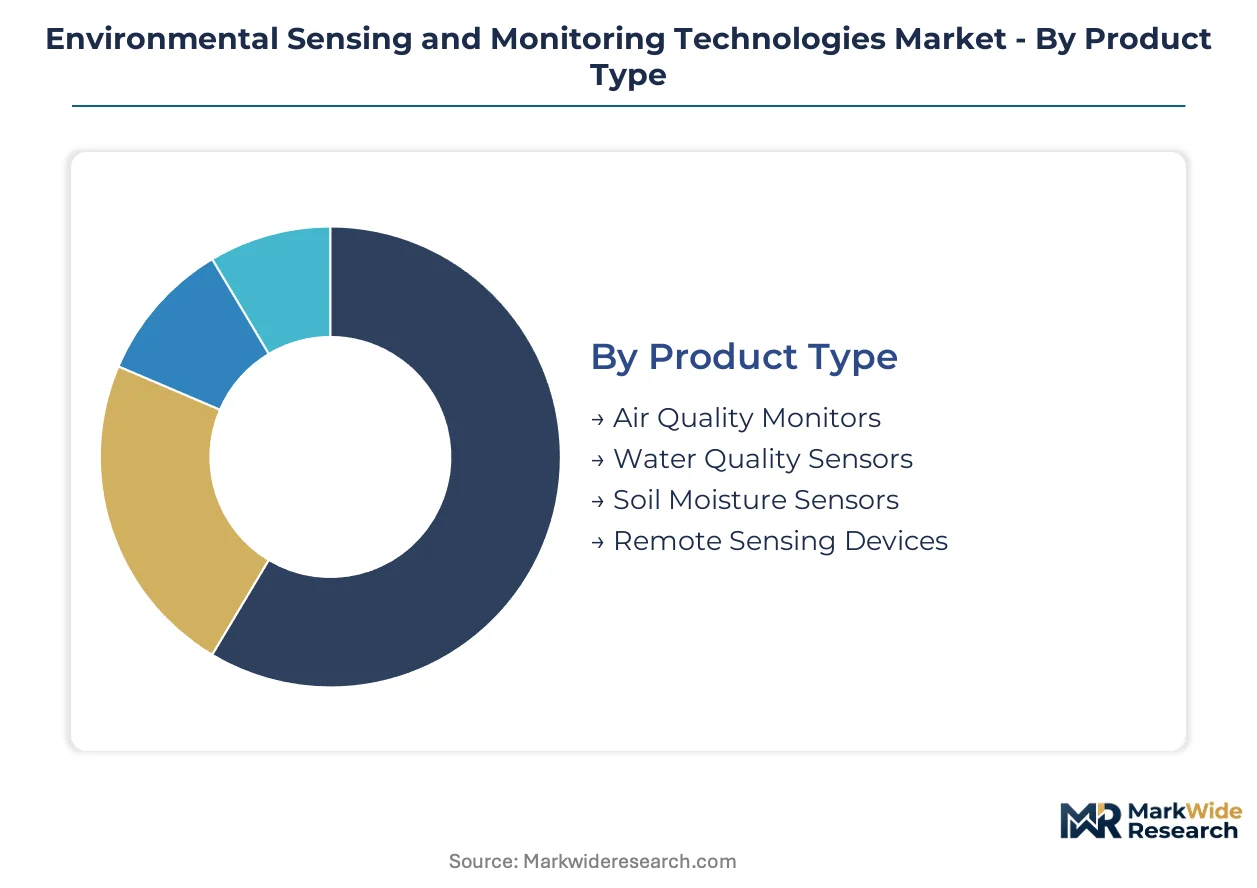
Segmentation in environmental sensing reveals how procurement specifications diverge across regulatory regimes and operational environments. Each dimension—product, technology, application, and end user—carries distinct margin structures and certification requirements that reshape competitive positioning.
Product Type:
Supply concentration for finished sensors clusters around MEMS foundries in Taiwan and South Korea, with final assembly gravitating toward Germany and Massachusetts for high-specification units.
- Air Quality Monitors:These systems integrate particulate matter, NOx, SO2, and ozone detection modules with cellular or LoRaWAN backhaul. Demand concentrates in Delhi, Mumbai, and Beijing where national clean air mandates drive municipal procurement of low-cost optical particle counters.
- Water Quality Sensors:Multi-parameter probes measure dissolved oxygen, pH, conductivity, and emerging contaminants including PFAS. German industrial clusters and California water utilities absorb premium units as EPA and EU discharge mandates tighten validation protocols.
- Soil Moisture Sensors:Capacitance and tensiometric designs serve precision-irrigation networks in Spain and California's Central Valley.
- Remote Sensing Devices:Satellite-mounted and drone-borne hyperspectral imagers support agricultural and emissions verification applications.
Water quality sensors absorb the bulk of installed capacity; soil moisture sensors are expanding most quickly.
Technology:
Cost tiers separate legacy electrochemical platforms from emerging photonic integrated circuits, with foundry economics determining accessibility for distributed deployments.
- Optical Sensors:Silicon photonics and chip-scale spectrometers decouple performance from electrochemical drift limitations. Dutch municipal authorities deploy these for urban air-quality grids where calibration overhead compression justifies unit premiums.
- IoT Solutions:Edge-computing architectures with embedded anomaly detection rewrite deployment economics for distributed networks. Agricultural producers in Australia and California adopt cellular-enabled soil and weather stations where subsidy programs offset hardware costs.
- Chemical Sensors:Electrochemical and metal-oxide semiconductor designs dominate legacy industrial emissions monitoring.
- Acoustic Sensors:Ultrasonic and hydrophone arrays detect pipeline leaks and marine ecosystem disturbances.
Optical sensors command the steepest expansion trajectory; chemical sensors retain the largest installed base.
Application:
Volume concentration varies sharply by subsidy availability and regulatory enforcement intensity, with precision agriculture and emissions compliance driving divergent specification requirements.
- Agricultural Monitoring:Soil-moisture, weather, and crop-health sensor networks enable variable-rate irrigation and fertilization. Spanish and Californian districts deploy commoditized hardware where drought-response funding intersects with water-use efficiency mandates.
- Industrial Emissions:Continuous emissions monitoring systems verify compliance with EU Green Deal binding targets and EPA Maximum Achievable Control Technology rules. German chemical and steel clusters represent the deepest procurement pool for certified analyzer systems.
- Urban Air Quality:Dense particulate and gas sensor grids in Indian and Chinese megacities prioritize unit cost over precision.
- Disaster Management:Flood, wildfire, and seismic early-warning networks require ruggedized telemetry packages.
Industrial emissions applications absorb the bulk of high-margin capacity; agricultural monitoring is gaining share fastest.
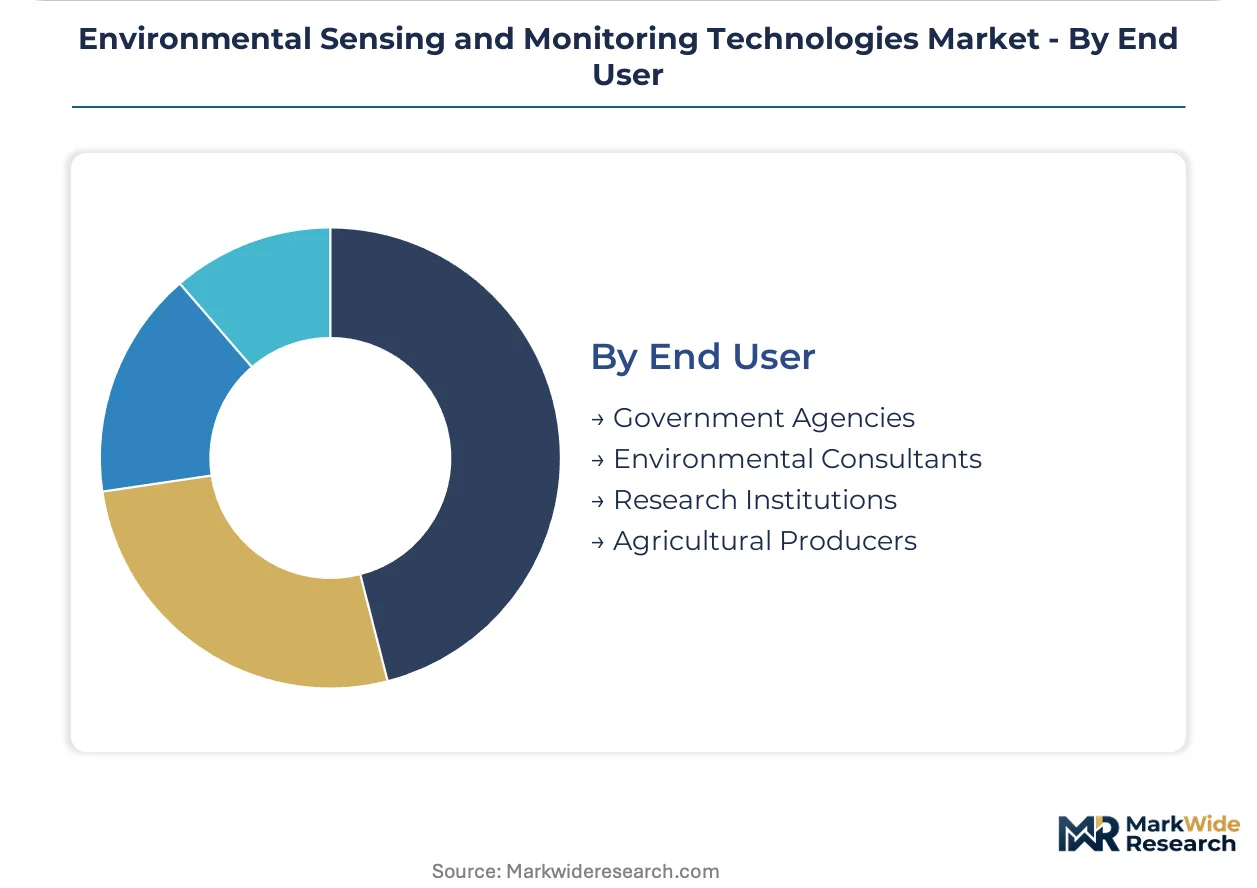
End User:
Customer type determines procurement modality—capital purchase versus sensor-as-a-service—and shapes vendor risk allocation through calibration and maintenance liability.
- Government Agencies:National environmental regulators and municipal utilities specify certified systems with documented traceability to NIST or EU reference standards. Dutch water authorities now contract for continuous data streams rather than hardware ownership, transferring operational risk to instrumentation vendors.
- Agricultural Producers:Individual farm operators and cooperative irrigation districts prioritize upfront cost minimization and cellular connectivity. California's Central Valley Water Quality Coalition aggregates demand for soil-moisture arrays through group procurement programs.
- Environmental Consultants:Field-service firms deploy portable analyzers for site assessment and compliance auditing.
- Research Institutions:Universities and national laboratories drive adoption of novel detection modalities including mass-spectrometry and quantum sensors.
Government agencies absorb the bulk of installed capacity; agricultural producers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates where EPA discharge mandates, EU Green Deal deadlines, and precision-irrigation subsidies intersect with industrial cluster density. Procurement velocity varies sharply across regulatory regimes and subsidy availability.
United States
Water utilities in California and Texas accelerate sensor deployments to meet tightening EPA National Pollutant Discharge Elimination System requirements. The Infrastructure Investment and Jobs Act channels federal funding toward municipal treatment plant upgrades. The Central Valley Water Quality Coalition aggregates agricultural demand for soil-moisture arrays through group procurement programs.
Germany
Industrial clusters in the Ruhr and Bavaria face binding EU Green Deal compliance deadlines that redirect capital toward continuous emissions monitoring systems. The country's national environmental regulator enforces strict validation protocols for particulate detection. Chemical and steel producers around Düsseldorf and Munich absorb premium analyzer systems certified to EU reference standards.
China
Municipal authorities in Beijing, Shanghai, and Shenzhen deploy dense urban air-quality grids prioritizing unit cost over laboratory precision. The Ministry of Ecology and Environment mandates real-time emissions disclosure for heavy industry. Yangtze River Delta manufacturing zones drive demand for multi-parameter water quality probes at discharge outfalls.
India
The National Clean Air Programme mandates low-cost particulate monitors with cellular backhaul in Delhi, Mumbai, and Bangalore. The Central Electricity Authority pushes sensor networks for grid-connected renewable forecasting. Precision-irrigation adoption accelerates in Maharashtra and Gujarat where state drought-response subsidies offset hardware costs.
Netherlands
Dutch water authorities pioneered sensor-as-a-service contracting, procuring continuous data streams rather than owning hardware. The country's national environmental agency specifies systems with documented traceability to EU reference standards. Rotterdam's port industrial complex deploys chip-scale spectrometers for emissions verification.
Environmental Sensing and Monitoring Technologies Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium water-quality instrumentation consolidating around life-science instrumentation groups and commoditized MEMS modules fragmenting across foundry-linked assemblers. Three archetypes dominate: diversified industrial conglomerates leveraging cross-divisional technology transfer, pure-play sensor specialists competing on drift stability and calibration protocols, and contract manufacturers serving private-label municipal procurement. Competitive moves concentrate on M&A to acquire photonic integration capabilities and strategic partnerships to secure MEMS foundry allocation.
Among diversified industrial groups, Honeywell International Inc. and Siemens AG occupy positions spanning building automation through emissions monitoring, their scale enabling integrated system bids that bundle sensors with control infrastructure. Danaher Corporation anchors the premium-tier vector through life-science instrumentation expertise, while Bosch Sensortec GmbH exemplifies the MEMS-specialist archetype with compact module supply for consumer and industrial IoT endpoints.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Danaher Corporation |
| Thermo Fisher Scientific Inc. |
| Agilent Technologies Inc. |
| PerkinElmer |
| Teledyne Technologies Incorporated |
| Siemens AG |
| Bosch Sensortec GmbH |
| Sensirion AG |
| Others |
Supply Flow & Price Mechanics
Captive MEMS foundry relationships anchor supply positioning and pricing power for tier-one environmental sensor vendors. Bosch Sensortec and Honeywell leverage in-house fabrication or priority allocation agreements at Taiwan Semiconductor Manufacturing to buffer unit cost volatility while EPA and EU Green Deal mandates tighten certification requirements that support premium pricing tiers.
Pricing Analysis
Volume concentrates in commoditized soil-moisture and basic air-quality modules where California agricultural subsidies and Indian National Clean Air Programme procurement drive cost-down pressure, while margins pool in multi-parameter water-quality systems certified to EPA and EU reference standards. Price differentiation hinges on NIST-traceable calibration protocols and MEMS foundry allocation priority. Pricing pressure stems from Taiwanese foundry capacity constraints that inflate input costs for distributed sensing networks. Municipal utilities in the Netherlands and Australia exhibit lowest price sensitivity through sensor-as-a-service contracting that transfers operational risk to vendors, whereas individual agricultural producers in Spain and California's Central Valley prioritize upfront hardware cost minimization.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles stage finished sensors for just-in-time delivery to municipal utilities and industrial clusters. Advanced MEMS fabrication concentrates in Taiwan and South Korea, with final assembly gravitating toward Germany and Massachusetts for high-specification units. Critical inputs include silicon wafers, rare gases for calibration mixtures, and photonic integrated circuit substrates. Single-source vulnerability at Taiwanese foundries exposes procurement timelines to geopolitical friction. Distribution runs through authorized instrumentation distributors and direct vendor relationships with national environmental regulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS foundry capacity scarcity props pricing power for vendors with captive allocation or backward integration into fabrication. Tier-one suppliers should exploit this constraint to defend margin structure.
For Market Incumbents: Hedge silicon photonics integration risk through strategic partnerships with Dutch and South Korean chip-scale spectrometer developers. Secure priority MEMS foundry allocation in Taiwan through long-term offtake agreements or equity stakes. Defend position against emerging optical sensor specialists by accelerating EPA and EU reference-standard certification timelines that create switching costs for municipal procurement.
For New Entrants and Emerging Players: Photonic integrated circuit miniaturization offers a technology-first wedge into urban air-quality monitoring where Indian and Chinese municipal authorities prioritize unit cost over laboratory precision. Target low-cost particulate monitor segments in Delhi, Mumbai, and Bangalore where National Clean Air Programme mandates outrun incumbent supply capacity. Pursue cellular-enabled hardware-as-a-service models that transfer calibration liability and accelerate technology refresh cycles.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking photonic integration capabilities and MEMS foundry access. Long-term viability favors vendors with demonstrated EPA or EU reference-standard certification and recurring revenue from sensor-as-a-service contracts. Monitor PFAS maximum contaminant level rule finalization in the United States as an inflection signal for chemosensor and mass-spectrometry acquisition demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integration Acquisition | Silicon photonics capabilities decouple performance from electrochemical cost structures for EPA compliance. |
| MEMS Foundry Allocation Agreement | Priority capacity at Taiwan Semiconductor Manufacturing insulates unit economics against supply shocks. |
| Sensor-as-a-Service Platform Launch | Dutch water authority contracting models transfer calibration liability and accelerate technology refresh. |
| PFAS Detection R&D Scale-Up | EPA maximum contaminant level rules redirect procurement toward novel chemosensor modalities. |
| NIST-Traceable Calibration Investment | Documented reference standards create switching costs for German industrial cluster procurement. |
Methodological Framework
EPA enforcement guidance documents, EU Green Deal implementation reports, and MEMS industry association capacity disclosures formed the secondary backbone. Primary interviews with water utility procurement directors, industrial emissions compliance officers, agricultural irrigation district managers, and MEMS foundry commercial leads combined with secondary validation. Bottom-up unit shipment estimates across air quality, water quality, soil moisture, and remote sensing product categories triangulated against top-down market size reconstructions from regulatory spending disclosures and infrastructure appropriations.
Historical trendline analysis of municipal sensor procurement cycles, precision-irrigation subsidy disbursement patterns, and industrial emissions monitoring capital expenditure informed projection frameworks. Segmentation modeling spanned product type, technology platform, application vertical, and end-user archetype across the projection horizon. CAGRs derived from regression analysis of regulatory mandate enforcement intensity, foundry capacity expansion schedules, and agricultural subsidy program renewals. Industry-specific inputs included EPA National Pollutant Discharge Elimination System permit renewal timelines and EU Green Deal binding target compliance deadlines.
Several conditions sit outside the modeled scope, including geopolitical disruption of Taiwanese foundry operations, abrupt repeal of California or Spanish drought-response subsidies, and technological substitution by quantum sensing modalities. Forecasts reflect stated assumptions regarding regulatory enforcement continuity and MEMS fabrication capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
United States Gas Sensors Market
Sensors and Controls
Thermal Anemometer Market
Sensors and Controls
Middle East and Africa Occupancy Sensors Market
Sensors and Controls
Aspiration Control Systems Market
Sensors and Controls
Global Battery Free RFID Sensor Market
Sensors and Controls
Europe Optical Sensors Market
Sensors and Controls
Embedded Biometric Sensor Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
High-End Accelerometer Market
Sensors and Controls
Ceramic Transducers Market
Sensors and Controls
Air Quality Monitoring System Market
Sensors and Controls
Volatile Organic Compound Gas Sensor Market
Sensors and Controls
Global Signal Conditioning Modules Market
Sensors and Controls
Global Acoustic Wave Sensor Market
Sensors and Controls
Micropump Market