
 Global Fluid Management and Visualization Systems Market | 2026-2036
Global Fluid Management and Visualization Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fluid Management and Visualization Systems Market Foresight
Integration of digital twin architectures with real-time process visualization is reshaping how fluid management systems are engineered and deployed across process industries. Medtronic plc leverages its surgical fluid control heritage to anchor positions in biopharma sterile processing. Stryker Corporation competes through visualization-integrated arthroscopy platforms that extend into broader fluid handling applications. Smith & Nephew plc specializes in advanced irrigation systems for orthopaedic procedures, occupying distinct premium segments.
Fluid management and visualization systems encompass instrumentation, software, and control hardware that monitor, measure, and regulate liquid and gas flows in industrial and clinical environments, typically achieving measurement accuracies within ±0.5% for Coriolis-based mass flow meters. These systems serve the primary commercial purpose of ensuring process repeatability, regulatory compliance, and operational safety in continuous manufacturing. Visualization software commands expanding margin pools as plants consolidate distributed control architectures onto unified analytics platforms. Ultrasonic technology leads installation volumes in water treatment due to non-invasive measurement advantages, while Coriolis instruments capture premium pricing in pharmaceutical production where mass-flow precision is mandatory. Chemical processing remains the largest application segment by installed base, though pharmaceutical production represents the fastest-growing demand vector.
FDA process analytical technology guidelines, EPA effluent monitoring mandates, and EU REACH chemical handling requirements collectively elevate instrumentation replacement cycles and compliance-driven procurement specifications. The EU Green Deal's industrial emissions benchmarks are forcing upgrades to higher-precision flow measurement across European process plants. Stakeholders must monitor how evolving cybersecurity frameworks for operational technology reshape vendor qualification criteria and system architecture decisions.
Market Dynamics
Digital twin architectures are compressing engineering cycles across process industries by unifying real-time visualization with predictive simulation, forcing incumbent vendors to rebuild software stacks around open API frameworks.
Growth Catalysts
- EPA effluent monitoring mandates:Water treatment facilities across the United States face stepped-up discharge enforcement, triggering wholesale instrumentation upgrades at municipal plants.
- Pharmaceutical sterile processing:Closed-loop fluid handling systems are displacing open batch methods as biologics manufacturers chase contamination control and batch record automation.
- Germany's chemical corridor:BASF and Bayer site clusters around Ludwigshafen and Leverkusen are anchoring demand for Coriolis-based mass flow precision in high-throughput chemical synthesis.
Market Restraints
- Stainless steel price volatility:Fluid contact surface fabrication depends on 316L and 317L grades, with nickel content swings compressing margins on standardized meter assemblies.
- Sensor supply concentration:Piezoelectric transducer manufacturing clusters in Japan and South Korea, exposing European and North American system integrators to single-source risk.
- Coriolis meter size limitations:Large-bore applications above 150mm remain technically constrained, ceding pipeline custody-transfer points to ultrasonic alternatives.
Strategic Opportunities
- India's PLI scheme for pharmaceuticals:Greenfield API manufacturing parks in Andhra Pradesh and Gujarat are specifying imported fluid management skids with local assembly requirements.
- EU Green Deal industrial emissions benchmarks:Carbon accounting rules are mandating mass-flow measurement for process CO2 quantification, opening retrofit cycles at refineries and crackers.
- Edge-to-cloud convergence:Integration of 5G-enabled field gateways with centralized analytics platforms is enabling subscription-based visualization software revenue streams.
Industry Challenges
- Cybersecurity certification timelines:IEC 62443 compliance for operational technology networks is extending vendor qualification cycles by 8-14 months at major chemical operators.
- Legacy DCS integration friction:Brownfield plants running 1990s-era distributed control architectures face protocol translation costs that erode digital twin business cases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fluid Management and Visualization Systems Market |
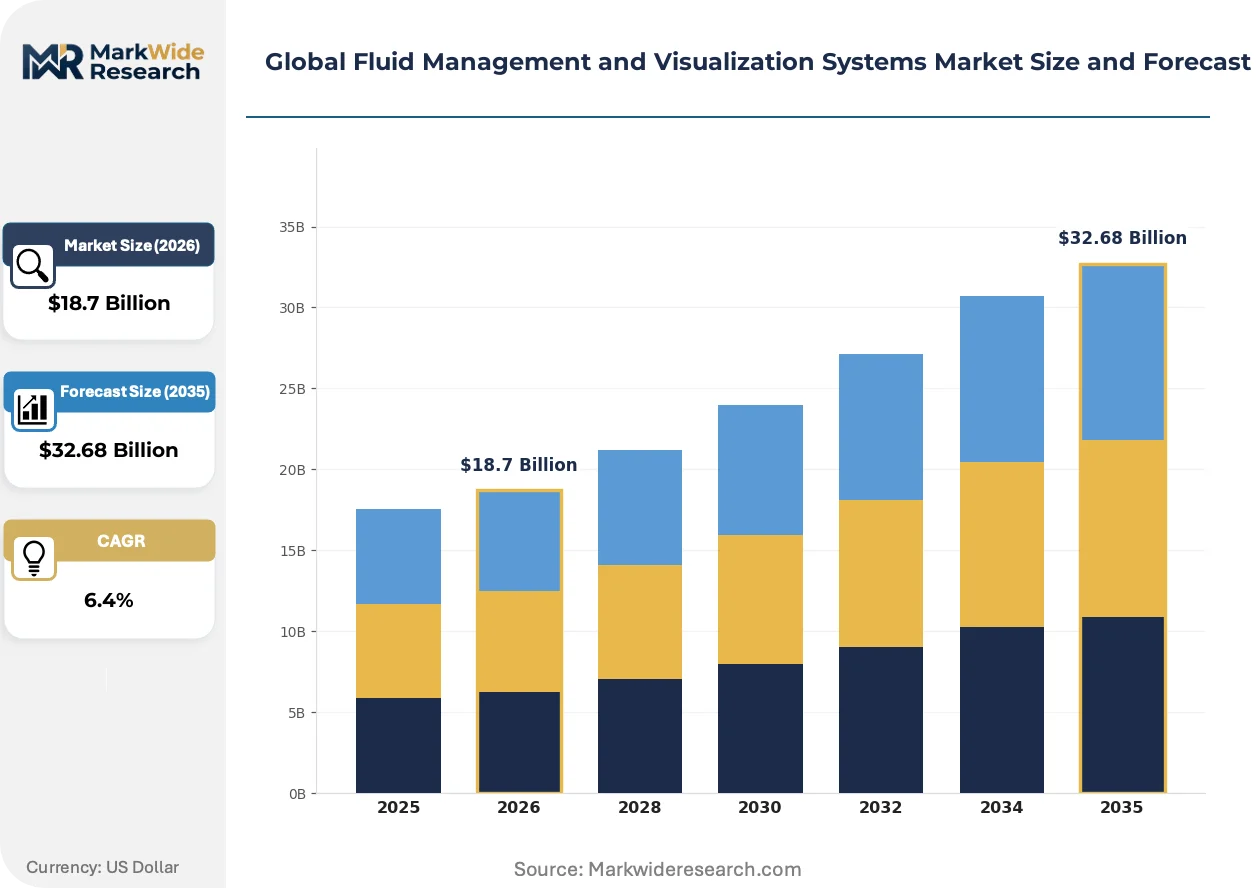
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Meters, Pressure Sensors, Level Transmitters, Visualization Software, Control Valves Technology: Ultrasonic, Electromagnetic, Coriolis, Thermal Mass, Laser Doppler Application: Chemical Processing, Water Treatment, Pharmaceutical Production, Food & Beverage, Oil Refining End User: Manufacturing Plants, Research Laboratories, Chemical Engineering Firms, Process Control Operators |
| Companies Covered | Medtronic plc, CONMED Corporation, Stryker Corporation, Smith & Nephew plc, B. Braun SE, Ecolab Inc., Olympus Corporation, Hologic Inc., AngioDynamics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fluid Management and Visualization Systems Market Shifts & Advancements
Real-time process visualization is migrating from supervisory screens to immersive operator interfaces, compressing response times and reshaping how control room staffing models are justified.
Edge-deployed machine learning inference engines are digitizing anomaly detection in multiphase flow regimes. Offshore oil and gas operators in the North Sea and Gulf of Mexico are piloting these systems at wellhead separation trains. The technology is digitizing maintenance scheduling by flagging hydrate formation and sand erosion patterns before they trigger shutdowns.
REACH chemical handling requirements are forcing material traceability into fluid contact component supply chains. European process OEMs must now document full substance declarations for seals, gaskets, and coating systems. Pharmaceutical and food-contact applications face the steepest compliance burdens, with some vendors exiting the market rather than bearing certification costs.
Buyer consolidation among contract manufacturing organizations is concentrating procurement leverage. Large CDMOs in Switzerland and Singapore are unbundling after-sales service contracts from hardware purchases, forcing meter vendors to compete on pure equipment margin while service revenue migrates to third-party specialists. This pattern is most pronounced in sterile fill-finish operations where uptime guarantees dominate vendor selection.
Global Fluid Management and Visualization Systems Market Segmentation
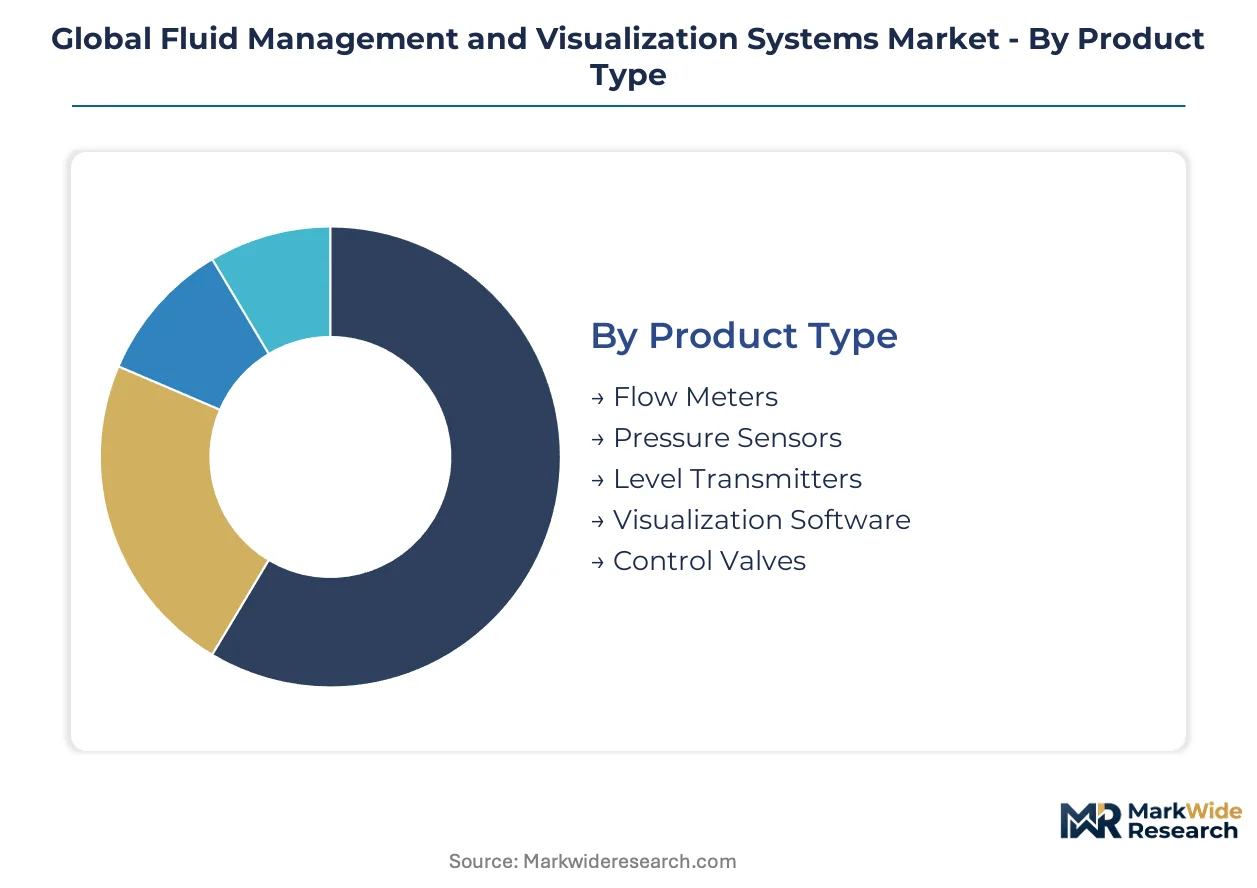
Fluid management and visualization systems fragment across multiple technical dimensions, each carrying distinct procurement cycles and margin structures. Understanding segment-level velocity helps vendors align R&D spend with replacement timelines and regulatory upgrade windows.
Product Type:
Replacement cycles vary dramatically across hardware versus software categories, with instrumentation facing 7-10 year depreciation schedules while visualization platforms refresh on 3-4 year enterprise software cycles.
- Flow Meters:Coriolis and ultrasonic variants dominate capital budgets, with pharmaceutical manufacturers specifying ±0.5% accuracy for sterile batch applications. Germany's chemical corridor around Ludwigshafen anchors demand for high-precision mass flow measurement in continuous synthesis operations.
- Visualization Software:Digital twin integration and real-time analytics dashboards command recurring license revenue, expanding fastest among brownfield chemical plants consolidating distributed control architectures onto unified platforms.
- Pressure Sensors:Piezoelectric and strain-gauge technologies serve custody-transfer and safety interlock applications.
- Level Transmitters:Radar and guided-wave radar systems address bulk liquid storage monitoring.
- Control Valves:Pneumatic and electric actuators regulate flow modulation in process loops.
Flow meters anchor the volume base while visualization software gains share at the steepest rate.
Technology:
Cost tiers separate invasive from non-invasive measurement approaches, with premium pricing attached to technologies eliminating process shutdown for calibration.
- Coriolis:Direct mass-flow measurement achieves highest accuracy grades required by FDA process analytical technology guidelines, commanding 3-4x price multiples over volumetric alternatives. Biologics manufacturers specify Coriolis for closed-loop sterile processing to eliminate density compensation errors.
- Ultrasonic:Clamp-on and inline variants lead installation volumes in water treatment due to zero pressure drop and minimal maintenance, though custody-transfer applications require dual-path redundancy that erodes cost advantages.
- Electromagnetic:Magmeters excel in conductive fluid applications with abrasive slurries.
- Thermal Mass:Constant-temperature anemometry serves compressed air and natural gas flow monitoring.
- Laser Doppler:Non-contact velocimetry addresses research and specialized multiphase flow regimes.
Ultrasonic technology captures the broadest installed base while Coriolis expands most quickly in regulated pharmaceutical environments.
Application:
Customer maturity and compliance burden create divergent procurement behaviors across process industries.
- Chemical Processing:Continuous manufacturing environments demand 99.9%+ measurement availability, with BASF and Bayer site clusters specifying redundant instrumentation architectures. EPA effluent monitoring mandates are accelerating ultrasonic meter deployment at discharge points.
- Pharmaceutical Production:Sterile fill-finish and biologics manufacturing drive specification intensity, with India's PLI scheme for pharmaceuticals triggering greenfield API plant investments in Andhra Pradesh and Gujarat.
- Water Treatment:Municipal and industrial facilities face stepped-up discharge enforcement.
- Food & Beverage:Hygienic design standards and CIP/SIP compatibility dominate vendor selection.
- Oil Refining:Large-bore custody transfer and process optimization applications persist.
Chemical processing maintains the largest installed base while pharmaceutical production climbs the fastest on biologics capacity expansion.
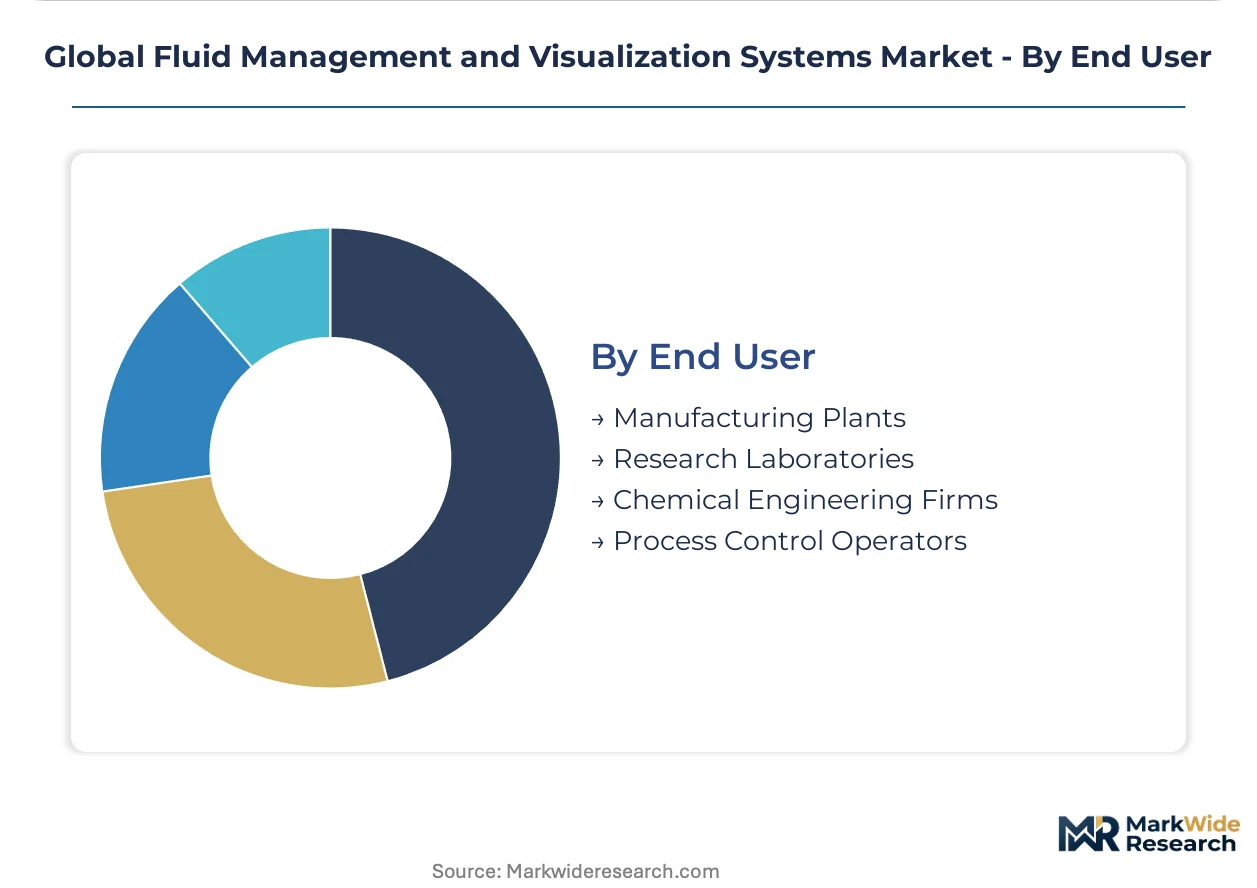
End User:
Procurement centralization versus fragmentation shapes pricing power and service contract structures across buyer types.
- Manufacturing Plants:Owner-operators in continuous process industries consolidate instrumentation standards to reduce spare parts complexity, with EU Green Deal industrial emissions benchmarks forcing mass-flow measurement upgrades for carbon accounting compliance.
- Research Laboratories:Academic and government facilities prioritize measurement range flexibility over absolute accuracy, accepting longer calibration intervals.
- Chemical Engineering Firms:EPC contractors specify vendor lists based on project geography and client preferences.
- Process Control Operators:Third-party automation specialists manage outsourced instrumentation maintenance.
Manufacturing plants dominate capital deployment while research laboratories show the steepest expansion trajectory on laboratory automation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process manufacturers and healthcare systems concentrate procurement authority in Germany, the United States, China, India, and Japan. Each geography imposes distinct regulatory compliance burdens on fluid management system vendors.
United States
EPA effluent monitoring mandates drive municipal water treatment instrumentation upgrades across the Great Lakes and Gulf Coast corridors. FDA process analytical technology guidelines accelerate biopharma sterile processing investments. Houston's petrochemical complex anchors demand for custody-transfer flow measurement at refinery and export terminal networks.
Germany
BASF and Bayer manufacturing clusters around Ludwigshafen and Leverkusen specify Coriolis-based mass flow precision for continuous chemical synthesis. EU Green Deal industrial emissions benchmarks mandate mass-flow measurement retrofits for carbon accounting compliance. The country's chemical corridor remains the densest concentration of high-precision fluid handling infrastructure in Europe.
China
NMPA regulatory harmonization with ICH standards elevates pharmaceutical production equipment specifications in Jiangsu and Zhejiang provinces. Dual carbon goals force process CO2 quantification upgrades at refinery and chemical complexes. Shanghai's biologics manufacturing parks specify closed-loop sterile processing systems for export-oriented contract manufacturing.
India
PLI scheme incentives for active pharmaceutical ingredient manufacturing trigger greenfield investments in Andhra Pradesh and Gujarat. CDSCO quality enforcement tightens equipment validation requirements at export-oriented facilities. Hyderabad's vaccine manufacturing cluster specifies imported fluid management skids with local assembly mandates.
Japan
METI industrial efficiency standards accelerate digital twin adoption at chemical and electronics process plants. PMDA pharmaceutical manufacturing guidelines enforce contamination control specifications at sterile fill-finish operations. Osaka's specialty chemical producers anchor regional demand for high-precision flow measurement in fine chemical synthesis.
Global Fluid Management and Visualization Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement hierarchies. Medical device conglomerates and industrial automation multinationals anchor the consolidated upper tier, while regional system integrators and component specialists populate fragmented lower tiers. Three archetypes dominate: surgical fluid control heritage players extending into biopharma processing, visualization-integrated platform vendors, and precision instrumentation pure-plays. Competitive moves concentrate on strategic partnerships for digital twin software stacks and geographic expansion through local assembly requirements in India and Southeast Asia.
Among medical technology conglomerates, Medtronic plc and Stryker Corporation exemplify archetype diversity. Medtronic leverages surgical fluid control heritage to anchor positions in biopharma sterile processing. Stryker competes through visualization-integrated platform architectures that extend into broader fluid handling applications. Smith & Nephew plc occupies a distinct premium segment specialization in advanced irrigation systems for orthopaedic procedures.
| Leading Market Players |
|---|
| Medtronic plc |
| CONMED Corporation |
| Stryker Corporation |
| Smith & Nephew plc |
| B. Braun SE |
| Ecolab Inc. |
| Olympus Corporation |
| Hologic Inc. |
| AngioDynamics Inc. |
| Others |
Supply & Pricing Matrix
Ludwigshafen's chemical corridor capacity dynamics concentrate supply leverage among Coriolis meter specialists, translating upstream component scarcity into tiered pricing power across pharmaceutical and chemical processing procurement channels. Stainless steel price volatility in 316L and 317L grades feeds directly into equipment margin compression, while sensor supply concentration in East Asian manufacturing clusters amplifies cost pass-through elasticity for European and North American system integrators.
Pricing Analysis
Cost-plus contracts with London Metal Exchange nickel indexation dominate large-bore Coriolis procurement in Germany's chemical corridor, insulating vendors from raw material swings while capping upside. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated sterile processing systems from general industrial grades, with certification tier and after-sales service bundling as the primary differentiation drivers. Pricing pressure stems from buyer consolidation among contract manufacturing organizations unbundling service contracts from hardware purchases. Research laboratories exhibit highest price sensitivity due to flexible calibration tolerance acceptance, while sterile fill-finish operators prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Export control regimes restricting piezoelectric transducer technology flows from Japan and South Korea constrain European system integrators' sourcing flexibility for ultrasonic and Coriolis sensor cores. Manufacturing concentrates in Germany for precision machining, Japan for piezoelectric components, and China for standard-grade electromagnetic meter assemblies. Raw material dependencies center on nickel-bearing stainless steels, ceramic sensor substrates, and specialty elastomer seals. Single-source vulnerability in transducer supply exposes integrators to 8-14 month qualification delays. Distribution runs through authorized system integrators with regional service footprints, though direct OEM relationships are consolidating among large chemical and pharmaceutical operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Visualization software subscriptions and predictive maintenance service layers are expanding at multiples of hardware depreciation cycles, positioning fluid management as a recurring-revenue attach opportunity rather than transactional equipment sale. After-sales contracts for calibration validation and digital twin integration now capture margin pools exceeding original equipment margins in brownfield chemical installations.
For Market Incumbents: Build switching-cost moats through digital twin platform entrenchment and IEC 62443 cybersecurity certification pre-qualification. Incumbents should anchor sterile processing accounts with closed-loop system validation packages that embed proprietary control algorithms, while adding local assembly capacity in Andhra Pradesh and Gujarat to satisfy India's PLI scheme domestic content requirements. Threats from open-API software entrants and ultrasonic alternatives in large-bore custody transfer applications demand defensive R&D allocation toward edge-AI anomaly detection. For New Entrants and Emerging Players: Pursue white-space capture in India's greenfield API manufacturing parks and Southeast Asian water treatment retrofit cycles, where procurement standards remain fluid and incumbent relationships are shallowest. The most penetrable segment lies in municipal effluent monitoring mandates across US Great Lakes and Gulf Coast corridors, where EPA enforcement timelines compress vendor qualification windows. A software-first go-to-market angle—lead with subscription analytics rather than hardware—sidesteps capital-intensive manufacturing barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance compounder play because FDA process analytical technology guidelines and EU Green Deal emissions benchmarks institutionalize replacement cycles regardless of macroeconomic cyclicality. Acquisition targets should prioritize visualization software specialists with open-API architectures and existing pharmaceutical validation records. The signal to watch is CDMO procurement centralization velocity in Switzerland and Singapore, where unbundled service contracts indicate tipping points for platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Unifies real-time visualization with predictive simulation, compressing engineering cycles for BASF and Bayer site clusters. |
| Backward Integration into Sensor Manufacturing | Mitigates piezoelectric transducer supply concentration risk from Japan and South Korean sources. |
| Local Assembly Partnership in India | Satisfies PLI scheme domestic content thresholds for greenfield API plants in Andhra Pradesh and Gujarat. |
| Cybersecurity Certification Pre-Investment | Accelerates IEC 62443 vendor qualification timelines that currently extend 8-14 months at major chemical operators. |
| Subscription-Based Visualization Software | Captures recurring revenue from brownfield chemical plants consolidating distributed control architectures onto unified analytics platforms. |
Research Methodology
Desk research of FDA guidance documents, EPA effluent monitoring enforcement records, and EU REACH substance declaration databases preceded structured interviews with plant engineers at continuous manufacturing facilities, procurement leads at contract manufacturing organizations, and aftermarket service heads at regional system integrators. Primary fieldwork combined with secondary validation from SEC filings of listed medical device and industrial automation conglomerates, trade customs data for fluid handling equipment imports, and technical standards documentation from IEC and ISO committees. Bottom-up equipment shipment analysis and top-down process industry capital expenditure triangulation anchored market sizing.
Assumptions held regulatory enforcement timelines and stainless steel price volatility bands fixed across the modeling period, while pharmaceutical production growth trajectories and digital twin adoption curves were stress-tested under sensitivity scenarios. Segmentation modeling incorporated product type, technology tier, application vertical, and end-user procurement centralization patterns. CAGRs were derived from replacement cycle analysis overlaid with regulatory upgrade windows and greenfield capacity announcements. Industry-specific inputs included biologics manufacturing capacity expansion pipelines and municipal water treatment instrumentation depreciation schedules.
Sensitivities concentrate around EPA enforcement intensity variations, nickel price volatility spikes, and cybersecurity certification timeline extensions. Forecasts reflect these documented assumptions and modeled scenario boundaries. Material shifts in FDA process analytical technology guidance scope or EU Green Deal emissions benchmark stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Smart Hydrophone Market
Sensors and Controls
Control Network Modules Market
Sensors and Controls
Piece-Level Inventory Tracking and Vision Systems Market
Sensors and Controls
Steam Flow Meter Market
Sensors and Controls
Electronic Differential Control Module Market
Sensors and Controls
Electromagnetic Tracking Systems Market
Sensors and Controls
Global Smartphone Sensors Market
Sensors and Controls
Magnetic Field Sensor Market
Sensors and Controls
Sensor Development Kit Market
Sensors and Controls
Asia-Pacific Thermocouple Temperature Sensors Market
Sensors and Controls
Doppler Lidar Market
Sensors and Controls
Global Tactile Sensor Market
Sensors and Controls
Global Space Sensors and Actuators Market
Sensors and Controls
Timing Device Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
APAC Chemical Sensors Market