
 Aluminum Phosphide Market | 2026-2036
Aluminum Phosphide Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Phosphide Market Outlook
Zinc phosphide is consolidating share in rodenticide applications where toxicity profiles favor alternatives, yet aluminum phosphide retains dominance in stored-grain fumigation due to superior gas penetration and residue economics. BASF SE leverages its agrochemical distribution network to sustain volume leadership across European grain-handling facilities. UPL Ltd. anchors its position in South Asian markets through localized tablet production and farmer-facing technical advisory programs. Detia Degesch GmbH specializes in precision-formulated pellet systems that differentiate on application safety and dosage accuracy.
Aluminum phosphide is a binary compound of aluminum and phosphorus (AlP), typically formulated as gray or dark yellow crystals that react with atmospheric moisture to release phosphine gas (PH₃) at concentrations lethal to insects, rodents, and nematodes while leaving minimal residue on food commodities. The manufacturing process involves direct synthesis from elemental aluminum and red phosphorus at elevated temperatures, followed by compression into tablets, pellets, or granules with controlled porosity to regulate phosphine liberation rates. Tablet formulations dominate current revenue pools due to standardized dosing protocols and established regulatory approvals across major grain-exporting nations. Pellet configurations represent the fastest-growing product category, driven by demand for automated dispensing equipment in large-scale warehousing operations. Agricultural pest control applications command the largest share of end-user spending, though food storage segments in tropical climates exhibit accelerated procurement intensity as climate-driven pest pressures intensify.
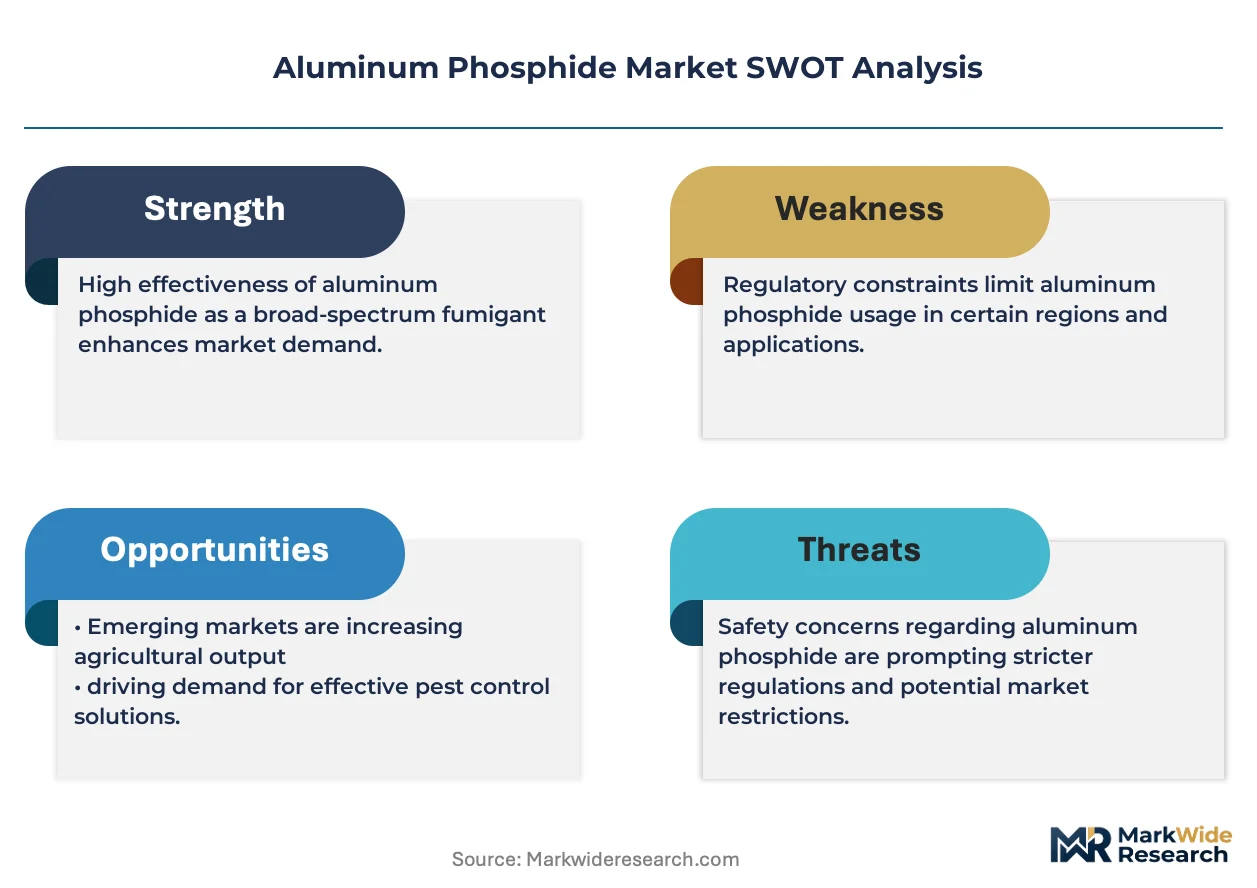
The EPA regulates aluminum phosphide under FIFRA as a restricted-use pesticide, mandiring certified applicator training and buffer-zone calculations that shape product labeling and market access protocols in the United States. India's Central Insecticides Board enforces registration requirements under the Insecticides Act that influence formulation standards and packaging specifications for domestic manufacturers and importers. EFSA and REACH classifications in Europe restrict certain competing fumigant chemistries, indirectly expanding aluminum phosphide's addressable market within EU grain logistics networks. Stakeholders must monitor evolving residue tolerance negotiations between CODEX and national food safety authorities, as harmonized maximum residue limits will determine which formulation types and application rates gain preferential adoption across integrated supply chains.
Market Dynamics
Phosphine-resistant pest populations are forcing grain storage operators toward higher-dosage protocols and precision-delivery equipment, restructuring procurement priorities across tropical agricultural belts.
Growth Catalysts
- EU F-Gas Regulation:Tightening restrictions on competing fumigants redirect procurement toward aluminum phosphide formulations across European grain logistics networks.
- India's warehouse modernization:Government-backed infrastructure programs sustain bulk purchases of tablet and pellet formulations in the country's agricultural belt.
- Phosphine gas penetration:Superior residue economics versus alternative chemistries anchors dominance in stored-grain fumigation applications.
Market Restraints
- Elemental phosphorus supply concentration:Synthesis feedstock dependence on limited geographic sources creates input cost volatility for manufacturers.
- EPA FIFRA restrictions:Mandated certified applicator training and buffer-zone calculations constrain market access protocols in the United States.
- Zinc phosphide substitution:Rodenticide applications favor alternative toxicity profiles where gas penetration requirements are less critical.
Strategic Opportunities
- Brazilian harvest protection:Expanding fumigation programs among grain storage operators create underpenetrated demand for pellet formulations.
- Automated dispensing equipment:Convergence of precision-formulated pellet systems with warehouse automation enables dosage accuracy differentiation.
- Codex harmonization:Evolving residue tolerance negotiations between international and national food safety authorities favor standardized formulation types.
Industry Challenges
- Certified applicator pipeline:EPA-mandated training requirements create talent bottlenecks for field deployment in regulated markets.
- Regulatory approval timelines:India's Central Insecticides Board registration protocols extend product launch cycles for new formulation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Phosphide Market |
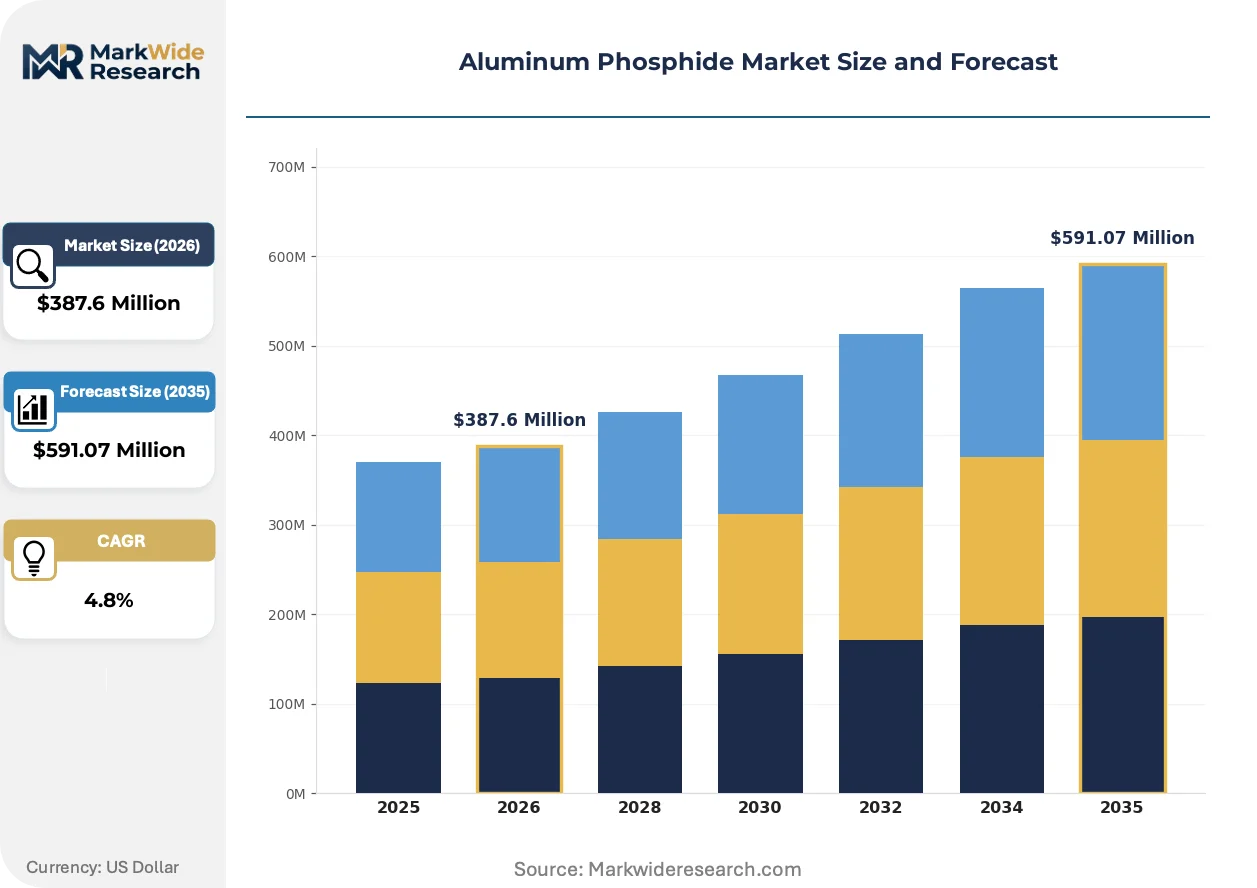
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Tablets, Pellets, Dust Application: Agricultural Pest Control, Food Storage, Fumigation, Industrial Processes End User: Agriculture, Warehousing, Manufacturing, Chemical Industry Packaging Type: Bags, Drums, Totes, Bulk Containers |
| Companies Covered | BASF SE, UPL Ltd., Nippon Chemical Industrial Co., Ltd., Sandhya Group, Detia Degesch GmbH, Teramerra Inc., Corteva Agriscience, Syngenta AG, Vinipul Inorganics Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Phosphide Market Strategic Shifts
Formulation engineering and regulatory chemistry are converging to reshape competitive positioning, with precision-delivery technologies and residue management protocols determining procurement winners.
Pellet configurations with controlled porosity engineering are expanding into large-scale warehousing operations through integration with automated dispensing systems. Grain elevator operators in Brazil and India adopt these systems at accelerating pace to manage phosphine-resistant pest pressures. The technology is expanding into premium pricing tiers where dosage accuracy justifies equipment investment.
REACH framework classifications in Europe restrict methyl bromide and sulfuryl fluoride alternatives, indirectly expanding aluminum phosphide's addressable market. EFSA residue limit negotiations determine which formulation types gain preferential adoption across integrated supply chains. Tablet formulations with established regulatory approvals capture disproportionate volume in EU grain-exporting nations.
Buyer concentration among government-backed warehouse operators compresses procurement cycles toward multi-year framework agreements. Traditional distributor networks face disintermediation as agricultural belt storage facilities contract directly with manufacturers for technical advisory programs. India's government procurement channels exhibit the most visible consolidation, with state warehouse corporations consolidating supplier panels.
Aluminum Phosphide Market Segmentation
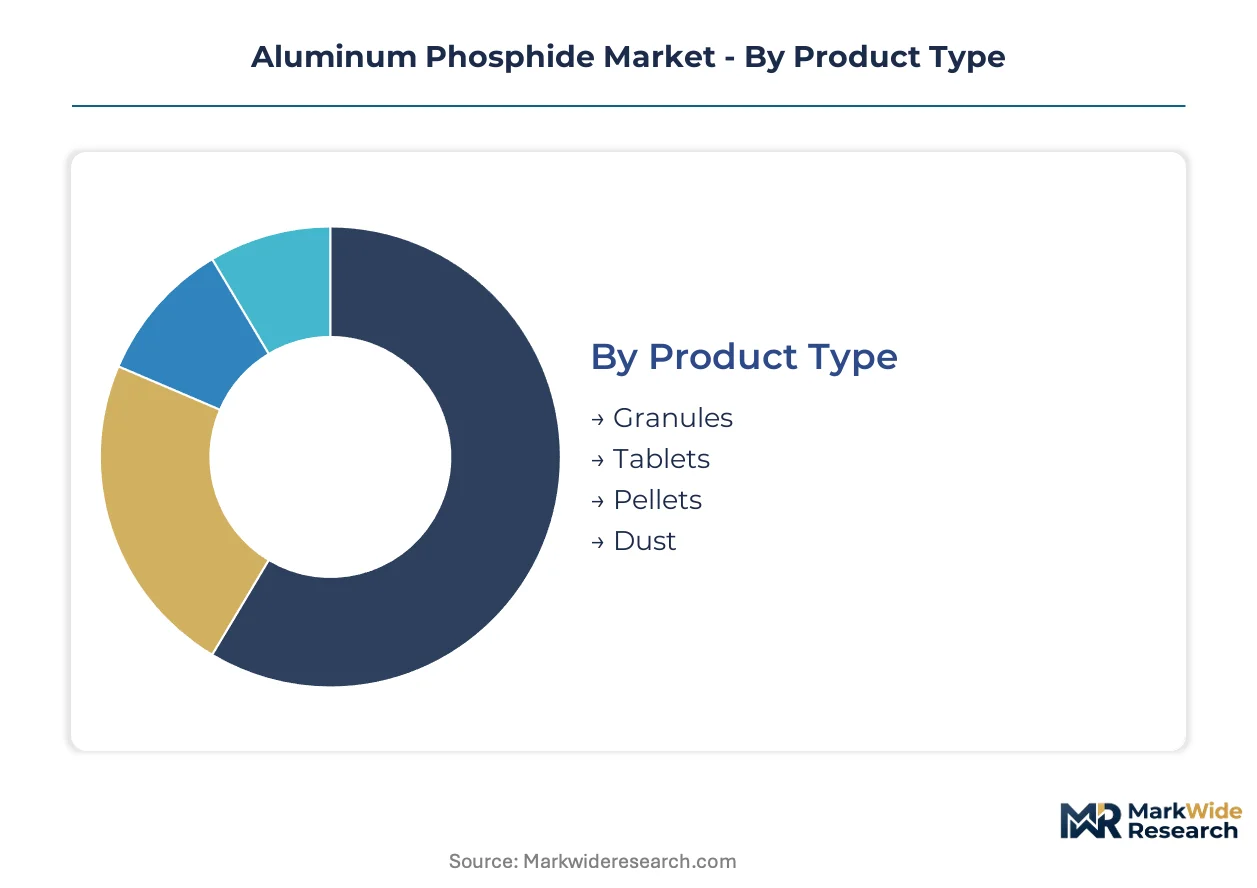
Formulation engineering and packaging logistics determine competitive positioning in aluminum phosphide markets. Procurement patterns diverge sharply across grain-exporting nations based on regulatory approval status and warehouse automation levels.
Product Type:
Manufacturing capacity concentrates among facilities with controlled-porosity compression technology and phosphine liberation rate calibration capabilities.
- Tablets:Standardized circular or oblong compressed formulations with uniform density for predictable phosphine release curves. India's state warehouse corporations and Brazilian grain elevator operators specify tablet configurations for manual application protocols in facilities lacking automated systems.
- Pellets:Precision-engineered spherical formulations with graded porosity layers that enable automated dispensing equipment integration. Large-scale warehousing operations in tropical agricultural belts adopt pellet systems to manage phosphine-resistant pest pressures through dosage accuracy.
- Granules:Irregular particulate formulations with high surface-area-to-volume ratios for rapid phosphine liberation in confined spaces.
- Dust:Fine-powder formulations with specialized application equipment requirements for niche industrial fumigation scenarios.
Tablets absorb the bulk of installed capacity; pellets are expanding most quickly.
Application:
End-use economics favor formulations with established residue tolerance negotiations versus emerging alternatives facing regulatory restriction.
- Agricultural Pest Control:Soil and crop-directed fumigation targeting nematodes, soil-borne insects, and pre-harvest pest suppression. Indian agricultural belt procurement channels sustain volume leadership through government-backed technical advisory programs and farmer-facing distribution networks.
- Food Storage:Post-harvest grain protection in warehouse and silo environments where phosphine gas penetration minimizes commodity residue. EU grain logistics networks redirect procurement toward aluminum phosphide as F-Gas Regulation restrictions eliminate competing chemistries.
- Fumigation:Structural and vessel-based pest elimination requiring sealed-environment protocols and certified applicator oversight.
- Industrial Processes:Non-agricultural fumigation applications in manufacturing equipment and transport container sanitation.
Food storage commands the largest revenue pool; agricultural pest control exhibits the steepest expansion trajectory in tropical climates.
End User:
Buyer concentration patterns reshape distribution economics as direct manufacturer contracting displaces traditional distributor networks.
- Agriculture:Farm-level and cooperative storage operators with variable technical capacity and regulatory compliance exposure. Brazil's expanding harvest protection programs create procurement intensity for pellet formulations with simplified application protocols.
- Warehousing:Centralized grain handling facilities with automated inventory management and multi-year framework agreement structures. India's Food Corporation of India and state warehouse corporations consolidate supplier panels through technical specification standardization.
- Manufacturing:Food processing and commodity handling facilities with integrated pest management requirements.
- Chemical Industry:Industrial fumigation service providers with specialized equipment fleets and certified applicator workforces.
Warehousing concentrates procurement volume; agriculture is gaining share fastest through warehouse modernization programs.
Packaging Type:
Logistics configuration directly determines market access for manufacturers with limited cold-chain or hazardous-material transport capabilities.
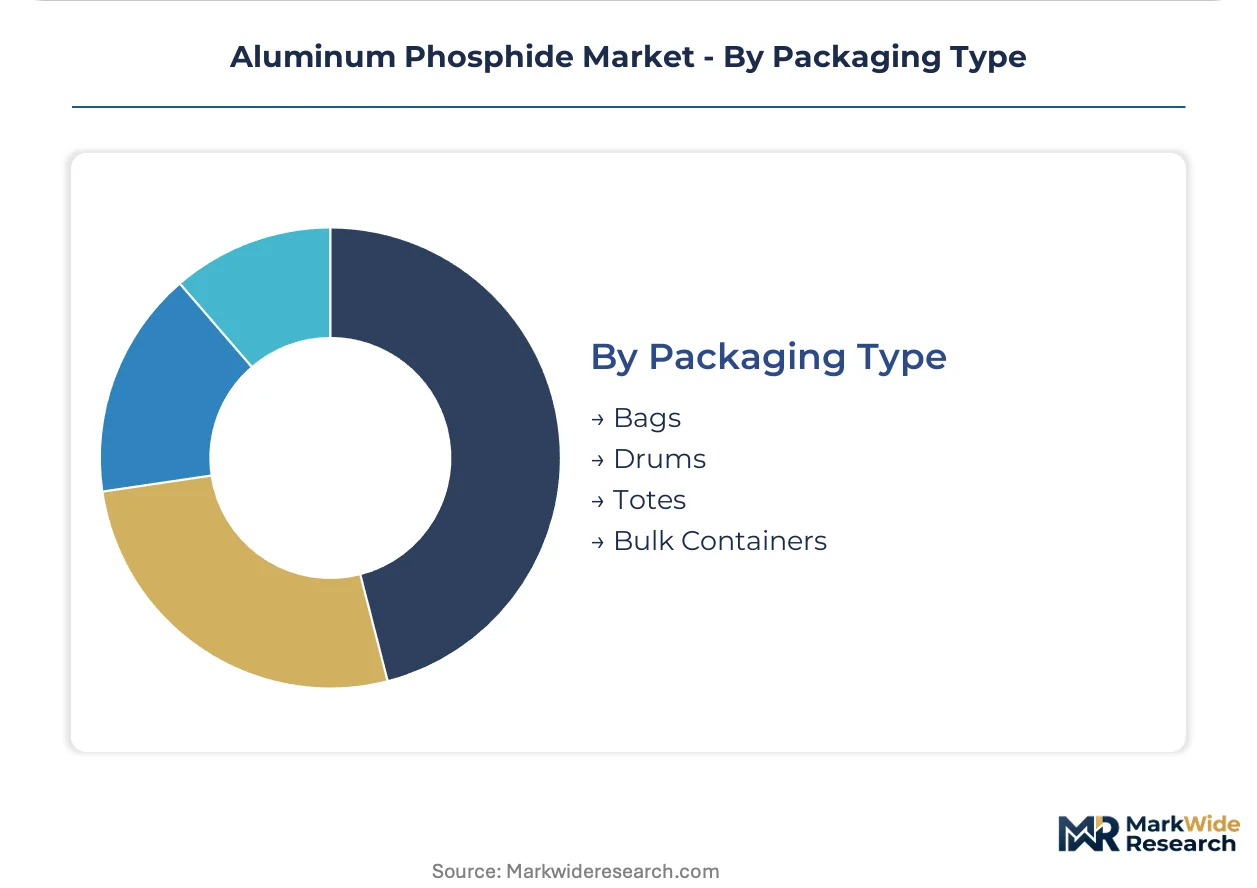
- Bags:Flexible multi-layer polymer packaging with moisture-barrier properties for small-batch agricultural distribution. Indian rural procurement channels specify bag configurations for last-mile delivery to farm-level storage operators.
- Drums:Rigid steel or fiber containers with UN-certified hazardous material specifications for intercontinental shipping. European grain-handling facilities specify drum packaging for bulk import compliance with REACH documentation requirements.
- Totes:Intermediate bulk containers with integrated dispensing systems for high-throughput warehousing operations.
- Bulk Containers:Dedicated tank or silo configurations for integrated supply chain operators with captive application infrastructure.
Drums capture the majority of international trade volume; totes are climbing the fastest through warehouse automation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's warehouse modernization corridors concentrate procurement demand through state-backed grain storage infrastructure. Special economic zones in Nagpur and Nashik anchor tablet formulation distribution networks serving central India's agricultural belt.
United States
EPA FIFRA restrictions mandate certified applicator training for grain elevator operators across the Corn Belt. Iowa and Illinois storage facilities deploy buffer-zone calculations for phosphine fumigation protocols. Omaha-based logistics operators contract directly with manufacturers for technical advisory programs.
Germany
REACH framework restrictions on methyl bromide redirect procurement toward aluminum phosphide formulations. EFSA residue limit negotiations determine formulation approvals for grain-exporting facilities. Hamburg port operators consolidate supplier panels through multi-year framework agreements.
Brazil
ANVISA registration requirements shape import protocols for phosphine-resistant pest management. Mato Grosso and Paraná grain storage operators expand pellet formulation procurement for automated dispensing systems. São Paulo-based distributors face disintermediation as warehouses contract manufacturers directly.
India
FSSAI residue tolerance standards influence tablet specifications for government warehouse corporations. Punjab and Haryana state warehouse operators sustain bulk purchases through Food Corporation of India channels. Gujarat manufacturing clusters supply compressed formulations with controlled porosity engineering.
China
GB standards for agricultural chemical storage regulate phosphine liberation rate specifications. Shandong and Henan grain-handling provinces adopt pellet systems for large-scale warehousing automation. Zhengzhou-based equipment manufacturers integrate precision-delivery technologies with formulation supply.
Aluminum Phosphide Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with formulation standardization favoring established players in regulated markets. The vendor base concentrates among facilities with controlled-porosity compression technology and phosphine liberation calibration capabilities. Three archetypes dominate: diversified agrochemical conglomerates with distribution networks, regional specialists with localized production, and precision-formulation engineers with automated dispensing integration. Competitive moves center on backward integration into elemental phosphorus sourcing and strategic partnerships with warehouse automation equipment providers.
Among European specialists, Detia Degesch GmbH exemplifies precision-formulation engineering with pellet systems designed for dosage accuracy. BASF SE anchors the diversified agrochemical tier through established grain-handling facility relationships. UPL Ltd. represents regional specialists with localized tablet production serving South Asian procurement channels.
| Leading Market Players |
|---|
| BASF SE |
| UPL Ltd. |
| Nippon Chemical Industrial Co., Ltd. |
| Sandhya Group |
| Detia Degesch GmbH |
| Teramerra Inc. |
| Corteva Agriscience |
| Syngenta AG |
| Vinipul Inorganics Pvt. Ltd. |
| Others |
Value Chain & Pricing Dynamics
EU REACH compliance mandates gate both qualified supply and premium-tier pricing access, as formulation manufacturers must demonstrate controlled-porosity engineering and phosphine liberation calibration to serve European grain logistics networks. Buyers lacking REACH documentation face exclusion from multi-year framework agreements with Hamburg port operators and German grain-exporting facilities.
Pricing Analysis
Short lead-time premiums command pricing power among Indian state warehouse corporations facing monsoon-driven harvest pressure, while spot inventory discounts attract smaller agricultural cooperatives with flexible procurement calendars. Tablet formulations with established Central Insecticides Board registrations capture premium positioning against unregistered alternatives. Cost compression in economy-tier granule formulations is intensifying because Chinese manufacturers are expanding Shandong production capacity. Government-backed warehouse operators exhibit lowest price sensitivity; farm-level storage operators in Brazil's Mato Grosso belt show highest sensitivity due to working capital constraints.
Supply Chain Analysis
Direct-to-warehouse channels handle Food Corporation of India demand through state-procurement panels, bypassing traditional distributor networks. Manufacturing gravity centers on India, China, and Germany, with Gujarat compression facilities and Shandong chemical parks anchoring global tablet and pellet output. Elemental phosphorus feedstock draws from limited geographic sources in China and Vietnam, creating input cost volatility. Single-source vulnerability concentrates in red phosphorus supply chains. Distribution runs through UN-certified drum packaging for intercontinental REACH compliance, with tote configurations climbing fastest through warehouse automation adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into elemental phosphorus sourcing anchors competitive positioning, as captive feedstock supply separates volume leaders from formulation-dependent competitors across regulated markets.
For Market Incumbents: Acquire controlled-porosity compression equipment manufacturers to secure dosage accuracy capabilities against precision-formulation specialists. Lock in multi-year red phosphorus offtake agreements with Vietnamese suppliers before feedstock competition intensifies. Defend against zinc phosphide substitution in rodenticide segments by emphasizing phosphine gas penetration economics in stored-grain applications.
For New Entrants and Emerging Players: The premium-to-economy price gap in automated pellet systems offers entry leverage for equipment-integrated formulations targeting Brazilian warehouse modernization. Brazil's Mato Grosso and Paraná storage corridors present the most penetrable geography, with ANVISA registration pathways less congested than EPA FIFRA or REACH compliance channels. Pursue technical advisory partnerships with São Paulo-based agricultural cooperatives to bypass disintermediated distributor networks.
For Investors and Strategic Acquirers: Consolidation of Indian state warehouse corporation supplier panels is the leading indicator that procurement concentration will favor integrated manufacturers over pure-play formulators. The five-to-ten-year viability window favors acquirers of precision-pellet engineering capabilities with automated dispensing integration. Target regional specialists with localized Central Insecticides Board registrations and existing farmer-facing distribution infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elemental Phosphorus | Captive red phosphorus supply from Vietnamese sources insulates margin structures against feedstock volatility. |
| Precision Pellet Manufacturing Scale-Up | Controlled-porosity engineering for automated dispensing systems commands premium positioning in Brazilian warehouses. |
| REACH Compliance Certification Program | EFSA residue limit alignment unlocks multi-year framework agreements with Hamburg port operators. |
| Technical Advisory Partnership Expansion | Farmer-facing programs with Indian agricultural cooperatives displace traditional distributor intermediation. |
| Phosphine-Resistant Pest R&D Collaboration | Dosage protocol development with Brazilian ANVISA-registered facilities addresses evolving pest pressures. |
Study Parameters
Document review covered customs and trade databases, SEC filings from agrochemical conglomerates, and Central Insecticides Board registration records, complemented by interviews with grain elevator operators, warehouse procurement managers, formulation plant engineers, and certified fumigation applicators. Secondary validation drew from EPA FIFRA enforcement data, EFSA residue limit consultations, and ANVISA import registration filings. Bottom-up volume estimates from tablet and pellet production capacities were triangulated against top-down demand projections from government warehouse procurement disclosures.
Historical procurement patterns from Indian Food Corporation of India and Brazilian CONAB storage programs were cross-referenced against panel input from equipment manufacturers and formulation distributors. Segmentation modeling covered formulation type, application protocol, end-user concentration, and regional regulatory cluster dimensions. CAGRs were derived from slope analysis of procurement volume trajectories across the analysis window, incorporating phosphine-resistant pest pressure indices and warehouse automation adoption curves as industry-specific forecast inputs.
Inputs from EPA enforcement databases and EFSA consultation records were available through the study window; gaps in private-label manufacturer production data introduce uncertainty bands around pellet formulation growth estimates. Forecasts reflect assumptions regarding REACH restriction timelines and Indian warehouse modernization appropriation continuity. Periodic stress-testing of base assumptions against ANVISA registration backlog trends and elemental phosphorus supply disruptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Immunochemicals Market
Chemicals
Silicone Textile Softeners Market
Chemicals
Calcium Hydride Market
Chemicals
Hypophosphorous Acid Market
Chemicals
Hydrophobing Agents Market
Chemicals
Middle East Construction Chemicals Market
Chemicals
Aluminum Chemicals Market
Chemicals
Ethylenediaminetetraacetic Acid Market
Chemicals
Global Biotechnology-Based Chemical Market
Chemicals
South America Construction Chemicals Market
Chemicals
3-Fluoro-5-Nitrotoluene Market
Chemicals
Oxybenzone Market
Chemicals
Global Syringaldehyde Market
Chemicals
Spirodiclofen Market
Chemicals
Diphosphate Market
Chemicals
Sodium Cyanide Market