
 Benzophenone (Oxybenzone) Market | 2026-2036
Benzophenone (Oxybenzone) Market Size, Share, and Industry Trends Forecast 2026-2036
Benzophenone (Oxybenzone) Market Outlook
Aftermarket service revenue around regulatory compliance consulting is reshaping how specialty chemical suppliers capture value beyond base product sales. BASF SE leverages its integrated polymer stabilization portfolio to cross-sell benzophenone variants into plastics and coatings applications. SONGWON Industrial Group anchors its position through backward integration into key phenol feedstocks, insulating margin pools from raw material volatility. Everspring Chemical Co., Ltd. competes on manufacturing scale out of Taiwan, serving regional personal care compounders with powder and liquid grades.
Benzophenone (Oxybenzone) denotes a class of aromatic ketones synthesized via Friedel-Crafts acylation of benzene with benzoyl chloride, characterized by conjugated carbonyl groups that absorb ultraviolet radiation in the 280-320 nanometer range. These compounds function primarily as photostabilizers in polymer systems and as UV filters in topical formulations, where their lipophilicity enables sustained epidermal retention. The personal care application segment carries the largest revenue footprint, though pharmaceutical-grade material commands superior unit economics due to stricter impurity profiles. Powder form dominates industrial procurement for polymer compounding, while cream and gel formulations concentrate in finished consumer goods where blending flexibility matters.
The European Chemicals Agency classifies certain benzophenone derivatives as substances of very high concern under REACH, compelling substitution strategies among EU-based formulators. The US FDA maintains benzophenone-3 as a permitted active ingredient in over-the-counter sunscreens while requiring concentration disclosures, preserving market access but elevating labeling compliance costs. China's Ministry of Ecology and Environment enforces discharge limits on benzophenone manufacturing effluents, raising capital requirements for domestic producers. Stakeholders must monitor divergent regulatory thresholds across jurisdictions to determine whether portfolio rationalization or geographic specialization delivers superior returns.
Market Dynamics
The European Commission's classification of benzophenone derivatives as endocrine-disrupting substances under REACH is forcing wholesale reformulation across personal care supply chains, compressing incumbent product lifecycles while opening substitution pathways for compliant alternatives.
Growth Catalysts
- Domestic sunscreen manufacturing in China:Local production capacity for UV-filter formulations has expanded substantially, absorbing benzophenone derivatives at volumes that now shape regional procurement patterns.
- REACH SVHC listing mechanics:The European Chemicals Agency's substance-of-very-high-concern designation process creates predictable compliance deadlines that manufacturers can anticipate and engineer around.
- Photostabilizer demand in polymer compounding:Packaging and automotive plastics manufacturers continue specifying benzophenone variants to prevent UV-induced degradation in finished goods.
Market Restraints
- Phenol feedstock volatility:Backward-integrated producers at SONGWON Industrial Group insulate margin pools from benzene and phenol price swings that squeeze non-integrated competitors.
- Substitution by mineral UV filters:Zinc oxide and titanium dioxide formulations are capturing share in premium personal care segments where clean-label positioning commands price premiums.
- Discharge limits from China's MEE:The Ministry of Ecology and Environment's effluent standards raise capital requirements for domestic producers without captive wastewater treatment infrastructure.
Strategic Opportunities
- Pharmaceutical-grade intermediate supply:Stricter impurity profiles for drug applications create unit economics superior to personal care grades, rewarding producers with GMP-certified manufacturing assets.
- Polymer stabilization cross-selling:Integrated suppliers leverage benzophenone portfolios to penetrate plastics and coatings applications beyond traditional sunscreen markets.
- Regulatory consulting services:Compliance advisory revenue streams are reshaping how specialty chemical suppliers capture value beyond base product transactions.
Industry Challenges
- Reformulation timeline compression:EU-based formulators face compressed development cycles to substitute benzophenone-3 ahead of regulatory deadlines without compromising SPF performance.
- Labeling compliance cost elevation:The US FDA's concentration disclosure requirements for over-the-counter sunscreens add administrative burden to product registration workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benzophenone (Oxybenzone) Market |
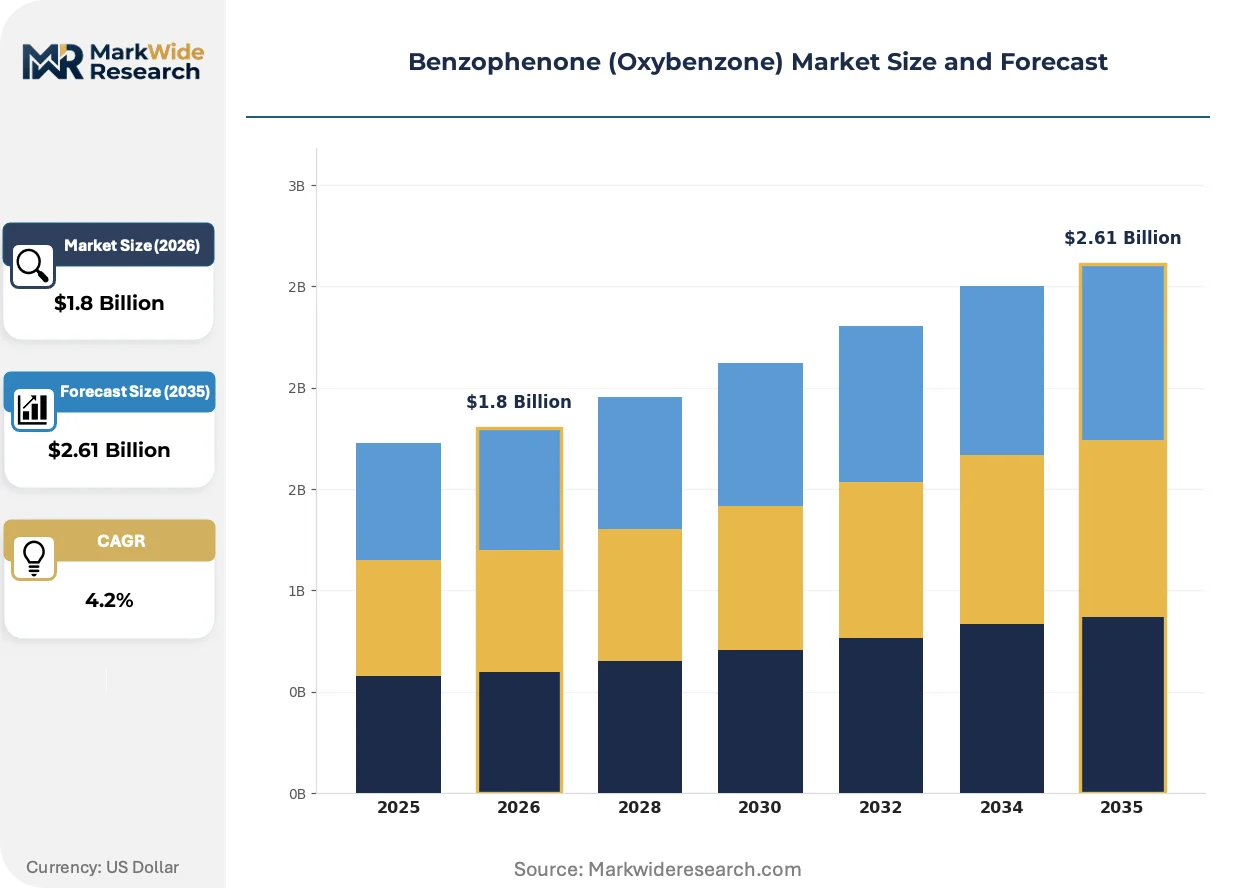
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sunscreen, Shampoo, Lip Balm, Cosmetics Application: Personal Care, Pharmaceuticals, Food Additives, Agricultural Form: Liquid, Powder, Gel, Cream End User: Manufacturers, Retailers, Consumers, Professionals |
| Companies Covered | SONGWON Industrial Group, Everspring Chemical Co., Ltd., Everlight Chemical Industrial Corp., ADEKA Corporation, Clariant AG, SI Group, Chitec Technology Co., Ltd., BASF SE, Rianlon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benzophenone (Oxybenzone) Market Strategic Shifts
Reformulation imperatives are accelerating investment in alternative UV-filter chemistries and process technologies that reduce benzophenone content while maintaining photoprotection efficacy in finished formulations.
Encapsulation technology for benzophenone-3 is migrating from niche pharmaceutical applications toward mainstream personal care manufacturing. Cosmetic compounders in South Korea and Japan are adopting microsphere delivery systems to reduce dermal penetration rates and address clean-label consumer preferences. This migration is compressing demand for conventional unencapsulated grades while creating specification premiums for advanced delivery formats.
REACH authorization procedures for benzophenone derivatives are tightening supply security requirements for EU-based manufacturers. The European Chemicals Agency's sunset date mechanics are forcing compounders to secure alternative sourcing or submit authorization applications with socioeconomic justifications. Personal care brands with pan-European distribution footprints are most affected, accelerating dual-track formulation strategies that maintain market access regardless of authorization outcomes.
Ingredient transparency preferences are reshaping procurement criteria among contract manufacturers serving North American and European personal care brands. Third-party certification programs for reef-safe and hormone-safe formulations are displacing conventional benzophenone specifications in premium product lines. This behavioral shift is most visible in direct-to-consumer sunscreen brands that use exclusionary ingredient lists as primary marketing differentiation.
Benzophenone (Oxybenzone) Market Segmentation
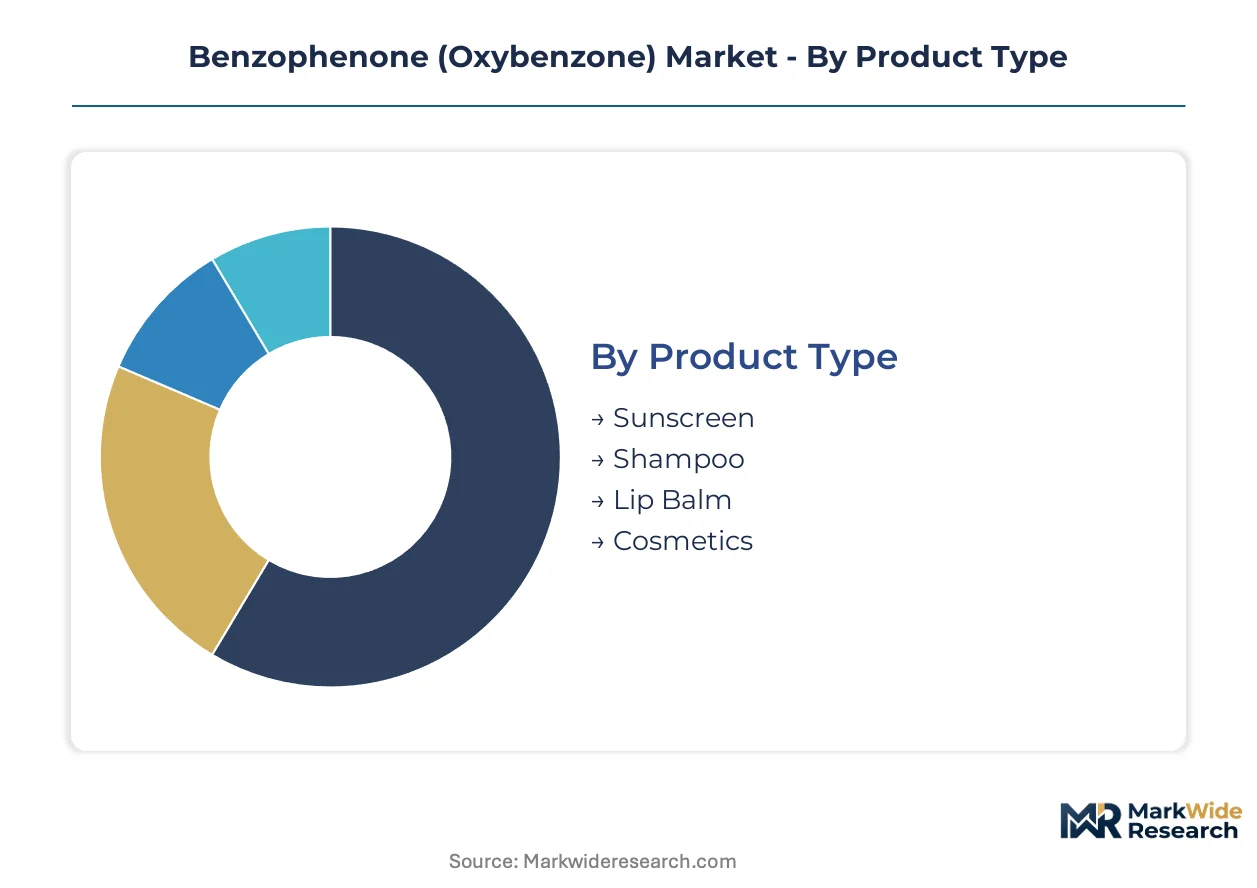
Segmentation in the benzophenone market reveals how regulatory pressure and formulation complexity fragment procurement patterns across distinct value chains. Each dimension exposes different margin structures, compliance burdens, and substitution vulnerabilities that suppliers must navigate.
Product Type:
Mature personal care applications anchor volume demand, while emerging clean-label categories reshape specification requirements.
- Sunscreen:Photoprotection formulations absorb the largest benzophenone-3 volumes, with SPF-rated products facing the most intense regulatory scrutiny from ECHA and FDA disclosure mandates. Chinese domestic manufacturers now supply the majority of regional demand for UV-filter compounding.
- Cosmetics:Color cosmetics and daily wear formulations specify benzophenone derivatives for photostability in packaging and product integrity. Premium brands in South Korea and Japan are migrating toward encapsulated grades to address dermal penetration concerns.
- Shampoo:Hair care applications leverage benzophenone-4 for product stability under UV exposure in transparent packaging.
- Lip Balm:Small-format protective products use lower concentrations due to ingestion risk profiles and stricter impurity thresholds.
Sunscreen handles the majority of throughput; cosmetics is gaining share fastest as encapsulation technology penetrates premium personal care lines.
Application:
Cost tier differentiation separates commodity-grade personal care supply from pharmaceutical-grade premium positioning.
- Personal Care:Sunscreen, cosmetics, and daily-use formulations constitute the baseline demand pool, with procurement concentrating among contract manufacturers serving multiple brand portfolios. REACH SVHC listings are forcing accelerated reformulation timelines across EU-based compounders.
- Pharmaceuticals:Drug intermediates and topical therapeutic applications command superior unit economics through GMP-certified manufacturing requirements and stringent impurity profiles. Production concentrates at facilities with dedicated pharmaceutical-grade isolation capabilities.
- Food Additives:Photostabilizer applications in food packaging films represent a niche but regulated specification segment.
- Agricultural:Crop protection formulations and greenhouse films use benzophenone variants for UV resistance in polymer-based agricultural infrastructure.
Personal Care handles the majority of throughput; Pharmaceuticals is climbing the fastest on margin expansion from certification requirements.
Form:
Volume scale separates industrial procurement patterns from finished goods flexibility requirements.
- Powder:Crystalline grades dominate polymer compounding and bulk pharmaceutical intermediate manufacturing, with specifications emphasizing particle size distribution and flow characteristics. Industrial buyers in China and Germany specify powder grades for high-throughput extrusion and blending operations.
- Liquid:Pre-dissolved solutions serve personal care compounders requiring rapid incorporation into emulsion systems without dissolution steps. Taiwan-based suppliers like Everspring Chemical capture regional demand through liquid grade distribution.
- Cream:Semi-solid preparations concentrate in finished consumer goods where viscosity and spreadability specifications matter.
- Gel:Transparent formulations target specific aesthetic requirements in premium skincare and clear sunscreen products.
Powder handles the majority of throughput; Liquid is expanding most quickly as contract manufacturers seek processing efficiency.
End User:
Customer type determines whether procurement emphasizes specification compliance, cost minimization, or formulation flexibility.
- Manufacturers:Brand-owning formulators and contract compounders drive specification development, with procurement decisions increasingly influenced by regulatory compliance service offerings from chemical suppliers. BASF SE and SONGWON Industrial Group compete through integrated technical support and reformulation consulting.
- Retailers:Private-label program managers and distribution intermediaries consolidate demand across multiple brand portfolios, emphasizing supply security and documentation standardization.
- Consumers:Direct purchasing concentrates in specialty and professional channels with ingredient transparency requirements.
- Professionals:Dermatology clinics and aesthetic medicine providers specify pharmaceutical-grade materials for compounded preparations.
Manufacturers handle the majority of throughput; Retailers are gaining share fastest as private-label sunscreen programs expand across North American and European distribution networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers absorb benzophenone volumes with minimal price elasticity, while European formulators face steep substitution costs from REACH-driven reformulation. Indian pharmaceutical intermediates demand exhibits intermediate sensitivity, and North American procurement balances specification compliance against mineral-filter alternatives.
China
Domestic sunscreen manufacturing and pharmaceutical intermediate production drive benzophenone absorption at volumes shaping regional procurement patterns. The Ministry of Ecology and Environment enforces discharge limits on manufacturing effluents, raising capital requirements for producers lacking captive wastewater infrastructure. Manufacturing clusters in Jiangsu and Zhejiang provinces host integrated phenol-to-benzophenone operations serving both personal care compounders and polymer stabilizer markets.
Germany
REACH SVHC listings for endocrine-disrupting properties compress product lifecycles while opening substitution pathways for compliant alternatives. The European Chemicals Agency's authorization procedures force compounders to secure alternative sourcing or submit socioeconomic justifications ahead of sunset dates. Industrial chemical parks along the Rhine corridor concentrate reformulation consulting services and GMP-certified pharmaceutical-grade production.
United States
FDA concentration disclosure requirements for over-the-counter sunscreens preserve market access while elevating labeling compliance costs. The agency maintains benzophenone-3 as a permitted active ingredient, sustaining demand against state-level reef-safe restrictions in Hawaii and Key West. New Jersey and Texas host polymer stabilization compounding operations specifying powder grades for packaging and automotive plastics.
South Korea
Cosmetic compounders adopt microsphere delivery systems to reduce dermal penetration rates and address clean-label consumer preferences. The Ministry of Food and Drug Safety oversees UV-filter safety assessments, creating predictable regulatory timelines for formulation registration. Seoul metropolitan area manufacturers concentrate encapsulation technology development for premium skincare exports.
India
Pharmaceutical-grade intermediate demand climbs on stricter impurity profiles and GMP certification requirements for drug applications. The Central Drugs Standard Control Organization regulates topical therapeutic formulations, separating compliant from commodity-grade supply tiers. Gujarat and Maharashtra pharmaceutical clusters drive specification premiums through dedicated isolation capabilities and API manufacturing integration.
Benzophenone (Oxybenzone) Market Competitive Environment
Capability concentration sits with integrated phenol producers; scale advantage sits with regional compounders serving contract manufacturers. The market structures around three tiers: backward-integrated chemical conglomerates, specialist UV-filter manufacturers, and regional distributors with blending capabilities. Dominant competitive moves include cross-selling polymer stabilization portfolios and building regulatory consulting revenue streams beyond base product transactions.
Within the integrated chemical tier, BASF SE and SONGWON Industrial Group exemplify producers leveraging captive feedstock control and multi-application portfolios. Everspring Chemical Co., Ltd. occupies a position among Taiwan-based specialists serving regional personal care compounders with differentiated form factors. These three anchors illustrate how geographic specialization and manufacturing format flexibility separate competitive positions in a market pressured by regulatory divergence.
| Leading Market Players |
|---|
| SONGWON Industrial Group |
| Everspring Chemical Co., Ltd. |
| Everlight Chemical Industrial Corp. |
| ADEKA Corporation |
| Clariant AG |
| SI Group |
| Chitec Technology Co., Ltd. |
| BASF SE |
| Rianlon Corporation |
| Others |
Value Chain & Pricing Dynamics
Integrated phenol production in China and South Korea captures upstream margin pools that downstream formulators in Europe and North America struggle to reclaim. Benzene and phenol feedstock control at SONGWON Industrial Group and regional Chinese producers enables cost structures that commodity traders and non-integrated compounders cannot match.
Pricing Analysis
Regulatory compliance consulting revenue streams now drive lifetime value beyond base chemical transactions. Three-tier pricing structure across pharmaceutical-grade, personal care-grade, and industrial-grade levels separates GMP-certified premiums from commodity spot markets. Cost compression in personal care grades intensifies as mineral UV filter substitution accelerates in premium segments. Contract manufacturers serving European brands exhibit highest price sensitivity due to reformulation timeline pressures, while pharmaceutical intermediates buyers absorb premiums for impurity-controlled supply security.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for EU-based formulators. Manufacturing concentrates in China, Taiwan, and Germany, with benzene and phenol feedstock sourcing anchoring cost structures. Single-source vulnerability runs through Jiangsu and Zhejiang province clusters where MEE discharge enforcement raises capital barriers. Distribution runs through regional chemical distributors with blending capabilities and direct technical service relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization mechanics transform benzophenone supply into a platform-economics inflection where regulatory data access separates sustainable suppliers from stranded capacity. ECHA sunset date transparency enables predictable ecosystem coordination between compounders and authorization holders.
For Market Incumbents: Harden regulatory consulting capabilities to capture recurring revenue streams as base product margins compress from substitution pressure. Deepen backward integration into phenol feedstock to insulate margin pools from benzene price volatility that squeezes non-integrated competitors. Prioritize GMP certification investments for pharmaceutical-grade positioning where unit economics remain defensible. For New Entrants and Emerging Players: Encapsulation technology supply to South Korean and Japanese cosmetic compounders represents the most penetrable entry point for differentiated UV-filter delivery systems. Pharmaceutical-grade intermediate manufacturing in India offers white-space expansion with CDSCO regulatory alignment as a go-to-market anchor. Clean-label contract manufacturing services for North American direct-to-consumer brands provide channel access without incumbent reformulation legacy burdens. For Investors and Strategic Acquirers: Secondary-cycle assets sit with Taiwan-based UV-filter specialists holding regional distribution relationships but lacking global regulatory dossier depth. Long-term viability hinges on authorization portfolio breadth under REACH sunset mechanics rather than manufacturing scale alone. Watch ECHA authorization application submission rates as the inflection signal separating sustainable from stranded capacity positions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol Feedstock | Captive benzene supply at SONGWON Industrial Group insulates margin pools from raw material volatility. |
| REACH Authorization Dossier Investment | ECHA submission capabilities preserve EU market access against sunset date mechanics. |
| Encapsulation Technology Licensing | Microsphere delivery systems address clean-label preferences in South Korean cosmetic exports. |
| GMP Certification for Pharmaceutical Grade | Stricter impurity profiles at CDSCO-regulated Indian facilities command superior unit economics. |
| Regulatory Consulting Service Launch | Compliance advisory revenue reshapes value capture beyond base benzophenone transactions. |
Study Parameters
Cross-validation between primary interviews with chemical plant managers, procurement leads at personal care compounders, distribution channel partners, and technical R&D directors anchors the qualitative findings. Secondary sources include customs and trade data, Cefic sector reports, SEC 10-K filings, and ECHA authorization databases. Bottom-up volume modeling triangulates against top-down value estimates derived from feedstock cost structures and grade-specific margin analysis.
Calibration against historical REACH SVHC listing impacts and FDA disclosure implementation timelines validates projection assumptions across the analysis window. Segmentation dimensions include product grade tier, end-use application, form factor, and regional regulatory cluster. CAGRs derive from fitted growth curves incorporating phenol feedstock cost trajectories, substitution elasticity estimates, and authorization timeline probabilities.
Practitioners should monitor ECHA authorization application submission rates and mineral UV filter patent filing velocities for early signals of structural demand shifts. Forecasts reflect assumptions around regulatory timeline adherence and feedstock cost stability that operating reality may revise. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Automotive Appearance Chemicals Market
Chemicals
Leather Tanning Chemicals Market
Chemicals
Periodic Acid Market
Chemicals
Hexamethylenetetramine (HMTA) Market
Chemicals
Spirodiclofen Market
Chemicals
Tributyl Phosphate Market
Chemicals
India Ethoxylates Market
Chemicals
Ferric Oxide Market
Chemicals
Methylamines Market
Chemicals
China Methanol Market
Chemicals
Trifluoroacetic Acid (TFA) Market
Chemicals
Global Methylene Chloride Market
Chemicals
Ethylenediaminetetraacetic Acid Market
Chemicals
Xanthates Market
Chemicals
Europe Calcium Peroxide Market
Chemicals
Fireworks Market