
 Glycine Soja (Soybean) Seed Extract Market | 2026-2036
Glycine Soja (Soybean) Seed Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Glycine Soja (Soybean) Seed Extract Market Foresight
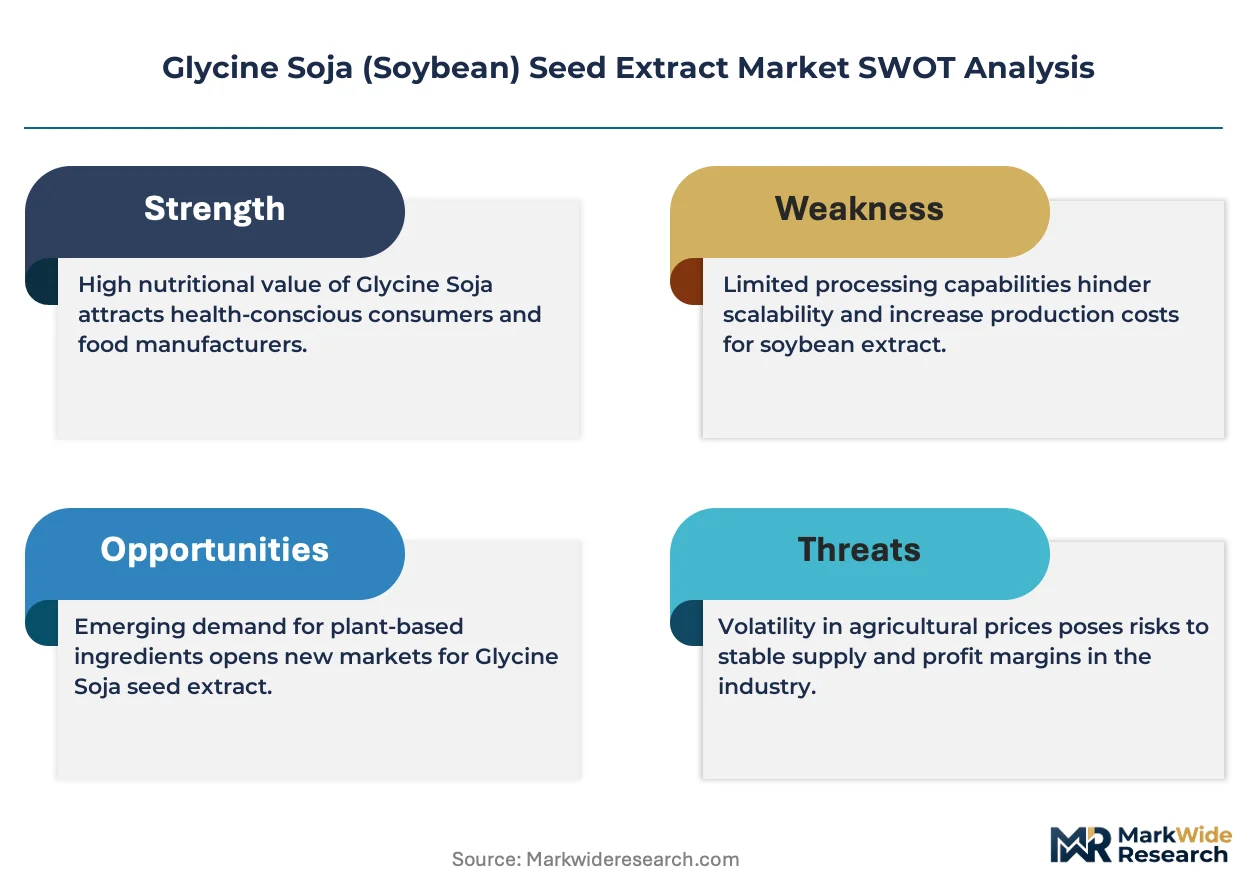
REACH compliance is broadening the cost-of-entry calculus for new suppliers of Glycine Soja seed extract, forcing investment in certified purification and traceability infrastructure. Symrise AG leverages its integrated botanical supply chain to sustain European market access under evolving chemical safety mandates. BASF SE anchors its position through proprietary extraction technologies that yield consistent isoflavone profiles. Cargill Incorporated dominates North American raw material flows with backward integration into identity-preserved soybean crushing.
Glycine Soja seed extract comprises lipophilic and hydrophilic fractions derived from dehulled soybean seeds, typically standardized for isoflavone content ranging from 10% to 40% depending on intended application, and serves primarily as an emollient, antioxidant, and protein source across cosmetic, nutritional, and feed formulations. The organic extract category commands premium positioning in personal care formulations where ECHA-compliant ingredient transparency influences brand purchasing decisions. Cosmetics applications lead volume absorption, while nutraceuticals represent the fastest-expanding consumption pool as dietary supplement manufacturers seek plant-derived protein alternatives to animal-sourced inputs.
The US FDA governs extract labeling and GRAS determinations for food additive applications, while ECHA administers REACH registration requirements that constrain import eligibility for non-European suppliers. China's SAMR enforces GB standards for botanical extracts entering the domestic nutraceutical channel, creating divergent compliance pathways for multinational suppliers. Stakeholders must monitor regulatory harmonization pressures between these frameworks as they evaluate regional manufacturing footprints and certification investments.
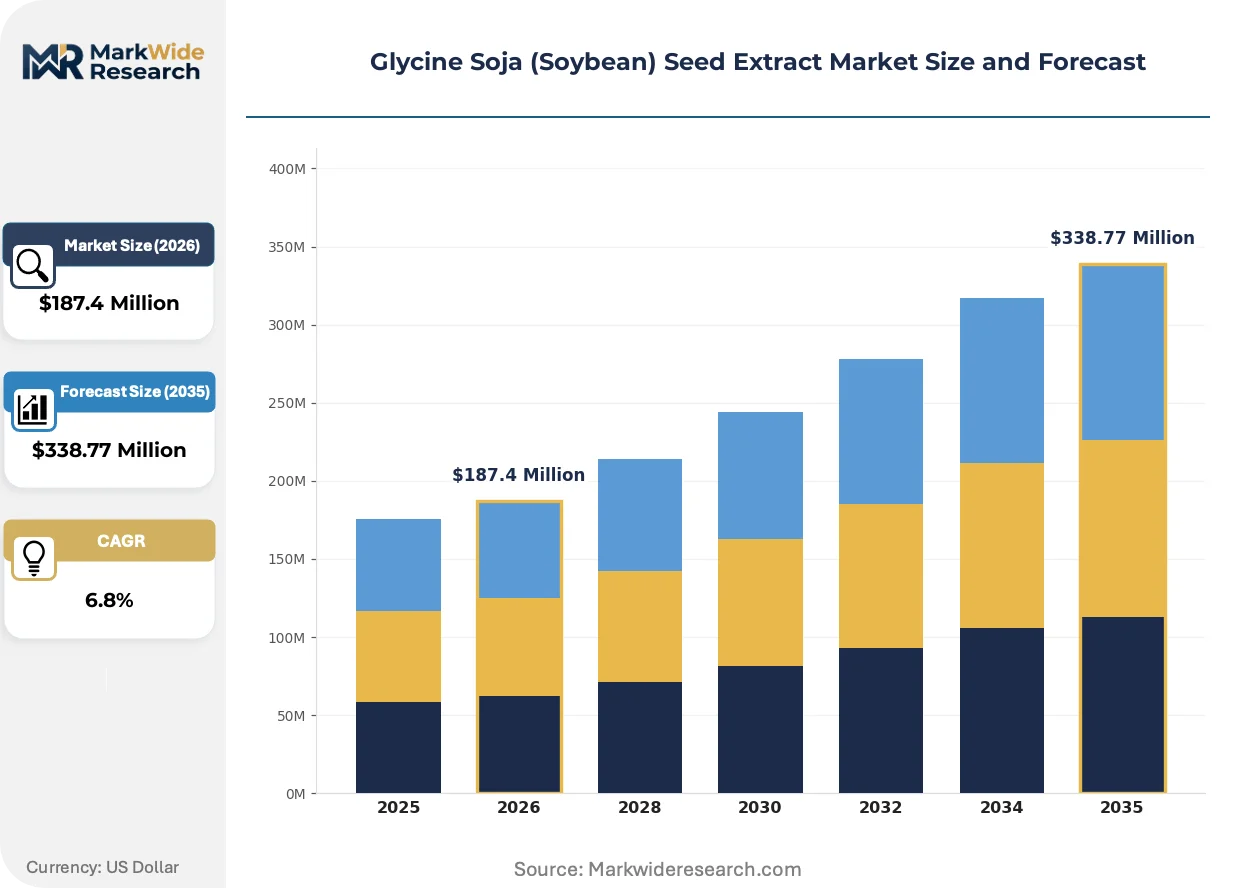
Market Dynamics
REACH registration requirements in Europe are forcing purification infrastructure investments that reshape supplier economics, while K-beauty procurement concentrates demand for certified organic grades in South Korea.
Growth Catalysts
- Clean-label cosmetics mandate:ECHA-compliant ingredient transparency requirements in Europe drive reformulation toward botanical actives with verifiable supply chains.
- South Korea K-beauty expansion:Seoul-based brands actively substitute synthetic emollients with plant-derived alternatives, concentrating procurement of standardized isoflavone extracts.
- Supercritical CO2 extraction:This solvent-free technology preserves thermolabile isoflavones for high-purity cosmetic applications, displacing conventional hexane-based processing.
Market Restraints
- Identity-preserved soybean premiums:Non-GMO and organic feedstock requirements inflate raw material costs by 15-40% versus commodity soybeans.
- Chinese supply concentration:Over 60% of global botanical extract processing capacity resides in Shandong and Jiangsu provinces, creating geopolitical and logistics vulnerability.
- Isoflavone bioavailability limits:Poor water solubility of aglycone forms constrains nutraceutical formulation efficacy without microencapsulation investments.
Strategic Opportunities
- India nutraceutical channel:FSSAI's streamlined botanical ingredient approvals open dietary supplement applications for protein-fortified products.
- Upcycled okara streams:Soymilk processing waste represents an underutilized isoflavone source for cost-competitive cosmetic-grade extraction.
- EU Green Deal bioeconomy incentives:Horizon Europe funding favors circular extraction technologies that valorize agricultural side streams.
Industry Challenges
- Analytical chemist scarcity:Qualified personnel for HPLC-based isoflavone standardization and contaminant screening command 30-50% salary premiums.
- Multi-jurisdiction dossier compilation:Parallel FDA GRAS, ECHA REACH, and SAMR GB standard submissions strain regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glycine Soja (Soybean) Seed Extract Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Extract, Conventional Extract, Powder Form, Liquid Form Application: Cosmetics, Food Additives, Nutraceuticals, Animal Feed End User: Food Industry, Personal Care Industry, Dietary Supplement Manufacturers, Veterinary Sector Distribution Channel: Online Stores, Specialty Retailers, Wholesale Distributors, Direct Sales |
| Companies Covered | Symrise AG, BASF SE, Cargill Incorporated, Archer Daniels Midland Company, Grau Aromatics GmbH & Co. KG, Lucas Meyer Cosmetics, Evonik Industries AG, DowDuPont, Givaudan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glycine Soja (Soybean) Seed Extract Market Shifts & Advancements
Extraction technology convergence and regulatory transparency mandates are compressing traditional supplier margins while rewarding integrated traceability systems.
Membrane filtration is modularizing downstream purification workflows for Glycine Soja seed extract processors. Mid-sized cosmetic ingredient suppliers in Germany and Italy adopt skid-mounted nanofiltration units to achieve ECHA-compliant purity thresholds without capital-intensive chromatography suites. This technology compression enables regional players to contest volume positions previously held by integrated multinationals.
REACH SVHC candidate list expansions are tightening impurity thresholds for botanical cosmetic ingredients entering European formulations. ECHA's 2024-2025 updates place additional phytosterol oxidation products under scrutiny, forcing extractors to validate degradation kinetics across storage conditions. Cosmetic brands respond by demanding batch-specific stability data, shifting procurement criteria from price-per-kilogram to total cost of compliance.
Direct-to-brand ingredient sourcing is displacing traditional distributor intermediaries in the personal care channel. Seoul and Los Angeles-based cosmetic formulators now contract directly with Shandong and Iowa extraction facilities for identity-preserved supply, bypassing regional chemical distributors. This channel compression concentrates volume with suppliers capable of dual-language documentation and real-time chain-of-custody verification.
Glycine Soja (Soybean) Seed Extract Market Segmentation
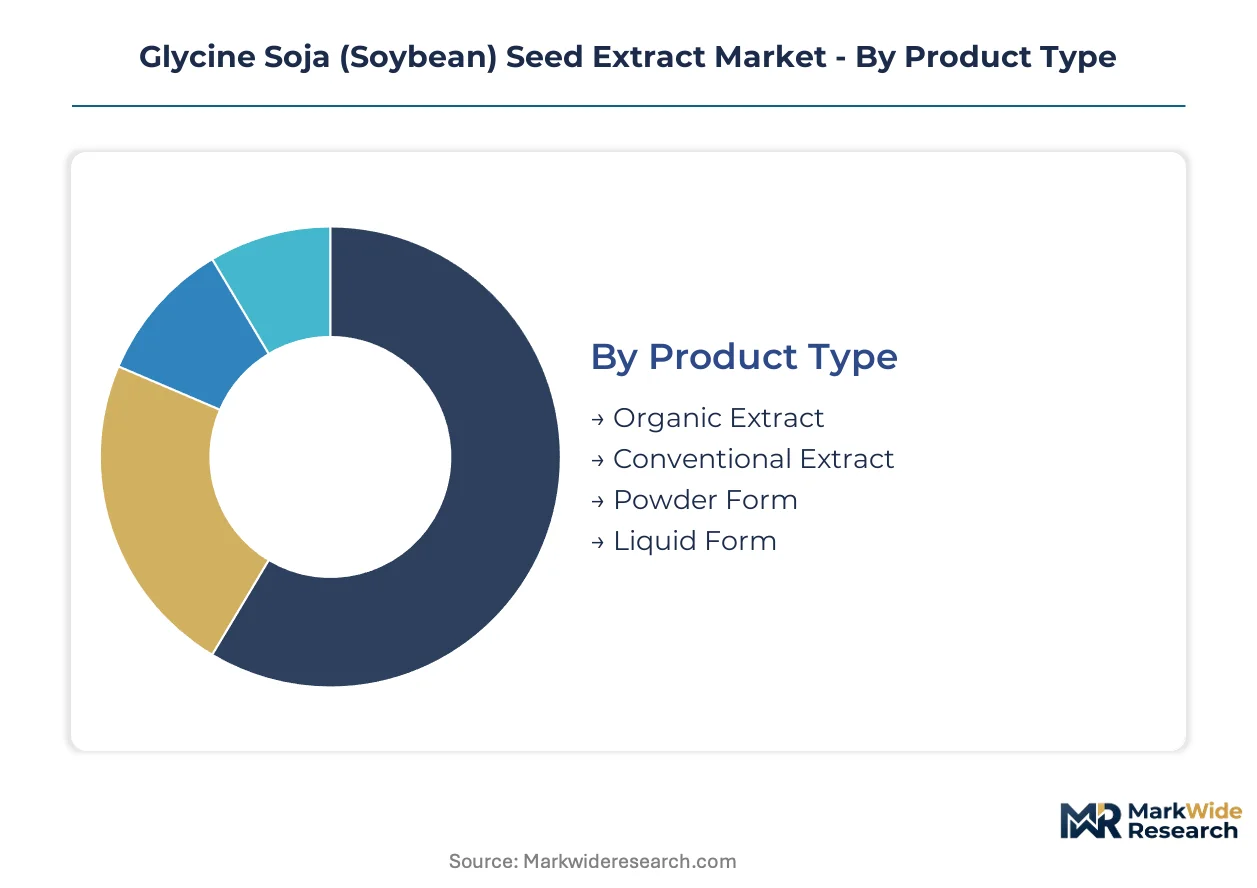
Procurement patterns for Glycine Soja seed extract diverge sharply across purity grades and end-use specifications. Formulators in Seoul and Los Angeles now demand batch-specific isoflavone certificates that reshape how suppliers structure their product hierarchies.
Product Type:
Upgrade cycles from conventional to certified organic grades are shortening as ECHA transparency mandates tighten procurement criteria for European cosmetic brands.
- Organic Extract:Certified organic grades command 15-40% feedstock premiums and require identity-preserved soybean traceability. Personal care formulators in Germany and South Korea concentrate procurement here as ECHA-compliant ingredient transparency becomes non-negotiable for market access.
- Conventional Extract:Hexane-processed conventional extracts retain cost advantages for mass-market cosmetic and feed applications. North American crushing operations supply this tier through backward integration into commodity soybean flows.
- Powder Form:Spray-dried powders suit nutraceutical encapsulation and protein fortification workflows.
- Liquid Form:Glycerin-based liquid extracts dominate cosmetic serum and emulsion formulations.
Organic Extract sits at the top of the volume ranking, with Powder Form climbing the fastest.
Application:
Margin structures vary dramatically across application tiers, with cosmetic-grade purification investments separating premium from commodity positioning.
- Cosmetics:Skin-conditioning and antioxidant applications drive supercritical CO2 extraction adoption for thermolabile isoflavone preservation. Seoul-based K-beauty brands actively reformulate with plant-derived emollients, concentrating demand for standardized 20-40% isoflavone extracts.
- Nutraceuticals:Dietary supplement manufacturers seek plant-derived protein alternatives, expanding aglycone and glycoside isoflavone demand for menopausal health and bone density formulations. Microencapsulation investments address bioavailability constraints.
- Food Additives:GRAS-designated extracts enter functional food fortification under FDA oversight.
- Animal Feed:Protein concentrate applications in aquaculture and poultry nutrition favor cost-optimized conventional grades.
Cosmetics captures the largest revenue share, while Nutraceuticals expands most quickly as protein alternatives displace animal-sourced inputs.
End User:
Customer-type concentration is reshaping channel economics, with direct-to-brand sourcing displacing traditional distributor intermediaries for qualified suppliers.
- Personal Care Industry:Cosmetic formulators in Los Angeles and Seoul now contract directly with Iowa and Shandong extraction facilities, bypassing regional chemical distributors. Dual-language documentation and real-time chain-of-custody verification determine supplier selection.
- Dietary Supplement Manufacturers:Protein-fortified product developers in India leverage FSSAI's streamlined botanical approvals to expand plant-derived formulation pipelines.
- Food Industry:Functional food developers utilize GRAS-determined extracts for clean-label positioning.
- Veterinary Sector:Aquaculture feed compounders source cost-competitive protein concentrates.
Personal Care Industry dominates procurement volume, with Dietary Supplement Manufacturers gaining share fastest on regulatory streamlining.
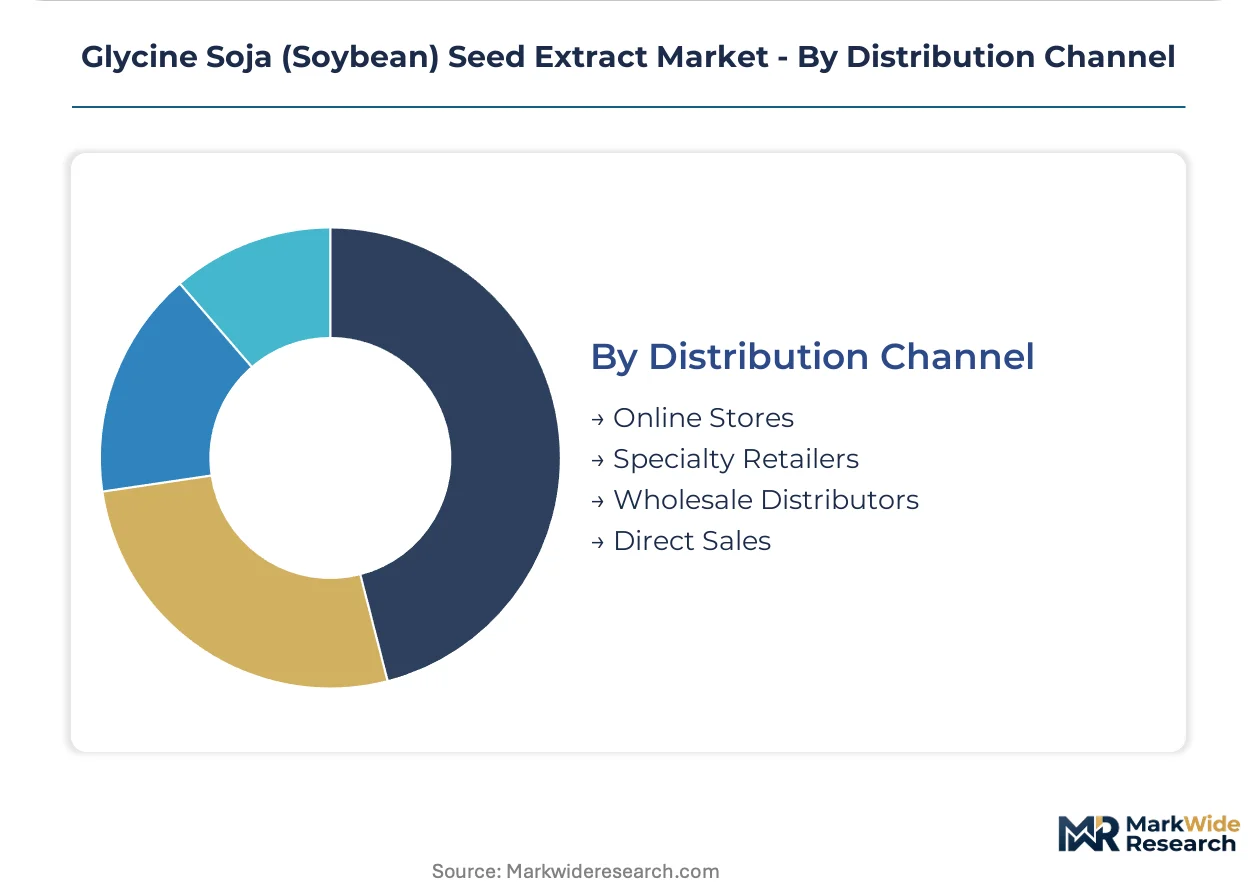
Distribution Channel:
Supply concentration in Shandong and Jiangsu provinces creates logistics vulnerability that channel selection must mitigate.
- Direct Sales:Extraction facilities in Iowa and Shandong build direct relationships with cosmetic formulators, offering real-time batch documentation and stability data that distributors cannot match. This channel compression rewards integrated traceability systems.
- Wholesale Distributors:Traditional chemical distributors retain relevance for mid-sized nutraceutical and feed compounders lacking procurement scale for direct contracts.
- Online Stores:E-commerce platforms serve small-batch cosmetic startups and research institutions.
- Specialty Retailers:Niche botanical suppliers target premium organic personal care brands.
Direct Sales leads channel volume, with Online Stores expanding fastest on startup formulation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soybean cultivation and extraction infrastructure originated in East Asia before industrial-scale processing migrated to North America and Europe. Contemporary demand concentrates in cosmetic formulation clusters across South Korea, Germany, and the United States, with regulatory divergence shaping regional procurement patterns.
South Korea
Seoul-based K-beauty brands drive premium-grade isoflavone extract procurement for skin-conditioning formulations. MFDS cosmetic ingredient notifications enforce batch-specific stability documentation for botanical actives. The Seoul Capital Area hosts concentrated R&D facilities where formulators substitute synthetic emollients with plant-derived alternatives.
Germany
ECHA REACH compliance mandates tighten purity thresholds for cosmetic-grade extracts entering European formulations. The EU Green Deal channels Horizon Europe funding toward circular extraction technologies valorizing agricultural side streams. Industrial clusters in North Rhine-Westphalia and Bavaria integrate membrane filtration systems to achieve contaminant screening without capital-intensive chromatography.
United States
Identity-preserved soybean crushing operations in Iowa and Illinois supply non-GMO feedstock for premium cosmetic applications. FDA GRAS determinations govern food additive pathways while state-level organic certification programs create parallel compliance tracks. Midwest extraction facilities build direct relationships with Los Angeles cosmetic formulators, bypassing traditional distributor intermediaries.
China
Shandong and Jiangsu provinces host over sixty percent of global botanical extract processing capacity, creating concentrated supply-side vulnerability. SAMR GB standards enforce divergent compliance pathways for nutraceutical channel entry versus cosmetic applications. Yangtze River Delta processors face escalating ECHA documentation demands for European export eligibility.
India
FSSAI streamlined botanical ingredient approvals accelerate dietary supplement applications for protein-fortified products. Maharashtra and Gujarat extraction facilities serve domestic nutraceutical compounders seeking plant-derived alternatives to animal-sourced inputs. Regulatory harmonization pressures between Indian, European, and American frameworks strain multinational dossier compilation bandwidth.
Glycine Soja (Soybean) Seed Extract Market Competitive Landscape
The competitive structure tilts toward integrated multinationals with captive supply chains and certified purification infrastructure. Tier-one positions concentrate with chemical conglomerates possessing backward integration into identity-preserved soybean sourcing and proprietary extraction technologies. Three archetypes dominate: integrated agribusiness-crushing operators, specialty chemical houses with botanical extraction divisions, and regional mid-tier processors leveraging modular membrane filtration. Capacity expansion and direct-to-brand channel compression represent the dominant competitive moves reshaping supplier economics.
Among German-based specialty chemical houses, Symrise AG and BASF SE exemplify archetypes combining integrated botanical supply chains with REACH-compliant purification infrastructure. Cargill Incorporated anchors the agribusiness-crushing operator category through upstream control over North American identity-preserved soybean flows. These three entities represent distinct strategic positions: chemical conglomerate with extraction technology specialization, diversified specialty chemicals player with cosmetic ingredient focus, and agricultural processor with downstream extraction capabilities.
| Leading Market Players |
|---|
| Symrise AG |
| BASF SE |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Grau Aromatics GmbH & Co. KG |
| Lucas Meyer Cosmetics |
| Evonik Industries AG |
| DowDuPont |
| Givaudan |
| Others |
Supply & Pricing Matrix
CBOT soybean futures volatility cascades through extraction economics into three distinct pricing tiers for Glycine Soja seed extract. Identity-preserved organic feedstock premiums compound with ECHA compliance costs to stratify supplier margins across premium cosmetic, standard nutraceutical, and economy feed applications.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs supplier positioning. Premium tiers hinge on certified organic traceability and supercritical CO2 extraction credentials; standard grades compete on volume scale for nutraceutical encapsulation; economy segments serve feed compounders with hexane-processed conventional extracts. Cost compression in the standard tier intensifies because Chinese processors are expanding membrane filtration capacity. Feed manufacturers exhibit highest price sensitivity, while Seoul-based K-beauty formulators absorb premiums for batch-specific stability documentation.
Supply Chain Analysis
Skilled analytical chemist shortages in Shandong and Jiangsu provinces constrain quality-control throughput for export-grade extracts. Global supply draws from identity-preserved soybean crushing in Iowa and Illinois, supercritical extraction equipment manufacturing in Germany and Italy, and downstream formulation clusters in South Korea and California. Single-source vulnerability concentrates in Yangtze River Delta processing hubs where over sixty percent of botanical extraction capacity resides. Distribution runs through direct-to-brand contracts for qualified suppliers, bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glycine Soja seed extract functions as a stable compounder anchored by persistent K-beauty procurement and clean-label cosmetics mandates across European and North American personal care markets.
For Market Incumbents: Hedge against Chinese supply concentration by diversifying extraction partnerships into Maharashtra and Gujarat facilities serving FSSAI-compliant nutraceutical channels. Invest in certified organic traceability infrastructure to defend margin position as ECHA SVHC candidate list expansions tighten impurity thresholds. Prioritize membrane filtration modularization over capital-intensive chromatography suites to maintain cost competitiveness against mid-tier regional processors. For New Entrants and Emerging Players: Capture white-space in upcycled okara stream valorization for cost-competitive cosmetic-grade isoflavone extraction. Target India's dietary supplement channel where FSSAI streamlined approvals reduce regulatory barriers to protein-fortified product entry. Lead with circular extraction technology positioning to access EU Green Deal Horizon Europe funding and differentiate from incumbent hexane-based processors. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier German and Italian membrane filtration specialists possessing ECHA-compliant purification infrastructure and direct relationships with Los Angeles cosmetic formulators. Long-term viability rests on sustained regulatory divergence between REACH, FDA GRAS, and SAMR GB frameworks that rewards multi-jurisdiction dossier compilation capabilities. Monitor ECHA candidate list publication cadence for early signals of impurity threshold tightening that would accelerate incumbent compliance investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Identity-Preserved Soybean Sourcing | Cargill's Iowa crushing operations secure non-GMO feedstock premiums for cosmetic-grade extraction. |
| Membrane Filtration Technology Adoption | Symrise AG's nanofiltration units achieve REACH purity thresholds without chromatography capital intensity. |
| Direct-to-Brand Channel Development | BASF SE's real-time batch documentation bypasses distributor intermediaries for Seoul formulators. |
| Upcycled Feedstock Valorization | EU Green Deal funding favors circular extraction from soymilk processing waste streams. |
| Multi-Jurisdiction Regulatory Certification | Dual FDA-ECHA dossier capability opens parallel cosmetic and nutraceutical market access. |
Research Methodology
Multiple input streams — extraction facility production data, customs trade flows, and regulatory filing documentation — were reconciled through bottom-up and top-down triangulation. Primary interviews with botanical extraction plant managers, cosmetic formulation R&D directors, and dietary supplement procurement leads informed capacity utilization and pricing dynamics. Secondary validation drew from ECHA REACH registration databases, FDA GRAS determination notices, FSSAI approval registers, and SEC 10-K disclosures from listed chemical conglomerates.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include organic versus conventional grade tiers, cosmetics versus nutraceutical versus feed end-use industries, and regional production hub clusters in Iowa, Shandong, and North Rhine-Westphalia. CAGRs were derived from volume-demand elasticity analysis against soybean feedstock price indices and isoflavone standardization cost curves.
Regulatory harmonization pressures, Chinese processing capacity expansion, and K-beauty procurement cyclicality are the dominant revision risks to forecast assumptions. Practitioners should monitor ECHA SVHC candidate list updates, Yangtze River Delta logistics disruptions, and Seoul-based brand reformulation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Middle East and Africa Cannabis Seeds Market
Seeds
Africa Grain Seed Market
Seeds
Cherry Tomato Seeds Market
Seeds
Nepal Seeds Market
Seeds
Africa Chia Seeds Market
Seeds
North America Alfalfa Seed Market
Seeds
Asia-Pacific Cotton Seed Market
Seeds
Global Forage Sorghum Seed Market
Seeds
Vietnam Seed Market
Seeds
Organic Chia Seeds Market
Seeds
Americas Seeds Market
Seeds
Europe Quinoa Seed Market
Seeds
Field Crop Seeds Market
Seeds
Global Forage Seeds Market
Seeds
Guar Market
Seeds
Southeast Asia Vegetable Seed Market