
 Field Crop Seeds Market | 2026-2036
Field Crop Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Field Crop Seeds Market Foresight
Multi-source germplasm licensing is shifting from concentrated patent holders toward broader research collaborations. Bayer Crop Science leverages its digital farming platform to integrate seed prescriptions with crop protection bundles. Corteva sustains one of the industry's largest proprietary breeding networks across multiple climate zones. Syngenta competes through advanced trait-stacking capabilities in corn and soybean genetics.
Field crop seeds comprise sexually propagated planting material bred for agronomic performance, typically specified by germination rate, genetic purity percentage, and trait expression stability under variable moisture and temperature regimes. Their commercial purpose centers on yield optimization, pest resistance, and climate adaptation for large-scale carbohydrate and protein production. Herbicide-tolerant and insect-resistant traits dominate volume shipments, while organic and drought-tolerant categories capture expanding margin pools as water stress intensifies across major production belts. Corn and soybean seed lines anchor revenue concentration due to their global acreage footprint and intensive input economics.
The EPA regulates plant-incorporated protectants as pesticides under FIFRA, requiring extensive environmental and food safety data before commercial release of biotech seed traits. The USDA oversees seed certification standards and interstate movement rules that govern market access for new varieties. China's MEE enforces biosafety protocols for imported germplasm that shape multinational breeding program priorities. Stakeholders must monitor evolving gene-editing regulatory classifications across major seed import jurisdictions to anticipate compliance cost structures and trait approval timelines.
Market Dynamics
Gene-editing regulatory reclassifications across major import jurisdictions are forcing seed developers to restructure trait approval timelines and compliance cost models. The EU Green Deal's Farm to Fork strategy compresses input allowances while Brazil's Cerrado expansion accelerates no-till system adoption.
Growth Catalysts
- EU Green Deal Farm to Fork:The strategy tightens pesticide and fertilizer input ceilings, redirecting R&D investment toward drought-tolerant and organic-certified trait portfolios that command premium positioning.
- Digital farming integration:Bayer Crop Science leverages its FieldView platform to bundle seed prescriptions with crop protection analytics, locking in multi-year grower contracts through data-driven yield optimization.
- Brazil Cerrado expansion:No-till soybean systems in this frontier zone require specialized seed coatings and rhizobia inoculation formulations, creating dedicated product lines for tropical soil conditions.
Market Restraints
- Concentrated germplasm patenting:Four multinationals control foundational CRISPR and RNAi trait platforms, restricting independent breeders' access to stacked-resistance genetics.
- Phosphate and potash volatility:Fertilizer cost spikes directly compress seed treatment margins, as growers defer premium biotech purchases during input price shocks.
- China MEE biosafety protocols:Extended environmental release trials for imported germplasm delay variety registration by 18-24 months, freezing revenue recognition on developed markets.
Strategic Opportunities
- Sub-Saharan Africa underpenetration:Commercial hybrid maize adoption sits below 15 percent across Kenya, Nigeria, and Ethiopia, opening distribution partnerships with national agricultural extension services.
- Carbon credit stacking:USDA Climate-Smart Commodities grants incentivize cover crop seed blends that sequester soil carbon, creating dual-revenue streams from grain and environmental credit markets.
- Gene-editing regulatory convergence:OECD harmonization discussions on SDN-1 classification could collapse multi-jurisdiction approval costs, accelerating trait pipeline velocity for developers with pre-positioned dossiers.
Industry Challenges
- Quantitative genetics talent scarcity:Computational breeding programs compete with tech sector data science salaries, constraining genomic selection model development at mid-tier seed houses.
- Trait purity certification timelines:OECD seed schemes require three generations of field isolation for genetic purity verification, delaying commercial launch windows for novel stacked varieties.
- Legacy inventory write-downs:Rapid regulatory shifts on neonicotinoid seed treatments force destruction of treated stockpiles, hitting working capital cycles for distributors with aged inventory positions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Field Crop Seeds Market |
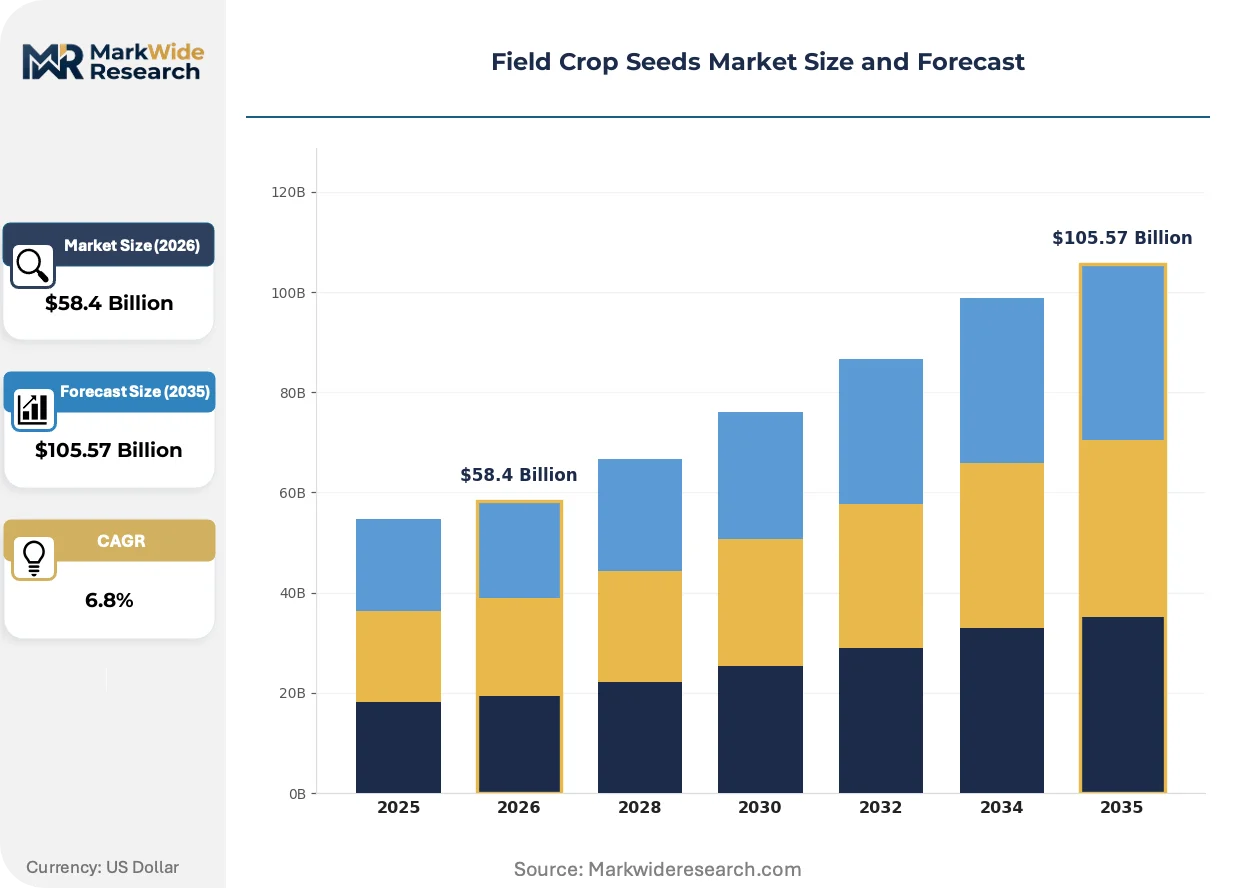
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $105.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat, Corn, Soybean, Barley Trait: Herbicide-Tolerant, Insect-Resistant, Drought-Tolerant, Organic Distribution Channel: Direct Sales, Retail, E-commerce, Agricultural Cooperatives End Use: Commercial Farming, Subsistence Farming, Research, Seed Banks |
| Companies Covered | Bayer Crop Science, Corteva, Syngenta, Limagrain, BASF, KWS, Vilmorin & Cie, S&W Seed Company, AgReliant Genetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Field Crop Seeds Market Shifts & Advancements
Biological seed treatments are displacing chemical coatings as the primary interface between genetics and soil microbiome performance. Three developments dominate current R&D allocation and commercial positioning.
RNA interference-based pest suppression is absorbing investment from synthetic insecticide seed treatments. Large-scale corn growers in the US Corn Belt are piloting RNAi-coated hybrids for rootworm management at 15-20 percent acreage penetration. This absorption is compressing neonicotinoid treatment volumes while requiring new fermentation capacity for dsRNA active ingredient production.
REACH authorization timelines for polymer seed coatings are extending from 18 to 36 months as ECHA scrutinizes microplastic shedding in agricultural soils. The industrial consequence forces reformulation toward biodegradable polysaccharide matrices. Organic certification bodies in Germany and France are accelerating pre-approval of these alternatives, creating first-mover positioning for compliant suppliers.
Direct-to-farm seed purchasing platforms are consolidating order aggregation for mid-size operations. Dealer networks in Iowa and Illinois are losing volume to cooperative buying groups that negotiate transparent pricing and bundled financing. This channel compression is most visible among 500-2,000 acre corn-soy rotations where price discovery friction historically favored incumbent distributors.
Field Crop Seeds Market Segmentation
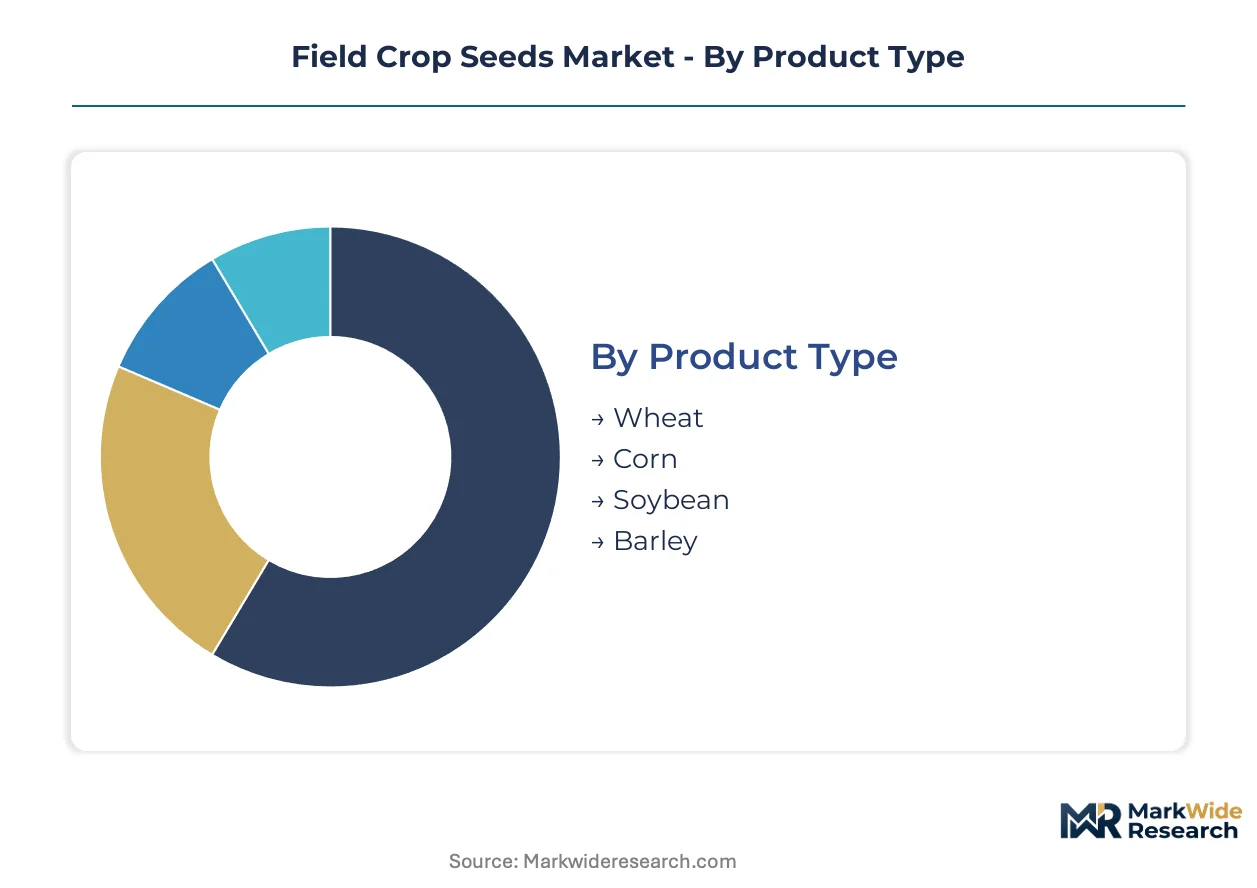
Field crop seeds segment along four intersecting dimensions that determine pricing power, regulatory exposure, and channel economics. Product type and trait combinations anchor volume concentration, while distribution channel and end-use splits reveal margin stratification and geographic penetration depth.
Product Type:
Supply concentration in corn and soybean germplasm creates asymmetric pricing leverage for breeders with stacked-trait portfolios, while wheat and barley remain fragmented across public and private breeding programs.
- Corn:Hybrids dominate commercial acreage with intensive input economics requiring precise maturity zone matching. Demand clusters in the US Corn Belt and Brazil's Mato Grosso, where 110-115 day relative maturity hybrids integrate with no-till systems and variable-rate planting equipment.
- Soybean:Varietal turnover accelerates as herbicide-tolerant trait stacks expand to four-way resistance. Brazil's Cerrado expansion zone drives specialized demand for tropical photoperiod-adapted lines with enhanced rhizobia nodulation.
- Wheat:Public breeding programs retain significant market share, particularly for hard red winter classes. Quality premiums for protein content and falling number specifications create regional specialization in Kansas and Ukraine black-soil zones.
- Barley:Malting-grade specifications dominate contract production, with brewing industry quality protocols restricting eligible varieties. Feed barley competes on yield with limited trait differentiation.
Today's leader: Corn. Tomorrow's challenger: Soybean.
Trait:
Cost tier stratification separates premium biotech stacks from certified organic and conventional untreated seed, with drought-tolerant categories capturing widening premiums as water stress intensifies.
- Herbicide-Tolerant:Glyphosate, glufosinate, and dicamba resistance traits stack in three-way and four-way combinations. Growers in Argentina's Pampas and the US Midwest prioritize these for reduced tillage weed management programs.
- Insect-Resistant:Bt protein expression targets lepidopteran and coleopteran pests in corn rootworm and corn borer management. Refuge requirements and resistance monitoring obligations structure commercial terms.
- Drought-Tolerant:Native gene discovery and transgenic water-use efficiency traits address yield volatility in Nebraska sandhills and Australian dryland wheat belts. Regulatory approval timelines vary sharply across import jurisdictions.
- Organic:Certification requires three-year field history isolation and prohibited substance verification. European demand under EU Green Deal Farm to Fork targets expands faster than certified seed supply.
Herbicide-tolerant lines command volume leadership. Drought-tolerant genetics are climbing the fastest as climate adaptation premiums widen.
Distribution Channel:
Customer type fragmentation splits order aggregation between large integrated operations with direct breeder relationships and smaller farms dependent on cooperative financing and retail credit terms.
- Direct Sales:Multinationals contract directly with operations exceeding 5,000 acres, bundling seed with crop protection and digital agronomy subscriptions. Bayer FieldView and Corteva Granular platforms lock in multi-year commitments.
- Retail:Independent dealers and farm supply stores serve 500-2,000 acre operations with localized agronomic support. Inventory financing and early-order discounts structure seasonal cash flow.
- E-commerce:Platform aggregation for transparent price discovery and cooperative buying groups. Illinois and Iowa farmer cooperatives negotiate volume discounts bypassing traditional dealer networks.
- Agricultural Cooperatives:Member-owned supply organizations in France, Germany, and Brazil's Mato Grosso pool procurement for imported germplasm with shared warehousing and treatment facilities.
Retail retains transaction volume leadership. E-commerce platforms are gaining share fastest among mid-size corn-soy rotations.
End Use:
Application maturity separates commercial farming's intensive input economics from subsistence systems where saved seed and public varieties dominate, creating divergent product development and pricing strategies.
- Commercial Farming:Large-scale operations purchasing certified seed annually for yield optimization and trait compliance. Input-intensive systems in Iowa, Mato Grosso, and Ukraine's Chernozem belt drive premium segment economics.
- Subsistence Farming:Saved seed and informal exchange networks predominate across Sub-Saharan Africa and South Asia. Hybrid adoption sits below 15 percent in Kenya and Nigeria, constraining commercial seed demand.
- Research:University and CGIAR breeding programs require genetic purity standards and phytosanitary certification for international germplasm exchange. USDA and China's MEE biosafety protocols govern shipment approvals.
- Seed Banks:Conservation repositories including the Svalbard Global Seed Vault and national gene banks maintain long-term genetic diversity collections. Regeneration cycles and viability monitoring drive specialized handling protocols.
Commercial farming anchors revenue concentration. Research applications represent the steepest expansion trajectory as gene-editing pipelines accelerate variety development cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting breeding investment toward jurisdictions with streamlined trait approval pathways, as developers seek to compress commercialization timelines and reduce compliance cost burdens relative to restrictive import markets.
United States
Commercial farming operations across Iowa and Illinois drive concentrated demand for stacked-trait corn and soybean hybrids. The EPA regulates plant-incorporated protectants under FIFRA, requiring extensive environmental release data before commercialization. The US Corn Belt anchors global germplasm innovation, with maturity zone-specific breeding programs in Nebraska and Indiana.
Brazil
No-till soybean expansion across Mato Grosso and the Cerrado frontier generates specialized demand for tropical-adapted photoperiod lines. Brazil's ANVISA coordinates with the Ministry of Agriculture on biosafety protocols for imported germplasm. The Mato Grosso industrial corridor concentrates seed treatment and coating facilities serving South American distribution networks.
China
Domestic corn and soybean breeding programs prioritize water-use efficiency traits for North China Plain production belts. China's MEE enforces extended environmental release trials for imported germplasm, delaying variety registration by 18-24 months. The Yangtze River Delta clusters state-owned seed enterprises with captive research stations and regional adaptation trials.
Germany
EU Green Deal Farm to Fork targets redirect demand toward organic-certified and drought-tolerant cereal varieties. ECHA REACH authorization timelines for polymer seed coatings have extended to 36 months, forcing biodegradable formulation shifts. Bavaria's agricultural research stations lead winter wheat breeding for protein content and falling number specifications.
India
Hybrid maize adoption remains below 15 percent across Maharashtra and Karnataka, constraining commercial seed penetration. India's BIS oversees seed certification standards and genetic purity verification protocols. The Indo-Gangetic Plain concentrates public breeding programs for wheat and rice, with private sector hybrid corn development accelerating in Telangana and Gujarat.
Field Crop Seeds Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biological seed treatment and gene-editing service partnerships. The vendor base stratifies across three tiers: integrated multinationals with stacked-trait platforms, regional specialists with climate-adapted germplasm, and biological input providers coating third-party genetics. Strategic moves center on digital farming platform integration and multi-year grower contract lock-ins through bundled agronomy subscriptions.
Within the integrated multinational tier, Bayer Crop Science, Corteva, and Syngenta anchor competitive positioning through proprietary breeding networks and trait-stacking capabilities. Bayer leverages its FieldView digital platform to bundle seed prescriptions with crop protection analytics. Corteva sustains broad germplasm collections across multiple climate zones. Syngenta competes through advanced RNAi and CRISPR trait development pipelines. These three entities exemplify the scale-driven archetype that dominates volume shipments in corn and soybean segments.
| Leading Market Players |
|---|
| Bayer Crop Science |
| Corteva |
| Syngenta |
| Limagrain |
| BASF |
| KWS |
| Vilmorin & Cie |
| S&W Seed Company |
| AgReliant Genetics |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between biotech-stacked hybrids and conventional untreated seed manifests in both pricing power and supply chain configuration. Premium trait portfolios command multi-year grower contracts through bundled agronomy subscriptions, while commodity untreated lines flow through dealer networks with seasonal inventory financing. This bifurcation concentrates margin capture among integrated multinationals with captive breeding infrastructure.
Pricing Analysis
Distributor margin layers in retail channels absorb 15-25 percent of final seed cost before reaching farmgate. Three-tier pricing structure across premium biotech stacks, certified conventional, and farm-saved seed segments buyers by input intensity and scale. Pricing pressure stems from phosphate and potash volatility compressing grower discretionary spend during fertilizer cost spikes. Mid-size operations in the 500-2,000 acre range exhibit highest price sensitivity, deferring premium purchases when input budgets tighten.
Supply Chain Analysis
Domestic-content mandates in China's germplasm import protocols reshape multinational sourcing toward captive research stations in the Yangtze River Delta. Germplasm innovation concentrates in the United States, Brazil, and China, with proprietary breeding networks anchored in Iowa, Mato Grosso, and Jiangsu provinces. Supply chain risk centers on extended environmental release trials for imported genetics, freezing revenue recognition for 18-24 month regulatory windows. Distribution runs through agricultural cooperatives in France and Germany, direct-to-farm platforms in Illinois and Iowa, and state-owned enterprises in China's provincial seed markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity into durable competitive moats. The EU Green Deal Farm to Fork strategy tightens input ceilings, redirecting R&D investment toward drought-tolerant and organic-certified portfolios that command premium positioning.
For Market Incumbents: To counter gene-editing regulatory fragmentation across import jurisdictions, Bayer Crop Science and Corteva should deepen backward integration into CRISPR trait platforms through exclusive licensing arrangements. Locking multi-year grower contracts via digital farming platform bundling—seed prescriptions married to crop protection analytics—defends share against cooperative buying groups gaining price transparency leverage. For New Entrants and Emerging Players: Capture underpenetrated hybrid maize demand across Kenya, Nigeria, and Ethiopia where commercial adoption sits below 15 percent. Partner with national agricultural extension services for distribution infrastructure rather than building captive networks. Biological seed treatment formulations for rhizobia inoculation in Brazil's Cerrado offer white-space entry with lower regulatory burden than transgenic trait development. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier seed houses lack computational breeding talent to compete with tech-sector data science salaries. Target regional specialists with climate-adapted germplasm collections in drought-stressed production belts. Watch for OECD harmonization on SDN-1 gene-editing classification as inflection signal collapsing multi-jurisdiction approval costs.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Farming Platform Integration | Bayer FieldView and Corteva Granular lock multi-year grower commitments through data-driven yield optimization bundling. |
| Biological Seed Treatment Scale-Up | RNAi-based pest suppression and biodegradable polysaccharide coatings displace neonicotinoid chemical treatments under ECHA REACH scrutiny. |
| Gene-Editing Regulatory Pre-Positioning | Developers with pre-positioned SDN-1 dossiers accelerate trait pipeline velocity if OECD harmonization collapses approval costs. |
| Sub-Saharan Distribution Partnerships | National agricultural extension services in Kenya and Nigeria provide infrastructure for hybrid maize penetration below 15 percent adoption. |
| Carbon Credit Stacking Infrastructure | USDA Climate-Smart Commodities grants incentivize cover crop seed blends generating dual revenue from grain and environmental credit markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with seed company breeding directors, agricultural cooperative procurement managers, regulatory affairs leads at germplasm importers, and farm operations managers across Iowa and Mato Grosso with secondary validation. USDA seed certification databases, EPA FIFRA registration filings, China's MEE biosafety protocols, and ANVISA trait approval records anchored supply-side characterization. Bottom-up acreage and pricing data triangulated against top-down breeder revenue disclosures.
Historical reference periods spanning germplasm innovation cycles and regulatory approval timelines anchored the projection horizon. The analytical framework modeled segmentation across product type, trait stack complexity, distribution channel, and end-use application intensity. CAGRs derived from acreage expansion trajectories in Brazil's Cerrado, trait penetration rates in US Corn Belt rotations, and organic certification growth under EU Farm to Fork targets. Water stress indices and fertilizer cost volatility fed climate adaptation premium scenarios.
Regulatory reclassification timelines, germplasm patent expiration waves, and gene-editing jurisdictional harmonization outcomes are the dominant revision risks to modeled trajectories. Forecasts reflect assumptions about OECD SDN-1 convergence and EU input ceiling enforcement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
South and Southeast Asia Seed Market
Seeds
Africa Seed Market
Seeds
Uganda Seeds Market
Seeds
Asia-Pacific Rice Seed Market
Seeds
North America Tomato Seed Market
Seeds
Eucommia Seed Oil Market
Seeds
Cherry Tomato Seeds Market
Seeds
Asia-Pacific Quinoa Seeds Market
Seeds
Middle East and Africa Cannabis Seeds Market
Seeds
Vietnam Seed Market
Seeds
Europe Chia Seeds Market
Seeds
Buckwheat Market
Seeds
Asia-Pacific Grain Seed Market
Seeds
Global Fruit and Vegetable Seeds Market
Seeds
Asia-Pacific Cannabis Seeds Market
Seeds
Native Grass Seeds Market