
 Cherry Tomato Seeds Market | 2026-2036
Cherry Tomato Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Cherry Tomato Seeds Market Insights
Organic seed certification under USDA National Organic Program standards is reorganizing competitive access in North America and Western Europe. Syngenta leverages its trait pipeline to anchor premium hybrid positions across controlled-environment agriculture. BASF SE sustains broad germplasm libraries that differentiate its portfolio in high-yield greenhouse segments. Sakata Seed Corporation specializes in determinate cherry varieties that dominate commercial propagation contracts in East Asia.
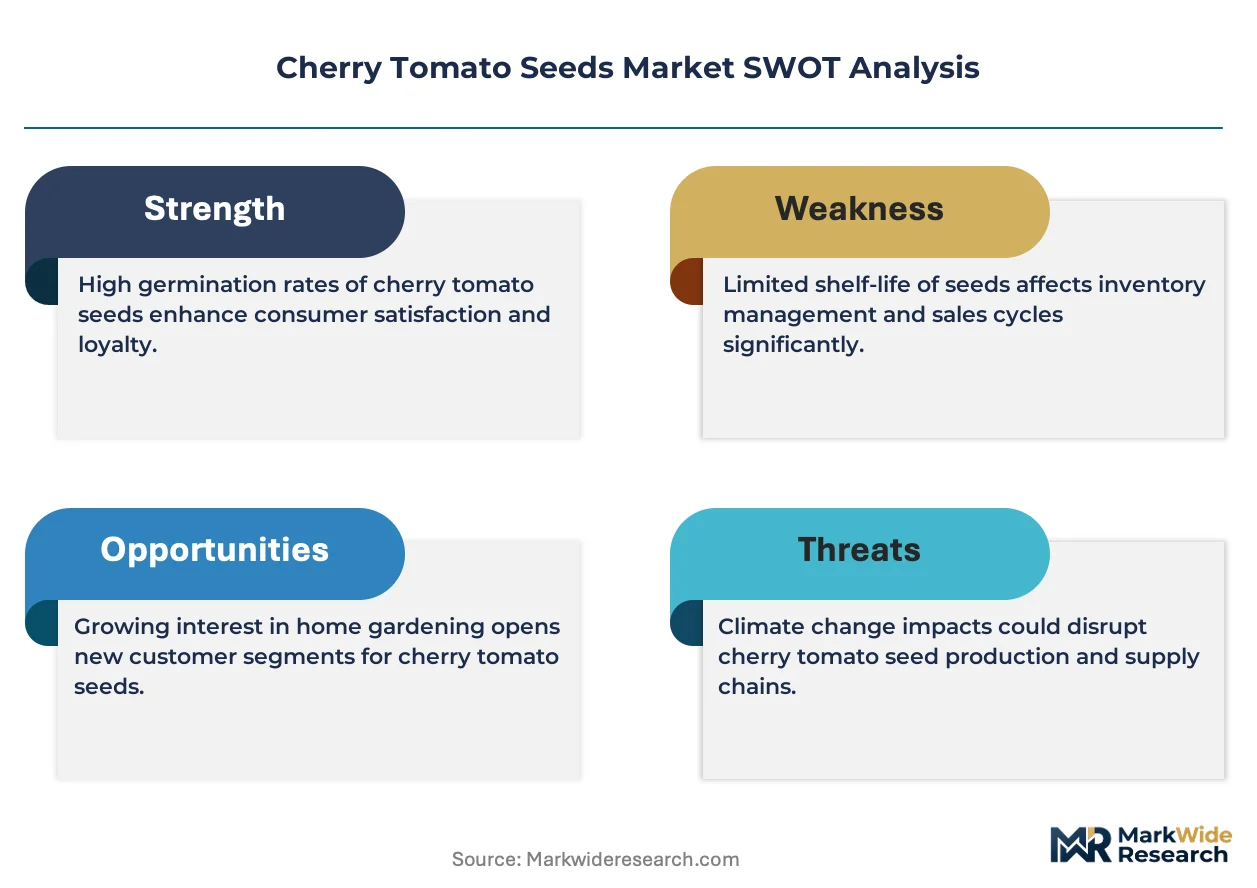
Cherry tomato seeds are sexually propagated planting material of Solanum lycopersicum var. cerasiforme, typically bred for brix concentration above 7.5%, crack resistance, and extended shelf-life post-harvest; their commercial purpose centers on standardized fruit output for fresh-market retail and foodservice supply chains. Hybrid seed types capture the dominant margin pool due to intellectual property protection and recurring purchase cycles, while heirloom varieties occupy niche premium channels where flavor differentiation commands price premiums. The greenhouse end-user segment leads volume absorption as climate-controlled environments maximize hybrid vigor expression and reduce disease pressure.
FDA seed labeling requirements, USDA organic certification, and EU Plant Health Regulation (EU) 2016/2031 collectively govern phytosanitary compliance, genetic traceability, and cross-border shipment eligibility. These frameworks elevate compliance costs for smaller breeders while consolidating procurement relationships around vertically integrated suppliers with in-house testing laboratories. Stakeholders must monitor evolving gene-editing regulatory classifications, as CRISPR-based trait development may soon redraw the boundary between regulated genetically modified organisms and exempt precision-bred varieties.
Market Dynamics
Commercial greenhouse operators in Spain, the Netherlands, and Morocco are consolidating acreage under climate-controlled cultivation, while the EU's F-Gas Regulation forces rapid variety turnover toward heat-tolerant genetics.
Growth Catalysts
- Protected Cultivation Expansion:Greenhouse acreage in Almería province anchors European off-season supply, creating sustained demand for determinate cherry varieties bred for high-density planting.
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon refrigerants pressures growers toward climate-resilient seed genetics that reduce heating and cooling loads.
- CRISPR Trait Development:Precision gene-editing accelerates breeding cycles for crack resistance and extended shelf-life, compressing time-to-market for hybrid lines.
Market Restraints
- Hybrid Seed Cost Structure:Recurring purchase cycles for F1 hybrids impose input cost volatility on smallholder growers relative to open-pollinated alternatives.
- Germplasm Concentration Risk:Four multinational breeders control dominant hybrid portfolios, creating supply vulnerability for regional seed distributors.
- Gene-Editing Regulatory Uncertainty:Divergent national classifications of CRISPR-derived varieties under EU Plant Health Regulation fragment cross-border shipment eligibility.
Strategic Opportunities
- Morocco Export Zone Expansion:Preferential trade access to EU markets positions Moroccan greenhouse clusters for year-round cherry tomato production using Dutch-propagated stock.
- Organic Certification Tailwind:USDA National Organic Program standards for seed sourcing create premium pricing tiers for certified organic propagation material in North American markets.
- Vertical Farming Convergence:Integration of LED photoperiod control with determinate dwarf varieties enables multi-layer cultivation in urban controlled-environment agriculture facilities.
Industry Challenges
- Phytosanitary Certification Timelines:EU Plant Health Regulation (EU) 2016/2031 compliance testing creates 18-24 month delays for new variety registration, straining breeder R&D amortization.
- Trait Stewardship Complexity:Intellectual property enforcement across fragmented national seed laws requires dedicated legal resources that mid-scale breeders lack.
- Climate Adaptation Lag:Existing germplasm libraries underrepresent heat-shock and drought-tolerance alleles needed for southern Mediterranean production intensification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cherry Tomato Seeds Market |
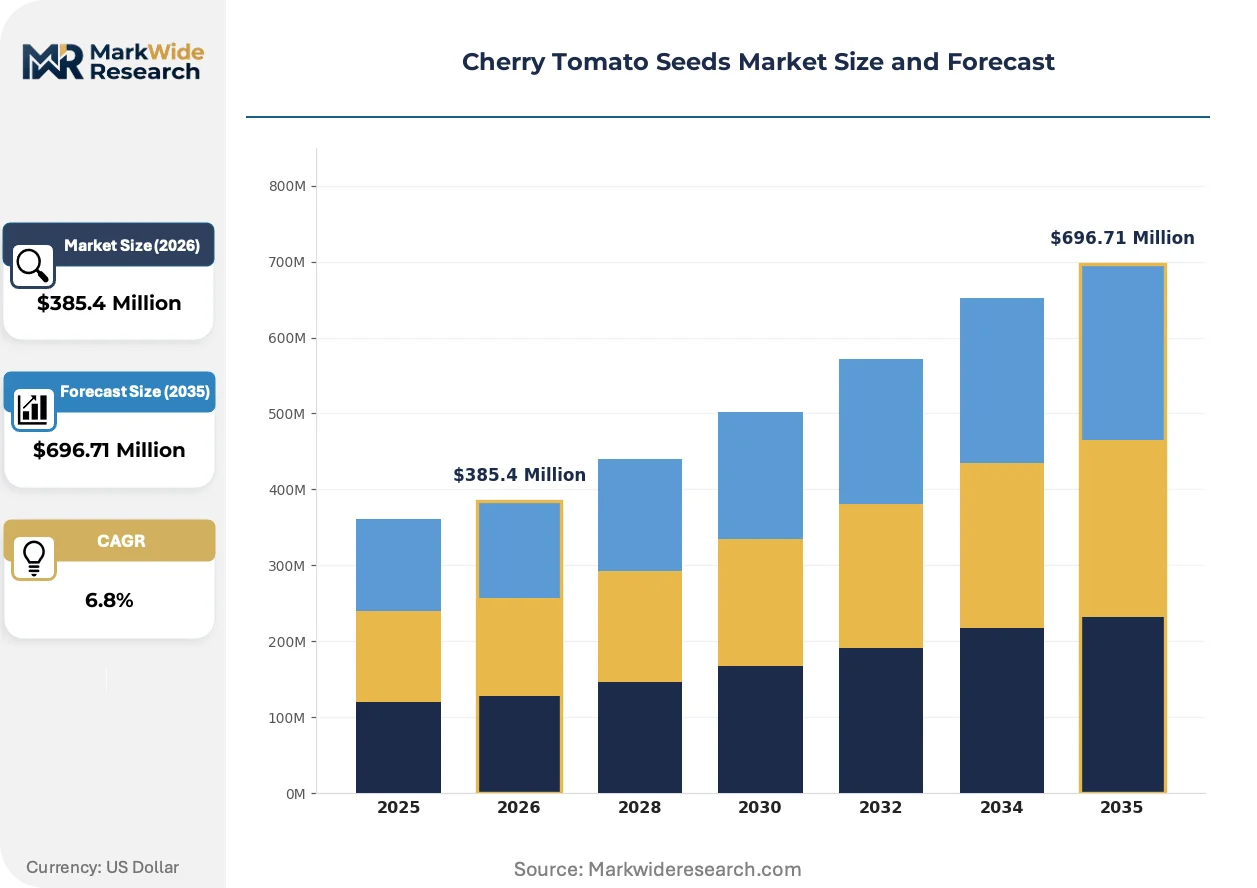
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Hybrid, Heirloom, Organic, Conventional End User: Home Gardeners, Commercial Growers, Retailers, Greenhouses Growth Type: Indeterminate, Determinate, Semi-determinate, Container Packaging Type: Bulk, Packets, Pouches, Jars |
| Companies Covered | Syngenta, BASF SE, Bayer CropScience, Rijk Zwaan, Sakata Seed Corporation, Enza Zaden, Seminis, Bejo Zaden, EastWest Seed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cherry Tomato Seeds Market Trends and Innovations
Breeding pipelines are pivoting toward climate-adaptive genetics as regulatory pressure and buyer concentration reshape variety selection criteria across protected cultivation.
Marker-assisted selection is decomposing traditional phenotypic screening timelines in hybrid development. Large-scale greenhouse operators in the Netherlands now specify genome-validated trait stacks in procurement contracts. This molecular breeding infrastructure compresses variety release cycles from eight years to four, enabling faster response to pathogen pressure and climate stress.
The EU F-Gas Regulation mandates refrigerant phase-downs that directly alter greenhouse environmental control economics. Spanish growers in Almería province face retrofit costs or variety substitution toward heat-tolerant lines. Seed distributors report accelerated turnover of temperate-climate genetics as carbon accounting rules tighten across member states.
Consolidated retail procurement now specifies brix concentration and shelf-life metrics in varietal contracts, displacing commodity spot purchasing. French and German supermarket chains source through single-breeder exclusive agreements that lock in three-year propagation supply. This buyer concentration shifts commercial risk onto seed companies while standardizing fruit quality parameters across the supply base.
Cherry Tomato Seeds Market Segmentation
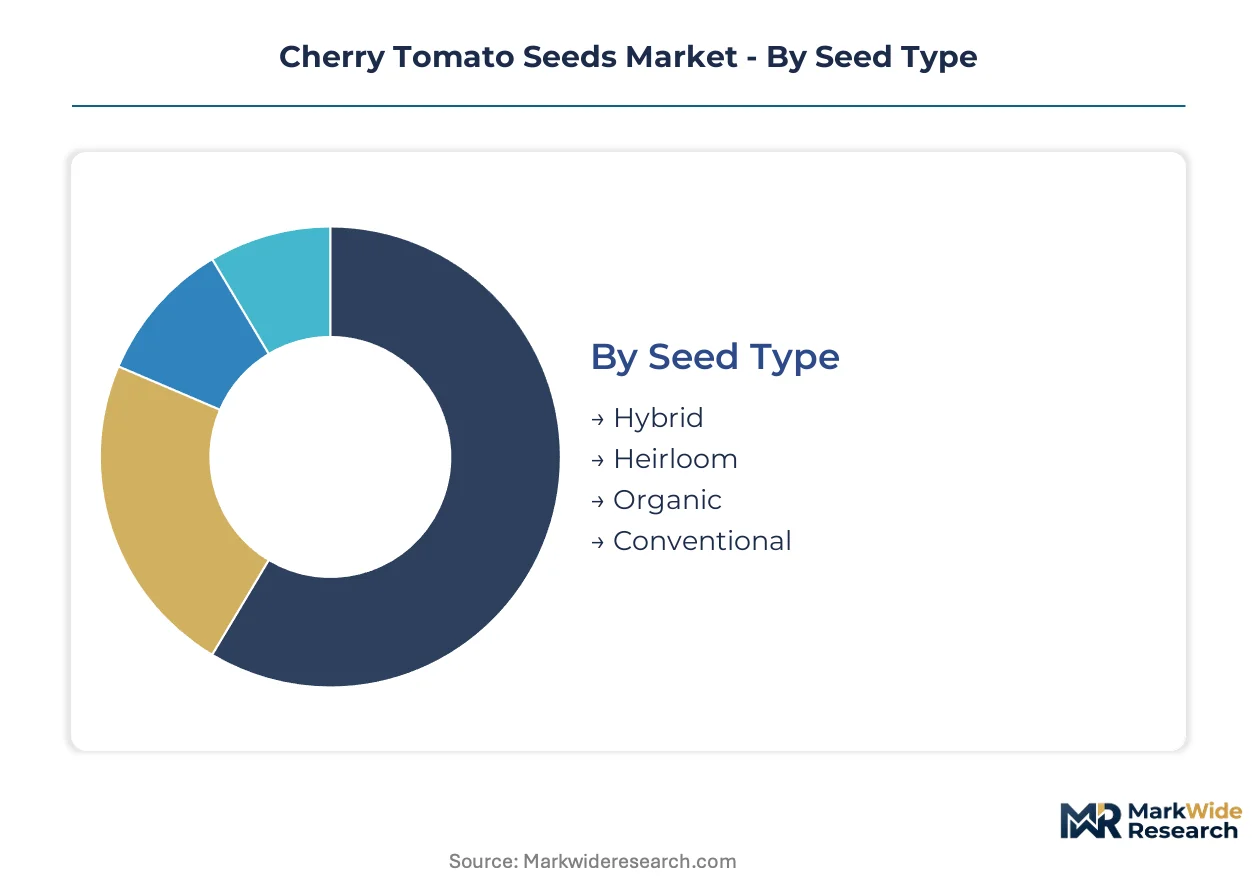
Cherry tomato seed procurement channels bifurcate sharply between recurring commercial contracts and episodic consumer purchases. Breeders structure distribution networks around these channel economics, with hybrid genetics flowing through specialized agricultural distributors while heirloom varieties reach gardeners via retail seed racks and e-commerce platforms.
Seed Type:
Channel economics favor hybrid seed flows through technical sales teams serving greenhouse operators, while heirloom and organic segments reach end-users through garden center retail and direct-to-consumer digital channels.
- Hybrid:F1 crosses combine inbred parental lines to express heterosis for yield uniformity, disease resistance, and shelf-life extension. Dutch greenhouse operators in Westland municipality specify hybrid contracts with genome-validated trait stacks, as EU F-Gas Regulation pressures intensify climate-adaptive variety turnover.
- Heirloom:Open-pollinated varieties preserve stable genetic lines across generations without hybrid vigor degradation. Italian specialty food retailers and French gastronomic wholesalers source specific heirloom cultivars like 'Sungold' and 'Black Cherry' for premium fresh-market positioning where flavor differentiation commands price premiums.
- Organic:USDA National Organic Program certification requires propagation material free from synthetic chemical treatment. North American distributors report premium pricing tiers for certified organic seed flowing through cooperative extension networks and natural food retail channels.
- Conventional:Standard untreated seed occupies commodity price bands for volume greenhouse operations prioritizing input cost control over branded genetics.
Hybrid seed dominates installed base in commercial protected cultivation. Organic certification is where expansion concentrates as retail procurement specifications tighten.
End User:
Customer type determines technical support intensity, with commercial growers demanding field agronomist access while home gardeners purchase through low-touch retail.
- Commercial Growers:Large-scale field operations in California's Central Valley and Florida's Immokalee region purchase hybrid seed through exclusive multi-year propagation agreements with integrated breeding companies. Volume commitments lock in variety access while transferring climate risk to seed suppliers.
- Greenhouses:Climate-controlled environments in Almería province, Spain, maximize hybrid vigor expression through precision irrigation and supplemental lighting. These operators specify determinate growth habits for high-density planting systems and automated harvesting compatibility.
- Home Gardeners:Consumer seed purchases concentrate in spring seasonal peaks through big-box retail and specialty garden center channels.
- Retailers:Supermarket chains and foodservice distributors increasingly specify variety-level sourcing for shelf-life and brix consistency.
Greenhouse operators dominate commercial volume absorption. Home gardening represents the most fragmented demand concentration.
Growth Type:
Plant architecture determines labor automation compatibility and spatial economics across cultivation systems.
- Determinate:Compact bush growth terminates at genetically fixed height, enabling high-density planting and mechanical harvesting. Dutch greenhouse technology providers specify determinate genetics for their automated crop handling systems exported to Moroccan and Spanish protected cultivation facilities.
- Indeterminate:Vine growth continues indefinitely under favorable conditions, requiring staking, pruning, and extended labor inputs. Italian passata processors and Spanish fresh-market field growers favor indeterminate lines for extended harvest windows and cumulative yield per plant.
- Semi-determinate:Intermediate growth habit offers partial height control with longer production cycles than true determinates.
- Container:Dwarf genetics bred for patio and balcony cultivation with restricted root volume tolerance.
Determinate varieties dominate mechanized greenhouse installations. Container types are climbing the fastest through urban agriculture and home gardening channels.
Packaging Type:
Packaging format signals channel position and customer technical sophistication, with bulk volumes flowing to professional propagation and unitized formats serving consumer markets.
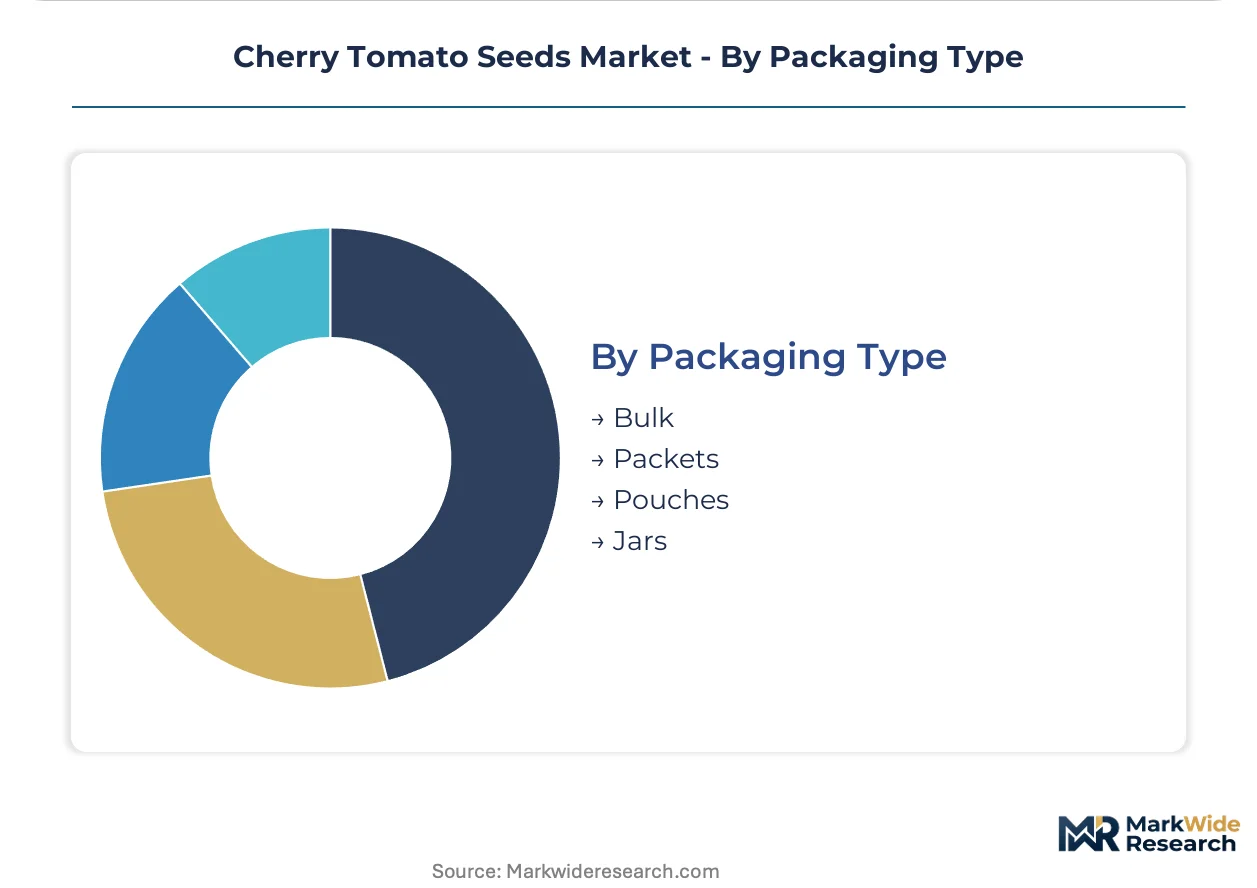
- Bulk:Large-volume seed lots ship in moisture-barrier containers to commercial propagators and greenhouse operators. Dutch breeding companies deliver bulk hybrid seed to Moroccan export zone greenhouses under phytosanitary certification protocols required by EU Plant Health Regulation.
- Packets:Paper or foil laminate envelopes dominate retail garden center and hardware store distribution. Consumer brands compete for shelf space through varietal storytelling and germination guarantee claims.
- Pouches:Flexible stand-up bags with resealable closures serve serious amateur growers and small-scale market farmers.
- Jars:Glass or plastic containers preserve seed viability for long-term storage and heritage variety preservation.
Bulk packaging dominates commercial propagation volume. Packet formats represent the steepest expansion trajectory through e-commerce direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale greenhouse operators in Spain, the Netherlands, and Morocco concentrate procurement volumes through multi-year propagation contracts. Retail supermarket chains in France and Germany now specify variety-level sourcing for shelf-life consistency. North American demand clusters around California's Central Valley field operations and Florida's winter production belt.
Spain
Almería province anchors European off-season cherry tomato supply through year-round protected cultivation. The EU F-Gas Regulation pressures growers toward heat-tolerant seed genetics that reduce climate-control energy loads. Dutch greenhouse technology providers export automated crop handling systems to Spanish facilities, driving demand for determinate varieties bred for mechanical harvesting compatibility.
Netherlands
Westland municipality greenhouse operators specify genome-validated hybrid trait stacks in procurement contracts with integrated breeding companies. National carbon accounting rules tighten environmental compliance costs for protected cultivation, accelerating variety turnover toward climate-resilient genetics. Wageningen University research clusters support marker-assisted selection pipelines that compress breeding cycles for crack resistance and extended shelf-life.
Morocco
Agadir and Larache export zones supply EU markets with year-round production using Dutch-propagated stock under preferential trade access. Phytosanitary certification protocols under EU Plant Health Regulation govern cross-border shipment eligibility for propagation material. Commercial greenhouse clusters expand acreage under climate-controlled cultivation to capture off-season price premiums in European retail channels.
United States
California's Central Valley field operations purchase hybrid seed through exclusive multi-year agreements that transfer climate risk to suppliers. FDA seed labeling requirements and USDA National Organic Program standards govern phytosanitary compliance and certified organic propagation material eligibility. Florida's Immokalee region concentrates winter production volumes for East Coast fresh-market supply chains.
China
Shandong Province greenhouse clusters absorb commercial volumes of determinate cherry varieties for domestic fresh-market retail. The Ministry of Agriculture and Rural Affairs oversees variety registration and genetic resource management under national seed law frameworks. Yangtze River Delta protected cultivation facilities integrate LED photoperiod control with dwarf genetics for multi-layer urban agriculture installations.
Cherry Tomato Seeds Market Competitive Landscape
Player mix skews toward multinational agrochemical conglomerates with integrated breeding divisions and specialized vegetable seed houses with regional germplasm depth. Market structure concentrates around four dominant hybrid portfolio holders that control recurring purchase cycles through intellectual property protection. Strategic archetypes include trait-pipeline integrators, germplasm library curators, and determinate variety specialists. Competitive moves center on exclusive propagation agreements with retail procurement chains and accelerated CRISPR-based breeding program investments.
Within the trait-pipeline integrator tier, Syngenta and BASF SE anchor premium hybrid positions across controlled-environment agriculture segments. Sakata Seed Corporation exemplifies the determinate variety specialist archetype, occupying a position in commercial propagation contracts throughout East Asian markets. Bayer CropScience sits within the agrochemical-breeding convergence space, representing backward integration into captive seed supply for crop protection bundle offerings.
| Leading Market Players |
|---|
| Syngenta |
| BASF SE |
| Bayer CropScience |
| Rijk Zwaan |
| Sakata Seed Corporation |
| Enza Zaden |
| Seminis |
| Bejo Zaden |
| EastWest Seed |
| Others |
Pricing and Supply Chain Analysis
Multi-year propagation contracts with genome-validated trait specifications lock in supply access for Dutch and Spanish greenhouse operators while anchoring price visibility against input cost volatility. These exclusive agreements transfer climate risk to integrated breeding companies and compress spot market liquidity for regional distributors.
Pricing Analysis
Cost-plus contracts indexed to parental line development expenses dominate hybrid seed procurement between integrated breeders and large-scale greenhouse operators. Three-tier pricing structure across premium, standard, and economy levels separates genome-validated hybrids from certified organic propagation material and conventional untreated seed. Pricing pressure stems from F-Gas Regulation compliance costs pressuring Spanish growers toward variety substitution. Smallholder field operations exhibit highest price sensitivity relative to Dutch greenhouse clusters with locked multi-year commitments.
Supply Chain Analysis
Eighteen-to-twenty-four month phytosanitary certification timelines strain inventory positioning for new variety introductions under EU Plant Health Regulation. Germplasm concentration rests on the Netherlands, Spain, and Morocco for commercial propagation volume, with parental line development drawing from proprietary inbred libraries and marker-assisted selection infrastructure. Single-source vulnerability concentrates around four multinational hybrid portfolio holders controlling recurring purchase cycles. Distribution runs through specialized agricultural distributors serving greenhouse operators and garden center retail channels reaching home gardeners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cherry tomato seed demand sits in early-cycle expansion as protected cultivation acreage accelerates across southern Mediterranean export zones and North American organic certification tightens sourcing specifications.
For Market Incumbents: Fortify germplasm library depth through accelerated CRISPR-based breeding investments targeting heat-shock tolerance alleles underrepresented in existing collections. Exclusive propagation agreements with French and German supermarket chains lock in three-year supply visibility against emerging regional seed house competition. Backward integration into captive parental line development reduces royalty exposure to third-party inbred licensors. For New Entrants and Emerging Players: Anchor in Moroccan greenhouse export zones where preferential EU trade access and Dutch technology transfer create propagation contract whitespace. Organic certification gaps in North American cooperative extension networks offer the most penetrable entry path against entrenched hybrid incumbents. Direct-to-consumer heirloom positioning through e-commerce channels bypasses distributor concentration around multinational breeding companies. For Investors and Strategic Acquirers: Capital is best deployed toward determinate variety specialists with established commercial propagation contracts in East Asian markets and transferable germplasm for Mediterranean climate adaptation. Long-term viability hinges on regulatory clarity for CRISPR-derived classifications across EU member states. Watch EU Plant Health Regulation harmonization negotiations as the inflection signal for cross-border shipment eligibility expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Trait Pipeline Investment | Marker-assisted breeding compresses variety release cycles from eight years to four under Wageningen University research partnerships. |
| Exclusive Retail Procurement Agreements | French supermarket chains now specify brix concentration and shelf-life metrics in three-year propagation contracts. |
| Moroccan Export Zone Capacity Expansion | Agadir and Larache clusters capture off-season EU price premiums using Dutch-propagated stock under preferential trade access. |
| Organic Certification Compliance Investment | USDA National Organic Program standards for seed sourcing create premium pricing tiers in North American cooperative extension channels. |
| Vertical Farming Technology Convergence | LED photoperiod control integration with determinate dwarf genetics enables multi-layer cultivation in Yangtze River Delta urban facilities. |
Research Methodology
Cross-validation between breeder R&D executives and greenhouse procurement managers anchors the qualitative findings on variety turnover timelines and trait specification priorities. Secondary validation draws from EU Plant Health Regulation compliance databases, USDA National Organic Program certification records, and Dutch customs propagation material shipment data. Bottom-up variety registration counts triangulate against top-down greenhouse acreage expansion estimates across Almería, Westland, and Shandong Province clusters.
Sensitivity analysis around F-Gas Regulation implementation pace and CRISPR regulatory classification scenarios shapes the analytical framework across the projection horizon. Segmentation dimensions model seed type, growth habit, end-user category, and regional regulatory cluster. CAGRs derive from installed base turnover rates and new protected cultivation acreage absorption curves, with climate adaptation allele penetration and organic certification adoption as primary industry-specific forecast inputs.
Material uncertainties — gene-editing regulatory harmonization delays, phytosanitary certification timeline extensions, and hybrid parental line supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions on breeder R&D amortization schedules and greenhouse operator contract renewal rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Global Onion Seed Market
Seeds
Psyllium Seed Market
Seeds
South Africa Forage Seed Market
Seeds
Africa Peas Market
Seeds
Organic Seed Market
Seeds
Global Forage Sorghum Seed Market
Seeds
Europe Forage Seed Market
Seeds
Hemp Seed Oil Market
Seeds
Global Sports Turf Seed Market
Seeds
Eucommia Seed Oil Market
Seeds
Grass Seed Market
Seeds
Europe Amaranth Market
Seeds
Russia Forage Seed Market
Seeds
Dodder Seed Market
Seeds
United States Garden Seeds Market
Seeds
Carrot Seed Oil Market