
 Asia-Pacific Cotton Seed Market | 2026-2036
Asia-Pacific Cotton Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cotton Seed Market Insights
Seed-plus-service bundling is restructuring buyer choice across the Asia-Pacific Cotton Seed Market. Bayer AG leverages its digital farming platform to tie variety selection with pest management protocols. Mahyco anchors its position through deep distribution into Maharashtra and Karnataka cooperative networks. Kaveri Seeds differentiates via specialized germplasm adapted to rain-fed Deccan Plateau conditions.
Cotton seed comprises the fertilized ovule of Gossypium species, typically bearing 28-40% oil content and 20-25% protein in its kernel, processed for edible oil extraction and livestock feed supplementation. Gossypium hirsutum dominates planted area across India and China due to high yield potential and Bt trait compatibility, while Gossypium barbadense occupies premium textile niches demanding extra-long staple fiber. Hybrid Seeds command the largest value pool through proprietary trait stacks and royalty structures, though Organic Seeds gain traction among export-oriented farmers serving EU and Japanese textile buyers.
India's CEA and China's MEE enforce seed treatment and environmental release standards that shape product registration timelines and trait approval pathways. India's BIS certification and China's GB standards create dual compliance burdens for multinationals operating across both jurisdictions. Stakeholders must monitor evolving gene-editing policy positions in Beijing and New Delhi, as regulatory clarity on CRISPR-derived varieties will determine R&D allocation between conventional breeding and biotech pipelines.
Market Dynamics
Contract farming expansion across Vietnam and Bangladesh is consolidating procurement decisions into textile mill agronomy departments, shifting seed selection authority from individual growers to vertically integrated processors with variety-specific fiber requirements.
Growth Catalysts
- India's PLI scheme for textiles:The production-linked incentive framework mandates certified hybrid seed usage for participating ginners, redirecting cooperative procurement toward trait-verified varieties with documented germplasm lineage.
- Bt trait stack penetration:Dual-gene and triple-gene configurations targeting pink bollworm and tobacco cutworm are expanding planted area in Maharashtra's irrigated zones where pest pressure justifies technology fees.
- Bangladesh garment sector backward integration:Denim and knitwear exporters are contracting directly with Punjab and Haryana farmers for identity-preserved seed programs ensuring specified micronaire and staple length parameters.
Market Restraints
- Gossypol toxicity in feed applications:Unprocessed cottonseed meal retains hepatotoxic compounds that limit inclusion rates in dairy rations, capping byproduct value recovery for ginning operations.
- Chinese MEE environmental release protocols:Trait approval timelines for biotech varieties extend 24-36 months, delaying variety turnover and locking farmers into aging germplasm with declining pest resistance.
- Monsoon dependency in Deccan Plateau:Rain-fed cultivation across Karnataka and Telangana exposes yield stability to precipitation variability, compressing farmer willingness to pay for premium hybrid seed.
Strategic Opportunities
- Myanmar's unpenetrated delta regions:Ayeyarwady Division lacks established distribution networks for certified seed, presenting first-mover positioning for hybrid varieties with demonstrated rain-fed performance.
- Gene-editing regulatory clarity:India's Department of Biotechnology and China's Ministry of Agriculture are drafting CRISPR-derived variety frameworks that could accelerate trait development timelines versus transgenic pathways.
- Blockchain seed traceability:Textile brands sourcing for EU and Japanese markets are piloting distributed ledger systems linking farm-level seed batch records to finished garment certification, creating premium positioning for documented provenance.
Industry Challenges
- Seed treatment compliance timelines:India's CEA mandates neonictinoid coating standards that extend processing batches and complicate just-in-time delivery to sowing windows.
- Trait licensing complexity:Stacked Bt and herbicide-tolerance configurations require navigating multiple patent estates, creating royalty stacking that erodes margins for regional seed producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cotton Seed Market |
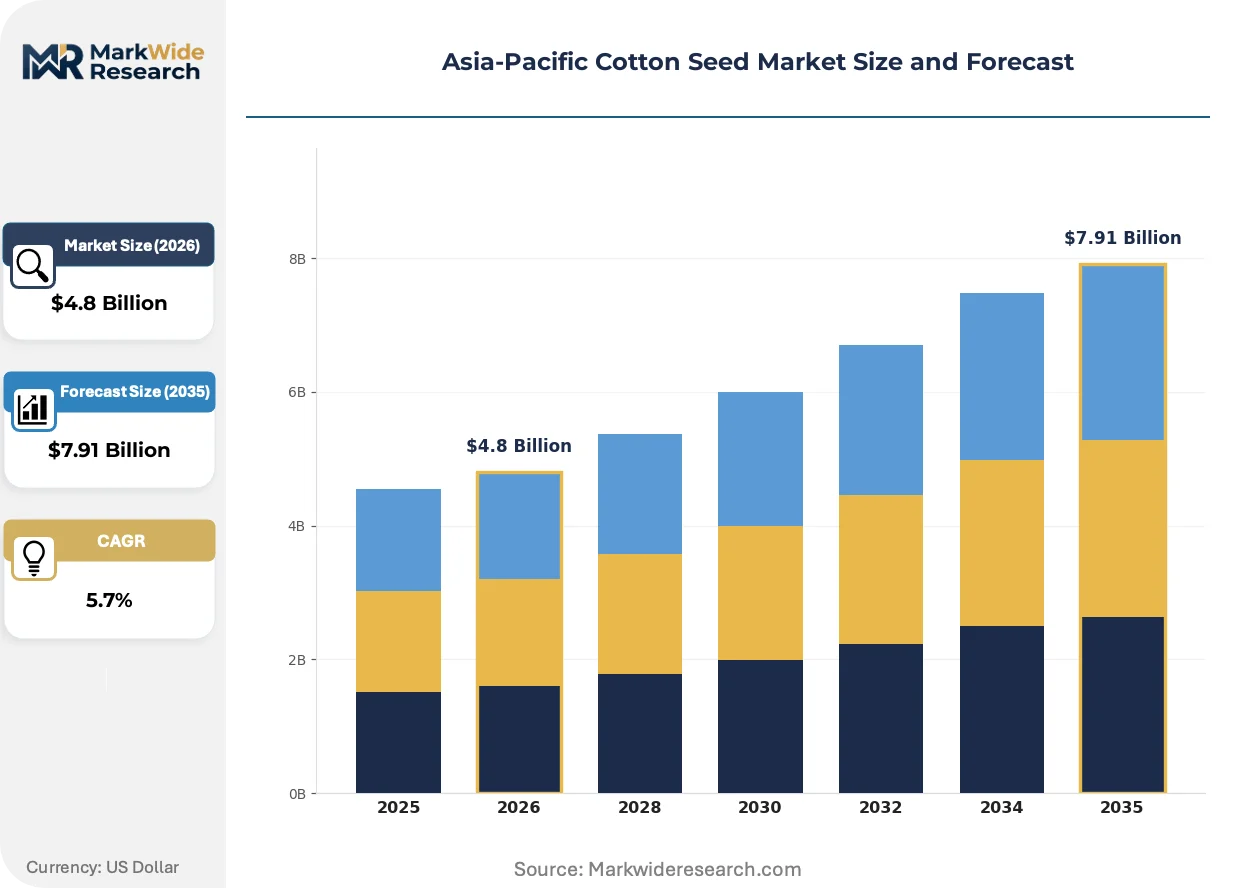
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Gossypium hirsutum, Gossypium barbadense, Hybrid Seeds, Organic Seeds End User: Farmers, Cooperative Societies, Corporations, Research Institutions Distribution Channel: Online Retailers, Agricultural Supply Stores, Distributors, Direct Sales Application: Textile Manufacturing, Oil Production, Seed Production, Research |
| Companies Covered | Anhui Tsuen Yin Hi-Tech Seed Industry Co. Ltd, Bayer AG, Kaveri Seeds, Krishak Bharati Co-Op Limited (KRIBHCO), Maharashtra Hybrid Seeds Co. (Mahyco), BASF SE, Syngenta Group, Corteva Agriscience, Longping High-tech, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cotton Seed Market Trends and Innovations
Digital agronomy platforms are embedding variety selection algorithms that match germplasm to micro-climatic zones, compressing the traditional extension agent role and accelerating farmer adoption cycles for newly released hybrids.
RNA interference technology targeting bollworm resistance genes is overtaking conventional Bt toxin expression in research pipelines. Maharashtra-based cooperative societies are field-testing siRNA-treated seed for the 2024-25 season. The technology is overtaking first-generation biotech varieties by eliminating refuge planting requirements and reducing resistance management complexity for smallholder aggregators.
India's BIS certification for cotton seed germination and genetic purity standards is tightening lot rejection thresholds. Seed processors in Gujarat are retrofitting conditioning facilities with automated optical sorting to meet revised viability metrics. Maharashtra cooperative networks face the steepest compliance burden due to fragmented lot sizes and distributed ginning infrastructure.
Textile mill agronomists are displacing traditional village-level dealers as the primary seed recommendation channel. Bangladesh's Pacific Jeans and Vietnam's Saitex have established dedicated cotton sourcing divisions that specify variety traits directly to Indian seed companies. This channel migration concentrates demand intelligence in processor hands and erodes the historical distributor margin pool across Punjab and Haryana.
Asia-Pacific Cotton Seed Market Segmentation
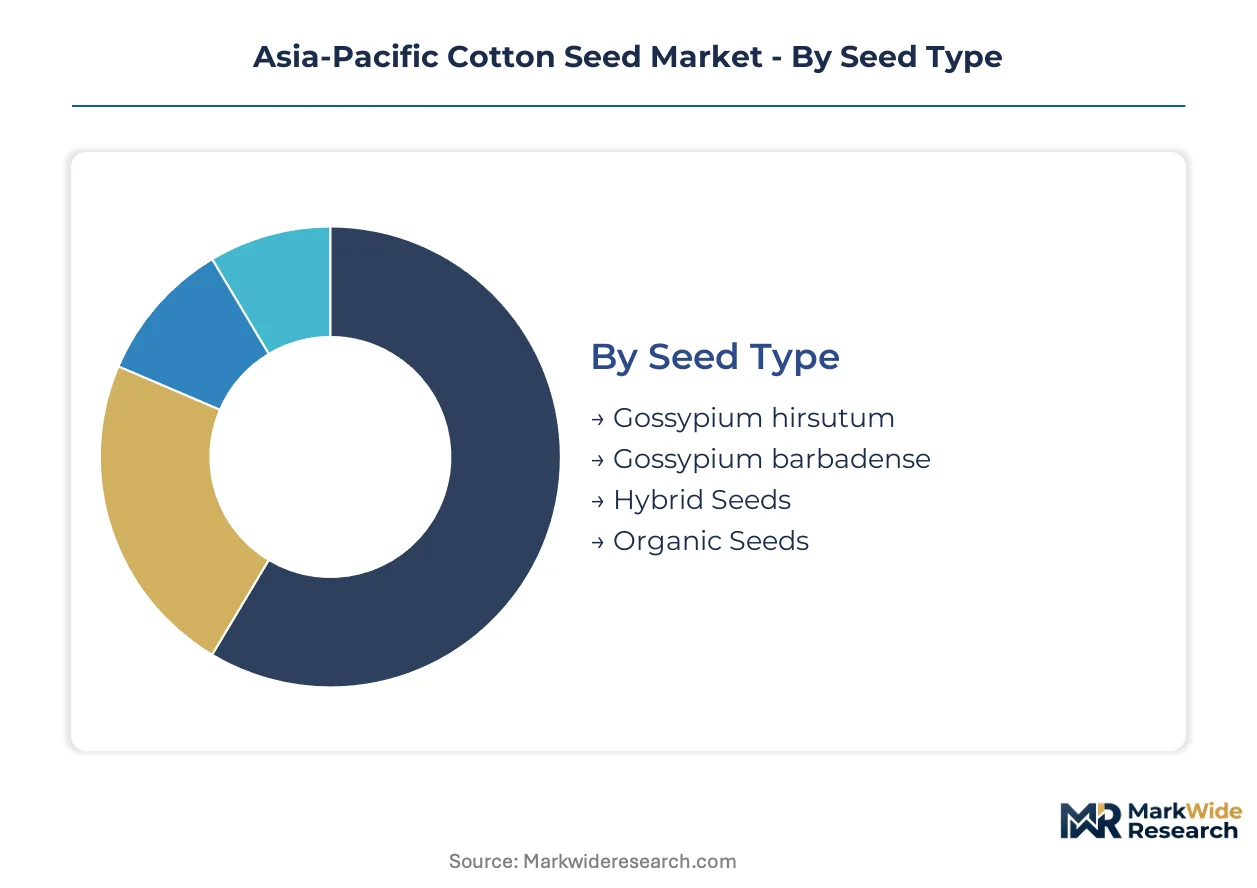
Asia-Pacific cotton seed segmentation reveals how fiber quality requirements, procurement scale, and regulatory compliance reshape purchasing patterns across diverse agricultural economies. Seed type selection increasingly ties to textile mill specifications, while distribution channel choice reflects cooperative consolidation versus individual farmer autonomy.
Seed Type:
Volume concentration favors high-yield hybrids, yet premium niches command disproportionate value through specialized germplasm and certification premiums.
- Gossypium hirsutum:Upland cotton dominates planted area across India and China due to Bt trait compatibility and adaptability to varied agro-climatic zones. Maharashtra and Gujarat ginning operations specify hirsutum varieties for standard denim and knitwear output, with cooperative procurement aggregating bulk orders for processing consistency.
- Hybrid Seeds:Proprietary trait stacks combining Bt genes with herbicide tolerance command the largest value pool through technology fee structures and royalty arrangements. India's PLI scheme for textiles mandates certified hybrid usage, redirecting cooperative societies toward documented germplasm lineage with verified pest resistance profiles.
- Gossypium barbadense:Extra-long staple fiber serves premium textile niches in Bangladesh garment sector backward integration programs demanding specified micronaire parameters.
- Organic Seeds:Export-oriented farmers serving EU and Japanese textile buyers adopt non-GMO varieties with blockchain-traceable provenance for finished garment certification.
Today's leader: Hybrid Seeds. Tomorrow's challenger: Organic Seeds.
End User:
Procurement authority is concentrating in entities with scale to negotiate variety-specific contracts and absorb compliance burdens.
- Cooperative Societies:Maharashtra and Karnataka networks aggregate bulk seed orders for ginning operations, consolidating farmer demand into volume contracts with trait-verified suppliers. These entities now dominate certified hybrid procurement under India's PLI textile incentives.
- Corporations:Bangladesh denim exporters and Vietnam textile mills establish dedicated cotton sourcing divisions that specify germplasm directly to seed companies, displacing traditional dealer channels.
- Farmers:Individual growers retain selection autonomy in rain-fed Deccan Plateau zones where precipitation variability compresses willingness to pay premium technology fees.
- Research Institutions:Maharashtra-based cooperatives field-test RNA interference seed for the 2024-25 season, accelerating adoption cycles for novel pest resistance mechanisms.
Scale advantages accrue to Cooperative Societies. Direct contracting by Corporations is gaining share fastest.
Distribution Channel:
Channel migration reflects compression of traditional margin pools and concentration of demand intelligence in processor hands.
- Direct Sales:Textile mill agronomists specify variety traits directly to Indian seed companies, bypassing historical distributor networks across Punjab and Haryana. Pacific Jeans and Saitex maintain dedicated procurement relationships for identity-preserved programs.
- Distributors:Fragmented lot sizes and distributed ginning infrastructure in Maharashtra cooperative networks sustain intermediary roles for seed treatment compliance and just-in-time delivery coordination.
- Agricultural Supply Stores:Village-level dealers retain influence in Telangana and Karnataka rain-fed zones where farmer autonomy persists and credit relationships anchor purchasing decisions.
- Online Retailers:Digital agronomy platforms embed variety selection algorithms matching germplasm to micro-climatic zones, compressing traditional extension agent roles.
Direct Sales commands premium positioning. Online Retailers show steepest expansion trajectory.
Application:
End-use specifications increasingly determine upstream seed selection, with fiber parameters overriding agronomic convenience in procurement decisions.
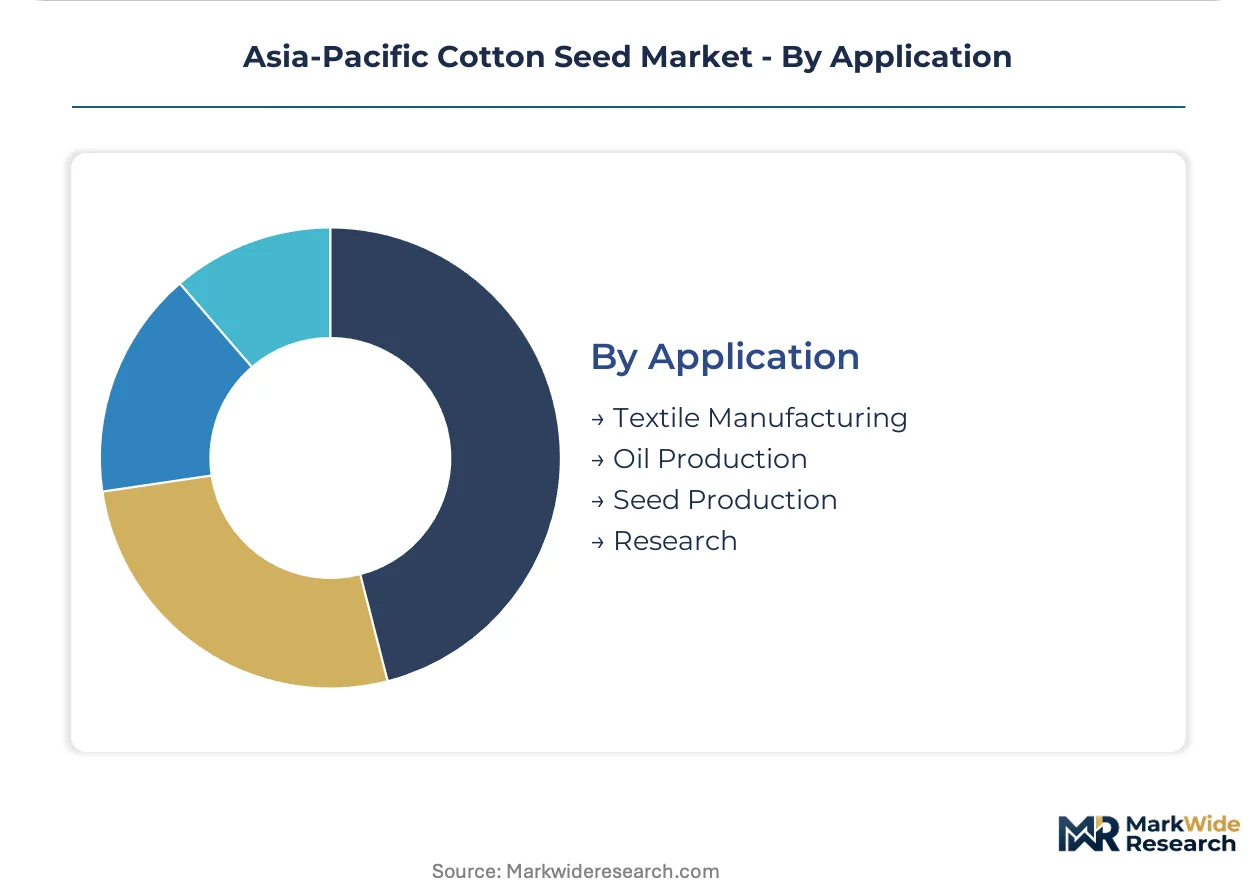
- Textile Manufacturing:Denim and knitwear exporters contract directly for specified staple length and micronaire parameters, with Bangladesh garment sector backward integration driving identity-preserved seed programs. Ginning operations prioritize varieties with documented fiber consistency for mill acceptance.
- Oil Production:Cottonseed kernel processing for edible oil extraction and livestock feed supplementation faces gossypol toxicity constraints that limit byproduct value recovery, capping meal inclusion rates in dairy rations.
- Seed Production:Gujarat processors retrofit conditioning facilities with automated optical sorting to meet India's BIS certification tightening for germination and genetic purity standards.
- Research:Gene-editing regulatory clarity in India's Department of Biotechnology and China's Ministry of Agriculture shapes R&D allocation between conventional breeding and biotech pipelines.
Textile Manufacturing drives current value. Research investment determines tomorrow's competitive map.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cotton seed cultivation in the Asia-Pacific traces its commercial lineage to British colonial ginning operations in Gujarat and Maharashtra during the nineteenth century, establishing varietal selection practices that persist in cooperative procurement networks today. Contemporary demand concentrates in textile manufacturing corridors where mill agronomists now specify germplasm traits directly.
India
Maharashtra and Gujarat cooperative societies aggregate bulk seed orders for ginning operations under the PLI textile scheme mandating certified hybrid usage. India's CEA enforces seed treatment standards that extend processing timelines. Maharashtra's irrigated zones deploy dual-gene and triple-gene Bt configurations targeting pink bollworm pressure.
China
Xinjiang's mechanized cotton belt drives volume demand for high-yielding varieties with herbicide tolerance stacks. China's MEE environmental release protocols extend trait approval timelines, locking farmers into aging germplasm. Yangtze River Delta textile mills increasingly specify fiber parameters upstream into seed selection.
Vietnam
Denim and knitwear exporters including Saitex establish dedicated cotton sourcing divisions that contract directly with Indian seed suppliers. The country's national agricultural regulator oversees import phytosanitary certification for germplasm. Ho Chi Minh City-based textile clusters drive backward integration into Punjab and Haryana identity-preserved programs.
Bangladesh
Garment sector exporters like Pacific Jeans specify micronaire and staple length parameters through direct farmer contracting. The central bank's trade financing facilities support seed import arrangements with Indian suppliers. Dhaka-Chittagong industrial corridor concentration accelerates mill agronomist displacement of traditional dealer channels.
Australia
Queensland and New South Wales irrigated valleys sustain premium extra-long staple production for Japanese and EU textile buyers. The national gene technology regulator oversees Bt trait approvals with environmental release protocols. Liverpool Plains seed processors retrofit optical sorting to meet tightening germination certification standards.
Asia-Pacific Cotton Seed Market Competitive Landscape
Premium-margin players sit above commodity-margin players across trait-stack complexity and royalty structure arrangements. The market structures around three tiers: multinational agrochemical conglomerates with integrated breeding platforms, regional hybrid specialists with deep cooperative distribution, and state-linked enterprises serving domestic food security mandates. Strategic archetypes include trait licensors extracting technology fees, germplasm aggregators consolidating landrace collections, and service-bundled platform operators. Dominant competitive moves encompass RNA interference pipeline investments and blockchain traceability partnerships with textile brands.
Within the multinational tier, Bayer AG and BASF SE anchor positions through integrated breeding and crop protection platforms. Maharashtra Hybrid Seeds Co. (Mahyco) and Kaveri Seeds exemplify regional specialists with cooperative network penetration. Anhui Tsuen Yin Hi-Tech Seed Industry Co. Ltd represents state-tethered Chinese germplasm development. Corteva Agriscience and Syngenta Group occupy positions linking global trait libraries to Asia-Pacific regulatory pathways.
| Leading Market Players |
|---|
| Anhui Tsuen Yin Hi-Tech Seed Industry Co. Ltd |
| Bayer AG |
| Kaveri Seeds |
| Krishak Bharati Co-Op Limited (KRIBHCO) |
| Maharashtra Hybrid Seeds Co. (Mahyco) |
| BASF SE |
| Syngenta Group |
| Corteva Agriscience |
| Longping High-tech |
| Others |
Pricing and Supply Chain Analysis
China's MEE environmental release protocols gate qualified supply for biotech cotton seed varieties, restricting premium-tier pricing access to processors meeting extended trait approval timelines. India's BIS certification tightening for germination standards further segments the market, with compliant Gujarat processors commanding technology fee premiums while Maharashtra cooperative networks absorb compliance cost compression.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and trait-stack complexity. Premium tiers capture proprietary Bt configurations with documented germplasm lineage under India's PLI textile scheme, while economy tiers serve rain-fed Deccan Plateau zones where farmer willingness to pay compresses. Price differentiation rests on blockchain-traceable provenance for EU and Japanese textile buyers versus untreated commodity seed. Pricing pressure intensifies in standard tiers as cooperative bulk procurement consolidates volume leverage. Individual farmers in Telangana and Karnataka exhibit highest price sensitivity; Bangladesh garment sector direct contractors show lowest sensitivity due to fiber specification mandates.
Supply Chain Analysis
Seed lot returns and conditioning facility refurbishment flows concentrate in Gujarat and Maharashtra processing hubs retrofitting optical sorting infrastructure. Raw material dependencies center on parental line germplasm from Bayer AG and BASF SE trait libraries, neonicotinoid treatment inputs, and moisture-controlled storage infrastructure. Single-source vulnerability pervades Bt gene licensing, with stacked configurations requiring navigation of multiple patent estates. Distribution runs through cooperative society aggregators in Maharashtra and Karnataka, textile mill agronomist direct channels across Punjab and Haryana, and digital agronomy platforms embedding micro-climatic matching algorithms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Cotton Seed Market reads as a late-cycle quality story as Bangladesh and Vietnam textile mills backward-integrate into identity-preserved seed programs demanding specified micronaire and staple length parameters.
For Market Incumbents: Deploy RNA interference pipeline investments to outflank first-generation Bt trait resistance. Mahyco and Kaveri Seeds should deepen cooperative network penetration in Maharashtra and Karnataka to defend against digital platform disintermediation. BASF SE and Bayer AG must accelerate gene-editing regulatory pre-positioning in India and China before CRISPR-derived variety frameworks crystallize competitive access. Patent estate consolidation around stacked Bt configurations represents the critical defensive lever.
For New Entrants and Emerging Players: Online agronomy platforms offer the fastest route to bypass entrenched cooperative distribution. Myanmar's Ayeyarwady Division presents unpenetrated white-space for rain-fed adapted hybrid varieties. Blockchain traceability partnerships with EU and Japanese textile brands enable premium positioning without legacy trait licensing burdens. Target research institution field-testing relationships in Maharashtra cooperative networks for accelerated variety validation.
For Investors and Strategic Acquirers: Roll-up economics work for regional hybrid specialists with deep cooperative distribution because India's PLI textile scheme concentrates certified seed procurement into volume-contracted aggregators. Acquisition candidates include germplasm aggregators with documented landrace collections and service-bundled platform operators linking digital agronomy to pest management protocols. Watch for gene-editing regulatory clarity in India's Department of Biotechnology and China's Ministry of Agriculture as the inflection signal determining R&D allocation between conventional breeding and biotech pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| RNA Interference Pipeline Investment | Maharashtra cooperatives field-test siRNA-treated seed for 2024-25, eliminating refuge planting requirements. |
| Blockchain Traceability Partnership | Pacific Jeans and Saitex pilot distributed ledger systems linking farm-level seed batch records to garment certification. |
| Gene-Editing Regulatory Pre-Positioning | India's Department of Biotechnology and China's Ministry of Agriculture draft CRISPR-derived variety frameworks. |
| Cooperative Network Deepening | Mahyco anchors position through distribution into Maharashtra and Karnataka cooperative networks. |
| Optical Sorting Infrastructure Retrofit | Gujarat processors retrofit conditioning facilities to meet India's BIS certification tightening for germination standards. |
Research Methodology
Coverage spans India, China, Vietnam, Bangladesh, and Australia, with primary inputs from each market's stakeholder ecosystem. The analysis combines interviews with seed company agronomists, cooperative society procurement managers, textile mill sourcing directors, and regulatory affairs leads at India's CEA and China's MEE with secondary validation from customs germplasm import records, BIS certification databases, and PLI scheme participation disclosures. Bottom-up variety-level shipment data triangulates against top-down ginning capacity estimates across Maharashtra and Gujarat.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. The analytical framework models segmentation by seed type, end user procurement authority, distribution channel, and application specification, with additional dimensioning by trait-stack complexity and certification tier. CAGRs derive from acreage expansion trajectories in Vietnam and Bangladesh contract farming zones, Bt penetration rates in Maharashtra irrigated belts, and organic seed adoption curves for EU and Japanese textile supply chains.
The model assumes a particular technology adoption path; alternative pathways for RNA interference and gene-editing would alter the outlook if regulatory clarity accelerates ahead of transgenic approval timelines. Forecasts reflect assumptions on monsoon precipitation patterns in Deccan Plateau zones and Chinese MEE trait approval velocity. Practitioners should monitor India's Department of Biotechnology CRISPR framework drafts and Bangladesh garment sector backward integration announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Sri Lanka Seed Market
Seeds
Asia-Pacific Rice Seed Market
Seeds
Nepal Seeds Market
Seeds
South America Quinoa Seeds Market
Seeds
Fruit Tomatoes Seed Market
Seeds
Africa Sorghum Seed Market
Seeds
India Forage Seed Market
Seeds
North America Tomato Seed Market
Seeds
Cherry Tomato Seeds Market
Seeds
Global Wheat Seed Market
Seeds
Crambe Abyssinica Seed Oil Market
Seeds
Southeast Asia Seed Market
Seeds
Global Rice Seed Market
Seeds
Okra Seed Market
Seeds
Spain Forage Seed Market
Seeds
Pumpkin Seeds Market