
 Glycerol Esters of Wood Rosins Market | 2026-2036
Glycerol Esters of Wood Rosins Market Size, Share, and Industry Trends Forecast 2026-2036
Glycerol Esters of Wood Rosins Market Foresight
Specialty beverage formulators are unwinding reliance on traditional gum bases as glycerol esters of wood rosins penetrate citrus oil stabilization. Eastman Chemical Company leverages backward integration into tall oil refining to secure rosin feedstock. Arakawa Chemical Industries anchors Asia-Pacific supply through hydrogenated rosin derivative capacity in Japan. Ingevity Corporation differentiates via pine chemistry expertise spanning adhesives and food-grade applications.
Glycerol esters of wood rosins are reaction products of glycerol with refined wood rosin acids, typically yielding Gardner color grades of 4-8 and softening points between 80°C and 100°C for tackifier and emulsifier functions. Natural glycerol esters dominate adhesive formulations where pale color and oxidative stability command premium positioning. Synthetic glycerol esters are gaining fastest in ink resins as printers seek consistent viscosity under high-speed web conditions. Modified glycerol esters capture margin pools in food additive grades where FDA and EFSA compliance requires fractional distillation and hydrogenation steps.
FDA food additive regulations under 21 CFR 172.735 govern glycerol ester usage in beverages, while REACH restricts residual abietic acid content in European industrial grades. EFSA evaluations of rosin derivative genotoxicity continue shaping reformulation timelines for food-contact applications. Stakeholders must monitor evolving biobased certification standards from USDA and evolving F-Gas Regulation thresholds that indirectly affect rosin-derived alternatives in sealant applications.
Market Dynamics
REACH compliance in Europe is forcing fractional distillation upgrades across the glycerol esters supply base, compressing margins for non-integrated compounders while hydrogenated grades capture premium positioning in food-contact applications.
Growth Catalysts
- Citrus beverage stabilization:Beverage manufacturers are expanding glycerol ester use as weighting agents in citrus-flavored carbonated drinks, displacing traditional brominated vegetable oil formulations under FDA 21 CFR 172.735.
- Biobased certification pull:USDA BioPreferred program requirements are accelerating demand for tall oil-derived esters in adhesive applications where end-users require renewable content documentation.
- China flavor compounder localization:Domestic modified ester resin capacity in Jiangsu and Zhejiang provinces is reducing import dependency for regional fragrance houses.
Market Restraints
- Tall oil rosin feedstock volatility:Crude tall oil supply concentration among Scandinavian pulp mills creates pricing pressure during kraft paper demand surges.
- Residual abietic acid limits:REACH Annex XVII restrictions on unpurified rosin derivatives block non-hydrogenated grades from European food-contact applications.
- Petroleum resin substitution:C5/C9 hydrocarbon tackifiers in hot-melt adhesives compete on cost in color-tolerant industrial bonding.
Strategic Opportunities
- India FSSAI food additive expansion:Pending approvals for glycerol ester emulsifiers in flavored dairy beverages open formulation access to 1.4 billion consumers.
- UV-curable ink convergence:Hybrid rosin-acrylate oligomers are penetrating high-speed web offset printing where photoinitiator compatibility demands novel resin architectures.
- Direct-to-compounder e-commerce:Specialty chemical platforms are disintermediating traditional distributor networks for sub-ton adhesive ingredient orders.
Industry Challenges
- Hydrogenation catalyst expertise scarcity:Food-grade ester production requires specialized palladium catalyst management that few compounders maintain in-house.
- Multi-jurisdiction certification lag:Simultaneous FDA, EFSA, and JECFA evaluations extend time-to-market for new modified ester variants by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glycerol Esters of Wood Rosins Market |
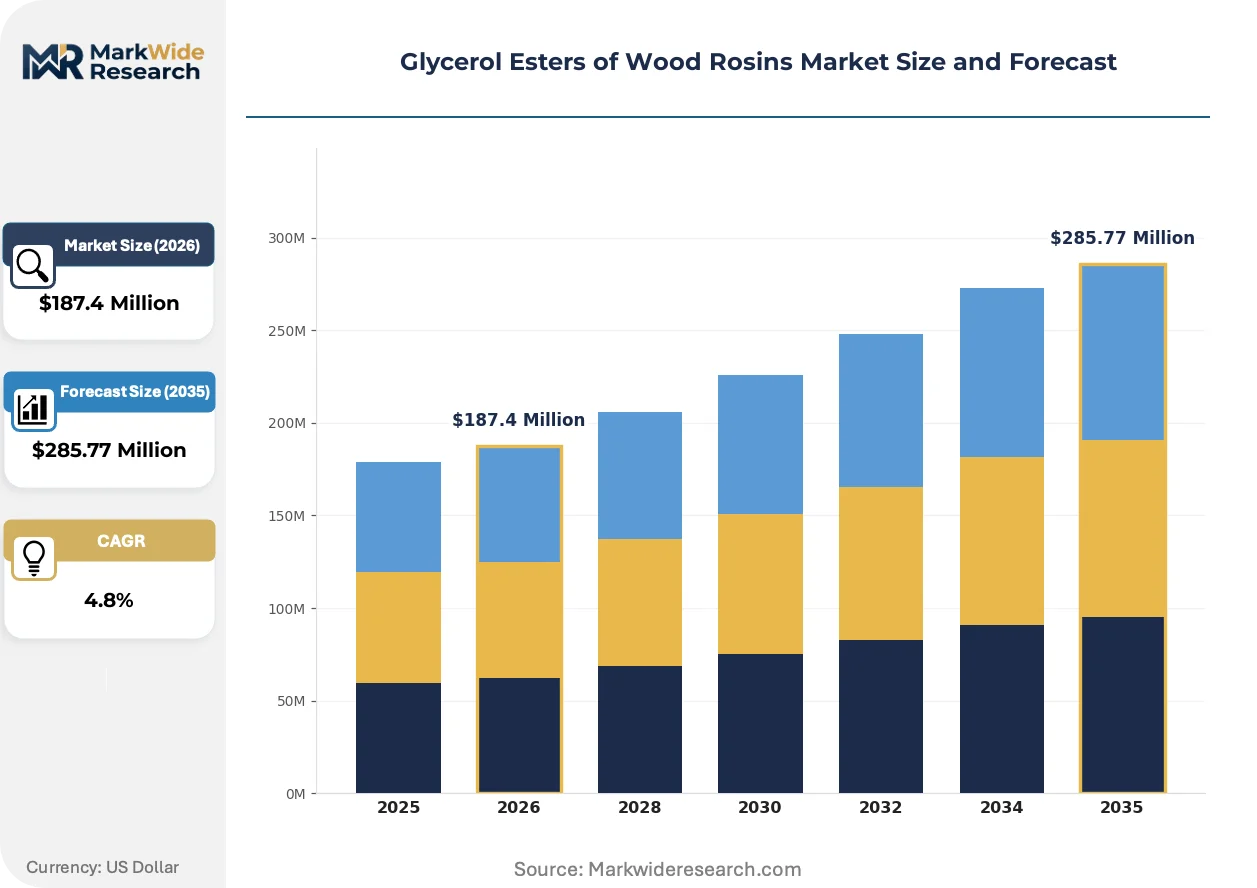
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Glycerol Esters, Synthetic Glycerol Esters, Modified Glycerol Esters, Blended Glycerol Esters End Use Industry: Adhesives, Coatings, Ink, Food Additives Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers Packaging Type: Bags, Drums, Bulk Containers, Pails |
| Companies Covered | Eastman Chemical Company, Arakawa Chemical Industries, Ingevity Corporation, Kraton Corporation, DRT, Florachem, Pinova, Foodchem International Corporation, Foshan Baolin Chemical Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glycerol Esters of Wood Rosins Market Shifts & Advancements
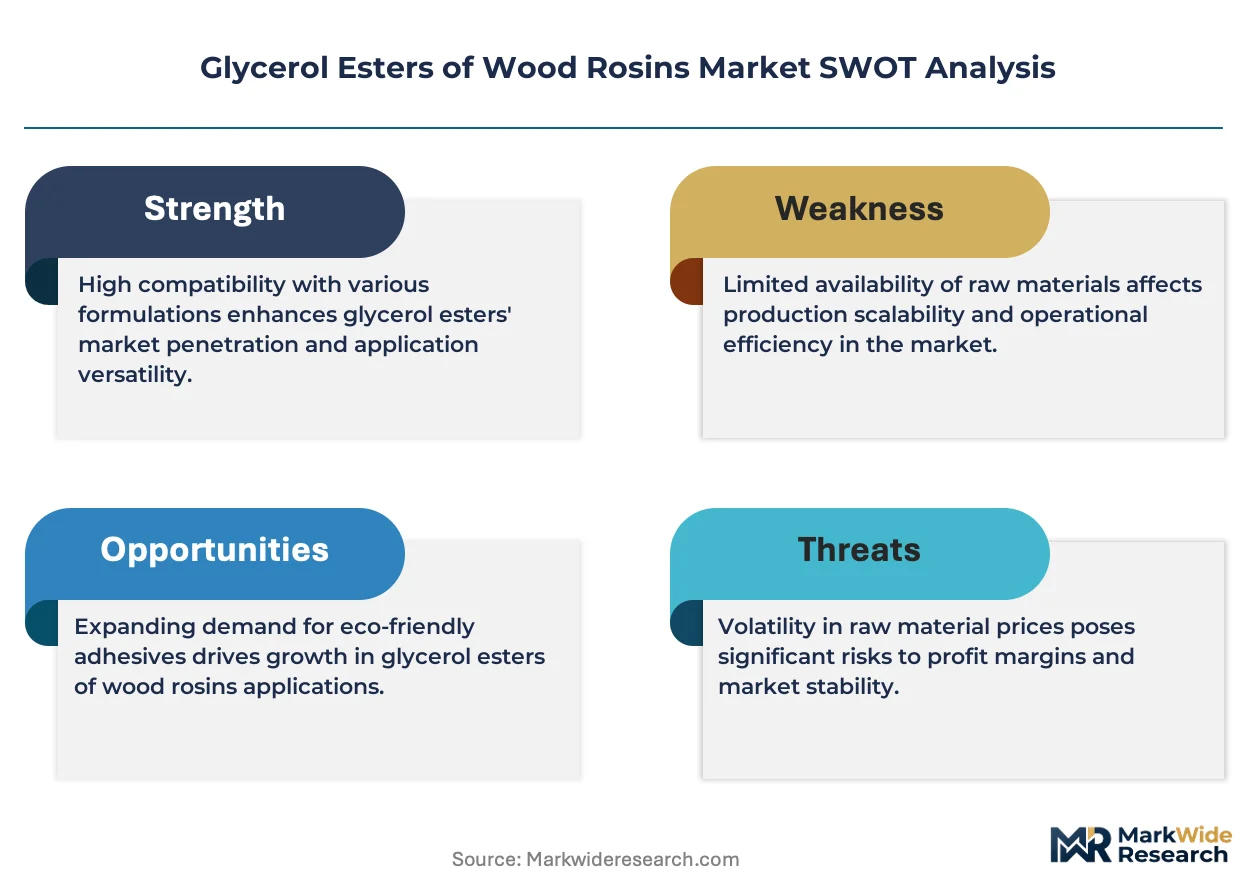
Formulation science around glycerol esters is fragmenting along purity-grade lines, with hydrogenated derivatives commanding technical investment while standard industrial grades face commoditization pressure from petroleum alternatives.
Synthetic glycerol ester production is bifurcating from natural tall oil routes as ink resin formulators prioritize batch-to-batch viscosity consistency over biobased content claims. High-speed web offset printers in Germany and Japan are adopting these synthetic grades to reduce fountain solution adjustment frequency. The resulting specification divergence is compressing margins for multi-grade producers unable to dedicate separate hydrogenation trains.
EFSA genotoxicity reassessments of rosin derivatives are tightening purity thresholds for food-contact applications across EU member states. Hydrogenated glycerol ester producers with in-house fractional distillation capacity are capturing reformulation contracts from citrus beverage compounders. Non-compliant imports from non-EU suppliers are facing elevated border inspection rates under RASFF alert protocols.
Compounders are consolidating purchase orders through regional distribution hubs to reduce freight exposure on rosin derivative shipments. Mid-sized adhesive manufacturers in the US Southeast are shifting from spot procurement to annual volume agreements with tall oil refiners. This concentration pattern is most pronounced in Georgia and the Carolinas, where transportation costs previously eroded margins on less-than-truckload deliveries.
Glycerol Esters of Wood Rosins Market Segmentation
Margin capture in glycerol esters of wood rosins hinges on purity grades and certification tiers. Product type and end-use specifications create divergent profitability pools across adhesive, food-contact, and ink resin applications.
Product Type:
Premium positioning concentrates in hydrogenated and modified grades where FDA and EFSA compliance commands price premiums over standard industrial esters.
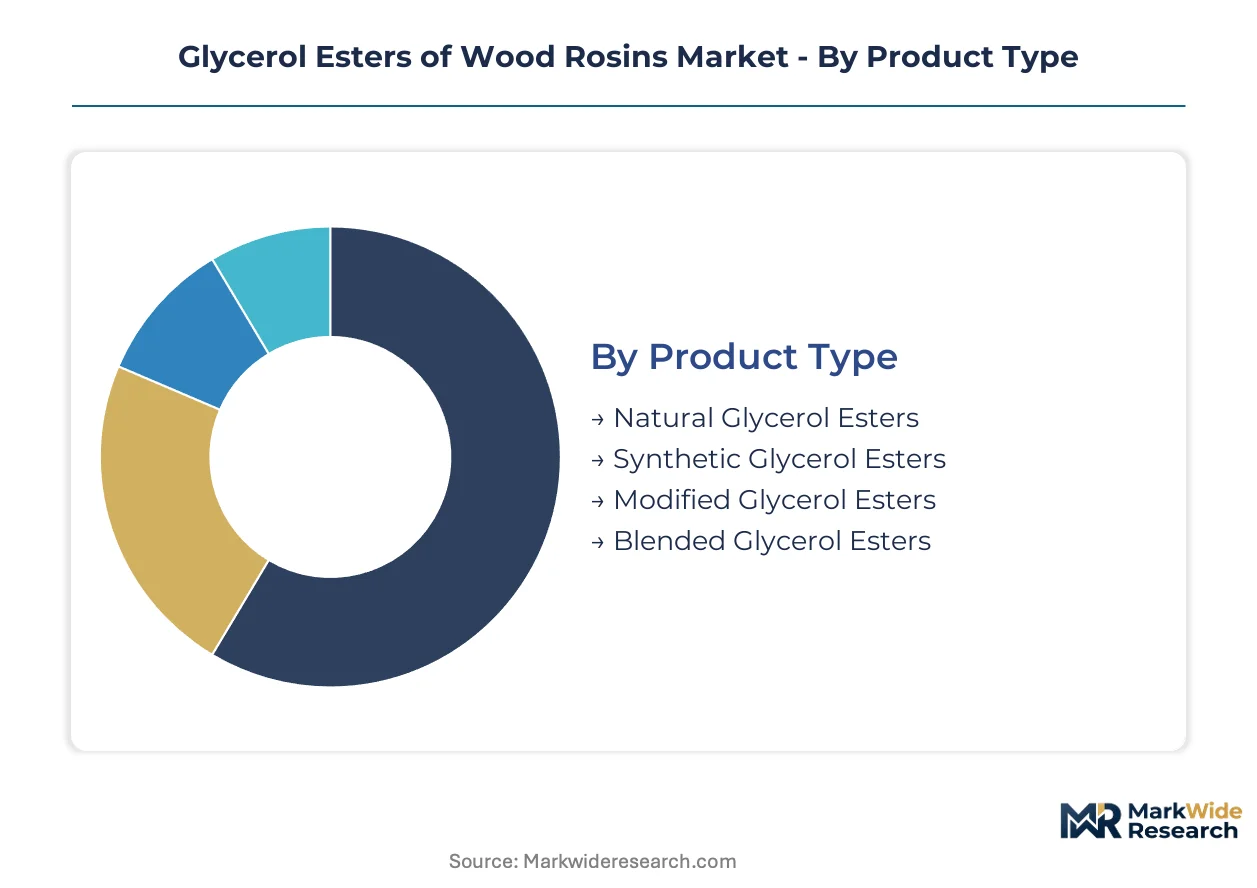
- Natural Glycerol Esters:Derived from tall oil rosin through direct esterification with glycerol, yielding Gardner color grades of 4-8 and softening points between 80°C and 100°C. Adhesive formulators in the US Southeast specify these grades for pale-color applications where oxidative stability determines supplier selection.
- Synthetic Glycerol Esters:Manufactured via controlled synthesis routes that deliver batch-to-batch viscosity consistency independent of rosin feedstock variability. German and Japanese high-speed web offset printers are adopting these grades to reduce fountain solution adjustment frequency and press downtime.
- Modified Glycerol Esters:Hydrogenated and fractionally distilled variants meeting food-contact purity thresholds under 21 CFR 172.735 and REACH Annex XVII limits on residual abietic acid.
- Blended Glycerol Esters:Custom-formulated combinations balancing cost and performance for specific adhesive tackifier requirements.
The dominant share belongs to Natural Glycerol Esters, while Modified Glycerol Esters is closing the gap fastest.
End Use Industry:
Application-level margins split between commodity adhesive volumes and specialty food-grade certifications requiring dedicated hydrogenation capacity.
- Adhesives:Hot-melt and pressure-sensitive formulations consume standard-grade esters where biobased content claims under USDA BioPreferred specifications influence procurement decisions. Georgia and Carolina-based manufacturers are consolidating annual volume agreements with tall oil refiners to reduce freight exposure.
- Food Additives:Citrus beverage stabilization under FDA 21 CFR 172.735 demands hydrogenated glycerol esters with fractional distillation provenance. EFSA genotoxicity reassessments are tightening purity thresholds and elevating border inspection rates for non-compliant imports under RASFF protocols.
- Coatings:Sealant and varnish applications competing with petroleum-derived C5/C9 tackifiers on cost in color-tolerant industrial bonding.
- Ink:UV-curable and conventional web offset formulations where synthetic ester grades are displacing natural variants for viscosity consistency.
Adhesives commands the largest volume position, though Food Additives exhibits the steepest expansion trajectory as beverage formulators unwind brominated vegetable oil reliance.
Distribution Channel:
Channel economics reflect order scale fragmentation, with sub-ton quantities shifting toward direct digital procurement while bulk volumes retain traditional distributor relationships.
- Direct Sales:Annual volume agreements between adhesive manufacturers and tall oil refiners in the US Southeast, capturing freight savings through consolidated procurement.
- Distributors:Regional hub consolidation serving mid-sized compounders with multi-grade inventory and technical support.
- Online Retail:Specialty chemical platforms disintermediating traditional networks for sub-ton adhesive ingredient orders.
- Wholesalers:Bulk container aggregation for industrial-scale coating and adhesive operations.
Direct Sales retains the dominant share, while Online Retail is expanding most quickly as procurement digitization penetrates specialty chemical sourcing.
Packaging Type:
Packaging selection correlates with end-use scale and handling automation, with bulk formats commanding freight efficiency and small containers serving formulation flexibility.
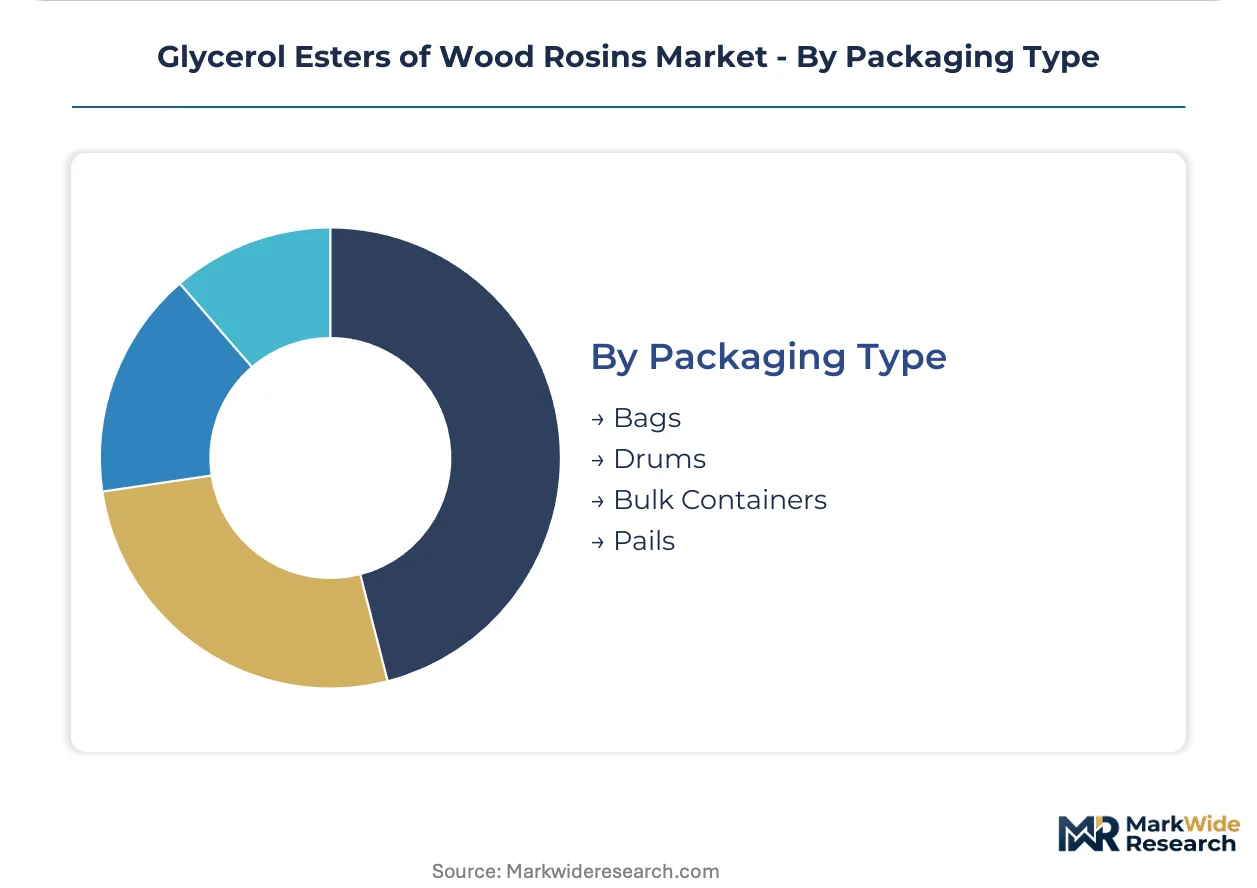
- Bulk Containers:Tanker and tote deliveries for high-volume adhesive manufacturers with dedicated storage and metered dispensing systems.
- Drums:Standard 55-gallon steel and fiber formats for mid-scale coating and ink compounders with moderate throughput requirements.
- Bags:Multi-wall paper and PE-lined formats for powder or flake ester grades in hot-melt adhesive compounding.
- Pails:5-gallon and smaller containers for specialty food-grade samples and R&D formulation work.
Bulk Containers holds the dominant position among high-volume adhesive operations, while Drums maintains the broadest cross-industry penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scandinavian tall oil refiners export hydrogenated rosin derivatives to German beverage compounders and Chinese adhesive manufacturers, anchoring trans-Atlantic and Asia-Pacific supply corridors.
United States
Georgia and Carolina-based adhesive manufacturers consolidate annual volume agreements with domestic tall oil refiners to reduce freight exposure on less-than-truckload deliveries. FDA 21 CFR 172.735 governs food-grade ester usage in citrus beverages, tightening purity documentation requirements. The US Southeast industrial cluster around Atlanta and Charlotte captures procurement digitization trends as mid-sized compounders shift from spot buying to contracted supply.
Germany
High-speed web offset printers in the Rhine-Ruhr and Baden-Württemberg regions adopt synthetic glycerol ester grades to reduce fountain solution adjustment frequency. REACH Annex XVII restrictions on residual abietic acid block non-hydrogenated imports from non-EU suppliers under elevated RASFF border inspection protocols. The Frankfurt chemical corridor hosts fractional distillation capacity serving pan-European beverage reformulation demand.
China
Jiangsu and Zhejiang provinces scale domestic modified ester resin capacity to reduce import dependency for regional fragrance and flavor houses. SAMR food additive regulations align with evolving FSSAI consultation frameworks for cross-border formulation approvals. The Yangtze River Delta chemical cluster concentrates hydrogenation expertise for food-contact grade production.
Japan
Arakawa Chemical Industries anchors Asia-Pacific supply through hydrogenated rosin derivative capacity serving ink resin and adhesive formulators. METI industrial standards govern tackifier specifications for pressure-sensitive applications. The Osaka-Kobe manufacturing belt maintains specialized palladium catalyst management capabilities that compounders elsewhere struggle to replicate.
India
Pending FSSAI approvals for glycerol ester emulsifiers in flavored dairy beverages open formulation access to domestic dairy processors. BIS purity standards for food-contact rosin derivatives remain under harmonization with Codex Alimentarius frameworks. Maharashtra and Gujarat chemical zones attract toll-manufacturing contracts from multinational beverage compounders seeking localized supply.
Glycerol Esters of Wood Rosins Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with publicly traded chemical conglomerates commanding hydrogenation capacity while family-owned rosin processors retain niche adhesive positions. The vendor base splits between backward-integrated tall oil refiners and formulation-focused compounders lacking upstream feedstock control. Three archetypes dominate: Scandinavian pulp-integrated refiners, Asian hydrogenation specialists, and North American pine chemistry diversifiers. Competitive moves concentrate on captive tall oil supply agreements and fractional distillation capacity additions for food-grade compliance.
Among North American pine chemistry diversifiers, Ingevity Corporation exemplifies the adhesive-to-food-grade pivot, while Eastman Chemical Company occupies a position reflecting backward integration into tall oil refining. Arakawa Chemical Industries represents the Asia-Pacific hydrogenation specialist archetype, anchoring regional supply through captive Japanese capacity. These three names illustrate how geographic feedstock access and certification tier concentration stratify competitive positioning across the value chain.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Arakawa Chemical Industries |
| Ingevity Corporation |
| Kraton Corporation |
| DRT |
| Florachem |
| Pinova |
| Foodchem International Corporation |
| Foshan Baolin Chemical Industry |
| Others |
Supply & Pricing Matrix
Fractional distillation capacity utilization in Scandinavian tall oil refineries sets price floors for hydrogenated glycerol ester grades, concentrating margin capture among backward-integrated producers while non-integrated compounders absorb feedstock volatility. Capacity scale directly determines certification-tier pricing power, with food-grade producers commanding premiums over industrial ester suppliers facing petroleum resin substitution.
Pricing Analysis
Current-generation hydrogenated glycerol esters trade at substantial premiums over standard industrial grades and legacy natural esters, with next-generation synthetic variants capturing ink resin premiums for viscosity consistency. Three-tier pricing structure across food-grade hydrogenated, industrial natural, and synthetic ink grades reflects FDA certification status and palladium catalyst recovery costs. Price differentiation centers on REACH Annex XVII compliance and residual abietic acid thresholds, with non-compliant imports facing border rejection costs. Pricing pressure stems from C5/C9 petroleum tackifier competition in color-tolerant adhesives, where mid-sized US Southeast manufacturers exhibit highest price sensitivity versus citrus beverage compounders with formulation-switching costs.
Supply Chain Analysis
Strategic stockpiling of crude tall oil concentrates among Scandinavian pulp-integrated refiners contrasts with just-in-time procurement patterns among Asian hydrogenation specialists. Supply concentrates in Sweden, Finland, and Japan, with China scaling Jiangsu and Zhejiang capacity to reduce import dependency. Feedstock draws from kraft paper mill byproduct streams, palladium catalyst supply, and glycerol refinement operations. Single-source vulnerability runs through Scandinavian crude tall oil concentration during pulp demand surges. Distribution runs through regional chemical hubs serving adhesive compounders, with direct refiner relationships capturing freight efficiency on bulk volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as beverage formulators accelerate brominated vegetable oil displacement under FDA 21 CFR 172.735, creating sustained formulation-switching demand for hydrogenated grades. Citrus oil stabilization adoption in emerging dairy beverage categories extends addressable market boundaries beyond carbonated drinks.
For Market Incumbents: Fortify captive tall oil supply agreements with Scandinavian pulp mills to secure feedstock priority during kraft paper demand cycles. Expand fractional distillation capacity in food-grade corridors before EFSA genotoxicity reassessments tighten purity thresholds further. Hydrogenation catalyst management expertise represents a defensible moat against commodity industrial ester competition. For New Entrants and Emerging Players: Technical service gaps in sub-ton adhesive formulation support present white-space opportunities for digital-native specialty chemical platforms. India FSSAI approval timelines for flavored dairy emulsifiers offer the most penetrable regulatory entry point among major consumer markets. Direct-to-compounder e-commerce models circumvent entrenched distributor relationships in fragmented US Southeast adhesive manufacturing clusters. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hydrogenation specialists with in-house fractional distillation over commodity industrial ester processors facing petroleum substitution. Long-term viability hinges on food-contact certification tier concentration rather than adhesive volume scale. Acquisition targets should demonstrate palladium catalyst recovery efficiency and multi-jurisdiction regulatory dossier depth. The signal to watch is EFSA purity threshold tightening velocity, which accelerates reformulation contract capture by compliant producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tall Oil Refining | Eastman Chemical's captive feedstock secures margin stability against Scandinavian supply volatility. |
| Hydrogenation Capacity Expansion | Arakawa Chemical's Japanese fractional distillation captures EFSA-driven reformulation demand from German beverage compounders. |
| Digital Platform Disintermediation | Specialty chemical e-commerce platforms reduce distributor capture on sub-ton adhesive ingredient orders. |
| Multi-Jurisdiction Certification Investment | Simultaneous FDA, EFSA, and JECFA dossier preparation compresses time-to-market for modified ester variants. |
| Regional Hub Consolidation | Georgia and Carolina manufacturers shift from spot procurement to annual volume agreements reducing freight exposure. |
Research Methodology
Operator-level perspectives from tall oil refinery managers, adhesive procurement leads at US Southeast manufacturers, citrus beverage formulation directors, and hydrogenation catalyst specialists anchored the qualitative base. Secondary validation drew from FDA 21 CFR filings, EFSA scientific opinions, REACH Annex XVII regulatory texts, and SEC 10-K disclosures from pine chemistry diversifiers. Bottom-up volume estimates from end-use consumption patterns triangulated against top-down tall oil production capacity assessments.
Sensitivity analysis tested forecast robustness across feedstock price volatility scenarios, regulatory approval timeline variations, and petroleum resin substitution elasticity assumptions. Segmentation modeling spanned product grade tiers, end-use industries, packaging formats, and regional production hub classifications. CAGRs derived from historical volume trajectories adjusted for formulation-switching adoption curves and certification lag effects. Industry-specific inputs included kraft paper demand cyclicality, palladium catalyst cost trajectories, and multi-jurisdiction approval pipeline status.
Underlying assumptions cover EFSA genotoxicity reassessment timelines, FSSAI approval progression for dairy applications, and crude tall oil supply concentration persistence, with deviation risk concentrated in regulatory threshold tightening velocity and petroleum resin cost competitiveness. Revision becomes warranted when hydrogenated grade purity requirements cross thresholds that strand non-integrated compounder capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Global Oxidized Polyethylene Wax Market
Oleochemicals
Iso-Octene Market
Oleochemicals
Isostearic Acid Market
Oleochemicals
Hydrocarbon Waxes Market
Oleochemicals
Disodium Oleamido MIPA Sulfosuccinate Market
Oleochemicals
North America Alcohol Ethoxylates Market
Oleochemicals
2-Hexyldecanol Market
Oleochemicals
US Esters Market
Oleochemicals
Tall Oil Rosin Market
Oleochemicals
Ethylhexyl Cocoate Market
Oleochemicals
Petrolatum Market
Oleochemicals
Glycerol Monostearate Market
Oleochemicals
Lauryl Betaine Market
Oleochemicals
Propane-1,2-Diol Esters Of Fatty Acid Market
Oleochemicals
Estolides Market
Oleochemicals
Partially Hydrogenated Oil Market