
 Disodium Oleamido MIPA Sulfosuccinate Market | 2026-2036
Disodium Oleamido MIPA Sulfosuccinate Market Size, Share, and Industry Trends Forecast 2026-2036
Disodium Oleamido MIPA Sulfosuccinate Market Insights
Green surfactant synthesis is narrowing the performance gap between petrochemical and bio-based feedstocks in sulfosuccinate manufacturing. Innospec leverages its integrated alkoxylation capabilities to secure oleochemical supply streams from North American and Southeast Asian sources. BASF SE anchors European production through its Ludwigshafen complex, where sulfosuccinate output feeds regional personal care compounders. Evonik AG differentiates via amino acid-derived surfactant technology that competes directly with oleamido MIPA chemistries in mild cleansing applications.
Disodium oleamido MIPA sulfosuccinate is an anionic surfactant synthesized through the sulfonation and esterification of oleic acid derivatives with maleic anhydride, then neutralized with sodium salts to yield a mild, foaming agent with pH tolerance between 5.0 and 8.0. Its primary commercial purpose centers on sulfate-free personal care formulations where reduced irritation profiles support facial cleansers, baby shampoos, and sensitive-skin body washes. Surfactants occupy the dominant product type position due to irreplaceable foaming and cleansing functionality across cosmetics and personal care applications. Industrial cleaning represents the fastest-growing application segment as institutional buyers replace conventional alkylbenzene sulfonates with biodegradable alternatives in hard-surface and vehicle-cleaning concentrates.
REACH registration requirements and the EU Green Deal's chemical sustainability taxonomy are elevating compliance costs for importers of oleochemical feedstocks into European formulation facilities. The US EPA Safer Choice program and state-level disclosure mandates in California are simultaneously redirecting procurement toward fully characterized sulfosuccinate grades with transparent supply chain documentation. Formulators and raw material distributors must monitor evolving biodegradability test protocols under OECD guidelines and adapt qualification workflows before next-generation mild surfactant specifications solidify across major personal care brand portfolios.
Market Dynamics
REACH registration requirements and the EU Green Deal's chemical sustainability taxonomy are elevating compliance costs for oleochemical feedstock importers into European formulation facilities. This regulatory compression is forcing sulfosuccinate manufacturers to requalify supply chains while premium personal care brands accelerate sulfate-free formulation transitions.
Growth Catalysts
- REACH and EU Green Deal standards:Tightened chemical disclosure rules in Europe are compelling formulators to source fully characterized, biodegradable sulfosuccinate grades with transparent supply chain documentation.
- Sulfate-free personal care formulations:Premium cosmetics brands in Germany's Rhine-Ruhr chemical cluster are specifying mild, biodegradable cleansing agents for facial cleansers and sensitive-skin body washes.
- Oleochemical feedstock availability:Integrated alkoxylation capabilities at major producers are securing reliable supply streams from North American palm and Southeast Asian coconut oil sources.
Market Restraints
- Oleic acid price volatility:Weather-driven fluctuations in palm and coconut oil harvests create input cost instability that compresses sulfosuccinate margins.
- Supply concentration in Ludwigshafen:BASF SE's European production anchoring creates geographic single-point vulnerability for regional personal care compounders.
- Amino acid surfactant substitution:Evonik AG's competing mild cleansing chemistries are capturing formulation slots in premium baby shampoo and facial cleanser segments.
Strategic Opportunities
- US EPA Safer Choice program:Federal procurement preferences and California state-level disclosure mandates are redirecting institutional buyers toward fully documented sulfosuccinate grades.
- Industrial cleaning concentrates:Hard-surface and vehicle-cleaning formulators are replacing conventional alkylbenzene sulfonates with biodegradable sulfosuccinate alternatives.
- Green surfactant synthesis convergence:Advances in enzymatic esterification combined with carbon-neutral hydrogenation are narrowing performance gaps between petrochemical and bio-based feedstocks.
Industry Challenges
- OECD biodegradability test protocol adaptation:Formulators must requalify mild surfactant specifications under evolving aquatic toxicity and biodegradation standards before next-generation brand portfolio deadlines.
- Alkoxylation capex intensity:In-house production of ethoxylated oleochemical intermediates requires significant reactor investment that mid-scale sulfosuccinate producers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disodium Oleamido MIPA Sulfosuccinate Market |
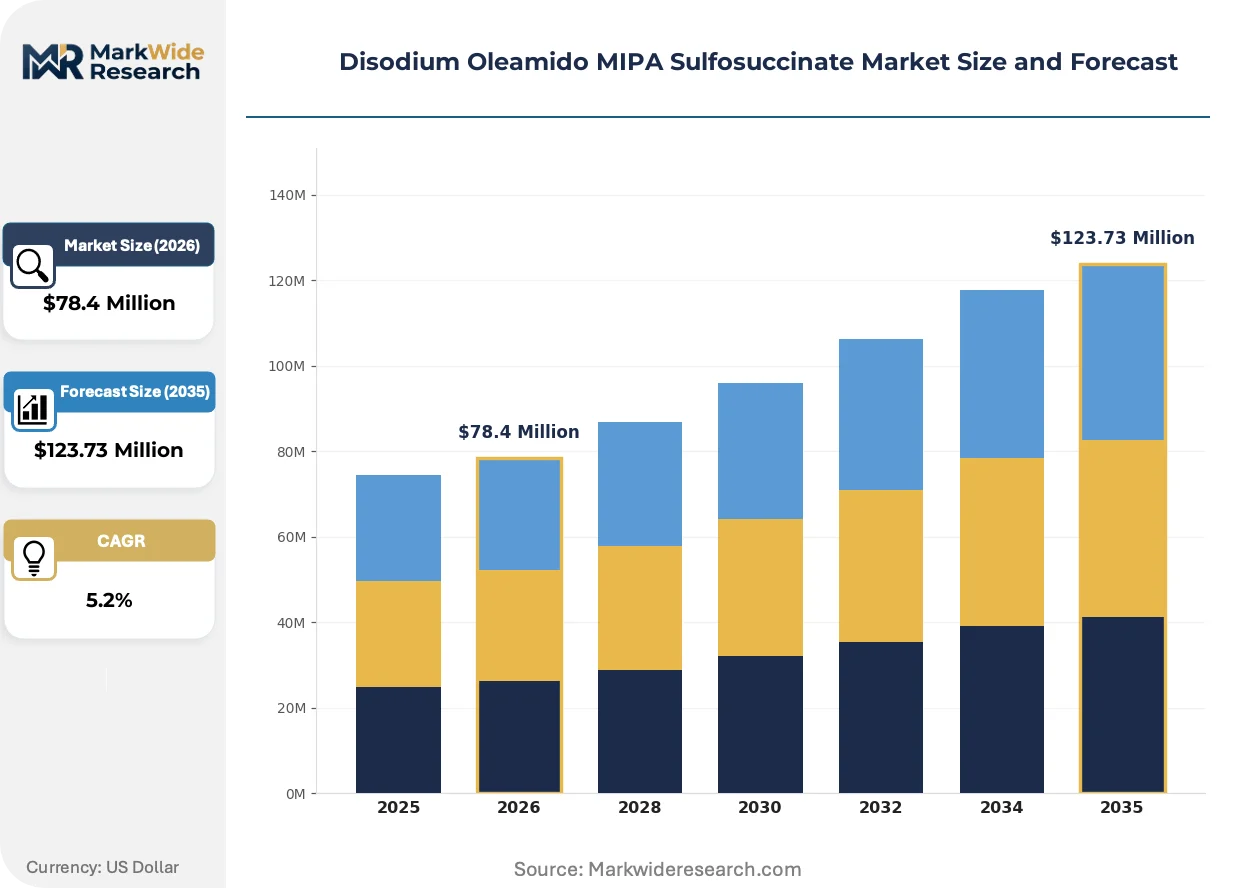
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $123.73 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surfactants, Emulsifiers, Stabilizers, Texturizers Application: Cosmetics, Personal Care, Household Products, Industrial Cleaning End User: Manufacturers, Retailers, Distributors, OEMs Distribution Channel: Online, Offline, Direct Sales, Third-Party Retailers |
| Companies Covered | Innospec, Nouryon, Cedar Concepts Corporation, Colonial Chemical, Clariant AG, BASF SE, Evonik AG, Croda International, MFG Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disodium Oleamido MIPA Sulfosuccinate Market Trends and Innovations
Green chemistry advances are compressing the performance differential between petroleum-derived and plant-based surfactant feedstocks. Formulation science is pivoting toward enzymatic processes that reduce solvent intensity while maintaining mildness profiles.
Enzymatic esterification using immobilized lipase catalysts is rendering obsolete traditional acid-catalyzed sulfosuccinate synthesis routes that required high-temperature conditions and generated significant solvent waste. Premium personal care compounders in Germany and France are qualifying these biocatalytic grades for facial cleanser launches. The technology is compressing capital requirements for mid-scale producers while tightening purity specifications that legacy petrochemical routes struggle to meet.
REACH registration dossier updates under the EU Green Deal's chemical sustainability taxonomy are forcing sulfosuccinate importers to submit extended safety data sets covering endocrine disruption and persistent bioaccumulative toxicity endpoints. The industrial consequence is a 12-18 month requalification timeline for existing supply contracts. Personal care brands with 2027 formulation refresh cycles are most affected, with several accelerating audits of Southeast Asian oleochemical suppliers.
Specification-driven procurement is consolidating buyer power among premium cosmetics houses that now require full supply chain documentation from oleochemical plantation to finished surfactant. Traditional distributors lacking batch-level traceability are losing shelf position to integrated producers with captive alkoxylation and sulfonation assets. This pattern is most visible in the Rhine-Ruhr cluster, where formulators serving multinational beauty brands have eliminated non-integrated trading houses from approved vendor lists.
Disodium Oleamido MIPA Sulfosuccinate Market Segmentation
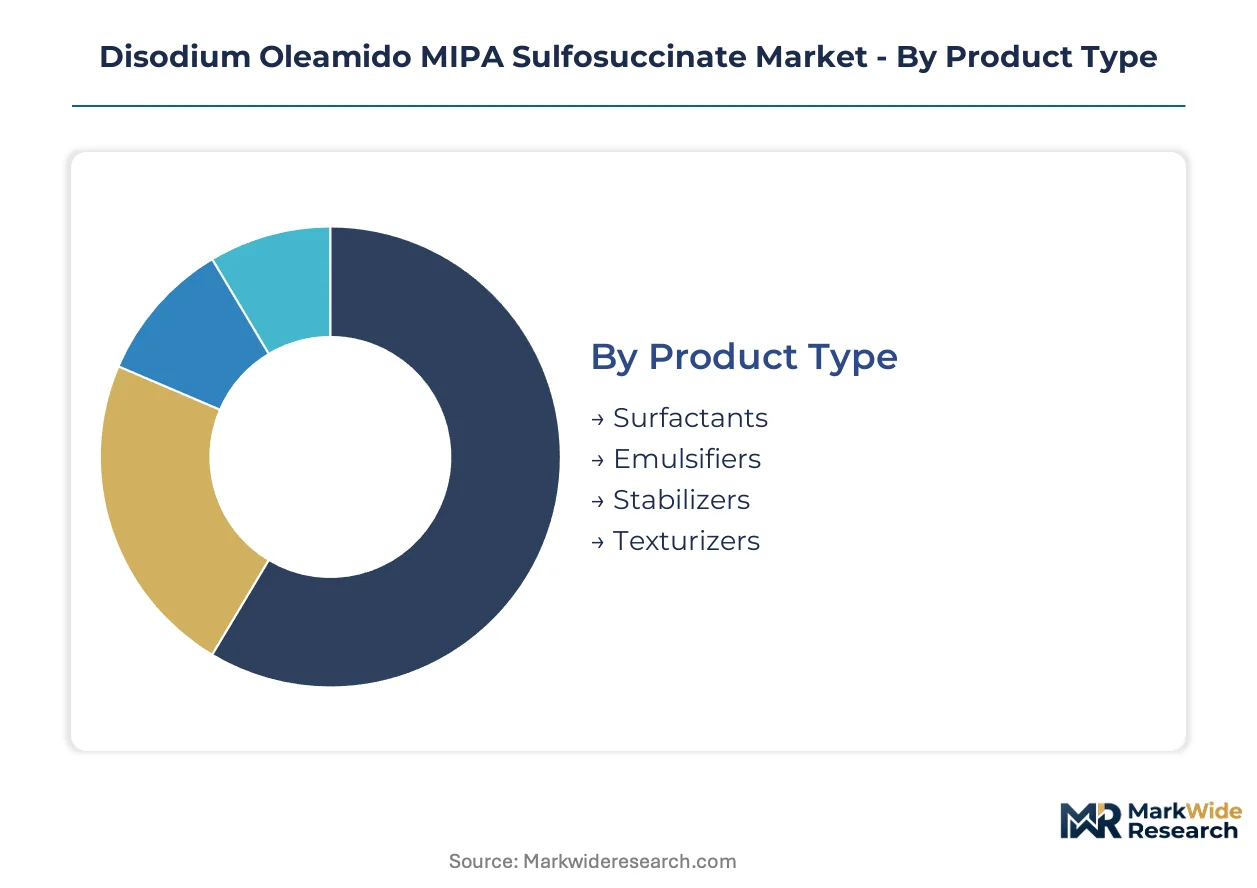
Segmentation reveals how sulfosuccinate value pools concentrate across formulation technologies and procurement channels. Technical specification requirements vary sharply between premium personal care compounders and industrial bulk buyers, reshaping supplier qualification protocols.
Product Type:
After-sales service intensity escalates with formulation complexity, as surfactant grades require ongoing technical support for pH stability and compatibility troubleshooting.
- Surfactants:Anionic foaming agents derived from oleic acid sulfonation deliver mild cleansing with pH tolerance between 5.0 and 8.0. Rhine-Ruhr formulators specify these grades for sulfate-free facial cleansers and baby shampoos as REACH disclosure rules tighten.
- Emulsifiers:Amphiphilic molecules stabilize oil-water interfaces in cream and lotion matrices. Demand concentrates among German premium cosmetics houses seeking batch-level traceability from oleochemical plantation to finished ingredient.
- Stabilizers:Rheology modifiers prevent phase separation in sensitive-skin formulations.
- Texturizers:Sensory enhancers adjust viscosity and spreadability in high-end body washes.
Surfactants hold the largest share; momentum sits with emulsifiers as clean-label skincare launches accelerate.
Application:
Volume concentration tracks regulatory pressure gradients, with EU Green Deal compliance costs driving fastest adoption in geographies with binding chemical sustainability mandates.
- Cosmetics:Premium color cosmetics and skincare formulations leverage sulfosuccinate mildness for sensitive-skin positioning. French and German beauty brands now require full OECD biodegradability documentation before supplier onboarding.
- Personal Care:Sulfate-free shampoos and body washes represent the anchor demand segment. US EPA Safer Choice procurement preferences redirect institutional buyers toward fully characterized grades with transparent supply chains.
- Household Products:Dishwashing liquids and surface cleaners incorporate biodegradable alternatives to conventional alkylbenzene sulfonates.
- Industrial Cleaning:Hard-surface and vehicle-cleaning concentrates are climbing the fastest as fleet maintenance operations replace petroleum-derived surfactants with plant-based options.
Personal Care dominates current value; Industrial Cleaning shows the steepest expansion trajectory.
End User:
Margin structures diverge sharply across buyer sophistication tiers, with integrated compounders capturing value that distributors lose to specification-driven procurement consolidation.
- Manufacturers:Integrated personal care compounders with captive formulation capabilities source sulfosuccinates directly for sensitive-skin product lines. These buyers command batch-level certificates of analysis and end-to-end oleochemical traceability.
- Retailers:Private-label skincare and haircare brands specify mild surfactant grades for store-brand sulfate-free launches. Demand clusters among German drugstore chains and French pharmacy retailers with clean-label positioning.
- Distributors:Traditional chemical traders face margin compression as brands eliminate non-integrated vendors lacking alkoxylation asset backing.
- OEMs:Contract manufacturers serving multinational beauty houses require just-in-time sulfosuccinate delivery with regulatory dossier support.
Manufacturers command the greatest share; OEMs are gaining share fastest as outsourcing accelerates.
Distribution Channel:
Customer type stratification determines channel economics, with technical buyers favoring direct relationships and price-sensitive purchasers accepting third-party intermediation.
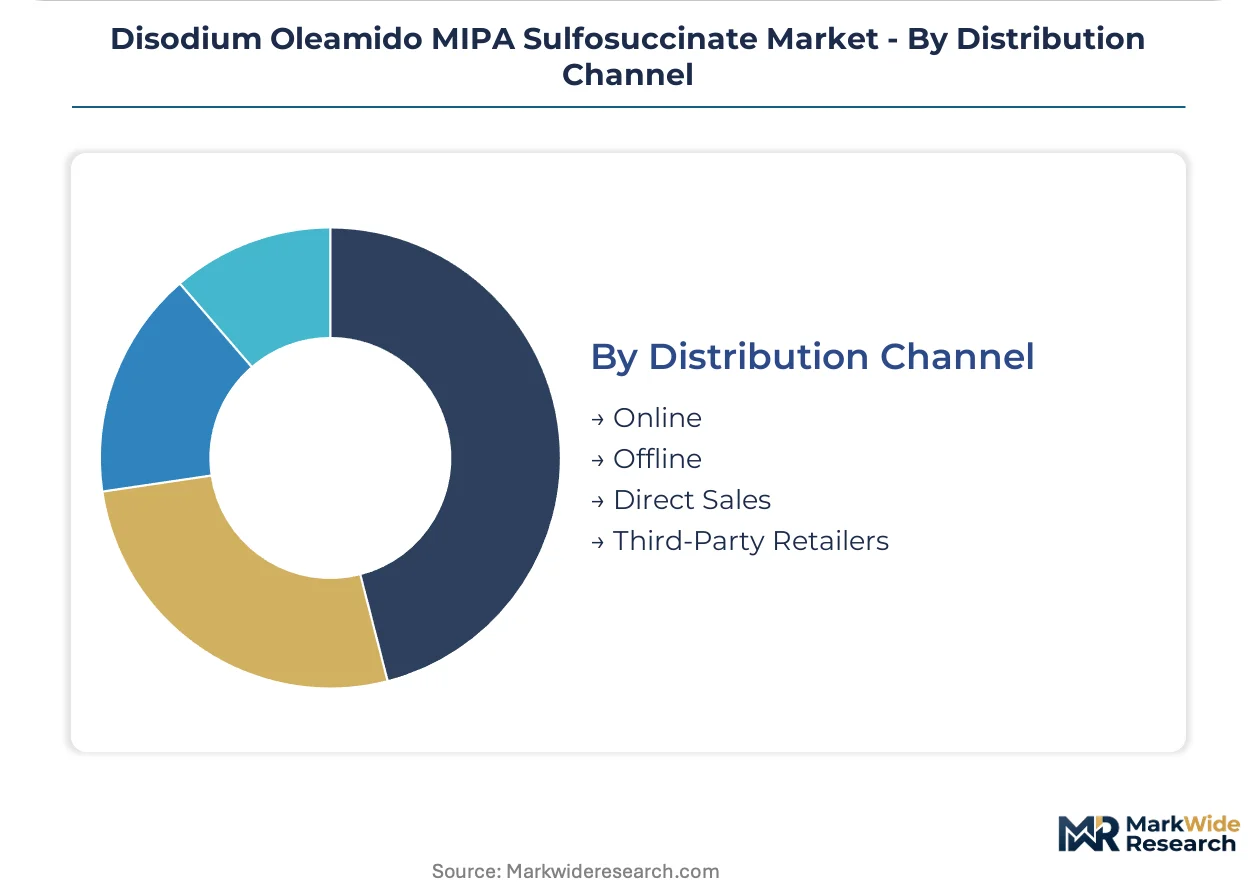
- Online:Digital procurement platforms enable mid-scale formulators to access sulfosuccinate technical data sheets and regulatory documentation. Southeast Asian oleochemical suppliers increasingly list REACH-registered grades through B2B marketplaces.
- Offline:Traditional chemical distribution networks retain relevance for buyers requiring sample evaluation and formulation guidance. German specialty chemical distributors maintain stocked warehouses serving Rhine-Ruhr cosmetics clusters.
- Direct Sales:Integrated producers with captive alkoxylation capabilities bypass intermediaries to serve premium personal care brands directly.
- Third-Party Retailers:Independent trading houses without batch traceability capabilities are losing approved vendor status across major beauty brand portfolios.
Offline channels retain the largest share; Direct Sales are expanding most quickly as specification requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian oleochemical exports flow into German formulation facilities, anchoring the Rhine-Ruhr cluster's sulfate-free surfactant supply. This trade corridor concentrates premium personal care compounder demand while REACH compliance costs reshape procurement patterns across destination markets.
Germany
Personal care formulators in the Rhine-Ruhr cluster specify mild sulfosuccinate grades for sensitive-skin facial cleansers. ECHA REACH registration dossiers now require extended endocrine disruption data, forcing 12-18 month requalification cycles. BASF SE's Ludwigshafen complex anchors European production, feeding regional cosmetics houses with batch-level traceability.
United States
EPA Safer Choice procurement preferences redirect institutional buyers toward fully documented sulfosuccinate grades. California's state-level disclosure mandates compound federal compliance requirements for hard-surface cleaning concentrates. Midwestern personal care compounders source through integrated distributors with captive alkoxylation assets.
France
Premium beauty brands in the Île-de-France region mandate OECD biodegradability documentation before supplier onboarding. ANSM cosmetic safety assessments intersect with EU Green Deal chemical sustainability taxonomy requirements. Lyon-based formulators accelerate enzymatic esterification qualification for 2027 facial cleanser launches.
China
Dual carbon goals and MEE environmental standards compress margins for conventional petrochemical surfactant routes. Yangtze River Delta oleochemical processors supply Southeast Asian sulfosuccinate manufacturers with palm-derived feedstocks. NMPA cosmetic ingredient filings now require carbon footprint disclosures for imported surfactant grades.
India
Bureau of Indian Standards certification for sulfate-free personal care products drives domestic sulfosuccinate formulation adoption. Maharashtra-based contract manufacturers serve multinational beauty brands with just-in-time surfactant delivery. CDSCO cosmetic safety assessments align with OECD biodegradability protocols for export-oriented production.
Disodium Oleamido MIPA Sulfosuccinate Market Competitive Landscape
Channel-controlling players compete with product-specialist players for formulation slot access in premium personal care portfolios. The vendor base stratifies between integrated alkoxylation operators and trading houses lacking batch traceability capabilities. Three archetypes dominate: petrochemical majors with captive oleochemical supply, regional oleochemical processors with sulfonation assets, and specialty distributors with regulatory dossier support. Competitive moves center on backward integration into ethoxylated intermediate production and strategic partnerships with Southeast Asian palm oil processors.
Within the integrated petrochemical tier, BASF SE and Evonik AG exemplify divergent strategic positioning around mild surfactant chemistry. BASF anchors European supply through its Ludwigshafen manufacturing complex, while Evonik occupies a position in amino acid-derived alternatives that compete directly with oleamido MIPA formulations. Among specialty chemical distributors, Innospec represents the channel-control archetype through integrated alkoxylation capabilities securing North American and Southeast Asian oleochemical streams. These three entities collectively illustrate how specification-driven procurement consolidation favors asset-backed players over traditional trading intermediaries.
| Leading Market Players |
|---|
| Innospec |
| Nouryon |
| Cedar Concepts Corporation |
| Colonial Chemical |
| Clariant AG |
| BASF SE |
| Evonik AG |
| Croda International |
| MFG Chemicals |
| Others |
Pricing and Supply Chain Analysis
Ludwigshafen's integrated chemical complex anchors European sulfosuccinate supply, with BASF SE's captive alkoxylation capacity translating into pricing power over Rhine-Ruhr formulators lacking alternative qualified sources. This geographic concentration lets integrated producers command premium certification-grade pricing while mid-scale compounders absorb margin compression from oleic acid feedstock volatility.
Pricing Analysis
Legacy acid-catalyzed sulfosuccinate grades trade at a discount to enzymatic biocatalytic alternatives that premium personal care brands now specify for facial cleanser launches. Three-tier pricing structure across REACH-registered premium, standard industrial, and economy spot grades reflects certification burden and batch traceability depth. Pricing pressure stems from amino acid surfactant substitution by Evonik AG in baby shampoo segments. Industrial cleaning buyers exhibit highest price sensitivity; premium cosmetics houses accept substantial premiums for end-to-end oleochemical documentation.
Supply Chain Analysis
Extended payment terms from Southeast Asian palm oil processors to German sulfosuccinate manufacturers are tightening working capital cycles across the value chain. Supply concentrates in Germany, Malaysia, and the United States, with Malaysian oleochemical exports feeding Ludwigshafen sulfonation units. Feedstock dependency rests on palm and coconut oil harvests, maleic anhydride derivatives, and sodium neutralization agents. Single-source vulnerability around BASF SE's Ludwigshafen complex exposes regional compounders to disruption risk. Distribution runs through integrated producers with direct sales forces and specialty chemical distributors with stocked regional warehouses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disodium oleamido MIPA sulfosuccinate demand is accelerating as enzymatic esterification and REACH disclosure mandates simultaneously reshape formulation procurement. The convergence of green chemistry advances with regulatory compression creates a high-growth disruption window for asset-backed players.
For Market Incumbents: Pre-empt amino acid surfactant displacement by accelerating enzymatic grade capacity expansion in the Rhine-Ruhr corridor. Secure backward integration into Southeast Asian oleochemical supply through offtake agreements with Malaysian plantation processors. Lock in multi-year supply contracts with premium cosmetics houses before 2027 formulation refresh cycles consolidate vendor lists. For New Entrants and Emerging Players: Hard-surface cleaning concentrates for US institutional buyers represent the most penetrable entry point given EPA Safer Choice procurement momentum and lower certification barriers versus personal care. Target mid-scale industrial cleaning formulators in the US Midwest lacking direct relationships with integrated European producers. Lead with transparent supply chain documentation and rapid regulatory dossier support as the primary go-to-market wedge. For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-driven specialty chemical consolidation play because specification-driven procurement is systematically eliminating non-integrated trading intermediaries. Target acquisition candidates with captive alkoxylation assets and established REACH registration dossiers. Monitor enzymatic esterification yield improvements as the critical signal for timing entry before next-generation mild surfactant specifications solidify across major brand portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleochemical Supply | Captive palm and coconut oil sourcing insulates margins from weather-driven feedstock volatility. |
| Enzymatic Esterification Capacity Buildout | Biocatalytic routes reduce solvent waste while meeting premium personal care purity specifications. |
| REACH Registration Dossier Expansion | Extended endocrine disruption data submission secures supplier status for EU Green Deal compliance. |
| Long-term Supply Agreement with Premium Cosmetics Houses | Multi-year contracts with Rhine-Ruhr formulators lock in volume before vendor consolidation accelerates. |
| Industrial Cleaning Segment Market Development | EPA Safer Choice qualification opens institutional procurement channels for biodegradable sulfosuccinate grades. |
Research Methodology
Desk research of customs trade data, ECHA REACH registration databases, and SEC chemical company filings preceded structured interviews with personal care formulation directors, oleochemical procurement managers, sulfosuccinate plant engineers, and specialty chemical distribution executives. Primary fieldwork across Germany's Rhine-Ruhr cluster, US Midwestern compounding facilities, and Malaysian oleochemical processing centers validated secondary demand indicators. Bottom-up volume modeling by grade tier and application segment was cross-checked against top-down industry association estimates.
Forecast assumptions held regulatory implementation timelines and enzymatic technology diffusion curves fixed while varying oleic acid price trajectories and amino acid surfactant substitution rates across sensitivity scenarios. Segmentation dimensions modeled include product grade tier, end-use application, buyer sophistication archetype, and regional production hub concentration. CAGRs were derived from segment-level volume buildups reconciled to aggregate market sizing. Key inputs incorporated OECD biodegradability protocol adoption schedules and EU Green Deal chemical sustainability taxonomy implementation phases.
Practitioners should monitor enzymatic esterification yield breakthroughs, REACH dossier rejection rates, and amino acid surfactant pricing moves for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Glycerol Esters Market
Oleochemicals
Europe Arachidonic Acid Market
Oleochemicals
Ethyl Linalool Market
Oleochemicals
Carbolic Oil Market
Oleochemicals
Isobutyl Stearate Market
Oleochemicals
Lauryl Betaine Market
Oleochemicals
Glycerol Diacetate Market
Oleochemicals
Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
Lactic Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
North America Alcohol Ethoxylates Market
Oleochemicals
Global Chlorinated Paraffin Market
Oleochemicals
Isopropyl Esters Market
Oleochemicals
Camphor Oil Market
Oleochemicals
Enzymatically Interesterified Oils Market
Oleochemicals
2-tert-Butylcyclohexanol Market
Oleochemicals
Paraffin Wax Market