
 Propane-1,2-Diol Esters Of Fatty Acid Market | 2026-2036
Propane-1,2-Diol Esters Of Fatty Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Propane-1,2-Diol Esters Of Fatty Acid Market Insights
Propylene glycol is shifting from petrochemical-derived routes toward bio-based glycerol pathways in emulsifier production, altering cost structures for downstream ester manufacturers. BASF SE leverages integrated propylene oxide capabilities to sustain feedstock cost advantages across European supply chains. Croda International anchors its position through backward integration into vegetable oil refining, while Palsgaard competes via specialized emulsifier blends for industrial bakery applications.
Propane-1,2-diol esters of fatty acid comprise monoesters, diesters, and mixed esters formed through esterification of propylene glycol with C12-C22 fatty acids, typically exhibiting HLB values between 3 and 8 for lipophilic emulsification in food and industrial systems. These compounds function primarily as emulsifiers, stabilizers, and plasticizers in polymer processing and personal care formulations. Monoesters command the dominant volume share in food-grade applications due to established GRAS status, while diesters capture higher margin pools in pharmaceutical and cosmetic segments where purity specifications exceed standard industrial grades. Mixed esters are gaining traction in agrochemical formulations where multifunctional surfactant properties reduce blend complexity.
FDA food additive regulations under CFR 172.854 govern propylene glycol ester usage in US food applications, while REACH registration requirements in Europe mandate comprehensive toxicological dossiers for import authorization. China's SAMR enforces GB 1886.236 standards for food-grade propylene glycol fatty acid esters, creating compliance barriers for non-domestic producers. Stakeholders must monitor evolving bio-based content thresholds in EU Green Deal implementation and corresponding carbon border adjustment mechanisms that could restructure cost competitiveness between petrochemical and renewable feedstock routes.
Market Dynamics
Feedstock route bifurcation between petrochemical propylene oxide and bio-based glycerol pathways is restructuring cost competitiveness and supplier positioning across emulsifier supply chains.
Growth Catalysts
- GB 1886.236 compliance mandates:China's SAMR enforcement of purity specifications for food-grade propylene glycol fatty acid esters is consolidating domestic production capacity toward certified manufacturers.
- Bakery processing automation:Industrial-scale bread and confectionery manufacturers in Asia-Pacific processing hubs are standardizing on monoester-stabilized dough systems for extended shelf-life formulations.
- REACH registration completion:Comprehensive toxicological dossier requirements for European import authorization have created competitive moats for established registrants against new market entrants.
Market Restraints
- Vegetable oil feedstock volatility:Palm and rapeseed oil price swings directly compress esterification margins, particularly for non-integrated producers lacking captive crushing capacity.
- Shandong-Jiangsu supply concentration:Over 60 percent of China's esterification capacity clusters in two coastal provinces, creating geographic risk exposure to regional environmental enforcement actions.
- Glycerol purity limitations:Technical-grade bio-based glycerol contains methanol and salt contaminants that degrade ester color and odor specifications for pharmaceutical-grade applications.
Strategic Opportunities
- EU Green Deal bio-content thresholds:Carbon border adjustment mechanisms and renewable content mandates are creating first-mover advantages for producers with verified bio-based propylene glycol supply chains.
- Agrochemical multifunctional blends:Mixed ester formulations are displacing separate surfactant packages in pesticide emulsifiable concentrates, reducing formulation complexity for crop protection manufacturers.
- Pharmaceutical-grade diester expansion:Purity specifications exceeding standard industrial grades command premium positioning in topical drug delivery systems and parenteral emulsion applications.
Industry Challenges
- Esterification process control expertise:Narrow HLB value targeting between 3 and 8 requires specialized chemical engineering talent scarce in emerging production regions.
- Dual certification timelines:Simultaneous FDA GRAS self-affirmation and EFSA novel food approval processes extend market entry cycles by 18 to 24 months for new molecular variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Propane-1,2-Diol Esters Of Fatty Acid Market |
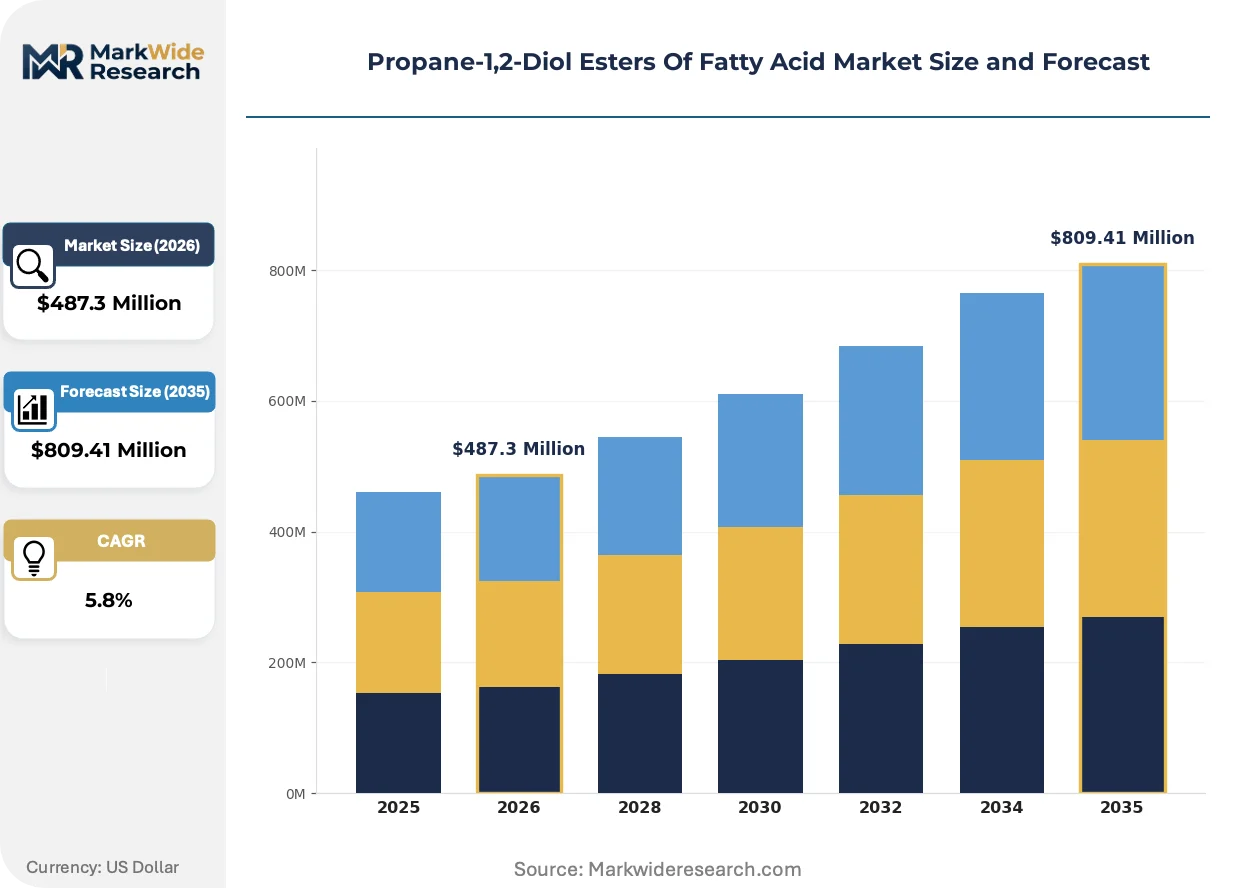
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoesters, Diesters, Triesters, Mixed Esters Application: Plasticizers, Lubricants, Cosmetics, Pharmaceuticals, Agrochemicals End Use Industry: Polymer Manufacturing, Personal Care Products, Crop Protection, Animal Nutrition Packaging Type: Drums, Totes, Bulk Containers, Bottles |
| Companies Covered | BASF SE, Croda International, Kerry Group, Palsgaard, Fine Organics, Henan Honest Chemical, Estelle Chemicals, Ervesa, Mohini Organics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Propane-1,2-Diol Esters Of Fatty Acid Market Trends and Innovations
Bio-based feedstock verification and enzymatic catalysis are converging to redefine production economics and sustainability credentials across emulsifier manufacturing.
Enzymatic esterification using immobilized lipase biocatalysts is absorbing capital allocation from traditional chemical catalysis routes. Specialty chemical producers in Northern Europe are scaling pilot facilities to 1,000-tonne annual capacity. The technology is absorbing margin pressure from energy-intensive high-temperature processing while enabling cold-press esterification of heat-sensitive polyunsaturated fatty acids.
REACH authorization list expansion under ECHA's SVHC candidate identification process is tightening substitution obligations for residual propylene oxide contaminants. Downstream formulators in cosmetics and infant nutrition segments are demanding sub-10 ppm epoxide specifications. German and Dutch compounders are responding by qualifying suppliers with dedicated molecular distillation finishing capabilities.
Direct procurement relationships between multinational food manufacturers and ester producers are compressing traditional distribution layers. Large bakery and confectionery groups in Germany, Japan, and the United States are establishing approved supplier lists with audit rights over fatty acid provenance. This disintermediation is most visible in clean-label product lines where supply chain transparency supports marketing claims.
Propane-1,2-Diol Esters Of Fatty Acid Market Segmentation
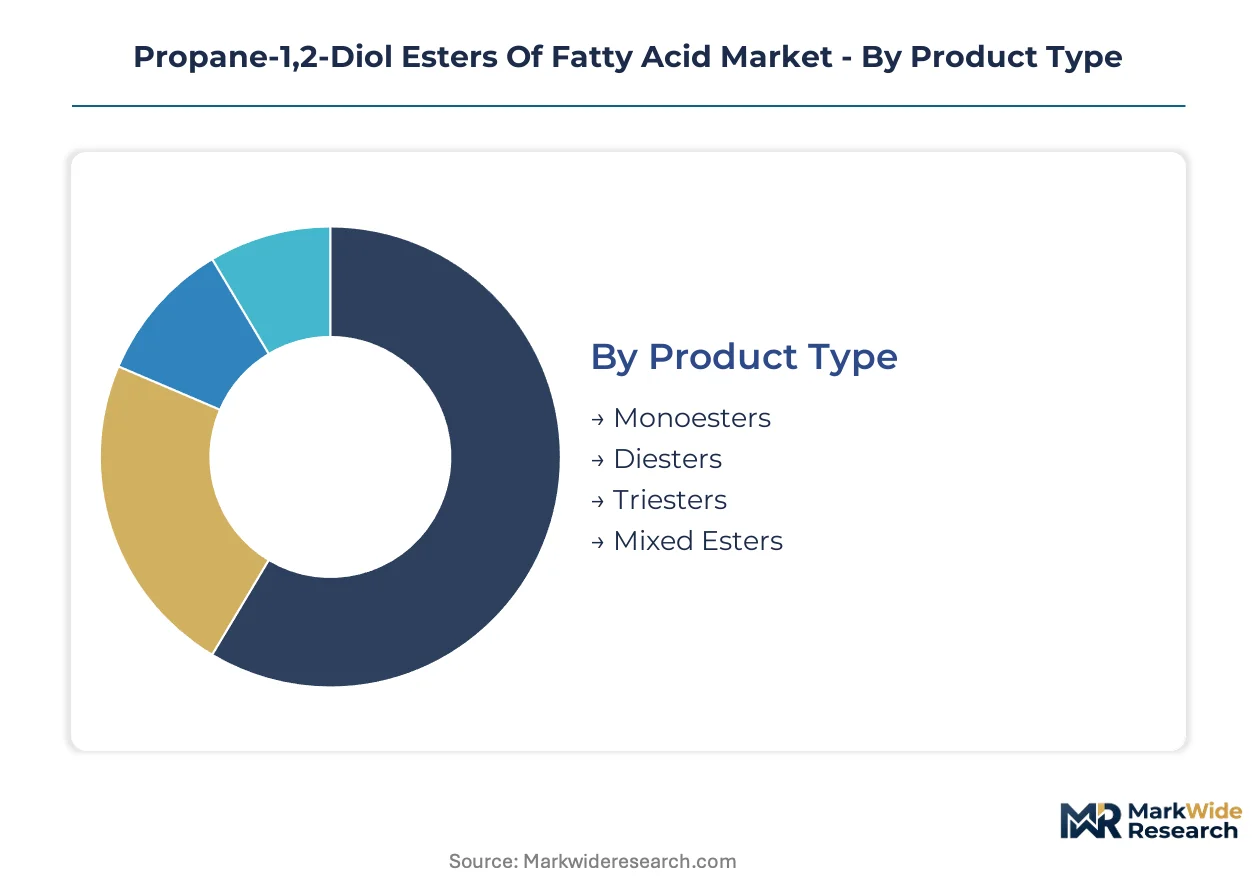
Propane-1,2-diol esters of fatty acid exhibit distinct performance profiles across molecular configurations and end-use requirements. Product substitution patterns between monoesters and diesters are reshaping procurement strategies for industrial formulators seeking HLB precision.
Product Type:
Upgrade cycles from standard-grade diesters to high-purity monoesters are accelerating as food manufacturers reformulate for extended shelf-life claims.
- Monoesters:Single fatty acid chains esterified to one hydroxyl group of propylene glycol deliver HLB values between 3 and 5 for water-in-oil emulsification. Bakery manufacturers in Germany and Japan are standardizing on monoester-stabilized dough systems to replace synthetic alternatives facing clean-label scrutiny.
- Diesters:Both hydroxyl groups esterified with identical or different fatty acids yield more lipophilic characteristics suited to polymer plasticization. Personal care formulators in France are qualifying diester grades for color cosmetic applications where oxidative stability requirements exceed monoester performance limits.
- Triesters:Specialized configurations incorporating additional ester linkages for high-temperature lubricant applications.
- Mixed Esters:Hybrid molecular structures combining mono- and diester fractions for multifunctional agrochemical surfactant properties.
Monoesters sit at the top of the volume ranking, with mixed esters climbing the fastest.
Application:
Cost tier differentiation separates commodity plasticizer grades from pharmaceutical-certified diesters commanding formulation premiums.
- Plasticizers:Diester and mixed ester fractions plasticize PVC and biopolymer films for flexible packaging. Polymer compounders in China's Shandong province are absorbing regional esterification capacity for captive film manufacturing.
- Lubricants:Technical-grade esters function as biodegradable base stocks for metalworking fluids. German automotive suppliers are qualifying bio-based propylene glycol esters for EU Green Deal compliance in fleet maintenance contracts.
- Cosmetics:Low-odor monoesters emulsify skincare and color cosmetic formulations.
- Pharmaceuticals:Parenteral-grade diesters exceed USP monograph purity thresholds for injectable emulsion systems.
- Agrochemicals:Mixed ester surfactants displace separate emulsifier packages in pesticide concentrates.
Plasticizers command the dominant volume position, with pharmaceuticals expanding most quickly.
End Use Industry:
Customer procurement patterns bifurcate between integrated polymer producers and specialty formulators requiring certified supply chain documentation.
- Polymer Manufacturing:PVC and PLA film producers specify diester plasticizers for flexible packaging applications. Italian and Spanish compounders are consolidating supplier lists to three approved ester producers with REACH registration completion.
- Personal Care Products:Cosmetic formulators demand sub-10 ppm propylene oxide residuals for facial skincare. Dutch and German brands are conducting fatty acid provenance audits to support clean-label marketing claims.
- Crop Protection:Pesticide manufacturers specify mixed ester emulsifiers for concentrate stability.
- Animal Nutrition:Feed-grade monoesters function as nutrient absorption enhancers for livestock applications.
Polymer manufacturing anchors volume demand, with personal care products gaining share fastest.
Packaging Type:
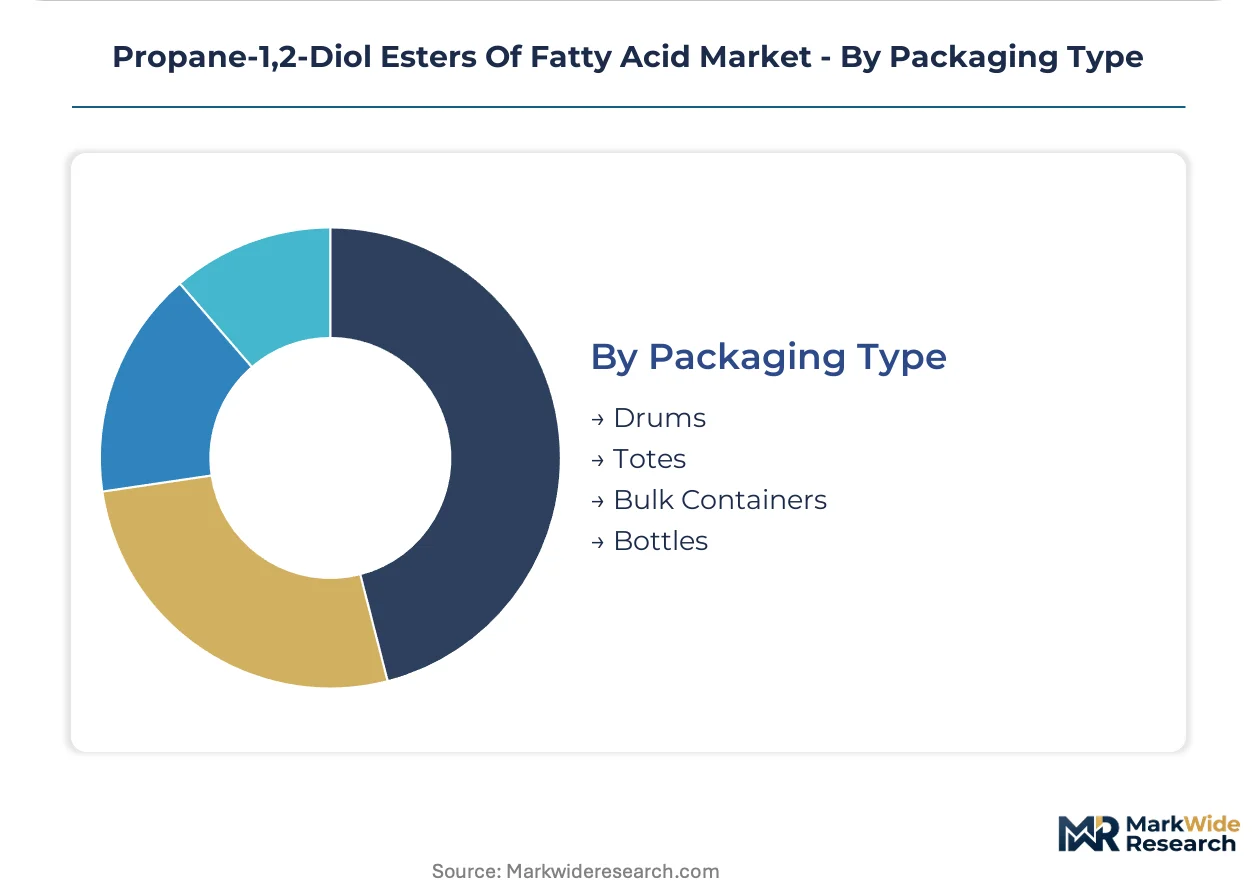
Supply concentration in bulk formats reflects downstream manufacturing scale and just-in-time delivery requirements.
- Drums:Standard 200-liter steel drums serve mid-volume personal care compounders and regional distributors. Japanese cosmetic manufacturers are specifying drum formats with nitrogen blanketing for oxidation-sensitive polyunsaturated ester grades.
- Totes:Intermediate bulk containers reduce handling costs for polymer compounders with weekly consumption above five tonnes. German automotive lubricant blenders are transitioning from drums to totes for metalworking fluid production.
- Bulk Containers:Tank truck and railcar deliveries serve integrated polymer manufacturers with captive esterification or direct procurement relationships.
- Bottles:Laboratory and pilot-scale packaging for pharmaceutical and cosmetic R&D sampling.
Bulk containers dominate volume throughput, with totes expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong-Jiangsu corridor anchors global esterification capacity, concentrating over sixty percent of China's output near fatty acid feedstock sources and coastal export infrastructure. Regulatory divergence across major consuming regions is fragmenting compliance requirements and reshaping supplier qualification protocols.
China
Industrial bakery automation in Shanghai and Guangzhou processing hubs is standardizing monoester-stabilized dough formulations for extended shelf-life claims. SAMR enforcement of GB 1886.236 purity specifications is consolidating domestic production toward certified manufacturers. Shandong and Jiangsu province clusters near Qingdao and Nantong ports are absorbing capacity expansion from environmental compliance upgrades.
Germany
REACH registration completion for propylene glycol esters has created competitive moats favoring established dossier holders against new import authorization seekers. ECHA's SVHC candidate list expansion is tightening substitution obligations for residual epoxide contaminants below ten parts per million. BASF SE leverages integrated Ludwigshafen propylene oxide capabilities to sustain feedstock cost advantages across European supply chains.
United States
FDA CFR 172.854 food additive regulations govern GRAS self-affirmation pathways for bakery and confectionery applications. Clean-label procurement patterns among multinational food manufacturers are compressing traditional distribution layers through direct supplier relationships. Midwest polymer compounders specify diester plasticizers for flexible packaging films serving retail bakery segments.
Japan
METI industrial standards for food-grade emulsifiers are accelerating qualification timelines for imported ester grades. Cosmetic formulators in Osaka and Tokyo metro areas demand sub-ten ppm propylene oxide residuals for facial skincare applications. Nitrogen-blanketed drum specifications from regional distributors are preserving oxidation-sensitive polyunsaturated ester grades.
India
FSSAI food additive safety standards are tightening import documentation requirements for propylene glycol fatty acid esters. Domestic bakery chains in Maharashtra and Karnataka are transitioning from synthetic emulsifiers to monoester-based clean-label alternatives. Gujarat-based oleochemical feedstock suppliers are backward integrating into esterification to capture margin from pharmaceutical-grade diester demand.
Propane-1,2-Diol Esters Of Fatty Acid Market Competitive Landscape
Capacity expansion dominates the current landscape as producers scale enzymatic esterification pilot facilities toward commercial throughput. The vendor base separates into three tiers: integrated petrochemical majors with captive propylene oxide supply, vegetable oil refiners with backward integration into fatty acid production, and specialized emulsifier blenders serving formulation-intensive end uses. Strategic archetypes include feedstock-integrated cost leaders, purity-focused pharmaceutical-grade specialists, and application-technical service providers. Competitive intensity concentrates on M&A activity targeting regional distribution networks and technology licensing agreements for enzymatic catalysis routes.
Among European-registered chemical majors, BASF SE and Croda International exemplify divergent archetype positioning. BASF SE represents the integrated petrochemical model with upstream control over propylene oxide feedstocks. Croda International anchors the vegetable oil refiner archetype through in-house production of fatty acid precursors. Palsgaard occupies a position within the specialized emulsifier blender tier, competing via formulation expertise for industrial bakery applications rather than commodity scale.
| Leading Market Players |
|---|
| BASF SE |
| Croda International |
| Kerry Group |
| Palsgaard |
| Fine Organics |
| Henan Honest Chemical |
| Estelle Chemicals |
| Ervesa |
| Mohini Organics |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal bio-content thresholds are gating both qualified supply and premium-tier pricing access for propane-1,2-diol ester manufacturers, as carbon border adjustment mechanisms favor producers with verified renewable propylene glycol pathways while petrochemical-derived grades face margin compression in European procurement.
Pricing Analysis
Input-cost pass-through from vegetable oil feedstock volatility structures pricing across three tiers: pharmaceutical-grade monoesters command formulation premiums, food-grade diesters track palm and rapeseed oil indices with quarterly adjustments, and technical-grade mixed esters compete on spot-market responsiveness. Price differentiation hinges on REACH registration completion and FDA GRAS certification status, with certified producers capturing margin from downstream formulators facing clean-label audit requirements. Cost compression in standard industrial grades is intensifying because Shandong-based capacity expansions are absorbing regional fatty acid supply. Polymer compounders with captive esterification capabilities exhibit lowest price sensitivity; mid-volume personal care formulators dependent on drum-format procurement face highest exposure to freight and handling surcharges.
Supply Chain Analysis
Specialized chemical engineering talent scarcity in Shandong and Jiangsu provinces is constraining esterification process control expertise expansion, even as capacity clusters near Qingdao and Nantong port infrastructure. Raw material dependencies rest on palm oil shipments from Southeast Asia, rapeseed oil from European crushing facilities, and propylene oxide from integrated petrochemical complexes or bio-based glycerol refiners. Single-source vulnerability concentrates in fatty acid feedstock supply, where environmental enforcement actions in China's coastal provinces can disrupt esterification output without warning. Distribution runs through direct procurement relationships between multinational food manufacturers and certified ester producers, compressing traditional distributor layers for clean-label product lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between China's GB 1886.236 compliance consolidation and Europe's REACH authorization requirements, where regulatory cost differentials create positioning windows for producers with dual-certification capabilities.
For Market Incumbents: Deploy enzymatic catalysis scale-up to defend margin position against high-temperature processing cost disadvantages. BASF SE and Croda International should deepen backward integration into vegetable oil refining to offset feedstock volatility exposure. Capacity additions in Northern European pilot facilities will absorb capital allocation pressure from sustainability-minded formulators demanding bio-based verification.
For New Entrants and Emerging Players: Launch via specialized emulsifier blending for agrochemical multifunctional formulations, where mixed ester demand is displacing separate surfactant packages. White-space targets include parenteral-grade diester production for pharmaceutical applications with purity specifications exceeding standard industrial grades. Go-to-market positioning should emphasize enzymatic esterification capabilities for cold-press processing of heat-sensitive polyunsaturated fatty acids.
For Investors and Strategic Acquirers: Roll-up economics work for regional distribution networks because direct procurement relationships are compressing traditional channel layers and fragmenting supplier access for mid-volume compounders. Acquisition targets should exhibit REACH registration completion and established fatty acid provenance audit protocols. The signal to watch is ECHA SVHC candidate list expansion for residual propylene oxide contaminants, which would accelerate substitution demand toward sub-10 ppm specification suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vegetable Oil Refining | Croda International's captive fatty acid production insulates margin from palm oil price swings. |
| Enzymatic Esterification Scale-Up | Specialty chemical producers in Northern Europe are absorbing capital toward 1,000-tonne pilot capacity. |
| Dual Certification Investment | Simultaneous FDA GRAS and EFSA novel food approvals extend competitive moats against import authorization seekers. |
| Direct Procurement Relationship Development | German and Japanese bakery manufacturers are consolidating approved supplier lists with audit rights over feedstock provenance. |
| Pharmaceutical-Grade Diester Capacity Expansion | Purity specifications exceeding USP monograph thresholds command premium positioning in parenteral emulsion systems. |
Research Methodology
Multiple input streams — technical discussions with esterification plant managers and procurement leads at polymer compounders, regulatory filings with ECHA and SAMR, and trade data from Shandong and Jiangsu export corridors — were reconciled through bottom-up capacity modeling and top-down demand validation across bakery, pharmaceutical, and agrochemical end uses. Secondary sources included customs records tracking fatty acid ester shipments, SEC filings from integrated petrochemical majors, and GB standards documentation from China's national food safety regulator.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with segmentation modeling across product type (monoester, diester, mixed ester), application tier (food-grade, pharmaceutical-grade, technical-grade), packaging format (bulk, tote, drum), and regional production hub. CAGRs were derived from elasticity-adjusted demand curves incorporating HLB value targeting precision and enzymatic catalysis adoption curves. Forecast inputs included bakery automation penetration rates in Asia-Pacific processing hubs and REACH authorization list expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt environmental enforcement actions in China's coastal provinces or sudden bio-based content threshold adjustments in EU Green Deal implementation. Material deviation in vegetable oil feedstock price volatility or glycerol purity contamination rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Glycerol Esters Market
Oleochemicals
Alpha Olefin Sulfonates Market
Oleochemicals
Global Wax Market
Oleochemicals
Stearyl Tartrate Market
Oleochemicals
Glycerol Monostearate Market
Oleochemicals
Paraffin Market
Oleochemicals
Pentalide (Cyclopentadecanolide) Market
Oleochemicals
Triisostearyl Citrate Market
Oleochemicals
Isooctyl Chloride Market
Oleochemicals
Isodecyl Pelargonate Market
Oleochemicals
Global Methyl Ester Ethoxylate Market
Oleochemicals
Global Decant Oil Market
Oleochemicals
Camphor Oil Market
Oleochemicals
Ethyl Linalool Market
Oleochemicals
Ethoxylated Castor Oil Market
Oleochemicals
Partially Hydrogenated Oil Market