
 Global Oxidized Polyethylene Wax Market | 2026-2036
Global Oxidized Polyethylene Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oxidized Polyethylene Wax Market Foresight
Distributor networks across Asia are rewriting procurement patterns for oxidized polyethylene wax as regional formulators seek localized supply security. BASF SE leverages its integrated European production complex to sustain premium-grade availability. Honeywell International Inc. anchors North American supply through specialized high-density product lines. Mitsui Chemicals Inc. competes on molecular weight precision for Japanese automotive coatings.
Oxidized polyethylene wax comprises polyethylene that has undergone controlled oxidation to introduce polar carboxyl and hydroxyl functional groups, yielding products with acid values typically ranging from 15 to 30 mg KOH/g and melt points between 100°C and 140°C; this modification imparts emulsifiability, hardness, and compatibility with polar systems for use as process aids, slip agents, and surface modifiers. Low molecular weight grades dominate volume flows into water-based coatings where emulsion stability commands priority, while high molecular weight variants capture margin concentration in engineered plastics requiring elevated thermal durability. The degraded segment occupies a narrowing but defended niche in cost-sensitive ink formulations where performance thresholds remain modest.
REACH in Europe, EPA TSCA in the United States, and China's GB standards under SAMR collectively tighten chemical registration burdens and VOC emission ceilings, forcing reformulation toward compliant wax additives. ECHA's evolving restrictions on persistent substances are redirecting R&D investment into biodegradable wax alternatives. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned product registrations.
Market Dynamics
REACH-mandated VOC ceilings in Europe are forcing coatings formulators to abandon solvent-borne systems, redirecting procurement toward emulsifiable oxidized PE wax grades that enable water-based performance parity. This regulatory compression is reshaping supplier qualification criteria and technical service requirements across the value chain.
Growth Catalysts
- Water-based coatings transition:Formulators in Germany are accelerating adoption of oxidized PE wax emulsions to meet ECHA emission thresholds without sacrificing surface hardness.
- Automotive lightweighting:Japanese OEMs are specifying high-density oxidized PE wax grades for engineering plastics to maintain thermal stability in thinner-wall components.
- Backward integration in China:Domestic producers are capturing ethylene feedstock supply through captive cracker investments, displacing import dependency for acid-functional waxes.
Market Restraints
- Ethylene feedstock volatility:Naphtha-cracker margins in Northeast Asia swing with crude differentials, compressing oxidized PE wax producer margins unpredictably.
- High-purity grade concentration:Premium molecular weight precision remains concentrated among integrated European complexes, creating supply security risks for Asian formulators.
- Biodegradable wax substitution:ECHA's evolving restrictions on persistent substances are redirecting R&D budgets toward plant-derived alternatives in cosmetic and food-contact applications.
Strategic Opportunities
- Indian coatings expansion:BIS standards alignment with REACH principles is opening procurement windows for compliant oxidized PE wax suppliers as domestic production scales.
- Digital inkjet penetration:High-speed inkjet presses require low-melt-point oxidized PE wax dispersions for rub resistance, creating specification opportunities outside traditional offset markets.
- South Korean battery materials:MFDS registration pathways for process aids in electrode coatings offer a regulatory-tailwind entry point for acid-functional wax grades.
Industry Challenges
- Emulsion stability expertise gap:Formulation chemists with deep knowledge of oxidized PE wax particle size distribution control remain scarce in emerging manufacturing clusters.
- Multi-jurisdiction registration timelines:SAMR's GB standard harmonization with REACH data requirements is extending product approval cycles for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oxidized Polyethylene Wax Market |
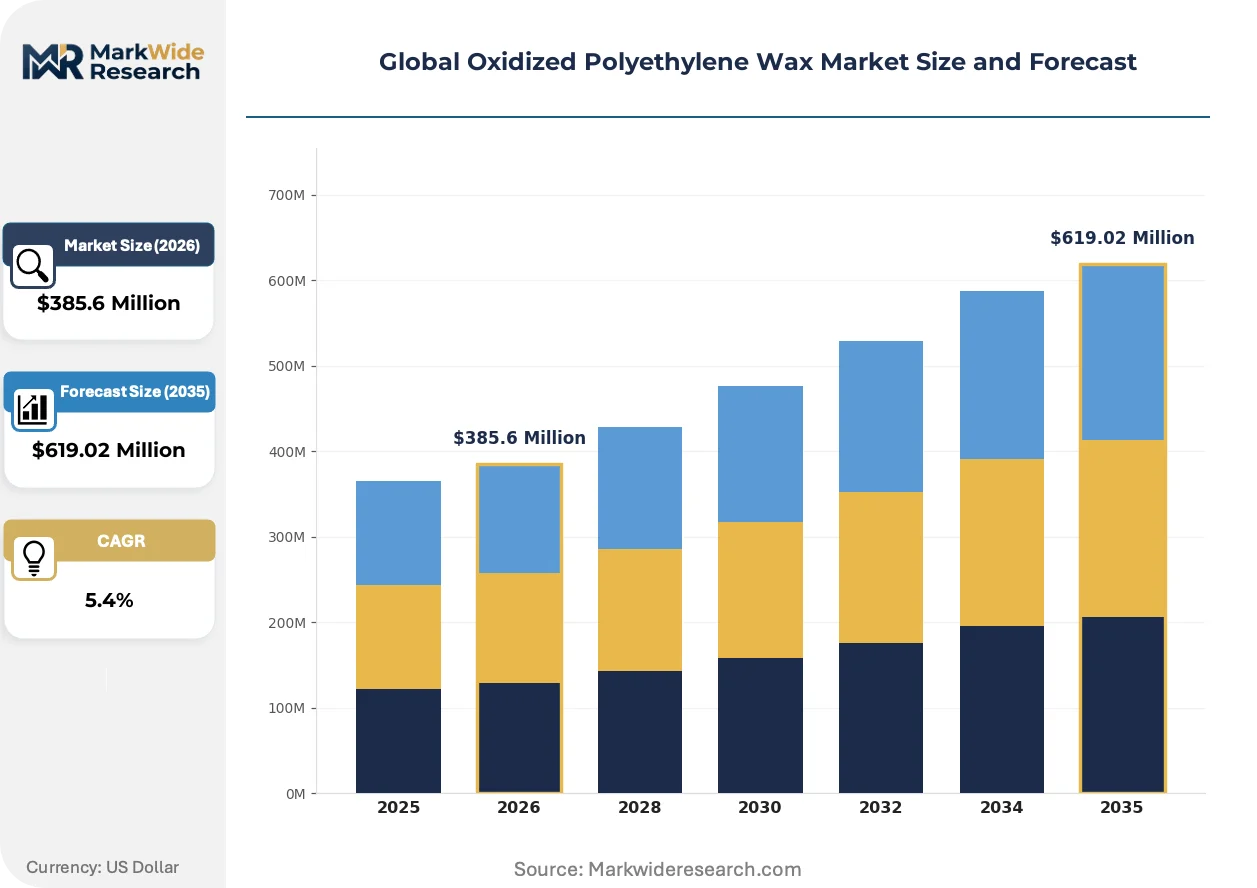
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $619.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Molecular Weight, High Molecular Weight, Ultra-High Molecular Weight, Degraded Application: Coatings, Adhesives, Plastics, Inks End User: Construction, Automotive, Packaging, Consumer Goods Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Mitsui Chemicals Inc., DEUREX AG, BASF SE, Micro Powders Inc., Shamrock Technologies, Clariant AG, The Lubrizol Corporation, Westlake Chemical Corporation, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oxidized Polyethylene Wax Market Shifts & Advancements
Controlled oxidation protocols are advancing precision over acid value distribution, enabling wax producers to target narrow performance windows previously requiring synthetic alternatives. This technical refinement is compressing the traditional trade-off between emulsifiability and thermal durability.
Precision oxidation technology is migrating from batch kettle systems to continuous reactor designs with inline FTIR monitoring. European coatings specialists are adopting these grades for automotive clearcoats where acid value consistency below 22 mg KOH/g eliminates haze defects. The shift is compressing tolerance for batch-to-batch variation and rewarding suppliers with statistical process control infrastructure.
EPA TSCA Section 5 notification burdens for new chemical substances are lengthening pre-market approval timelines for modified polyethylene waxes with novel functionalization. American formulators are responding by qualifying existing oxidized grades for expanded use categories rather than sponsoring new substance registrations. This regulatory friction is cementing incumbent product positions and raising barriers for molecular architecture innovation.
Formulator procurement is consolidating around technical service partnerships rather than transactional spot purchasing. Water-based ink producers in China are signing annual offtake agreements with oxidized PE wax suppliers embedding application laboratories at customer sites. This service bundling is displacing distributor intermediaries in technical-grade segments where formulation support determines specification lock-in.
Global Oxidized Polyethylene Wax Market Segmentation
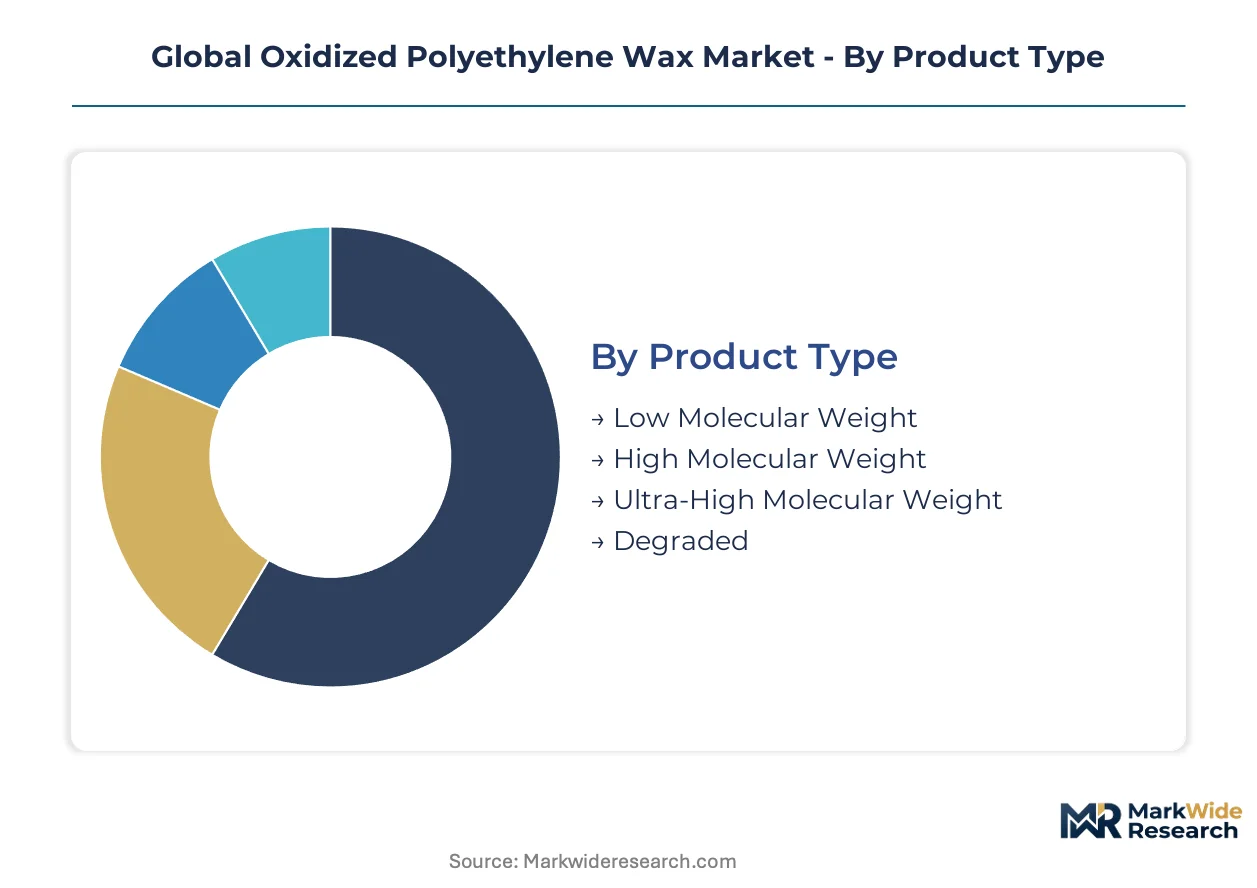
Segmentation in oxidized polyethylene wax markets tracks how molecular architecture, application chemistry, and procurement channels create divergent margin profiles. Formulators select grades based on emulsion stability requirements, thermal durability thresholds, and regulatory compliance burdens rather than commodity pricing alone.
Product Type:
Cycle times vary sharply across molecular weight tiers, with low molecular weight grades turning inventory fastest in coatings emulsion plants while ultra-high variants sit in engineered plastics pipelines for quarters.
- Low Molecular Weight:Acid values between 15-22 mg KOH/g enable rapid water-based emulsification without surfactant overload. German coatings manufacturers are standardizing these grades for REACH-compliant automotive clearcoats where haze elimination commands premium qualification. The segment rotates inventory fastest due to just-in-time emulsion plant procurement.
- High Molecular Weight:Melt points extending to 140°C deliver thermal durability for engineering plastics in thinner-wall automotive components. Japanese OEMs specify these grades for lightweighting applications where heat distortion resistance cannot degrade. Demand concentrates in injection molding compounds with extended qualification cycles.
- Ultra-High Molecular Weight:Specialized rheology control for high-temperature polymer processing.
- Degraded:Cost-sensitive ink formulations with modest performance thresholds.
Low molecular weight grades anchor the volume base while high molecular weight variants gain share at the steepest rate through automotive specification creep.
Application:
Cost tier stratification separates coatings and adhesives command from plastics and inks procurement, with formulators paying premiums for technical service integration in water-based systems.
- Coatings:Water-based architectural and industrial finishes dominate procurement volume, with ECHA-mandated VOC ceilings forcing solvent-borne abandonment. German formulators are locking in annual offtake agreements embedding supplier laboratories at customer sites for emulsion stability troubleshooting.
- Adhesives:Hot-melt and pressure-sensitive formulations require precise acid value distribution for polar substrate bonding. Construction sector demand in China is scaling through domestic backward integration into ethylene feedstocks, displacing import dependency for acid-functional waxes.
- Plastics:Process aids and surface modifiers for extrusion and molding operations.
- Inks:Rub resistance and gloss control for offset, gravure, and digital printing.
Coatings commands the revenue concentration while adhesives applications expand most quickly through construction sector procurement localization.
End User:
Customer type segmentation reveals divergent technical service appetites, with automotive and packaging buyers demanding molecular weight certificates while construction and consumer goods prioritize unit economics.
- Construction:Sealants, caulks, and waterproofing membranes drive volume procurement with price-sensitive specifications. Indian BIS standards alignment with REACH principles is opening compliant supplier windows as domestic coatings production scales.
- Automotive:Lightweighting mandates and interior air quality regulations specify high-purity grades with batch-to-batch consistency below 2% acid value variation. European integrated complexes dominate qualification lists due to statistical process control infrastructure.
- Packaging:Food-contact and cosmetic applications facing biodegradable substitution pressure from ECHA persistent substance restrictions.
- Consumer Goods:Personal care and household product formulations with modest performance thresholds.
Construction anchors absolute volume throughput while automotive specifications capture the steepest margin expansion trajectory.
Distribution Channel:
Supply concentration patterns favor direct relationships in technical grades while commodity flows fragment across distributor networks with inventory risk transfer.
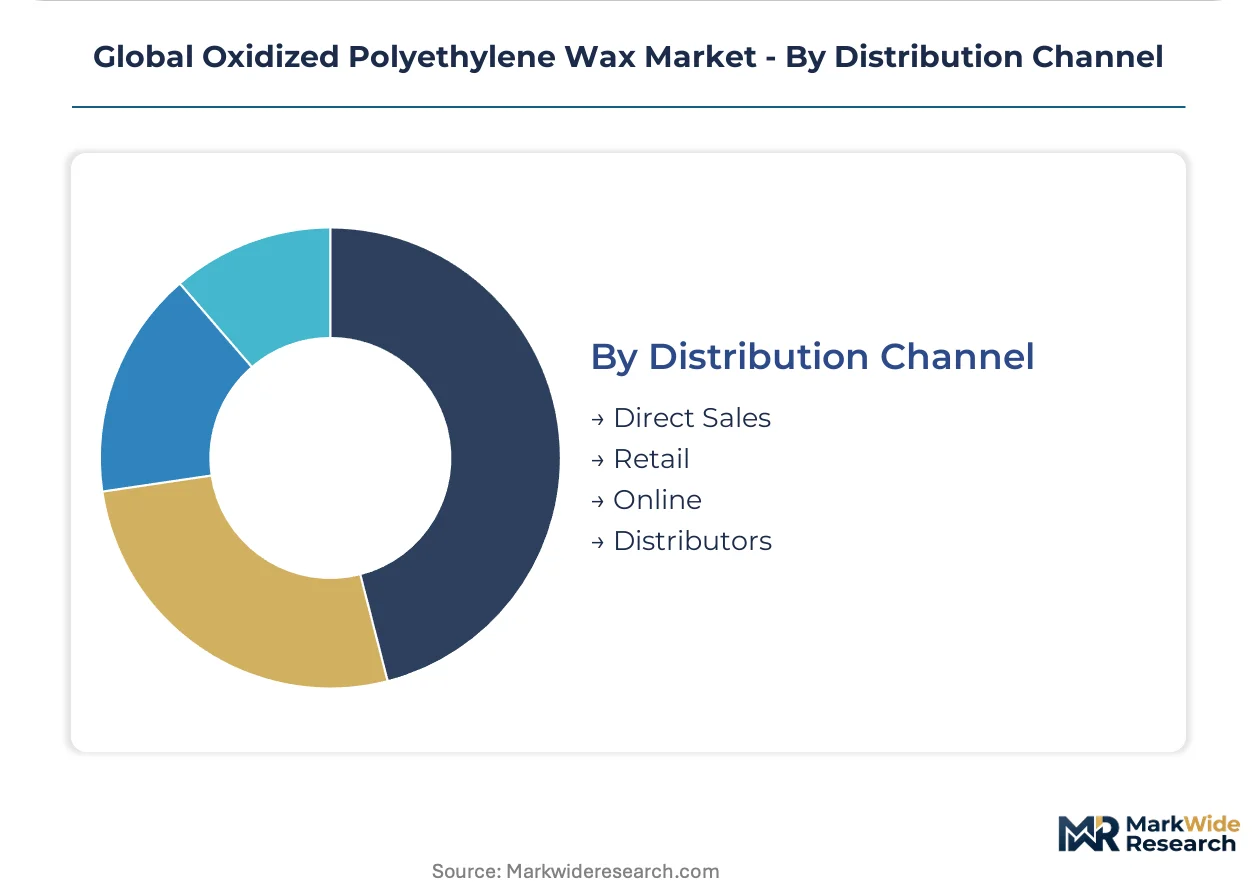
- Direct Sales:Annual offtake agreements with embedded technical service dominate premium grade procurement. Chinese water-based ink producers are displacing distributor intermediaries through on-site application laboratory partnerships that lock in specification control.
- Distributors:Inventory buffering and credit extension for mid-tier formulators without qualification resources. Asian regional distributors are rewriting procurement patterns as localized supply security concerns mount.
- Retail:Small-volume procurement for specialty formulators and research laboratories.
- Online:Emerging channel for standard-grade spot purchasing with limited technical support.
Direct sales channels anchor the value concentration while distributor relationships retain volume dominance in emerging manufacturing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH framework anchors European demand dynamics, yet oxidized polyethylene wax procurement patterns diverge sharply across manufacturing clusters in Germany, China, the United States, Japan, and India.
Germany
Automotive clearcoat formulators in Stuttgart and Munich are locking in annual offtake agreements for low acid value grades. ECHA's tightening VOC ceilings under REACH Annex XVII are forcing solvent-borne system abandonment. BASF SE's integrated Ludwigshafen complex supplies statistical process control infrastructure that premium specifications demand.
China
Domestic producers in the Yangtze River Delta are capturing ethylene feedstock through captive cracker investments. SAMR's GB standards alignment with REACH data requirements is extending product approval cycles for cross-border suppliers. Shanghai-based water-based ink manufacturers are displacing distributor intermediaries through embedded application laboratory partnerships.
United States
EPA TSCA Section 5 notification burdens are lengthening pre-market approval timelines for modified polyethylene waxes. American formulators are qualifying existing oxidized grades for expanded use categories rather than sponsoring new substance registrations. Houston and Gulf Coast chemical corridors concentrate high-density product line availability for engineering plastics compounders.
Japan
METI's chemical management frameworks are redirecting procurement toward molecular weight precision grades for automotive lightweighting applications. Osaka and Nagoya industrial clusters specify high-density variants for thinner-wall interior components. Japanese OEMs maintain extended qualification cycles that favor established supplier relationships with batch-to-batch consistency below 2% acid value variation.
India
BIS standards alignment with REACH principles is opening procurement windows for compliant oxidized PE wax suppliers. Domestic coatings production scaling in Gujarat and Maharashtra is driving construction sector volume procurement. Mumbai and Ahmedabad formulators prioritize unit economics over technical service integration in sealant and waterproofing membrane applications.
Global Oxidized Polyethylene Wax Market Competitive Landscape
Integrated petrochemical conglomerates and specialized wax refiners split the market into distinct capability tiers. European complexes leverage backward integration into ethylene feedstocks to sustain premium-grade availability. Asian producers compete on localized supply security and emulsion stability expertise. Competitive moves concentrate on capacity expansion in high-growth manufacturing clusters and strategic partnerships embedding technical service at customer sites.
Within the integrated petrochemical tier, BASF SE and Honeywell International Inc. exemplify scale-driven positioning anchored by captive feedstock control. Mitsui Chemicals Inc. occupies a specialist position emphasizing molecular weight precision for specification-critical applications. These three entities represent divergent geographic anchoring—European, North American, and Japanese respectively—while sharing investment in statistical process control infrastructure that premium formulators require.
| Leading Market Players |
|---|
| Mitsui Chemicals Inc. |
| DEUREX AG |
| BASF SE |
| Micro Powders Inc. |
| Shamrock Technologies |
| Clariant AG |
| The Lubrizol Corporation |
| Westlake Chemical Corporation |
| Honeywell International Inc. |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta's captive cracker investments are compressing import parity pricing for acid-functional wax grades across Asia-Pacific formulator networks. European integrated complexes sustain premium-grade premiums through statistical process control infrastructure that automotive clearcoat specifications demand.
Pricing Analysis
Geographic price spreads between European premium grades and Asian standard variants reflect divergent cost structures rather than quality gaps alone. Three-tier pricing structure across premium, standard, and economy levels segments by acid value precision and batch-to-batch consistency certification. Cost compression in economy grades is intensifying because domestic Chinese producers are achieving backward integration into ethylene feedstocks. Construction sector buyers in India exhibit the highest price sensitivity, while automotive OEMs in Germany accept substantial premiums for sub-2% acid value variation guarantees.
Supply Chain Analysis
Export control regimes on high-purity polyethylene production technologies limit capacity replication outside established manufacturing clusters. Supply concentrates in Germany, China, and Japan, with each hub serving distinct specification tiers. The chain draws from naphtha-cracker ethylene, specialized oxidation catalysts, and precision emulsification equipment. Single-source vulnerability runs through European statistical process control infrastructure for automotive-grade certification. Distribution runs through direct technical service partnerships in premium segments and regional distributor networks for standard grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face mounting substitution pressure from plant-derived biodegradable wax alternatives as ECHA persistent substance restrictions tighten. Defending specification lock-in requires preemptive moves against this threat.
For Market Incumbents: Insulate premium-grade positioning by embedding application laboratories at automotive formulator sites in Stuttgart and Nagoya, converting transactional supply into specification-locked partnerships. Accelerate certification investment for REACH-compliant biodegradable wax hybrids to neutralize substitution threats from renewable alternatives before ECHA restrictions harden.
For New Entrants and Emerging Players: Build out emulsion stability expertise capabilities to serve Chinese water-based ink producers displacing distributor intermediaries, as this segment offers the most penetrable procurement window. Target annual offtake agreements with embedded technical service as the go-to-market angle, replicating the partnership model that incumbent integrated complexes use to lock out spot-market competitors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized wax refiners with molecular weight precision capabilities rather than commodity-scale polymer producers. Long-term viability hinges on regulatory compliance infrastructure that survives tightening VOC ceilings across multiple jurisdictions. Acquisition targets should demonstrate existing SAMR registration progress and REACH data packages. Watch for ECHA's evolving persistent substance restriction timelines as the inflection signal that accelerates biodegradable substitution or extends incumbent runway.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive ethylene supply from Yangtze River Delta crackers shields Chinese producers from naphtha volatility. |
| Capacity Expansion | Specialized high-molecular-weight lines in Osaka industrial clusters serve Japanese automotive lightweighting specifications. |
| Long-term Supply Agreement | Annual offtake contracts with embedded laboratories displace distributor intermediaries in Chinese ink formulation. |
| Joint Venture | European-Asian partnerships bridge REACH data requirements and SAMR GB standard harmonization for cross-border registration. |
| Green Manufacturing Transition | Biodegradable wax R&D investment responds to ECHA persistent substance restrictions in cosmetic and food-contact segments. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with coatings formulators, polymer procurement leads, oxidation plant managers, and technical R&D directors; and secondary validation through customs trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated petrochemical conglomerates, and SAMR registration databases. Bottom-up triangulation across molecular weight grade volumes and top-down reconciliation against ethylene feedstock flow estimates anchored market sizing integrity.
Forecast inputs span acid value tier adoption curves, automotive lightweighting specification creep, and water-based coatings transition velocity across regulatory jurisdictions. Segmentation dimensions modeled include molecular weight architecture, application chemistry, end-use industry procurement behavior, and regional production hub supply security. CAGRs derive from ethylene derivative demand elasticity and coatings formulation substitution rates. Crude-naphtha spread volatility and ECHA restriction timeline uncertainty constitute key industry-specific forecast sensitivities.
Stress conditions across ethylene feedstock price bands, REACH enforcement intensity, and biodegradable wax substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about cracker margin stability and regulatory harmonization progress. Material shifts in ECHA persistent substance restriction scope or SAMR approval timeline acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Petrolatum Market
Oleochemicals
Allyl Caproate Market
Oleochemicals
Rice Bran Wax Market
Oleochemicals
Lauric Aldehyde Market
Oleochemicals
Global Specialty Oleochemicals Market
Oleochemicals
White Mineral Oil Market
Oleochemicals
Ethylhexyl Palmitate Market
Oleochemicals
Diisostearyl Fumarate Market
Oleochemicals
Candelilla Wax Market
Oleochemicals
Esters Market
Oleochemicals
Fatty Acid Ester Market
Oleochemicals
Undecanoyl Chloride Market
Oleochemicals
Ethylhexyl Cocoate Market
Oleochemicals
Alpha Olefin Sulfonates Market
Oleochemicals
2-Hexyldecanol Market
Oleochemicals
Oxo-Octyl Acetate Market