
 Global 1,5-Cyclooctadiene Market | 2026-2036
Global 1,5-Cyclooctadiene Market Size, Share, and Industry Trends Forecast 2026-2036
Global 1,5-Cyclooctadiene Market Analysis
Modular supply arrangements for 1,5-cyclooctadiene is consolidating buyer preference away from spot purchases toward contracted purity-tier bundles. Evonik Industries AG leverages its integrated precursor supply chain to offer captive diene output to captive polymerization units. Sigma Aldrich differentiates through analytical-grade certification protocols that satisfy pharmaceutical audit requirements. Tokyo Chemical Industry Co., Ltd anchors East Asian distribution through regional warehousing in Osaka and Singapore.
1,5-Cyclooctadiene is a cyclic diene hydrocarbon with the formula C8H12, typically produced via butadiene dimerization or extraction from C8 streams, serving primarily as a ligand precursor for transition-metal catalysts and as a monomer in specialty polymer synthesis. Purified grades command margin premiums in pharmaceutical intermediate applications where residual impurity thresholds fall below 0.1 percent. Technical grade volumes dominate tonnage flows into material production for adhesives and elastomer modification. Chemical synthesis applications represent the fastest-growing demand cluster as metal-organic framework researchers adopt COD-ligated palladium precursors.
EPA oversight under the Toxic Substances Control Act shapes import documentation and substance notification requirements for 1,5-cyclooctadiene entering United States manufacturing channels. REACH registration mandates in the European Union enforce full supply-chain transparency on tonnage bands and hazard classifications for cyclodiene derivatives. China's SAMR implements national GB standards for chemical purity that diverge from ISO reference methods, creating dual-certification burdens for multinational suppliers. Stakeholders must monitor regulatory harmonization negotiations between OECD member states and assess whether diverging purity standards will fragment procurement specifications across major demand zones.
Market Dynamics
Modular supply arrangements for 1,5-cyclooctadiene are consolidating buyer preference away from spot purchases toward contracted purity-tier bundles, restructuring how specialty chemical manufacturers secure feedstock for precision polymerization workflows.
Growth Catalysts
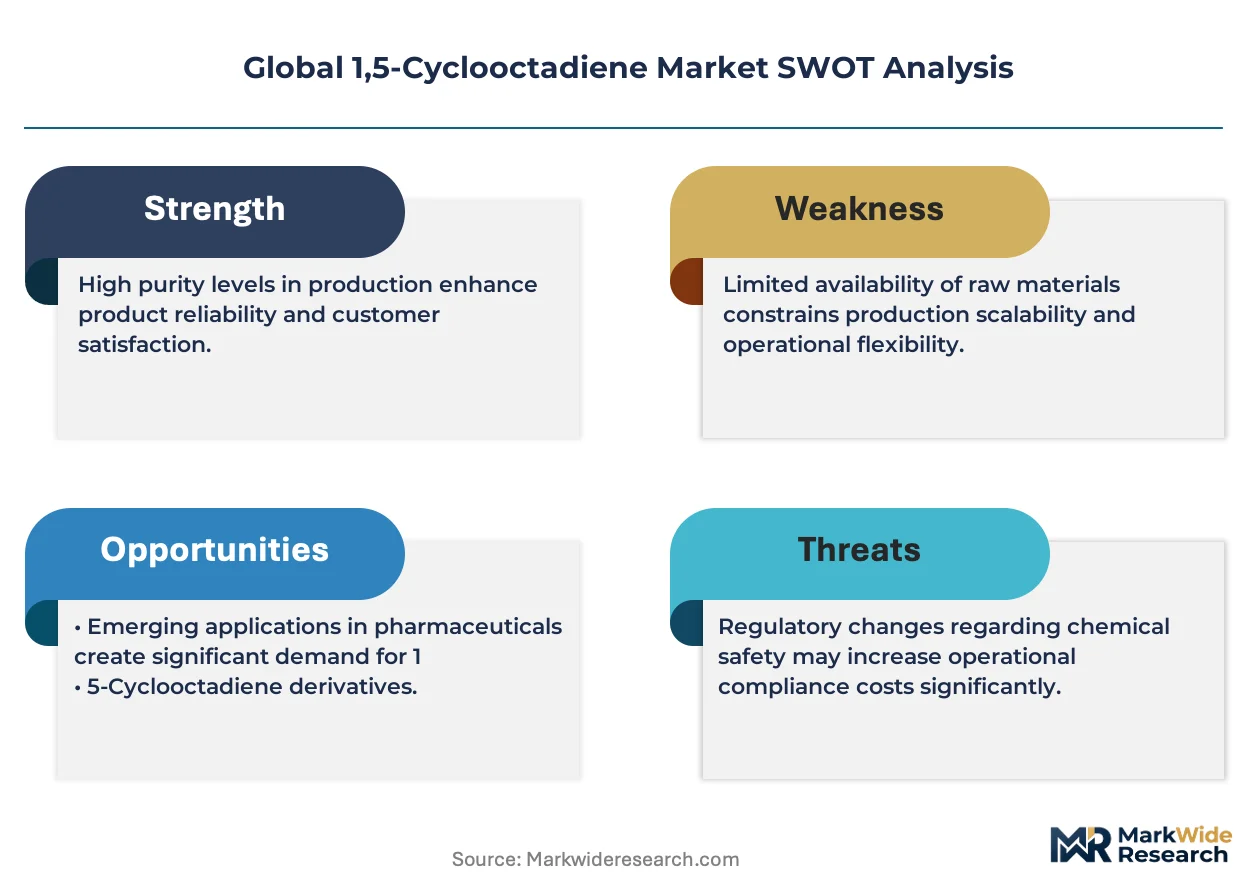
- REACH compliance mandates:Tightening purity thresholds in the European Union are forcing importers to upgrade documentation and certification protocols, creating captive demand for analytical-grade COD suppliers who can demonstrate full supply-chain transparency.
- Metal-organic framework research:Academic and industrial laboratories are expanding adoption of COD-ligated palladium precursors for catalytic applications, pulling volumes into chemical synthesis faster than traditional polymerization demand.
- Germany's industrial chemical corridor:Concentrated specialty polymer production along the Rhine-Ruhr and Ludwigshafen clusters is generating sustained offtake for high-purity grades with residual impurity thresholds below 0.1 percent.
Market Restraints
- Butadiene feedstock volatility:Input costs for dimerization routes fluctuate with C4 stream availability from steam cracker operations, compressing margins for non-integrated producers during ethylene demand cycles.
- Chinese GB standard divergence:SAMR-mandated purity testing protocols diverge from ISO reference methods, forcing multinational suppliers to maintain dual certification laboratories and quality systems.
- Substitute ligand competition:Norbornadiene and cyclooctene derivatives offer comparable coordination chemistry for certain palladium-catalyzed transformations, threatening COD volume in price-sensitive pharmaceutical intermediate applications.
Strategic Opportunities
- India's specialty chemical expansion:PLI scheme incentives for advanced material manufacturing are attracting greenfield polymerization investments that will require certified COD feedstock for catalyst precursor synthesis.
- Biobased butadiene dimerization:Converging fermentation-derived C4 platforms with existing dimerization infrastructure offers pathway to lower-carbon intensity COD for sustainability-mandated European buyers.
- Pharmaceutical audit requirements:Sigma Aldrich-style analytical-grade certification protocols that satisfy FDA and EMA inspection standards command margin premiums in GMP intermediate supply chains.
Industry Challenges
- Organometallic synthesis expertise scarcity:Qualified technicians capable of handling air-sensitive COD-ligated precursor production remain concentrated in legacy German and Japanese chemical clusters, constraining capacity expansion.
- Dual-certification timeline compression:Simultaneous validation against REACH dossier requirements and China's GB standards extends new supplier qualification periods to 18-24 months, freezing out smaller entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 1,5-Cyclooctadiene Market |
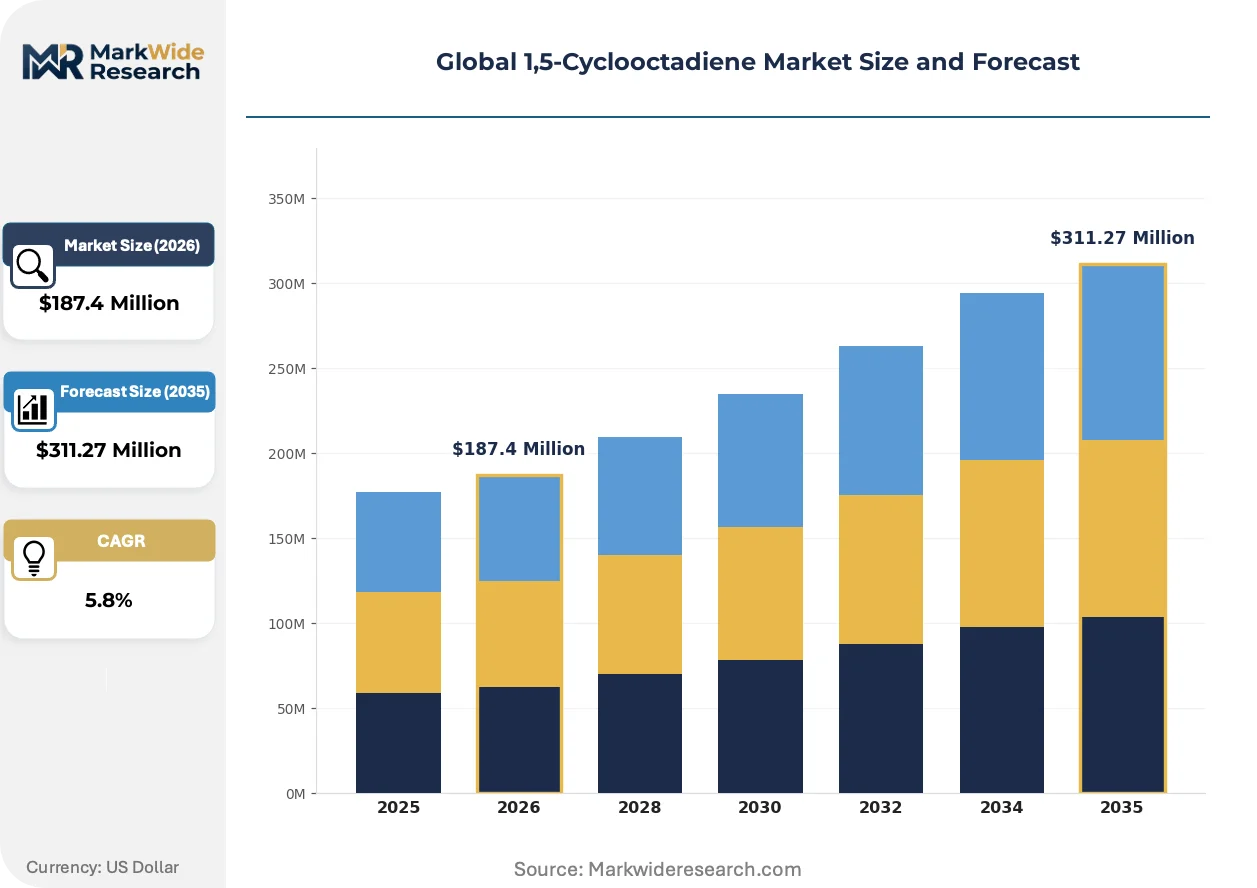
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purified, Technical Grade, Analytical Grade, Industrial Grade Application: Chemical Synthesis, Material Production, Pharmaceutical Intermediates, Adhesives End User: Chemical Industry, Pharmaceuticals, Research Laboratories, Manufacturing Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Tokyo Chemical Industry Co., Ltd, Oakwood Chemical, Sigma Aldrich, Hairui Chemical, ABCR Gmbh, Evonik Industries AG, Biosynth Carbosynth, AK Scientific, TCI Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 1,5-Cyclooctadiene Market Emerging Trajectories
Continuous flow dimerization reactors and advanced extractive distillation sequences are reshaping how producers balance yield, purity, and energy intensity in COD manufacturing, with downstream certification requirements now dictating upstream process design.
Membrane-assisted extractive distillation is absorbing residual impurity loads that previously required multiple crystallization stages, enabling single-pass production of pharmaceutical-grade COD. Specialty polymer manufacturers in the US Gulf Coast petrochemical cluster are adopting these units to secure 99.5-plus percent purity without batch processing delays. The technology is absorbing capital allocation that previously funded conventional purification trains, compressing payback periods for integrated producers.
ECHA's 2023 updated REACH guidance on cyclodiene derivative hazard classifications is forcing importers to resubmit extended safety data sheets with revised exposure scenario documentation. German specialty chemical distributors are absorbing compliance costs by bundling COD with certified handling equipment and spill-response protocols. The regulation is absorbing attention from quality assurance teams at polymerization facilities across the European Union, delaying spot purchases in favor of pre-qualified supplier relationships.
Specification-driven procurement now dominates COD purchasing, with buyers unbundling purity certification from volume commitments to enable multi-source qualification. Pharmaceutical intermediate manufacturers are replacing annual supply agreements with quarterly purity-tier auctions that reward analytical-grade consistency over scale discounts. This pattern concentrates in the Osaka-Singapore distribution corridor, where Tokyo Chemical Industry's regional warehousing enables rapid certificate-of-analysis turnaround for audit-sensitive buyers.
Global 1,5-Cyclooctadiene Market Segmentation
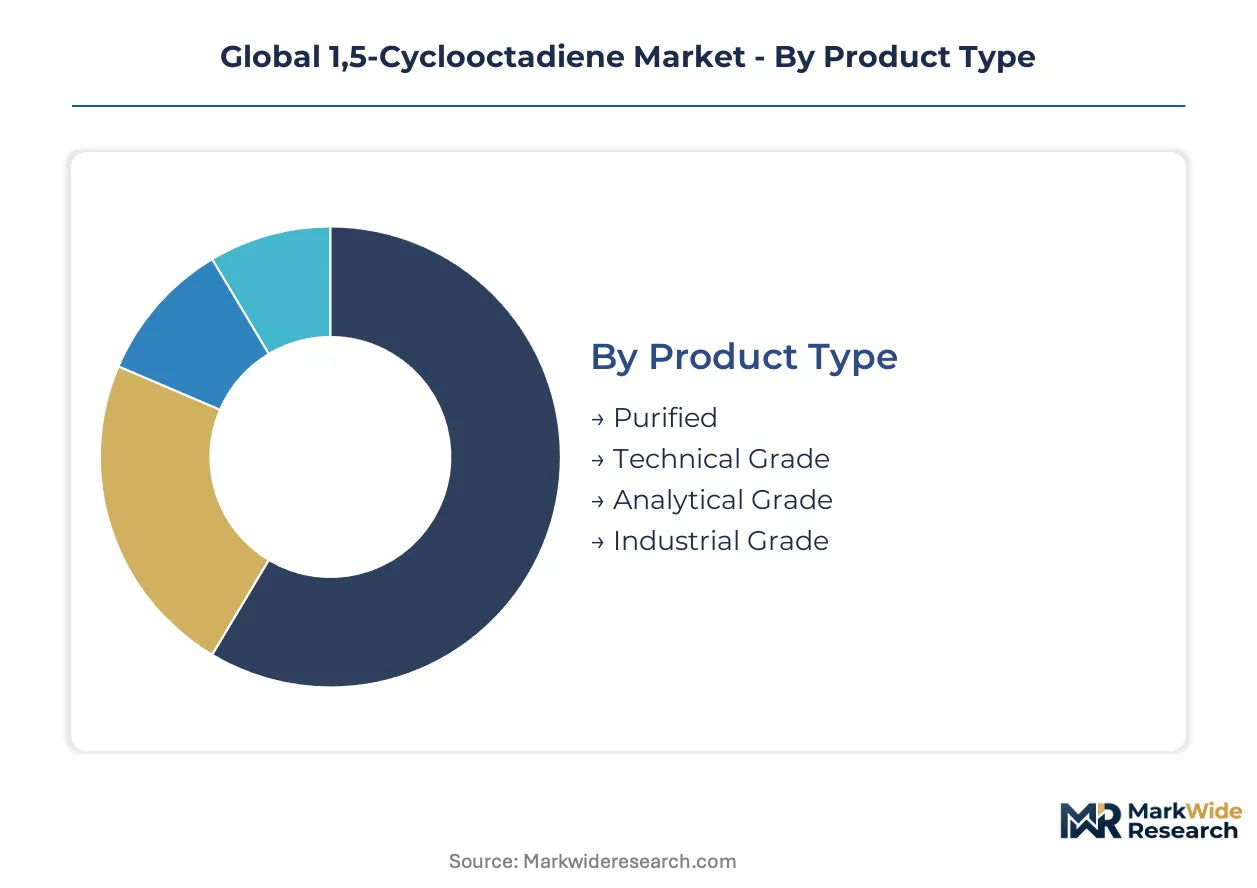
1,5-Cyclooctadiene procurement patterns diverge sharply across purity tiers and end-use certifications. Buyers in pharmaceutical supply chains demand analytical-grade documentation that polymer manufacturers rarely require.
Product Type:
Purified grades command substantial margin premiums over technical alternatives, while analytical certification creates a discrete price tier for audit-sensitive applications.
- Purified:Residual impurity thresholds below 0.1 percent satisfy pharmaceutical intermediate specifications. German specialty polymer producers along the Rhine-Ruhr corridor absorb the majority of volumes for precision catalyst precursor synthesis.
- Technical Grade:Standard dimerization output serves adhesives and elastomer modification without further refinement. US Gulf Coast petrochemical clusters favor this tier for captive consumption in material production workflows.
- Analytical Grade:Certificate-of-analysis protocols align with FDA and EMA inspection standards for GMP intermediate manufacturing.
- Industrial Grade:Bulk dimerization output meets general chemical synthesis requirements where purity specifications remain permissive.
Mature deployment sits with Technical Grade. Newer deployment is concentrated in Analytical Grade.
Application:
End-use differentiation tracks certification burden and volume scale, with research-intensive applications pulling premium grades while commodity material production absorbs technical volumes.
- Chemical Synthesis:COD-ligated palladium precursors enable metal-organic framework research and organometallic catalysis. Academic laboratories in Japan and industrial R&D facilities in Germany are expanding offtake faster than traditional polymerization demand.
- Material Production:Specialty polymer manufacturers incorporate COD-derived monomers into high-performance elastomers and adhesives. The Osaka-Singapore distribution corridor channels technical-grade volumes into East Asian manufacturing.
- Pharmaceutical Intermediates:Transition-metal catalyst precursors require REACH-compliant documentation and residual solvent testing.
- Adhesives:Elastomer modification applications tolerate higher impurity loads than pharmaceutical specifications permit.
Volume concentration remains in Material Production. Steepest expansion trajectory belongs to Chemical Synthesis.
End User:
Customer type determines procurement modality, with large chemical manufacturers favoring contracted purity-tier bundles while research buyers prioritize certificate turnaround speed.
- Chemical Industry:Integrated producers like Evonik Industries AG consume captive diene output for internal polymerization units. Specialty manufacturers without backward integration into butadiene dimerization rely on pre-qualified supplier relationships.
- Pharmaceuticals:GMP-compliant intermediate manufacturers demand quarterly purity-tier auctions that reward analytical-grade consistency over volume discounts.
- Research Laboratories:Metal-organic framework investigators require rapid certificate-of-analysis turnaround for grant-funded procurement cycles.
- Manufacturing:Adhesives and sealant producers absorb technical-grade volumes through distributor networks.
Contracted volume sits with Chemical Industry. Spot-purchase flexibility concentrates in Research Laboratories.
Distribution Channel:
Channel selection reflects buyer scale and certification urgency, with direct relationships dominating large-volume procurement while digital platforms serve fragmented research demand.
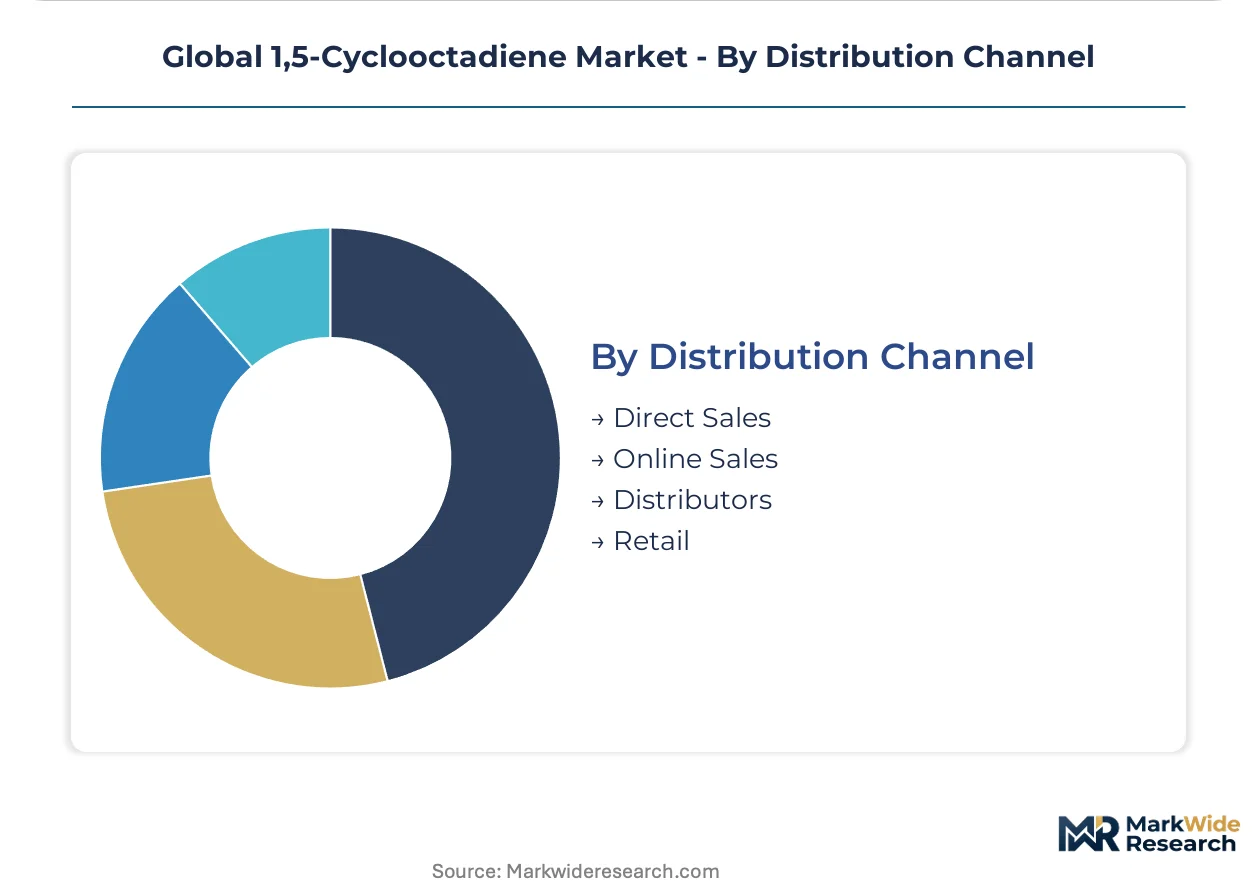
- Direct Sales:Specialty polymer manufacturers in Germany and the United States negotiate multi-year purity-tier bundles with integrated producers. These arrangements absorb compliance costs through bundled handling equipment and spill-response protocols.
- Distributors:Regional warehousing in Osaka and Singapore enables rapid certificate turnaround for audit-sensitive buyers across East Asia.
- Online Sales:Sigma Aldrich-style platforms serve research laboratories with analytical-grade certification and documented chain-of-custody.
- Retail:Small-scale chemical synthesis buyers access technical-grade volumes through local chemical supply houses.
Large-volume procurement runs through Direct Sales. Fragmented demand channels through Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany and the United States while consumption spreads across East Asian research hubs. This geographic split shapes trade flows and certification requirements.
Germany
Rhine-Ruhr and Ludwigshafen chemical corridors absorb high-purity COD for specialty polymerization workflows. ECHA's updated REACH guidance forces importers to resubmit extended safety data sheets with revised exposure scenarios. German distributors bundle COD with certified handling equipment to absorb compliance costs.
United States
EPA oversight under the Toxic Substances Control Act shapes import documentation for COD entering manufacturing channels. The US Gulf Coast petrochemical cluster favors technical-grade volumes for captive consumption in adhesives and elastomer production. Membrane-assisted extractive distillation units enable single-pass pharmaceutical-grade production.
Japan
Academic laboratories in Kanto and Osaka expand offtake for metal-organic framework research using COD-ligated palladium precursors. METI standards align with international reference methods, reducing certification burdens for domestic suppliers. Tokyo Chemical Industry anchors East Asian distribution through regional warehousing.
China
SAMR-mandated GB standards for chemical purity diverge from ISO methods, creating dual-certification requirements for multinational suppliers. Yangtze River Delta polymer manufacturers drive technical-grade consumption for material production. The central government's dual carbon goals pressure producers to explore biobased butadiene feedstocks.
India
PLI scheme incentives for advanced material manufacturing attract greenfield polymerization investments requiring certified COD feedstock. Maharashtra and Gujarat specialty chemical parks develop catalyst precursor synthesis capabilities. The country's national pharmaceutical regulator tightens documentation for imported intermediates.
Global 1,5-Cyclooctadiene Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct purity-tier segments. The vendor base spans integrated chemical producers, analytical-grade distributors, and regional warehousing specialists. Three archetypes dominate: backward-integrated petrochemical players, certification-heavy laboratory suppliers, and East Asian distribution platforms. Competitive moves concentrate on multi-year purity-tier bundles and rapid certificate-of-analysis turnaround.
Within the integrated producer tier, Evonik Industries AG exemplifies captive diene supply for internal polymerization units. Among laboratory-grade specialists, Sigma Aldrich occupies a position defined by analytical certification protocols satisfying pharmaceutical audit requirements. Tokyo Chemical Industry Co., Ltd anchors the East Asian distribution archetype through regional warehousing infrastructure in Osaka and Singapore.
| Leading Market Players |
|---|
| Tokyo Chemical Industry Co., Ltd |
| Oakwood Chemical |
| Sigma Aldrich |
| Hairui Chemical |
| ABCR Gmbh |
| Evonik Industries AG |
| Biosynth Carbosynth |
| AK Scientific |
| TCI Chemicals |
| Others |
Supply Flow & Price Mechanics
Butadiene feedstock volatility from steam cracker C4 stream availability transmits directly through dimerization economics into technical-grade COD pricing, while REACH dossier preparation costs embed as premiums in analytical-grade quotations for European pharmaceutical buyers.
Pricing Analysis
Margin tightening in technical-grade tiers reflects butadiene cost compression during ethylene demand downcycles. Three-tier pricing structure across analytical, purified, and technical levels separates pharmaceutical audit-grade certification from standard polymerization feedstock. Cost-down pressure on technical grades accelerates because non-integrated producers lack captive C4 sourcing. Research laboratories exhibit lowest price sensitivity due to grant-funded procurement cycles and certificate-of-analysis urgency.
Supply Chain Analysis
Dual-sourcing requirements from pharmaceutical GMP manufacturers mandate multi-supplier qualification against both REACH and FDA inspection standards. Production concentrates in Germany, the United States, and Japan, with raw material dependencies on butadiene dimerization output, palladium catalyst precursors, and analytical certification reagents. Single-source vulnerability sits with qualified technicians for air-sensitive organometallic synthesis. Distribution runs through regional warehousing platforms in Osaka and Singapore for East Asian research demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ECHA's updated REACH guidance on cyclodiene derivative hazard classifications creates an 18-24 month qualification moat freezing out undercapitalized entrants.
For Market Incumbents: Acquire membrane-assisted extractive distillation assets to secure single-pass pharmaceutical-grade production without batch crystallization delays. Deepen backward integration into butadiene dimerization to insulate margins from C4 stream volatility. Consolidate distributor relationships in the Osaka-Singapore corridor to control certificate-of-analysis turnaround speed for audit-sensitive buyers. For New Entrants and Emerging Players: Launch via online analytical-grade platforms serving metal-organic framework research laboratories in Japan and Germany with rapid documentation turnaround. India's PLI scheme incentives for advanced material manufacturing offer the most penetrable geography for greenfield catalyst precursor synthesis facilities. Target quarterly purity-tier auction procurement modalities replacing annual supply agreements. For Investors and Strategic Acquirers: Biobased butadiene dimerization pilot announcements from European producers are the leading indicator that sustainability-mandated buyers will pay carbon-intensity premiums for lower-COD feedstock. Five-to-ten year viability favors certification-heavy laboratory suppliers with established FDA and EMA audit track records over commodity technical-grade producers. Watch for SAMR-REACH regulatory harmonization negotiations as the signal for dual-certification burden relief.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butadiene Dimerization | Captive C4 sourcing from steam cracker operations insulates margin compression during ethylene demand cycles. |
| Membrane-Assisted Extractive Distillation Deployment | Single-pass pharmaceutical-grade production eliminates batch crystallization delays for US Gulf Coast polymer manufacturers. |
| Regional Warehousing Expansion | Osaka and Singapore hub positioning enables rapid certificate-of-analysis turnaround for audit-sensitive East Asian buyers. |
| Biobased Feedstock Qualification | Fermentation-derived C4 platforms align with EU Green Deal carbon intensity mandates for sustainability-driven procurement. |
| Dual-Certification Laboratory Investment | Simultaneous REACH and SAMR validation capabilities compress new supplier qualification timelines from 24 to 12 months. |
Methodological Framework
Independent corroboration across plant managers at butadiene dimerization facilities, procurement leads at German specialty polymer manufacturers, distribution channel partners in the Osaka-Singapore corridor, and technical R&D directors at metal-organic framework laboratories underwrites the qualitative findings. Secondary validation draws from customs and trade data, Cefic sector reports, SEC 10-K filings from integrated chemical producers, and ECHA REACH registration dossiers. Bottom-up volume estimates from purity-tier consumption patterns triangulate against top-down market sizing from production capacity declarations.
Comparable-period anchoring to historical dimerization output and palladium precursor demand patterns shaped the projection horizon across the analysis window. Segmentation dimensions modeled include grade tier, end-use application, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projections for chemical synthesis versus material production applications. Forecast inputs incorporate butadiene feedstock cost trajectories and pharmaceutical audit requirement evolution.
Feedstock cost volatility, regulatory harmonization failure between REACH and SAMR standards, and substitute ligand adoption in palladium-catalyzed transformations are the dominant revision risks. Deviation in biobased butadiene dimerization scale-up timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Cellulose Ether and Derivatives Market
Specialty Chemicals
Superdisintegrants Market
Specialty Chemicals
South Korea Cleanroom Disposable Gloves Market
Specialty Chemicals
Hydroxypropionic Acid Market
Specialty Chemicals
Octocrylene Market
Specialty Chemicals
Sophorolipids Market
Specialty Chemicals
Global Lactobionic Acid Market
Specialty Chemicals
Isophytol Market
Specialty Chemicals
Sandarac Market
Specialty Chemicals
Bio-Based Aromatics Market
Specialty Chemicals
Hydroxyproline Market
Specialty Chemicals
Polyacrylamide Gel Electrophoresis (PAGE) Market
Specialty Chemicals
Global Specialty Fuel Additives Market
Specialty Chemicals
Squalene Market
Specialty Chemicals
Stearates Market
Specialty Chemicals
Global 28-Homobrassinolide Market