
 P2P Antennas Market | 2026-2036
P2P Antennas Market Size, Share, and Industry Trends Forecast 2026-2036
P2P Antennas Market Outlook
The EU Green Deal is decoupling P2P antenna procurement from carbon-intensive supply chains across European telecom builds. Ubiquiti Networks leverages its vertically integrated manufacturing to control component sourcing for outdoor installations. Cambium Networks competes through specialized fixed wireless access portfolios aimed at ISP backhaul. MikroTik anchors its position with cost-optimized hardware for emerging market deployments.
Point-to-point antennas are radio frequency transducers engineered for directional communication between two fixed nodes, typically operating across licensed and unlicensed spectrum bands from sub-6 GHz to E-band frequencies, with gain specifications ranging from 15 dBi to 40 dBi depending on dish diameter and frequency. These devices serve as backhaul infrastructure for cellular networks, enterprise campus links, and last-mile broadband extension where fiber deployment proves economically unviable. Directional antennas capture the dominant share of product type revenue due to their spectral efficiency and interference rejection in licensed microwave bands. mmWave technology represents the fastest-expanding segment as carriers densify urban networks with high-capacity, short-hop links. Panel antennas occupy the most mature product position, with margin pools shifting toward integrated radio-and-antenna units that reduce tower loading and installation labor.
FCC spectrum auctions and the EU Radio Equipment Directive shape product certification timelines and frequency availability for P2P hardware entering the US and European markets. India's TRAI mandates on backhaul spectrum pricing directly influence ISP procurement decisions for rural point-to-point links. China's MIIT equipment certification requirements create a separate compliance pathway for manufacturers targeting domestic 5G transport networks. Stakeholders must monitor spectrum reallocation proceedings and equipment authorization rulemakings across these three jurisdictions to anticipate demand shifts and certification cost structures.
Market Dynamics
Spectrum densification is compressing link distances and forcing hardware refresh cycles as carriers migrate from sub-6 GHz to E-band and mmWave frequencies for urban capacity expansion.
Growth Catalysts
- Rural Digital Opportunity Fund:The FCC's infrastructure subsidies accelerate backhaul procurement across underserved US corridors, reducing fiber trenching requirements for last-mile extension.
- 5G transport densification:Mobile operators deploy high-capacity P2P links for fronthaul and midhaul connectivity in urban small cell clusters.
- India:TRAI's backhaul spectrum pricing reforms enable cost-competitive fixed wireless access for regional ISPs serving tier-2 and tier-3 cities.
Market Restraints
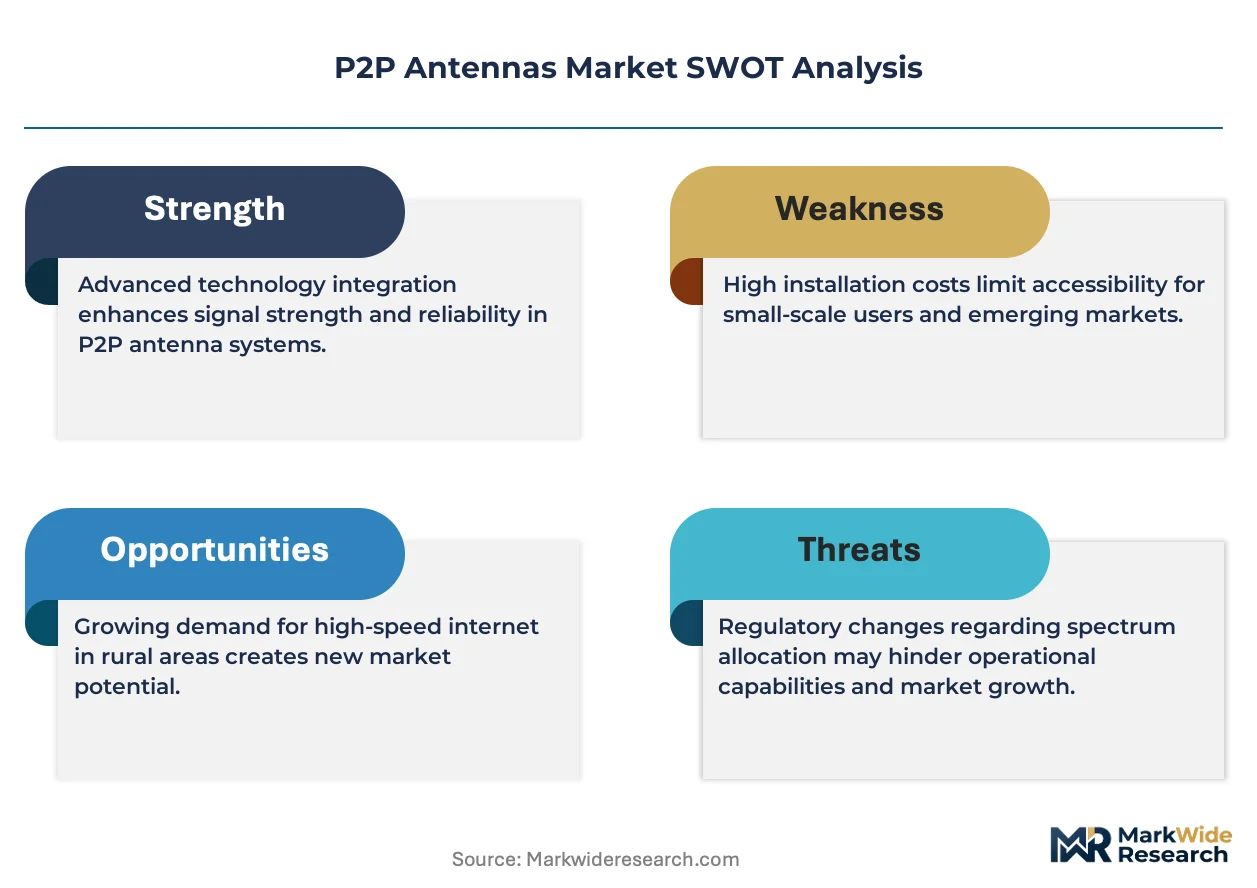
- Aluminum and copper volatility:Raw material cost swings for reflector dishes and waveguide assemblies compress hardware margins for antenna manufacturers.
- Single-source dependency:Gallium nitride substrate supply concentrates among Japanese and Korean semiconductor foundries, creating chokepoint risk for high-power RF amplifiers.
- EU Radio Equipment Directive:Extended certification timelines for E-band equipment delay product launches by 8-14 months compared to unlicensed band alternatives.
Strategic Opportunities
- German industrial corridors:Manufacturing automation and private 5G networks create demand for campus-scale P2P backhaul with sub-50 microsecond latency requirements.
- Integrated radio-antenna units:Converged all-outdoor platforms reduce tower loading and installation labor, capturing premium positioning in greenfield deployments.
- EU Green Deal procurement criteria:Carbon footprint disclosure requirements favor suppliers with renewable-powered manufacturing and circular material recovery programs.
Industry Challenges
- RF engineering talent scarcity:mmWave design expertise concentrates among legacy microwave vendors, constraining product development velocity for new market entrants.
- Legacy TDM migration:Circuit-switched backhaul infrastructure in rural networks requires phased Ethernet transition planning, complicating upgrade roadmaps for incumbent operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | P2P Antennas Market |
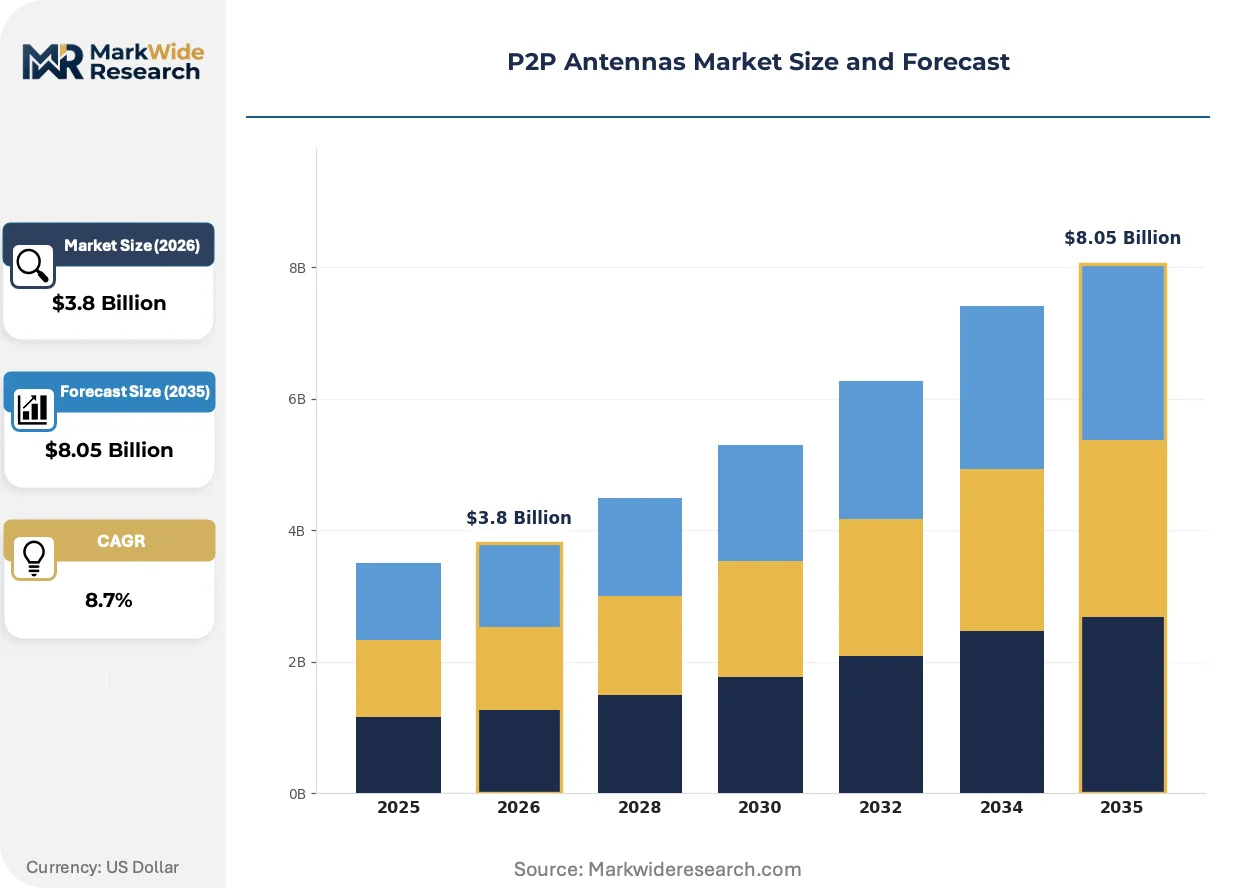
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Directional, Omni-Directional, Sector Antennas, Panel Antennas Technology: Wi-Fi, LTE, Microwave, mmWave Installation: Rooftop, Ground-Based, In-Building, Outdoor End User: Telecom Providers, ISPs, Enterprises, Residential Users |
| Companies Covered | TP-Link, Netgear, Ubiquiti Networks, Radwin, D-Link, Cambium Networks, MikroTik, Siklu Communication, CommScope, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
P2P Antennas Market Strategic Shifts
Antenna architectures are compressing from discrete component assemblies toward software-defined platforms, enabling dynamic beam steering and automated interference mitigation without mechanical realignment.
Beamforming ASICs are converging with passive antenna elements to create active electronically steered arrays for fixed wireless access. Tier-1 carriers in South Korea and Japan deploy these systems for rapid site commissioning. The technology is converging with network automation platforms to eliminate manual antenna alignment and reduce truck rolls.
The EU Green Deal's carbon border adjustment mechanism is reshaping procurement specifications for telecom infrastructure. Equipment vendors must now document embodied emissions across aluminum casting, PCB fabrication, and surface treatment processes. German and French operators have integrated these requirements into RFP scoring matrices ahead of formal mandate deadlines.
Direct vendor relationships are displacing traditional distribution channels for high-volume ISP procurement. Large fixed wireless access providers in India and the United States negotiate frame agreements directly with original equipment manufacturers, bypassing regional distributors for price transparency and firmware customization. This pattern concentrates purchasing power among the top twenty ISP groups while compressing margins for intermediary channel partners.
P2P Antennas Market Segmentation
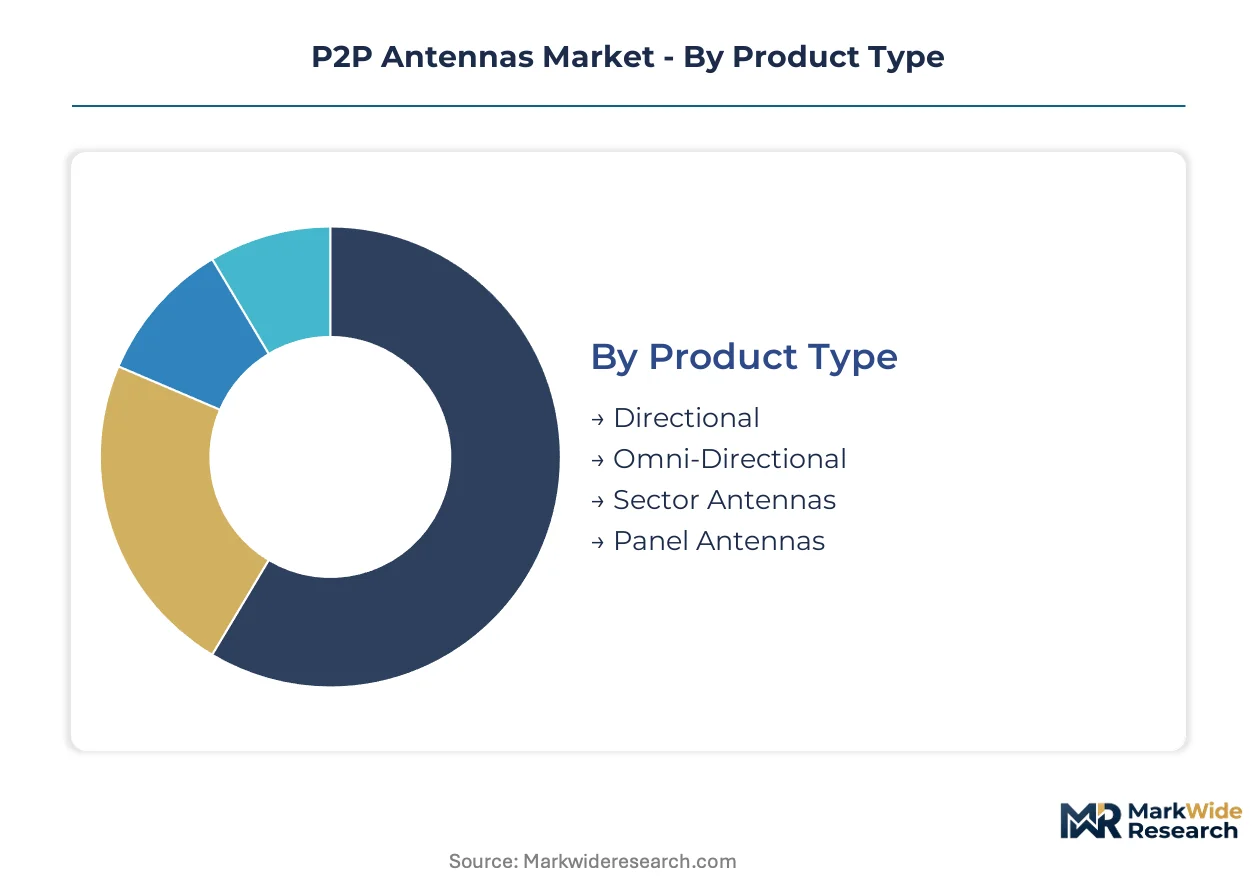
P2P antenna procurement patterns diverge sharply across deployment contexts, with spectrum licensing costs and installation topology driving hardware specification choices. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume scales.
Product Type:
Capital intensity escalates with antenna gain requirements and mechanical complexity, particularly for precision-aligned microwave dishes requiring tower-mounted positioning systems.
- Directional:High-gain parabolic or flat-panel designs with narrow beamwidth concentrate RF energy over long-haul links. Telecom providers in Germany and the United States deploy these for licensed microwave backhaul where spectral efficiency and interference rejection justify premium hardware costs.
- Panel Antennas:Flat-profile planar arrays integrate into compact enclosures for street-level or building-mounted installations. ISPs in India favor these for cost-optimized fixed wireless access in dense urban corridors where visual impact and wind loading constraints apply.
- Omni-Directional:Radiates signal uniformly in azimuth for multipoint distribution scenarios.
- Sector Antennas:Divides coverage into angular segments for cellular base station sectorization.
Directional hardware absorbs the bulk of installed capacity; mmWave-enabled variants are expanding most quickly.
Technology:
Frequency band selection determines component costs, with mmWave front-ends requiring specialized packaging and thermal management compared to sub-6 GHz alternatives.
- mmWave:E-band and V-band transceivers enable multi-gigabit throughput over short-hop urban links. South Korean carriers deploy these for 5G fronthaul densification, though gallium nitride amplifier costs constrain adoption in price-sensitive markets.
- Microwave:Licensed 6-42 GHz bands dominate carrier backhaul with proven reliability. Indian TRAI spectrum pricing reforms are accelerating procurement of these systems for rural ISP networks.
- Wi-Fi:Unlicensed 2.4 GHz and 5 GHz bands serve enterprise campus bridging.
- LTE:Cellular band antennas support private network and fixed wireless access deployments.
Microwave retains the largest installed base; mmWave is climbing the fastest as urban capacity demands intensify.
Installation:
Site preparation and labor scale nonlinearly with mounting height and structural reinforcement requirements.
- Rooftop:Elevated mounting on commercial buildings and cell towers maximizes line-of-sight clearance. German industrial zones favor these installations for private 5G campus networks requiring sub-50 microsecond latency.
- Outdoor:Pole-mounted or wall-mounted enclosures withstand environmental exposure without building integration. US Rural Digital Opportunity Fund projects concentrate procurement here for last-mile extension.
- Ground-Based:Self-supporting towers or monopoles in rural corridors.
- In-Building:Distributed antenna systems for enterprise coverage extension.
Outdoor mounting captures the dominant deployment volume; rooftop installations are gaining share fastest in private network builds.
End User:
Budget authority and technical sophistication vary dramatically, with carrier procurement teams negotiating frame agreements while residential buyers transact through distributor channels.
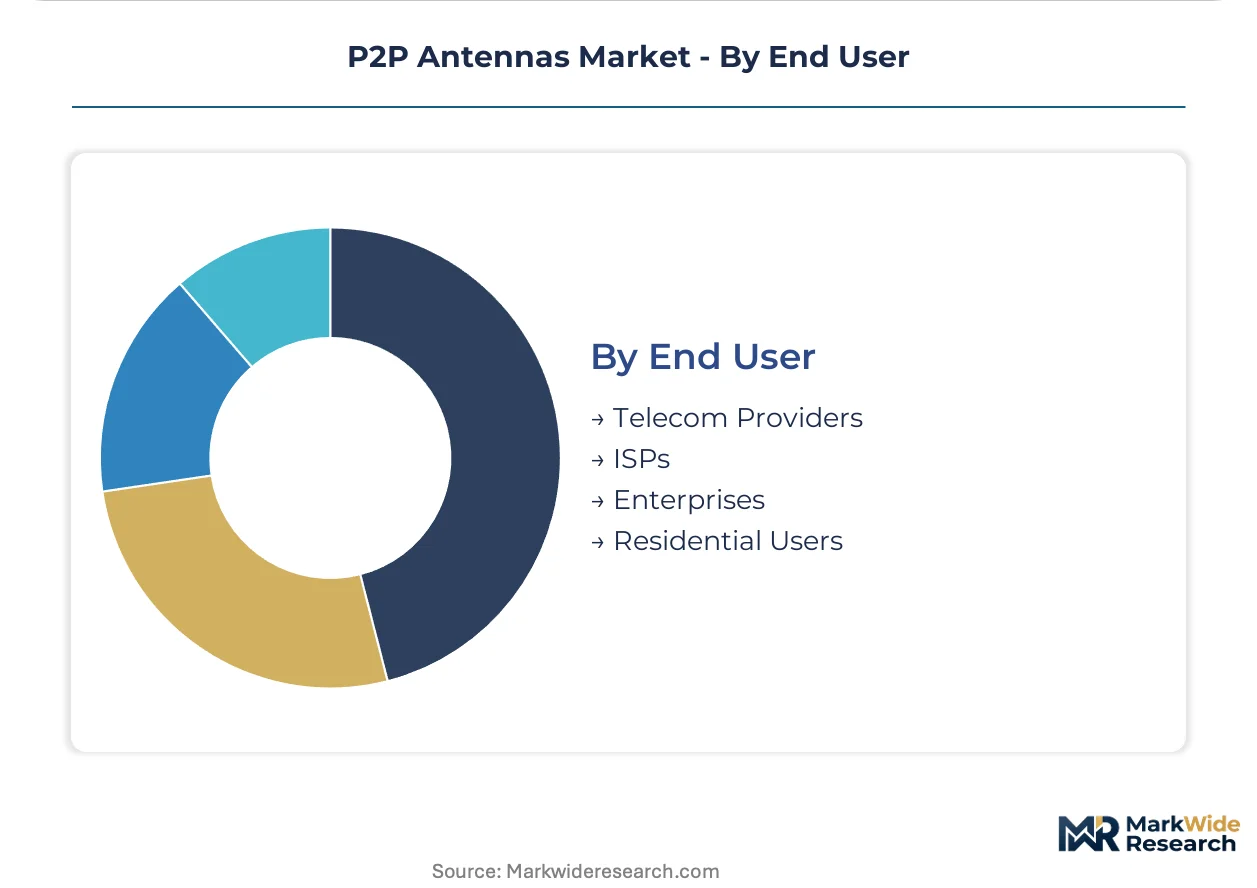
- Telecom Providers:Mobile operators specify carrier-grade hardware with network management integration and decade-long service life. FCC spectrum auctions in the United States and MIIT certification requirements in China shape their procurement timelines.
- ISPs:Fixed wireless access providers prioritize cost-per-subscriber metrics and rapid site commissioning. Large Indian and US operators now negotiate direct with original equipment manufacturers, bypassing distribution intermediaries.
- Enterprises:Manufacturing and logistics campuses procure campus-scale backhaul for automation networks.
- Residential Users:Consumer-grade equipment for broadband extension in remote properties.
Telecom providers command the largest procurement volumes; ISP procurement is expanding most quickly as competitive fixed wireless access scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dallas-Fort Worth anchors North American P2P antenna deployment as rural broadband expansion accelerates across Texas corridors. The FCC's Rural Digital Opportunity Fund channels infrastructure subsidies into backhaul procurement across underserved counties. Carrier densification projects in the metroplex drive demand for high-gain directional hardware.
United States
Telecom providers in Texas, California, and the Midwest expand licensed microwave backhaul for 5G transport networks. FCC spectrum auctions for E-band and V-band frequencies compress link distances in urban clusters. Dallas-Fort Worth and Austin technology corridors concentrate private 5G campus deployments for manufacturing automation.
Germany
Industrial zones in Bavaria and North Rhine-Westphalia procure campus-scale P2P links for factory automation networks. The EU Radio Equipment Directive mandates extended certification timelines for E-band equipment entering European markets. Stuttgart and Munich automotive clusters deploy sub-50 microsecond latency backhaul for robotics coordination.
India
Regional ISPs in Maharashtra, Karnataka, and Telangana scale fixed wireless access for tier-2 and tier-3 city coverage. TRAI backhaul spectrum pricing reforms enable cost-competitive procurement for emerging market deployments. Hyderabad and Bangalore technology corridors concentrate ISP headquarters negotiating direct manufacturer frame agreements.
South Korea
Mobile operators in Seoul and Busan densify urban networks with mmWave fronthaul for small cell clusters. The national spectrum regulator allocates high-frequency bands for 5G transport infrastructure. Pangyo and Songdo smart city developments deploy active electronically steered arrays for rapid site commissioning.
Japan
Carriers in Tokyo, Osaka, and Nagoya migrate sub-6 GHz infrastructure toward E-band frequencies for capacity expansion. METI industrial policy supports domestic equipment certification pathways for 5G transport networks. Yokohama and Kawasaki port zones integrate P2P backhaul for logistics automation systems.
P2P Antennas Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology sophistication and certification depth. The vendor base stratifies into three tiers: vertically integrated hardware specialists, software-defined platform developers, and cost-optimized volume manufacturers. Two strategic archetypes dominate: integrated radio-antenna unit providers capturing greenfield premium positioning, and unlicensed-band specialists serving price-sensitive ISP procurement. Competitive moves concentrate on direct distribution channel establishment and carbon footprint disclosure alignment with EU procurement criteria.
Among North American platform developers, Ubiquiti Networks and Cambium Networks exemplify divergent positioning strategies. Ubiquiti Networks occupies a position within the vertically integrated tier, leveraging captive manufacturing control for outdoor installation hardware. Cambium Networks sits within the specialized fixed wireless access segment, anchoring carrier-grade backhaul portfolio development. MikroTik represents the cost-optimized archetype, serving emerging market volume procurement with hardware-agnostic firmware platforms.
| Leading Market Players |
|---|
| TP-Link |
| Netgear |
| Ubiquiti Networks |
| Radwin |
| D-Link |
| Cambium Networks |
| MikroTik |
| Siklu Communication |
| CommScope |
| Others |
Value Chain & Pricing Dynamics
Direct ISP procurement frame agreements in India and the United States are compressing intermediary margins and forcing manufacturers to absorb logistics costs or cede volume to competitors with captive distribution networks.
Pricing Analysis
Throughput-based value anchors dominate carrier-grade procurement, with E-band and mmWave hardware commanding premiums tied to spectral efficiency guarantees and latency specifications. Three-tier pricing structure across premium, standard, and economy levels separates carrier-grade certified equipment from ISP-optimized hardware and unlicensed consumer alternatives. Price differentiation hinges on FCC and EU Radio Equipment Directive certification depth alongside volume scale commitments. Cost compression in the economy tier is intensifying because Indian ISPs negotiate direct manufacturer relationships that bypass distributor markups. Residential buyers exhibit highest price sensitivity; telecom providers with decade-long service life requirements show lowest.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and South Korea anchor hub-and-spoke fulfillment patterns for carrier-grade hardware with extended certification timelines. Manufacturing concentrates in China for PCB fabrication and surface treatment, Taiwan for precision aluminum casting of reflector dishes, and Japan for gallium nitride substrate production. Raw material dependencies span aluminum for reflector assemblies, copper for waveguide components, and rare earth elements for high-power RF amplifiers. Single-source vulnerability in gallium nitride substrate supply creates chokepoint exposure for E-band amplifier production. Distribution runs through direct vendor relationships for high-volume ISP procurement, with traditional channels retaining enterprise and residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal carbon disclosure mandates and FCC Rural Digital Opportunity Fund procurement concentration are forcing sub-scale manufacturers toward exit or acquisition as compliance costs outstrip revenue.
For Market Incumbents: To counter direct distribution displacement by Indian and US ISPs, deepen channel control through exclusive firmware customization partnerships and frame agreement lock-ins. Counter gallium nitride supply concentration by securing long-term offtake agreements with Japanese foundries or investing in alternative semiconductor packaging. Certification investment in EU Radio Equipment Directive pre-approval testing preserves premium positioning against faster-to-market unlicensed competitors. For New Entrants and Emerging Players: TRAI backhaul spectrum pricing reforms in India open a window for cost-optimized microwave hardware targeting tier-2 and tier-3 city ISP deployments. White-space targets include German industrial corridor private 5G campus networks with sub-50 microsecond latency requirements and US Rural Digital Opportunity Fund outdoor installation projects. Go-to-market angle centers on integrated radio-antenna units that reduce tower loading and accelerate site commissioning. For Investors and Strategic Acquirers: The window for entry favors vertically integrated hardware specialists with captive manufacturing and established FCC or EU certification portfolios. Long-term viability rests on carbon footprint disclosure capabilities aligned with EU Green Deal procurement scoring matrices. Acquisition target archetype: mid-cap manufacturers with E-band certification depth and renewable-powered production facilities. Watch for spectrum reallocation proceedings in the United States, India, and China as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Radio-Antenna Unit Development | Converged platforms reduce tower loading and capture greenfield premium positioning in 5G transport builds. |
| EU Green Deal Certification Alignment | Carbon disclosure capabilities unlock German and French operator RFP scoring advantages ahead of mandate deadlines. |
| Direct Distribution Channel Establishment | Frame agreements with Indian and US ISPs bypass intermediary compression and enable firmware customization. |
| Gallium Nitride Supply Security | Long-term foundry partnerships or alternative semiconductor investments mitigate Japanese-Korean chokepoint risk. |
| mmWave Beamforming ASIC Integration | Active electronically steered arrays eliminate manual alignment and reduce truck rolls for South Korean carriers. |
Study Parameters
Independent corroboration across FCC equipment authorization databases, EU Radio Equipment Directive certification registries, and TRAI spectrum pricing circulars underwrites the qualitative findings. Primary interviews with RF engineering directors at telecom providers, ISP procurement leads in India and the United States, and antenna manufacturing operations heads combined with secondary validation from customs trade data, SEC 10-K filings of listed equipment vendors, and hyperscaler capex disclosures. Bottom-up shipment estimates triangulated against top-down infrastructure subsidy allocations from the Rural Digital Opportunity Fund and EU structural investment programs.
Rate-of-change decomposition across the analysis window segments volume and value by product type, technology band, installation topology, and end-user procurement authority. Modeled dimensions include directional versus panel versus omni-directional hardware, mmWave versus microwave versus sub-6 GHz frequency deployment, rooftop versus outdoor versus ground-based mounting, and telecom provider versus ISP versus enterprise budget authority. CAGRs derived from infrastructure subsidy run-rate analysis and carrier densification project pipelines. Forecast inputs incorporate FCC spectrum auction schedules and MIIT equipment certification timelines.
Caveats apply where spectrum reallocation proceedings, raw material cost volatility in aluminum and copper, or gallium nitride supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding subsidy disbursement velocity and carrier migration timelines from sub-6 GHz to E-band frequencies. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Wireless Connectivity Market
Wireless Technologies
Wi-Fi 7 Market
Wireless Technologies
Near Field Communication Market
Wireless Technologies
Global Massive MIMO Market
Wireless Technologies
Global Wireless Health Market
Wireless Technologies
Asia-Pacific Wi-Fi 6 Market
Wireless Technologies
Global Wireless Data Radio Modem Market
Wireless Technologies
Europe Fixed Wireless Access (FWA) Market
Wireless Technologies
Global Bluetooth Audio Codec Market
Wireless Technologies
5G Spectrum Market
Wireless Technologies
Outdoor Wi-Fi Market
Wireless Technologies
Wireless Phone Chargers Market
Wireless Technologies
5G Wireless Equipment Market
Wireless Technologies
Base Transceiver Station (BTS) Market
Wireless Technologies
Industrial 5G Market
Wireless Technologies
Voice Over Wifi Market