
 Base Transceiver Station (BTS) Market | 2026-2036
Base Transceiver Station (BTS) Market Size, Share, and Industry Trends Forecast 2026-2036
Base Transceiver Station (BTS) Market Outlook
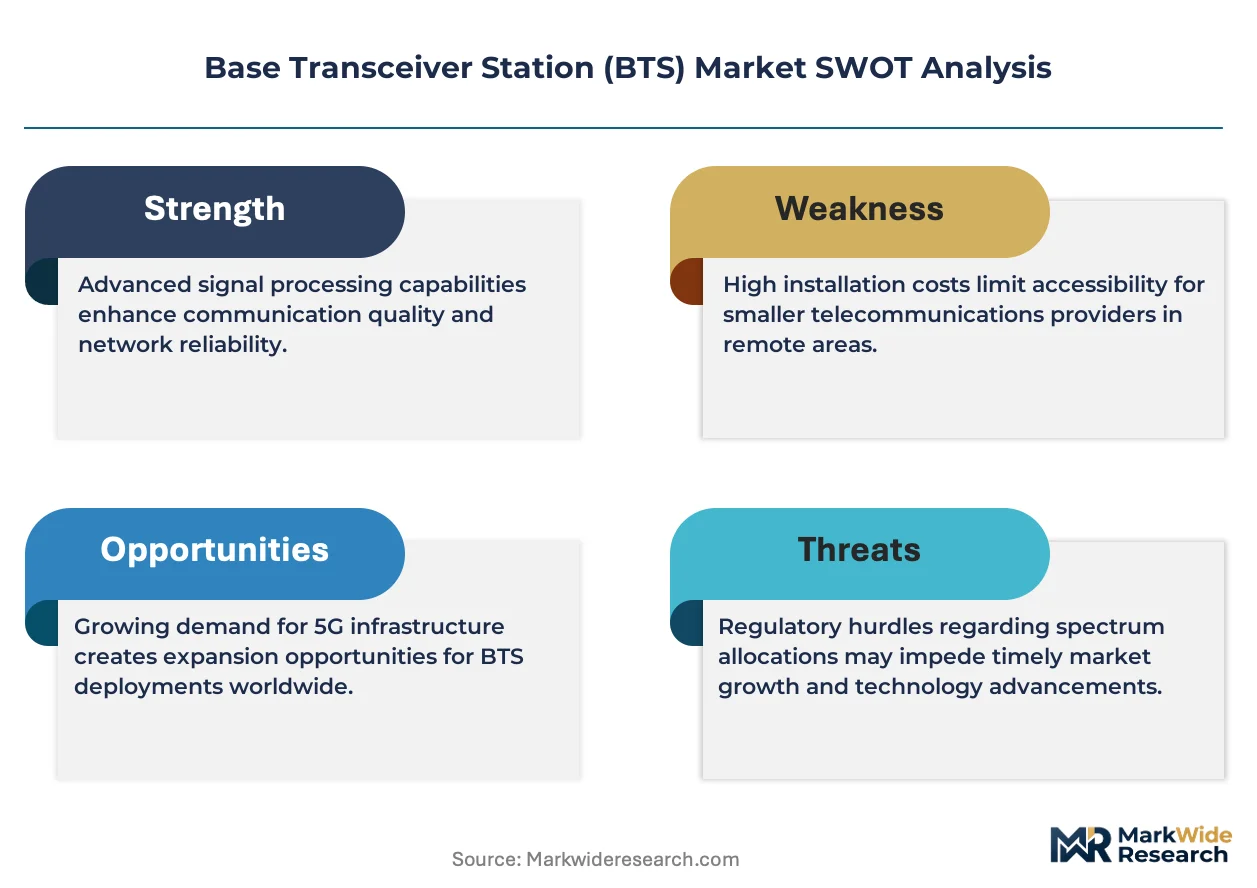
Open RAN disaggregation is tilting baseband processing toward software-defined implementations that separate hardware from protocol stacks. Huawei Technologies leverages its captive semiconductor fabrication to sustain cost advantages in integrated macro cell platforms. Ericsson anchors its position through deep operator relationships in European 5G rollouts. Nokia differentiates via its AirScale portfolio targeting cloud-native deployments for telecom operators.
A base transceiver station comprises radio transceivers, antennas, and signal processing equipment that interface mobile devices with the core network, typically operating across frequency bands from 700 MHz to 3.5 GHz with output power ranging from milliwatts in femtocells to hundreds of watts in macro installations. 5G technology segments command premium positioning as carriers deploy massive MIMO arrays requiring denser site grids. Macro cell installations retain volume dominance due to coverage obligations in rural and suburban zones, while pico cell and femtocell categories capture margin pools from indoor enterprise and smart building applications. Street furniture deployments are gaining traction in urban corridors where rooftop and tower access remains constrained.
The Federal Communications Commission shapes US spectrum allocation and auction rules that directly determine BTS deployment timelines, while the European Telecommunications Standards Institute mandates interoperability protocols under its 5G specifications. India's Telecom Regulatory Authority enforces local sourcing requirements through production-linked incentive frameworks that redirect supply chain localization. Stakeholders must monitor spectrum refarming decisions and Open RAN maturity benchmarks as procurement criteria diverge between integrated legacy stacks and disaggregated vendor ecosystems.
Market Dynamics
Open RAN disaggregation is forcing a fundamental restructuring of vendor relationships and procurement patterns across the Base Transceiver Station ecosystem. Telecom operators are decoupling hardware from software stacks, fragmenting traditional integrated supplier positions while creating entry points for specialized component vendors.
Growth Catalysts
- 5G Massive MIMO Deployment:Carriers are densifying site grids to support higher-order antenna arrays, expanding addressable hardware volumes for macro and small cell installations.
- India PLI Localization Mandate:The Department of Telecommunications production-linked incentive framework is redirecting supply chain investment toward domestic manufacturing of radio units and baseband equipment.
- Street Furniture Integration:Municipal authorities in dense urban corridors are permitting lamp post and bus shelter deployments where rooftop access remains restricted.
Market Restraints
- Semiconductor Supply Concentration:Advanced RF front-end components and baseband processors depend on concentrated foundry capacity in East Asia, creating vulnerability to geopolitical friction.
- Site Acquisition Cost Escalation:Right-of-way negotiations and zoning approvals in metropolitan areas extend deployment timelines and inflate total cost of ownership for operators.
- Legacy 2G/3G Refarming Drag:Spectrum reallocation timelines constrained by residual narrowband IoT dependencies delay 5G mid-band clearing in multiple jurisdictions.
Strategic Opportunities
- Enterprise Private Networks:Manufacturing campuses and logistics hubs are deploying dedicated 5G BTS infrastructure to replace Wi-Fi for deterministic latency applications.
- Cloud-Native RAN Architectures:Containerized baseband functions running on commodity servers enable operators to virtualize signal processing and reduce proprietary hardware dependence.
- Smart Building Femtocell Integration:Real estate developers are pre-installing indoor coverage systems as standard infrastructure in premium commercial and residential projects.
Industry Challenges
- RF Engineer Talent Scarcity:The specialized skill set for antenna design and propagation modeling faces generational replacement gaps as experienced practitioners exit the workforce.
- Multi-Vendor Integration Complexity:Open RAN interoperability testing between disaggregated radio units, distributed units, and centralized units extends deployment validation cycles.
- Power Consumption Optimization:Massive MIMO arrays impose thermal management and energy cost burdens that strain operator opex models at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Base Transceiver Station (BTS) Market |
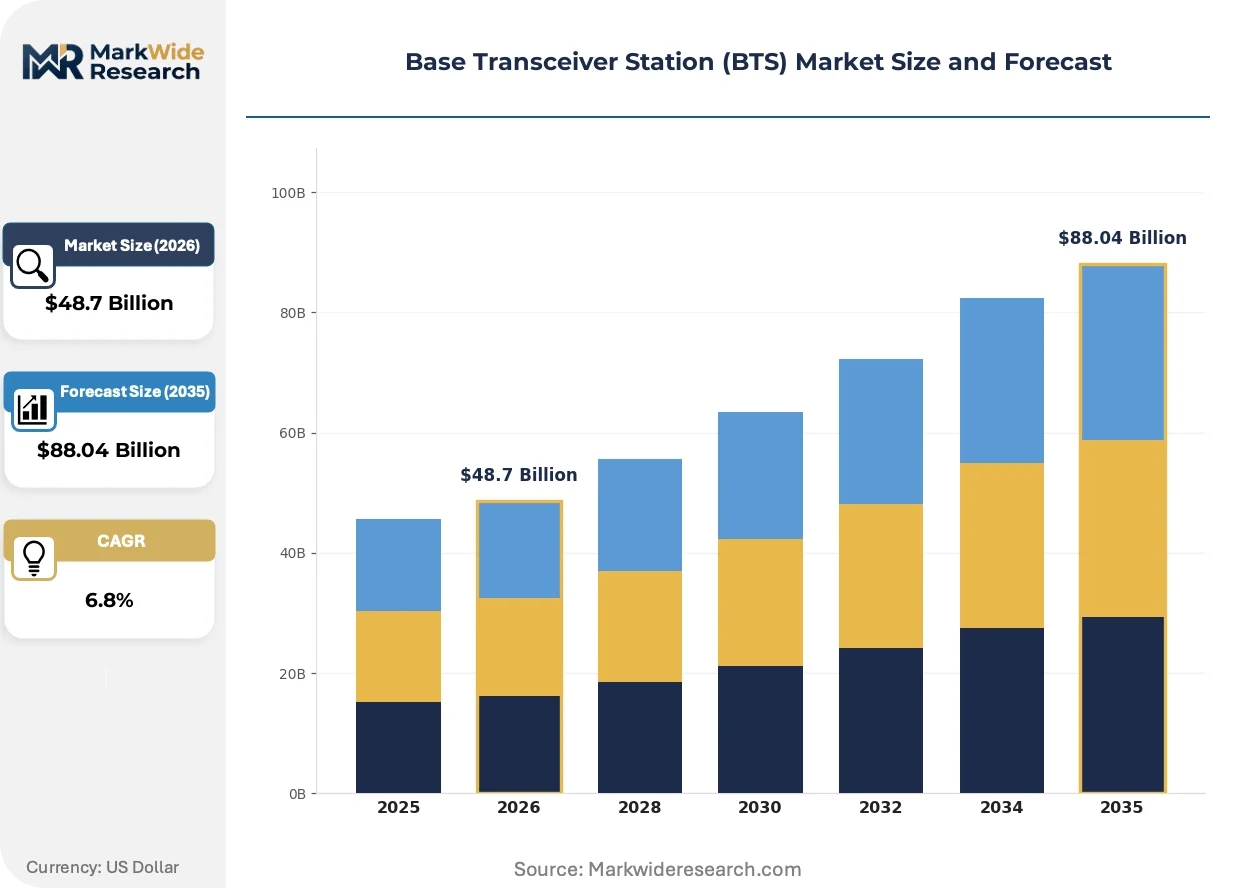
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 3G, 4G, 5G, GSM Product Type: Macro Cell, Micro Cell, Pico Cell, Femtocell End User: Telecom Operators, Enterprises, Government, Service Providers Installation Type: Outdoor, Indoor, Rooftop, Street Furniture |
| Companies Covered | Huawei Technologies, Ericsson, Nokia, Samsung Electronics, ZTE, China Mobile Communications, Vodafone Group, AT&T, Qualcomm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Base Transceiver Station (BTS) Market Strategic Shifts
Software-defined architectures are dissolving the historical boundary between radio hardware and digital baseband, enabling programmable network functions that adapt to traffic patterns in real time. This shift is compressing product lifecycles while expanding the addressable supplier base beyond traditional integrated vendors.
Massive MIMO active antenna units are migrating from passive distributed antenna systems in stadium and arena deployments. Sports venue operators and large public facility managers are specifying integrated active arrays to simplify cabling infrastructure and enable dynamic beamforming for crowd density spikes. The structural consequence is collapsing demand for traditional passive coaxial distribution networks and their installation ecosystem.
The European Telecommunications Standards Institute 5G security specifications and the FCC spectrum auction rules are jointly accelerating equipment certification timelines. Vendors must now demonstrate compliance with both EU cybersecurity mandates and US emission standards before commercial deployment, compressing development schedules and raising testing overhead. Multi-region operators are prioritizing modular designs that satisfy both regulatory regimes through software configuration rather than hardware variants.
Telecom procurement teams are unbundling long-term managed service contracts from hardware supply agreements. Tier-1 carriers in North America and Western Europe are separating network operations from equipment acquisition, creating direct purchasing relationships with component suppliers previously accessed through system integrators. This disintermediation is most visible in Open RAN pilot deployments where operators contract directly with radio unit specialists and software stack vendors.
Base Transceiver Station (BTS) Market Segmentation
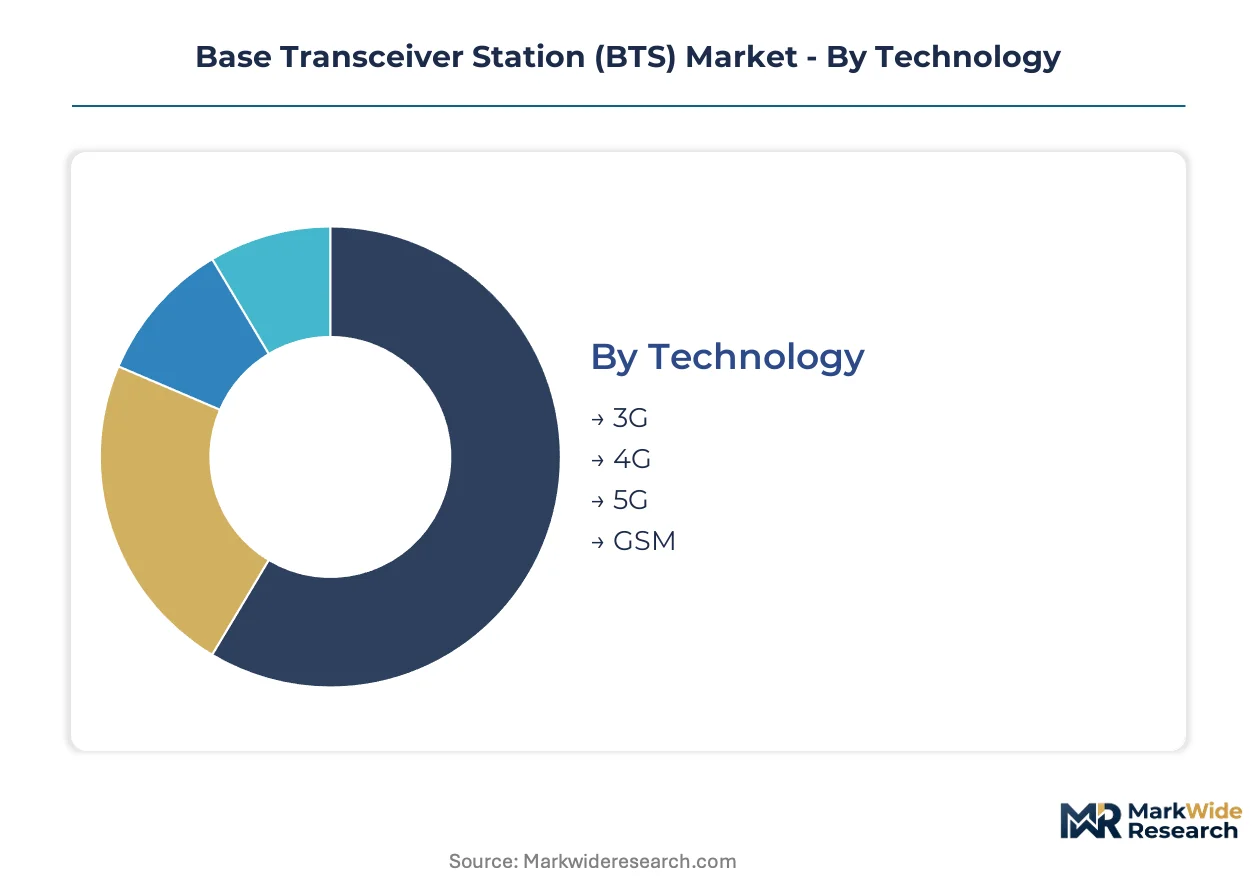
BTS procurement patterns diverge sharply across technology generations and deployment scenarios. Vendor positioning and pricing power fluctuate based on whether installations target wide-area coverage or capacity-dense hotspots.
Technology:
Cost tier determines hardware complexity and margin structure across wireless generations.
- 5G:Massive MIMO active antenna systems integrate 64+ radiating elements with embedded baseband processing. Carrier densification programs in Germany and South Korea are absorbing premium equipment volumes despite energy consumption penalties.
- 4G:Established LTE macro platforms leverage mature semiconductor nodes and standardized antenna configurations. Indian telecom operators under TRAI production-linked incentive mandates are localizing 4G radio unit assembly to meet domestic content thresholds.
- 3G:Legacy W-CDMA infrastructure sustains narrowband IoT services in rural coverage obligations.
- GSM:2G voice networks persist in emerging market roaming corridors and machine-to-machine telemetry.
5G commands the established base. The steepest expansion runs through 4G rural densification in price-sensitive jurisdictions.
Product Type:
Volume concentration shifts with coverage radius and output power specifications.
- Macro Cell:High-power outdoor installations exceeding 40 watts output dominate suburban and rural coverage footprints. Tower companies in Brazil and Indonesia are consolidating macro site portfolios to reduce tenancy ratios and streamline maintenance.
- Femtocell:Low-power indoor units under 100 milliwatts address residential dead zones and enterprise small offices. Japanese real estate developers are pre-installing femtocell infrastructure in Tokyo commercial towers to guarantee tenant connectivity.
- Micro Cell:Mid-range urban infill solutions balance coverage gaps with zoning constraints.
- Pico Cell:Compact indoor deployments target retail venues and transportation hubs with moderate density.
Macro Cell anchors carrier capital allocation. The steepest expansion trajectory belongs to Femtocell as building codes mandate indoor coverage.
End User:
Customer type dictates procurement scale and service integration depth.
- Telecom Operators:National carriers deploy multi-vendor RAN strategies with centralized purchasing functions. Verizon and Deutsche Telekom are unbundling managed services from hardware supply to negotiate direct component contracts.
- Enterprises:Manufacturing campuses and logistics hubs are acquiring dedicated 5G infrastructure for deterministic latency. BMW's Leipzig assembly plant operates a private 5G network replacing Wi-Fi for robotic control.
- Government:Public safety agencies require hardened infrastructure with encryption and priority access.
- Service Providers:Neutral host operators aggregate multiple carrier traffic in venues and transit systems.
Telecom Operators control the installed base. Enterprise verticals are gaining share fastest through private network exemptions.
Installation Type:
Site acquisition economics and zoning permissiveness shape deployment modality selection.
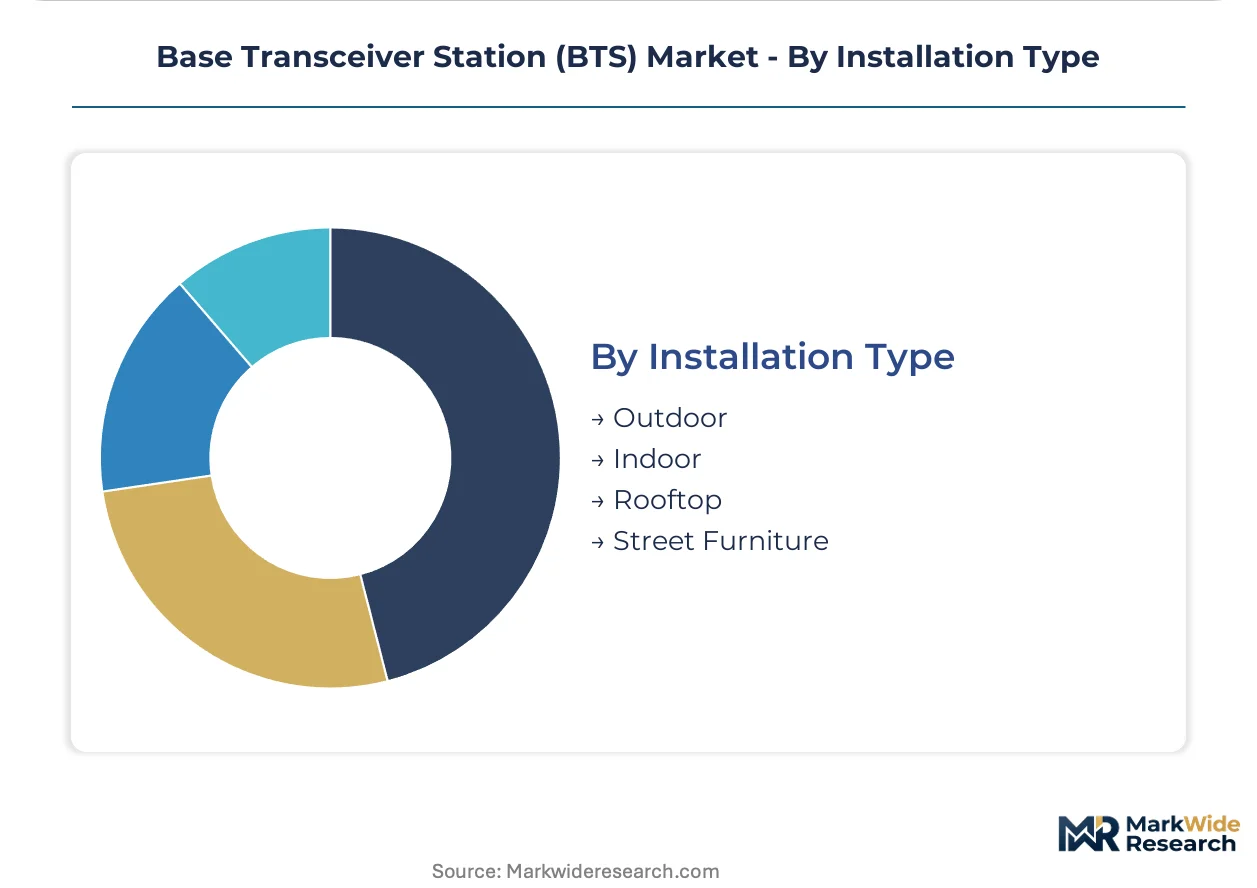
- Outdoor:Greenfield tower and monopole installations serve coverage obligations in low-density geographies. Australian operators face extended approval timelines under local council heritage and environmental review.
- Street Furniture:Lamp post and bus shelter attachments bypass rooftop access constraints in dense urban corridors. London and Barcelona municipal authorities have standardized street furniture attachment specifications to accelerate 5G small cell rollouts.
- Indoor:Distributed antenna systems penetrate subterranean and shielded environments.
- Rooftop:Existing building infrastructure reduces civil works expenditure in suburban zones.
Outdoor installations retain volume dominance. Street Furniture is climbing the fastest as metropolitan zoning tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese BTS equipment flows into carrier networks across Southeast Asia and Africa, while European operators source from Nordic vendors under diversification mandates. Trade corridors reflect geopolitical alignment more than pure cost optimization.
United States
Verizon and AT&T are densifying mid-band 5G coverage in secondary metros. The FCC's spectrum auction rules compress equipment certification timelines. Tower companies in Texas and Florida are consolidating site portfolios to reduce tenancy ratios.
Germany
Deutsche Telekom's Open RAN pilots are fragmenting procurement across specialized vendors. The EU cybersecurity certification framework mandates enhanced testing for critical infrastructure. Industrial clusters in Bavaria host automotive private network deployments at BMW and Siemens facilities.
India
Reliance Jio and Bharti Airtel are expanding 4G and 5G into semi-urban districts under coverage obligations. TRAI's production-linked incentive scheme redirects supply chain investment toward domestic radio unit assembly. Manufacturing concentration in Tamil Nadu and Karnataka is absorbing new semiconductor packaging capacity.
South Korea
SK Telecom and KT are deploying massive MIMO arrays for urban capacity densification. The national spectrum regulator accelerates millimeter-wave clearing for fixed wireless access. Seoul's digital infrastructure cluster drives active antenna innovation for stadium and transit deployments.
Brazil
Claro and Vivo are extending macro coverage into Amazon basin corridors under universal service mandates. Anatel's infrastructure sharing rules reduce site duplication in dense urban cores. Tower operators in São Paulo state are monetizing street furniture attachments for small cell densification.
Base Transceiver Station (BTS) Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement channels. Integrated system vendors retain leverage in macro cell deployments where carrier relationships run deep. Three archetypes dominate: captive semiconductor fabricators, software-defined stack vendors, and neutral host infrastructure operators. Competitive moves concentrate on unbundling managed services from hardware supply and securing direct component contracts.
Within the integrated infrastructure tier, Huawei Technologies and Ericsson exemplify divergent strategic postures. Huawei leverages captive silicon fabrication to sustain cost positioning in macro platforms. Ericsson anchors European 5G rollouts through established operator relationships. Nokia occupies a position between these poles with cloud-native portfolio emphasis.
| Leading Market Players |
|---|
| Huawei Technologies |
| Ericsson |
| Nokia |
| Samsung Electronics |
| ZTE |
| China Mobile Communications |
| Vodafone Group |
| AT&T |
| Qualcomm |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Rotterdam container freight corridors transmit cost volatility from concentrated semiconductor foundry zones directly into BTS equipment landed costs, amplifying price spreads between integrated legacy platforms and disaggregated Open RAN alternatives while forcing procurement teams to renegotiate volume commitments.
Pricing Analysis
5G massive MIMO active antenna systems command substantial premiums over 4G macro platforms and legacy 2G/3G infrastructure due to embedded baseband processing and 64-element radiating arrays. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service bundling, with EU cybersecurity certification and FCC emission compliance driving top-tier positioning. Cost compression in 4G rural densification segments intensifies because Indian PLI localization mandates force assembly cost reductions. Enterprise private network buyers exhibit least price sensitivity due to deterministic latency requirements, while emerging market telecom operators remain most cost-constrained.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for RF front-end components and baseband processors. Taiwan, South Korea, and China anchor advanced semiconductor fabrication for gallium nitride power amplifiers and massive MIMO beamforming chips. BTS equipment draws from concentrated rare earth processing for magnet materials, high-purity copper for antenna conductors, and specialized laminates for printed circuit boards. Single-source vulnerability in East Asian foundry capacity creates procurement contingency requirements. Distribution runs through carrier-direct contracts unbundled from system integrators, with component specialists gaining direct purchasing relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed service and software maintenance contracts expand faster than hardware shipments as Open RAN architectures fragment procurement and extend vendor relationships beyond initial equipment delivery.
For Market Incumbents: Harden cloud-native RAN software stacks against containerized baseband competitors by deepening operator relationships in European 5G rollouts. Invest in certification pre-positioning for both FCC emission standards and ETSI cybersecurity mandates to compress multi-region deployment timelines. Acquire specialized radio unit vendors in India to satisfy TRAI production-linked incentive localization thresholds. For New Entrants and Emerging Players: Establish a beachhead in enterprise private 5G networks for manufacturing campuses and logistics hubs where deterministic latency requirements override carrier-scale procurement leverage. Target Brazilian Amazon basin macro coverage extensions under universal service mandates where incumbent tower consolidation creates tenancy gaps. Pursue direct component contracts with North American Tier-1 carriers unbundling managed services from hardware supply. For Investors and Strategic Acquirers: Carve-out targets emerge from telecom equipment divisions of diversified industrial conglomerates seeking portfolio simplification. Long-term viability hinges on software-defined architecture positioning rather than integrated hardware legacy. Monitor Open RAN interoperability maturity benchmarks as inflection indicator for procurement pattern shifts away from traditional supplier ecosystems.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native RAN Software Development | Containerized baseband functions enable Deutsche Telekom and Verizon to virtualize signal processing on commodity servers. |
| Production-Linked Incentive Localization | TRAI mandates redirect supply chain investment toward Tamil Nadu and Karnataka radio unit assembly operations. |
| Managed Service Contract Unbundling | Telecom procurement teams separate network operations from equipment acquisition to negotiate direct component terms. |
| Enterprise Private Network Deployment | BMW Leipzig and Siemens Bavaria facilities deploy dedicated 5G infrastructure replacing Wi-Fi for robotic control. |
| Street Furniture Attachment Standardization | London and Barcelona municipal specifications accelerate small cell densification where rooftop access remains restricted. |
Study Parameters
The analysis maps macro cell, small cell, and femtocell deployment categories, each validated through primary interviews with RAN procurement directors, network planning engineers, and tower company portfolio managers combined with secondary triangulation across FCC spectrum auction records, ETSI 5G security specifications, TRAI production-linked incentive filings, and carrier capex disclosures. Bottom-up equipment volume estimates and top-down carrier spending patterns were cross-referenced to constrain projection ranges.
Assumptions regarding spectrum refarming timelines, Open RAN interoperability maturity, and semiconductor foundry capacity expansion were held fixed across baseline scenarios while tariff escalation and geopolitical friction were varied in stress testing. Segmentation dimensions modeled include technology generation, product type, end user category, and installation modality across the analysis window. CAGRs were derived from equipment shipment trajectories and carrier densification program announcements, with massive MIMO penetration rates and enterprise private network adoption curves serving as key forecast inputs.
Stress conditions across semiconductor supply concentration, municipal zoning permissiveness, and legacy network refarming drag were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and vendor ecosystem fragmentation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Wireless Intercoms Market
Wireless Technologies
5G Wireless Ecosystem Market
Wireless Technologies
Global Wireless Health Market
Wireless Technologies
Global Bluetooth Audio Codec Market
Wireless Technologies
Global Wireless Testing Market
Wireless Technologies
Industrial Wireless Solution Market
Wireless Technologies
Latin America Wireless Mesh Networking Market
Wireless Technologies
Europe Wireless Charging Market
Wireless Technologies
Fixed Wireless Access (5G/Wttx/LTE) Market
Wireless Technologies
APAC Small Cell Tower Market
Wireless Technologies
Voice Over Wifi Market
Wireless Technologies
France Fixed Wireless Access (FWA) Market
Wireless Technologies
Femtocell Market
Wireless Technologies
Industrial Bluetooth Market
Wireless Technologies
Light Fidelity Market
Wireless Technologies
Global WLAN Market