
 Wireless Intercoms Market | 2026-2036
Wireless Intercoms Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Intercoms Market Analytics
Silicon-based RF components are displacing legacy gallium arsenide transceivers in wireless intercom hardware, which is realigning unit economics toward lower-cost, higher-volume production. Motorola Solutions sustains technology leadership in professional-grade mesh networking for public safety deployments. Clear-Com, LLC dominates theater and broadcast applications with specialized low-latency audio protocols. Panasonic Corporation leverages its semiconductor fabrication scale to control component costs across consumer and commercial product tiers.
A wireless intercom comprises a bidirectional audio communication system operating over radio frequency bands—typically 1.9 GHz DECT, 2.4 GHz Wi-Fi, or sub-GHz proprietary protocols—enabling voice transmission without dedicated wiring infrastructure between fixed base stations and portable handsets or headsets. These systems serve critical coordination functions in environments where mobility, rapid deployment, or structural barriers preclude conventional wired installations. Multi-channel architectures command premium positioning in live event production and industrial control rooms where simultaneous talk paths prevent channel congestion. Wi-Fi technology segments are gaining fastest in educational deployments, where existing network infrastructure eliminates dedicated gateway costs. Standalone products retain volume leadership in residential entry and small commercial security applications where simplicity and price sensitivity dominate purchase criteria.
FCC Part 15 rules govern unlicensed device emissions in the United States, constraining transmit power and spurious emissions while enabling broad market access for consumer and professional equipment. CE marking under the EU Radio Equipment Directive mandates interoperability and electromagnetic compatibility testing for products distributed in Europe, creating compliance cost barriers for smaller manufacturers. ETSI EN 301 406 standards for DECT equipment shape spectral efficiency requirements that directly influence chipset selection and product architecture decisions. Stakeholders must monitor spectrum reallocation proceedings and emerging cybersecurity certification mandates as these regulatory vectors increasingly determine competitive viability and market access conditions.
Market Dynamics
The migration from wired nurse call systems to wireless platforms in US healthcare facilities is compressing replacement cycles and reshaping vendor procurement criteria toward interoperability certification.
Growth Catalysts
- FCC Part 15 spectrum rules:Unlicensed device emissions frameworks in the United States eliminate licensing friction for DECT and Wi-Fi deployments, accelerating hospital infrastructure upgrades.
- Germany's industrial safety mandates:Factory modernization programs require real-time worker coordination systems, driving hardware replacement in manufacturing plants.
- Silicon RF component substitution:Gallium arsenide transceiver displacement is collapsing unit production costs and enabling volume scaling across consumer tiers.
Market Restraints
- Semiconductor fabrication concentration:Advanced RF chip production clusters in East Asia create supply vulnerability for North American and European hardware vendors.
- CE marking compliance burden:EU Radio Equipment Directive testing requirements impose fixed costs that disproportionately constrain smaller equipment manufacturers.
- Legacy wired infrastructure persistence:Existing copper nurse call installations in aging US hospital wings delay full wireless conversion budgets.
Strategic Opportunities
- Educational Wi-Fi convergence:K-12 and university campuses are repurposing existing network infrastructure to bypass dedicated gateway capital expenditure.
- ETSI EN 301 406 spectral efficiency standards:DECT protocol refinements create chipset selection advantages for vendors optimizing European market entry.
- Live event production multi-channel demand:Theater and broadcast venues require simultaneous talk path architectures that command premium positioning.
Industry Challenges
- RF engineering talent scarcity:Specialized microwave and antenna design expertise concentrates in defense and telecommunications sectors, constraining intercom vendor hiring pipelines.
- Legacy system integration complexity:Hybrid wireless-to-wired bridge deployments in healthcare and industrial settings demand custom protocol engineering that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Intercoms Market |
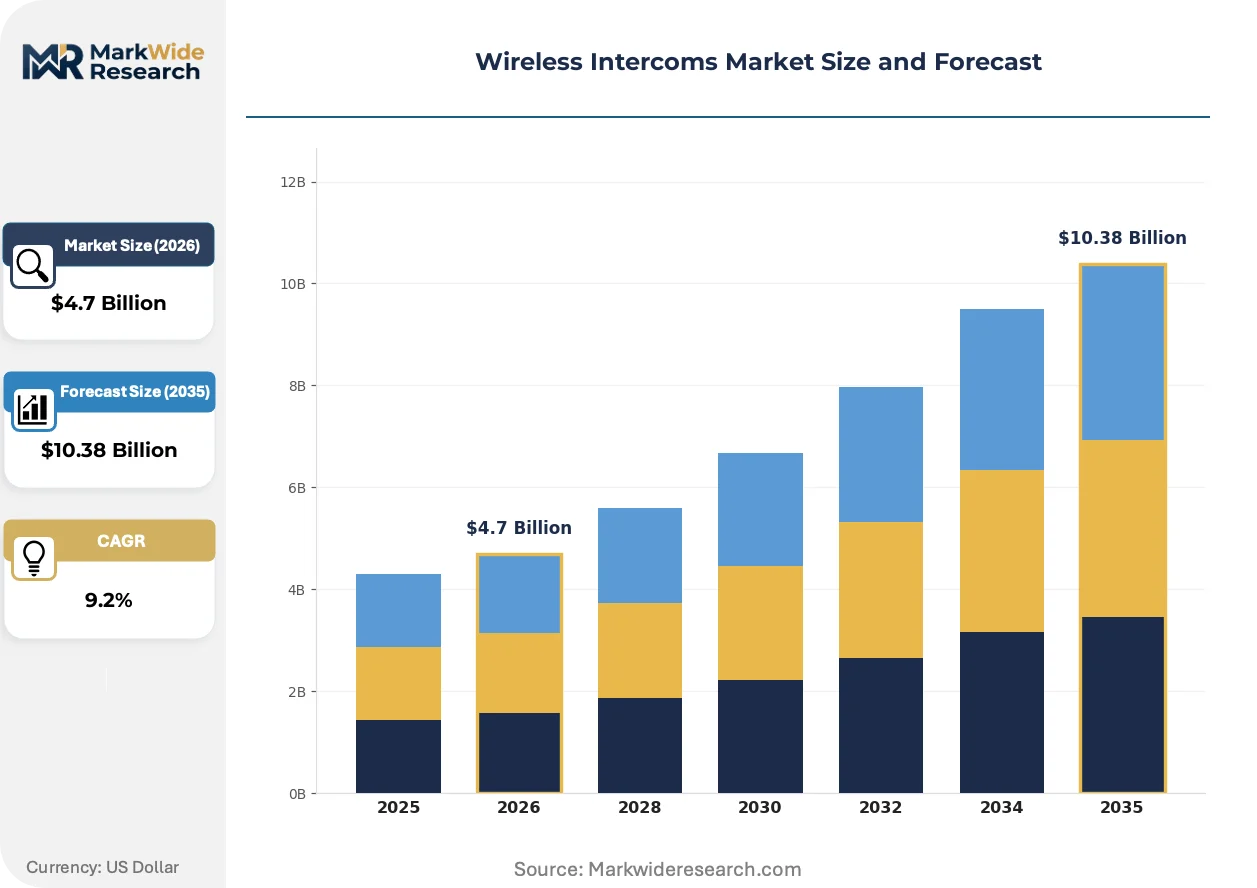
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $10.38 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Multi-Channel, Wireless Handsets, Intercom Systems Installation Type: Wall-Mounted, Portable, In-Wall, Surface-Mounted End User: Residential, Commercial, Industrial, Educational Technology: DECT, Wi-Fi, Bluetooth, Analog |
| Companies Covered | Panasonic Corporation, Motorola Solutions Inc., Clear-Com, LLC, Aiphone Co., Ltd., Zenitel NV, Riedel Communications GmbH & Co. KG, Commend International GmbH, Samsung Electronics Co., Ltd., Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Intercoms Market Evolving Landscape
Audio transmission protocols and hardware architectures are undergoing simultaneous transformation as spectral efficiency mandates collide with buyer demands for simplified deployment.
Mesh networking topologies are rewriting coordination capabilities in public safety and industrial environments. First responders and plant safety managers are adopting self-healing node architectures that eliminate single-point-of-failure vulnerabilities. This topology is compressing competitive differentiation around network resilience rather than raw audio fidelity.
ETSI EN 301 406 standards for DECT equipment are tightening spectral efficiency requirements across European markets. Chipset vendors must redesign modulation schemes to maintain certification, forcing hardware architecture decisions that ripple through product roadmaps. German hospital procurement offices are prioritizing pre-certified platforms to accelerate installation timelines.
Buyer preference for subscription-based service models is displacing perpetual license structures in enterprise and institutional deployments. Facility managers in US healthcare systems favor predictable operational expenditure over capital-intensive ownership. This shift is visible most acutely in multi-site hospital networks standardizing fleet management through vendor-hosted cloud platforms.
Wireless Intercoms Market Segmentation
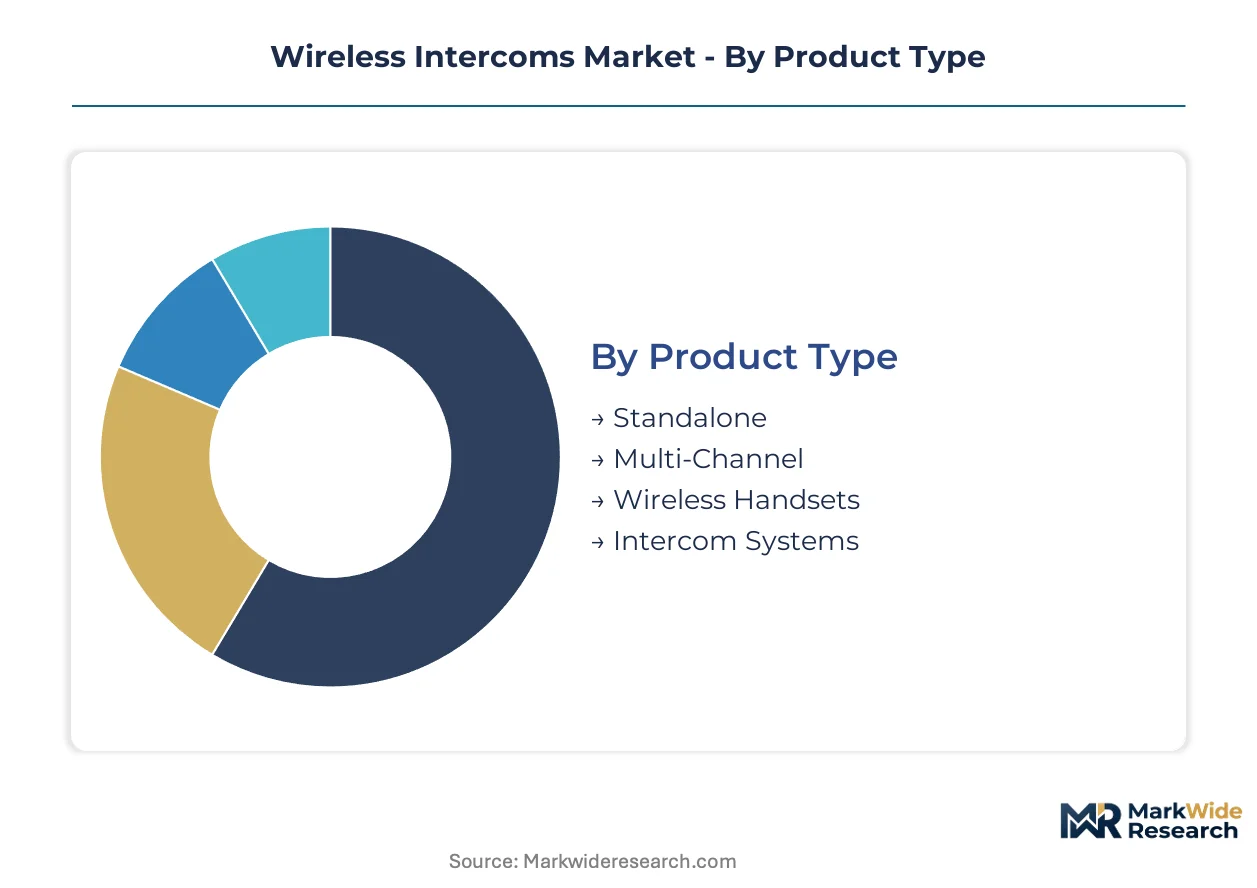
Wireless intercom procurement decisions hinge on infrastructure compatibility, spectral licensing constraints, and mobility requirements that vary sharply across residential security, healthcare modernization, and live production environments. Segmentation reveals how hardware architectures and protocol choices align with distinct buyer risk tolerances and total cost of ownership thresholds.
Product Type:
Buyers prioritize deployment simplicity versus channel density trade-offs when selecting hardware form factors.
- Standalone:Self-contained base-and-handset configurations operate over proprietary sub-GHz protocols without gateway dependencies. Residential entry systems and small commercial security deployments in Germany favor these units for their plug-and-play installation and minimal IT infrastructure demands.
- Multi-Channel:Simultaneous talk-path architectures enable concurrent communication groups without channel congestion. Theater control rooms in London and broadcast facilities in Los Angeles specify these systems for production coordination where audio latency below 30 milliseconds is mandatory.
- Wireless Handsets:Portable DECT or Wi-Fi endpoints roam across distributed access points.
- Intercom Systems:Integrated base station clusters with centralized management software.
Standalone leads on scale; Multi-Channel leads on momentum.
Installation Type:
Physical mounting constraints determine antenna placement, RF propagation characteristics, and retrofit feasibility in existing structures.
- Wall-Mounted:Fixed-position units with external antenna arrays maximize transmit power and range stability. US healthcare facilities specify these for nurse station corridors where coverage reliability outweighs mobility requirements.
- Portable:Battery-powered handhelds with integrated antennas support field coordination. German manufacturing plants deploy these for temporary safety perimeters during equipment maintenance cycles.
- In-Wall:Flush-mounted units preserve architectural aesthetics in commercial lobbies.
- Surface-Mounted:External bracket installations accelerate deployment in retrofit scenarios.
Wall-Mounted dominates retrofit healthcare budgets; Portable climbs fastest on industrial safety mandates.
End User:
Application environment dictates spectral congestion tolerance, cybersecurity posture, and integration complexity.
- Residential:Price-sensitive single-family and multi-unit dwellings prioritize encrypted entry communication with smartphone app pairing. Japanese apartment complexes favor DECT-based video intercoms for their coexistence with dense 2.4 GHz congestion.
- Commercial:Office buildings, retail chains, and hospitality properties require scalable fleet management. French hotel groups standardize on Wi-Fi platforms to leverage existing infrastructure and reduce gateway capital expenditure.
- Industrial:Hardened equipment for manufacturing, energy, and logistics environments.
- Educational:K-12 and university campuses repurposing network infrastructure for campus-wide coordination.
Commercial leads on scale; Educational expands most quickly on infrastructure convergence.
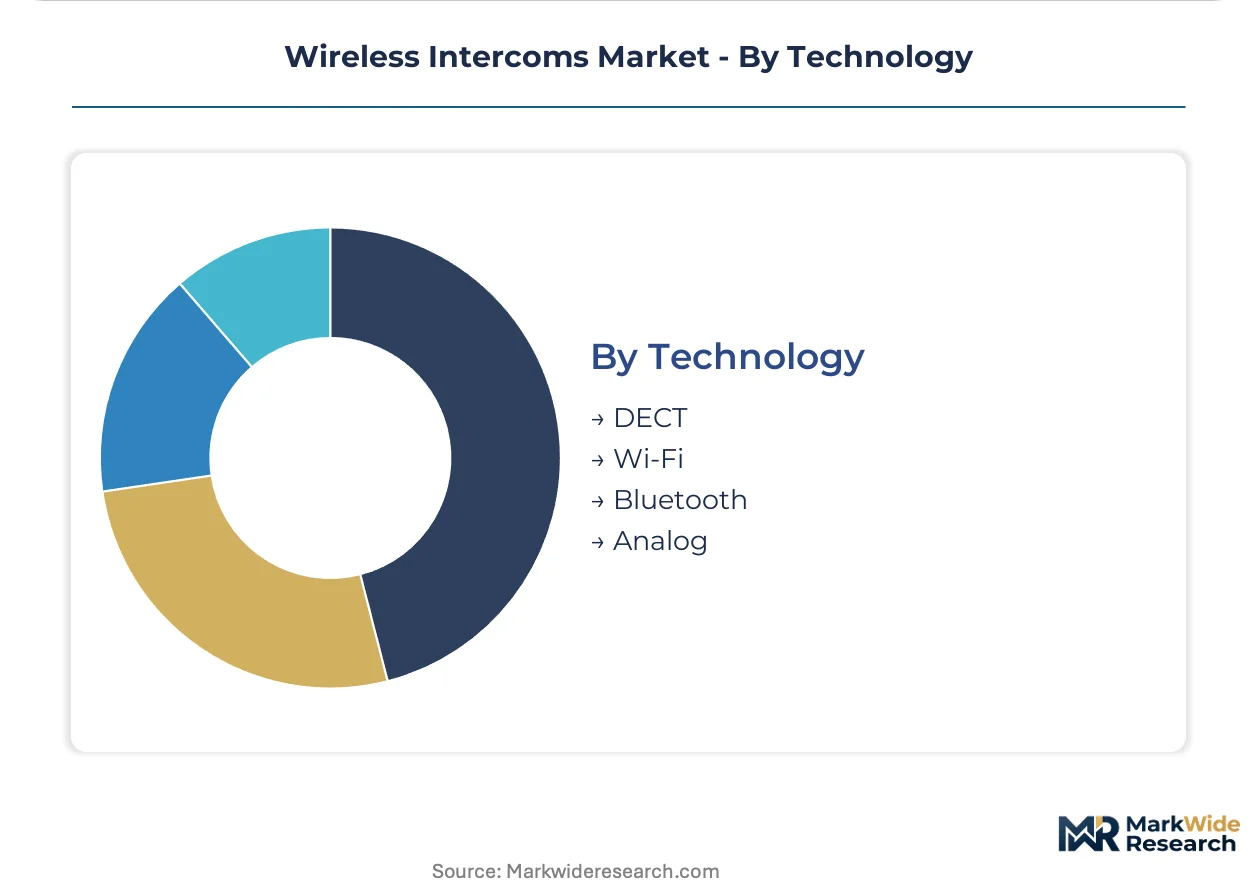
Technology:
Protocol selection locks buyers into specific chipset ecosystems, spectral licensing regimes, and interoperability certifications.
- DECT:1.9 GHz dedicated spectrum allocation eliminates Wi-Fi interference in dense deployments. German hospital procurement offices prioritize ETSI EN 301 406 pre-certified DECT platforms to accelerate installation timelines and ensure spectral compliance.
- Wi-Fi:2.4 GHz and 5 GHz operation leverages existing enterprise network infrastructure. US educational institutions adopt these systems to bypass dedicated gateway procurement and align with IT department standardization policies.
- Bluetooth:Short-range pairing for smartphone-integrated entry systems.
- Analog:Legacy FM or AM modulation in budget-conscious replacement scenarios.
Wi-Fi leads on scale; DECT gains share fastest on regulatory clarity and interference immunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital procurement offices are accelerating DECT platform adoption as industrial safety mandates reshape replacement cycles across manufacturing and healthcare infrastructure.
United States
Healthcare facilities in Texas and California are replacing wired nurse call systems with wireless platforms to improve staff mobility. FCC Part 15 rules governing unlicensed device emissions eliminate licensing friction for hospital infrastructure upgrades. The Greater Boston medical cluster is standardizing on Wi-Fi-based systems to leverage existing network investments.
Germany
Factory modernization programs in North Rhine-Westphalia require real-time worker coordination systems in heavy manufacturing plants. ETSI EN 301 406 spectral efficiency standards shape DECT equipment certification requirements for European market access. Bavarian hospital networks are prioritizing pre-certified platforms to compress installation timelines and ensure regulatory compliance.
Japan
Dense urban residential developments in Tokyo and Osaka favor DECT-based video intercoms for their coexistence with congested 2.4 GHz spectrum. METI industrial standards influence procurement criteria for building automation integration. The Kansai manufacturing belt is deploying hardened wireless coordination systems for plant safety perimeters.
United Kingdom
Theater control rooms in London specify multi-channel architectures with sub-30 millisecond latency for live production coordination. CE marking under the EU Radio Equipment Directive mandates electromagnetic compatibility testing for professional equipment distribution. Manchester broadcast facilities are upgrading to mesh-networked systems for resilience in event production.
China
Educational institutions in Beijing and Shanghai are repurposing existing campus Wi-Fi infrastructure for intercom deployments to reduce capital expenditure. MIIT spectrum allocation rules for unlicensed devices enable broad market access for consumer and commercial equipment. The Yangtze River Delta manufacturing corridor is adopting industrial-grade wireless coordination for logistics automation.
Wireless Intercoms Market Competitive Landscape
Capacity expansion dominates the current landscape as vendors scale silicon RF component production to capture collapsing unit economics. The market structures around three tiers: diversified electronics conglomerates with captive semiconductor fabrication, specialized professional audio vendors with low-latency protocol expertise, and regional security equipment manufacturers serving price-sensitive residential segments. Strategic archetypes include spectrum-certified platform specialists, cloud-hosted fleet management providers, and legacy wired system migrators. M&A activity and technology licensing agreements represent the primary competitive vectors as vendors secure chipset supply and interoperability certifications.
Within the professional-grade mesh networking tier, Motorola Solutions Inc. and Clear-Com, LLC exemplify divergent specialization strategies. Panasonic Corporation anchors the diversified electronics archetype with semiconductor fabrication scale. These three entities occupy positions that span public safety, broadcast production, and consumer-to-commercial product tiering respectively.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Motorola Solutions Inc. |
| Clear-Com, LLC |
| Aiphone Co., Ltd. |
| Zenitel NV |
| Riedel Communications GmbH & Co. KG |
| Commend International GmbH |
| Samsung Electronics Co., Ltd. |
| Honeywell International Inc. |
| Others |
Value Network & Pricing Analysis
RF engineering talent scarcity in Taiwan and South Korea widens labor-cost differentials between premium-tier DECT certification specialists and economy-tier analog assemblers, compressing mid-market margins while tiering pricing spreads by technical complexity.
Pricing Analysis
Input-cost pass-through from silicon RF component substitution collapses production economics at the economy tier while premium multi-channel systems maintain pricing power through ETSI EN 301 406 certification bundling. Three-tier pricing structure across certified professional, standard enterprise, and uncertified residential levels separates buyers by interoperability requirements and installation support depth. Pricing pressure stems from gallium arsenide-to-silicon transceiver displacement enabling volume manufacturers to undercut legacy hardware. Residential entry systems exhibit highest price sensitivity; live event production venues show lowest.
Supply Chain Analysis
Workforce availability constraints in Malaysian contract manufacturing and Vietnamese assembly operations limit scaling velocity for mid-tier vendors competing on cost. Advanced RF semiconductor fabrication concentrates in Taiwan, South Korea, and mainland China, drawing from gallium arsenide wafer supplies and silicon foundry capacity. Raw material dependencies span rare earth substrates, lithium-ion cells for portable units, and copper antenna elements. Single-source vulnerability in DECT chipset supply creates procurement risk for European-focused vendors. Distribution runs through authorized dealer networks for professional systems and mass retail channels for residential products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon RF component cost compression creates margin-expansion headroom for vendors capturing premium-tier certification positioning, while subscription service models shift revenue toward predictable recurring structures.
For Market Incumbents: Acquire DECT protocol certification assets and ETSI pre-validation capabilities to defend against Wi-Fi convergence threats in healthcare procurement. Consolidate mesh networking IP through selective licensing agreements. Expand captive silicon foundry partnerships to secure component supply against East Asian concentration risk. For New Entrants and Emerging Players: FCC Part 15 in the United States opens a window for unlicensed device specialists to bypass legacy licensing barriers in hospital infrastructure replacement cycles. Target educational Wi-Fi convergence segments where existing network infrastructure eliminates gateway capital requirements. Pursue cloud-hosted fleet management positioning to capture operational expenditure preference in multi-site healthcare networks. For Investors and Strategic Acquirers: Valuations sit cheapest among regional security equipment manufacturers lacking ETSI certification pathways but holding distribution density in price-sensitive residential tiers. Long-term viability favors vendors with backward integration into silicon RF component sourcing or forward integration into subscription service platforms. Watch FCC spectrum reallocation proceedings and emerging cybersecurity certification mandates as inflection indicators for competitive viability re-rating.| Strategic Initiative | Industry Significance |
|---|---|
| ETSI EN 301 406 Certification Investment | Pre-certified DECT platforms accelerate German hospital procurement timelines and ensure European market access. |
| Silicon RF Component Backward Integration | In-house semiconductor fabrication collapses unit economics and insulates against Taiwan foundry concentration risk. |
| Cloud-Hosted Fleet Management Launch | Subscription models align with US healthcare system preference for operational expenditure over capital ownership. |
| Mesh Networking Protocol Acquisition | Self-healing node architectures eliminate single-point-of-failure vulnerabilities in public safety deployments. |
| Educational Wi-Fi Convergence Partnership | Leveraging existing campus infrastructure bypasses dedicated gateway costs in K-12 and university procurement. |
Research Methodology
Multiple input streams — primary interviews with RF hardware engineering directors, hospital procurement managers, and live event production technical directors; secondary validation through FCC equipment authorization databases, ETSI harmonized standards publications, and semiconductor trade flow data; plus bottom-up vendor shipment analysis cross-referenced against top-down healthcare IT expenditure estimates — were reconciled to construct market sizing and segmentation.
Historical growth trajectories were cross-referenced against expert panel assessments of replacement cycle timing and regulatory compliance cost evolution across the projection horizon. Segmentation modeling incorporated product architecture, installation type, end-use environment, and technology protocol dimensions. CAGR derivation rested on installed base depreciation rates, hospital modernization program budgets, and industrial safety mandate implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FCC spectrum reallocation decisions and CE marking cybersecurity expansion. Projections reflect assumptions regarding DECT-Wi-Fi technology substitution velocity and German industrial safety enforcement intensity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Industrial Wireless Broken Signal Solutions Market
Wireless Technologies
Global Gi Fi Technology Market
Wireless Technologies
Global Bluetooth Audio Codec Market
Wireless Technologies
Wi-Fi Hotspot (Dongle) Market
Wireless Technologies
Wireless Connectivity Market
Wireless Technologies
Asia-Pacific Distributed Antenna System Market
Wireless Technologies
Near Field Communication Market
Wireless Technologies
Global Wireless Data Communication Market
Wireless Technologies
5G Spectrum Market
Wireless Technologies
5G Fixed Wireless Access Market
Wireless Technologies
Wireless LAN Controller Market
Wireless Technologies
Global Wireless Testing Market
Wireless Technologies
Voice Over Wifi Market
Wireless Technologies
Wi-Fi Booster Market
Wireless Technologies
Wireless Smart Home Market
Wireless Technologies
Wireless Phone Chargers Market