
 Global Wind Turbine Condition Monitoring System Market | 2026-2036
Global Wind Turbine Condition Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wind Turbine Condition Monitoring System Market Outlook
European sensor manufacturers are expanding production capacity for offshore-rated vibration monitoring hardware. AB SKF leverages its bearing diagnostics heritage to dominate European aftermarket service contracts. Siemens AG sustains integrated hardware-software bundles tied to its turbine OEM installed base. General Electric Co. competes through digital twin platforms that anchor long-term service agreements with utility customers.
A wind turbine condition monitoring system integrates accelerometers, oil particle counters, thermal cameras, and acoustic sensors with edge-computing gateways to detect blade icing, gearbox wear, and generator misalignment before catastrophic failure. The hardware segment leads absolute revenue as retrofit sensor kits ship to aging onshore fleets in Germany and Spain. Vibration monitoring occupies the largest technology share due to mature ISO 10816 standards and proven fault-frequency libraries. Predictive maintenance applications are expanding fastest among independent power producers seeking to reduce unplanned outage penalties.
FDA standards for medical-grade sensor calibration do not apply here; instead IEC 61400-25 governs turbine communication protocols while ISO 13374 establishes condition monitoring data processing frameworks. The EU Green Deal and F-Gas Regulation indirectly tighten reliability mandates by penalizing refrigerant leaks and downtime that triggers fossil backup generation. Stakeholders must weigh backward integration into sensor manufacturing against platform partnerships as hardware commoditization pressures margin pools.
Market Dynamics
Offshore wind farm operators are accelerating predictive maintenance adoption as blade diameters exceed 220 meters and gearbox accessibility becomes prohibitively expensive. This structural shift compresses sensor deployment timelines and elevates edge-computing requirements across turbine fleets.
Growth Catalysts
- EU F-Gas Regulation:Penalties for refrigerant leaks and downtime-triggered fossil backup generation tighten reliability mandates across member states, forcing operators to install continuous thermal monitoring.
- Offshore expansion:Floating platform installations in the North Sea and Baltic Sea demand subsea-rated vibration sensors with corrosion-resistant housings and redundant data transmission.
- Aging onshore retrofit demand:Turbines commissioned during the 2005-2010 European and Chinese installation waves require sensor kit upgrades to extend operational life beyond original design specifications.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet generators in direct-drive turbines depend on Chinese neodymium processing, exposing sensor calibration equipment to input cost volatility and export restriction risk.
- Technical interoperability gaps:Proprietary SCADA protocols from Vestas, Siemens, and GE block seamless third-party condition monitoring integration, fragmenting data architectures.
- Certification timeline friction:IEC 61400-25 compliance testing for new sensor hardware extends market entry by 14-18 months, freezing startup innovation capital.
Strategic Opportunities
- India's offshore readiness gap:The country's 30 GW offshore wind target by 2030 lacks indigenous monitoring infrastructure, creating first-mover advantage for sensor-software bundled entrants.
- Drone-coupled thermography convergence:Autonomous aerial platforms with FLIR payloads enable blade leading-edge inspection without rope-access teams, collapsing per-turbine survey costs.
- US Inflation Reduction Act production credits:Domestic content bonuses for nacelle assembly incentivize co-located sensor manufacturing in Texas and Colorado manufacturing clusters.
Industry Challenges
- Embedded systems firmware expertise scarcity:Edge-computing gateway development requires rare combinations of signal processing and wind-specific failure-mode knowledge, constraining vendor scaling.
- Legacy turbine SCADA integration complexity:Pre-2010 turbines with proprietary Modbus implementations demand custom protocol adapters, inflating deployment engineering hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wind Turbine Condition Monitoring System Market |
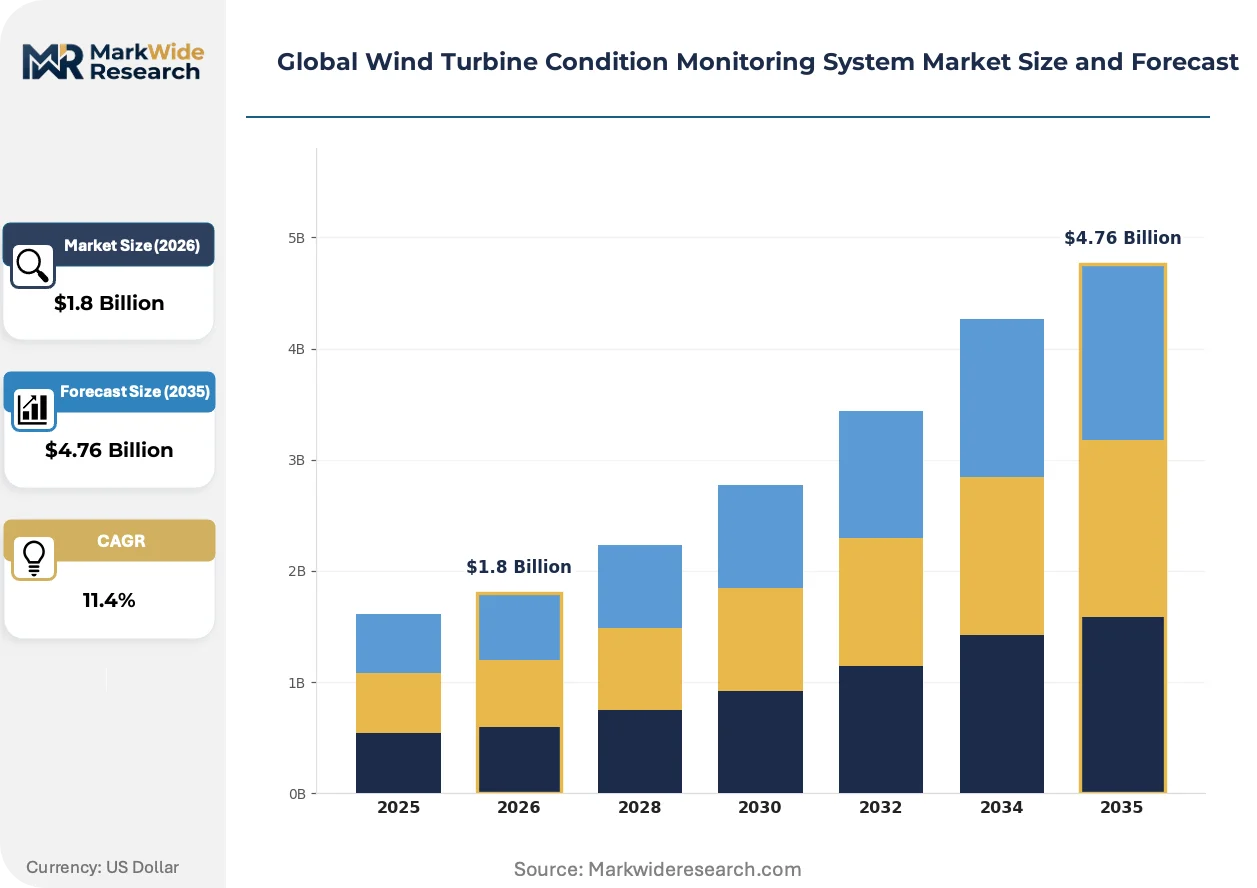
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Hardware, Software, Service, Platform End User: Utilities, Independent Power Producers, OEMs, Asset Managers Technology: Vibration Monitoring, Oil Analysis, Thermal Imaging, Acoustic Monitoring Application: Fault Detection, Predictive Maintenance, Performance Optimization, Asset Management |
| Companies Covered | Emerson Electric Co., Advantech Co. Ltd., AB SKF, ONYX Insight, Fluke Corp., General Electric Co., Baker Hughes Co., Bruel & Kjr Vibro, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wind Turbine Condition Monitoring System Market Strategic Shifts
Digital twin architectures are absorbing condition monitoring data streams to simulate component degradation trajectories, compressing the gap between sensor deployment and actionable maintenance scheduling.
Edge-computing gateways with onboard FFT analysis are consolidating vibration signal processing that previously required cloud transmission. Independent power producers in Germany and Spain deploy these units to reduce latency in gearbox fault detection from minutes to milliseconds. This consolidation is eliminating tier-1 cloud dependency for time-critical alerts.
The EU AI Act's risk classification framework is mandating algorithmic transparency for automated turbine shutdown decisions. Condition monitoring platforms must now document feature importance and decision thresholds for grid-connected assets. Offshore operators in Danish and German waters are responding by embedding explainable AI modules alongside neural network classifiers.
Service contract unbundling is fragmenting long-term turbine maintenance agreements. Utility procurement teams in the United States now separately tender sensor hardware, analytics software, and field engineering, compressing vendor margins and elevating pure-play software valuations. This pattern is most visible among Texas and Oklahoma wind farm operators managing merchant power exposure.
Global Wind Turbine Condition Monitoring System Market Segmentation
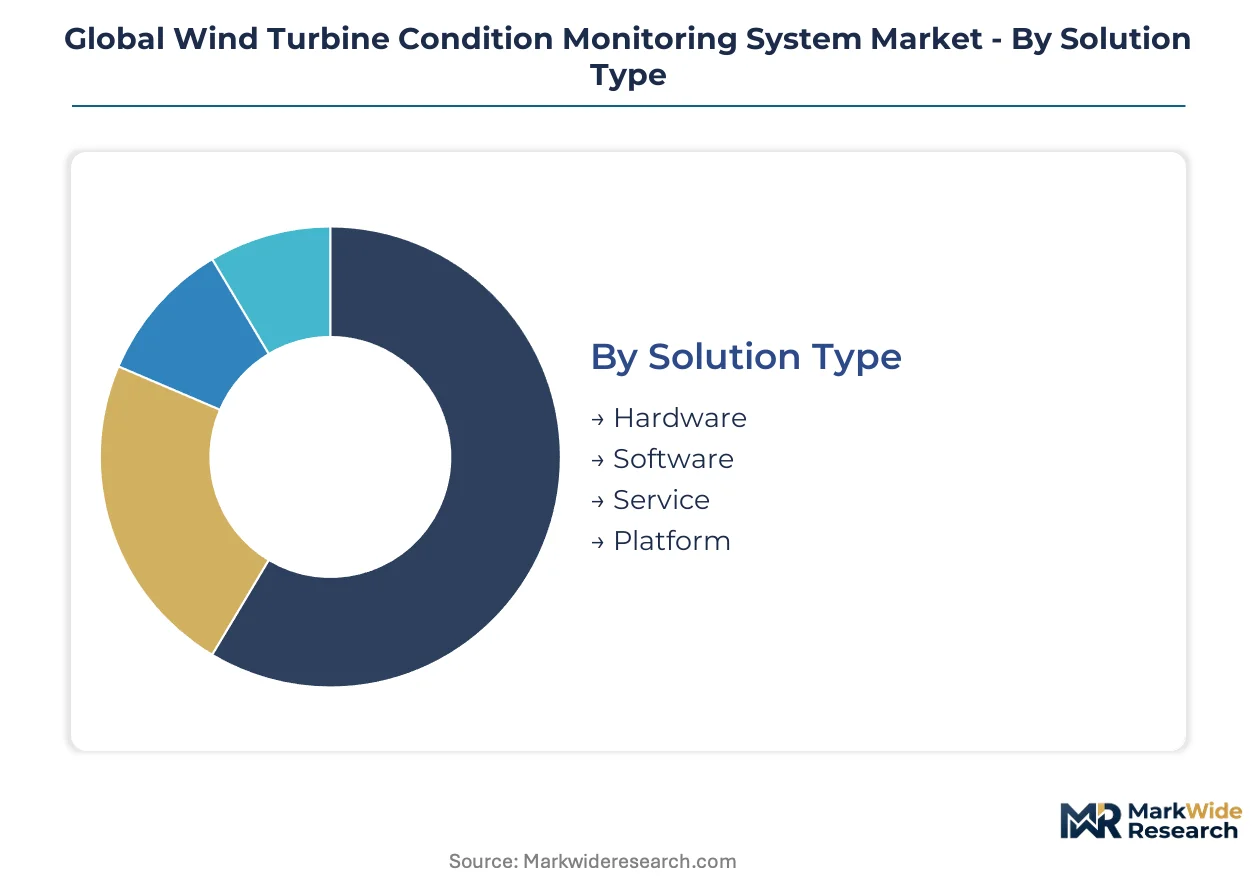
Condition monitoring architectures vary sharply in integration depth, from standalone sensor kits retrofitted to aging fleets to deeply embedded systems within turbine OEM control networks. These structural differences dictate procurement patterns, margin profiles, and vendor competitive positioning across the value chain.
Solution Type:
Hardware components function as standalone retrofit units or embedded subsystems depending on turbine vintage and SCADA architecture compatibility.
- Hardware:Accelerometers, oil particle counters, thermal cameras, and edge-computing gateways ship predominantly as retrofit kits to German and Spanish onshore fleets commissioned during the 2005-2010 installation wave. Demand concentrates among independent power producers seeking to extend operational life beyond original design specifications without full control system replacement.
- Software:Predictive analytics platforms process vibration spectra, thermal signatures, and acoustic emissions through cloud-based or edge-deployed algorithms. Deployment in Danish and German offshore waters is accelerating as the EU AI Act mandates explainable AI documentation for automated turbine shutdown decisions.
- Service:Field engineering contracts cover sensor calibration, firmware updates, and failure verification. Contracts cluster around Texas and Oklahoma merchant wind farms where utility procurement teams unbundle maintenance agreements.
- Platform:Integrated hardware-software bundles with long-term service commitments anchor OEM-installed base retention strategies. Siemens AG leverages this structure across its European turbine fleet.
Volume placements concentrate in Hardware; the faster expansion belongs to Platform.
End User:
Procurement sophistication and integration requirements vary by end-user category, shaping vendor sales motion and contract structure.
- Utilities:Vertically integrated grid operators in Germany and the United States mandate IEC 61400-25 compliance and centralized SCADA integration. Procurement teams separately tender sensor hardware, analytics software, and field engineering.
- Independent Power Producers:Merchant power operators in Texas and Oklahoma prioritize edge-computing latency reduction and unplanned outage penalty avoidance. These operators deploy FFT-capable gateways to compress gearbox fault detection from minutes to milliseconds.
- OEMs:Turbine manufacturers embed condition monitoring as standard equipment on offshore platforms with blade diameters exceeding 220 meters. AB SKF dominates European aftermarket service contracts through bearing diagnostics heritage.
- Asset Managers:Third-party portfolio operators aggregate monitoring data across multi-vendor fleets. Demand is climbing fastest among renewable infrastructure funds acquiring aging European onshore assets.
Contract values peak with Utilities; the steepest expansion trajectory is Asset Managers.
Technology:
Technology selection follows failure-mode criticality and accessibility constraints, with offshore applications demanding corrosion-resistant and redundant configurations.
- Vibration Monitoring:Piezoelectric accelerometers measuring shaft rotation, gear mesh frequencies, and bearing defect harmonics anchor the installed base. Mature ISO 10816 standards and proven fault-frequency libraries drive standardization across German and Chinese fleets.
- Oil Analysis:Particle counters and spectrometers detect gearbox wear debris and lubricant degradation. North Sea floating platforms deploy subsea-rated sampling systems with redundant data transmission.
- Thermal Imaging:Infrared cameras identify refrigerant leaks, electrical hot spots, and blade icing. EU F-Gas Regulation penalties for downtime-triggered fossil backup generation tighten reliability mandates across member states.
- Acoustic Monitoring:Ultrasonic sensors detect blade leading-edge erosion and nacelle structural anomalies. Drone-coupled thermography convergence is collapsing per-turbine survey costs for blade inspection.
Revenue share concentrates in Vibration Monitoring; the fastest technology climb is Acoustic Monitoring.
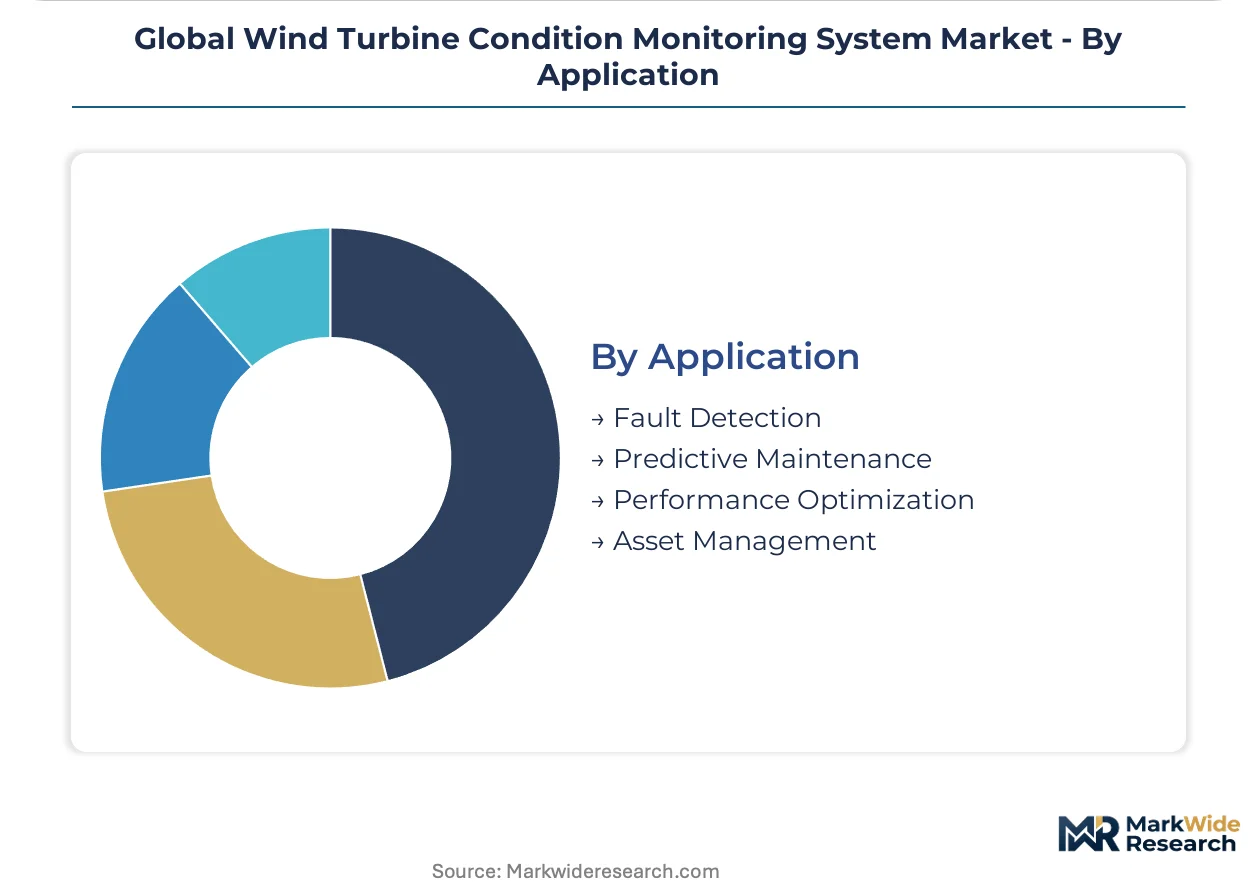
Application:
Application maturity correlates with data infrastructure investment and organizational analytics capability.
- Fault Detection:Rule-based threshold alerting for catastrophic failure prevention. Pre-2010 turbines with proprietary Modbus implementations demand custom protocol adapters, inflating deployment engineering hours.
- Predictive Maintenance:Machine learning models forecast component degradation trajectories. Offshore wind farm operators accelerate adoption as gearbox accessibility becomes prohibitively expensive.
- Performance Optimization:Real-time pitch and yaw adjustment based on aerodynamic sensor feedback. Digital twin architectures absorb condition monitoring data streams to simulate degradation trajectories.
- Asset Management:Portfolio-level risk quantification and residual life valuation for financial reporting. CSRD disclosure requirements in Europe elevate monitoring data to audit-grade asset records.
Deployment breadth concentrates in Fault Detection; the fastest application expansion is Predictive Maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth magnet processing concentration in China anchors supply chain exposure for calibration equipment manufacturers serving turbine operators worldwide.
Germany
Offshore expansion in the North Sea and Baltic Sea drives subsea-rated sensor demand. The EU F-Gas Regulation tightens reliability mandates through refrigerant leak penalties. Hamburg and Bremerhaven host corrosion-resistant hardware manufacturing clusters supplying floating platform installations.
China
Neodymium processing dominance exposes sensor calibration equipment to export restriction risk. Dual carbon goals accelerate direct-drive turbine deployment with permanent magnet generators. Shandong Peninsula manufacturing bases supply vibration monitoring hardware to domestic retrofit fleets.
United States
Aging onshore fleets in Texas and Oklahoma require sensor kit upgrades to extend operational life. The Inflation Reduction Act production credits incentivize co-located sensor manufacturing in Colorado and Texas clusters. Merchant power operators prioritize edge-computing latency reduction for gearbox fault detection.
India
The 30 GW offshore wind target by 2030 lacks indigenous monitoring infrastructure. Central Electricity Authority guidelines push reliability standards for grid-connected assets. Gujarat and Tamil Nadu coastal zones attract first-mover sensor-software bundled entrants.
Denmark
Floating platform installations in Danish waters demand redundant data transmission systems. The EU AI Act mandates explainable AI documentation for automated turbine shutdown decisions. Copenhagen-area technology clusters develop algorithmic transparency modules for neural network classifiers.
Global Wind Turbine Condition Monitoring System Market Competitive Environment
Global majors compete with regional champions across hardware manufacturing and predictive analytics software. The market structure shows moderate concentration with tiered specialization across vibration monitoring, thermal imaging, and integrated platform bundles. Three archetypes dominate: bearing diagnostics heritage firms, turbine OEM-anchored integrators, and pure-play digital twin platform vendors. Capacity expansion and strategic partnerships represent the dominant competitive moves as vendors seek to capture unbundled service contract fragments.
Among European heritage specialists, AB SKF exemplifies the bearing diagnostics archetype through aftermarket service contract dominance. Siemens AG occupies the integrated hardware-software tier with turbine OEM-installed base retention strategies. General Electric Co. anchors the digital twin platform segment through long-term utility service agreements. These three companies represent distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Advantech Co. Ltd. |
| AB SKF |
| ONYX Insight |
| Fluke Corp. |
| General Electric Co. |
| Baker Hughes Co. |
| Bruel & Kjr Vibro |
| Siemens AG |
| Others |
Value Chain & Pricing Dynamics
Firmware engineering talent scarcity in Denmark and Germany widens pricing spreads between premium integrated platforms and economy retrofit kits. Labor cost differentials between Copenhagen-area edge-computing specialists and Spanish field installation teams compress margins on unbundled service contracts while elevating bundled platform valuations.
Pricing Analysis
Warranty and long-term service bundling separates OEM-anchored platform pricing from pure hardware transactional sales. Three-tier pricing structure across premium, standard, and economy levels reflects IEC 61400-25 certification grade and edge-computing latency performance. Price erosion runs through economy sensor kits as Chinese manufacturers expand vibration accelerometer capacity. Independent power producers in Texas and Oklahoma exhibit highest price sensitivity, while German utilities prioritize compliance-grade systems with minimal cost elasticity.
Supply Chain Analysis
US Inflation Reduction Act domestic content bonuses and India's phased manufacturing program are reshaping component sourcing decisions for nacelle-integrated sensors. Supply concentrates in China for neodymium magnet processing, Germany for precision accelerometer manufacturing, and Denmark for edge-computing gateway assembly. Rare earth magnet supply rests on Chinese export licensing. Single-source vulnerability in permanent magnet generators exposes calibration equipment to input disruption. Distribution runs through turbine OEM captive channels and independent aftermarket distributors serving retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as IEC 61400-25 certification timelines and firmware expertise scarcity force subscale sensor vendors toward strategic exits.
For Market Incumbents: Hedge against pure-play software encroachment by deepening bearing diagnostics data moats and securing exclusive edge-computing partnerships with North Sea offshore operators. Capacity addition in Hamburg-Bremerhaven manufacturing clusters anchors floating platform supply security. Certification investment in EU AI Act explainable AI modules defends against algorithmic transparency mandates. For New Entrants and Emerging Players: Independent power producers in Texas and Oklahoma present the most penetrable buyer segment given their unbundled procurement patterns and merchant power exposure. India's 30 GW offshore wind target offers white-space entry for sensor-software bundled offerings before indigenous infrastructure matures. Drone-coupled thermography service partnerships provide low-capital go-to-market positioning. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play digital twin platform vendors given EU AI Act compliance requirements and utility demand for algorithmic transparency. Long-term viability favors analytics specialists with embedded turbine OEM relationships rather than hardware-commoditized sensor manufacturers. Watch for IEC 61400-25 certification backlog clearance as inflection signal for vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Gateway Capacity Expansion | Danish manufacturers reduce latency for North Sea gearbox fault detection. |
| Backward Integration into Accelerometer Production | SKF and Siemens secure supply continuity against rare earth volatility. |
| EU AI Act Compliance Certification | Explainable AI modules become mandatory for automated turbine shutdowns. |
| Drone-Coupled Thermography Service Launch | FLIR payload integration collapses blade inspection costs for Texas operators. |
| India Offshore Wind Joint Venture | Gujarat and Tamil Nadu coastal zones attract bundled sensor-software entrants. |
Study Parameters
Multi-period observation of sensor deployment timelines, firmware update frequencies, and service contract renewal rates anchored the trend analysis, supplemented by interviews with wind farm operations directors, turbine OEM procurement managers, edge-computing firmware engineers, and aftermarket service heads. Secondary validation drew from IEC 61400-25 certification databases, FERC interconnection queue filings, EU ETS emissions trading records, and EIA power plant operations data. Bottom-up unit economics triangulated against top-down market sizing across hardware, software, service, and platform segments.
Input-output matrices mapped vibration monitoring, thermal imaging, oil analysis, and acoustic sensor volumes against end-user procurement patterns through the projection horizon. Segmentation dimensions modeled included solution type integration depth, end-user sophistication tier, technology failure-mode criticality, and application maturity level. CAGRs were derived from fitted growth curves incorporating offshore installation wave timing, retrofit fleet age profiles, and regulatory compliance deadline clustering.
Caveats apply where rare earth export restrictions, IEC certification timeline extensions, or AI Act enforcement variability could materially shift the outlook. Forecasts reflect assumptions about floating platform deployment rates and merchant power market stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Italy Big Data Analytics in Energy Market
Energy Analytics and Software
Power Monitoring and Control Software Market
Energy Analytics and Software
Industrial Energy Monitoring Market
Energy Analytics and Software
Digital Energy Platform Market
Energy Analytics and Software
Energy Intelligence Solutions Market
Energy Analytics and Software
Automated Power Generation Dispatch Software Market
Energy Analytics and Software
Big Data in Oil and Gas Market
Energy Analytics and Software
Global Geophysical Services and Equipment Market
Energy Analytics and Software
Building Energy Simulation Software Market
Energy Analytics and Software
GCC Well Testing Services Market
Energy Analytics and Software
Smart Grid Data Analytics Market
Energy Analytics and Software
Asia-Pacific Big Data Analytics in Energy Market
Energy Analytics and Software
Europe Big Data Analytics in Energy Market
Energy Analytics and Software
Oil and Gas Data Management Software Market
Energy Analytics and Software
Predictive Maintenance in the Energy Market
Energy Analytics and Software
Australia Big Data Analytics in Energy Market