
 Australia Big Data Analytics in Energy Market | 2026-2036
Australia Big Data Analytics in Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Big Data Analytics in Energy Market Insights
ISO 50001 energy management certification is rotating as a baseline qualification for vendors serving Australian energy utilities. Microsoft Corporation leverages its Azure cloud infrastructure to anchor analytics deployments across AEMO-connected grids. SAP SE sustains deep ERP integration capabilities that differentiate its offerings for multi-site generation portfolios. Siemens Aktiengesellschaft dominates hardware-software convergence in substation digitalization projects across eastern Australia.
Big data analytics in energy encompasses the collection, processing, and algorithmic analysis of high-velocity operational datasets from generation, transmission, and distribution systems to optimize asset performance and market dispatch decisions. Platforms typically ingest SCADA telemetry, smart meter intervals, and weather forecasts at sub-second latency to enable automated control responses. Cloud Analytics leads deployment preference among Australian utilities seeking elastic compute for seasonal demand spikes. Predictive Analytics within the Technology dimension captures the fastest expansion as generators face escalating penalties under reliability obligations. Demand Response applications now attract disproportionate vendor investment following regulatory reforms that monetize flexible load participation.
The Australian Energy Regulator enforces data reporting standards under National Electricity Rules that mandate granular visibility into network constraints and generator bidding behavior. Energy Safe Victoria and equivalent state bodies impose cybersecurity frameworks aligned with the Australian Energy Sector Cyber Security Framework that filter vendor eligibility. The Clean Energy Regulator's carbon accounting requirements shape analytics feature roadmaps for renewable certificate tracking. Stakeholders must monitor how the proposed National Energy Transformation Partnership reshapes interoperability standards before committing to platform architectures.
Market Dynamics
AEMO's 2024 reliability reforms and the Australian Energy Regulator's tightened bidding transparency rules are compressing deployment timelines for real-time analytics platforms across National Electricity Market participants.
Growth Catalysts
- Australian Energy Sector Cyber Security Framework:Mandatory compliance requirements under this framework are filtering vendor eligibility and accelerating procurement of certified analytics platforms by New South Wales and Victoria utilities.
- Smart meter interval data:The proliferation of sub-15-minute consumption telemetry is enabling granular demand response optimization that generators now monetize under reformed market rules.
- Queensland renewable zones:Concentrated solar and wind buildouts in this state are driving demand for predictive generation forecasting to manage intermittency penalties.
Market Restraints
- Cloud compute cost volatility:Elastic pricing for seasonal demand spike processing is compressing utility IT budget predictability and delaying multi-year platform commitments.
- SCADA system vendor concentration:Legacy substation hardware from a narrow supplier base in eastern Australia creates integration friction for software-native analytics vendors.
- Data residency requirements:State-level sovereignty mandates under the Australian Energy Regulator's governance standards restrict cross-border cloud deployment architectures.
Strategic Opportunities
- South Australia grid-forming inverter analytics:Underpenetrated need for synthetic inertia monitoring in this high-renewable penetration state offers first-mover positioning for specialized platform vendors.
- ISO 50001 certification mandates:Emerging procurement preferences by multi-site generation portfolios are creating tiered vendor qualification pathways.
- Edge-to-cloud convergence:Integration of substation edge computing with centralized Azure deployments is enabling sub-second latency use cases previously uneconomical.
Industry Challenges
- Data engineering talent scarcity:Utilities in Victoria and New South Wales face recruitment gaps for SCADA-fluent analytics architects capable of bridging operational technology and cloud infrastructure.
- Multi-vendor integration complexity:Siemens hardware-software stacks require specialized middleware development to connect with third-party predictive maintenance platforms, extending deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Big Data Analytics in Energy Market |
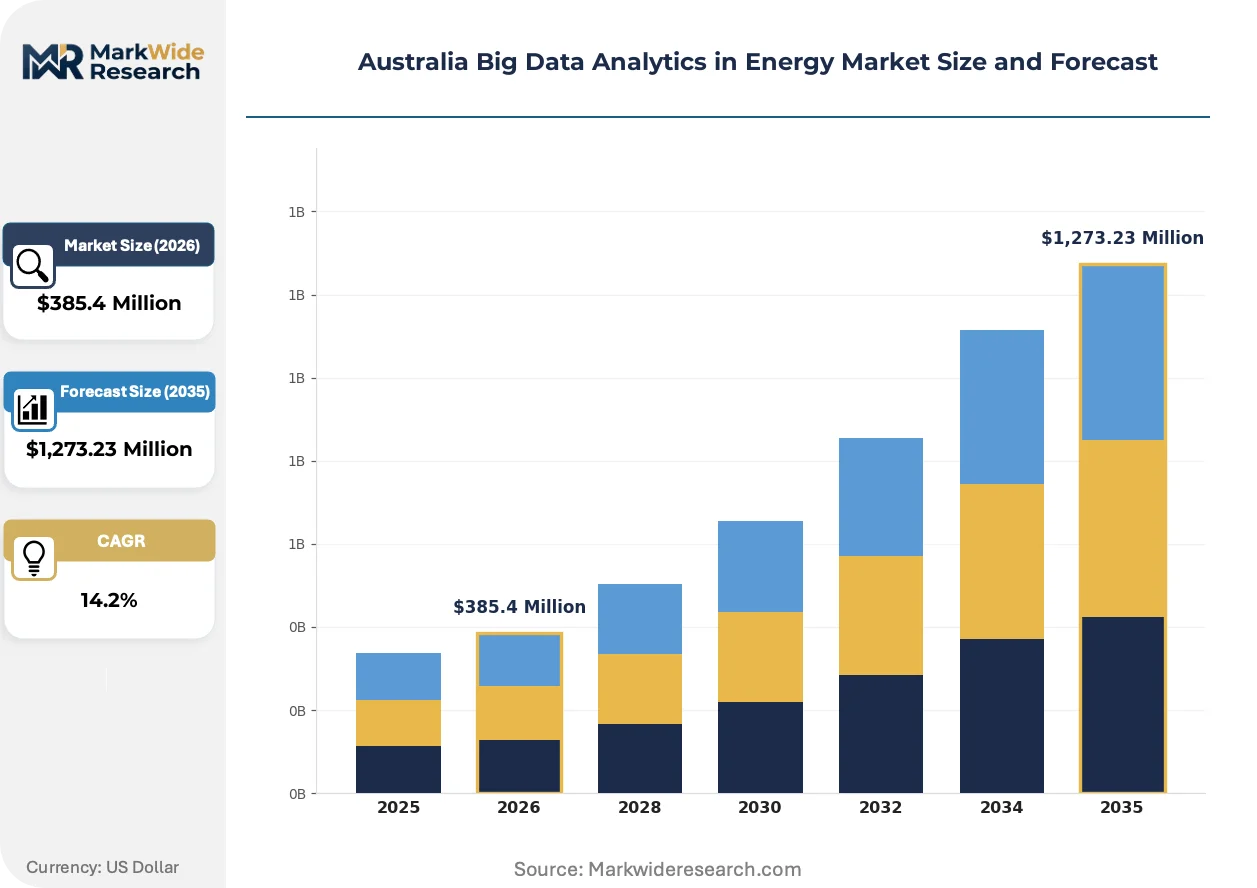
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,273.23 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud Analytics, On-Premises Solutions, Hybrid Models, Edge Analytics Technology: Machine Learning, Predictive Analytics, Data Warehousing, Visualization Tools End User: Utilities, Renewable Energy Providers, Oil & Gas Companies, Industrial Manufacturers Application: Load Forecasting, Asset Management, Demand Response, Operational Efficiency |
| Companies Covered | International Business Machines Corporation, SAP SE, Microsoft Corporation, Siemens Aktiengesellschaft, Accenture plc, Dell Technologies Inc., CSIRO, Australian Energy Market Operator, Oracle Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Big Data Analytics in Energy Market Trends and Innovations
Real-time digital twin architectures are displacing static asset models as the foundational layer for grid investment decisions, with Australian utilities prioritizing vendors demonstrating live synchronization with physical infrastructure.
Digital twin platforms that fuse SCADA telemetry with meteorological forecasting layers are supplanting spreadsheet-based asset degradation models. AEMO-connected distribution network operators in Victoria and New South Wales are deploying these systems at 18-month replacement cycles. The shift is compressing competitive differentiation around physics-informed machine learning rather than generic cloud infrastructure.
The Australian Energy Regulator's 2024 amendments to National Electricity Rules Chapter 10 are mandating granular generator bidding data disclosure at 5-minute intervals. Industrial consequence includes forced retirement of manual bid optimization workflows across coal and gas fleet operators. Baseload generators in Queensland and New South Wales are responding by licensing automated dispatch algorithms that embed constraint forecasting directly into bidding engines.
Subscription-based analytics procurement is replacing perpetual license models among mid-sized renewable developers lacking capital for upfront platform investment. Software vendors are unbundling implementation services from core compute licensing to capture this segment. Tasmania's emerging pumped hydro projects and Western Australia's remote microgrids represent the most visible adoption frontiers for this commercial restructuring.
Australia Big Data Analytics in Energy Market Segmentation
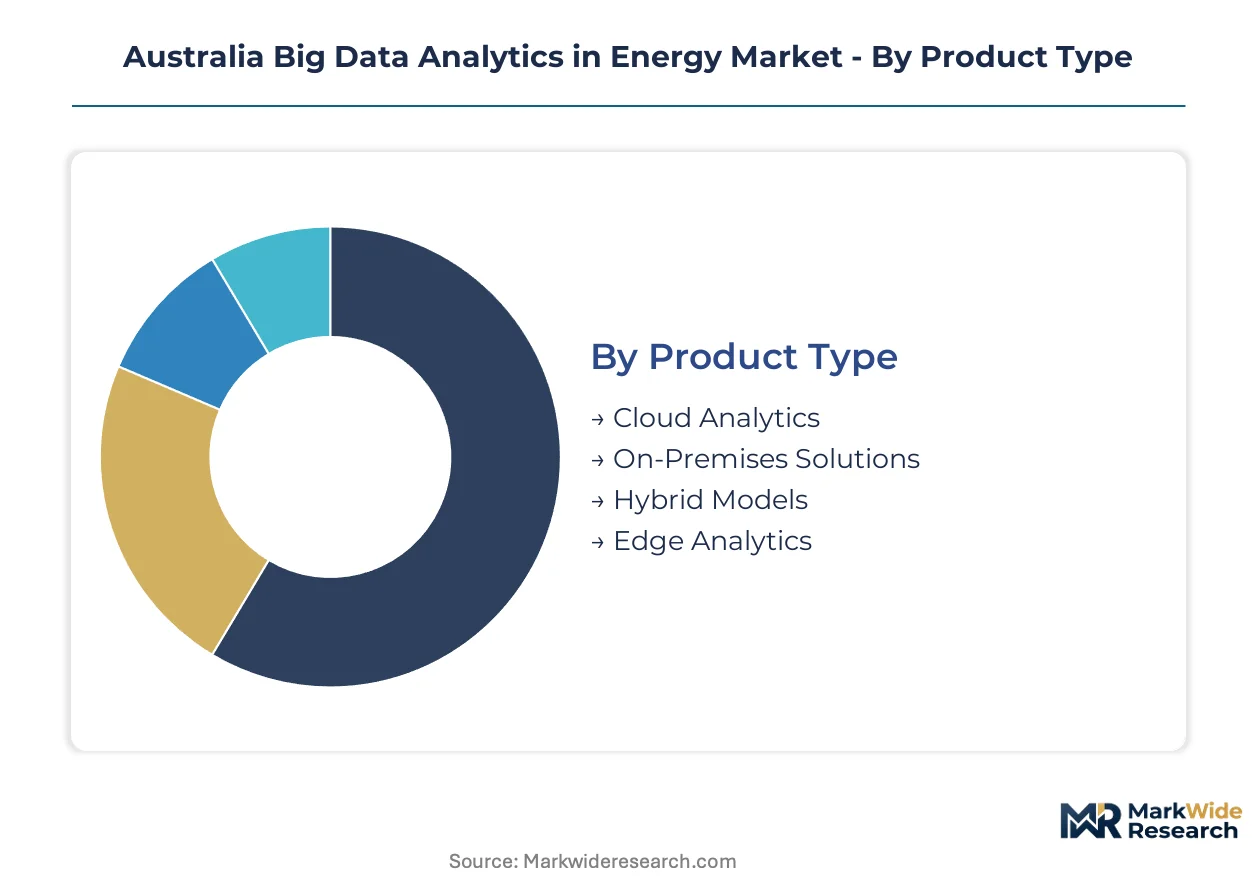
Segmentation reveals how procurement patterns diverge across Australian energy market participants. Utilities prioritize deployment architectures that align with AEMO reliability obligations, while renewable developers optimize for intermittency forecasting capabilities.
Product Type:
Domestic demand concentrates in cloud-native architectures serving National Electricity Market participants, while hybrid models attract export-oriented vendors seeking Australian reference deployments.
- Cloud Analytics:Elastic compute infrastructure processes SCADA telemetry and smart meter intervals at sub-second latency. New South Wales and Victoria utilities deploy these platforms to manage seasonal demand spikes without capital-intensive server procurement. Cloud Analytics holds the largest share; momentum sits with Edge Analytics.
- Edge Analytics:Substation-deployed processing units enable real-time control responses independent of wide-area network reliability. Queensland renewable zones and South Australia's high-penetration solar networks drive concentrated procurement for synthetic inertia monitoring.
- Hybrid Models:Split architectures retain sensitive operational data on-premises while pushing non-critical workloads to Azure or AWS infrastructure.
- On-Premises Solutions:Air-gapped deployments persist in critical generation facilities governed by Australian Energy Sector Cyber Security Framework tier-one mandates.
Cloud Analytics holds the largest share; momentum sits with Edge Analytics.
Technology:
Cost tiering separates enterprise-grade predictive platforms from visualization tools targeting mid-sized renewable developers with constrained IT budgets.
- Predictive Analytics:Algorithmic forecasting of asset degradation and network constraints embeds directly into automated bidding engines. Baseload generators in Queensland and New South Wales license these capabilities to comply with AEMO's 5-minute disclosure mandates.
- Machine Learning:Physics-informed neural networks fuse meteorological data with SCADA telemetry for generation forecasting. The technology climbs fastest as solar and wind buildouts accelerate intermittency penalty exposure.
- Data Warehousing:Centralized repositories aggregate decades of operational history for long-term investment planning.
- Visualization Tools:Dashboard platforms translate complex grid telemetry into operator-facing interfaces for control room decision support.
Predictive Analytics dominates utility procurement; Machine Learning expands most quickly.
End User:
Application maturity varies sharply—utilities operate decade-old SCADA integrations while renewable entrants deploy greenfield cloud architectures.
- Utilities:Transmission and distribution network operators across the National Electricity Market deploy comprehensive analytics stacks spanning generation forecasting to demand response optimization. Australian Energy Regulator reliability standards mandate granular visibility into network constraints.
- Renewable Energy Providers:Solar and wind developers prioritize predictive generation forecasting to manage AEMO intermittency penalties. Queensland's concentrated renewable zones and Western Australia's remote microgrids represent visible adoption frontiers.
- Oil & Gas Companies:Upstream and midstream operators apply predictive maintenance to pipeline compression and LNG facility assets.
- Industrial Manufacturers:Energy-intensive facilities deploy demand response analytics to monetize flexible load participation under reformed market rules.
Utilities command the largest deployment base; Renewable Energy Providers gain share fastest.
Application:
Supply concentration aligns with regulatory pressure points—AEMO reforms directly shape where vendors concentrate feature development.
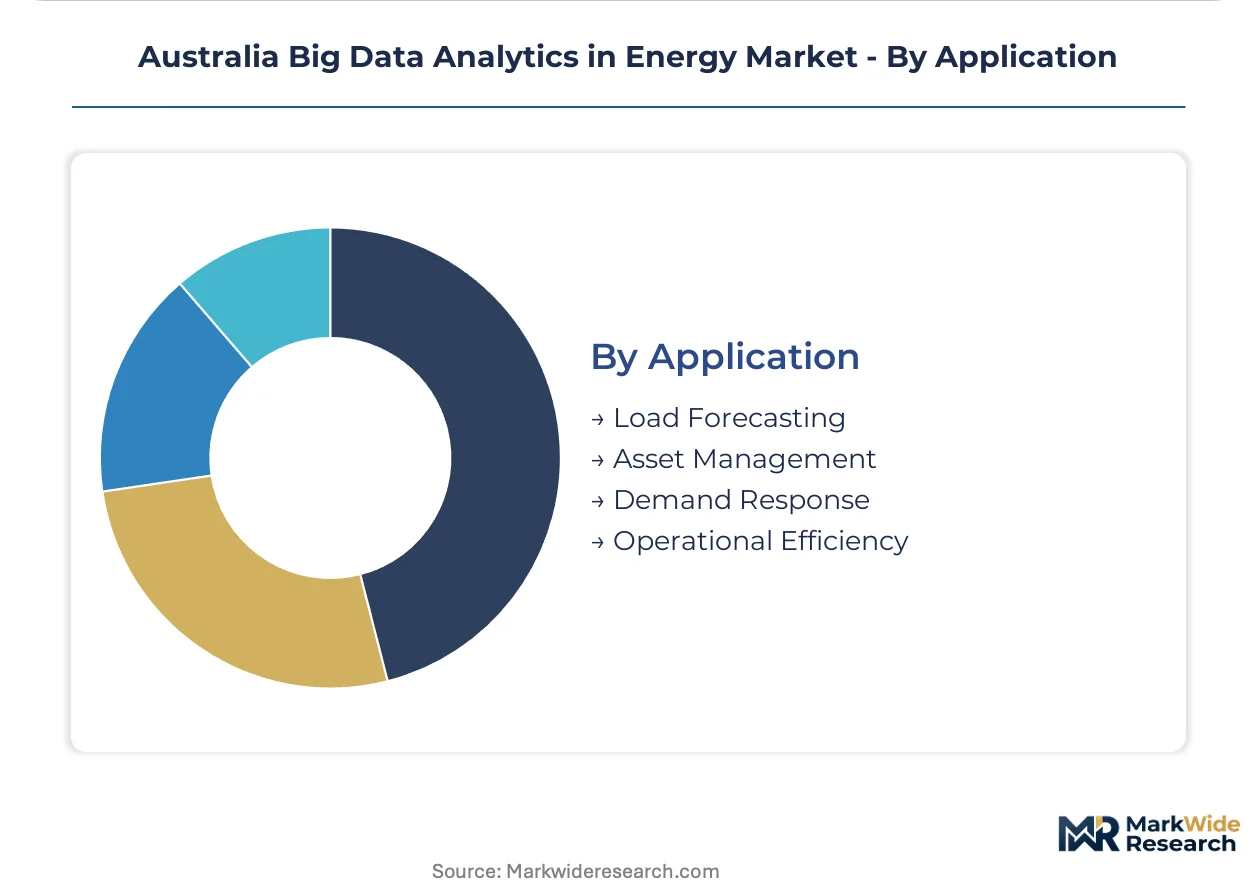
- Demand Response:Automated load curtailment platforms enable industrial and commercial facilities to bid flexibility into wholesale markets. The application attracts disproportionate vendor investment following regulatory reforms that monetize flexible load participation.
- Asset Management:Digital twin architectures fuse live SCADA synchronization with physics-informed degradation models. Victorian and New South Wales distribution network operators replace static spreadsheet models at 18-month cycles.
- Load Forecasting:Granular consumption prediction underpins generation dispatch and network investment decisions.
- Operational Efficiency:Real-time analytics optimize unit commitment and maintenance scheduling across multi-site generation portfolios.
Asset Management retains the largest installed base; Demand Response exhibits steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes concentrate in state-level utilities and renewable developers across Australia's eastern seaboard, with procurement patterns diverging between National Electricity Market participants and remote microgrid operators.
New South Wales
Grid modernization investments and predictive maintenance deployments drive demand across Ausgrid and Endeavour Energy networks. The Australian Energy Regulator's reliability standards mandate granular network constraint visibility. Sydney and the Hunter Valley host concentrated utility procurement for cloud-native analytics platforms.
Victoria
Smart meter interval data proliferation enables demand response optimization for commercial and industrial load aggregators. Energy Safe Victoria enforces cybersecurity frameworks aligned with the Australian Energy Sector Cyber Security Framework. Melbourne anchors the state's distribution network operator analytics deployments.
Queensland
Concentrated solar and wind buildouts in renewable zones create predictive generation forecasting demand to manage AEMO intermittency penalties. The state's renewable energy zones program shapes vendor feature roadmaps. Brisbane and regional hubs like Townsville drive procurement for synthetic inertia monitoring.
South Australia
High renewable penetration rates create underpenetrated need for grid-forming inverter analytics and synthetic inertia monitoring. The state's distributed energy resources roadmap accelerates edge computing deployments. Adelaide-based network operators prioritize sub-second latency use cases for voltage stability management.
Western Australia
Remote microgrids and isolated grid systems attract subscription-based analytics procurement from capital-constrained renewable developers. The state's wholesale electricity market reforms enable flexible load participation monetization. Pilbara mining operations and southwestern agricultural processors represent emerging demand frontiers.
Australia Big Data Analytics in Energy Market Competitive Landscape
Player mix skews toward diversified technology conglomerates with cloud infrastructure assets, creating a tiered structure where hardware-software convergence capabilities separate premium vendors from point-solution providers. Strategic archetypes include hyperscale cloud platforms, industrial automation specialists, and systems integration consultancies. Competitive moves concentrate on strategic partnerships for substation digitalization and portfolio diversification into edge-to-cloud architectures.
Within the cloud platform tier, Microsoft Corporation exemplifies hyperscale infrastructure anchoring, while SAP SE represents ERP-integrated analytics positioning. Siemens Aktiengesellschaft occupies the hardware-software convergence archetype for substation deployments. These three companies illustrate how vendor qualification pathways increasingly filter through ISO 50001 certification mandates and Australian Energy Sector Cyber Security Framework compliance requirements.
| Leading Market Players |
|---|
| International Business Machines Corporation |
| SAP SE |
| Microsoft Corporation |
| Siemens Aktiengesellschaft |
| Accenture plc |
| Dell Technologies Inc. |
| CSIRO |
| Australian Energy Market Operator |
| Oracle Corporation |
| Others |
Pricing and Supply Chain Analysis
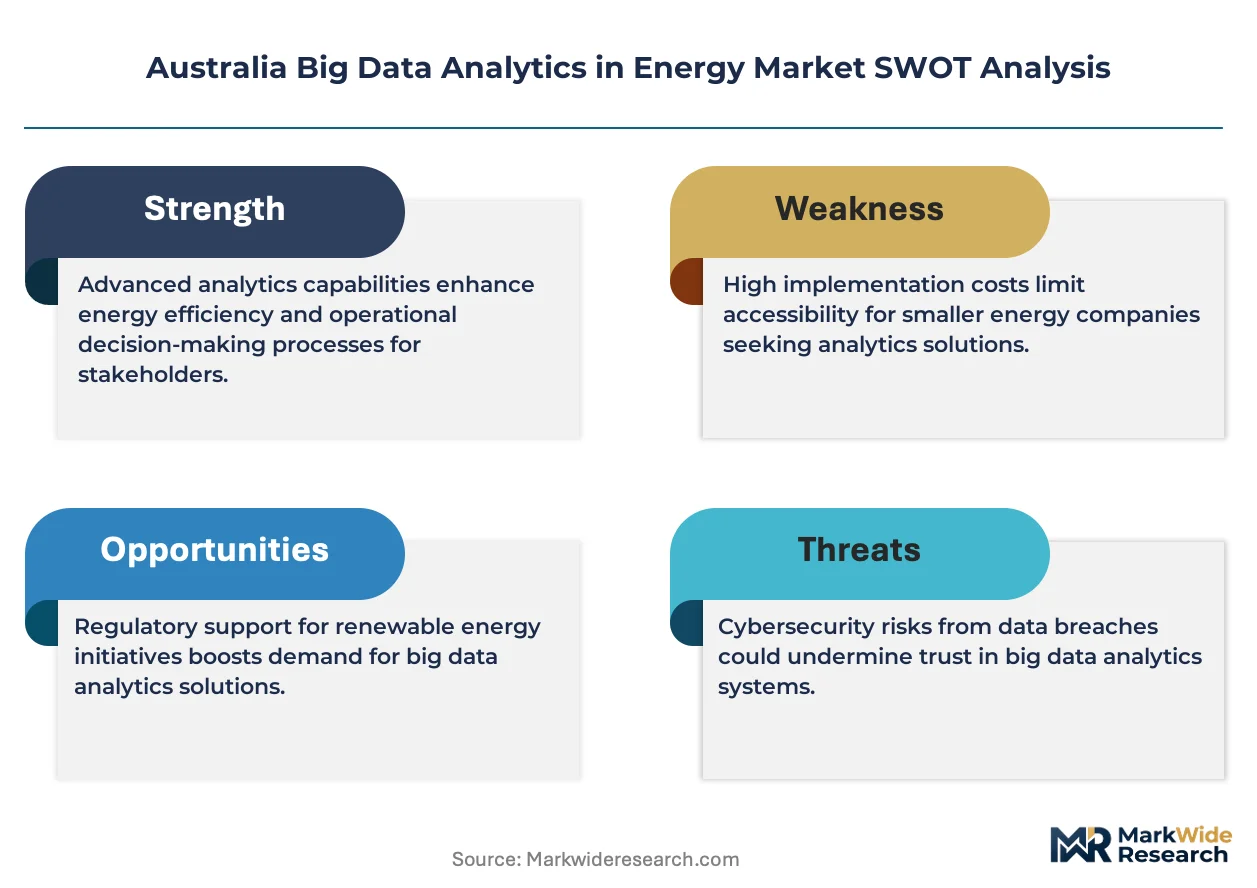
ISO 50001 energy management certification gates both vendor qualification pathways and price differentiation simultaneously, creating tiered procurement barriers where uncertified platforms face 30-40% discount pressure against accredited alternatives. Utilities in New South Wales and Victoria now mandate this baseline credential, compressing margins for point-solution providers while rewarding integrated platform vendors with pricing power anchored to compliance value.
Pricing Analysis
Cost-plus contracts with CPI indexation dominate multi-year analytics deployments across AEMO-connected utilities, insulating vendors from cloud compute volatility while transferring infrastructure risk to buyers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 50001-certified platforms with embedded cybersecurity compliance from unbundled visualization tools. Price differentiation rests on certification tier and edge-to-cloud integration depth. Cost compression in the economy tier is intensifying because subscription-based procurement from capital-constrained renewable developers forces vendors to unbundle implementation services. Mid-sized renewable developers in Western Australia and Tasmania exhibit highest price sensitivity; baseload generators in Queensland and New South Wales show lowest.
Supply Chain Analysis
Inventory cycles for substation edge hardware extend 12-16 weeks, creating procurement bottlenecks that cascade into deployment timeline penalties for software-native vendors lacking Siemens-integrated stacks. Supply concentrates in Germany, the United States, and China for industrial-grade servers and networking equipment feeding Australian grid modernization. Component dependencies include NVIDIA GPU accelerators for machine learning inference, Intel Xeon processors for SCADA data ingestion, and specialized fiber-optic transceivers for substation connectivity. Single-source vulnerability runs through NVIDIA's data center GPU allocation queues, which prioritize hyperscale cloud providers over regional utility deployments. Distribution runs through systems integration consultancies with AEMO project credentials, bypassing direct vendor relationships for all but the largest generation portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's big data analytics in energy market sits in early-cycle expansion, with AEMO's reliability reforms and 5-minute bidding disclosure mandates accelerating first-time platform adoption among coal and gas fleet operators previously reliant on manual workflows.
For Market Incumbents: Compound defensive positioning through ISO 50001 certification maintenance and deeper Azure integration partnerships that raise switching costs for utility customers. Siemens Aktiengesellschaft's hardware-software convergence in eastern Australian substations creates integration friction threats for pure-play analytics vendors; incumbents should prioritize middleware development capacity to bridge legacy SCADA with cloud-native platforms. Vertical integration into edge computing hardware represents the critical lever for margin defense against hyperscale cloud entrants. For New Entrants and Emerging Players: ISO 50001 certification fast-track through accredited third-party auditors unlocks procurement eligibility with New South Wales and Victoria utilities within 6-9 months. South Australia's grid-forming inverter analytics segment offers the most penetrable white-space, with underdeveloped synthetic inertia monitoring capabilities and no entrenched vendor relationships. Western Australia's remote microgrids provide a second beachhead through subscription-based commercial models targeting capital-constrained renewable developers. Go-to-market execution should anchor to AEMO-connected distribution network operator references in Victoria or New South Wales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across edge analytics sub-segments as standardized hardware commoditizes substation-deployed processing units. Long-term viability over the next decade favors vendors with physics-informed machine learning capabilities fused to live SCADA synchronization, not generic cloud infrastructure plays. Acquisition target archetype: specialized platform vendors with Queensland renewable zone deployments and proven synthetic inertia monitoring algorithms. The signal to watch is AEMO's intermittency penalty enforcement intensity, which directly correlates with predictive forecasting platform pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 50001 Certification Investment | Unlocks procurement eligibility with New South Wales and Victoria utilities under tightened qualification pathways. |
| Edge-to-Cloud Architecture Convergence | Enables sub-second latency use cases for South Australian voltage stability management previously uneconomical. |
| Physics-Informed Machine Learning Development | Differentiates forecasting platforms from generic cloud infrastructure as digital twin adoption accelerates. |
| Subscription-Based Commercial Restructuring | Captures Western Australian and Tasmanian renewable developers lacking capital for upfront platform investment. |
| Middleware Integration Partnership | Bridges Siemens hardware-software stacks with third-party predictive maintenance platforms to compress deployment cycles. |
Research Methodology
Cross-validation between utility planning officer interviews and AEMO regulatory filing analysis anchors the qualitative findings on procurement timeline compression. Primary fieldwork engaged distribution network operators in Victoria and New South Wales, renewable energy developers in Queensland's renewable zones, and EPC contractors specializing in substation digitalization. Secondary validation drew from Australian Energy Regulator enforcement notices, AEMO market reports, Clean Energy Regulator certificate tracking disclosures, and utility annual reports. Bottom-up deployment sizing triangulates against top-down market value estimates across cloud, edge, hybrid, and on-premises architecture segments.
Sensitivity analysis on cloud compute cost volatility and SCADA integration friction informs the forecast framework across the analysis window. Segmentation dimensions include product architecture, technology tier, end-user category, and application use case, with regulatory compliance intensity as an energy-specific overlay. CAGRs derive from deployment velocity modeling against AEMO reliability obligation timelines and renewable buildout schedules in Queensland and Western Australia. Key inputs include smart meter penetration curves, substation digitalization investment pipelines, and ISO 50001 certification adoption rates among vendor ecosystems.
Decision-makers should treat outputs as directional under assumptions of continued AEMO reform implementation and stable cloud infrastructure pricing; material deviation in either would warrant model refresh. Forecasts reflect base-case assumptions on regulatory enforcement intensity and technology adoption S-curves. Specific risks include Australian Energy Sector Cyber Security Framework tier escalation, data residency mandate expansion, and hyperscaler cloud pricing regime shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Oil and Gas Data Management Software Market
Energy Analytics and Software
Industrial Energy Monitoring Market
Energy Analytics and Software
Big Data Analytics in Power Sector Market
Energy Analytics and Software
Smart Grid Software Market
Energy Analytics and Software
Digital Energy Platform Market
Energy Analytics and Software
Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data in Oil and Gas Market
Energy Analytics and Software
China Big Data Analytics in Energy Market
Energy Analytics and Software
Energy As a Service (Eaas) Market
Energy Analytics and Software
India Big Data Analytics in Energy Market
Energy Analytics and Software
Energy and Utilities Analytics Market
Energy Analytics and Software
Power System Analysis Software Market
Energy Analytics and Software
Asia-Pacific Big Data Analytics in Energy Market
Energy Analytics and Software
Europe Big Data Analytics in Energy Market
Energy Analytics and Software
Germany Big Data Analytics in Energy Market
Energy Analytics and Software
Global Geophysical Services and Equipment Market