
 Big Data in Oil and Gas Market | 2026-2036
Big Data in Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Big Data in Oil and Gas Market Analysis
Platform licensing revenue is reshaping competitive economics in the sector, as vendors shift from perpetual software sales to recurring cloud subscriptions. Schlumberger Limited leverages its DELFI cognitive E&P environment to anchor deep relationships with national oil companies across the Middle East. Microsoft Corporation extends its Azure energy data platform through partnerships with supermajors seeking scalable compute for seismic processing. IBM differentiates via Watson-enabled predictive maintenance suites that compete directly with independent software vendors.
Big Data in Oil and Gas encompasses the capture, storage, processing, and analysis of petabyte-scale datasets generated across upstream exploration, midstream logistics, and downstream refining operations, typically requiring distributed computing architectures with latency thresholds below 50 milliseconds for real-time drilling decisions. Its primary purpose is to transform raw operational telemetry into actionable intelligence that reduces unplanned downtime and improves hydrocarbon recovery rates. Predictive Analytics commands the largest share of technology spending as operators prioritize failure forecasting for subsea equipment, while Cloud Computing represents the fastest-expanding deployment mode as majors migrate seismic libraries off aging on-premise server farms. Reservoir Management applications attract disproportionate R&D investment due to their direct linkage to reserve replacement metrics, whereas Asset Tracking remains comparatively mature with established vendor relationships.
The US EPA enforces methane monitoring mandates under the Inflation Reduction Act that compel operators to install continuous emissions detection systems with auditable data trails, while the EU CSRD requires granular sustainability disclosures that drive demand for carbon accounting software. ISO 27001 information security standards govern data governance protocols for cross-border seismic transfers, particularly affecting cloud deployment decisions. Stakeholders must weigh the trade-off between edge computing latency advantages and the capital efficiency of centralized cloud analytics as portfolio complexity intensifies.
Market Dynamics
Upstream operators face intensifying pressure to compress decision latency below 50 milliseconds for real-time drilling optimization, forcing architectural trade-offs between edge computing capital deployment and cloud analytics scalability.
Growth Catalysts
- EPA Methane Monitoring Mandates:US operators must install continuous emissions detection systems with auditable data trails, accelerating investment in sensor networks and analytics infrastructure across the Permian Basin.
- Reservoir Digital Twins:National oil companies deploy physics-based simulations integrated with live production telemetry to optimize recovery rates from mature fields.
- EU CSRD Disclosure Requirements:Granular sustainability reporting obligations drive demand for carbon accounting software that traces emissions across complex hydrocarbon value chains.
Market Restraints
- Specialized Talent Scarcity:Geoscientists with hybrid petroleum engineering and machine learning expertise command premium compensation, constraining analytics program scaling.
- Seismic Data Sovereignty Rules:Cross-border transfer restrictions on subsurface imaging data complicate cloud migration strategies for multinational operators.
- Legacy SCADA Integration Friction:Decades-old well pad control systems lack standardized APIs, forcing costly middleware development for unified analytics platforms.
Strategic Opportunities
- Carbon Capture Analytics:Emerging CO2 monitoring applications create white space for vendors offering reservoir sequestration verification and leakage detection algorithms.
- Brazil Pre-Salt Developments:Underpenetrated deepwater fields present first-mover advantages for predictive maintenance vendors targeting subsea equipment failure forecasting.
- Digital Thread Convergence:Integration of drilling telemetry, supply chain logistics, and refining yield data enables end-to-end margin optimization previously impossible with siloed systems.
Industry Challenges
- Data Lake Governance Complexity:Petabyte-scale seismic archives require metadata standardization across decades of proprietary formats before analytics deployment.
- Cybersecurity Certification Burden:ISO 27001 compliance timelines extend 18-24 months for offshore platforms, delaying cloud-connected sensor rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Big Data in Oil and Gas Market |
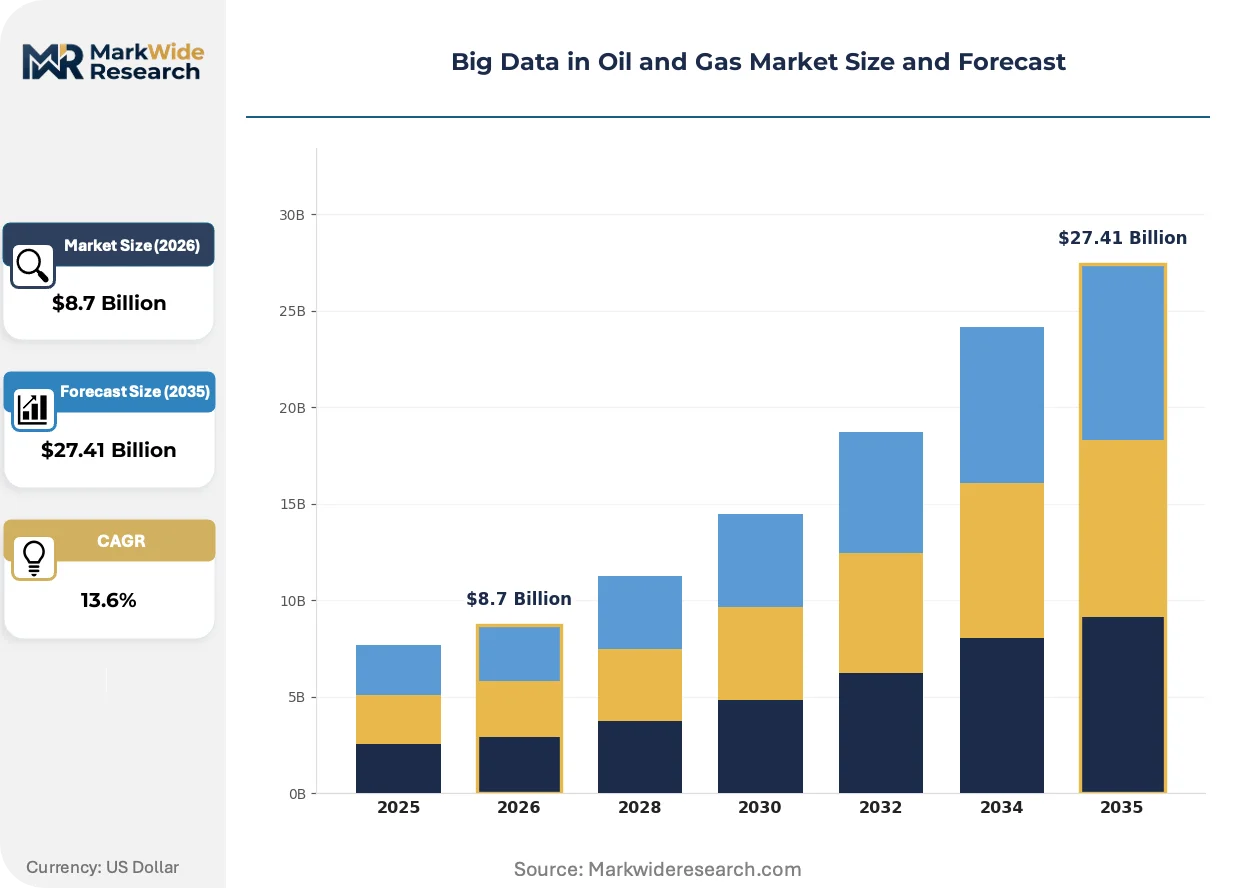
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Predictive Analytics, Data Visualization, Cloud Computing Application: Exploration, Production Optimization, Reservoir Management, Asset Tracking End User: Upstream Companies, Downstream Companies, Service Providers, Energy Consultants Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Schlumberger Limited, Halliburton Company, IBM, Amazon.com Inc, Accenture plc, Microsoft Corporation, Baker Hughes Company, Alphabet Inc, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Big Data in Oil and Gas Market Emerging Trajectories
Computational architectures are fragmenting across latency tiers as operators split workloads between well pad edge nodes and hyperscale cloud environments, creating new vendor positioning battles.
Edge computing infrastructure is hybridizing real-time drilling telemetry processing with intermittent cloud synchronization. Permian Basin producers deploy ruggedized servers at well pads to execute automated kick detection algorithms without satellite latency. This architecture compresses emergency response windows while reserving seismic imaging and reservoir simulation for centralized Azure and AWS clusters.
EU CSRD sustainability disclosure mandates force granular carbon accounting across Scope 1-3 emissions. Hydrocarbon majors reconfigure ERP systems to capture combustion data from every flare stack, compressor station, and marine vessel. Midstream logistics operators in the Netherlands and Germany face the steepest compliance curves due to dense pipeline networks requiring continuous monitoring.
Subscription pricing for analytics platforms displaces perpetual software licenses among independent exploration companies. Smaller Permian operators now access predictive maintenance algorithms through monthly SaaS arrangements rather than seven-figure capital commitments. This shift concentrates vendor relationships with cloud-native specialists and erodes traditional oilfield service incumbents' lock-in advantages.
Big Data in Oil and Gas Market Segmentation
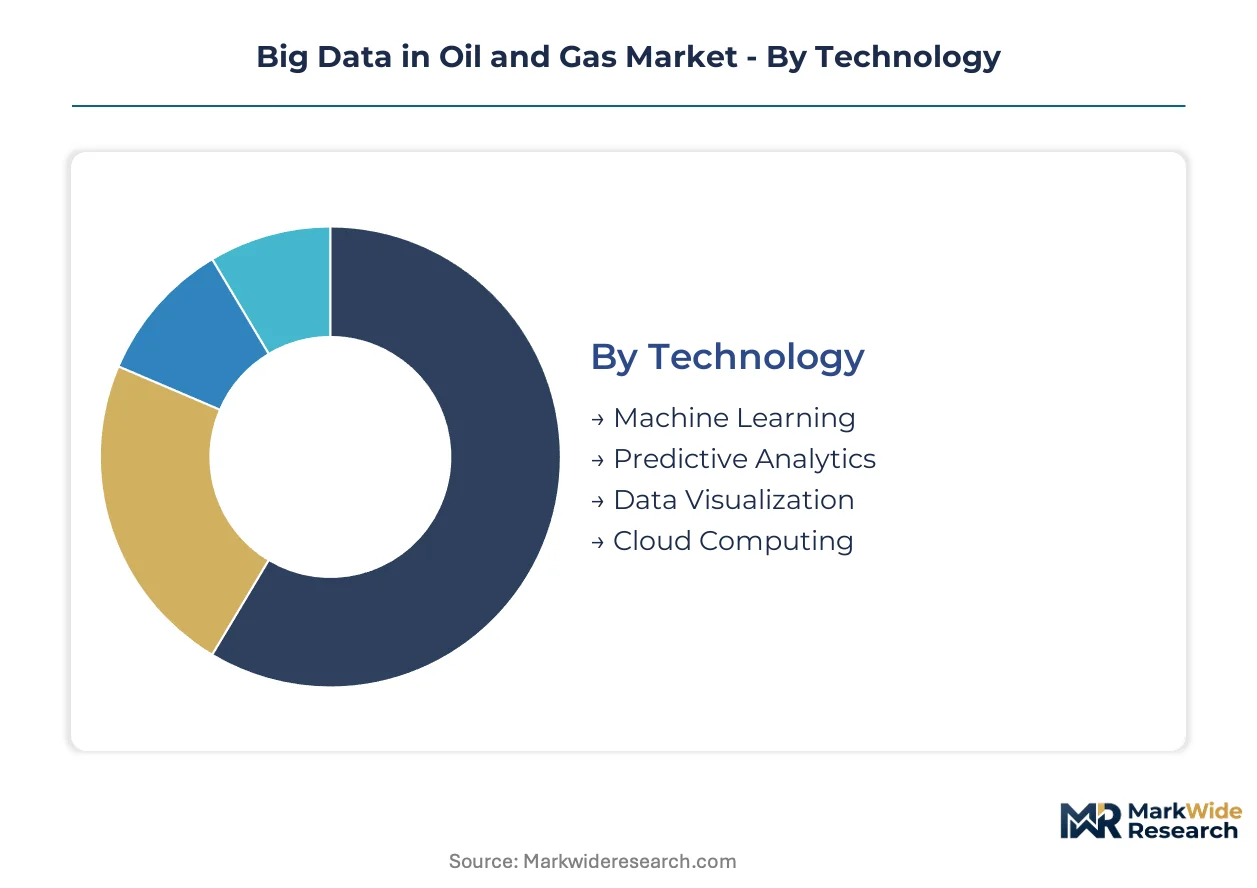
Technology choices in this market determine capital efficiency and decision velocity across hydrocarbon value chains. Deployment architecture directly shapes regulatory compliance capabilities and operational risk profiles.
Technology:
Cost tier positioning separates established analytics platforms from emerging AI-native entrants competing on subscription economics.
- Predictive Analytics:Failure forecasting algorithms process subsea equipment sensor streams to preempt blowout events and compressor degradation. Permian Basin operators prioritize these capabilities for artificial lift optimization in high-density drilling programs.
- Cloud Computing:Hyperscale infrastructure migrates petabyte seismic libraries from aging on-premise server farms, enabling elastic compute for reservoir simulation workloads. Supermajors in the Gulf of Mexico leverage Azure and AWS partnerships to compress processing timelines for 4D seismic interpretation.
- Machine Learning:Neural network architectures automate pattern recognition in drilling telemetry, reducing geosteering decision cycles.
- Data Visualization:Real-time dashboarding layers translate complex subsurface models into operational directives for field engineers.
Predictive Analytics holds installed capacity. Cloud Computing is rotating up the share rankings.
Application:
Application focus reveals where operators assign R&D priority based on reserve replacement economics and regulatory exposure.
- Reservoir Management:Physics-based digital twins integrate live production telemetry with geological models to optimize recovery factors from mature fields. National oil companies in the Middle East deploy these systems to extend plateau production from carbonate reservoirs.
- Production Optimization:Real-time drilling analytics compress decision latency below 50 milliseconds for automated kick detection and geosteering adjustments. Permian producers deploy edge nodes at well pads to execute these algorithms without satellite transmission delays.
- Exploration:Seismic processing pipelines identify stratigraphic traps and direct hydrocarbon indicators from broadband surveys.
- Asset Tracking:RFID and GPS-enabled logistics monitoring traces equipment utilization across dispersed well pad inventories.
Reservoir Management commands the deepest R&D commitments. Production Optimization is climbing the fastest as drilling intensity accelerates.
End User:
Customer type dictates procurement authority and contract structure, from capital-intensive platform licensing to contingent service fees.
- Upstream Companies:Integrated majors and independent E&Ps own the largest analytics budgets, deploying proprietary platforms across global portfolios. These operators prioritize reservoir simulation and predictive maintenance for subsea infrastructure.
- Service Providers:Schlumberger and Halliburton bundle analytics modules with drilling and completion contracts, embedding software into physical service delivery. Their scale advantages concentrate in deepwater basins where integrated project execution dominates.
- Downstream Companies:Refiners apply yield optimization algorithms to crude slate selection and process unit scheduling.
- Energy Consultants:Boutique advisory firms deliver carbon accounting and regulatory compliance analytics on project-specific engagements.
Upstream Companies anchor procurement volume. Service Providers are gaining share fastest through bundled service-software contracts.
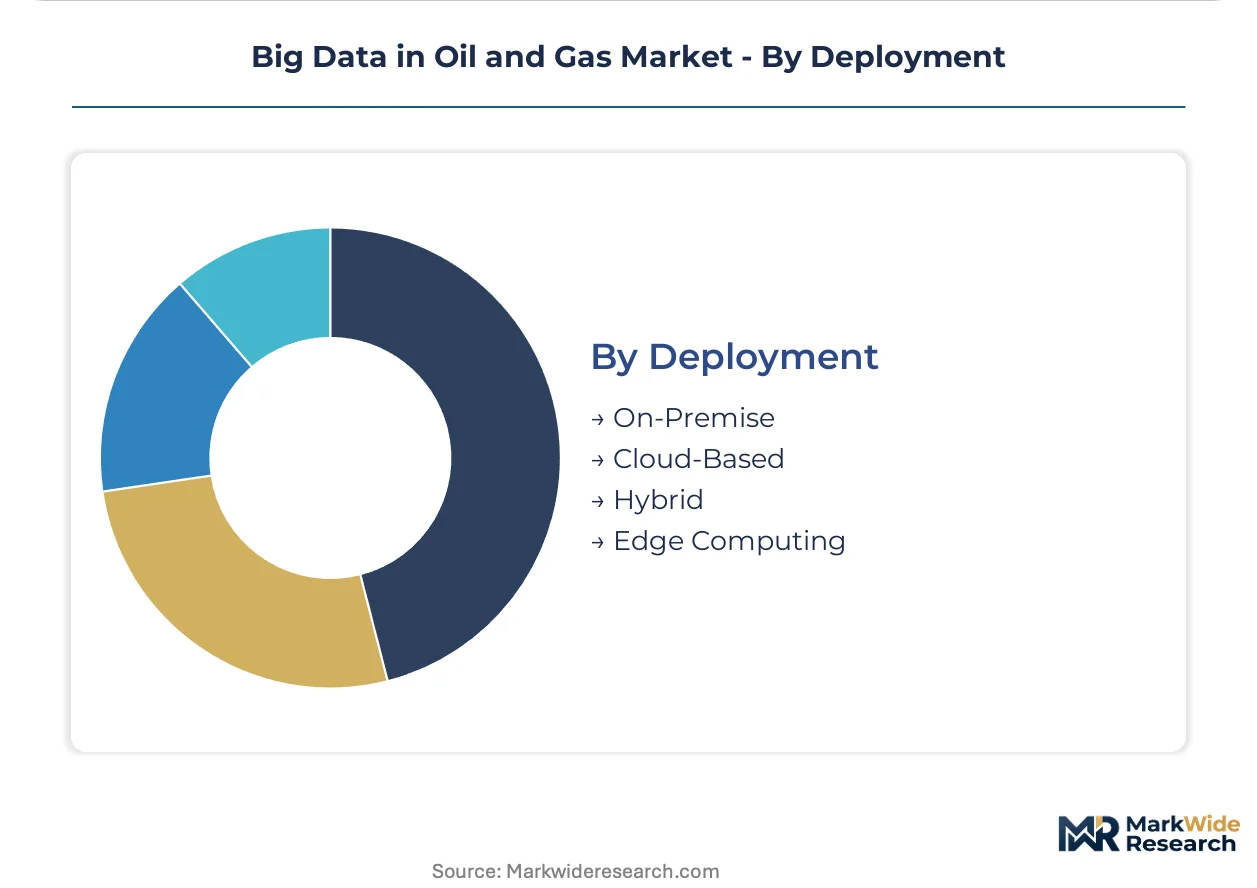
Deployment:
Volume distribution across deployment modes reflects the latency-scalability trade-off governing architectural decisions.
- Edge Computing:Ruggedized servers at well pads process drilling telemetry locally, eliminating satellite latency for emergency response automation. Permian Basin installations lead this architecture as pad drilling density intensifies real-time decision requirements.
- Hybrid:Split workloads synchronize time-sensitive well control with cloud-based seismic imaging and reservoir simulation. This architecture satisfies EPA methane monitoring mandates requiring continuous edge detection with centralized audit trails.
- Cloud-Based:Fully centralized analytics migrate legacy SCADA data to hyperscale environments for supply chain optimization.
- On-Premise:Air-gapped installations persist in jurisdictions with strict seismic data sovereignty restrictions.
Edge Computing holds installed capacity. Hybrid deployments are expanding most quickly as operators balance latency requirements with capital efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the Permian Basin demonstrate the lowest price elasticity, absorbing premium analytics costs to compress drilling decision latency below 50 milliseconds. European operators under CSRD mandates show moderate elasticity, prioritizing compliance-grade carbon accounting over raw compute performance. Asian national oil companies exhibit the highest sensitivity, favoring bundled service contracts over standalone platform licensing.
United States
Upstream operators in the Permian Basin deploy edge computing nodes at well pads to process drilling telemetry without satellite transmission delays. The EPA enforces methane monitoring mandates under the Inflation Reduction Act that compel continuous emissions detection with auditable data trails. Houston anchors the vendor ecosystem, where Schlumberger and Halliburton maintain integrated analytics-service delivery centers.
Saudi Arabia
National oil companies prioritize reservoir digital twins integrating physics-based simulations with live production telemetry from mature carbonate fields. The country's national petroleum regulator mandates enhanced recovery reporting that drives investment in subsurface modeling infrastructure. Dhahran concentrates predictive analytics R&D, where Aramco operates dedicated computational research facilities.
Norway
Offshore operators in the North Sea apply predictive maintenance algorithms to subsea equipment failure forecasting in harsh deepwater environments. The country's national petroleum safety authority enforces strict data governance protocols for cross-border seismic transfers affecting cloud deployment decisions. Stavanger hosts specialized vendor operations targeting subsea infrastructure analytics.
Brazil
Pre-salt field developers seek first-mover predictive maintenance capabilities for subsea equipment in underpenetrated deepwater basins. The national petroleum regulator requires granular production reporting that accelerates investment in real-time monitoring infrastructure. Rio de Janeiro anchors the service provider cluster, where international vendors localize deepwater-specific analytics modules.
United Kingdom
North Sea operators migrate aging seismic libraries to hyperscale cloud environments to compress 4D seismic interpretation timelines. The national petroleum regulator enforces decommissioning cost forecasting requirements that drive demand for asset lifecycle analytics. Aberdeen maintains its position as the European hub for offshore data science talent and specialized vendor operations.
Big Data in Oil and Gas Market Vendor Landscape
Capability concentration sits with cloud-native specialists; scale advantage sits with integrated oilfield service conglomerates. The market structure bifurcates between subscription-economy platforms and bundled service-software contracts. Three archetypes dominate: hyperscale cloud providers licensing energy-specific compute environments, traditional oilfield services embedding analytics into physical service delivery, and independent software vendors competing on specialized reservoir simulation. M&A activity concentrates on tuck-in acquisitions of machine learning startups, while strategic partnerships between supermajors and cloud providers reshape deployment architecture standards.
Within the integrated service tier, Schlumberger Limited and Halliburton Company exemplify bundled analytics-physical service models, embedding software modules into drilling and completion contracts. Microsoft Corporation occupies a distinct position anchoring hyperscale cloud partnerships with supermajors seeking elastic compute for seismic processing workloads. These three entities represent the dominant competitive vectors reshaping procurement authority across upstream, midstream, and downstream segments.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| IBM |
| Amazon.com Inc |
| Accenture plc |
| Microsoft Corporation |
| Baker Hughes Company |
| Alphabet Inc |
| Oracle Corporation |
| Others |
Supply Flow & Price Mechanics
Houston's vendor ecosystem concentrates predictive analytics platform development, translating concentrated R&D capacity into pricing power for subscription-tiered deployments. The Permian Basin's drilling intensity absorbs premium edge-computing costs without demand destruction, while European compliance-driven buyers face steeper price elasticity under CSRD mandates.
Pricing Analysis
Long-term SaaS subscriptions displace perpetual software licenses as the dominant contract structure, with monthly arrangements now standard among independent Permian operators. Price differentiation hinges on latency-grade certification and after-sales integration depth, with sub-50-millisecond edge deployments commanding substantial premiums over cloud-only tiers. Pricing pressure stems from hyperscaler cloud partnerships eroding traditional oilfield service margins. National oil companies exhibit lowest price sensitivity, while Asian independents show highest elasticity favoring bundled service-software contracts.
Supply Chain Analysis
Extended payment terms from supermajors compress working capital cycles for edge-computing hardware vendors, accelerating supply-chain finance facility adoption. Manufacturing concentrates in the United States, China, and Taiwan for GPU accelerators and ruggedized server components. The supply chain draws from specialized semiconductor foundries, seismic sensor fabricators, and subsea cable manufacturers. Single-source vulnerability in advanced node chip fabrication poses structural risk. Distribution runs through integrated oilfield service conglomerates and direct hyperscaler partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where interoperability between edge nodes and cloud environments determines vendor survival, with DELFI-style cognitive environments and Azure energy partnerships establishing competing ecosystem standards.
For Market Incumbents: Pre-empt hyperscaler encroachment by embedding proprietary analytics modules into physical drilling contracts, deepening captive relationships with national oil companies. Lock in seismic data sovereignty compliance through ISO 27001 certification investments that cloud-native entrants cannot replicate quickly. Vertical integration into edge hardware manufacturing secures latency-grade supply security against semiconductor allocation constraints. For New Entrants and Emerging Players: Build out carbon capture verification algorithms as a white-space target, where reservoir sequestration monitoring lacks established vendor relationships. Brazil's pre-salt developments offer the most penetrable geography for subsea predictive maintenance specialization. A project-based proof-of-concept go-to-market with Petrobras or Equinor bypasses incumbent procurement lock-in. For Investors and Strategic Acquirers: Long-term, this sits as a data-sovereignty play because seismic archive governance and cross-border transfer compliance create durable moats around analytics platforms. Target acquisition archetypes include machine learning startups with reservoir simulation specialization and edge-computing hardware vendors with oilfield certification. Watch EPA methane rule enforcement stringency as the signal for emissions-monitoring infrastructure inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Interoperability between DELFI cognitive environments and Azure hyperscale clusters reshapes procurement authority. |
| Acquisition of Specialist Firm | Machine learning startups with neural geosteering capabilities fill capability gaps in incumbent portfolios. |
| Geographic Expansion | Localization in Brazil's pre-salt basin captures first-mover advantages in underpenetrated deepwater analytics. |
| Strategic Partnership | Supermajor-cloud provider alliances establish deployment architecture standards across seismic processing workloads. |
| Product Launch | Carbon accounting modules addressing EU CSRD Scope 3 disclosure requirements open compliance-driven revenue streams. |
Methodological Framework
Desk research of SEC 10-K filings from oilfield service conglomerates, EPA enforcement databases, and EU regulatory transparency portals preceded structured interviews with reservoir engineers, drilling operations managers, cloud procurement officers, and sustainability compliance leads. Primary fieldwork across the Permian Basin, North Sea, and Middle East production clusters validated secondary estimates. Bottom-up platform deployment counts and top-down vendor revenue analysis were triangulated against hyperscaler energy vertical disclosures.
Assumptions held regulatory enforcement timelines and cloud migration capex cycles fixed while varying drilling intensity scenarios and methane pricing mechanisms across the analysis window. Segmentation modeling incorporated technology tier, deployment architecture, application criticality, and end-user procurement authority. CAGRs were derived from elasticity-adjusted adoption curves and vendor capacity expansion announcements. Reservoir simulation workload growth and edge node installation rates served as primary volume indicators.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by hyperscale cloud providers or national oil companies would shift outcomes. Macroeconomic commodity price collapse, accelerated EPA methane rule tightening, or breakthrough quantum computing applications for seismic processing would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
US Big Data Analytics in Energy Market
Energy Analytics and Software
Oil Condition Monitoring Market
Energy Analytics and Software
Industrial Energy Monitoring Market
Energy Analytics and Software
Power Monitoring and Control Software Market
Energy Analytics and Software
Carbon and Energy Software Market
Energy Analytics and Software
Australia Big Data Analytics in Energy Market
Energy Analytics and Software
Spain Big Data Analytics in Energy Market
Energy Analytics and Software
Solar Analyzer Market
Energy Analytics and Software
Digital Energy Platform Market
Energy Analytics and Software
India Big Data Analytics in Energy Market
Energy Analytics and Software
Solar Digitalization Platform Market
Energy Analytics and Software
GCC Well Testing Services Market
Energy Analytics and Software
Automated Power Generation Dispatch Software Market
Energy Analytics and Software
Japan Big Data Analytics in Energy Market
Energy Analytics and Software
Europe Big Data Analytics in Energy Market
Energy Analytics and Software
Oil and Gas Data Management Software Market