
 Predictive Maintenance in the Energy Market | 2026-2036
Predictive Maintenance in the Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Predictive Maintenance in the Energy Market Analytics
Buyer concentration among European utilities is restructuring procurement patterns for predictive maintenance platforms as national grid operators consolidate vendor relationships under framework agreements. Siemens AG leverages its digital twin portfolio to anchor long-term service contracts across German transmission networks. Schneider Electric SE competes through its EcoStruxure architecture, which sustains recurring revenue from integrated asset performance management deployments. GE Vernova specializes in gas turbine anomaly detection, dominating predictive analytics for combined-cycle installations in North American power fleets.
Predictive Maintenance in the Energy encompasses sensor-driven prognostics, algorithmic failure forecasting, and prescriptive intervention scheduling for generation, transmission, and distribution assets. Systems typically integrate vibration thresholds above ISO 10816 standards with thermal imaging and dissolved gas analysis to preempt transformer and rotating equipment failures. Condition monitoring services command the largest revenue share due to recurring hardware installation and calibration cycles across legacy coal and nuclear plants. Machine learning technology represents the fastest-expanding segment as utilities deploy neural networks to correlate weather patterns, load curves, and equipment degradation signals. Edge computing architectures are gaining traction where latency constraints prevent cloud-dependent decision-making for critical safety systems.
The US Federal Energy Regulatory Commission and the Environmental Protection Agency shape compliance requirements for emissions-linked maintenance scheduling and grid reliability reporting. Europe's F-Gas Regulation and CE marking directives constrain sensor refrigerant choices and equipment interoperability standards, respectively. Stakeholders must monitor how evolving cybersecurity mandates from national regulators interface with open IoT protocols as attack surfaces expand across distributed energy resources.
Market Dynamics
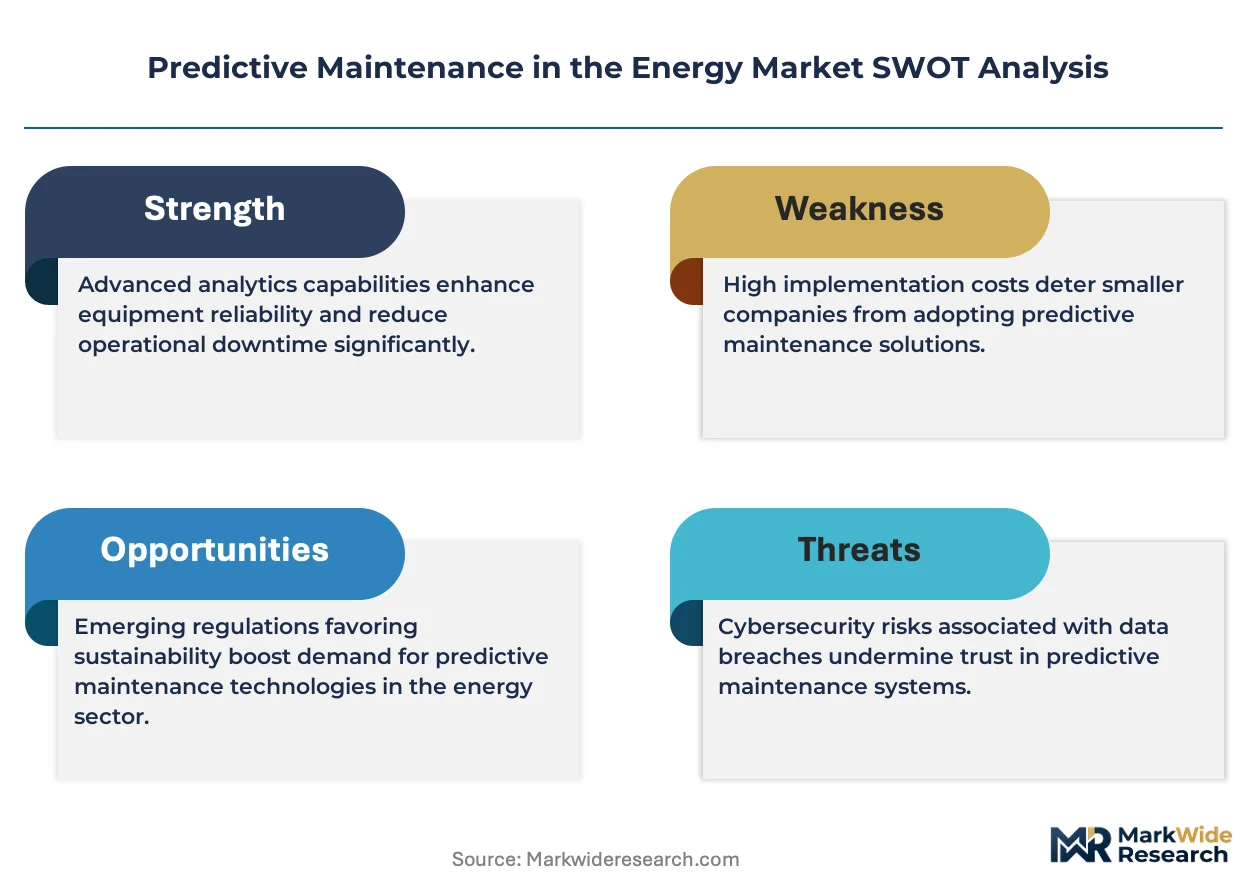
Machine learning platforms are compressing fault-detection cycles from weeks to hours across transmission and generation fleets, forcing asset owners to restructure maintenance workflows and vendor relationships.
Growth Catalysts
- Grid Modernization Mandates:The US Inflation Reduction Act and EU Green Deal channel capital toward sensor deployment on aging infrastructure.
- Variable Renewable Integration:Wind and solar intermittency is accelerating condition monitoring adoption to manage ramping stress on thermal backup units.
- ISO 10816 Vibration Standards:Updated thresholds for rotating machinery are mandating continuous monitoring rather than periodic inspection.
Market Restraints
- Sensor Hardware Concentration:Precision accelerometer and thermal imaging supply concentrates among German and Japanese component specialists.
- Cybersecurity Compliance Friction:Open IoT protocols face escalating scrutiny from national regulators expanding attack-surface mandates.
- Legacy Asset Retrofit Costs:Pre-digital coal and nuclear plants require extensive cabling and gateway installation to enable edge connectivity.
Strategic Opportunities
- Offshore Wind Expansion:Salt-corrosion and accessibility constraints on North Sea installations create demand for autonomous drone-based inspection systems.
- Digital Twin Convergence:Physics-based modeling fused with operational data streams enables prescriptive rather than merely predictive intervention.
- Performance-Based Service Contracts:Availability guarantees are displacing time-and-materials billing across independent power producer fleets.
Industry Challenges
- Interdisciplinary Skill Scarcity:Utilities struggle to hire personnel fluent in both rotating equipment engineering and neural network architecture.
- Legacy SCADA Integration:Decades-old control systems lack standardized APIs, forcing custom middleware development for each deployment.
- Calibration Cycle Burden:Dissolved gas analysis and thermal sensors require frequent recertification to maintain diagnostic accuracy thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Predictive Maintenance in the Energy Market |
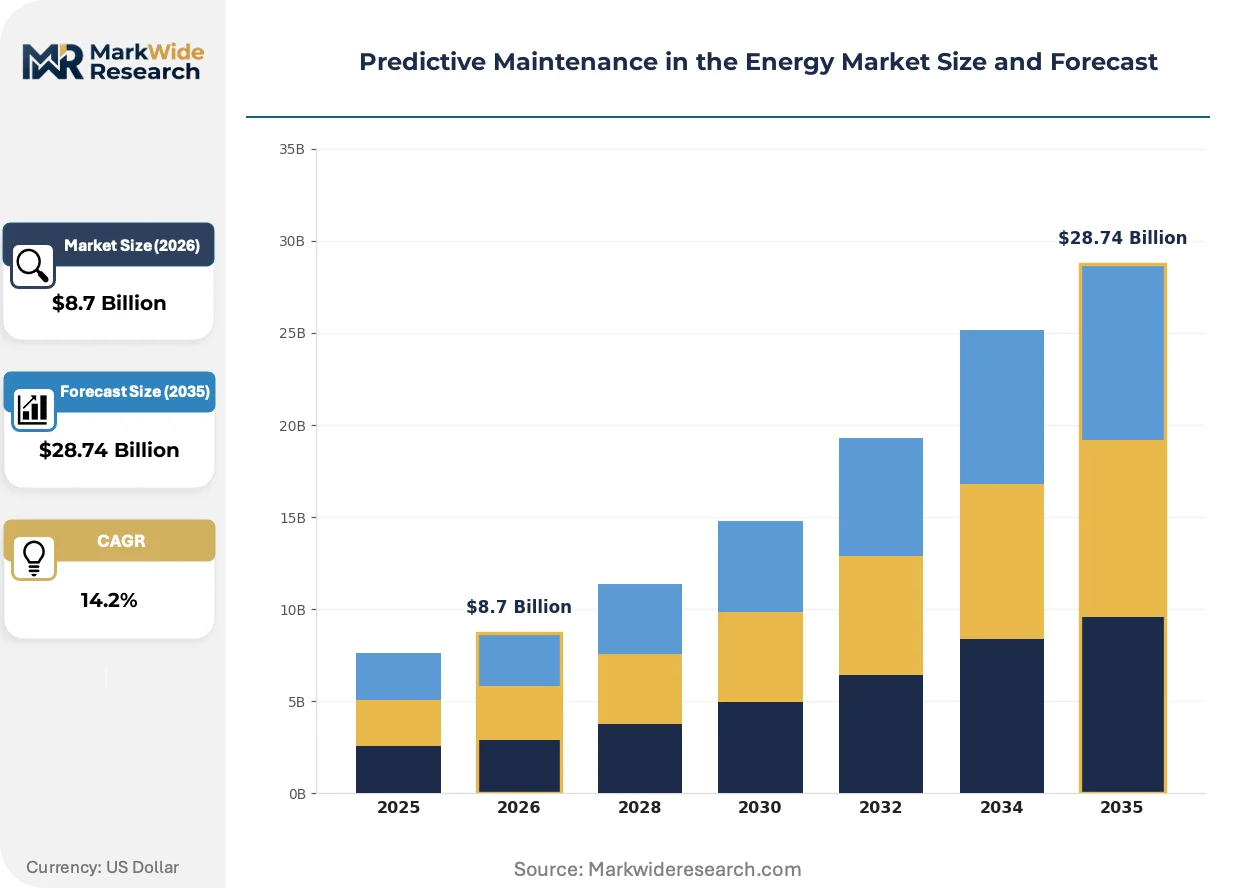
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Condition Monitoring, Vibration Analysis, Data Analytics, Asset Management Technology: IoT Sensors, Machine Learning, Cloud Computing, Edge Computing End User: Utilities, Industrial Sector, Renewable Energy, Oil & Gas Application: Equipment Maintenance, Performance Optimization, Failure Prediction, Safety Management |
| Companies Covered | Siemens AG, Schneider Electric SE, GE Vernova, Honeywell International Inc., ABB Ltd., Siemens Energy, General Electric Company, SAP SE, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Predictive Maintenance in the Energy Market Evolving Landscape
Edge computing architectures are redistributing analytical workloads away from centralized cloud platforms, enabling millisecond-latency safety decisions at substation and turbine level.
Digital twin technology is decentralizing maintenance decision-making by embedding physics-based degradation models directly at generation sites. Combined-cycle operators in Texas and California are deploying these systems to correlate combustion dynamics with blade creep forecasts. The shift compresses response times for critical safety interventions while reducing bandwidth dependency on wide-area networks.
The EU F-Gas Regulation is restricting refrigerant choices for thermal imaging sensors used in transformer monitoring. Equipment manufacturers must reformulate cooling systems or source alternative sensor technologies to maintain CE marking compliance. German transmission operators are accelerating procurement timelines to secure grandfathered inventory before phase-down deadlines tighten.
Long-term framework agreements are consolidating vendor relationships under national grid operator procurement reforms. Siemens AG and Schneider Electric SE are anchoring multi-year service contracts that bundle hardware, software, and analytics across entire transmission networks. This concentration is most visible in Germany and France, where TenneT and RTE have shifted from project-based purchasing to integrated asset performance partnerships.
Predictive Maintenance in the Energy Market Segmentation
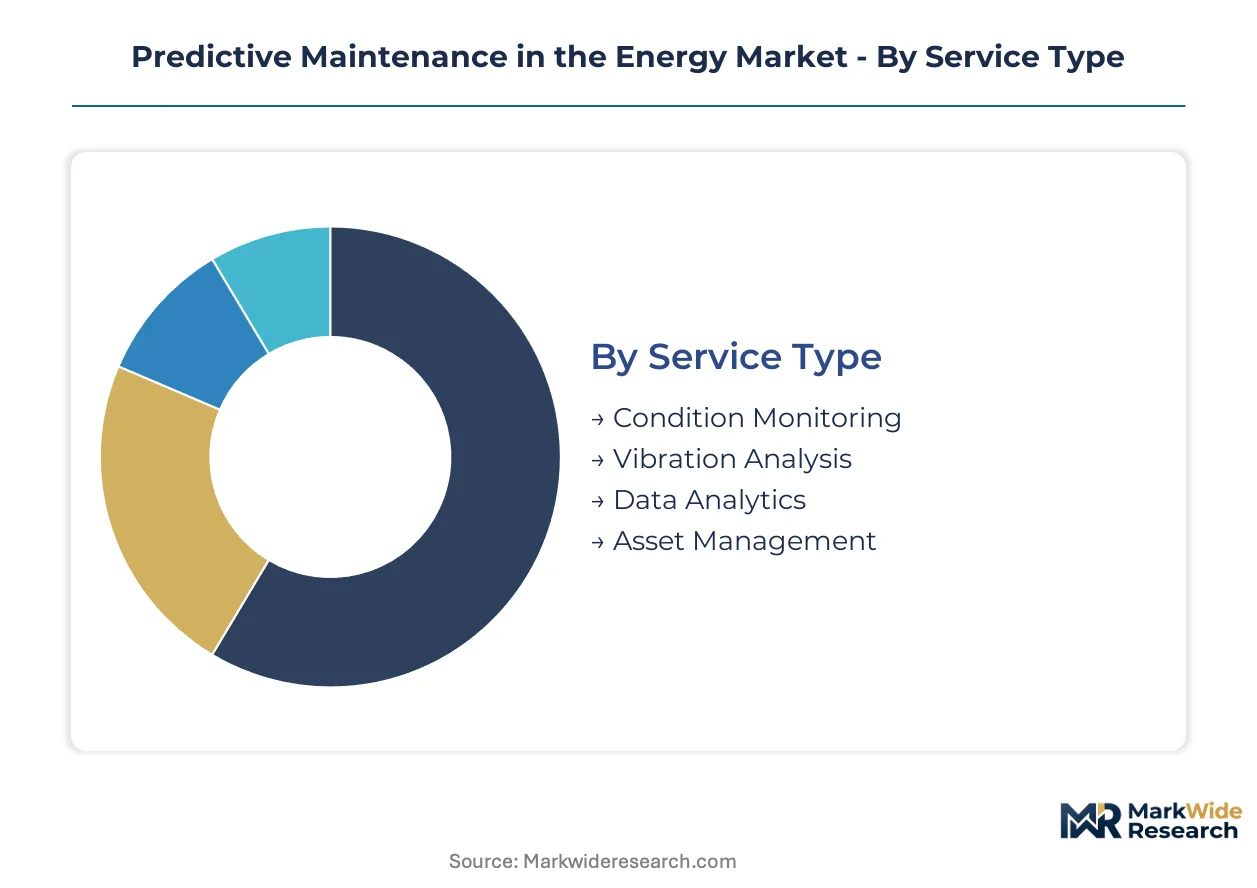
Predictive maintenance deployments vary sharply by operational maturity and regulatory exposure. Segment boundaries determine which vendors qualify for procurement frameworks and which technologies face certification delays.
Service Type:
CE marking applies to hardware-heavy segments while ISO 10816 compliance governs rotating equipment diagnostics across all service tiers.
- Condition Monitoring:Continuous sensor networks track thermal, vibration, and dissolved gas parameters on transformers and turbines. German transmission operators bundle these services into decade-long framework agreements to amortize installation costs across aging coal and nuclear fleets.
- Vibration Analysis:Precision accelerometer deployments measure shaft alignment and bearing degradation against ISO 10816 thresholds. North American combined-cycle operators prioritize this segment to manage ramping stress from renewable backup cycling.
- Data Analytics:Algorithmic pattern recognition platforms correlate operational telemetry with failure modes.
- Asset Management:Integrated lifecycle planning systems coordinate maintenance scheduling with capital replacement timelines.
Condition Monitoring sits at the top of the volume ranking, with Data Analytics climbing the fastest.
Technology:
Cost tiers separate capital-intensive edge deployments from subscription-based cloud architectures.
- IoT Sensors:Precision accelerometers, thermal imagers, and dissolved gas detectors form the physical layer of predictive systems. Supply concentrates among German and Japanese component specialists, creating procurement bottlenecks for utilities accelerating retrofit timelines.
- Machine Learning:Neural networks correlate weather patterns, load curves, and equipment degradation signals to compress fault-detection cycles from weeks to hours. European utilities deploy these platforms most aggressively to manage variable renewable intermittency.
- Cloud Computing:Centralized data lakes enable cross-fleet benchmarking and vendor-managed algorithm updates.
- Edge Computing:Millisecond-latency processing at substation level satisfies critical safety system requirements where cloud dependency is prohibited.
IoT Sensors commands the largest installed base, though Machine Learning gains share fastest among new deployments.
End User:
Customer type dictates procurement complexity, from regulated utility frameworks to industrial spot contracts.
- Utilities:Grid operators and generation owners operate under FERC reliability mandates and EU Green Deal modernization targets. TenneT and RTE in Europe have shifted from project-based purchasing to integrated asset performance partnerships spanning entire networks.
- Industrial Sector:Manufacturing and process industries with captive generation assets deploy predictive systems to avoid production-line disruptions.
- Renewable Energy:Wind and solar operators face salt-corrosion and accessibility constraints that favor autonomous inspection systems.
- Oil & Gas:Upstream and midstream operators monitor compression and pumping equipment under EPA emissions-linked maintenance requirements.
Utilities dominate current procurement volumes, with Renewable Energy expanding most quickly on offshore wind buildouts.
Application:
Maturity stages separate established equipment maintenance from emerging safety management use cases.
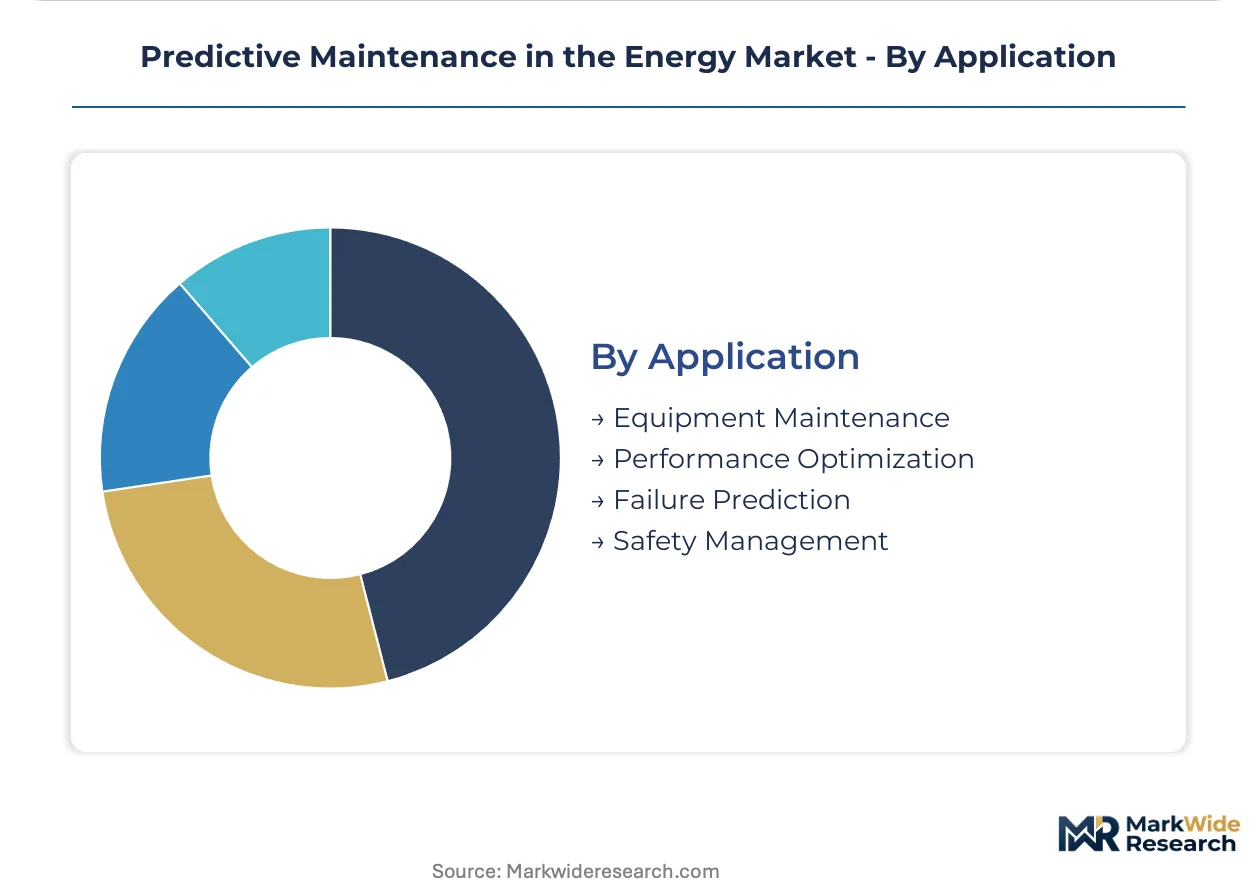
- Equipment Maintenance:Scheduled intervention based on degradation forecasts for transformers, turbines, and switchgear. This application captures the majority of current spending as utilities retrofit legacy thermal fleets with continuous monitoring.
- Performance Optimization:Real-time tuning of combustion dynamics and blade angles to maximize output efficiency.
- Failure Prediction:Prognostic algorithms estimate remaining useful life to trigger pre-emptive component replacement.
- Safety Management:Automated trip decisions and emergency isolation protocols for critical fault conditions.
Equipment Maintenance holds the volume lead, while Safety Management shows the steepest expansion trajectory as regulators tighten reliability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys predictive maintenance platforms more aggressively than the United States to manage thermal fleet cycling from renewable intermittency, though both markets channel substantial capital toward grid modernization mandates.
United States
Texas and California combined-cycle operators deploy edge-computing architectures to manage combustion dynamics under FERC reliability mandates. The Inflation Reduction Act accelerates sensor deployment on aging transmission infrastructure across ERCOT and CAISO territories. Houston and Austin clusters concentrate vendor partnerships for gas turbine anomaly detection systems.
Germany
TenneT and 50Hertz bundle condition monitoring services into decade-long framework agreements to amortize installation costs across coal and nuclear phase-out schedules. The EU F-Gas Regulation constrains thermal imaging sensor refrigerant choices for transformer monitoring. Bavaria and North Rhine-Westphalia host the densest concentrations of digital twin deployments for transmission network optimization.
China
State Grid Corporation integrates machine learning platforms to correlate load curves with equipment degradation across ultra-high-voltage transmission corridors. MIIT cybersecurity mandates shape IoT protocol selection for critical substation safety systems. Yangtze River Delta provinces concentrate domestic sensor manufacturing and algorithm development for wind turbine prognostics.
United Kingdom
National Grid ESO procures integrated asset performance partnerships spanning generation and transmission networks under Ofgem price control frameworks. The UK Net Zero Strategy mandates continuous monitoring rather than periodic inspection for offshore wind interconnectors. Scotland's North Sea clusters drive autonomous drone-based inspection demand for salt-corrosion management.
Japan
Tokyo Electric and Chubu Electric deploy dissolved gas analysis systems to preempt transformer failures under METI grid resilience directives. JIS standards for rotating machinery diagnostics align with updated ISO 10816 vibration thresholds. Osaka and Nagoya industrial corridors concentrate precision accelerometer supply relationships for captive generation assets.
Predictive Maintenance in the Energy Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across predictive maintenance platform procurement. Siemens AG and Schneider Electric SE anchor multi-year service contracts through bundled hardware-software-analytics offerings, while smaller vendors concentrate on isolated diagnostic modules. The market structure favors integrated asset performance partnerships over project-based purchasing. Dominant competitive moves include framework agreement consolidation and digital twin technology licensing.
Within the diversified industrial technology tier, Siemens AG and Schneider Electric SE exemplify integrated platform providers, while GE Vernova occupies a position specializing in rotating equipment prognostics. Siemens AG represents the archetype of vendor consolidation through transmission network framework agreements. Schneider Electric SE exemplifies recurring revenue architectures via EcoStruxure deployments. GE Vernova anchors the gas turbine anomaly detection specialization for North American combined-cycle fleets.
| Leading Market Players |
|---|
| Siemens AG |
| Schneider Electric SE |
| GE Vernova |
| Honeywell International Inc. |
| ABB Ltd. |
| Siemens Energy |
| General Electric Company |
| SAP SE |
| IBM Corporation |
| Others |
Value Network & Pricing Analysis
Sovereign-backed transmission operators in Germany and China anchor procurement discipline through decade-long framework agreements, compressing vendor margins while securing supply priority for precision sensor components. This ownership pattern tightens pricing power on the buy side and forces suppliers into bundled service contracts that amortize hardware costs across extended calibration cycles.
Pricing Analysis
Capacity additions in China's Yangtze River Delta sensor manufacturing clusters are reshaping price floors for precision accelerometers and thermal imaging modules. Three-tier pricing structure across premium certified, standard compliant, and economy unbundled levels separates vendors by CE marking and ISO 10816 calibration status. Cost compression in the economy tier intensifies because domestic Chinese producers are displacing German and Japanese component specialists. Independent power producers exhibit the sharpest price sensitivity, while national grid operators absorb premium tier costs through availability-guarantee contracts.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Houston, and Shanghai coordinate hub-and-spoke patterns for sensor hardware and edge computing gateways. Supply concentrates among Germany, Japan, and China for precision accelerometers, thermal imagers, and dissolved gas analysis equipment. Raw material dependencies span rare earth elements for sensor magnets, semiconductor substrates for edge processors, and specialized refrigerants for thermal imaging systems. Single-source vulnerability runs through German component specialists for ISO 10816-certified vibration sensors. Distribution runs through authorized service integrators who bundle installation, calibration, and analytics subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance platforms offer margin expansion through software-as-a-service tiering that captures recurring revenue from hardware-installed bases. Cost-down drivers include edge computing architectures that reduce cloud bandwidth dependency and enable localized processing at substation level.
For Market Incumbents: Anticipate margin pressure from machine learning pure-plays by deepening captive supply relationships with German and Japanese sensor specialists. Anchor multi-year framework agreements with national grid operators before procurement consolidation peaks. Certification investment in EU F-Gas Regulation compliance represents the priority defensive lever as refrigerant phase-down deadlines tighten.
For New Entrants and Emerging Players: Captive renewable energy operators with offshore wind portfolios represent an underserved buyer archetype accessible through autonomous drone-based inspection systems. White-space targets span salt-corrosion monitoring for North Sea installations and prescriptive maintenance modules for solar inverter fleets. Direct equipment-as-a-service contracts bypass entrenched utility procurement channels.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap vibration analysis specialists lacking integrated analytics platforms. Long-term viability hinges on neural network talent retention and edge computing IP portfolios. Watch for inflection where utilities shift from pilot machine learning deployments to network-wide algorithm standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Licensing | Physics-based degradation models embedded at generation sites compress response times for critical safety interventions. |
| Framework Agreement Consolidation | Multi-year service contracts bundling hardware, software, and analytics displace project-based purchasing across German transmission networks. |
| Edge Computing Deployment | Millisecond-latency processing at substation level satisfies FERC reliability mandates prohibiting cloud dependency. |
| Machine Learning Platform Integration | Neural networks correlating weather patterns with equipment degradation signals compress fault-detection cycles from weeks to hours. |
| Performance-Based Contracting | Availability guarantees displace time-and-materials billing across independent power producer fleets under EPA emissions-linked requirements. |
Research Methodology
Coverage spans Germany, the United States, China, the United Kingdom, and Japan, with primary inputs from each market cluster. Utility planning officers, independent power producer project developers, EPC contractors, grid operators, and aftermarket service heads contributed through structured interviews. Secondary validation drew from EIA generation statistics, IEA grid modernization reports, FERC reliability filings, and EU Green Deal implementation tracking. Bottom-up equipment deployment estimates triangulated against top-down capital expenditure projections across the analysis window.
Segmentation dimensions were modeled at the service-type, technology-tier, end-user category, and application-level across the projection horizon. Fuel source, generation capacity tier, and regional grid type shaped energy-specific forecast inputs. CAGRs were derived from weighted scenario analysis incorporating policy mandate acceleration curves and renewable integration stress factors.
Underlying measurement precision varies by segment; condition monitoring services carry tighter precision than emerging safety management applications. Forecasts reflect documented assumptions regarding grid modernization spend trajectories and machine learning adoption curves. Cybersecurity compliance friction and legacy SCADA integration bottlenecks represent specific risk factors that could revise projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Solar Analyzer Market
Energy Analytics and Software
Energy Intelligence Solutions Market
Energy Analytics and Software
Asia-Pacific Big Data Analytics in Energy Market
Energy Analytics and Software
Oil Condition Monitoring Market
Energy Analytics and Software
Carbon and Energy Software Market
Energy Analytics and Software
Netherlands Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data in Oil and Gas Market
Energy Analytics and Software
Big Data Analytics in Energy Market
Energy Analytics and Software
Africa Big Data Analytics in Energy Market
Energy Analytics and Software
Smart Grid Data Analytics Market
Energy Analytics and Software
France Big Data Analytics in Energy Market
Energy Analytics and Software
Automated Power Generation Dispatch Software Market
Energy Analytics and Software
Germany Big Data Analytics in Energy Market
Energy Analytics and Software
Industrial Energy Monitoring Market
Energy Analytics and Software
Japan Big Data Analytics in Energy Market
Energy Analytics and Software
Energy and Utilities Analytics Market