
 Power Monitoring and Control Software Market | 2026-2036
Power Monitoring and Control Software Market Size, Share, and Industry Trends Forecast 2026-2036
Power Monitoring and Control Software Market Outlook
The split between premium enterprise-grade suites and commodity monitoring tools is rebalancing as buyers prioritize predictive analytics over basic telemetry dashboards. Siemens leverages deep domain expertise in industrial automation to anchor its position among heavy manufacturing accounts. Schneider Electric differentiates through integrated power and building management convergence, while ABB competes on real-time digital twin architectures for grid operators.
Power monitoring and control software comprises applications that collect, process, and visualize electrical parameter data from generation through consumption points, typically sampling voltage, current, power factor, and harmonic distortion at sub-second intervals to enable load optimization and fault isolation. Its primary commercial purpose is to reduce energy waste, prevent equipment failure, and ensure compliance with grid codes. Cloud-based deployment is capturing the fastest expansion as utilities migrate SCADA workloads off aging on-premises infrastructure, while integrated product types command the deepest margin pools by bundling monitoring with control logic and energy procurement workflows.
The Federal Energy Regulatory Commission enforces mandatory reliability standards under NERC jurisdiction that compel utilities to deploy continuous monitoring and automated response capabilities, directly expanding addressable demand for control software. EPA emissions tracking requirements and state-level renewable portfolio standards add parallel compliance layers that software platforms must encode. Stakeholders should weigh whether to build native AI-driven forecasting modules or partner with specialized analytics vendors as grid edge complexity intensifies.
Market Dynamics
The migration from reactive SCADA architectures to predictive, cloud-native platforms is compressing replacement cycles and forcing incumbent vendors to re-engineer core offerings around AI-driven load forecasting.
Growth Catalysts
- NERC CIP Reliability Mandates:North American utilities face escalating penalties for grid instability, compelling deployment of continuous monitoring with automated islanding capabilities.
- Hyperscale Data Center Expansion:Virginia and Texas server clusters now exceed 500MW per campus, requiring sub-cycle power quality analytics to prevent cascading failures.
- Edge Computing Architectures:Distributed generation and microgrids demand localized control logic that traditional centralized SCADA cannot deliver.
Market Restraints
- Semiconductor Supply Concentration:Specialized ADC and FPGA components for high-speed sampling concentrate in Taiwanese and South Korean foundries, exposing lead time volatility.
- Interoperability Friction:Legacy Modbus and DNP3 protocols resist seamless integration with modern MQTT and OPC-UA stacks, inflating deployment costs.
- Skilled Labor Scarcity:Power systems engineers with combined domain expertise in electrical engineering and cloud infrastructure command premium compensation that squeezes project margins.
Strategic Opportunities
- India Smart Grid Modernization:The country's Central Electricity Authority mandates AMI rollout targets that exceed domestic software vendor capacity, opening entry for foreign platforms.
- Carbon Accounting Convergence:EPA emissions tracking requirements and EU CSRD disclosure rules create bundled demand for power monitoring fused with Scope 2 reporting automation.
- Digital Twin Integration:Real-time electrical system simulation is absorbing AI-based predictive maintenance modules from adjacent industrial software categories.
Industry Challenges
- Cybersecurity Certification Timelines:NERC CIP-013 supply chain security standards impose multi-quarter validation protocols that delay product releases.
- Legacy System Integration Complexity:Brownfield industrial sites operate 15-25 year-old protection relays whose proprietary communication stacks resist API-based extraction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Monitoring and Control Software Market |
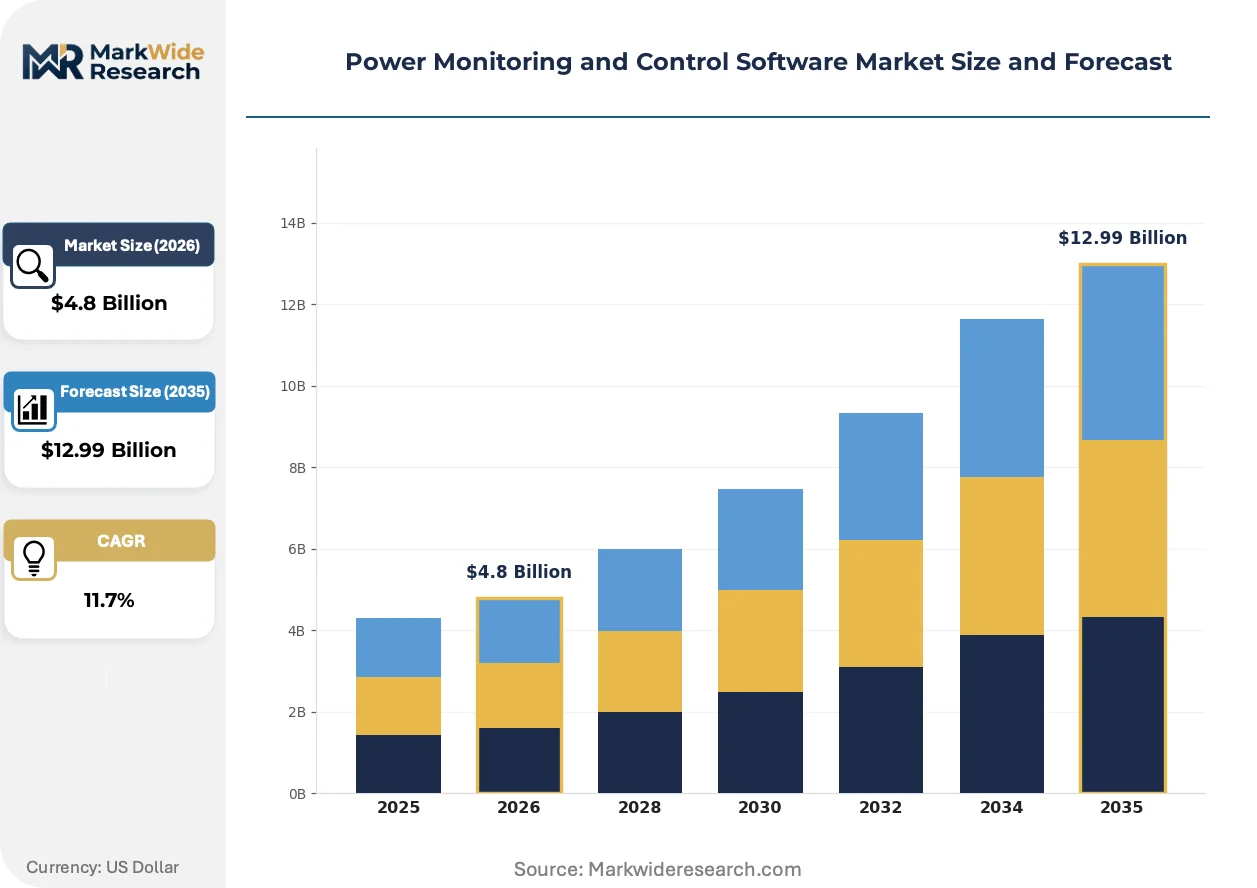
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Cloud-based, Integrated, Hybrid End User: Utilities, Manufacturing, Residential, Commercial Deployment: On-premises, SaaS, Managed Services, Edge Computing Features: Real-time Monitoring, Data Analytics, Alerts, Reporting |
| Companies Covered | Honeywell, IBM, Siemens, TTMS, EnergyCAP, Schneider Electric, GE Vernova, Techstack, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Monitoring and Control Software Market Strategic Shifts
Software architectures are pivoting from periodic polling to event-driven streaming, enabling millisecond-level anomaly detection that was technically infeasible under traditional SCADA paradigms.
Time-series databases optimized for electrical waveform storage are absorbing GPU-accelerated inference engines that execute harmonic distortion classification at the edge. Large data center operators in Northern Virginia deploy these stacks to preempt transformer saturation events before thermal damage accumulates. The technology is absorbing workloads previously handled by dedicated power quality analyzers, compressing the instrument-to-software boundary.
EPA enforcement of greenhouse gas reporting under the Inflation Reduction Act now requires hourly granularity for grid-connected assets above 25MW. Industrial facilities must retrofit monitoring infrastructure to capture marginal emissions factors in real time. Chemical processing plants along the US Gulf Coast represent the most affected segment, with compliance deadlines accelerating procurement of integrated metering and reporting platforms.
Subscription pricing for power analytics is displacing perpetual license models among mid-sized manufacturing accounts. Equipment OEMs now bundle monitoring software into long-term service agreements rather than selling standalone seats. This pattern is most visible in Germany's automotive supplier base, where foundries and stamping plants prefer operational expenditure treatment for energy management tools.
Power Monitoring and Control Software Market Segmentation
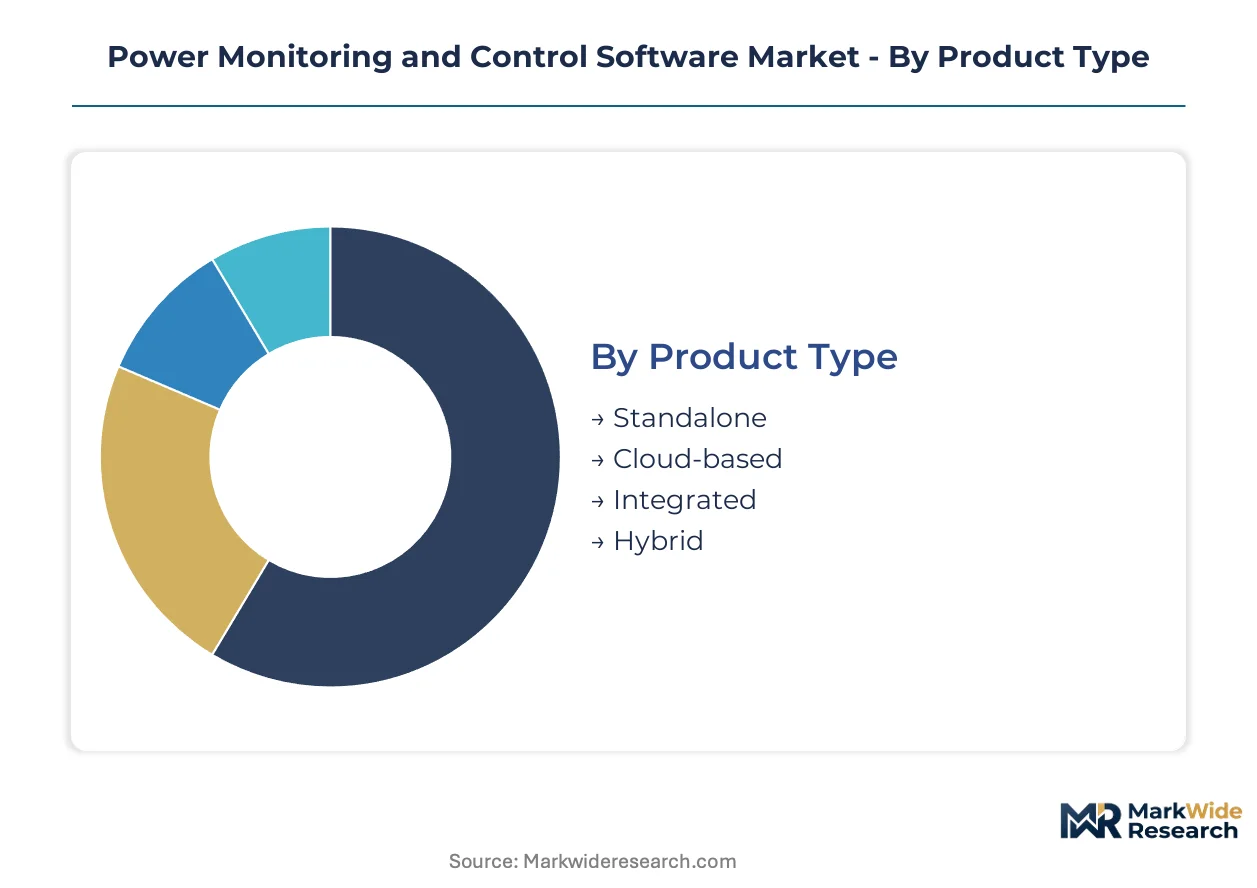
Segmentation in power monitoring and control software reveals distinct capital requirements and operational priorities across deployment modes and end-use environments. Each category carries implications for software architecture, integration complexity, and recurring revenue potential.
Product Type:
Capital intensity varies sharply across product architectures, with integrated suites demanding the heaviest upfront engineering investment for embedded control logic.
- Integrated:Bundles monitoring dashboards with programmable control logic and energy procurement workflows through unified codebases. Data center operators in Virginia and Texas deploy these stacks to manage 500MW-plus campuses under NERC CIP reliability mandates.
- Cloud-based:Delivers meter data ingestion and visualization through multi-tenant architectures with API-native interoperability. Utilities migrating aging SCADA workloads drive demand as FERC-enforced reliability standards tighten.
- Standalone:Single-function telemetry tools for basic voltage and current logging without control capabilities.
- Hybrid:Combines on-premises edge processing with cloud analytics tiers for latency-sensitive fault detection.
Most installed capacity flows through Integrated suites. Expansion is steepest in Cloud-based architectures.
End User:
Application context determines software complexity, with utilities requiring the most extensive compliance encoding and manufacturing prioritizing predictive maintenance modules.
- Utilities:Grid operators deploy continuous monitoring with automated islanding to satisfy FERC-enforced NERC CIP standards and prevent cascading instability penalties.
- Manufacturing:Heavy industrial accounts absorb real-time digital twin architectures for equipment failure prevention, with Siemens anchoring position through deep automation domain expertise.
- Commercial:Building portfolios fuse power monitoring with HVAC and lighting control through Schneider Electric's converged management stacks.
- Residential:Smart home energy dashboards with basic load disaggregation and utility rate optimization.
Utilities command the largest contract values. Manufacturing is expanding most quickly as brownfield retrofit cycles compress.
Deployment:
Operational expenditure treatment dominates customer preference, shifting procurement away from capital-intensive perpetual licenses toward subscription models.
- SaaS:Subscription pricing for analytics displaces perpetual licenses among mid-sized manufacturing accounts, particularly in Germany's automotive supplier base.
- Managed Services:Equipment OEMs bundle monitoring software into long-term service agreements rather than standalone seat sales.
- On-premises:Legacy SCADA architectures retained where air-gapped security or sub-millisecond control loops are mandatory.
- Edge Computing:Localized control logic for distributed generation and microgrids that centralized SCADA cannot deliver.
SaaS carries the largest revenue concentration. Edge Computing is gaining share fastest as grid complexity intensifies.
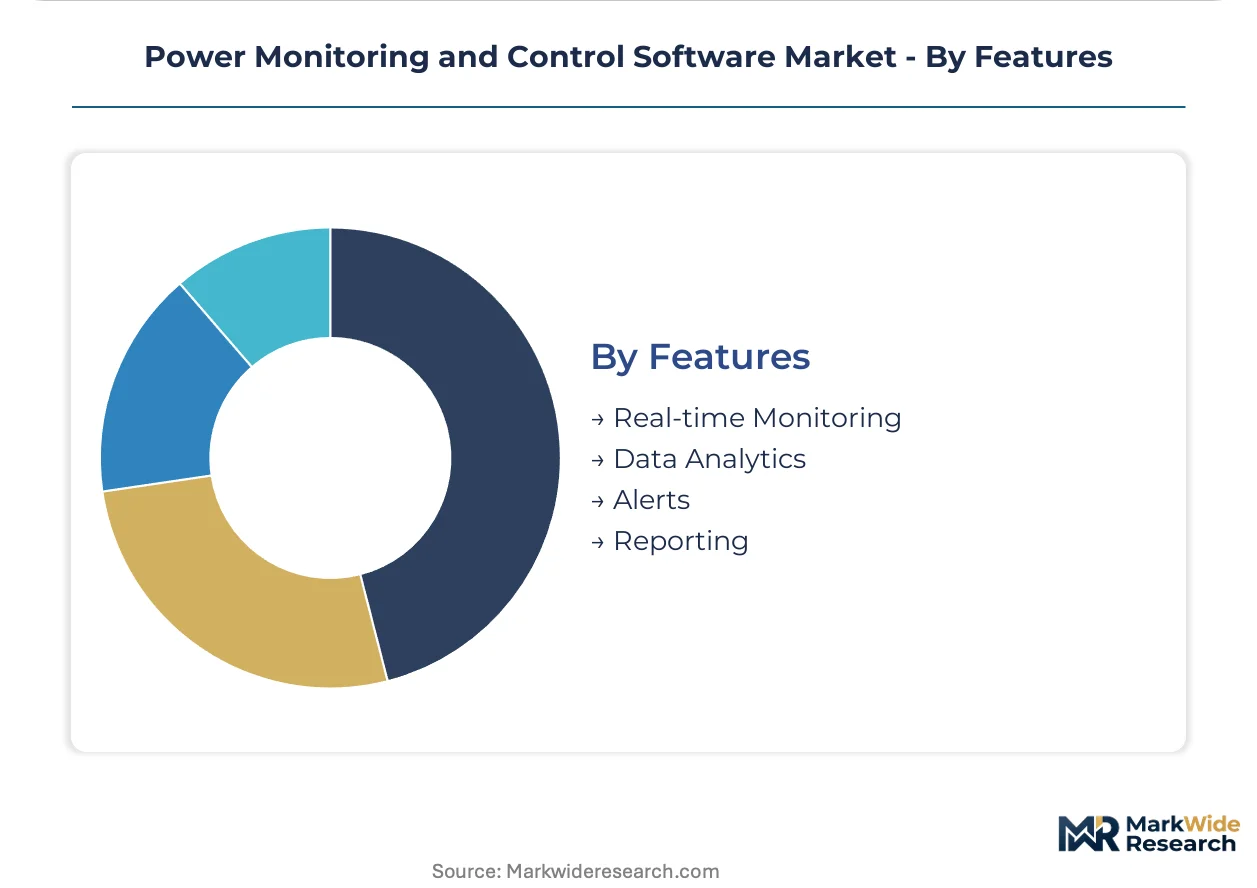
Features:
Functional depth separates premium enterprise-grade suites from commodity tools, with predictive capabilities commanding pricing premiums over basic telemetry dashboards.
- Data Analytics:GPU-accelerated inference engines execute harmonic distortion classification at the edge, absorbing workloads from dedicated power quality analyzers.
- Real-time Monitoring:Event-driven streaming architectures enable millisecond-level anomaly detection previously infeasible under periodic polling SCADA paradigms.
- Alerts:Automated threshold violations with escalation workflows for operator notification.
- Reporting:EPA emissions tracking automation for hourly granularity requirements under Inflation Reduction Act enforcement.
Data Analytics dominates R&D investment. Real-time Monitoring is climbing the fastest as sub-cycle power quality becomes critical.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power systems engineers with combined electrical engineering and cloud infrastructure expertise cluster in the United States, Germany, and India, anchoring software development and deployment capacity for grid modernization projects.
United States
Hyperscale data center operators in Northern Virginia and Texas drive concentrated demand for sub-cycle power quality analytics. FERC-enforced NERC CIP reliability standards mandate continuous monitoring with automated islanding capabilities for grid-connected assets. Server clusters exceeding 500MW per campus in Loudoun County and Dallas-Fort Worth require predictive platforms to prevent cascading transformer failures.
Germany
Automotive suppliers and foundries in the automotive sector absorb subscription-based energy management tools through operational expenditure models. EU CSRD disclosure rules and the national renewable energy transition create bundled demand for power monitoring fused with Scope 2 emissions reporting. Industrial concentrations in Bavaria and Baden-Württemberg retrofit brownfield protection relays with API-native extraction layers.
China
State Grid Corporation's smart grid investments and dual carbon goals accelerate deployment of digital twin architectures for real-time electrical system simulation. MIIT standards for industrial internet platforms encode interoperability requirements that reshape vendor procurement patterns. Yangtze River Delta manufacturing hubs integrate edge computing stacks for distributed generation control.
India
Central Electricity Authority mandates for AMI rollout exceed domestic software vendor capacity, opening entry for foreign monitoring platforms. PLI scheme incentives for domestic manufacturing drive power quality investments in Gujarat and Maharashtra industrial corridors. Telangana and Karnataka data center clusters emerge as secondary demand nodes for cloud-native SCADA migration.
Japan
METI grid modernization programs and earthquake-resilience requirements drive adoption of hybrid deployment architectures combining on-premises edge processing with cloud analytics. Kanto region utilities prioritize millisecond-level anomaly detection for islanding scenarios. Osaka-based heavy manufacturers absorb predictive maintenance modules from adjacent industrial software categories.
Power Monitoring and Control Software Market Competitive Environment
Top-tier vendors anchor the integrated suite segment, while specialized analytics providers and regional system integrators occupy mid-market and niche vertical positions. The vendor base stratifies across three tiers: multinational industrial automation conglomerates with deep domain expertise, cloud-native software specialists with API-first architectures, and regional implementation partners with legacy protocol integration capabilities. Dominant competitive moves include portfolio diversification into carbon accounting convergence and strategic partnerships with specialized AI forecasting vendors.
Within the industrial automation tier, Siemens and ABB exemplify archetypes of deep manufacturing domain expertise versus real-time digital twin specialization. Schneider Electric occupies a converged position spanning power and building management integration. Among cloud-native entrants, IBM represents the enterprise IT platform archetype seeking energy vertical penetration through hybrid cloud deployment models.
| Leading Market Players |
|---|
| Honeywell |
| IBM |
| Siemens |
| TTMS |
| EnergyCAP |
| Schneider Electric |
| GE Vernova |
| Techstack |
| ABB |
| Others |
Value Chain & Pricing Dynamics
Power systems engineers with combined electrical engineering and cloud infrastructure expertise cluster in the United States, Germany, and India, anchoring labor-cost differentials that widen pricing-tier spreads between premium enterprise suites and commodity monitoring tools.
Pricing Analysis
The bundled-vs-unbundled service split separates integrated suites with embedded control logic from standalone telemetry dashboards. Subscription SaaS pricing for cloud-native analytics is displacing perpetual licenses among mid-sized manufacturing accounts, particularly in Germany's automotive supplier base. Price differentiation rests on certification grade—NERC CIP compliance encoding commands premiums—and customization depth for legacy protocol integration. Pricing pressure stems from skilled labor scarcity, as engineers commanding premium compensation squeeze project margins. Utilities show least price sensitivity due to regulatory mandate urgency, while residential smart home segments exhibit highest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale data center demand in Northern Virginia and Texas, while regional system integrators serve brownfield industrial retrofits. Specialized ADC and FPGA components for high-speed sampling concentrate in Taiwanese and South Korean foundries, exposing lead time volatility. Software development draws from US, German, and Indian engineering talent pools, with cloud infrastructure provisioning anchored in hyperscaler data center regions. Supply chain risk centers on single-source vulnerability for semiconductor components critical to edge computing deployments. Distribution runs through equipment OEMs bundling monitoring into long-term service agreements, compressing standalone software vendor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with FERC-enforced NERC CIP reliability standards mandating continuous monitoring deployment and expanding addressable demand regardless of macroeconomic cycles.
For Market Incumbents: Anticipate margin compression from cloud-native entrants by hardening API-native interoperability layers and pre-integrating carbon accounting modules. Incumbents should deepen backward integration into edge computing hardware to capture hybrid deployment architectures, while accelerating AI-driven forecasting partnerships to match specialized analytics vendor capabilities.
For New Entrants and Emerging Players: The gap between premium integrated suites and economy standalone tools offers entry points for mid-market manufacturing accounts in India and Southeast Asia. Target India's AMI rollout mandates exceeding domestic vendor capacity, and pursue white-label partnerships with European equipment OEMs seeking cloud-native software stacks for service agreement bundling.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional system integrators with legacy protocol expertise but limited AI capabilities. Long-term viability favors platforms converging power monitoring with Scope 2 emissions reporting automation. Watch for EPA enforcement intensity under IRA greenhouse gas tracking requirements as the inflection signal accelerating procurement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Forecasting Partnership | Specialized analytics vendors supply predictive load modules that incumbent platforms absorb through licensing. |
| Carbon Accounting Convergence | EPA emissions tracking and EU CSRD rules bundle power monitoring with automated Scope 2 reporting workflows. |
| Edge Computing Hardware Integration | Hybrid deployment architectures demand localized control logic that centralized SCADA cannot deliver. |
| Legacy Protocol API Extraction | Brownfield industrial sites retrofit 15-25 year-old protection relays with modern interoperability layers. |
| Subscription Pricing Migration | Equipment OEMs bundle monitoring software into long-term service agreements displacing perpetual licenses. |
Study Parameters
Bottom-up utility and data center operator modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with utility planning officers, hyperscale facility engineers, industrial automation procurement leads, and grid reliability consultants were validated against secondary sources including FERC filings, EIA generation data, NERC compliance databases, and equipment OEM service agreement disclosures. Triangulation across these inputs ensures segmentation integrity across deployment modes, end-use environments, and feature architectures.
Historical trendline analysis of SCADA replacement cycles and cloud migration patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type architecture, end-use compliance intensity, deployment operational expenditure treatment, and regional regulatory framework clusters. CAGRs were derived from weighted scenario analysis incorporating AMI rollout trajectories, data center capacity expansion pipelines, and emissions tracking enforcement timelines.
Caveats apply where semiconductor supply volatility, cybersecurity certification delays, or skilled labor scarcity could materially shift the outlook. Forecasts reflect assumptions regarding NERC CIP penalty escalation, IRA enforcement intensity, and hyperscaler capex continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Utility Analytics and Energy Analytics Market
Energy Analytics and Software
GCC Well Testing Services Market
Energy Analytics and Software
Carbon and Energy Software Market
Energy Analytics and Software
France Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data in Oil and Gas Market
Energy Analytics and Software
Smart Grid Data Analytics Market
Energy Analytics and Software
Energy As a Service (Eaas) Market
Energy Analytics and Software
Netherlands Big Data Analytics in Energy Market
Energy Analytics and Software
Power System Analysis Software Market
Energy Analytics and Software
Canada Big Data Analytics in Energy Market
Energy Analytics and Software
Digital Energy Platform Market
Energy Analytics and Software
Oil and Gas Data Management Software Market
Energy Analytics and Software
Energy and Utilities Analytics Market
Energy Analytics and Software
Germany Big Data Analytics in Energy Market
Energy Analytics and Software
AI in Energy Market