
 Global Geophysical Services and Equipment Market | 2026-2036
Global Geophysical Services and Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Geophysical Services and Equipment Market Foresight
A shift from single-source seismic acquisition contracts toward multi-vendor project structures is decoupling equipment ownership from survey execution across the upstream sector. Schlumberger Limited leverages its integrated technology platform to bundle processing with hardware deployment. CGG competes through specialized ocean-bottom node manufacturing and imaging software. Fugro anchors its position in marine site characterization, serving offshore wind clients alongside traditional hydrocarbon operators.
Geophysical services and equipment encompass the acquisition, processing, and interpretation of subsurface physical property data using seismic waves, magnetic fields, gravity gradients, and electromagnetic emissions, typically resolving structures from tens of meters to several kilometers depth with frequency ranges of 1–200 Hz for reflection seismic. The primary purpose is to de-risk capital-intensive drilling, construction, and resource extraction decisions by mapping geology ahead of penetration. Seismic survey services dominate value generation due to the capital intensity of source vessels and streamer arrays, while borehole logging commands premium pricing in mature basins where reservoir optimization outweighs greenfield discovery. Ground penetrating radars within equipment type are gaining traction in civil engineering and utility detection, though magnetometers retain their grip on mineral exploration workflows.
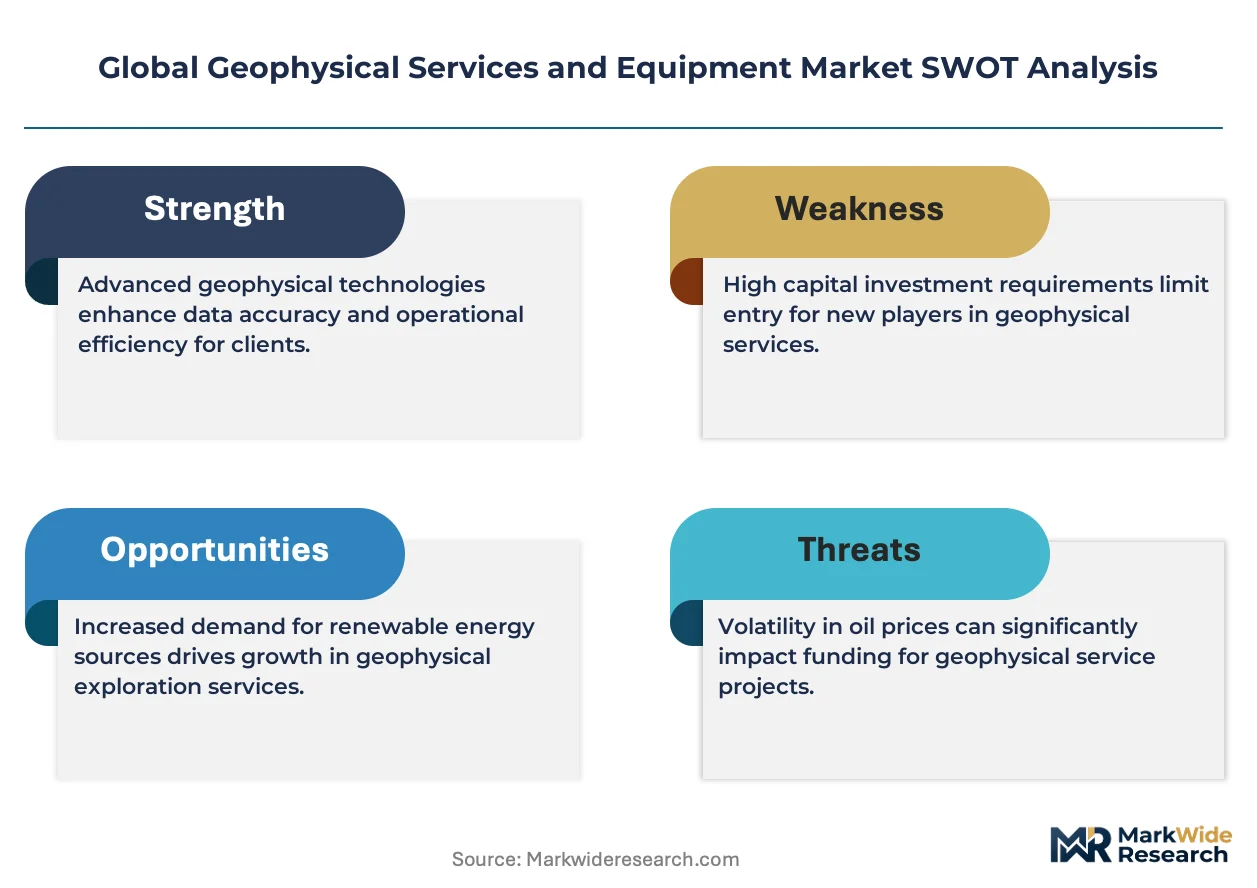
The International Maritime Organization's carbon intensity regulations are reshaping vessel charter economics for marine seismic fleets, while the EU F-Gas Regulation constrains airgun compressor refrigerant choices. Brazil's national petroleum regulator imposes local content requirements that force equipment suppliers to maintain domestic fabrication partnerships or joint ventures. Stakeholders must weigh stranded asset exposure in hydrocarbon-dependent service lines against the capital requirements of pivoting toward offshore wind site investigation and carbon storage monitoring contracts.
Market Dynamics
Marine seismic fleets face a structural squeeze between decarbonization mandates and pre-salt basin demand, forcing operators to retrofit vessels with dual-fuel engines while charter rates absorb compliance premiums. This tension concentrates investment in Brazil and West Africa where contract visibility extends across multi-year campaigns.
Growth Catalysts
- EU Green Deal critical raw material security framework:Accelerated permitting timelines for mineral exploration geophysics across Scandinavia and Iberian Peninsula deposits.
- Offshore wind site investigation demand:Developers in the North Sea and US Atlantic lease areas require high-resolution geophysical surveys for foundation design and cable routing.
- Pre-salt carbonate reservoir characterization:Brazil's national petroleum regulator mandates advanced wide-azimuth seismic for production optimization in deepwater blocks.
Market Restraints
- Specialized vessel supply concentration:Marine seismic fleet ownership clusters among Norwegian and Singapore-based contractors, creating charter rate volatility during demand spikes.
- EU F-Gas Regulation refrigerant constraints:Airgun compressor systems face retrofit costs or replacement timelines as hydrofluorocarbon phase-down tightens.
- Electromagnetic methods for shallow target resolution:Controlled-source electromagnetics substitutes for seismic in certain offshore wind and groundwater applications below 500-meter depth.
Strategic Opportunities
- Carbon capture and storage monitoring contracts:North Sea and Gulf Coast injection projects require time-lapse seismic and microseismic arrays for plume tracking and containment verification.
- India's critical mineral exploration push:Lithium and rare earth reconnaissance in Rajasthan and Karnataka creates demand for airborne gravity and magnetic surveys.
- Ocean-bottom node manufacturing scale-up:Convergence of autonomous underwater vehicle deployment with nodal retrieval systems reduces crewed vessel dependency in remote basins.
Industry Challenges
- Geophysicist and seismic processor talent scarcity:Academic programs in quantitative earth sciences have not kept pace with retirement waves in Houston and London service hubs.
- Multi-vendor project integration complexity:Decoupled equipment ownership from survey execution creates data format standardization and liability allocation friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Geophysical Services and Equipment Market |
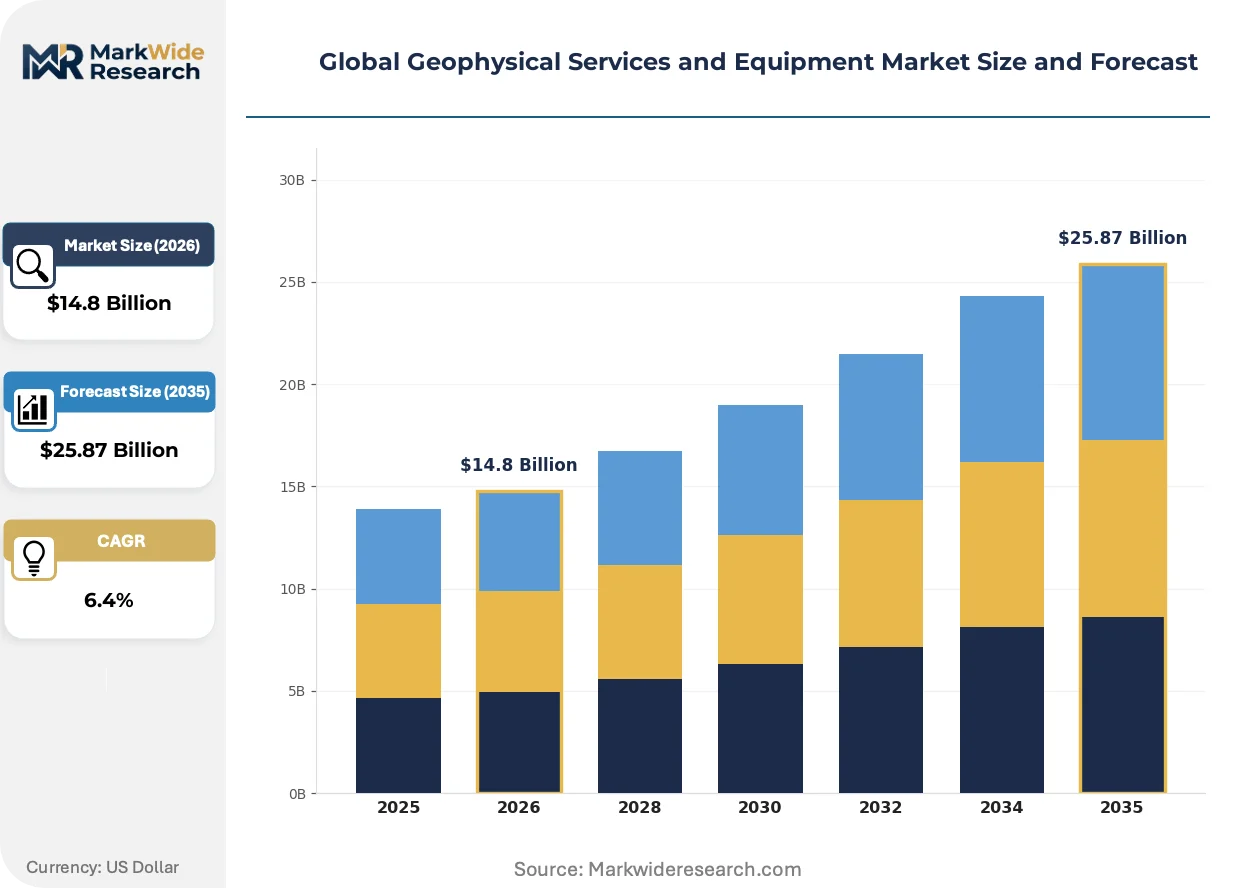
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Seismic Survey, Magnetic Survey, Gravity Survey, Electromagnetic Survey, Borehole Logging Equipment Type: Seismographs, Magnetometers, Gravimeters, Ground Penetrating Radars, Resistivity Meters Application: Mineral Exploration, Oil & Gas Exploration, Environmental Assessments, Engineering Surveys, Archaeological Investigations End User: Exploration Companies, Research Institutions, Civil Engineering Firms, Government Agencies, Environmental Consultants |
| Companies Covered | Schlumberger Limited, CGG, PGS, TGS, Halliburton, Fugro, Sercel SA, ION Geophysical, Ramboll Group A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Geophysical Services and Equipment Market Shifts & Advancements
Computational advances and sensor miniaturization are compressing survey timelines while expanding the addressable depth range for subsurface imaging. These developments favor integrated service providers capable of bundling acquisition with real-time processing.
Autonomous ocean-bottom node retrieval systems are automating deployment and recovery cycles in deepwater environments. Offshore wind developers and carbon storage operators are adopting these platforms for repeatability-critical monitoring arrays. The technology is automating crew reduction on support vessels and enabling operations in weather windows previously considered unworkable.
REACH and RoHS substance restrictions are tightening traceability requirements for electronic components in marine seismic streamers and downhole logging tools. Manufacturers must document hazardous substance content across complex multi-tier supply chains. European-flagged vessels and North Sea operators face the most immediate compliance deadlines, driving consolidation among component suppliers.
Buyers are unbundling after-sales processing from acquisition contracts, creating standalone imaging software subscriptions. National oil companies in Brazil and West Africa increasingly retain seismic data ownership while licensing processing algorithms. This pattern is most pronounced where data rooms and farm-out negotiations require rapid, in-house interpretation turnaround.
Global Geophysical Services and Equipment Market Segmentation
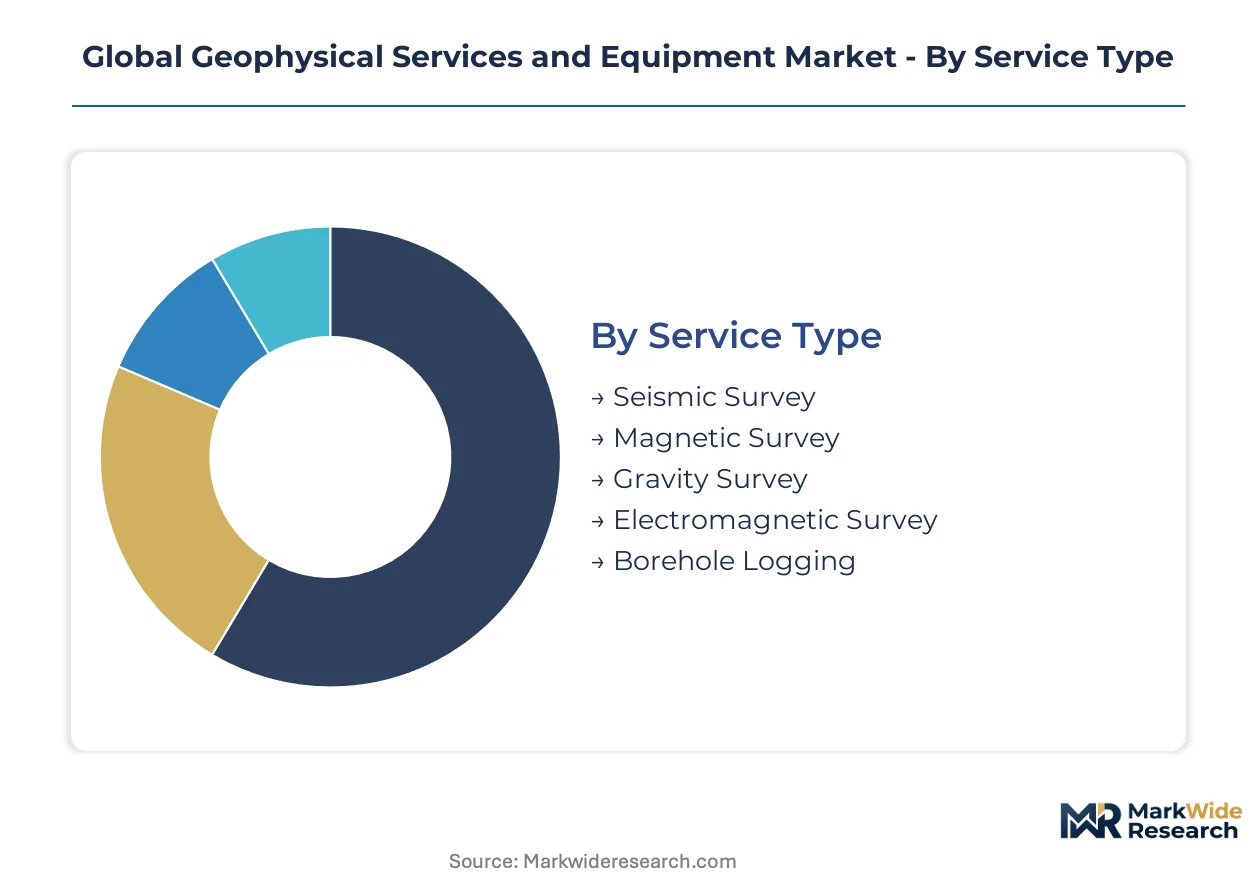
Segmentation in geophysical services and equipment reflects divergent capital intensity, technical sophistication, and regulatory exposure across subsurface imaging workflows. Buyers select service and equipment combinations based on target depth, resolution requirements, and permitting constraints rather than cost alone.
Service Type:
Oil and gas operators prioritize contract structures that decouple acquisition from processing, while mineral explorers favor integrated survey-to-interpretation packages to accelerate permitting timelines.
- Seismic Survey:Reflection and refraction methods using controlled energy sources resolve structures from tens of meters to several kilometers depth. Brazil's national petroleum regulator mandates wide-azimuth marine seismic for pre-salt carbonate characterization, sustaining multi-year vessel charter demand.
- Borehole Logging:Wireline and logging-while-drilling tools measure formation properties within drilled holes, commanding premium pricing in mature basins where reservoir optimization outweighs greenfield discovery. North Sea operators deploy time-lapse logging for carbon storage plume verification.
- Magnetic Survey:Airborne and ground magnetometers detect variations in Earth's magnetic field to identify iron ore and basement structure.
- Gravity Survey:Gravimeters measure minute gravitational field variations to map density contrasts in sedimentary basins and salt domes.
- Electromagnetic Survey:Controlled-source and natural-field methods image conductive ore bodies and groundwater systems.
Seismic survey services lead volumes today; borehole logging is gaining share fastest in carbon storage monitoring contracts.
Equipment Type:
Equipment procurement patterns split between asset-heavy seismic vessel operators and lightweight mineral exploration contractors with rapid deployment requirements.
- Seismographs:Digital recording systems with 24-bit resolution and multi-channel capacity capture reflected energy from airgun, vibroseis, or explosive sources. Marine streamer arrays and ocean-bottom nodes dominate capital allocation in Brazil and West Africa pre-salt campaigns.
- Ground Penetrating Radars:Electromagnetic pulse systems operating between 10 MHz and 2.5 GHz resolve shallow subsurface features for utility detection and civil engineering. EU infrastructure stimulus programs in Germany and France are accelerating unit deployment for trenchless construction verification.
- Magnetometers:Proton precession and optically pumped sensors measure magnetic field intensity for mineral reconnaissance.
- Gravimeters:Spring-based and superconducting instruments detect density variations for basin modeling and geothermal exploration.
- Resistivity Meters:Direct-current and induced polarization systems map groundwater contamination and ore body geometry.
Seismographs anchor equipment revenue; ground penetrating radars are climbing the fastest on civil engineering demand.
Application:
Application selection determines regulatory jurisdiction, with hydrocarbon exploration facing carbon intensity constraints and mineral projects benefiting from critical raw material security frameworks.
- Oil & Gas Exploration:2D, 3D, and 4D seismic programs de-risk drilling decisions in frontier and mature basins. The International Maritime Organization's carbon intensity regulations are reshaping vessel charter economics for marine seismic fleets serving this segment.
- Mineral Exploration:Gravity, magnetic, and electromagnetic surveys target lithium, rare earth, and copper deposits. The EU Green Deal's critical raw material security framework is accelerating permitting timelines for geophysical work across Scandinavia and Iberian Peninsula deposits.
- Environmental Assessments:Geophysical methods characterize contaminated sites, landfill boundaries, and groundwater systems.
- Engineering Surveys:Shallow seismic and ground penetrating radar support foundation design and tunnel alignment.
- Archaeological Investigations:Magnetometry and ground penetrating radar map subsurface cultural heritage features.
Oil and gas exploration leads application volumes today; mineral exploration is expanding most quickly on energy transition metal demand.
End User:
End user procurement sophistication varies from national oil companies with captive processing capabilities to environmental consultants outsourcing entire survey workflows.
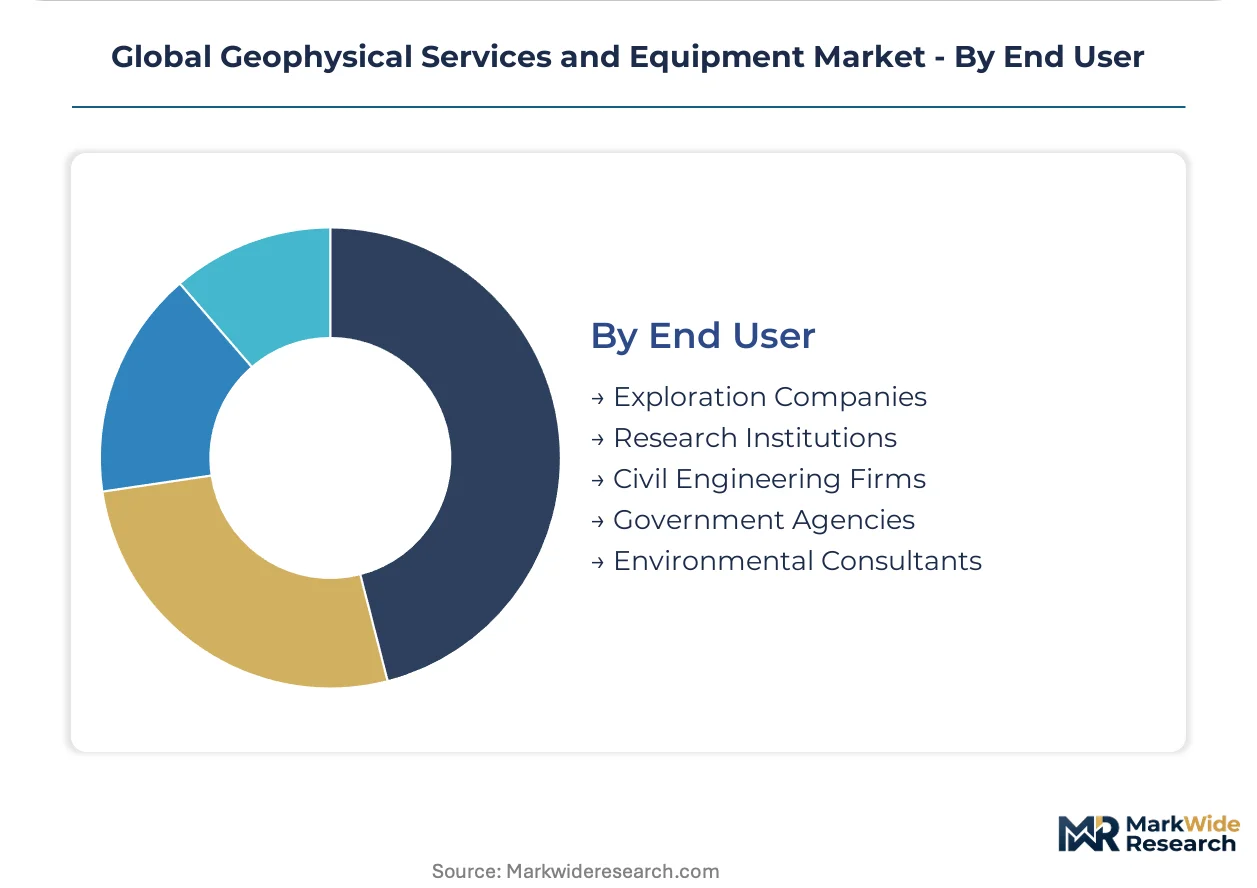
- Exploration Companies:International and national oil companies, plus mining majors, contract integrated seismic and logging services. Brazil's Petrobras and West African national operators increasingly retain seismic data ownership while licensing processing algorithms.
- Government Agencies:Geological surveys and environmental regulators commission baseline studies and resource assessments. India's critical mineral exploration push in Rajasthan and Karnataka is creating demand for airborne gravity and magnetic surveys.
- Research Institutions:Universities and government laboratories advance acquisition and imaging methodologies.
- Civil Engineering Firms:Infrastructure developers require geotechnical site characterization for transportation and energy projects.
- Environmental Consultants:Specialist firms deliver contaminated site assessment and remediation monitoring.
Exploration companies dominate end user spending; government agencies are gaining share fastest on critical mineral security mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's pre-salt basins anchor investment intensity across marine seismic services, with vessel charter rates absorbing dual-fuel retrofit premiums under International Maritime Organization carbon intensity rules.
Brazil
Petrobras mandates wide-azimuth seismic for carbonate reservoir characterization in deepwater Santos Basin blocks. The national petroleum regulator enforces local content requirements that force equipment suppliers into domestic fabrication joint ventures. Rio de Janeiro clusters marine seismic vessel operations and ocean-bottom node manufacturing partnerships.
Norway
North Sea offshore wind developers require high-resolution geophysical surveys for foundation design and cable routing across lease areas. The country's national petroleum regulator imposes strict carbon storage monitoring protocols for injection projects using time-lapse seismic arrays. Stavanger concentrates marine seismic fleet ownership and autonomous underwater vehicle deployment expertise.
United States
Gulf Coast carbon capture operators contract microseismic monitoring for plume tracking and containment verification in saline formations. EPA underground injection control regulations mandate continuous seismic surveillance for Class VI well permits. Houston hosts seismic data processing centers serving Permian Basin operators and carbon storage developers.
India
Geological Survey of India commissions airborne gravity and magnetic surveys for lithium and rare earth reconnaissance in Rajasthan and Karnataka hard rock terrains. The national critical mineral exploration push accelerates permitting timelines for geophysical contractors under PLI scheme incentives. Hyderabad clusters government survey agencies and private airborne geophysics operators.
Germany
Utility detection and trenchless construction verification drives ground penetrating radar deployment across federal infrastructure stimulus corridors. REACH and RoHS substance restrictions tighten traceability requirements for electronic components in seismic streamers and logging tools. Munich anchors environmental geophysics consultancies serving contaminated site characterization contracts.
Global Geophysical Services and Equipment Market Competitive Landscape
Global majors compete with regional champions across technology integration depth, with vessel ownership and software bundling determining contract capture rates. Market structure tilts toward consolidated equipment manufacturing alongside fragmented service execution. Two strategic archetypes dominate: integrated technology platforms combining hardware with processing algorithms, and specialized marine site characterization operators pivoting toward offshore wind clients. Competitive moves concentrate on autonomous ocean-bottom node deployment systems and carbon storage monitoring contract capture.
Among integrated service providers, Schlumberger Limited occupies a position exemplifying bundled processing with hardware deployment archetypes. CGG sits within the specialized manufacturing tier, representing ocean-bottom node production and imaging software specialists. Fugro anchors the marine site characterization segment, exemplifying operators serving offshore wind developers alongside traditional hydrocarbon clients.
| Leading Market Players |
|---|
| Schlumberger Limited |
| CGG |
| PGS |
| TGS |
| Halliburton |
| Fugro |
| Sercel SA |
| ION Geophysical |
| Ramboll Group A/S |
| Others |
Supply & Pricing Matrix
Pre-salt basin operators in Brazil demanding multi-year vessel charter visibility with dual-fuel compliance specifications are forcing marine seismic contractors to absorb retrofit premiums into contract rates. This procurement preference concentrates pricing power among Norwegian and Singapore-based fleet owners while squeezing margins for equipment suppliers locked into domestic fabrication joint ventures.
Pricing Analysis
Input-cost pass-through from dual-fuel engine retrofits and F-Gas Regulation compressor refrigerant replacements is compressing margins for marine seismic vessel operators. Project-based contract structures dominate, with price differentiation anchored in vessel specification tier and real-time processing bundling. Pricing pressure stems from buyer unbundling of acquisition and processing services. National oil companies in Brazil and West Africa exhibit lowest price sensitivity due to regulatory mandates; mineral exploration contractors in India and Scandinavia face acute cost compression.
Supply Chain Analysis
Brazil's national petroleum regulator local content requirements are reshaping sourcing patterns, compelling ocean-bottom node manufacturers to establish Rio de Janeiro fabrication partnerships. Component supply concentrates in Norway, Singapore, and the United States, with specialized vessel hull construction drawing from South Korean shipyards. Raw material dependencies span high-tensile steel alloys, marine-grade electronics, and hydrofluorocarbon refrigerants. Single-source vulnerability runs through Norwegian-controlled seismic streamer arrays. Distribution runs through integrated service providers bundling hardware deployment with processing algorithms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on autonomous deployment systems collapsing crewed vessel days and carbon storage monitoring contracts commanding premium pricing for repeatability-critical arrays.
For Market Incumbents: Cement defensible positions by deepening backward integration into ocean-bottom node manufacturing and securing multi-year carbon storage monitoring contracts with North Sea operators. Controlled-source electromagnetics substitution below 500-meter depth threatens seismic survey incumbents; counter by accelerating autonomous underwater vehicle retrieval system deployment to reduce crewed vessel dependency. For New Entrants and Emerging Players: Autonomous ocean-bottom node deployment technology offers a technology-first wedge into offshore wind site investigation contracts in the North Sea and US Atlantic lease areas. White-space targets include India's critical mineral exploration push in Rajasthan and Karnataka, and Gulf Coast carbon capture microseismic monitoring. A processing-algorithm licensing go-to-market angle bypasses capital-intensive vessel ownership barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized marine site characterization operators pivoting toward offshore wind clients alongside carbon storage developers. Long-term viability favors asset-light imaging software subscriptions over vessel-heavy integrated service providers. The signal to watch is national oil company data ownership retention patterns accelerating standalone processing algorithm demand.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Node Deployment Scale-Up | Reduces crewed vessel dependency in Brazil pre-salt and North Sea wind campaigns. |
| Carbon Storage Monitoring Contract Capture | Locks in multi-year revenue from North Sea and Gulf Coast injection verification mandates. |
| Processing Algorithm Licensing Pivot | Captures value as Petrobras and West African NOCs retain seismic data ownership. |
| Domestic Fabrication Joint Venture | Satisfies Brazil local content requirements for equipment suppliers bidding pre-salt contracts. |
| Dual-Fuel Vessel Retrofit Completion | Preserves charter rate competitiveness under International Maritime Organization carbon intensity rules. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with seismic vessel operators, petroleum geoscience directors at national oil companies, offshore wind project developers, and carbon storage site characterization leads with secondary validation. Secondary sources encompassed International Maritime Organization regulatory filings, EU F-Gas Regulation implementation guidance, Brazil national petroleum regulator local content decrees, and customs data on marine seismic equipment trade flows. Bottom-up project pipeline analysis and top-down market sizing triangulated volume estimates.
Segment-weighting approaches distributed value across service type, equipment category, application, and end user dimensions, with additional granularity on vessel specification tier and processing bundling intensity. CAGRs derived from trend extrapolation against named project backlogs and regulatory mandate timelines. Industry-specific forecast inputs included Petrobras pre-salt seismic commitment schedules and EU Green Deal critical raw material exploration permit acceleration targets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to International Maritime Organization carbon intensity regulation stringency and electromagnetic method substitution rates in shallow-target applications. Forecasts reflect documented assumptions on vessel retrofit completion timelines and national oil company procurement pattern continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
France Big Data Analytics in Energy Market
Energy Analytics and Software
Oil and Gas Data Management Software Market
Energy Analytics and Software
US Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data in Oil and Gas Market
Energy Analytics and Software
Utility Analytics and Energy Analytics Market
Energy Analytics and Software
Solar Digitalization Platform Market
Energy Analytics and Software
Germany Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data Analytics in Energy Market
Energy Analytics and Software
Asia-Pacific Big Data Analytics in Energy Market
Energy Analytics and Software
Building Energy Simulation Software Market
Energy Analytics and Software
Industrial Energy Monitoring Market
Energy Analytics and Software
Netherlands Big Data Analytics in Energy Market
Energy Analytics and Software
Europe Big Data Analytics in Energy Market
Energy Analytics and Software
Energy and Utilities Analytics Market
Energy Analytics and Software
Canada Big Data Analytics in Energy Market
Energy Analytics and Software
Energy As a Service (Eaas) Market