
 Europe Big Data Analytics in Energy Market | 2026-2036
Europe Big Data Analytics in Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Big Data Analytics in Energy Market Analytics
Platform licensing revenue is tilting from perpetual software contracts toward recurring cloud subscriptions across European energy majors. Siemens Aktiengesellschaft leverages deep domain expertise in grid automation to anchor its analytics stack within TSO procurement frameworks. SAP SE competes through native integration with enterprise resource planning environments already deployed at major utilities. Microsoft Corporation extends its position via Azure-hosted energy data lakes that aggregate SCADA, meteorological, and market price feeds at scale.
Europe Big Data Analytics in Energy encompasses the computational processing, statistical modeling, and machine-learning inference applied to heterogeneous energy datasets—including sub-second SCADA telemetry, satellite-derived irradiance measurements, and wholesale market clearing prices—to optimize asset performance, demand response, and infrastructure investment decisions. Predictive Analytics solutions dominate current procurement volumes as grid operators prioritize outage prevention and renewable intermittency forecasting over retrospective reporting. Cloud-based Deployment Models capture the fastest expansion trajectory, though Hybrid architectures retain structural importance where national cybersecurity requirements mandate on-premise data sovereignty for critical infrastructure.
The EU AI Act, CE marking for digital energy products, and GDPR's data governance requirements collectively shape platform architecture decisions and vendor qualification pathways across member states. EMA and national regulators like Germany's BNetzA enforce transparency standards for algorithmic dispatch recommendations that influence wholesale market outcomes. Stakeholders must monitor evolving conformity assessment procedures under the EU Green Deal's digitalization pillar to anticipate procurement specification changes before tender publication cycles lock in vendor selection criteria.
Market Dynamics
Grid operators across Germany and France now embed predictive models into daily dispatch operations, compressing decision cycles from hours to minutes as renewable intermittency strains legacy infrastructure.
Growth Catalysts
- EU Green Deal digitalization mandates:Platform procurement timelines accelerate as member states transpose binding decarbonization targets into tender specifications.
- Utility-scale renewable integration:Iberian solar parks and Nordic offshore wind clusters generate terabyte-scale telemetry requiring real-time inference.
- SCADA-to-cloud pipeline maturation:Edge computing architectures now stream sub-second sensor data into centralized lakes without breaching operational technology security perimeters.
Market Restraints
- GDPR data sovereignty requirements:Cross-border model training faces structural friction where personal data and critical infrastructure telemetry intermingle.
- Legacy SCADA vendor concentration:Proprietary protocols from dominant automation suppliers create integration bottlenecks for third-party analytics layers.
- Cybersecurity certification costs:CE marking for digital energy products under evolving NIS2 directives inflates platform qualification budgets.
Strategic Opportunities
- Hybrid cloud architectures:National cybersecurity requirements mandating on-premise sovereignty for critical infrastructure create specialized deployment niches.
- Algorithmic dispatch transparency:BNetzA and peer regulators enforce explainable AI standards, opening compliance-as-a-service revenue streams.
- Cross-border flexibility markets:Nordic corridor TSOs pilot federated learning across jurisdictions to optimize interconnector utilization.
Industry Challenges
- Power systems data science talent scarcity:Grid operators compete with fintech and autonomous vehicle sectors for practitioners fluent in both electrical engineering and probabilistic forecasting.
- Model retraining infrastructure capex:Continuous learning pipelines for weather-to-generation forecasting demand GPU clusters that strain regulated utility balance sheets.
- Interoperability standard fragmentation:IEC 61850 implementations vary across French, German, and Spanish TSOs, complicating pan-European platform rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Big Data Analytics in Energy Market |
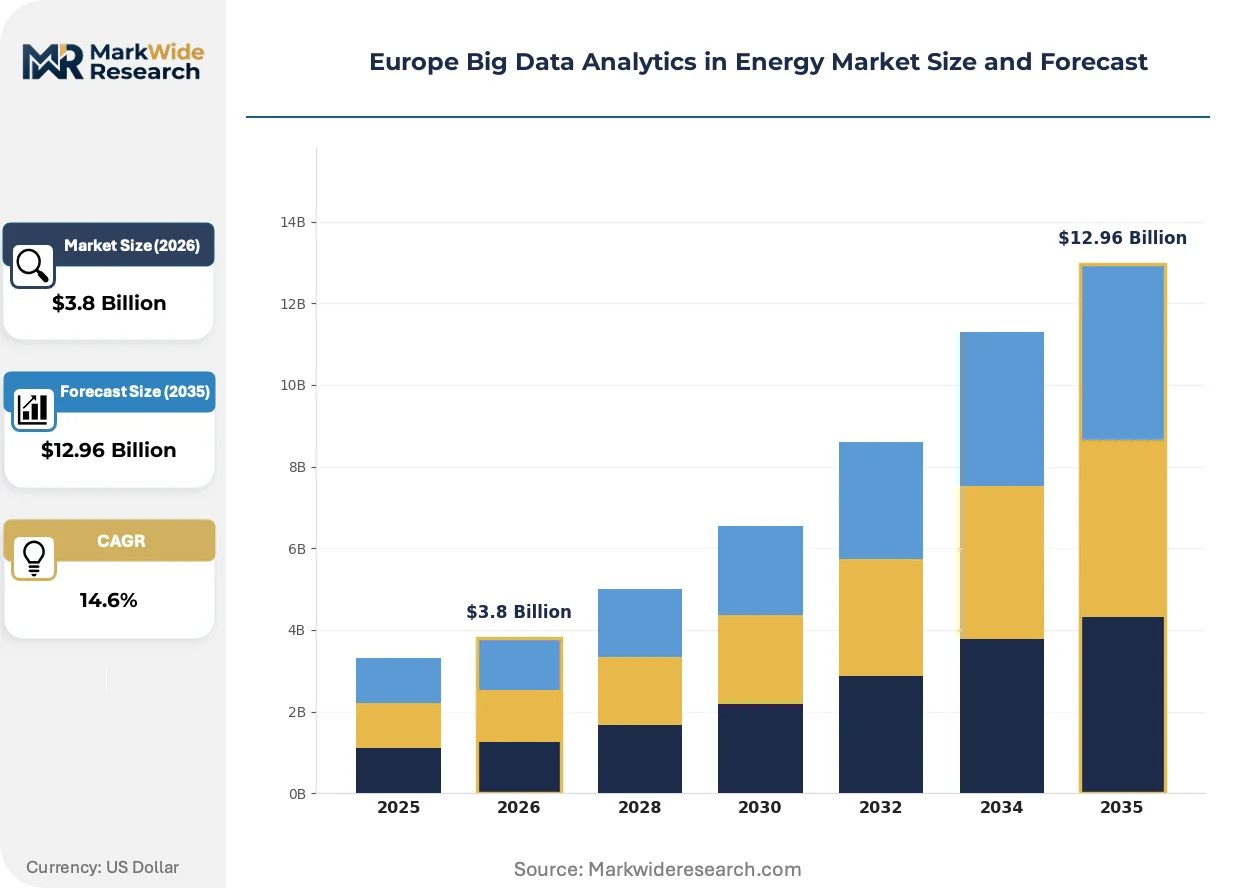
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Predictive Analytics, Real-time Analytics, Visualization Tools, Reporting Tools Deployment Model: On-premise, Cloud-based, Hybrid, Edge Computing End User: Utilities, Oil & Gas Companies, Renewable Energy Firms, Industrial Sector Application Area: Energy Management, Load Forecasting, Asset Optimization, Supply Chain Management |
| Companies Covered | Siemens Aktiengesellschaft, Oracle Corporation, IBM, DNV, Accenture plc, SAP SE, Schneider Electric, C3.ai, Microsoft Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Big Data Analytics in Energy Market Evolving Landscape
Foundation models trained on multi-year SCADA archives are rendering obsolete rule-based dispatch heuristics, compressing the competitive window for vendors lacking proprietary energy datasets.
Digital twin architectures that fuse meteorological forecasts with asset degradation curves are rendering obsolete scheduled maintenance calendars. Transmission system operators in Denmark and the Netherlands deploy these twins for transformer fleet optimization, slashing unplanned outage rates. The structural consequence is a shift from time-based to condition-based capital allocation across high-voltage infrastructure.
The EU AI Act's risk classification framework for critical infrastructure algorithms tightens conformity assessment pathways for predictive dispatch systems. Grid operators must now document training data provenance and model drift monitoring protocols before regulatory approval. German TSOs have responded by embedding compliance documentation into DevOps pipelines, treating algorithmic transparency as a first-class engineering requirement.
Subscription-based platform licensing displaces perpetual software contracts as European energy majors prioritize operational expenditure flexibility over capital ownership. Procurement teams at Iberian utilities now structure multi-year agreements with usage-scaled pricing, transferring model performance risk to vendors. This shift is most visible in renewable asset management, where operators demand uptime guarantees tied to forecast accuracy thresholds rather than software feature checklists.
Europe Big Data Analytics in Energy Market Segmentation
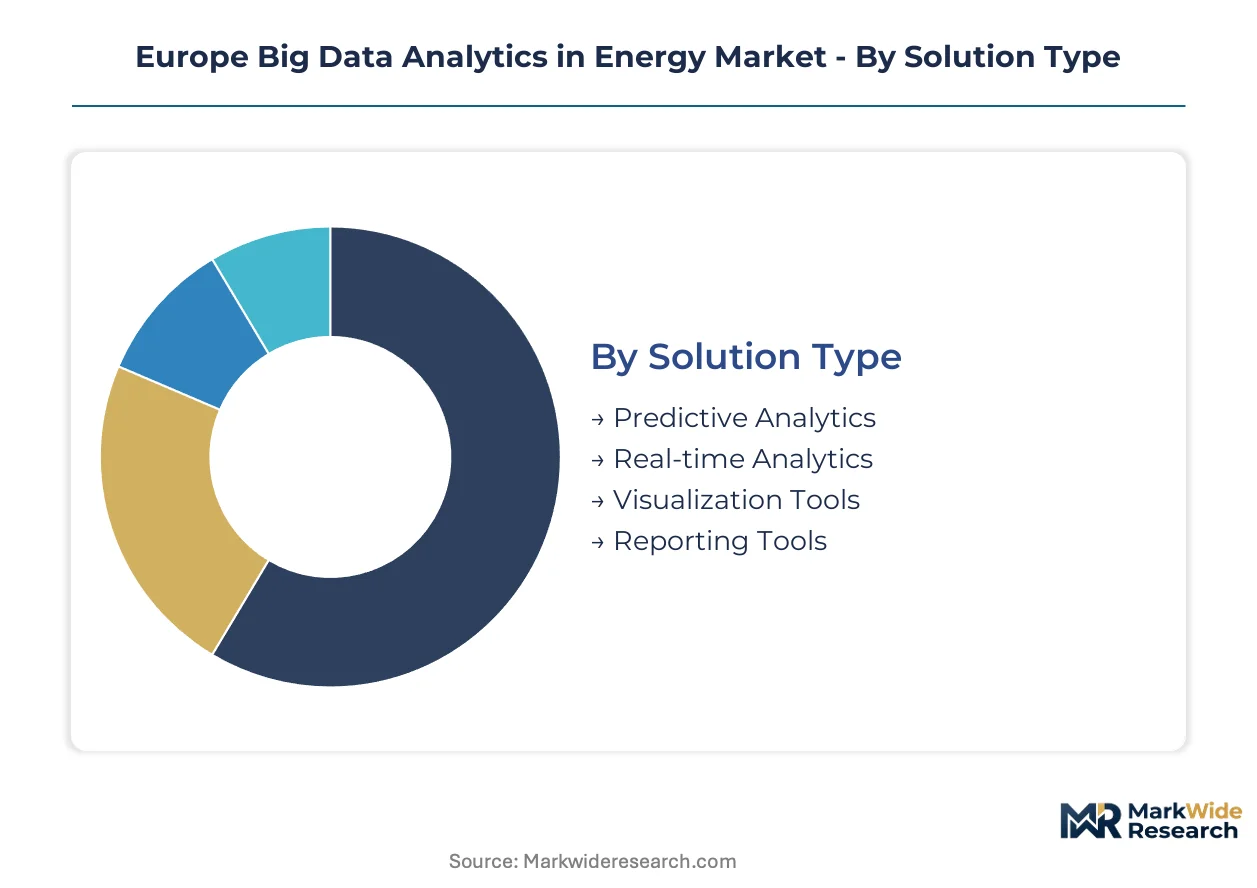
Segmentation reveals how procurement cycles and technical requirements diverge across European energy stakeholders. Grid operators, oil majors, and renewable developers each impose distinct performance specifications on analytics platforms.
Solution Type:
Predictive Analytics contracts refresh every 18-24 months as model drift accelerates, while Reporting Tools installations persist for 7-10 years with minimal vendor turnover.
- Predictive Analytics:Machine-learning inference engines that forecast renewable generation, equipment failure, and price volatility from multi-source telemetry. Iberian solar operators and Nordic offshore wind developers drive procurement as intermittency management becomes mission-critical.
- Real-time Analytics:Sub-second stream processing architectures that ingest SCADA, meteorological, and market data for immediate dispatch decisions. German and French TSOs embed these systems into control room operations where latency tolerance has compressed from minutes to seconds.
- Visualization Tools:Dashboard and geospatial interfaces rendering complex grid states for human operators. These layers integrate with existing control systems across European utilities.
- Reporting Tools:Retrospective analytics generating compliance documentation and regulatory filings. Long procurement cycles reflect stable EU CSRD and national utility disclosure requirements.
Reporting Tools dominate installed base. Predictive Analytics is where expansion concentrates.
Deployment Model:
Cost tiers stratify sharply: Edge Computing deployments command premium pricing for specialized hardware, while Cloud-based subscriptions minimize upfront capital outlay for mid-size utilities.
- Cloud-based:Centralized data lakes hosted on hyperscale infrastructure aggregating telemetry across distributed assets. Nordic corridor utilities favor this model for cross-border flexibility market participation where data pooling accelerates model training.
- Hybrid:Architectures partitioning sensitive operational data on-premise while pushing anonymized training workloads to cloud environments. German TSOs mandate this configuration under BNetzA cybersecurity guidelines for critical infrastructure.
- On-premise:Fully sovereign installations satisfying national data residency requirements. French nuclear operators and Spanish grid infrastructure maintain these deployments for air-gapped security.
- Edge Computing:Distributed inference nodes processing telemetry at substation or turbine level before cloud transmission. Iberian solar farms deploy these to reduce bandwidth costs across remote installations.
On-premise systems dominate installed base. Cloud-based deployment is climbing the fastest.
End User:
Customer sophistication varies: Utilities demand enterprise-grade integration, while Renewable Energy Firms prioritize lightweight, rapidly deployable SaaS layers.
- Utilities:Vertically integrated power companies operating generation, transmission, and retail functions. These buyers specify deep ERP integration and multi-decade vendor relationships.
- Renewable Energy Firms:Independent power producers and asset managers optimizing solar, wind, and storage portfolios. These operators drive demand for forecast-accuracy-based pricing models.
- Oil & Gas Companies:Integrated majors and downstream operators applying analytics to refining optimization and retail network management. European majors leverage existing data science teams from trading operations.
- Industrial Sector:Energy-intensive manufacturers managing consumption, on-site generation, and demand response participation. German automotive and chemical clusters represent concentrated demand.
Utilities dominate installed base. Renewable Energy Firms is where expansion concentrates.
Application Area:
Maturity gradients separate established use cases from emerging priorities: Load Forecasting carries decades of institutional knowledge, while Supply Chain Management analytics remain nascent in European energy.
- Load Forecasting:Statistical and machine-learning models predicting electricity consumption patterns across temporal horizons. TSOs in Germany, France, and the Netherlands deploy these for day-ahead market bidding and real-time balancing.
- Asset Optimization:Condition monitoring and predictive maintenance extending equipment life cycles. Danish and Dutch transmission operators apply digital twins to transformer fleet management.
- Energy Management:Enterprise-wide consumption analytics identifying efficiency opportunities and curtailment strategies. Industrial facilities across the Benelux region implement these for EU ETS compliance.
- Supply Chain Management:Analytics applied to fuel procurement, spare parts inventory, and logistics optimization. This application remains underdeveloped relative to operational analytics in European energy.
Load Forecasting dominates installed base. Asset Optimization is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across European buyers. Nordic utilities prioritize forecast accuracy over licensing costs, while Southern European independents squeeze vendors on subscription terms. German TSOs absorb premium pricing for cybersecurity-certified deployments.
Germany
Transmission system operators drive demand for predictive dispatch systems as renewable penetration exceeds fifty percent of generation mix. BNetzA enforces strict algorithmic transparency standards under national implementation of the EU AI Act. The industrial corridor between Cologne and Frankfurt hosts concentrated procurement activity from RWE and E.ON data science divisions.
France
Nuclear operators and grid manager RTE seek analytics platforms integrating legacy SCADA with weather forecasting pipelines. ANSM cybersecurity requirements for critical infrastructure create compliance barriers for non-EU vendors. The Paris-Saclay research cluster spawns specialized startups focused on transformer digital twin technology.
Spain
Iberian solar developers dominate procurement for edge-computing inference nodes across remote installations. National data residency regulations under GDPR implementation restrict cross-border model training. The Extremadura and Andalusia solar belt generates concentrated demand for terabyte-scale telemetry processing.
Netherlands
TenneT and regional operators pilot federated learning architectures for interconnector optimization. CE marking for digital energy products accelerates platform qualification timelines relative to Southern Europe. The Rotterdam port energy cluster applies analytics to industrial demand response and hydrogen integration planning.
Denmark
Energinet leads deployment of foundation models trained on multi-year SCADA archives for offshore wind forecasting. National cybersecurity requirements mandate hybrid cloud architectures with on-premise sovereignty for critical dispatch algorithms. The Copenhagen-Aarhus corridor concentrates vendor development centers serving Nordic TSOs.
Europe Big Data Analytics in Energy Market Competitive Landscape
Capability concentration sits with industrial automation specialists; scale advantage sits with hyperscale cloud providers. The market structures around three tiers: legacy industrial software houses with deep grid domain expertise, enterprise technology conglomerates leveraging existing utility relationships, and vertical-focused AI platforms betting on energy-specific model performance. Dominant competitive moves include strategic partnerships between automation vendors and cloud infrastructure providers, plus portfolio diversification into compliance-as-a-service offerings.
Among Germany-based industrial conglomerates, Siemens Aktiengesellschaft anchors the automation-heritage tier with embedded positions in TSO procurement frameworks. SAP SE exemplifies the enterprise software vector, competing through native integration with resource planning environments already deployed at major utilities. Microsoft Corporation occupies the hyperscale position, extending cloud infrastructure into energy-specific data lake architectures. These three represent distinct strategic postures rather than direct substitutability.
| Leading Market Players |
|---|
| Siemens Aktiengesellschaft |
| Oracle Corporation |
| IBM |
| DNV |
| Accenture plc |
| SAP SE |
| Schneider Electric |
| C3.ai |
| Microsoft Corporation |
| Others |
Value Network & Pricing Analysis
Overcapacity in cloud infrastructure across Ireland and the Netherlands compresses hyperscaler pricing for energy data lakes while simultaneously pressuring on-premise hardware vendors to extend financing terms. This utilization asymmetry rewards buyers with hybrid deployment preferences and squeezes margins for edge-computing specialists serving Iberian solar developers.
Pricing Analysis
After-sales revenue from model retraining services and compliance documentation subscriptions now drives lifetime value for predictive analytics vendors. Subscription-based SaaS tiers dominate procurement, with price differentiation anchored in cybersecurity certification grade and forecast accuracy guarantees. Cost compression in standard-tier cloud subscriptions intensifies as Microsoft Azure and Amazon Web Services compete for utility data lake contracts. Renewable energy firms exhibit highest price sensitivity, while German TSOs absorb premium pricing for BNetzA-certified on-premise deployments.
Supply Chain Analysis
Extended payment terms from Nordic TSOs now reach 90-120 days, forcing mid-tier analytics vendors to secure supply-chain finance facilities. Component sourcing concentrates on Germany for industrial automation hardware, Ireland for hyperscale cloud infrastructure, and Taiwan for GPU accelerators. Raw material dependencies span silicon wafers, rare earth elements for magnetic sensors, and specialized optical fiber for substation networking. Single-source vulnerability in NVIDIA GPU supply chains threatens continuous learning pipeline deployments. Distribution runs through systems integrators like Accenture and specialized energy consultancies rather than direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Big Data Analytics in Energy Market represents high-growth disruption as foundation models trained on multi-year SCADA archives displace rule-based dispatch heuristics. The EU AI Act's risk classification framework for critical infrastructure algorithms accelerates this inflection by mandating compliance documentation as a first-class engineering requirement.
For Market Incumbents: Insulate embedded positions in TSO procurement frameworks by deepening backward integration into proprietary energy datasets and accelerating CE marking for digital energy products under evolving NIS2 directives. Siemens Aktiengesellschaft and SAP SE must counter emerging vertical-focused AI platforms by embedding algorithmic transparency documentation directly into DevOps pipelines before regulatory approval cycles lock in vendor selection criteria. For New Entrants and Emerging Players: Mid-market renewable energy firms in Spain and Portugal represent the most penetrable entry point, as these operators prioritize lightweight SaaS layers with forecast-accuracy-based pricing models over enterprise-grade ERP integration. Nordic corridor flexibility markets offer secondary white-space opportunity through federated learning architectures for interconnector optimization. A direct-to-TSO sales motion emphasizing rapid deployment timelines outperforms channel-dependent approaches. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertical-focused AI platforms with proprietary SCADA training data and established BNetzA compliance pathways. Long-term viability across the analysis window favors acquisition targets combining energy-specific model performance with hybrid cloud deployment expertise. Watch for inflection signals in CE marking acceleration timelines under the EU Green Deal's digitalization pillar.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance-as-a-Service Expansion | EU AI Act documentation requirements open recurring revenue streams from German TSOs. |
| Federated Learning Partnerships | Nordic corridor TSOs pilot cross-border model training to optimize interconnector utilization. |
| Edge Computing Hardware Integration | Iberian solar developers demand distributed inference nodes for remote telemetry processing. |
| SCADA Data Lake Consolidation | Azure-hosted aggregation of meteorological and market price feeds scales platform stickiness. |
| Digital Twin Certification | CE marking for transformer fleet optimization tools accelerates platform qualification timelines. |
Research Methodology
A standing panel of utility planning officers, IPP project developers, grid operators, and EPC contractors provided ongoing calibration across the primary research phase. This practitioner input combined with secondary validation from EIA data, IEA reports, FERC filings, and European project development databases. Bottom-up segmentation modeling and top-down macroeconomic anchoring ensured triangulation integrity.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing for regulatory acceleration under the EU AI Act and cybersecurity mandate evolution. Segmentation dimensions modeled include deployment model, organization size, solution type, application area, and regional grid type. CAGRs derived from installed base growth rates, replacement cycle compression, and new procurement velocity. Forecast inputs incorporated renewable penetration trajectories and SCADA-to-cloud pipeline maturation timelines.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments, energy commodity volatility, or EU funding disbursement schedules would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation timelines and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
GCC Well Testing Services Market
Energy Analytics and Software
Energy Intelligence Solutions Market
Energy Analytics and Software
Global Geophysical Services and Equipment Market
Energy Analytics and Software
Global Wind Turbine Condition Monitoring System Market
Energy Analytics and Software
China Big Data Analytics in Energy Market
Energy Analytics and Software
Spain Big Data Analytics in Energy Market
Energy Analytics and Software
Solar Digitalization Platform Market
Energy Analytics and Software
US Big Data Analytics in Energy Market
Energy Analytics and Software
Automated Power Generation Dispatch Software Market
Energy Analytics and Software
AI in Energy Market
Energy Analytics and Software
Carbon and Energy Software Market
Energy Analytics and Software
Energy As a Service (Eaas) Market
Energy Analytics and Software
Building Energy Simulation Software Market
Energy Analytics and Software
Smart Grid Data Analytics Market
Energy Analytics and Software
Utility Analytics and Energy Analytics Market
Energy Analytics and Software
Germany Big Data Analytics in Energy Market