
 GCC Well Testing Services Market | 2026-2036
GCC Well Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Well Testing Services Market Intelligence
Capital-intensity divergence between integrated majors and regional specialists is reorganizing competitive tiers across the GCC well testing landscape. Schlumberger Limited leverages its modular testing platforms to anchor premium contracts in Qatar's high-pressure sour gas developments. Halliburton Company sustains scale advantages through captive manufacturing of downhole tools at its Abu Dhabi service base. MB Petroleum Services competes on rapid mobilization timelines for smaller operators in Oman's mature block concessions.
GCC well testing services encompass surface and subsurface diagnostic procedures that measure reservoir pressure, fluid composition, and flow rates to characterize hydrocarbon-bearing formations. Downhole formation testers typically acquire fluid samples at pressures exceeding ten thousand psi while real-time data transmission enables immediate decision-making on completion design. Production testing currently occupies the largest revenue share among service types as operators prioritize reservoir management over greenfield exploration. Wireline technology leads deployment frequency due to its proven reliability in high-temperature carbonate reservoirs prevalent across Saudi Arabia and Kuwait. Advanced well testing represents the fastest-expanding segment as digital twins and automated surface sampling reduce rig time and personnel exposure.
Saudi Arabia's national regulator mandates well integrity certification under its petroleum standards framework, while the UAE's environmental authority enforces zero-flare protocols that directly shape testing equipment specifications. The International Association of Oil and Gas Producers maintains recommended practices for well test design that most GCC national oil companies adopt as contractual baselines. Stakeholders must monitor how carbon intensity disclosure requirements from European offtakers reshape procurement criteria for testing service awards.
Market Dynamics
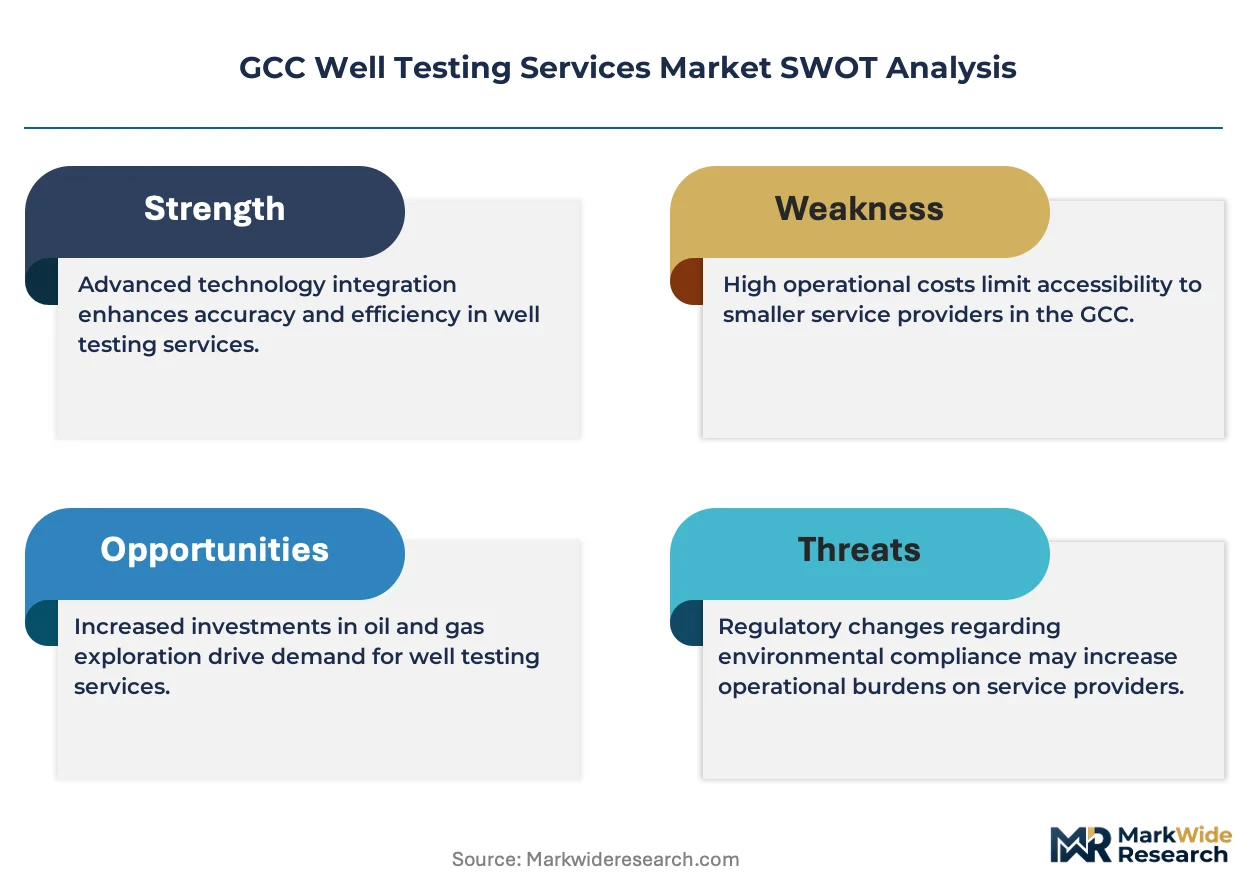
Zero-flare mandates from UAE environmental authorities and Saudi Arabia's petroleum standards framework are compressing testing windows while elevating equipment specifications, forcing service providers to reconfigure surface facility footprints.
Growth Catalysts
- North Field expansion corridors:Qatar's phased sour gas development program requires high-pressure diagnostic capabilities that only specialized testing fleets can deliver.
- Closed-loop testing systems:Tightening environmental discharge regulations across Gulf jurisdictions mandate zero-surface-discharge operations during well cleanup.
- Digital twin integration:Real-time reservoir characterization through automated surface sampling reduces rig time and accelerates completion decisions.
Market Restraints
- Specialized alloy supply concentration:Corrosion-resistant metallurgy for sour gas applications sources predominantly from European and East Asian foundries, creating procurement bottlenecks.
- High-temperature electronics limitation:Downhole gauge reliability degrades above 175°C in Saudi Arabia's deep carbonate reservoirs, forcing redundant tool strings.
- SFDA certification timelines:Saudi Arabia's equipment approval processes extend field deployment schedules by 8-12 weeks for new technology introductions.
Strategic Opportunities
- Oman mature block concessions:Smaller operators in Dhofar and central Oman lack captive testing capabilities, creating service outsourcing potential.
- Wireline-conveyed formation testing:Convergence of modular sampling tools with electric line telemetry enables single-trip reservoir evaluation.
- Carbon intensity disclosure requirements:European offtaker procurement criteria now prioritize low-emission testing methodologies, rewarding early adopters.
Industry Challenges
- Reservoir engineer scarcity:Interpretation of high-pressure sour gas data requires specialized expertise concentrated among a limited pool of regional specialists.
- Legacy SCADA integration:Automated surface sampling systems must interface with 1990s-era wellhead control architectures common in Kuwait's Burgan field.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Well Testing Services Market |
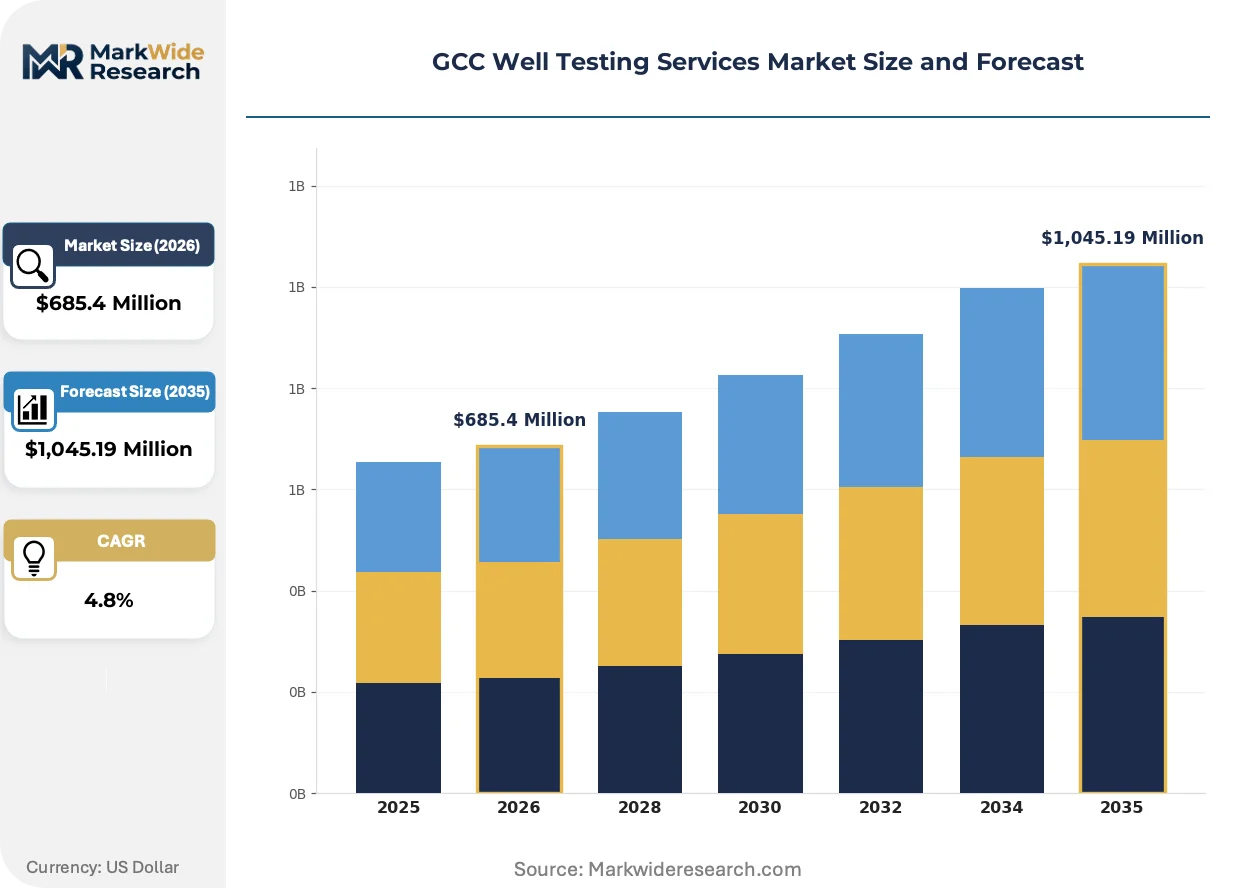
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Production Testing, Formation Testing, Well Integrity Testing, Advanced Well Testing Technology: Wireline, Slickline, Coiled Tubing, Modular End User: Oil & Gas Operators, Service Companies, Government Agencies, Research Institutions Application: Exploration, Development, Enhanced Oil Recovery, Decommissioning |
| Companies Covered | Schlumberger Limited, Halliburton Company, Weatherford International Ltd., SGS Middle East, Energy Services Limited Co., MB Petroleum Services, Gulf Energy, Middle East Oilfield Services, Tetra Technologies Inc., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Well Testing Services Market Strategic Shifts & Innovations
Digital automation and regulatory stringency are compressing traditional testing workflows while fragmenting the service provider landscape into equipment specialists and data analytics platforms.
Modular surface testing units are fragmenting the conventional integrated service model. These containerized systems separate fluid separation, metering, and flare recovery into interchangeable skids. National oil companies in Saudi Arabia and Qatar now specify platform-agnostic interfaces that allow mixing components from competing vendors. The technology is fragmenting procurement decisions away from bundled contracts toward component-level sourcing.
Zero-flare protocols enforced by UAE's environmental authority now mandate closed-loop surface systems for all new well completions. This regulatory shift eliminates conventional open-pit burning during cleanup operations. Testing contractors must now deploy vapor recovery units and temporary pipeline connections, compressing allowable surface footprint by 60 percent in offshore Abu Dhabi developments.
Performance-based contracting is displacing day-rate pricing for reservoir characterization services. Saudi Aramco and ADNOC now tie service payments to delivered data quality metrics rather than rig time. Kuwait Oil Company has piloted this model in its heavy oil trials, with penalties for failed sample acquisition and bonuses for real-time decision support. The shift concentrates vendor selection on diagnostic accuracy rather than equipment inventory scale.
GCC Well Testing Services Market Segmentation
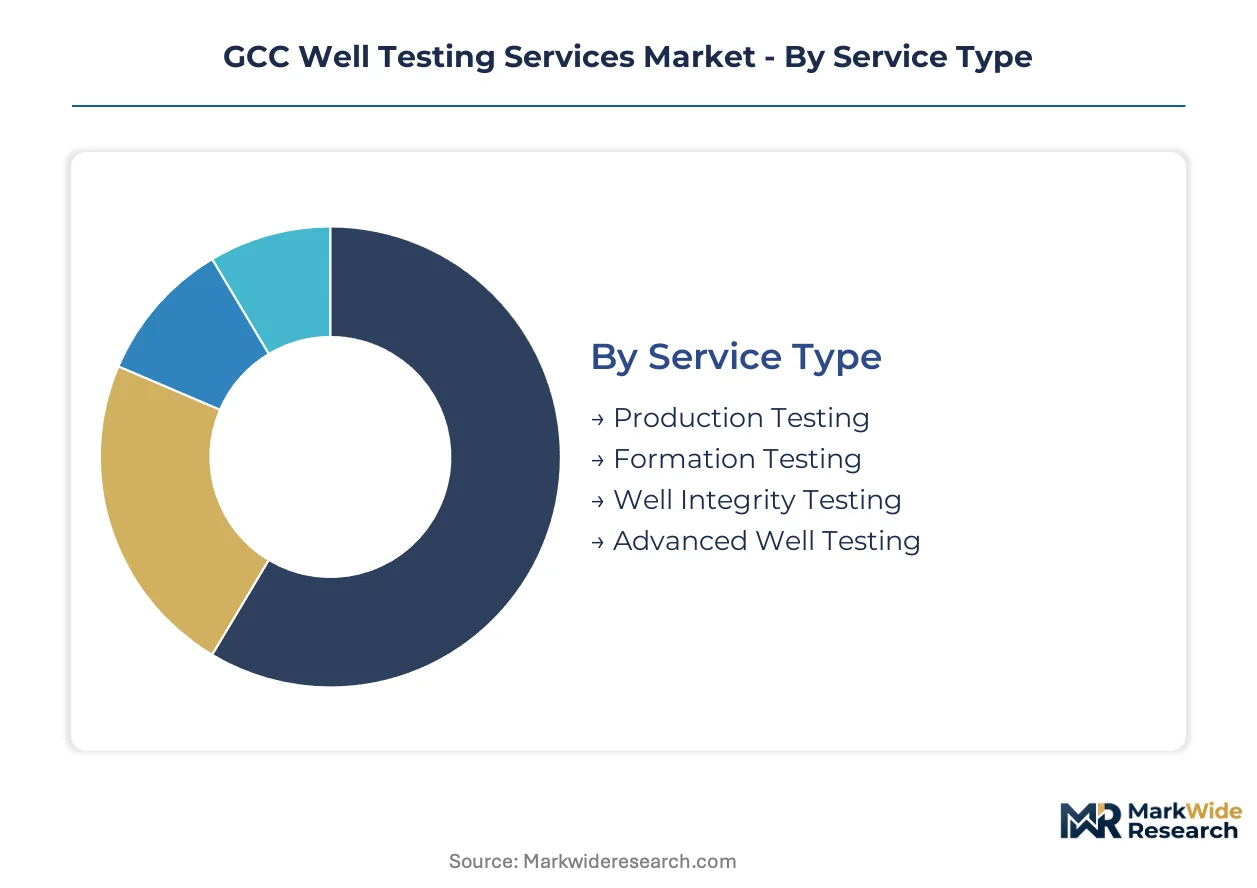
Service procurement patterns across GCC national oil companies fragment along operational maturity and reservoir complexity lines. Contracting structures diverge between bundled integrated services and component-level sourcing, with channel selection directly tied to field development stage and regulatory jurisdiction.
Service Type:
Channel mix varies sharply by service complexity, with integrated majors favoring bundled contracts for high-pressure applications while independent operators source discrete services through regional specialists.
- Production Testing:Surface and subsurface diagnostic procedures measure reservoir pressure, fluid composition, and flow rates during active hydrocarbon extraction. Demand concentrates in Saudi Arabia's onshore mature fields where reservoir management priorities eclipse greenfield exploration. Operators prioritize real-time data transmission for immediate completion design decisions.
- Advanced Well Testing:Digital twin integration and automated surface sampling reduce rig time and personnel exposure in high-risk environments. Qatar's North Field expansion corridors drive adoption as sour gas developments demand specialized diagnostic capabilities. SFDA certification timelines for new technology introductions extend deployment schedules.
- Formation Testing:Downhole fluid sampling at extreme pressures characterizes hydrocarbon-bearing formations prior to completion.
- Well Integrity Testing:Regulatory-mandated verification under Saudi Arabia's petroleum standards framework and UAE zero-flare protocols.
By volume, Production Testing leads. By growth pace, Advanced Well Testing is ahead.
Technology:
Cost tier differentiation separates premium electric-line systems from economy mechanical alternatives, with procurement decisions hinging on temperature tolerance and telemetry requirements.
- Wireline:Electric-conveyed tools deploy sensors and samplers with real-time surface telemetry. Deployment frequency leads in Saudi Arabia and Kuwait's high-temperature carbonate reservoirs where proven reliability outweighs cost premiums. Redundant tool strings compensate for electronics degradation above 175°C.
- Modular:Containerized surface systems separate fluid separation, metering, and flare recovery into interchangeable skids. Abu Dhabi offshore developments specify platform-agnostic interfaces that allow mixing vendor components, compressing allowable surface footprint by 60 percent under zero-flare mandates.
- Slickline:Mechanical wireline for gauge setting and basic well intervention without electrical telemetry.
- Coiled Tubing:Continuous pipe deployment for live well intervention and cleanup operations.
Wireline commands the largest installed base. Modular platforms are expanding most quickly.
End User:
Customer type determines contract scale and duration, with national oil companies locking in multi-year frameworks while independents seek spot-market flexibility.
- Oil & Gas Operators:Saudi Aramco and ADNOC anchor demand through performance-based contracting tied to data quality metrics rather than day-rates. Procurement criteria increasingly weight carbon intensity disclosure requirements from European offtakers.
- Service Companies:Halliburton's Abu Dhabi manufacturing base and Schlumberger's modular platforms sustain captive capabilities. Regional specialists compete on rapid mobilization for smaller operators in Oman's Dhofar and central mature block concessions.
- Government Agencies:Regulatory oversight and standards enforcement through petroleum frameworks and environmental authorities.
- Research Institutions:Collaborative reservoir characterization for unconventional resource evaluation.
Oil & Gas Operators dominate contract value. Service Companies show the steepest capability expansion.
Application:
Field life-cycle stage dictates service intensity, with development-phase testing consuming multiple rig days per well versus streamlined decommissioning protocols.
- Development:Comprehensive reservoir characterization during field construction and production ramp-up. Kuwait Oil Company pilots performance-based models in heavy oil trials with penalties for failed sample acquisition. North Field expansion corridors require high-pressure diagnostic capabilities.
- Enhanced Oil Recovery:Injection monitoring and production optimization in mature assets. Burgan field legacy SCADA integration challenges automated surface sampling deployment.
- Exploration:Initial reservoir evaluation prior to commercial development decisions.
- Decommissioning:Final integrity verification and abandonment certification.
Development absorbs the greatest service volume. Enhanced Oil Recovery is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Qatar's North Field expansion show lowest price elasticity due to sour gas complexity, while Oman's smaller operators in Dhofar exhibit highest sensitivity to mobilization costs and day-rate variations across service tiers.
Saudi Arabia
Saudi Aramco's upstream investment program drives demand for reservoir management services in mature onshore fields. SFDA certification timelines extend equipment deployment schedules by 8-12 weeks for new technology introductions. The Eastern Province concentrates testing activity where high-temperature carbonate reservoirs require redundant downhole gauge strings.
United Arab Emirates
ADNOC's zero-flare mandates compress allowable surface footprints by 60 percent in offshore Abu Dhabi developments. MOHAP environmental authority enforcement shapes closed-loop testing equipment specifications across all new well completions. Dubai-based procurement hubs coordinate multi-vendor component sourcing for modular platform contracts.
Qatar
North Field expansion corridors require high-pressure diagnostic capabilities that only specialized sour gas testing fleets can deliver. QatarEnergy's phased development program locks in multi-year performance-based contracting frameworks. Ras Laffan Industrial City anchors equipment staging and technical specialist concentration for extreme-pressure applications.
Kuwait
Kuwait Oil Company pilots performance-based models in heavy oil trials with penalties for failed sample acquisition. Legacy SCADA integration challenges from 1990s-era wellhead architectures complicate automated surface sampling deployment. The Burgan field absorbs significant wireline-conveyed formation testing volume for enhanced oil recovery monitoring.
Oman
Smaller operators in Dhofar and central mature block concessions lack captive testing capabilities, creating outsourcing demand for rapid mobilization specialists. Petroleum Development Oman concession terms favor spot-market flexibility over long-term framework agreements. Muscat service corridors connect to remote well sites with compressed logistics timelines.
GCC Well Testing Services Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier that competes on mobilization speed and regional relationship depth. The upper tier commands premium pricing through captive manufacturing and modular platform scale, while mid-tier players differentiate through zero-flare compliance specialization and sour gas metallurgy expertise. Two dominant competitive moves are reshaping positioning: performance-based contracting that ties payments to data quality metrics rather than day-rates, and backward integration into corrosion-resistant alloy sourcing to bypass European and East Asian foundry bottlenecks.
Within the integrated services tier, Schlumberger Limited and Halliburton Company occupy positions defined by modular platform scale and captive manufacturing footprints. Schlumberger exemplifies the premium-tier archetype through its Qatar-focused high-pressure sour gas capabilities. Halliburton anchors scale advantages via its Abu Dhabi service base. MB Petroleum Services represents the rapid-mobilization specialist archetype competing for smaller operator contracts in Oman's concession landscape.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Weatherford International Ltd. |
| SGS Middle East |
| Energy Services Limited Co. |
| MB Petroleum Services |
| Gulf Energy |
| Middle East Oilfield Services |
| Tetra Technologies Inc. |
| Others |
Cost & Logistics Intelligence
Captive manufacturing footprints at Abu Dhabi service bases and Ras Laffan equipment staging yards create scale economies that compress unit costs for integrated majors while elevating price floors for regional specialists competing on rapid mobilization. These capacity concentrations concentrate procurement leverage among national oil companies in Saudi Arabia and Qatar, forcing mid-tier providers to absorb margin compression or exit sour gas certification tiers entirely.
Pricing Analysis
After-sales revenue from extended service contracts and spare parts provisioning drives lifetime value for testing fleet operators more than initial equipment deployment. Performance-based contracting now dominates Saudi Aramco and ADNOC procurement, with payments tied to data quality metrics rather than day-rates, compressing margins for accuracy-deficient vendors. Price differentiation separates premium-tier providers with SFDA-certified high-pressure capabilities from economy-tier mechanical slickline operators. Pricing pressure stems from European offtaker carbon intensity disclosure requirements that prioritize low-emission methodologies. Smaller operators in Oman's Dhofar concessions exhibit highest price sensitivity, while QatarEnergy's North Field expansion shows lowest elasticity due to irreplaceable sour gas expertise requirements.
Supply Chain Analysis
Strategic stockpiling of corrosion-resistant alloy components dominates inventory strategy over just-in-time approaches, given European and East Asian foundry lead time volatility for sour gas metallurgy. Geographic supply concentration centers on Germany and Japan for high-temperature electronics, Italy and South Korea for specialized valve assemblies, and domestic UAE fabrication for modular skid integration. Raw material dependencies include nickel-based superalloys, ceramic pressure transducers, and fluoropolymer seal compounds. Single-source vulnerability from concentrated European foundry capacity for hydrogen sulfide-resistant components creates structural supply risk. Distribution runs through Dubai-based procurement hubs coordinating multi-vendor component sourcing for Abu Dhabi offshore developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: SFDA certification timelines and UAE zero-flare mandates create switching costs that lock national oil companies into proven vendor relationships, raising barriers for unqualified entrants.
For Market Incumbents: Consolidate market position by deepening backward integration into corrosion-resistant alloy sourcing to bypass European foundry bottlenecks, and expand captive manufacturing capacity at Abu Dhabi service bases to capture Qatar's North Field expansion volume. Performance-based contracting from Saudi Aramco threatens margin stability for accuracy-deficient competitors, creating acquisition opportunities among distressed regional specialists.
For New Entrants and Emerging Players: Differentiate on zero-flare compliance specialization for UAE environmental authority mandates, targeting the gap between integrated majors and economy-tier mechanical providers. Oman's Dhofar and central mature block concessions offer the most penetrable geography, where smaller operators lack captive testing capabilities and prioritize rapid mobilization over brand prestige. A go-to-market angle anchored in modular platform interoperability addresses national oil company preferences for component-level sourcing.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among providers with multi-year performance-based frameworks at QatarEnergy and Saudi Aramco, suggesting long-term viability through the analysis window. Acquisition targets should prioritize regional specialists with established SFDA certification and sour gas metallurgy expertise rather than undifferentiated mechanical service providers. The signal to watch is European offtaker procurement criteria evolution, where carbon intensity disclosure thresholds crossing specified levels would accelerate low-emission testing methodology adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Sourcing | Captive supply of corrosion-resistant metallurgy bypasses European foundry bottlenecks for sour gas applications. |
| Modular Platform Certification | Platform-agnostic interfaces align with Saudi Aramco and ADNOC component-level procurement preferences. |
| Zero-Flare Technology Deployment | Closed-loop surface systems satisfy UAE MOHAP environmental mandates and European offtaker carbon criteria. |
| Performance-Based Contracting Capability | Data-quality payment structures secure multi-year frameworks with QatarEnergy's North Field expansion. |
| Rapid Mobilization Network Expansion | Muscat service corridors capture outsourcing demand from Oman's Dhofar concession operators. |
Research Approach
Cross-validation between executive interviews at national oil company procurement divisions and secondary analysis of petroleum standards frameworks anchors the qualitative findings in this study. Primary fieldwork encompassed reservoir engineering directors, well testing service managers, regulatory compliance officers at SFDA and MOHAP, and equipment procurement leads at integrated service companies. Secondary sources included Saudi petroleum standards documentation, UAE environmental authority discharge protocols, QatarEnergy tender disclosures, and International Association of Oil and Gas Producers recommended practices. Bottom-up segmentation modeling triangulated against top-down national production forecasts ensures methodological robustness.
Sensitivity analysis around hydrocarbon price trajectories and regulatory enforcement stringency shapes the forecast framework across the analysis window. Segmentation dimensions modeled encompass service type complexity tiers, technology deployment modes, end-user contract scale, and application life-cycle stages. CAGRs derive from equipment fleet utilization rates, national upstream investment program announcements, and adoption curves for digital twin integration. Industry-specific forecast inputs include SFDA certification pipeline volumes and North Field expansion phase scheduling.
The analysis sits within stated boundaries; outcomes outside sustained Brent price assumptions or accelerated zero-flare mandate enforcement would require recalibration. Forecasts reflect documented assumptions regarding national oil company capital allocation priorities and technology adoption timelines. Revision becomes warranted when European offtaker carbon intensity disclosure thresholds cross implementation thresholds or when sour gas metallurgy supply constraints exceed modeled parameters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Smart Grid Software Market
Energy Analytics and Software
Global Geophysical Services and Equipment Market
Energy Analytics and Software
Europe Big Data Analytics in Energy Market
Energy Analytics and Software
China Big Data Analytics in Energy Market
Energy Analytics and Software
Germany Big Data Analytics in Energy Market
Energy Analytics and Software
Digital Energy Platform Market
Energy Analytics and Software
France Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data Analytics in Power Sector Market
Energy Analytics and Software
Asia-Pacific Big Data Analytics in Energy Market
Energy Analytics and Software
Power System Analysis Software Market
Energy Analytics and Software
Big Data in Oil and Gas Market
Energy Analytics and Software
Australia Big Data Analytics in Energy Market
Energy Analytics and Software
Italy Big Data Analytics in Energy Market
Energy Analytics and Software
Industrial Energy Monitoring Market
Energy Analytics and Software
Energy Intelligence Solutions Market
Energy Analytics and Software
Power Monitoring and Control Software Market