
 Oil and Gas Data Management Software Market | 2026-2036
Oil and Gas Data Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Data Management Software Market Analytics
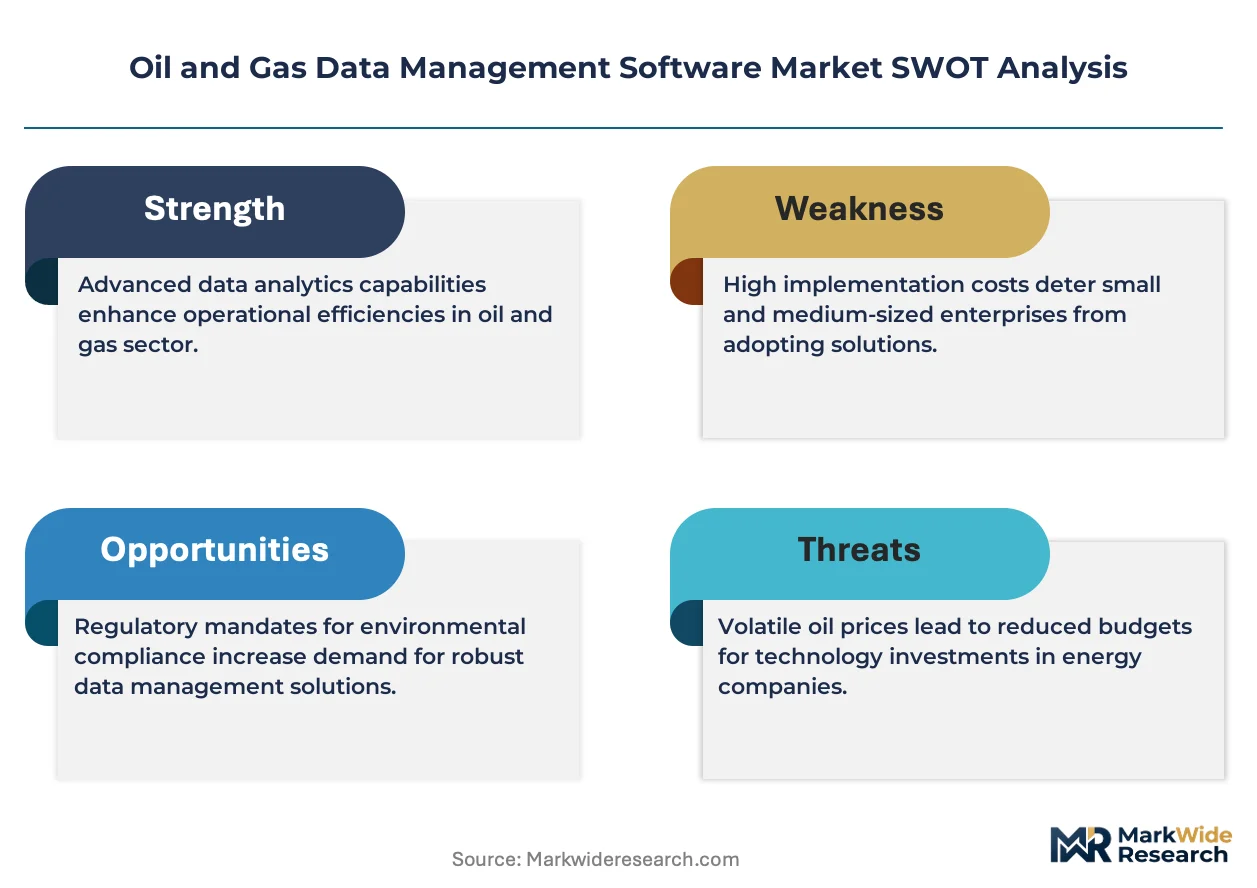
Modular platform bundling is expanding across the oil and gas data management software sector, with vendors packaging analytics engines, visualization layers, and compliance modules into configurable stacks. Schlumberger leverages its subsurface expertise to anchor enterprise deployments across deepwater and unconventional assets. Baker Hughes competes through edge-native architectures that process wellhead telemetry before cloud transmission. IBM sustains large-account relationships by integrating its data fabric with legacy SCADA infrastructure at supermajor operators.
Oil and gas data management software comprises enterprise applications that ingest, validate, store, and analyze hydrocarbon lifecycle information from seismic acquisition through abandonment, typically handling time-series sensor data, spatial coordinates, and regulatory filings in petabyte-scale reservoirs. The software's primary commercial purpose is to reduce non-productive time, optimize recovery factors, and automate compliance reporting across geographically dispersed asset portfolios. Cloud computing deployments now capture the fastest expansion as majors retire on-premises data centers and adopt hybrid architectures for latency-sensitive drilling operations. Analytics tools represent the deepest margin pool, particularly physics-informed machine learning modules that fuse reservoir simulation with real-time production data. Edge computing segments show concentrated growth in offshore environments where satellite bandwidth constraints limit centralized processing.
EPA greenhouse gas reporting mandates and BSEE safety management system requirements are forcing operators to upgrade from spreadsheet-based tracking to automated data governance platforms with audit trails. The EU Green Deal's methane intensity benchmarks and CSRD sustainability disclosure rules are shaping product roadmaps for vendors serving international supermajors with European trading exposure. Stakeholders must monitor how evolving SEC climate disclosure standards interact with existing FDA-equivalent process safety frameworks to determine whether compliance software investments should prioritize emissions quantification or traditional asset integrity monitoring.
Market Dynamics
Upstream operators are consolidating fragmented data silos into unified platforms as EPA methane monitoring mandates and BSEE safety requirements force real-time telemetry integration across wellhead-to-enterprise workflows.
Growth Catalysts
- EPA Subpart W reporting:Mandatory quarterly greenhouse gas disclosures for petroleum systems above 25,000 metric tons CO2e are forcing operators to retire manual spreadsheets in favor of automated data governance platforms with immutable audit trails.
- Permian Basin drilling intensity:Texas and New Mexico operators managing multi-pad development programs require petabyte-scale reservoir analytics to optimize child well spacing and parent-child fracture interference.
- Physics-informed neural networks:These hybrid models fuse traditional reservoir simulation with production time-series data, compressing history-matching cycles from weeks to hours for unconventional asset teams.
Market Restraints
- Cloud egress cost volatility:Seismic survey datasets exceeding 50 terabytes per acquisition trigger unpredictable data transfer charges that erode operating budget certainty for independent producers.
- Satellite bandwidth constraints:Offshore platforms in the Gulf of Mexico face throughput limitations that prevent centralized processing of high-frequency downhole pressure measurements.
- Legacy SCADA protocol fragmentation:Proprietary Modbus and OPC-DA implementations at brownfield sites resist standardization, forcing costly middleware development for each facility integration.
Strategic Opportunities
- Bakken formation digitization:North Dakota operators lag Permian peers in real-time completion analytics, creating whitespace for vendors offering frac stage-by-stage optimization suites.
- EU CSRD alignment:Supermajors with European trading exposure require Scope 3 emissions quantification modules that trace hydrocarbon molecules through midstream and downstream value chains.
- Edge-to-cloud federation:Convergence of containerized microservices with 5G private networks enables sub-second latency for automated well control decisions at remote pad sites.
Industry Challenges
- Petroleum data science talent scarcity:Reservoir engineers with production optimization expertise lack Python and cloud architecture skills, forcing operators to choose between retraining programs and inflated compensation for hybrid profiles.
- Multi-vendor integration complexity:Seismic interpretation platforms from specialized vendors resist API-level interoperability with drilling execution software, fragmenting digital twin implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Data Management Software Market |
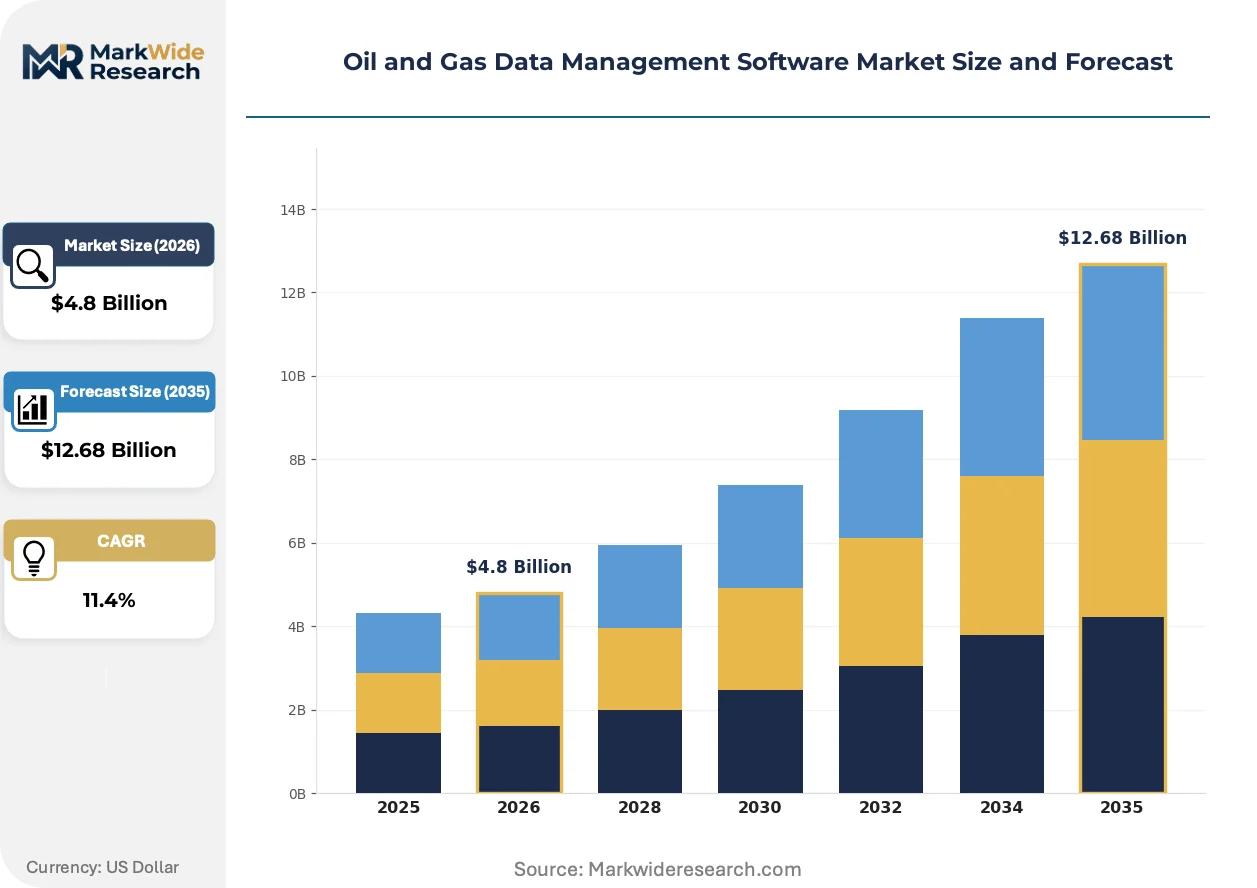
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Integration, Analytics Tools, Reporting Solutions, Visualization Platforms Technology: Cloud Computing, On-Premises, Hybrid Solutions, Edge Computing End User: Exploration Companies, Production Firms, Service Providers, Regulators Application: Data Governance, Asset Management, Risk Assessment, Compliance Monitoring |
| Companies Covered | Schlumberger, Halliburton, Baker Hughes, IBM, SAP, Oracle, AVEVA, AspenTech, Emerson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Data Management Software Market Evolving Landscape
Real-time analytics architectures are compressing decision cycles from reservoir management to regulatory filing, while automated data validation pipelines reduce manual quality assurance overhead across geographically dispersed asset portfolios.
Serverless query engines for time-series sensor data are overtaking traditional relational databases in production operations centers. Apache Arrow-based columnar formats enable sub-second aggregation of decade-long well histories. Majors including BP and Shell have migrated subsurface analytics to these architectures, collapsing data preparation timelines that previously consumed 60% of reservoir study duration.
EPA's November 2024 supplemental proposal to strengthen methane emissions standards is forcing producers to deploy continuous monitoring equipment with 95% detection sensitivity. This hardware mandate cascades into software procurement for alert correlation and repair workflow management. Bakken and Permian operators are prioritizing platforms that integrate optical gas imaging alerts with maintenance management systems to demonstrate prompt repair compliance.
Subscription pricing for analytics modules is displacing perpetual license models among capital-constrained independents. Pioneer Natural Resources and Diamondback Energy have shifted to consumption-based contracts that scale with active well count rather than enterprise-wide commitments. This flexibility appeals to private equity-backed operators in the Anadarko Basin who face portfolio churn through acquisition and divestiture cycles.
Oil and Gas Data Management Software Market Segmentation
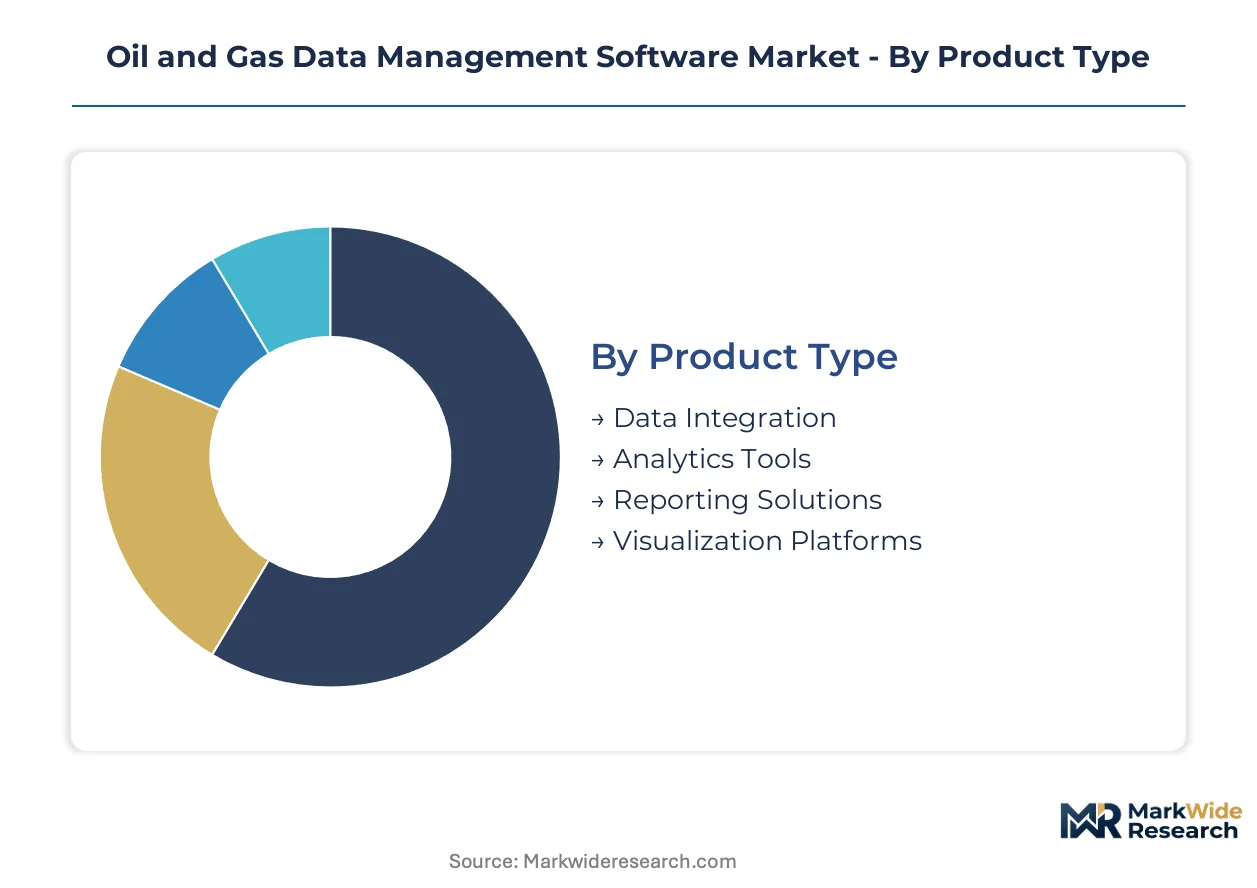
Oil and gas data management software vendors configure product roadmaps around four intersecting axes: technical architecture, functional capability, customer workflow, and regulatory pressure. Segmentation clarity determines whether operators purchase point solutions or integrated platforms.
Product Type:
Functional modules align with the hydrocarbon data lifecycle from ingestion through decision support.
- Data Integration:Middleware pipelines normalize time-series sensor feeds, seismic SEG-Y files, and SCADA protocols into unified schemas. Permian Basin operators demand petabyte-scale reservoir data lakes to optimize multi-pad drilling programs. EPA methane monitoring mandates force real-time telemetry aggregation across wellhead-to-enterprise workflows.
- Analytics Tools:Physics-informed machine learning modules fuse reservoir simulation with production time-series data, compressing history-matching cycles from weeks to hours. Bakken formation operators lag Permian peers in completion analytics, creating whitespace for frac stage-by-stage optimization suites.
- Reporting Solutions:Automated compliance engines generate EPA Subpart W greenhouse gas disclosures with immutable audit trails. Supermajors with European trading exposure require CSRD-aligned sustainability disclosure modules.
- Visualization Platforms:Subsurface interpretation interfaces render 4D seismic and well log correlations for asset team collaboration.
Data Integration leads on scale; Analytics Tools leads on momentum.
Technology:
Deployment architecture determines latency, sovereignty, and total cost of ownership across geographically dispersed assets.
- Cloud Computing:Serverless query engines for time-series data overtake relational databases in production operations centers. BP and Shell have migrated subsurface analytics to Apache Arrow-based columnar formats, collapsing data preparation timelines.
- Hybrid Solutions:Containerized microservices split processing between edge nodes and centralized reservoirs, balancing latency-sensitive drilling decisions with archival scale. 5G private networks enable sub-second automated well control at remote pad sites.
- Edge Computing:Native architectures process wellhead telemetry before satellite transmission, critical for Gulf of Mexico platforms with bandwidth constraints.
- On-Premises:Legacy data centers persist where regulatory data sovereignty or air-gapped security requirements override cloud economics.
Cloud Computing dominates new procurement; Hybrid Solutions is gaining share fastest.
End User:
Customer type dictates feature prioritization, from exploration velocity to regulatory defensibility.
- Production Firms:Operators managing mature assets prioritize recovery factor optimization and automated workover scheduling. Subscription pricing scales with active well count rather than enterprise commitments.
- Exploration Companies:Seismic-heavy workflows demand high-throughput data ingestion for velocity model building and prospect risking.
- Service Providers:Schlumberger and Baker Hughes bundle data management into integrated drilling and completion service contracts.
- Regulators:BSEE and EPA require direct data feeds for safety management system oversight and emissions verification.
Production Firms anchor revenue; Regulators drive compliance module roadmaps.
Application:
Use-case segmentation reflects operational priorities from reservoir stewardship to regulatory defense.
- Compliance Monitoring:Continuous emissions detection equipment with 95% sensitivity triggers software procurement for alert correlation and repair workflow management. Bakken and Permian operators integrate optical gas imaging with maintenance systems.
- Asset Management:Digital twin implementations unify wellbore integrity, surface facility performance, and predictive maintenance schedules.
- Data Governance:Automated validation pipelines reduce manual quality assurance overhead across dispersed portfolios.
- Risk Assessment:Quantified geological, operational, and regulatory risk aggregation supports capital allocation decisions.
Compliance Monitoring commands premium pricing; Asset Management shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum data management software originated in the United States where supermajors pioneered digital subsurface workflows during the 1980s shale revolution. The technology stack migrated through North Sea operators in the 1990s before reaching Middle Eastern national oil companies seeking reservoir optimization at scale.
United States
Permian Basin operators drive petabyte-scale reservoir analytics demand as multi-pad drilling programs optimize child well spacing. EPA Subpart W quarterly greenhouse gas disclosures mandate automated data governance platforms with immutable audit trails. Midland-Odessa clusters anchor deployment density where physics-informed neural networks compress history-matching cycles from weeks to hours.
Norway
Equinor-led deepwater projects demand edge-native architectures processing wellhead telemetry before satellite transmission to overcome North Sea bandwidth constraints. The country's petroleum regulator enforces safety management system requirements forcing real-time telemetry integration across offshore workflows. Stavanger-Bergen corridor hosts specialized vendors serving subsea digital twin implementations.
Saudi Arabia
Aramco's unconventional gas programs in Jafurah Basin require completion analytics suites for frac stage-by-stage optimization. The national hydrocarbon regulator mandates enhanced oil recovery data reporting that automates reservoir performance tracking. Dhahran-Riyadh corridor concentrates procurement decisions for integrated analytics platforms serving megaproject developments.
United Kingdom
North Sea decommissioning obligations drive asset integrity monitoring software procurement as mature fields approach end-of-life. The North Sea Transition Authority enforces emissions reduction targets that require continuous monitoring equipment with automated alert correlation. Aberdeen energy technology cluster hosts vendors specializing in legacy SCADA integration for brownfield facilities.
United Arab Emirates
ADNOC's artificial intelligence program demands data fabric architectures unifying seismic interpretation with production time-series analysis. The Supreme Petroleum Council's digital transformation mandates accelerate cloud migration for latency-sensitive drilling operations. Abu Dhabi-Dubai corridor anchors procurement for supermajor operators with European trading exposure requiring CSRD-aligned sustainability disclosure modules.
Oil and Gas Data Management Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across physics-informed analytics specialization and subsurface domain depth. The vendor base concentrates around three strategic tiers: integrated oilfield service conglomerates bundling software into drilling contracts, enterprise technology incumbents leveraging data fabric relationships, and specialized reservoir analytics boutiques. Dominant competitive moves include strategic partnerships between cloud hyperscalers and domain specialists, plus vertical integration into edge hardware for bandwidth-constrained environments.
Within the integrated service tier, Schlumberger, Halliburton, and Baker Hughes exemplify contrasting architectural philosophies. Schlumberger anchors enterprise deployments through subsurface expertise across deepwater and unconventional assets. Halliburton occupies a position emphasizing completion optimization workflows for North American shale operators. Baker Hughes represents edge-native processing approaches that handle wellhead telemetry before cloud transmission, critical for offshore bandwidth constraints.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton |
| Baker Hughes |
| IBM |
| SAP |
| Oracle |
| AVEVA |
| AspenTech |
| Emerson |
| Others |
Value Network & Pricing Analysis
Physics-informed analytics specialization creates a sharp bifurcation between premium-margin vendors and commodity-margin players, with subsurface domain depth commanding enterprise-wide contracts while standardized data integration modules face subscription pricing compression. This tier divergence manifests in supply chain configurations where premium players backward integrate into edge hardware for bandwidth-constrained offshore environments, while commodity vendors rely on hyperscaler cloud infrastructure with unpredictable egress cost exposure.
Pricing Analysis
Consumption-based subscription models with modular tiering now dominate procurement conversations among capital-constrained independents in the Anadarko Basin and Bakken formation. Price differentiation hinges on physics-informed machine learning capability depth and EPA Subpart W compliance automation certification, with supermajors paying premiums for CSRD-aligned Scope 3 emissions quantification. Pricing pressure stems from hyperscaler cloud egress volatility on petabyte-scale seismic datasets, eroding budget certainty for Permian operators. Private equity-backed independents exhibit highest price sensitivity, while Aramco and ADNOC prioritize performance guarantees over unit economics.
Supply Chain Analysis
Domestic-content mandates in Saudi Arabia's Vision 2030 and the UAE's In-Country Value programs are reshaping vendor sourcing toward Dhahran-Riyadh and Abu Dhabi-Dubai corridor partnerships. Software development concentrates in the United States, Norway, and the United Kingdom, with Stavanger-Bergen and Aberdeen clusters hosting specialized subsurface analytics boutiques. Raw material dependencies center on NVIDIA GPU accelerators for neural network training, Apache Arrow-compatible storage arrays, and 5G private network infrastructure for edge-to-cloud federation. Single-source vulnerability runs through Taiwan-semiconductor-dependent inference hardware. Distribution runs through direct enterprise sales with embedded professional services, supplemented by Schlumberger-Halliburton-Baker Hughes field service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate between EPA-mandated US compliance spending and EU CSRD disclosure requirements, where vendors can repurpose Subpart W automation modules for European supermajor sustainability reporting at minimal incremental R&D cost.
For Market Incumbents: Anchor enterprise deployments through subsurface digital twin implementations that resist disintermediation by hyperscaler data fabric offerings. Defensive consolidation moves should prioritize API-level interoperability acquisitions that bridge seismic interpretation platforms with drilling execution software, countering multi-vendor integration complexity that fragments customer workflows. Capacity addition in the Bakken formation addresses whitespace where North Dakota operators lag Permian peers in real-time completion analytics adoption. For New Entrants and Emerging Players: Cloud hyperscaler partnerships offer the most penetrable channel for physics-informed neural network modules targeting mid-cap independents without legacy SCADA integration burdens. White-space targets include frac stage-by-stage optimization suites for Jafurah Basin unconventional gas programs and optical gas imaging alert correlation platforms for EPA November 2024 methane detection mandates. Go-to-market positioning should emphasize serverless query engine architectures that collapse data preparation timelines for reservoir engineers lacking Python proficiency. For Investors and Strategic Acquirers: Consolidation pressure builds where petroleum data science talent scarcity forces operators toward outsourced analytics subscriptions rather than captive capability building. Long-term viability favors vendors with demonstrated edge-native architectures for Gulf of Mexico bandwidth constraints and hybrid deployment flexibility across on-premises legacy SCADA and cloud-native greenfield sites. Acquisition target archetypes include reservoir analytics boutiques with proven physics-informed machine learning modules and established BSEE safety management system integrations. The signal to watch is Pioneer Natural Resources-style consumption-based contract proliferation, indicating pricing power erosion for perpetual license incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies seismic interpretation with real-time production telemetry for Permian multi-pad optimization. |
| Strategic Partnership | Hyperscaler alliances enable Apache Arrow-based columnar formats that collapse reservoir study timelines. |
| Acquisition of Specialist Firm | Addresses API interoperability gaps between seismic platforms and drilling execution software. |
| Product Launch | CSRD-aligned Scope 3 emissions modules capture European supermajor sustainability disclosure procurement. |
| Geographic Expansion | Bakken formation presence exploits North Dakota lag in completion analytics relative to Permian peers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary conversations with reservoir engineers, IT procurement officers at supermajor operators, petroleum data scientists, EPA compliance leads, and BSEE safety management system auditors with secondary validation against SEC 10-K filings, EIA production databases, IEA energy technology reports, and FERC infrastructure disclosures. Bottom-up well-count and active rig data triangulated against top-down vendor revenue segmentation across deployment models and customer tiers.
Historical reference periods anchored the projection horizon through trailing-edge cloud migration adoption curves and regulatory implementation timelines for EPA methane monitoring mandates. The analytical framework modeled segmentation across deployment architecture, functional capability, customer workflow, and regulatory pressure dimensions, with CAGRs derived from physics-informed analytics penetration rates and edge computing adoption in offshore environments. Forecast inputs incorporated satellite bandwidth constraint severity in the Gulf of Mexico and 5G private network deployment trajectories at remote pad sites.
Revisions become necessary when EPA supplemental methane standards accelerate hardware procurement timelines, hyperscaler cloud pricing restructuring alters total cost of ownership calculations, or EU CSRD disclosure requirements expand to encompass midstream and downstream value chain traceability. Forecasts reflect documented assumptions regarding Permian drilling intensity sustainability and petroleum data science talent pipeline expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Energy As a Service (Eaas) Market
Energy Analytics and Software
Big Data Analytics in Power Sector Market
Energy Analytics and Software
Predictive Maintenance in the Energy Market
Energy Analytics and Software
Building Energy Simulation Software Market
Energy Analytics and Software
Industrial Energy Monitoring Market
Energy Analytics and Software
Digital Energy Platform Market
Energy Analytics and Software
India Big Data Analytics in Energy Market
Energy Analytics and Software
Australia Big Data Analytics in Energy Market
Energy Analytics and Software
Italy Big Data Analytics in Energy Market
Energy Analytics and Software
Power System Analysis Software Market
Energy Analytics and Software
Spain Big Data Analytics in Energy Market
Energy Analytics and Software
Energy and Utilities Analytics Market
Energy Analytics and Software
Oil Condition Monitoring Market
Energy Analytics and Software
Canada Big Data Analytics in Energy Market
Energy Analytics and Software
France Big Data Analytics in Energy Market
Energy Analytics and Software
Africa Big Data Analytics in Energy Market