
 Asia-Pacific Big Data Analytics in Energy Market | 2026-2036
Asia-Pacific Big Data Analytics in Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Big Data Analytics in Energy Market Analytics
Edge-to-cloud data architecture is fragmenting legacy centralized analytics deployments across Asia-Pacific energy networks. IBM leverages its hybrid cloud stack to anchor large-scale utility contracts in Japan and Australia. Siemens dominates industrial IoT integration for thermal power operators, while C3.ai specializes in enterprise AI applications that extend predictive capabilities across generation and transmission assets.
Big data analytics in energy encompasses the collection, processing, and modeling of high-velocity operational datasets from generation assets, grid infrastructure, and consumption endpoints to optimize dispatch decisions, forecast equipment failures, and balance load fluctuations in real time. Predictive Analytics leads product-type revenue as grid operators prioritize outage prevention over retrospective reporting, while Grid Management anchors application demand due to renewable intermittency challenges across archipelagic geographies. Machine Learning underpins technology adoption for pattern recognition in demand forecasting, though Cloud Computing infrastructure grows fastest as national utilities migrate from on-premise legacy systems.
Japan's METI enforces grid code revisions that mandate real-time data transparency from distributed energy resources, while China's MIIT coordinates GB standards for smart meter interoperability that shape procurement specifications for domestic and foreign vendors. India's CEA issues renewable integration directives requiring predictive analytics capabilities for interstate transmission scheduling. Stakeholders must monitor how divergent national data localization requirements reshape cross-border platform deployment and partnership structures.
Market Dynamics
Edge-to-cloud data architecture is fragmenting legacy centralized analytics deployments across Asia-Pacific energy networks. This structural shift forces grid operators to rebuild data infrastructure while navigating divergent national localization mandates.
Growth Catalysts
- Renewable Integration Mandates:India's CEA issues directives requiring predictive analytics for interstate transmission scheduling. Grid operators must deploy real-time forecasting to manage solar and wind intermittency.
- Smart Meter Standardization:China's MIIT coordinates GB standards for interoperability that reshape procurement specifications. Domestic and foreign vendors align product roadmaps to these technical requirements.
- Grid Code Transparency:Japan's METI enforces real-time data disclosure rules from distributed energy resources. Utilities invest in analytics platforms to comply with visibility mandates.
Market Restraints
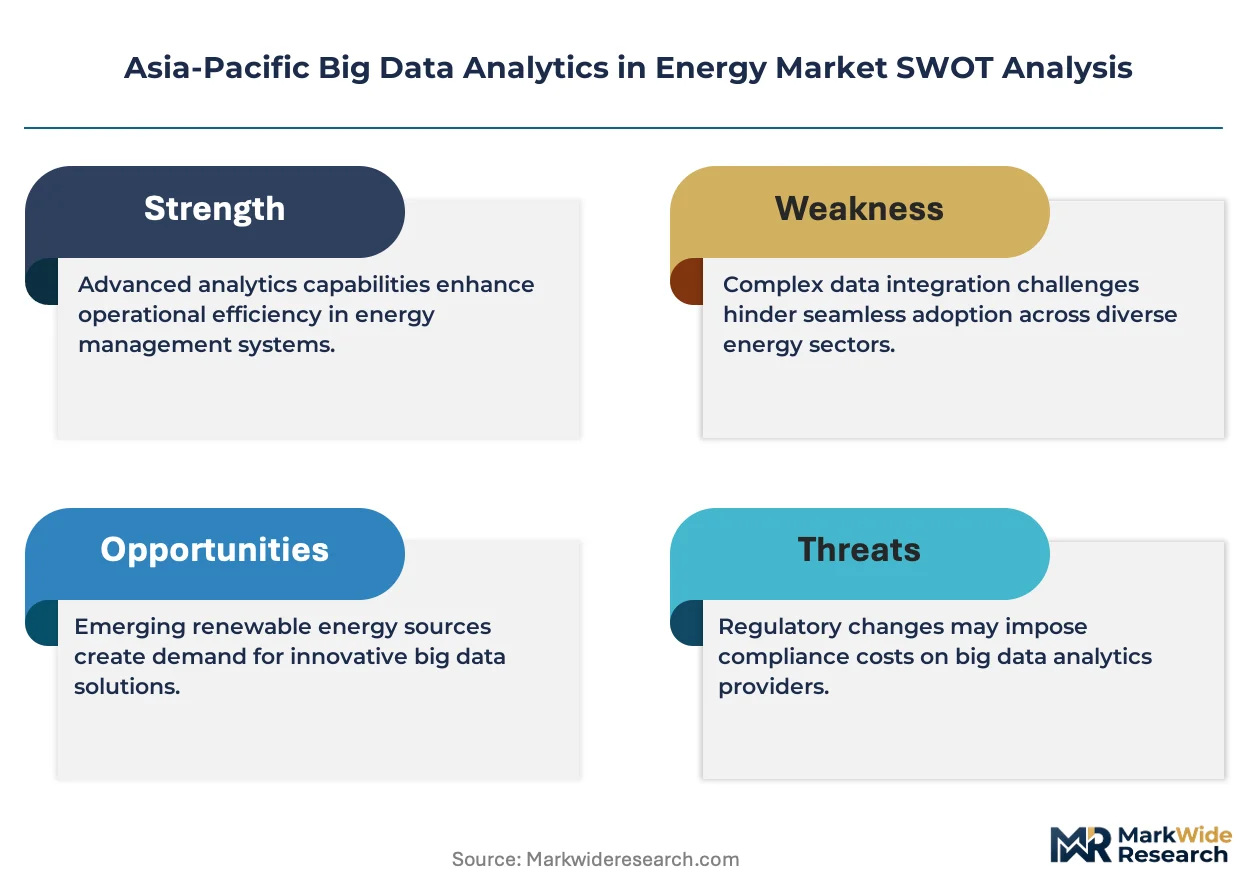
- Data Localization Requirements:Divergent national data sovereignty laws fragment cross-border platform deployment. Vendors must replicate infrastructure across jurisdictions, inflating operational costs.
- Legacy System Entrenchment:On-premise SCADA and historian systems dominate generation asset monitoring. Migration to cloud-native architectures demands capital-intensive retrofitting.
- Specialized Talent Scarcity:Shortage of data engineers with combined power systems and machine learning expertise constrains deployment velocity. Training pipelines lag market requirements.
Strategic Opportunities
- Archipelagic Grid Management:Southeast Asian island networks lack unified visibility across fragmented generation assets. Analytics platforms can anchor multi-utility consolidation plays.
- Industrial IoT Convergence:Integration of digital twins with predictive maintenance unlocks new service revenue streams. Thermal power operators seek unified asset performance management.
- Provincial Pilot Expansion:China's smart grid pilot zones in Guangdong and Jiangsu validate platform scalability. Successful deployments create reference architectures for national rollout.
Industry Challenges
- Cybersecurity Certification Complexity:Critical infrastructure protection standards vary across Asia-Pacific jurisdictions. Vendors face elongated approval timelines for cross-border data flows.
- Interoperability Integration Friction:Heterogeneous meter protocols and communication standards complicate unified analytics layer deployment. Utilities absorb substantial systems integration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Big Data Analytics in Energy Market |
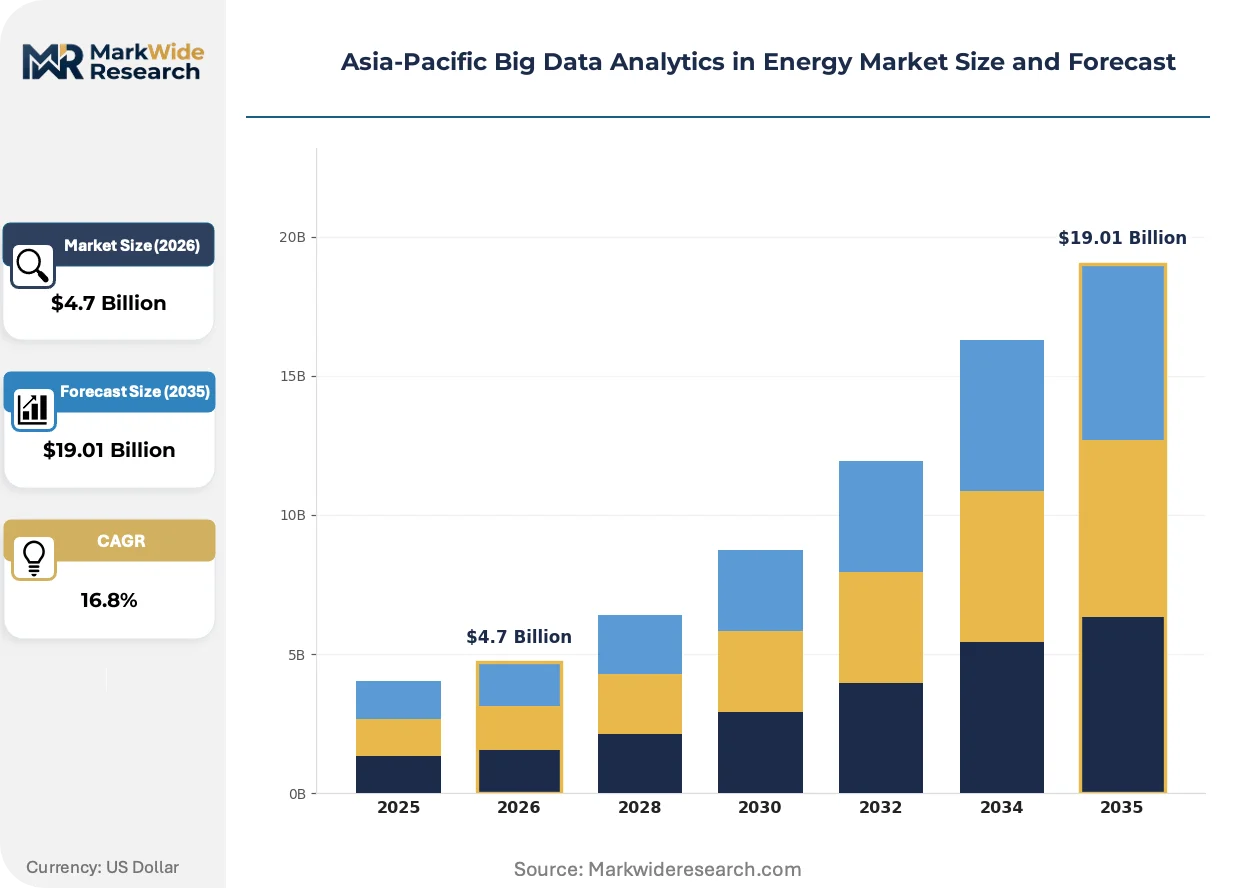
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $19.01 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Management, Predictive Analytics, Visualization Tools, Reporting Solutions Application: Grid Management, Load Forecasting, Asset Management, Demand Response End User: Utilities, Energy Producers, Regulators, Consultants Technology: Machine Learning, Cloud Computing, IoT, Blockchain |
| Companies Covered | IBM, SAP SE, Oracle, Siemens, Accenture, Microsoft, GE Digital, Teradata, C3.ai, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Big Data Analytics in Energy Market Evolving Landscape
Real-time operational intelligence is displacing retrospective reporting as the primary value proposition for utility analytics procurement. Vendors are repositioning platforms around predictive and prescriptive capabilities rather than historical dashboards.
Digital twin technology for generation assets is rendering obsolete scheduled maintenance calendars based on operating hours. Thermal power operators in Australia and Japan are deploying physics-based models that simulate equipment degradation under actual load profiles. These virtual replicas compress maintenance windows and extend asset life cycles through condition-based intervention.
Japan's METI grid code revisions mandate transparent data exchange between distributed solar assets and regional load dispatch centers. This regulatory pressure forces utilities to expose previously siloed operational data to third-party analytics platforms. Commercial and industrial microgrid operators face the steepest compliance burden as they retrofit monitoring infrastructure.
Subscription-based platform licensing is displacing perpetual software purchases among national utilities. Procurement teams in South Korea and Singapore prioritize operational expenditure models that align vendor compensation with uptime and forecast accuracy outcomes. This shift transfers implementation risk to platform providers and accelerates pilot-to-production timelines.
Asia-Pacific Big Data Analytics in Energy Market Segmentation
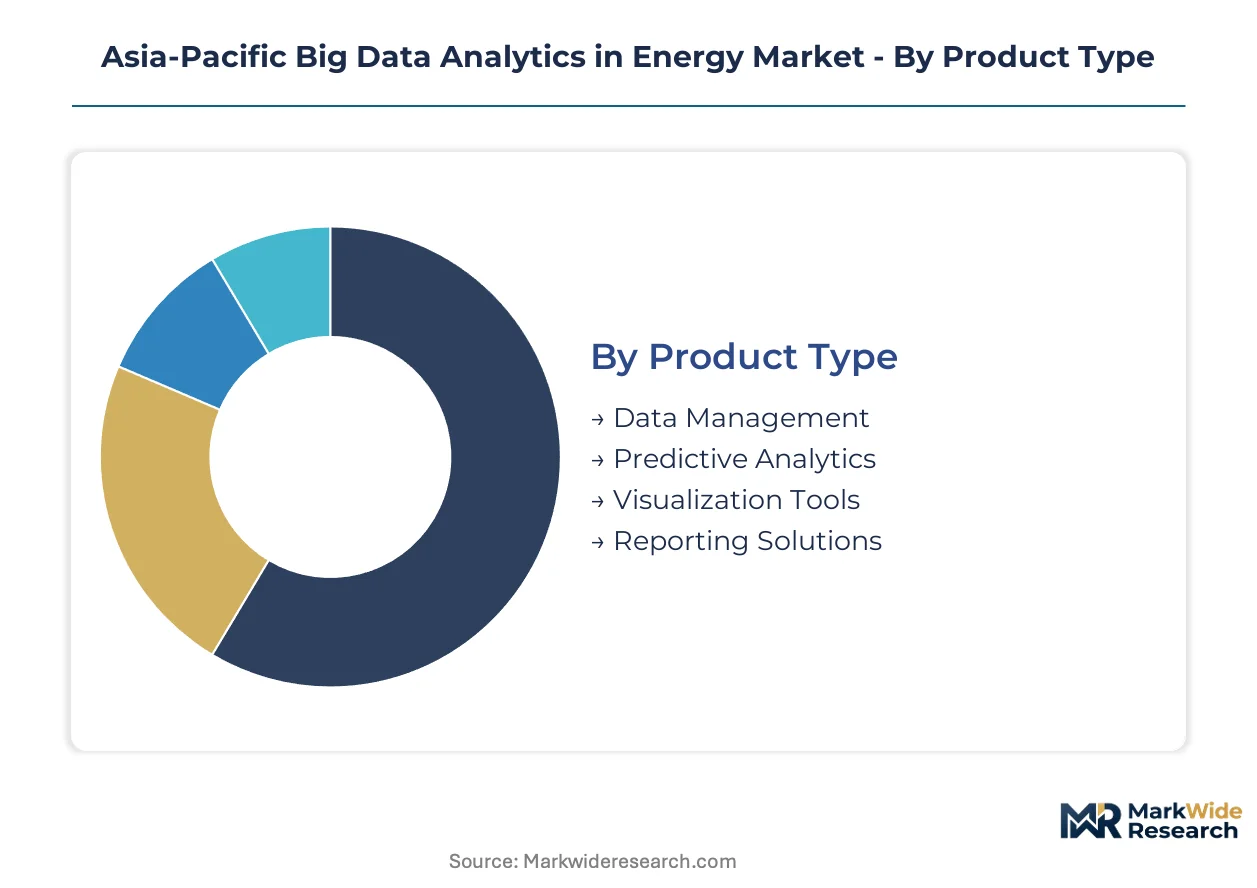
Segmentation reveals how analytics procurement diverges across Asia-Pacific energy infrastructure maturity levels. Grid operators prioritize predictive capabilities while industrial generators favor asset-centric platforms.
Product Type:
Use-case spectrum spans from retrospective reporting to real-time intervention across generation, transmission, and distribution networks.
- Predictive Analytics:Pattern recognition algorithms process sensor streams to forecast equipment degradation and demand spikes. Grid operators in Japan and Australia deploy these platforms for outage prevention rather than reactive maintenance scheduling.
- Data Management:Ingestion pipelines, data lakes, and governance frameworks consolidate operational technology and information technology streams. China's provincial smart grid pilots require petabyte-scale infrastructure to harmonize distributed solar telemetry.
- Visualization Tools:Dashboard interfaces translate complex grid telemetry into dispatch-ready intelligence for control room operators.
- Reporting Solutions:Compliance documentation and regulatory filing automation serves CEA-mandated disclosure requirements in India.
Established volume favors Data Management; emerging adoption favors Predictive Analytics.
Application:
Functional deployment maps directly to renewable penetration rates and grid architecture complexity across the region.
- Grid Management:Real-time balancing algorithms integrate intermittent solar and wind output across archipelagic transmission networks. Southeast Asian utilities deploy these systems to compensate for fragmented generation asset visibility.
- Asset Management:Digital twin platforms simulate thermal power equipment degradation under actual load profiles. Australian and Japanese operators compress maintenance windows through condition-based intervention rather than operating-hour calendars.
- Load Forecasting:Machine learning models project consumption patterns across industrial zones and residential clusters.
- Demand Response:Automated curtailment systems align industrial consumption with real-time pricing signals.
Current procurement concentrates in Grid Management; steepest expansion trajectory appears in Asset Management as thermal fleets age.
End User:
Buyer sophistication varies from national-scale procurement teams to specialized consultancies serving regulatory compliance.
- Utilities:Integrated generation-transmission-distribution operators deploy enterprise-wide platforms spanning millions of meter endpoints. METI transparency mandates in Japan accelerate platform refresh cycles.
- Energy Producers:Independent power producers and renewable asset operators require modular analytics for fleet optimization.
- Regulators:CEA in India and provincial energy bureaus in China consume aggregated analytics for market oversight and tariff setting.
- Consultants:Systems integrators and advisory firms embed white-label analytics into digital transformation engagements.
Utility procurement dominates contract value; consultant channel gains share fastest as mid-sized operators seek external expertise.
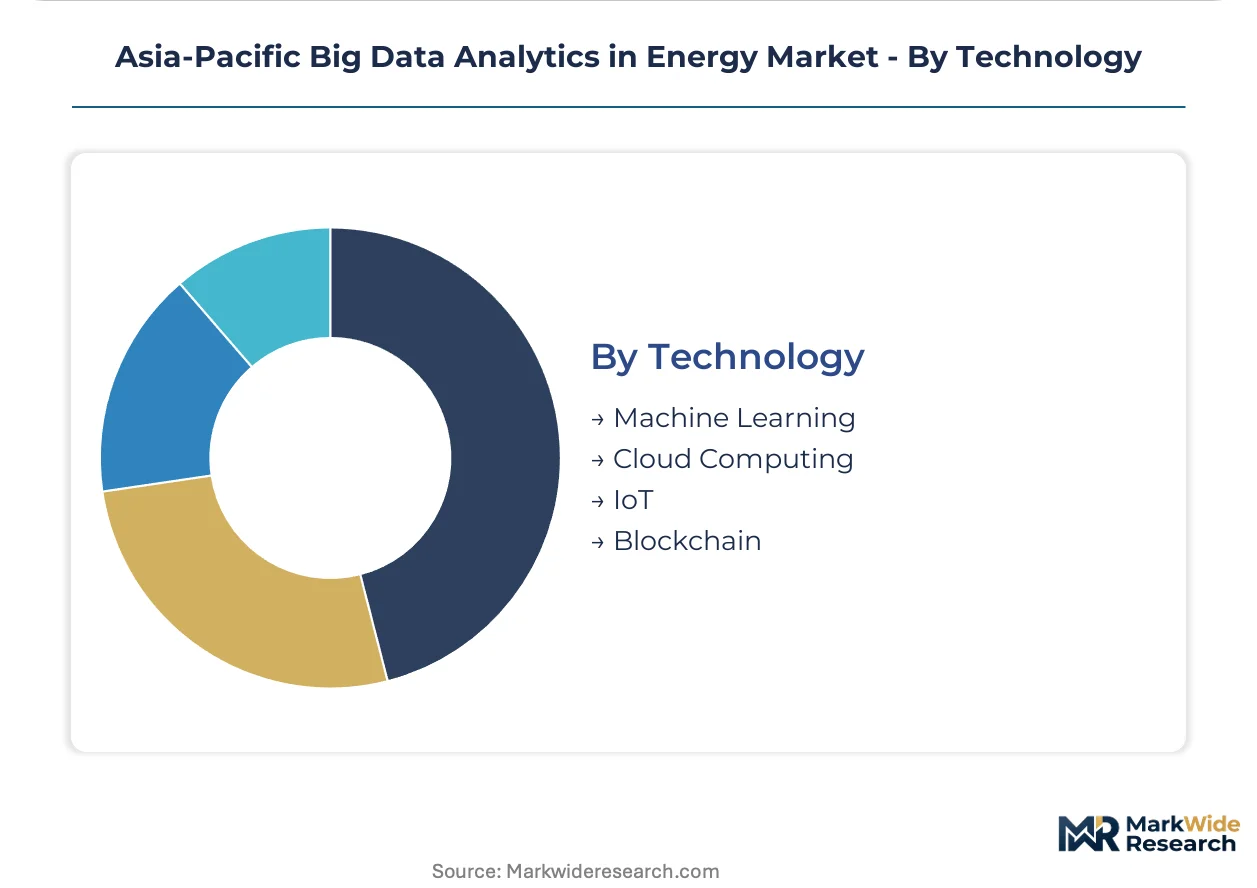
Technology:
Infrastructure choices reflect migration timelines from on-premise SCADA heritage to cloud-native architectures.
- Cloud Computing:Elastic compute and storage resources replace capital-intensive data center builds. South Korean and Singaporean utilities prioritize operational expenditure models that align vendor compensation with uptime outcomes.
- Machine Learning:Supervised and unsupervised algorithms detect anomalies in equipment vibration, temperature, and electrical signature data. Pattern recognition capabilities underpin demand forecasting accuracy improvements.
- IoT:Sensor networks and edge devices stream telemetry from remote generation assets and substations.
- Blockchain:Distributed ledger applications address peer-to-peer energy trading and renewable certificate tracking.
Machine Learning anchors current deployment; Cloud Computing infrastructure expands most quickly as national utilities retire legacy systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian analytics platforms serve Southeast Asian grid operators seeking archipelagic network management capabilities. Japan exports predictive maintenance frameworks to thermal power operators across the region. Indian software vendors supply load forecasting tools to Bangladesh and Sri Lankan distribution utilities.
China
Provincial smart grid pilots in Guangdong and Jiangsu validate platform scalability for national rollout. MIIT coordinates GB standards for smart meter interoperability that reshape procurement specifications for domestic and foreign vendors. Yangtze River Delta utilities deploy petabyte-scale data lakes to harmonize distributed solar telemetry from millions of endpoints.
Japan
Grid operators prioritize outage prevention through predictive analytics deployment across transmission networks. METI enforces grid code revisions mandating real-time data transparency from distributed energy resources. Tokyo Electric and regional utilities invest in analytics platform refreshes to comply with visibility mandates for commercial microgrid operators.
India
Interstate transmission scheduling drives demand for renewable integration forecasting capabilities. CEA issues directives requiring predictive analytics capabilities for managing solar and wind intermittency. Maharashtra and Gujarat host the highest concentration of data infrastructure investment under the PLI scheme for renewable energy manufacturing.
Australia
Thermal power operators deploy digital twin platforms to compress maintenance windows through condition-based intervention. AEMO mandates data disclosure standards that accelerate utility procurement of real-time operational intelligence systems. Queensland and New South Wales utilities lead adoption of subscription-based platform licensing aligned with uptime outcomes.
South Korea
National utilities prioritize operational expenditure models that transfer implementation risk to platform providers. KEPCO drives standardization of edge-to-cloud architectures across generation and distribution assets. Seoul Capital Area concentrators anchor pilot-to-production timelines for machine learning-based demand forecasting deployments.
Asia-Pacific Big Data Analytics in Energy Market Competitive Landscape
On the supply side, the industry is consolidating around hybrid cloud providers and industrial IoT specialists with established utility relationships. Technology conglomerates anchor large-scale enterprise contracts through integrated hardware-software stacks. Pure-play AI vendors occupy niche positions in predictive analytics applications. Vertical integration into edge device manufacturing and strategic partnerships with systems integrators represent the dominant competitive moves reshaping vendor positioning.
Within the technology conglomerate tier, IBM and Microsoft exemplify platform providers leveraging hybrid cloud infrastructure to anchor utility contracts. Siemens occupies a position among industrial automation specialists integrating IoT capabilities for thermal power operators. C3.ai represents the pure-play AI archetype specializing in enterprise predictive applications across generation and transmission assets.
| Leading Market Players |
|---|
| IBM |
| SAP SE |
| Oracle |
| Siemens |
| Accenture |
| Microsoft |
| GE Digital |
| Teradata |
| C3.ai |
| Others |
Value Network & Pricing Analysis
Underutilized edge-computing infrastructure in Southeast Asian utilities is forcing analytics vendors toward outcome-based contracting models that transfer deployment risk from capital-constrained grid operators to platform providers. This capacity slack simultaneously compresses upfront licensing premiums and elongates payback timelines for systems integrators.
Pricing Analysis
Cloud-native deployment pricing is diverging sharply from on-premise legacy licensing across Asia-Pacific energy analytics procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by integration complexity and data sovereignty compliance depth. Price differentiation hinges on METI-aligned certification tiers in Japan and MIIT GB standard adherence in China. Pricing pressure stems from KEPCO-mandated operational expenditure models in South Korea that commoditize baseline forecasting modules. State-owned utilities in China exhibit lowest price sensitivity due to provincial pilot funding; independent power producers in Vietnam and Indonesia face acute budget constraints.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for analytics platforms serving India's CEA-mandated renewable integration projects. Supply concentration centers on China for edge device manufacturing, Japan for industrial IoT sensors, and Singapore for cloud infrastructure orchestration. Component dependencies include NVIDIA GPU clusters for machine learning training, ARM-based edge processors for substation telemetry, and quantum-resistant encryption modules for critical infrastructure protection. Single-source vulnerability runs through Taiwan-semiconductor-dependent inference accelerators. Distribution runs through systems integrators like Accenture and local EPC contractors rather than direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific energy analytics sits in early-cycle expansion as provincial smart grid pilots in China and METI transparency mandates in Japan accelerate first-mover procurement beyond pilot-to-production thresholds.
For Market Incumbents: Harden defensive moats around hybrid cloud infrastructure by anchoring multi-utility consolidation plays in Southeast Asian archipelagic networks. Prioritize backward integration into edge device manufacturing to offset margin compression from outcome-based contracting. Threat substitution from pure-play AI vendors like C3.ai demands differentiated digital twin capabilities for thermal power operators. For New Entrants and Emerging Players: Vietnam and Philippines distribution utilities represent the most penetrable white-space for modular load forecasting platforms unburdened by legacy SCADA entrenchment. Target CEA-compliant predictive analytics for interstate transmission scheduling as India's renewable integration mandates outpace incumbent deployment capacity. Go-to-market through consultant channel partnerships accelerates credibility with mid-sized operators lacking internal data engineering expertise. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native platform providers as subscription licensing displaces perpetual software purchases. Long-term viability favors vendors with demonstrated provincial pilot-to-national-rollout trajectories in China. Acquisition target archetype: industrial IoT specialists with captive utility relationships in Japan or Australia. Signal to watch: MIIT acceleration of GB standard harmonization timelines that would consolidate vendor qualification pools.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | IBM's hybrid cloud stack anchors large-scale utility contracts across Japan and Australia. |
| Strategic Partnership | Siemens dominates industrial IoT integration for thermal power operators seeking unified asset management. |
| Geographic Expansion | C3.ai extends predictive capabilities across generation and transmission assets in Southeast Asian pilot zones. |
| Product Launch | Digital twin platforms displace scheduled maintenance calendars in Australian and Japanese thermal fleets. |
| Acquisition of Specialist Firm | Edge device manufacturers face consolidation pressure as vendors seek backward integration control. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, IPP project developers, grid operators, and EPC contractors across China, Japan, India, Australia, and South Korea. Secondary validation drew from EIA data, IEA reports, FERC filings, and project development databases. Bottom-up triangulation across deployment-scale assumptions and top-down reconciliation against national renewable integration targets anchored market sizing.
Calibration against historical platform procurement volumes in China's Guangdong and Jiangsu pilot zones informed penetration trajectory assumptions. Segmentation dimensions modeled include product type, application, end user, and technology infrastructure choice across the projection horizon. CAGRs were derived from utility capex disclosure patterns and vendor contract value disclosures. Forecast inputs incorporated METI grid code revision timelines and CEA directive implementation schedules.
Practitioners should monitor MIIT standard harmonization acceleration and CEA enforcement consistency for early signals of vendor consolidation timing. Forecasts reflect documented assumptions on provincial pilot expansion rates and cloud migration timelines. Macroeconomic deviation in utility borrowing costs, regulatory restriction on cross-border data flows, or technological disruption in edge computing architectures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
AI in Energy Market
Energy Analytics and Software
Australia Big Data Analytics in Energy Market
Energy Analytics and Software
Building Energy Simulation Software Market
Energy Analytics and Software
Big Data in Oil and Gas Market
Energy Analytics and Software
Japan Big Data Analytics in Energy Market
Energy Analytics and Software
Global Wind Turbine Condition Monitoring System Market
Energy Analytics and Software
Smart Grid Data Analytics Market
Energy Analytics and Software
Power System Analysis Software Market
Energy Analytics and Software
Europe Big Data Analytics in Energy Market
Energy Analytics and Software
Italy Big Data Analytics in Energy Market
Energy Analytics and Software
Smart Grid Software Market
Energy Analytics and Software
Germany Big Data Analytics in Energy Market
Energy Analytics and Software
Energy Intelligence Solutions Market
Energy Analytics and Software
France Big Data Analytics in Energy Market
Energy Analytics and Software
Africa Big Data Analytics in Energy Market
Energy Analytics and Software
Netherlands Big Data Analytics in Energy Market