
 Lactic Acid Esters of Mono and Diglycerides of Fatty Acids Market | 2026-2036
Lactic Acid Esters of Mono and Diglycerides of Fatty Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Lactic Acid Esters of Mono and Diglycerides of Fatty Acids Market Foresight
Clean-label food manufacturers is unwinding legacy emulsifier procurement patterns across the bakery and dairy sectors. BASF SE leverages its integrated lactic acid supply chain to secure cost positions in European emulsifier production. Jungbunzlauer Suisse AG anchors its competitiveness through fermentation-derived ingredient platforms that align with natural-positioning trends. Corbion specializes in microbial fermentation technology for consistent ester purity across bakery applications.
Lactic acid esters of mono and diglycerides of fatty acids comprise glycerol molecules esterified with both fatty acids and lactic acid, yielding amphiphilic compounds with hydrophilic-lipophilic balance values typically between 3 and 8. These emulsifiers stabilize oil-water interfaces, retard starch retrogradation, and improve dough handling in industrial baking operations. Enhanced emulsifiers command premium positioning as manufacturers seek multi-functional ingredients that reduce label complexity. Dairy applications represent the fastest-growing consumption segment as plant-based analogues require sophisticated fat-protein stabilization. Direct sales channels dominate bulk procurement by multinational food manufacturers, while distributors occupy fragmented regional bakery markets.
EFSA maintains positive safety opinions for lactic acid esters under EU food additive regulations, while FDA GRAS status under 21 CFR 184.1505 enables unrestricted use in US food categories. China's NMPA and national food safety standards GB 2760 govern emulsifier approvals, with SAMR intensifying post-market surveillance of imported food additives. Manufacturers must monitor evolving clean-label definitions across jurisdictions, as regulatory divergence between natural-derived and chemically modified classifications threatens to fragment formulation strategies and complicate global product registrations.
Market Dynamics
Clean-label reformulation mandates from Western European retailers are compressing procurement timelines for synthetic emulsifier replacements. Food manufacturers face binding sustainability commitments that require immediate ingredient transitions without compromising functional performance.
Growth Catalysts
- EU Green Deal food sector targets:The European Commission's Farm to Fork strategy accelerates synthetic additive phase-outs. Lactic acid esters qualify as processing aids in clean-label bakery applications.
- Plant-based dairy analogues:Oat and almond milk processors require sophisticated fat-protein stabilization. These emulsifiers prevent phase separation in extended shelf-life beverages.
- Fermentation technology maturation:Microbial production platforms achieve cost parity with chemical synthesis. Consistent ester purity now supports industrial-scale bakery deployment.
Market Restraints
- Lactic acid feedstock volatility:Corn and sugar beet price swings directly impact ester production economics. European bioethanol policy competition tightens carbohydrate supply.
- Chinese import additive scrutiny:SAMR post-market surveillance intensifies documentation requirements. Registration timelines for new emulsifier variants extend unpredictably.
- Enzymatic emulsifier substitution:Lipase-modified lecithin and phospholipid alternatives claim comparable functionality. Some clean-label positioning strategies favor these non-ester options.
Strategic Opportunities
- Precision fermentation scale-up:Microbial chassis engineering enables tailored hydrophilic-lipophilic balance values. Custom ester profiles address specific bakery texture requirements.
- Direct-to-bakery distribution:Regional craft bakeries bypass traditional ingredient distributors. Digital procurement platforms aggregate fragmented demand into viable order quantities.
- India FSSAI clean-label recognition:Emerging regulatory frameworks distinguish natural-derived emulsifiers from chemically modified alternatives. Early registration secures positioning in reformulating processed food sectors.
Industry Challenges
- Fermentation scale-up expertise scarcity:Industrial microbiology talent pools concentrate in pharmaceutical and enzyme sectors. Food-grade microbial production requires distinct contamination control protocols.
- Clean-label definition divergence:Retailer specifications vary across Germany, France, and UK markets. Formulation teams maintain multiple product variants for single continental customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactic Acid Esters of Mono and Diglycerides of Fatty Acids Market |
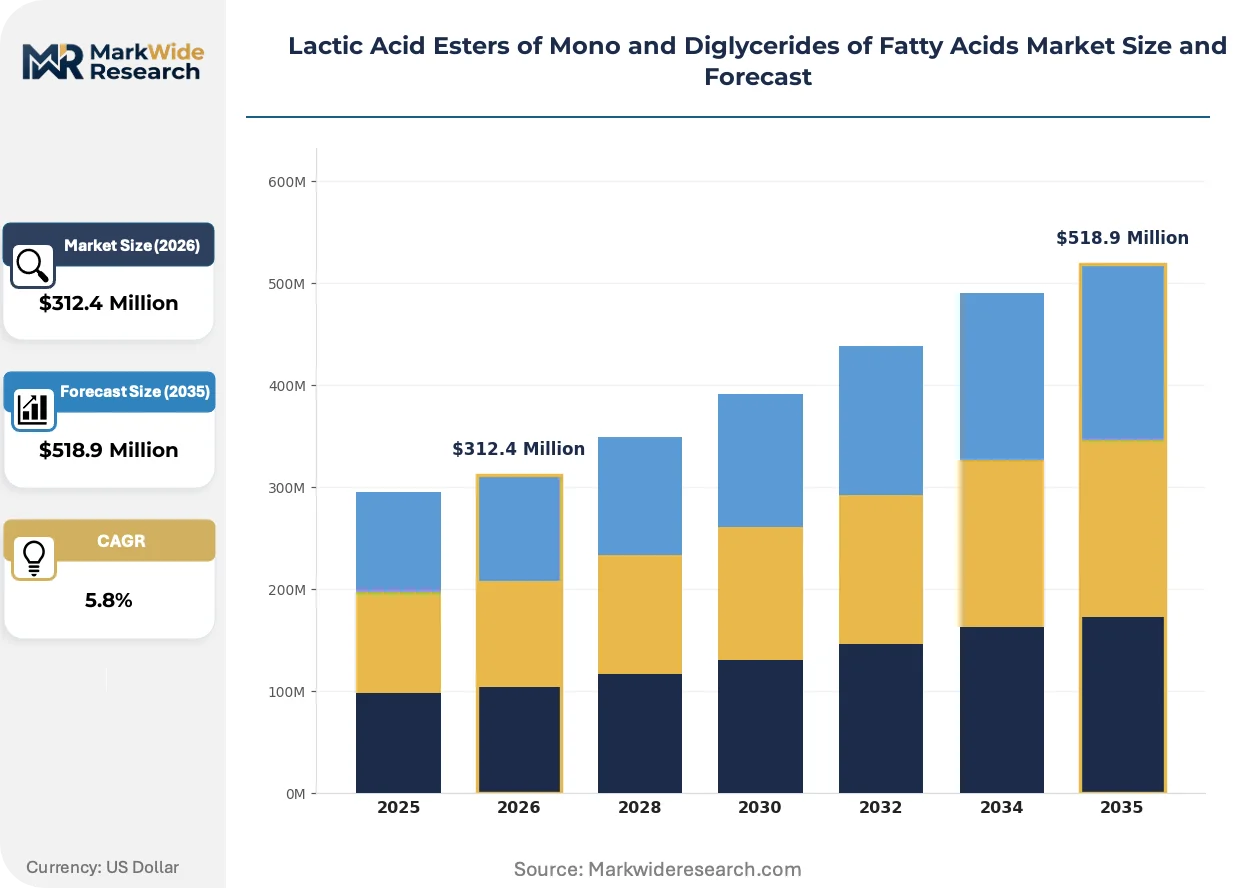
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lactic Acid Esters, Mono-Diglycerides, Fatty Acid Esters, Enhanced Emulsifiers Application: Baked Goods, Dairy Products, Snack Foods, Confectionery End User: Food Manufacturing, Personal Care, Pharmaceuticals, Animal Feed Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | BASF SE, Jungbunzlauer Suisse AG, Zhejiang Weishi Biotechnology Co., Ltd., AAK AB, Stepan Company, Corbion, Henan Jindan Lactic Acid Technology Co., Ltd., Croda International Plc, Galactic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactic Acid Esters of Mono and Diglycerides of Fatty Acids Market Shifts & Advancements
Bioprocess engineering advances are collapsing the cost gap between fermentation-derived and petrochemical emulsifiers. Simultaneously, regulatory frameworks across major economies are crystallizing definitions of natural-derived status that will determine competitive positioning for the next decade.
Enzymatic esterification technology is miniaturizing production footprints for lactic acid ester manufacturing. Regional bakery ingredient suppliers adopt modular bioreactor systems to serve local clean-label demand without centralized bulk import dependence. This distributed production architecture compresses supply chain lead times from months to weeks.
EFSA's updated food additive guidance on enzymatic processing aids reclassifies certain esterification pathways as natural-derived. Industrial bakery manufacturers in Germany and France accelerate reformulation to capture this regulatory window before competitor synthetic alternatives lose shelf access. The distinction between chemical modification and biocatalytic processing determines ingredient eligibility in premium retail channels.
Ingredient specification sheets now dominate bakery procurement decisions previously driven by price-volume negotiations. Multinational food manufacturers consolidate emulsifier suppliers to three approved vendors per region, replacing fragmented multi-source purchasing. This concentration trend is most visible in Scandinavian markets where retailer sustainability scorecards directly influence supplier retention.
Lactic Acid Esters of Mono and Diglycerides of Fatty Acids Market Segmentation
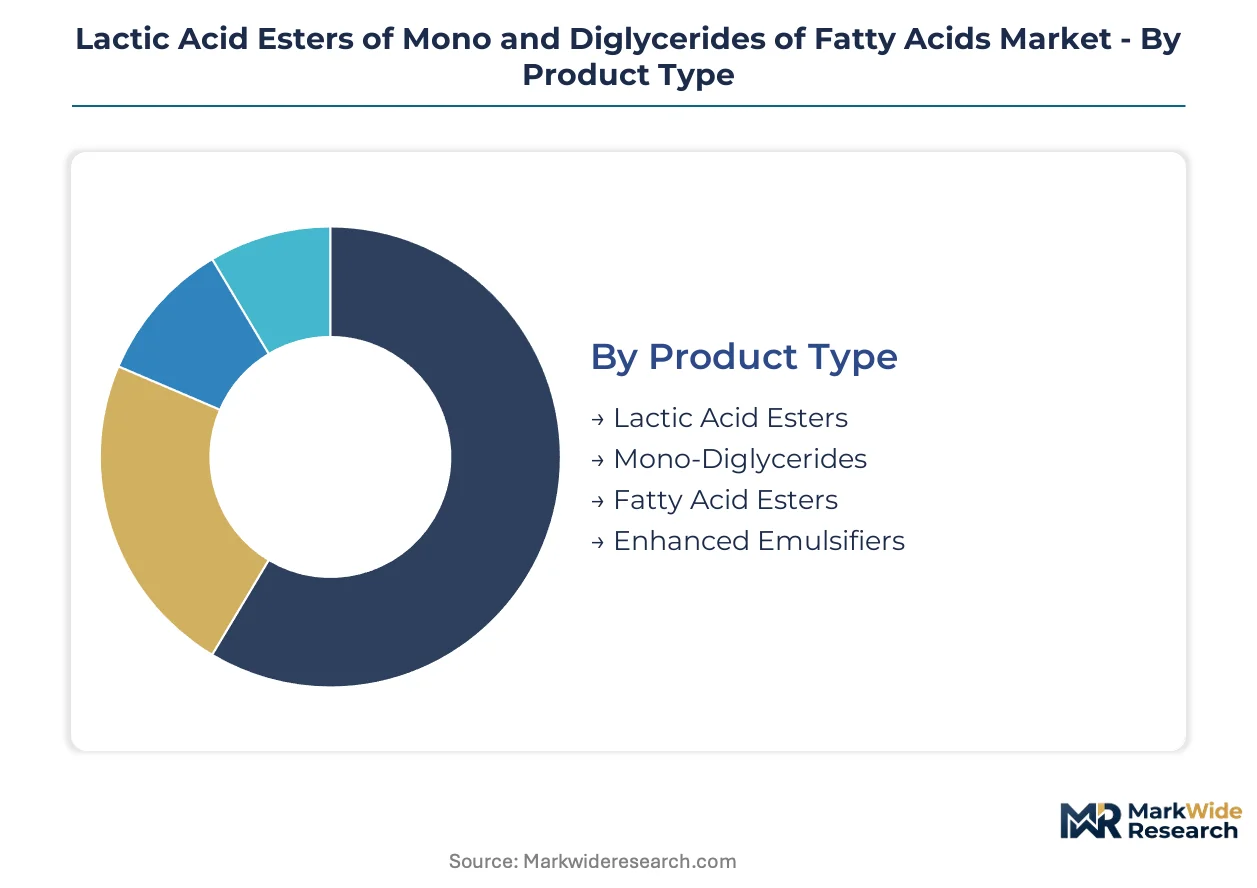
Segmentation reveals where lactic acid ester emulsifiers face immediate substitution pressure from enzymatic alternatives and where fermentation-derived positioning commands premium access. Procurement patterns diverge sharply between multinational food manufacturers seeking single-source consolidation and regional bakeries demanding flexible order quantities.
Product Type:
Substitution pressure from lipase-modified lecithin concentrates most intensely on standard ester formulations, while enhanced and fermentation-derived variants defend positioning through functional complexity.
- Lactic Acid Esters:Glycerol molecules esterified with lactic acid yield amphiphilic compounds with hydrophilic-lipophilic balance values between 3 and 8. Demand concentrates in Western European industrial baking operations where EFSA processing aid classifications enable clean-label deployment against synthetic emulsifier phase-out timelines.
- Enhanced Emulsifiers:Multi-functional formulations combine ester stabilization with anti-staling and dough-conditioning properties in single ingredients. Plant-based dairy processors in China specify these variants for oat and almond milk fat-protein stabilization where extended shelf-life requirements prevent phase separation.
- Mono-Diglycerides:Standard glycerol-fatty acid esters without lactic acid modification serve cost-sensitive bakery applications.
- Fatty Acid Esters:Simpler ester structures face direct price competition from chemical synthesis routes.
Standard mono-diglycerides retain volume leadership; enhanced emulsifiers hold the steepest expansion curve.
Application:
Cost tier stratification separates premium reformulation mandates from commodity replacement cycles across food manufacturing verticals.
- Baked Goods:Industrial bread and pastry operations deploy lactic acid esters for starch retrogradation retardation and dough handling improvement. Western European retailer sustainability scorecards compress procurement timelines for synthetic emulsifier replacements in Germany, France, and UK manufacturing facilities.
- Dairy Products:Plant-based milk analogues require sophisticated fat-protein stabilization that standard emulsifiers fail to deliver. Chinese oat and almond milk processors drive specification intensity as SAMR intensifies post-market surveillance of imported additive documentation.
- Snack Foods:Extruded and coated applications prioritize cost-efficient emulsification over label positioning.
- Confectionery:Chocolate and fat-based sweets use esters for viscosity control and bloom prevention.
Baked goods retain volume leadership; dairy products hold the steepest expansion curve.
End User:
Customer type determines procurement channel structure, with food manufacturing consolidating suppliers while personal care and pharmaceutical segments fragment across specialized distributors.
- Food Manufacturing:Multinational bakery and dairy processors consolidate emulsifier suppliers to three approved vendors per region, replacing fragmented multi-source purchasing. Direct sales channels dominate bulk procurement as Scandinavian retailer sustainability scorecards directly influence supplier retention decisions.
- Pharmaceuticals:Excipient-grade ester purity requirements command specification-driven procurement with extended qualification timelines.
- Personal Care:Cosmetic emulsifier applications prioritize sensory profile over food-grade regulatory compliance.
- Animal Feed:Cost-minimization drives specification with minimal clean-label premium tolerance.
Food manufacturing retains volume leadership; pharmaceuticals holds the steepest expansion curve.
Distribution Channel:
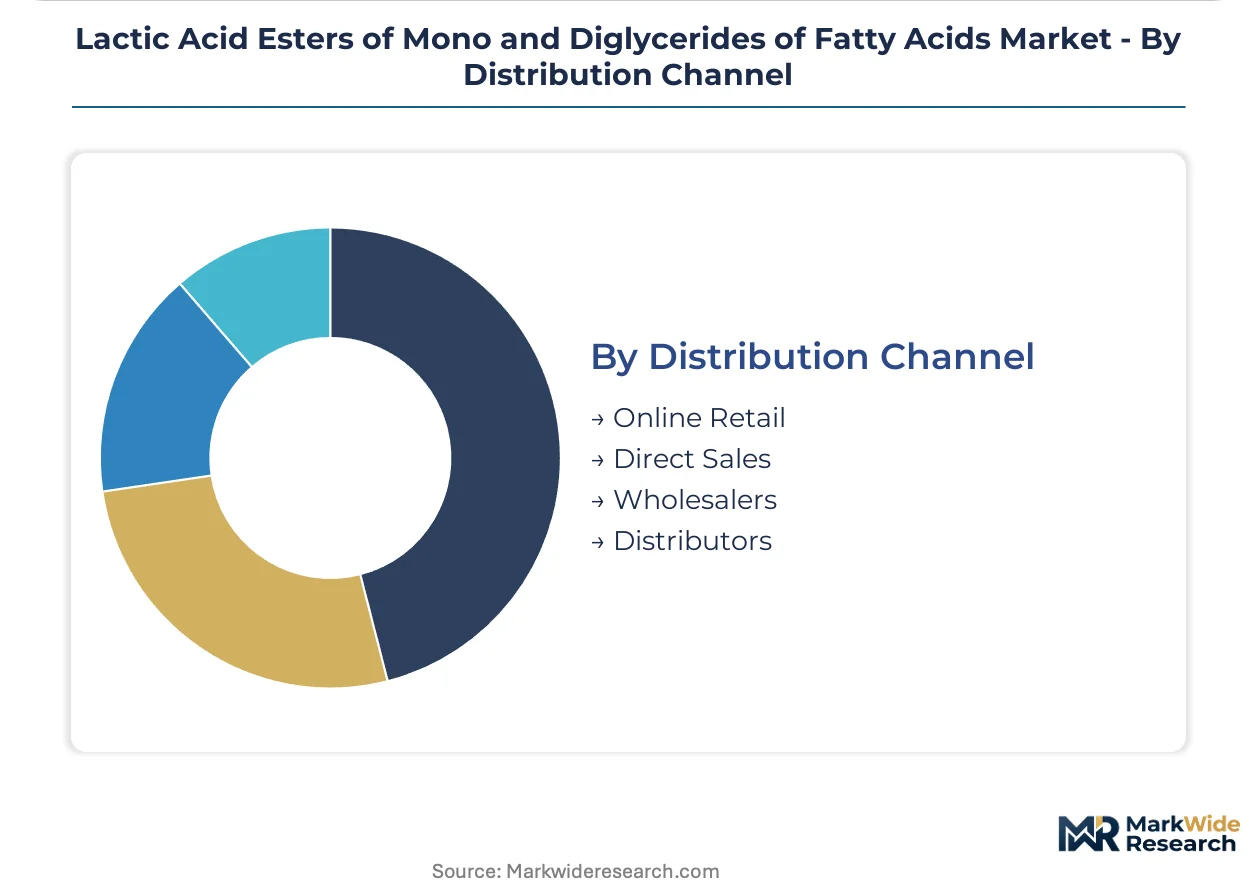
Supply concentration in fermentation-capable production regions shapes channel viability, with direct sales requiring scale thresholds that exclude smaller regional accounts.
- Direct Sales:Multinational food manufacturers negotiate consolidated regional contracts with fermentation-integrated producers. BASF SE leverages its captive lactic acid supply chain to secure cost positions in European emulsifier production through direct relationships with industrial bakery groups.
- Distributors:Fragmented regional bakery markets depend on ingredient distributors for technical support and flexible order quantities. Digital procurement platforms now aggregate craft bakery demand into viable order quantities, bypassing traditional distributor markups in Germany and France.
- Online Retail:Small-scale specialty ingredient sales serve artisan producers and research applications.
- Wholesalers:Commodity-grade ester volumes move through bulk agricultural supply networks.
Direct sales retain volume leadership; distributor channels hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk handling infrastructure underwrites Western Europe's dominance in lactic acid ester distribution, connecting fermentation facilities to industrial bakery clusters across the continent. This logistics backbone enables rapid formulation turnaround for clean-label reformulation mandates.
Germany
Industrial bread manufacturers in Lower Saxony and North Rhine-Westphalia drive specification intensity for starch retrogradation retardation. EFSA's processing aid classifications under EU food additive regulations enable clean-label deployment against synthetic emulsifier phase-out timelines. The Farm to Fork strategy accelerates procurement shifts in Munich and Stuttgart processing facilities.
China
Oat and almond milk processors in Jiangsu and Zhejiang provinces require sophisticated fat-protein stabilization for extended shelf-life beverages. SAMR intensifies post-market surveillance of imported additive documentation under GB 2760 standards. Yangtze River Delta fermentation facilities scale microbial production platforms to serve domestic dairy analogue demand.
United States
Multinational food manufacturers consolidate emulsifier suppliers to three approved vendors per region under FDA GRAS status per 21 CFR 184.1505. The Midwest bakery belt spanning Illinois, Michigan, and Ohio compresses procurement timelines for synthetic replacements. Chicago and Minneapolis distribution hubs aggregate bulk orders for direct sales channels.
France
Retailer sustainability scorecards in Paris and Lyon directly influence supplier retention decisions for clean-label baked goods. ANSM monitors additive compliance alongside EFSA guidance on enzymatic processing aids. Auvergne-Rhône-Alpes fermentation specialists capture regulatory windows before synthetic alternatives lose premium retail shelf access.
India
Processed food reformulation in Maharashtra and Gujarat creates early-mover positioning for natural-derived emulsifier recognition. FSSAI clean-label frameworks distinguish fermentation-derived ingredients from chemically modified alternatives. Mumbai and Ahmedabad bakery ingredient distributors aggregate fragmented regional demand through digital procurement platforms.
Lactic Acid Esters of Mono and Diglycerides of Fatty Acids Market Competitive Landscape
Concentration sits with fermentation-integrated multinationals and regional carbohydrate-feedstock specialists. The vendor base stratifies across three tiers: captive lactic acid producers, microbial technology licensors, and commodity ester fabricators. Strategic moves center on backward integration into carbohydrate supply and precision fermentation scale-up for tailored hydrophilic-lipophilic balance values.
Within the fermentation-integrated tier, BASF SE and Corbion exemplify archetypes leveraging captive supply chains and microbial platforms respectively. Jungbunzlauer Suisse AG occupies a position among Swiss specialists emphasizing natural-positioning alignment. These three anchors represent competitive positioning through supply chain control, bioprocess engineering, and regulatory navigation rather than commodity volume.
| Leading Market Players |
|---|
| BASF SE |
| Jungbunzlauer Suisse AG |
| Zhejiang Weishi Biotechnology Co., Ltd. |
| AAK AB |
| Stepan Company |
| Corbion |
| Henan Jindan Lactic Acid Technology Co., Ltd. |
| Croda International Plc |
| Galactic |
| Others |
Supply & Pricing Matrix
Six-to-eight-week fermentation batch cycles compress inventory buffers for lactic acid ester producers, concentrating pricing power with fermentation-integrated suppliers in Germany and China while forcing distributors to absorb working capital strain. This lead-time rigidity amplifies cost pass-through during carbohydrate feedstock volatility, locking procurement managers into long-term offtake contracts to secure volume allocation.
Pricing Analysis
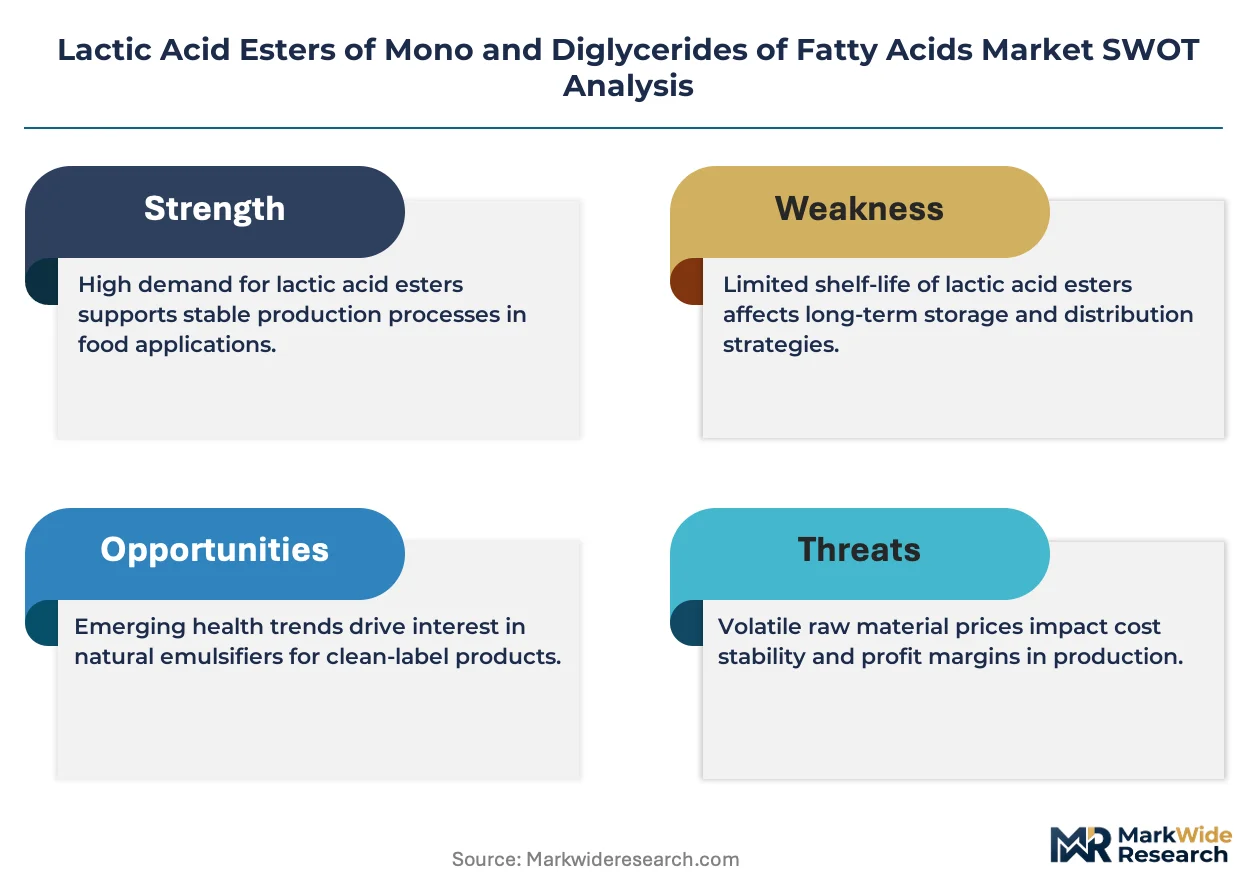
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with fermentation-derived variants commanding spreads over chemically synthesized alternatives based on EFSA natural-derived classification and SAMR registration completeness. Premium tiers attach to enhanced emulsifiers with tailored hydrophilic-lipophilic balance values for plant-based dairy applications, while economy segments serve commodity bakery replacements. Cost compression in standard ester tiers is intensifying because lipase-modified lecithin alternatives capture clean-label bakery accounts. Regional craft bakeries exhibit highest price sensitivity, whereas multinational dairy processors prioritize specification compliance over unit cost.
Supply Chain Analysis
China, Germany, and the Netherlands anchor lactic acid ester production through integrated fermentation facilities and Port of Rotterdam liquid bulk infrastructure. Corn and sugar beet feedstocks from European bioethanol-competing regions and Chinese Yangtze River Delta agricultural zones feed microbial production platforms. Single-source vulnerability concentrates in lactic acid supply, where BASF SE's captive production and Corbion's fermentation technology create dependency bottlenecks for non-integrated processors. Distribution runs through direct sales channels for multinational food manufacturers and digital procurement platforms aggregating fragmented regional bakery demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label regulatory crystallization across EFSA, FDA, and SAMR jurisdictions is accelerating synthetic emulsifier displacement, creating a high-growth disruption window for fermentation-derived positioning. This technological-regulatory inflection rewards early movers with premium shelf access and supplier consolidation leverage.
For Market Incumbents: Compound defensive positioning through backward integration into carbohydrate feedstock supply and precision fermentation capacity expansion in Lower Saxony and Jiangsu production clusters. Lipase-modified lecithin substitution threats in standard bakery tiers demand specification escalation toward enhanced multi-functional formulations that non-integrated competitors cannot replicate.
For New Entrants and Emerging Players: FSSAI clean-label fast-track registration in India offers the most penetrable regulatory entry point, with Maharashtra and Gujarat processed food reformulation creating first-mover positioning before domestic fermentation capacity matures. Target regional craft bakeries through digital procurement platform partnerships, bypassing established distributor relationships in fragmented German and French markets.
For Investors and Strategic Acquirers: Long-term, this sits as a fermentation-technology consolidation play because microbial chassis engineering capabilities concentrate in pharmaceutical and enzyme sectors with limited food-grade contamination control expertise. Acquisition targets should display precision fermentation scale-up infrastructure and existing EFSA processing aid classifications. The signal to watch is SAMR registration timeline compression for new emulsifier variants, indicating regulatory pathway maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbohydrate Feedstock | BASF SE's captive lactic acid supply chain demonstrates margin defense against corn price volatility in European bioethanol-competing regions. |
| Precision Fermentation Scale-Up | Corbion's microbial chassis engineering enables tailored HLB values for specific plant-based dairy texture requirements in Chinese oat milk processing. |
| Regulatory Fast-Track Registration | FSSAI clean-label recognition in India secures positioning before domestic fermentation capacity saturates reformulating processed food sectors. |
| Digital Procurement Platform Partnership | Aggregation of fragmented German and French craft bakery demand compresses distributor markups and accelerates direct customer relationships. |
| Enhanced Emulsifier Specification Escalation | Multi-functional formulations combining stabilization with anti-staling properties defend against lipase-modified lecithin substitution in Western European retail channels. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with bakery procurement directors, dairy processing plant managers, fermentation technology R&D leads, and food additive regulatory affairs specialists. Secondary validation drew from EFSA food additive guidance documents, SAMR GB 2760 standards updates, SEC 10-K filings of listed ingredient suppliers, and customs trade data for lactic acid derivative flows. Bottom-up volume modeling across product type, application, and end-user segments was triangulated against top-down market sizing from production capacity assessments.
Across the projection horizon, the analytical framework modeled segmentation dimensions including fermentation-derived versus chemically synthesized grade tiers, baked goods versus dairy versus pharmaceutical end-use industries, and direct sales versus distributor channel structures. CAGRs were derived from regression analysis of historical procurement volume trends against clean-label reformulation mandate intensity. Forecast inputs incorporated EFSA processing aid reclassification timing, SAMR post-market surveillance escalation patterns, and plant-based dairy analogue capacity build-out trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal synthetic additive phase-out timelines and stable carbohydrate feedstock availability; material deviation in bioethanol policy competition or SAMR regulatory stringency would warrant model refresh. Specific risk factors include enzymatic emulsifier substitution acceleration in standard bakery tiers and fermentation scale-up expertise scarcity constraining supply response. Recalibration cycles align with material shifts in EFSA guidance updates, SAMR registration pathway changes, and major retailer sustainability scorecard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Isobutyl Stearate Market
Oleochemicals
Oleochemicals Market
Oleochemicals
Decanoyl Chloride Market
Oleochemicals
Isooctyl Chloride Market
Oleochemicals
North America Alcohol Ethoxylates Market
Oleochemicals
Allyl Caproate Market
Oleochemicals
Carbolic Oil Market
Oleochemicals
Higher Olefins Market
Oleochemicals
Octyl Octanoate Market
Oleochemicals
Octanoyl Chloride Market
Oleochemicals
Isopropyl Esters Market
Oleochemicals
Undecanoyl Chloride Market
Oleochemicals
Oleyl Alcohol Market
Oleochemicals
Global Palm Wax Market
Oleochemicals
Global White Oil Market
Oleochemicals
Global Methyl Ester Ethoxylate Market