
 Lauric Aldehyde Market | 2026-2036
Lauric Aldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
Lauric Aldehyde Market Outlook
Fragrance compounding is decoupling from traditional mass-market applications toward niche perfumery and luxury personal care, redirecting volume flows across the value chain. Kao Corporation leverages captive oleochemical infrastructure across Asia to secure feedstock continuity. Symrise AG differentiates through biotechnology-derived aldehyde platforms that reduce batch variability. Givaudan SA anchors European demand through its Grasse-based fragrance creation centers.
Lauric aldehyde, or dodecanal, is a saturated twelve-carbon aliphatic aldehyde with a waxy, floral-orange odor profile, typically produced via catalytic dehydrogenation of lauryl alcohol or selective oxidation of dodecane. It functions primarily as a fragrance raw material and flavoring agent, imparting citrus-fatty notes at concentrations between 0.1% and 5% in finished compositions. The fragrance application segment dominates value capture given its integration into premium perfume formulations with elevated margin structures. Fatty alcohols as a product type sustain volume leadership due to their role as direct precursors in aldehyde synthesis. The cosmetics application channel is expanding fastest, driven by clean-label formulations demanding naturality credentials.
REACH registration requirements under ECHA mandate full toxicological dossiers for lauric aldehyde imports into Europe, elevating compliance costs for non-EU manufacturers. FDA flavorant status under FEMA GRAS and evolving EPA chemical data reporting obligations shape US market access parameters. ISO 9235 standards for natural aromatic raw materials influence procurement specifications across fragrance houses. Stakeholders must monitor regulatory divergence between EU hazard classification updates and US TSCA modernization efforts to anticipate reformulation requirements.
Market Dynamics
Fragrance houses are decoupling from petrochemical feedstocks as biotechnology-derived aldehyde platforms compress batch variability and naturality credentials reshape procurement specifications across European and Southeast Asian supply chains.
Growth Catalysts
- REACH registration dossiers:ECHA toxicological requirements elevate purity specifications, filtering marginal suppliers and concentrating volume among compliant manufacturers with full substance characterization.
- Fine fragrance compounding:Niche perfumery and luxury personal care segments redirect volume flows toward higher-margin formulations demanding specific citrus-fatty odor profiles.
- Malaysian oleochemical clusters:Captive lauryl alcohol production infrastructure secures feedstock continuity for integrated aldehyde manufacturers serving Asian fragrance creation centers.
Market Restraints
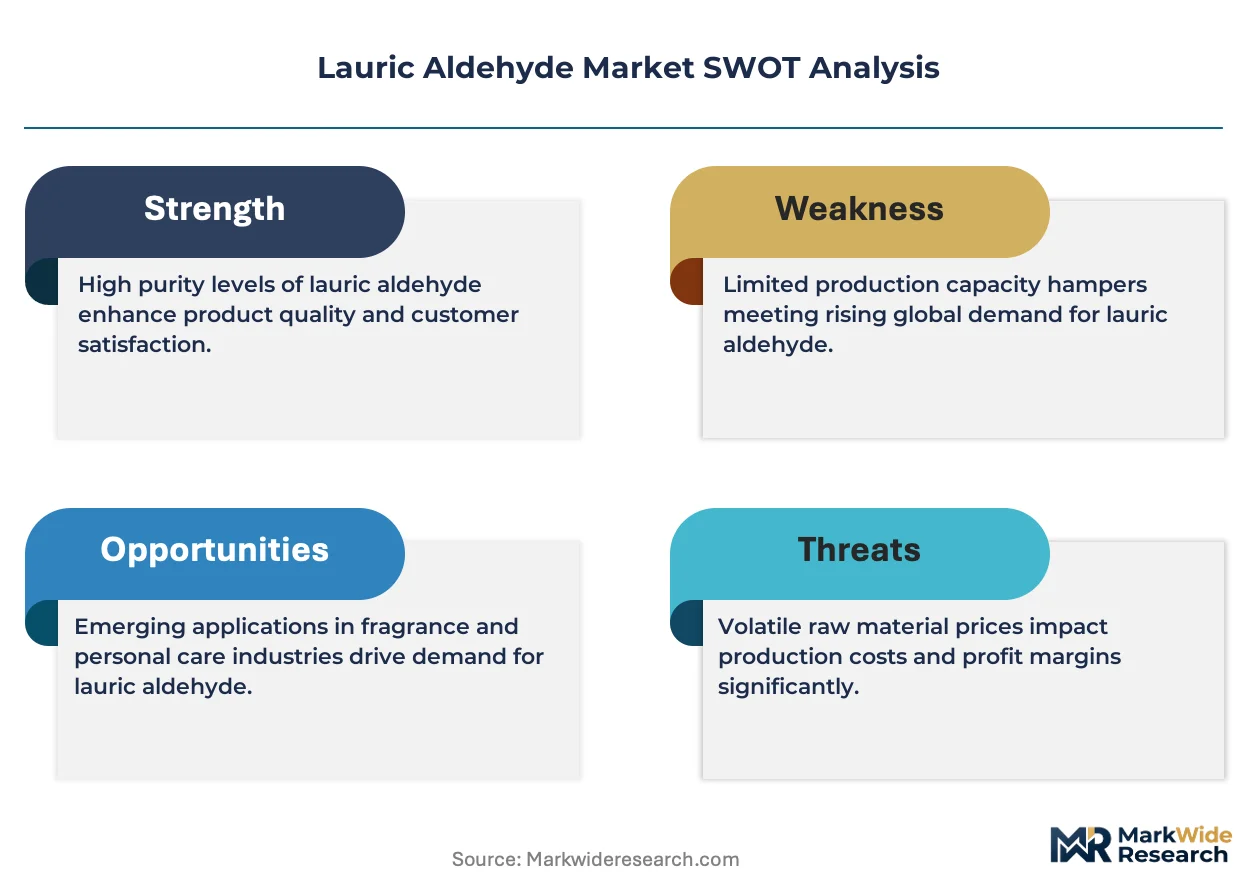
- Coconut and palm kernel oil volatility:Raw material price swings in tropical feedstock markets compress margin predictability for non-integrated producers lacking upstream control.
- Indonesian supply concentration:Geographic clustering of precursor fatty alcohol production creates single-source vulnerability for European and North American formulators.
- Catalytic dehydrogenation yields:Technical limitations in selective oxidation processes constrain throughput efficiency relative to petrochemical aldehyde synthesis routes.
Strategic Opportunities
- Biotechnology convergence:Fermentation-derived aldehyde platforms reduce dependency on agricultural feedstocks while satisfying ISO 9235 natural aromatic raw material specifications.
- Clean-label cosmetics:Formulators in premium skincare and haircare segments seek naturality credentials that biotechnology-derived lauric aldehyde can substantiate through carbon-14 verification.
- US flavorant reassessment:Evolving FDA FEMA GRAS safety evaluations create entry pathways for suppliers with enhanced toxicological documentation exceeding legacy standards.
Industry Challenges
- REACH compliance timelines:Extended substance registration periods and data-sharing negotiations delay market access for new suppliers targeting European fragrance houses.
- Bioprocess scale-up capital:Fermentation infrastructure requires significant fixed investment before achieving cost parity with established catalytic dehydrogenation routes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lauric Aldehyde Market |
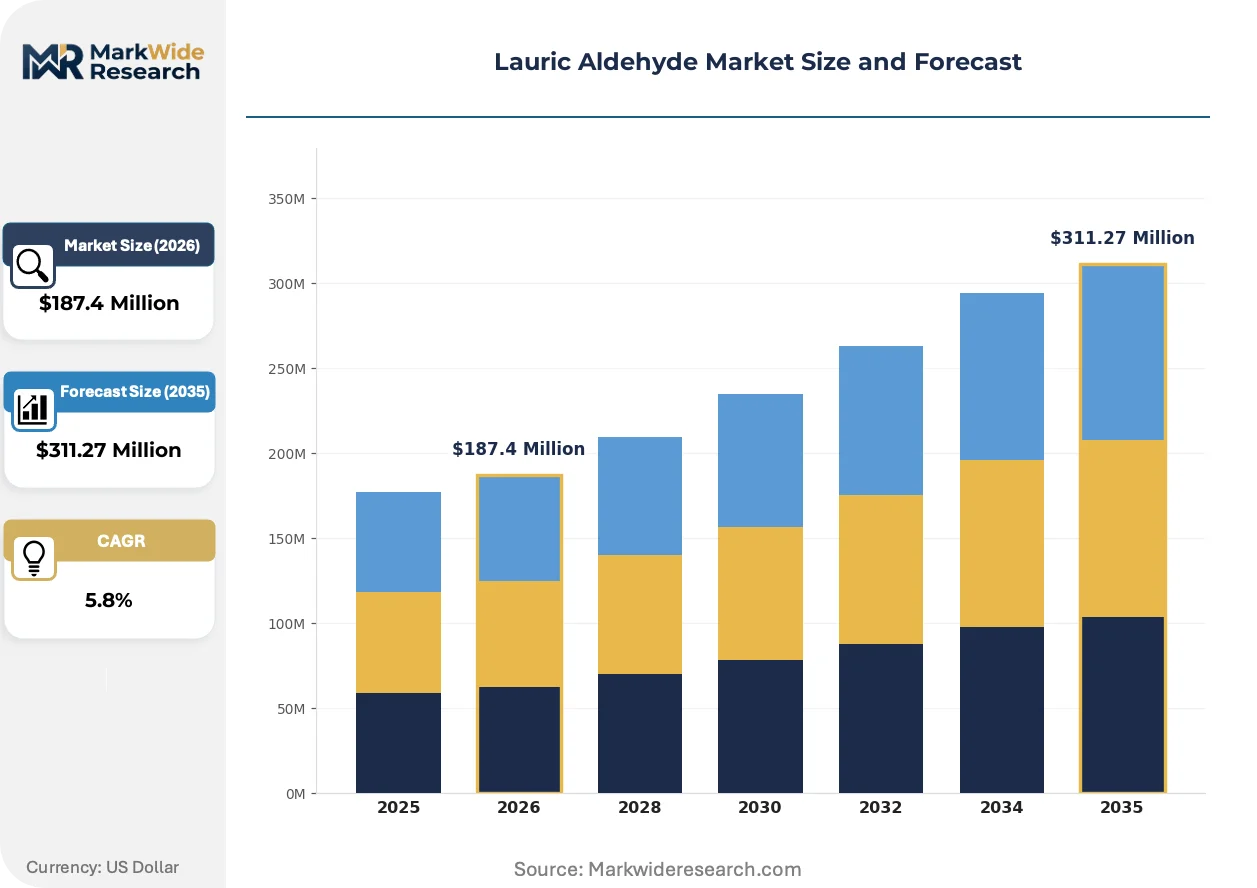
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aldehydes, Ketones, Fatty Alcohols, Esters Application: Fragrance, Flavoring, Cosmetics, Pharmaceuticals End Use Industry: Food & Beverage, Personal Care, Household Products, Healthcare Packaging Type: Drums, Jerricans, IBC Tanks, Bottles |
| Companies Covered | Kao Corporation, Symrise AG, Givaudan SA, Vigon International, Firmenich SA, BASF SE, International Flavors & Fragrances Inc., Sigma-Aldrich (Merck Group), Takasago International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lauric Aldehyde Market Strategic Shifts
Biotechnology platforms are displacing conventional petrochemical synthesis as the primary innovation vector, while regulatory divergence between EU hazard classification and US flavorant safety frameworks forces dual-track compliance architectures.
Enzymatic oxidation pathways for aldehyde production is converging with traditional catalytic processes as fragrance houses seek supply redundancy. Givaudan and Symrise have accelerated internal biotechnology programs to secure captive production capacity. This convergence is compressing the premium pricing historically commanded by natural-extraction methods.
REACH authorization requirements under ECHA now mandate updated toxicological dossiers for lauric aldehyde imports into Europe. The industrial consequence is a bifurcation between compliant suppliers with full substance characterization and non-EU manufacturers facing elevated registration costs. Fine fragrance formulators in Grasse and Geneva are consolidating procurement around pre-registered supply bases.
Buyer concentration among multinational fragrance houses has compressed switching cycles for raw material suppliers. Long-term supply agreements with minimum volume commitments are displacing spot-market transactions. This pattern is most visible in Southeast Asian oleochemical corridors, where Malaysian and Indonesian producers negotiate directly with European creation centers.
Lauric Aldehyde Market Segmentation
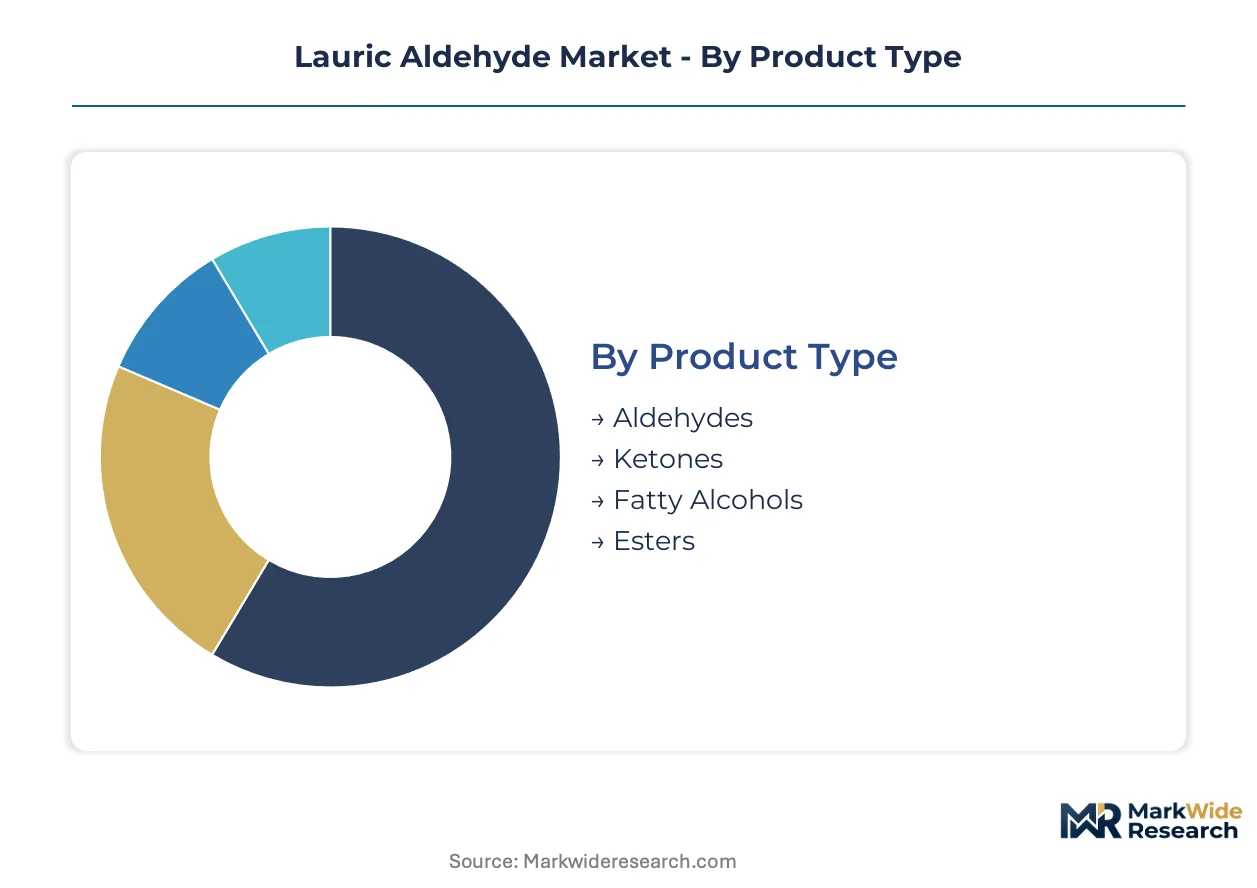
Lauric aldehyde procurement patterns diverge sharply across product grades and application specifications. Formulators select segments based on odor purity thresholds, regulatory documentation depth, and feedstock traceability requirements rather than commodity pricing alone.
Product Type:
Replacement cycles in fragrance compounding favor aldehyde grades with tighter batch-to-batch consistency, driving specification upgrades across synthetic and biotechnology-derived categories.
- Fatty Alcohols:Lauryl alcohol serves as the direct catalytic precursor for lauric aldehyde synthesis via dehydrogenation. Demand concentrates in Malaysian and Indonesian oleochemical corridors where captive upstream integration secures feedstock continuity for integrated manufacturers.
- Aldehydes:Dodecanal specifications for fine fragrance applications require carbon chain purity above 98.5% with minimal branched isomer contamination. European fragrance houses in Grasse and Geneva source these grades under long-term supply agreements with minimum volume commitments.
- Ketones:Co-product streams from fatty alcohol oxidation contain methyl ketone fractions used in industrial solvent applications.
- Esters:Laurate ester derivatives function as emollients and solubilizers in cosmetic base formulations.
Volume placements concentrate in Fatty Alcohols; the faster expansion belongs to Aldehydes.
Application:
Margin structures across application channels separate premium fragrance compounding from commodity flavoring based on documentation burden and odor specificity requirements.
- Fragrance:Fine perfumery formulations deploy lauric aldehyde at 0.1% to 5% concentration for citrus-fatty top notes. Niche and luxury segments in European creation centers command elevated pricing contingent on REACH-registered supply chains and ISO 9235 naturality credentials.
- Cosmetics:Clean-label skincare and haircare brands specify biotechnology-derived grades with carbon-14 verification. Procurement is shifting toward suppliers with fermentation-based platforms that bypass agricultural feedstock volatility.
- Flavoring:FEMA GRAS status governs US food applications, with evolving FDA safety assessments elevating toxicological documentation requirements for new market entrants.
- Pharmaceuticals:Excipient-grade specifications demand full ECHA substance characterization for European market access.
Revenue concentration sits with Fragrance; Cosmetics gains share fastest on clean-label formulation trends.
End Use Industry:
Customer scale and specification rigor separate multinational fragrance houses from regional personal care formulators across end use channels.
- Personal Care:Premium skincare and haircare manufacturers in Southeast Asian manufacturing clusters specify high-purity grades for export-oriented production. Procurement patterns favor suppliers with biotechnology-derived platforms and carbon-14 substantiation.
- Food & Beverage:Flavor houses serving North American markets navigate evolving FDA FEMA GRAS evaluations with enhanced safety dossiers.
- Household Products:Mass-market cleaning and air care applications tolerate broader specification ranges.
- Healthcare:Pharmaceutical excipient demand requires full REACH registration and toxicological characterization.
Procurement volume clusters in Personal Care; Healthcare shows steepest specification escalation.
Packaging Type:
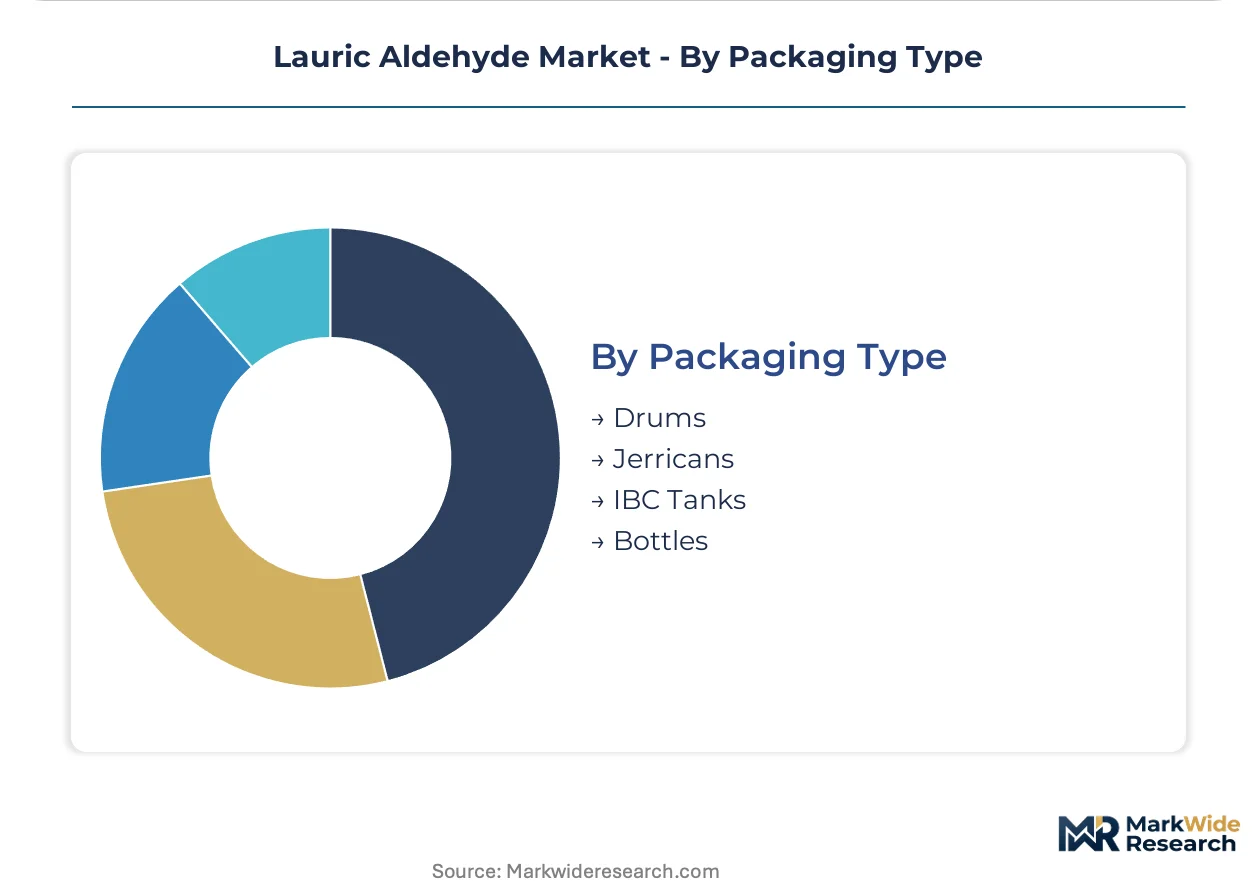
Supply chain configuration and order scale determine packaging selection, with bulk formats dominating integrated manufacturer flows and smaller units serving specialty formulators.
- IBC Tanks:Intermediate bulk containers serve high-volume fragrance compounding facilities with dedicated storage infrastructure. Malaysian and Indonesian producers negotiate direct supply agreements with European creation centers using this format.
- Drums:Standard 200-liter steel drums balance handling efficiency with flexibility for mid-scale formulators.
- Jerricans:Polyethylene containers suit specialty flavor and cosmetic laboratories requiring smaller batch sizes.
- Bottles:Glass or fluorinated polymer bottles preserve odor integrity for analytical reference standards and niche perfumery samples.
Shipment volumes favor IBC Tanks; bottle demand climbs fastest in niche fragrance sampling applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian oleochemical special economic zones and Indonesian industrial parks concentrate upstream lauric aldehyde capacity through tax-advantaged feedstock processing infrastructure.
Malaysia
Kuantan and Pasir Gudang industrial corridors host integrated fatty alcohol-to-aldehyde operations serving European fragrance houses. The Malaysian Investment Development Authority grants pioneer status incentives for biotechnology-derived chemical platforms. Kao Corporation leverages captive lauryl alcohol infrastructure across Johor manufacturing clusters to secure aldehyde feedstock continuity.
Indonesia
Medan and Surabaya oleochemical processing centers process palm kernel oil into fatty alcohol precursors for regional aldehyde synthesis. The country's national industrial regulator enforces emission standards on catalytic dehydrogenation facilities. North Sumatra concentration creates single-source vulnerability for European formulators dependent on Indonesian lauryl alcohol supply.
Germany
Ludwigshafen chemical complexes and Hamburg fragrance distribution hubs anchor European aldehyde formulation and REACH compliance services. ECHA registration dossiers mandate full toxicological characterization for lauric aldehyde imports under REACH authorization timelines. BASF SE maintains integrated aldehyde production serving domestic flavorant and fragrance compounders.
United States
New Jersey flavor houses and California personal care formulators drive demand for FEMA GRAS-certified aldehyde grades. FDA evolving safety assessments for flavorant applications elevate toxicological documentation requirements beyond legacy standards. Sigma-Aldrich distribution networks supply analytical-grade material to pharmaceutical excipient manufacturers.
Switzerland
Geneva and Zurich headquarters of multinational fragrance houses concentrate procurement decision-making for global aldehyde supply agreements. Swissmedic pharmaceutical excipient standards influence purity specifications across European healthcare applications. Firmenich SA anchors premium fragrance creation demand through internal compounding facilities.
Lauric Aldehyde Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated oleochemical producers commanding upstream aldehyde supply while fragrance houses control formulation value capture. The vendor base organizes around three strategic archetypes: captive oleochemical operators with backward integration into fatty alcohols, biotechnology platforms pursuing fermentation-derived routes, and specialty distributors serving analytical and niche perfumery segments. M&A activity concentrates on biotechnology capability acquisition, while capacity expansion focuses on Malaysian and Indonesian feedstock corridors.
Within the integrated oleochemical tier, Kao Corporation and BASF SE exemplify backward-integrated operators controlling precursor supply chains from tropical feedstock through aldehyde finishing. Among biotechnology-focused platforms, Symrise AG occupies a position representing enzymatic oxidation pathways that reduce batch variability. Givaudan SA anchors the fragrance house tier, consolidating procurement around pre-registered European supply bases.
| Leading Market Players |
|---|
| Kao Corporation |
| Symrise AG |
| Givaudan SA |
| Vigon International |
| Firmenich SA |
| BASF SE |
| International Flavors & Fragrances Inc. |
| Sigma-Aldrich (Merck Group) |
| Takasago International Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive oleochemical integration across Malaysian and Indonesian manufacturing clusters anchors both supply security and pricing power for lauric aldehyde producers. This upstream control buffers integrated operators from palm kernel oil volatility while forcing non-integrated competitors into spot-market exposure.
Pricing Analysis
Short lead-time premiums command substantial markups in fine fragrance channels, while spot inventory discounts attract mass-market flavor houses. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered grades with full toxicological dossiers from basic industrial specifications. Cost compression in standard-tier aldehydes is intensifying because Indonesian supply concentration limits alternative sourcing. Mass-market cleaning applications show highest price sensitivity; European niche perfumeries demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore orchestrate hub-and-spoke patterns for European and Asian fragrance houses. Manufacturing concentrates in Malaysia, Indonesia, and Germany, with lauryl alcohol, palm kernel oil, and catalytic hydrogenation equipment as critical inputs. Single-source vulnerability in North Sumatra fatty alcohol production threatens European formulators lacking supply redundancy. Distribution runs through long-term supply agreements with minimum volume commitments rather than spot transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance timelines and bioprocess capital requirements are forcing consolidation, eliminating marginal suppliers unable to sustain registration costs or fermentation scale-up investments.
For Market Incumbents: Cement market position through captive biotechnology platform acquisition and backward integration into Johor-based lauryl alcohol production. Biotechnology-derived competitors threaten premium positioning; ECHA registration maintenance represents the critical defensive lever. For New Entrants and Emerging Players: Begin with carbon-14 verified grades targeting clean-label cosmetics formulators in Southeast Asian export manufacturing. US flavorant reassessment under evolving FDA frameworks offers the most penetrable regulatory entry pathway. Lead with toxicological documentation exceeding legacy FEMA GRAS standards. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated fragrance houses seeking captive biotechnology capacity. Long-term viability favors operators with fermentation-derived platforms and established REACH dossiers. Watch for ECHA authorization timeline acceleration as the key inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Platform Acquisition | Symrise AG and Givaudan SA are securing captive fermentation capacity to reduce batch variability. |
| Backward Integration into Fatty Alcohols | Kao Corporation's Johor manufacturing clusters ensure feedstock continuity for aldehyde synthesis. |
| REACH Registration Investment | Full ECHA toxicological dossiers filter non-compliant suppliers from European fragrance house procurement. |
| Long-term Supply Agreement | Malaysian producers negotiate directly with Grasse creation centers, displacing spot-market transactions. |
| Carbon-14 Verification Program | Clean-label cosmetics brands demand substantiated naturality credentials from biotechnology-derived grades. |
Study Parameters
Multi-period observation of REACH registration timelines, fatty alcohol capacity additions, and biotechnology platform investments anchored the trend analysis, supplemented by interviews with fragrance house procurement directors, oleochemical plant managers, ECHA regulatory consultants, and clean-label cosmetics formulators. Secondary validation drew from ECHA substance databases, Malaysian Investment Development Authority incentive disclosures, SEC filings of listed fragrance houses, and customs trade flow records. Bottom-up volume estimates triangulated against top-down market sizing.
Segment-weighting applied product grade tiers, application channels, end-use industries, and regional production hub configurations across the projection horizon. CAGRs derived from trend extrapolation of historical volume trajectories adjusted for regulatory inflection points. Forecast inputs incorporated palm kernel oil price elasticity and biotechnology scale-up cost curves.
Underlying measurement precision varies by segment; REACH-registered aldehyde grades carry tighter precision than industrial solvent applications. Forecasts assume stable ECHA authorization timelines and sustained Malaysian tax incentives. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Oleochemicals Market
Oleochemicals
Ethoxylated Castor Oil Market
Oleochemicals
Octanoyl Chloride Market
Oleochemicals
Trimethyl Pentanediol Monoisobutyrate Market
Oleochemicals
Iso-Octene Market
Oleochemicals
Global Emollient Esters Market
Oleochemicals
Caprylic/Capric Triglyceride Market
Oleochemicals
Isopropyl Esters Market
Oleochemicals
2-tert-Butylcyclohexanol Market
Oleochemicals
Candelilla Wax Market
Oleochemicals
Isostearic Acid Market
Oleochemicals
Global Oxidized Polyethylene Wax Market
Oleochemicals
Ozokerite Wax Market
Oleochemicals
Rice Bran Wax Market
Oleochemicals
Ethylene Bis Stearamide Market
Oleochemicals
Fatty Acid Ester Market