
 1-Decene Market | 2026-2036
1-Decene Market Size, Share, and Industry Trends Forecast 2026-2036
1-Decene Market Intelligence
Growing consolidation among large-scale polymer and synthetic lubricant producers is recalibrating supply chain relationships in the 1-decene market. This shift favors suppliers with significant production scale and consistent quality control. Chevron Phillips Chemical Company LLC leverages its integrated petrochemical operations to maintain a cost-competitive position. Shell Chemicals sustains its market presence through an extensive global distribution network for its alpha olefins. SASOL specializes in producing 1-decene via its proprietary Fischer-Tropsch synthesis technology, offering a distinct production route.
1-Decene is a linear alpha olefin (LAO), a colorless liquid hydrocarbon with the chemical formula C10H20. It is primarily produced through the oligomerization of ethylene. Its main industrial function is as a comonomer in the production of polymers like linear low-density polyethylene (LLDPE) and high-density polyethylene (HDPE). The application landscape is dominated by polymer production, but the synthetic lubricants segment is expanding rapidly due to demand for high-performance engine oils. Among product types, linear alpha olefins constitute the vast majority of supply, aligning with established manufacturing processes.
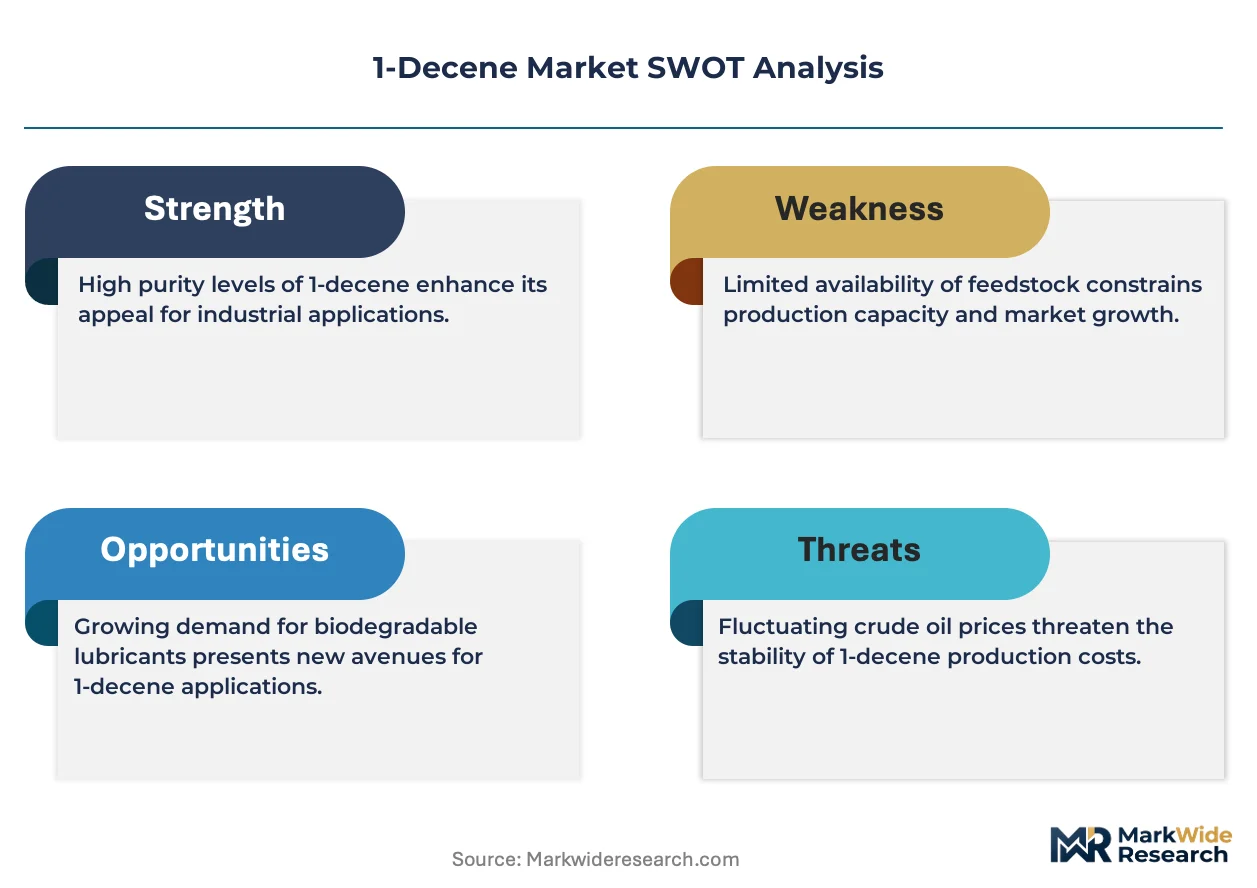
The regulatory environment significantly influences market access and product specifications. In Europe, compliance with REACH and ECHA requirements is mandatory for all chemical substances sold. In the United States, the EPA sets limits on volatile organic compounds (VOCs), which can affect the use of 1-decene in certain coatings and adhesive formulations. These frameworks compel producers to invest in compliance and transparent documentation. The critical decision for suppliers now centers on allocating capital between expanding capacity for high-purity grades for lubricants versus standard grades for polymers.
Market Dynamics
The market's central dynamic is the capital allocation conflict between expanding capacity for standard-grade 1-decene for polymers versus investing in high-purity production lines. This choice is dictated by divergent margin profiles and performance requirements from lubricants versus plastics.
Growth Catalysts
- Emissions Standards:Stricter regulations, such as those from the EPA in the US and under the EU Green Deal, compel the use of advanced synthetic lubricants in modern engines, boosting demand.
- Polymer Innovation:The use of 1-decene as a comonomer in LLDPE production is expanding to create higher-performance films for sophisticated packaging applications demanded in consumer goods.
- Automotive Production:Sustained growth in automotive manufacturing, particularly in China, directly increases the consumption of high-performance polyalphaolefin (PAO) based engine oils and lubricants.
Market Restraints
- Feedstock Volatility:Production costs are directly tied to the price of ethylene, a highly volatile commodity, creating margin pressure for 1-decene manufacturers without integrated upstream operations.
- Substitution Risk:In some polyethylene applications, other comonomers like 1-octene or 1-hexene can be used, posing a technical substitution threat based on price and availability.
- Regulatory Friction:Compliance with Europe's REACH framework requires extensive and costly substance registration, creating a barrier to entry for smaller producers or new market entrants.
Strategic Opportunities
- Bio-Based Production:Developing pathways to produce 1-decene from renewable feedstocks like bio-ethylene presents a significant opportunity to capture sustainability-focused customers and meet ESG mandates.
- New Lubricant Formulations:There is untapped demand for 1-decene in specialized industrial applications, including high-performance industrial gear oils and fluids for the energy sector.
- Geographic Expansion:Targeting the growing industrial and automotive sectors in Southeast Asian nations offers a path to diversify sales beyond established markets in China and North America.
Industry Challenges
- Capital Expenditure:The construction of new world-scale ethylene oligomerization units requires massive upfront capital investment, posing a significant hurdle to capacity expansion.
- Purity Certification:Achieving and consistently documenting the high purity levels required by synthetic lubricant formulators is a significant operational and quality control challenge for producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 1-Decene Market |
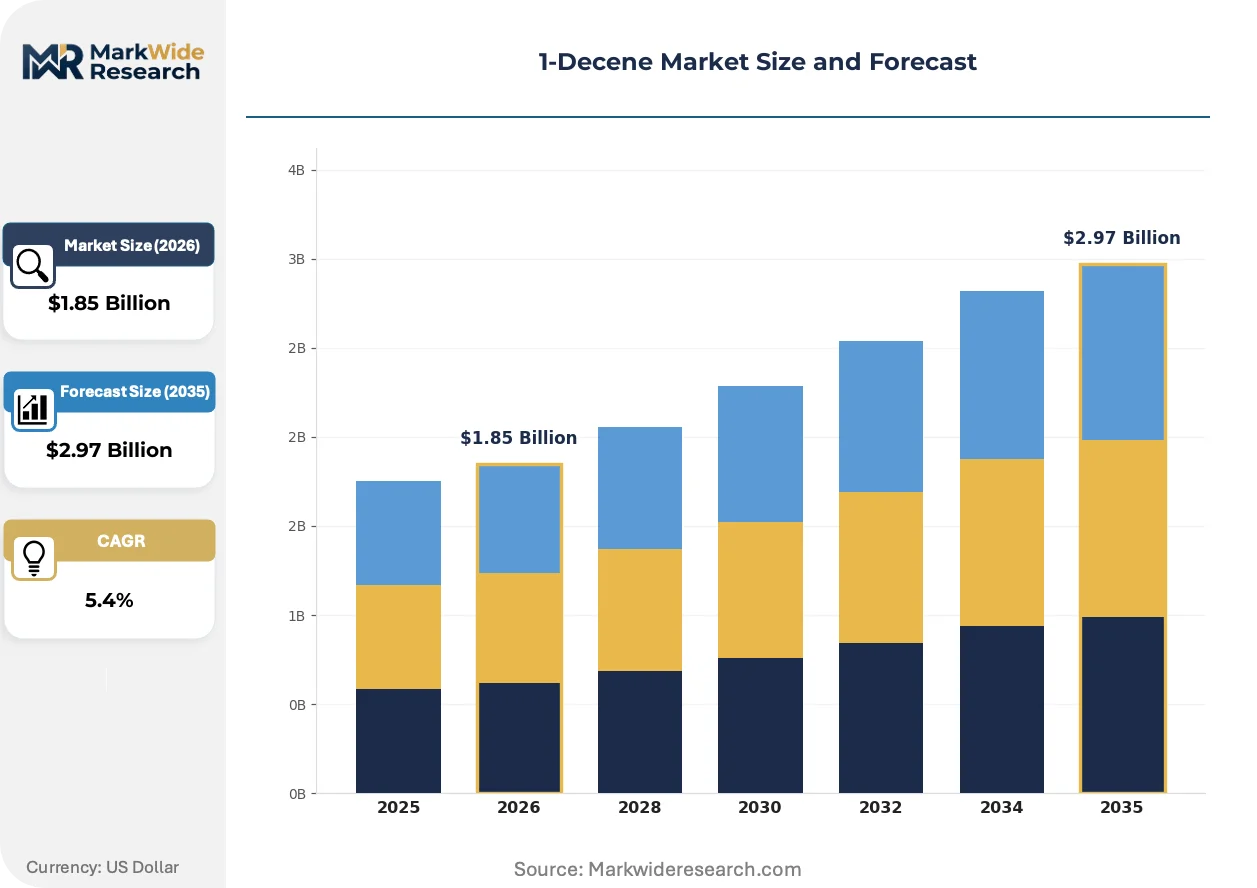
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Alpha Olefins, Internal Olefins, Branched Olefins, Cyclic Olefins, Others Application: Polymer Production, Synthetic Lubricants, Surfactants, Adhesives, Plasticizers, Coatings End User Industry: Chemical Manufacturers, Cosmetics Producers, Automotive Component Makers, Paints & Inks Suppliers, Detergent Suppliers, Industrial Fabricators Packaging Type: Drums, Bulk Tanks, Intermediate Bulk Containers, Iso Containers, Flexible Packaging |
| Companies Covered | Chevron Phillips Chemical Company LLC, Shell Chemicals, INEOS, ExxonMobil Corporation, SABIC, Qatar Chemical Company Ltd, Idemitsu Kosan Co., Ltd, SASOL, LyondellBasell Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
1-Decene Market Strategic Shifts & Innovations
A fundamental shift toward higher-purity grades and sustainable production routes defines the current market evolution. This movement is driven by a convergence of stringent performance requirements in end-use applications and increasing regulatory scrutiny over chemical life cycles.
Advanced process control systems integrate real-time data analytics into ethylene oligomerization. Major chemical producers are adopting these to enhance yield and ensure consistent output quality. This technology is automating critical quality control checks and process adjustments, reducing batch-to-batch variability for high-performance lubricants.
The EU Green Deal's chemicals strategy creates new compliance obligations for producers in Europe. This framework incentivizes documenting product life-cycle emissions and encourages sustainable manufacturing. The synthetic lubricants segment is most affected, prompting investment in alternative production routes and bio-based feedstocks to meet market access rules.
Buyers in the synthetic lubricants sector are adopting performance-based specifications for procurement. This shift disrupts the commodity sales model, favoring suppliers with extensive application testing data and technical support. The trend is most prominent within high-performance automotive and industrial lubricant markets in North America and Europe.
1-Decene Market Segmentation
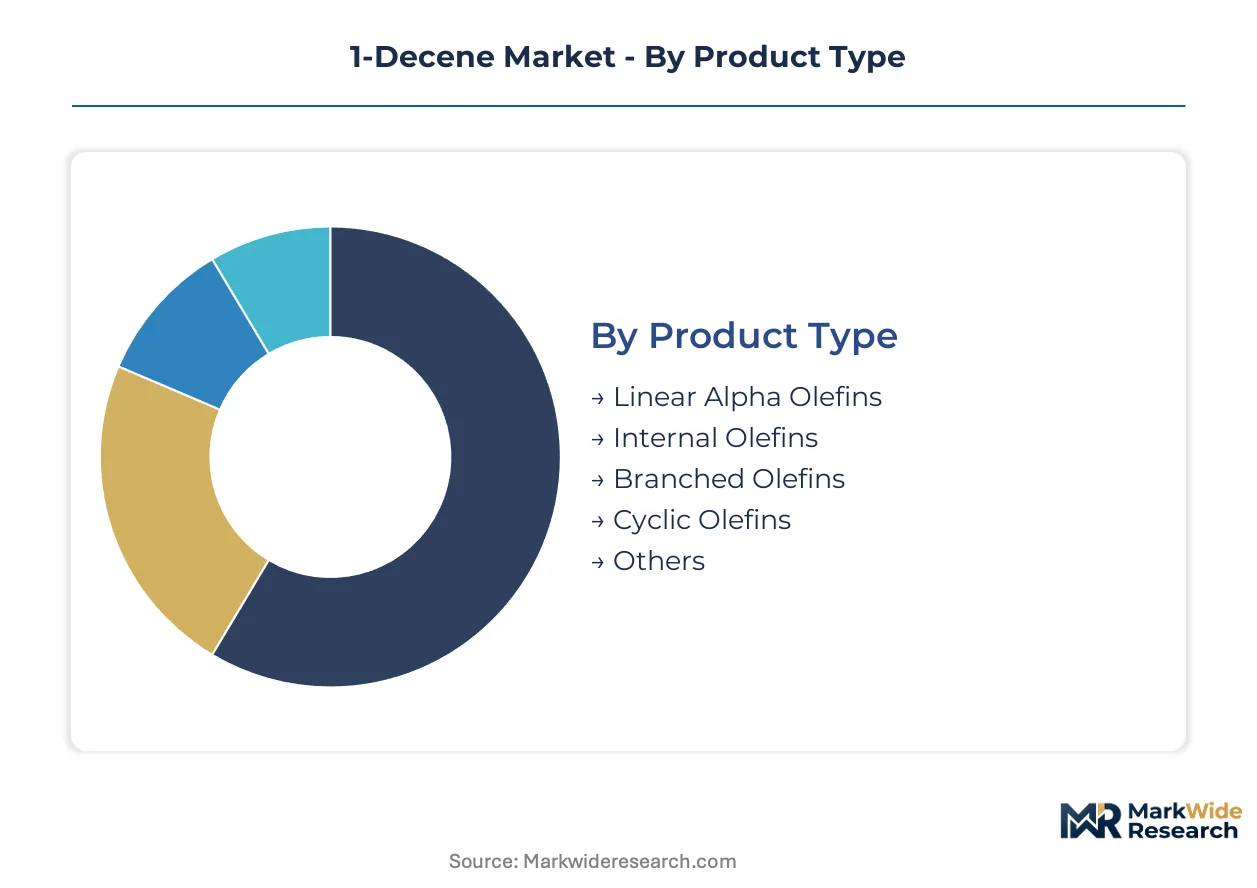
The 1-decene market segments reflect the diverse applications and purity requirements driving demand. Understanding these distinct categories provides clarity on supply chain dynamics and strategic investment priorities. This segmentation analysis dissects the market's structure, revealing where value is created and captured.
Product Type:
Buyers in the 1-decene market differentiate their procurement based on the specific molecular structure and purity profile required for their downstream processes.
- Linear Alpha Olefins:These are straight-chain hydrocarbons with a double bond at the alpha (first) carbon, typically C10H20. Demand concentrates heavily in polymer production, particularly for LLDPE and HDPE, due to their excellent comonomer properties.
- Internal Olefins:Internal olefins feature the double bond located within the carbon chain, not at the terminal position. Their application extends to specialized lubricants and detergents, where their distinct reactivity offers performance advantages over alpha olefins.
- Branched Olefins:Branched olefins possess side chains, influencing their physical properties and suitability for specific plasticizer and synthetic fluid formulations.
- Cyclic Olefins:Cyclic olefins, characterized by a ring structure, find niche uses in advanced polymer synthesis and specialty chemical intermediates.
- Others:This category encompasses various other olefinic structures and blends, catering to highly specialized research and industrial applications.
Volume sits with Linear Alpha Olefins; growth tilts toward Internal Olefins due to specialized lubricant demand.
Application:
The utility of 1-decene is defined by its end-use application, dictating required purity and performance characteristics for diverse industrial processes.
- Polymer Production:This application utilizes 1-decene as a comonomer to enhance the properties of polyethylene, such as strength and flexibility. Demand is high in China, driven by expansive LLDPE and HDPE manufacturing for packaging and films.
- Synthetic Lubricants:1-decene serves as a primary feedstock for polyalphaolefins (PAOs), crucial for high-performance engine oils and industrial fluids. Stricter emissions standards in the US and Europe compel the use of these advanced lubricant formulations.
- Surfactants:1-decene derivatives are employed in surfactant manufacturing, contributing to the efficacy of cleaning agents and emulsifiers.
- Adhesives:Certain adhesive formulations incorporate 1-decene to improve flexibility, tack, and overall bond strength in specialized products.
- Plasticizers:1-decene-based plasticizers enhance the workability and flexibility of polymers, particularly in PVC applications.
- Coatings:1-decene finds use in specific coating formulations, offering improved durability and chemical resistance for industrial finishes.
This segment reflects the market's core demand drivers, with Polymer Production dominating overall consumption.
End User Industry:
End-user industries define their 1-decene procurement based on their specific manufacturing processes and regulatory compliance needs.
- Chemical Manufacturers:These entities consume 1-decene as a critical intermediate for synthesizing various downstream products, including polyalphaolefins and specialty chemicals. Their demand is extensive across global petrochemical hubs, particularly in China.
- Cosmetics Producers:Cosmetics producers utilize 1-decene derivatives in formulations for personal care products, valuing their emollient and stabilizing properties.
- Automotive Component Makers:This industry relies on 1-decene-derived lubricants for engine oils and transmission fluids, meeting stringent performance requirements for modern vehicles. Demand correlates directly with global automotive production volumes, especially in Asia.
- Paints & Inks Suppliers:Paints and inks suppliers incorporate 1-decene into their formulations to improve flow characteristics, drying times, and film properties.
- Detergent Suppliers:Detergent suppliers use 1-decene as a feedstock for producing specific surfactants that enhance cleaning efficiency.
- Industrial Fabricators:Industrial fabricators employ 1-decene in specialized cutting fluids, coolants, and processing aids for metalworking applications.
The sector's growth trajectory is heavily influenced by the expansion of Chemical Manufacturers and the evolving needs of Automotive Component Makers.
Packaging Type:
Packaging types for 1-decene are determined by shipment volume, logistics infrastructure, and specific customer handling requirements.
- Drums:Drums are utilized for smaller volume shipments of 1-decene, suitable for customers with lower consumption rates or specialized needs.
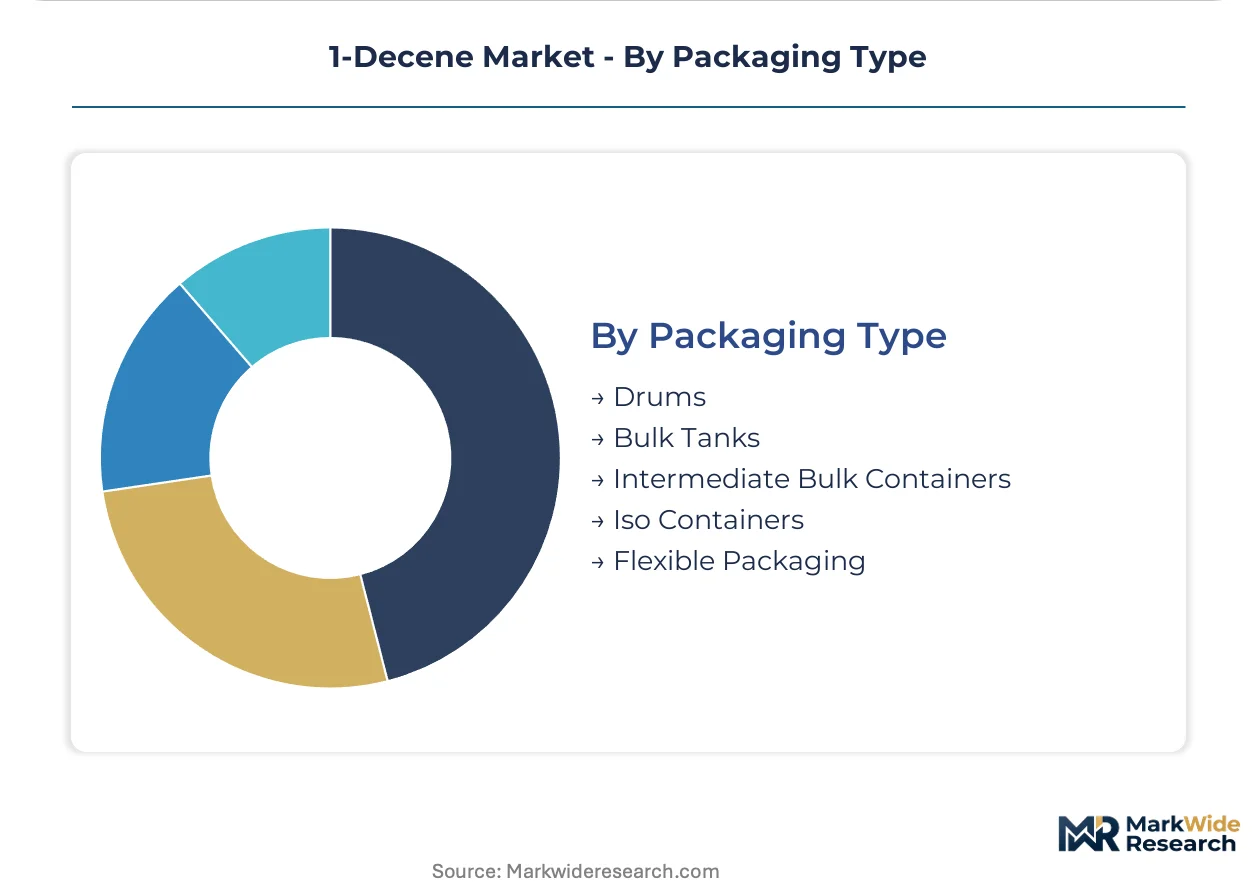
- Bulk Tanks:Bulk tanks facilitate large-volume transportation of 1-decene, primarily for major industrial consumers with integrated storage facilities. This method is cost-effective for high-volume transfers to chemical manufacturers.
- Intermediate Bulk Containers:IBCs offer a middle-ground solution for 1-decene transport, balancing volume capacity with ease of handling for various end-users.
- Iso Containers:Iso containers provide efficient intermodal transport for 1-decene across continents, ensuring product integrity for international trade. They are critical for supplying distant markets like Southeast Asia from major production hubs.
- Flexible Packaging:Flexible packaging solutions are emerging for specific 1-decene derivatives, offering lightweight and customizable options for niche applications.
Logistics efficiency and cost considerations drive the preference for Bulk Tanks in large-scale deliveries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for 1-decene concentrates significantly in regions with robust chemical manufacturing and automotive production. This linear alpha olefin finds extensive use in polymer production and advanced synthetic lubricants. Stricter emissions standards worldwide are also compelling increased adoption of high-performance formulations.
China
China's expansive chemical manufacturing sector drives substantial 1-decene demand for polymer production. The country's dual carbon goals incentivize more efficient chemical processes and sustainable materials. Major petrochemical complexes in the Yangtze River Delta continue to expand LLDPE and HDPE capacity.
United States
The United States petrochemical industry requires 1-decene for both polymer synthesis and high-performance synthetic lubricants. EPA regulations on volatile organic compounds influence coating and adhesive formulations utilizing 1-decene derivatives. The Gulf Coast region, a hub for chemical production, sees continuous investment in alpha olefin capacity.
Germany
Germany's advanced automotive sector and specialty chemical industry create strong demand for 1-decene in synthetic lubricants. The EU Green Deal's chemicals strategy mandates stringent compliance for chemical substances sold within the bloc. Chemical parks in the Rhine-Main area focus on developing high-purity grades for specialized applications.
India
India's rapidly expanding automotive production and packaging film industry increase 1-decene consumption. The country's PLI scheme for automotive and chemical sectors encourages domestic manufacturing and innovation. Petrochemical clusters in Gujarat are scaling up production to meet rising industrial requirements.
Japan
Japan's sophisticated industrial base and advanced materials sector demand high-purity 1-decene for specialized polymers and lubricants. METI regulations often guide industrial chemical standards and promote energy efficiency in manufacturing. Major chemical producers in the Tokyo Bay area invest in process optimization for alpha olefin synthesis.
1-Decene Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue high-purity grades for specialized lubricant applications. The 1-decene market exhibits consolidation among major petrochemical players with significant vertical integration. Strategic archetypes include integrated chemical giants, specialized technology providers, and regional commodity suppliers. Competitive moves center on capacity expansion, particularly for high-purity grades, and forming strategic partnerships to secure feedstock and enhance distribution.
Among integrated petrochemical giants, Chevron Phillips Chemical Company LLC exemplifies a cost-competitive position through its extensive upstream operations and scale. Shell Chemicals, a global energy and chemicals corporation, maintains market presence via its broad distribution network for alpha olefins and diversified product portfolio. SASOL, a South African chemical and energy company, occupies a specialized technology niche, producing 1-decene using its proprietary Fischer-Tropsch synthesis. These companies collectively represent diverse approaches to market leadership within the 1-decene landscape, from feedstock integration to unique process technologies.
| Leading Market Players |
|---|
| Chevron Phillips Chemical Company LLC |
| Shell Chemicals |
| INEOS |
| ExxonMobil Corporation |
| SABIC |
| Qatar Chemical Company Ltd |
| Idemitsu Kosan Co., Ltd |
| SASOL |
| LyondellBasell Industries |
| Others |
Cost & Logistics Intelligence
High-purity grade divergence in 1-decene significantly impacts both pricing and supply chain configurations. This split reflects distinct performance requirements for synthetic lubricants versus standard polymer applications.
Pricing Analysis
Volume-driven standard-grade 1-decene commands lower margins compared to high-purity variants for specialized lubricants. The dominant pricing structure involves contract-based long-term offtake agreements, supplemented by spot market transactions. Price differentiation arises from quality grade, volume scale, and bundled technical support. Pricing softness for standard grades stems from ethylene feedstock volatility. Polymer producers exhibit high price sensitivity, while synthetic lubricant formulators prioritize performance over price for high-purity inputs.
Supply Chain Analysis
Certification and qualification gating significantly influences the 1-decene supply chain, particularly for high-purity lubricant grades. Supply concentrates in major petrochemical hubs like the United States, China, and the Middle East. The production relies heavily on ethylene as a primary feedstock. A key structural risk is the commodity price volatility of ethylene, impacting manufacturer margins. Distribution runs primarily through bulk tanks for large-scale chemical manufacturers, complemented by ISO containers for efficient intercontinental transport.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 1-decene market represents a consolidation play, driven by the massive capital expenditure required for new ethylene oligomerization units. This financial hurdle forces out smaller, less integrated producers.
For Market Incumbents: Lock in long-term supply agreements with key automotive and polymer customers to secure demand. Deepen upstream control over ethylene feedstock to mitigate price volatility and enhance cost competitiveness. Invest in advanced process control systems to consistently meet stringent purity requirements for synthetic lubricants. This strategy counters substitution risk from alternative alpha olefins in certain polymer applications.
For New Entrants and Emerging Players: Sustainability-focused industrial buyers represent an underserved archetype for bio-based 1-decene. Target niche applications in high-performance industrial gear oils or fluids for the energy sector. Develop proprietary bio-based production pathways to capture customers seeking ESG-compliant materials. Offer extensive application testing data and technical support as a go-to-market differentiator.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated chemical giants with established global distribution networks. The 1-decene market offers long-term viability due to sustained demand from automotive and packaging sectors. Acquire companies with proprietary Fischer-Tropsch synthesis technology or significant capacity for high-purity grades. A critical signal to watch is the acceleration of regulatory frameworks favoring bio-based chemical production.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for High-Purity Grades | Addresses growing demand for advanced synthetic lubricants in automotive. |
| Backward Integration into Ethylene Production | Mitigates feedstock price volatility and enhances cost control for manufacturers. |
| Green Manufacturing Transition | Attracts sustainability-focused customers and ensures compliance with evolving regulations. |
| Long-term Supply Agreement with OEMs | Secures stable demand for 1-decene in the high-performance automotive sector. |
| Joint Venture for Bio-Based Production | Accelerates development of renewable 1-decene, meeting ESG mandates. |
Research Approach
Document review covered customs/trade data, ACC/Cefic reports, SEC 10-K filings, and government regulatory documents, complemented by interviews. Primary research engaged plant managers, procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors. This approach facilitated bottom-up and top-down triangulation to validate market data and insights.
The quantitative model produced detailed volume and value forecasts across the analysis window. Segmentation dimensions included product type, application, end-user industry, packaging type, and regional production hub. Compound annual growth rates derived from historical trends and projected future demand. Key industry-specific forecast inputs included ethylene price forecasts and global automotive production volumes.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical instability and significant technological breakthroughs in alternative feedstocks. Forecasts reflect documented assumptions at the time of publication. A model refresh is warranted upon material change in ethylene supply or demand dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Squalane Market
Oleochemicals
Stearoyl Lactylates Market
Oleochemicals
Rice Bran Wax Market
Oleochemicals
2-tert-Butylcyclohexanol Market
Oleochemicals
Global Methyl Ester Ethoxylate Market
Oleochemicals
Global Hexyl Cinnamal Market
Oleochemicals
Tall Oil Rosin Market
Oleochemicals
Ethyl Linalool Market
Oleochemicals
Pentalide (Cyclopentadecanolide) Market
Oleochemicals
Lauric Aldehyde Market
Oleochemicals
Allyl Caproate Market
Oleochemicals
Lipid Rich Powder Market
Oleochemicals
Fatty Acid Amides Market
Oleochemicals
Triisostearyl Citrate Market
Oleochemicals
Ozokerite Wax Market
Oleochemicals
Ethylhexyl Cocoate Market