
 Global Decant Oil Market | 2026-2036
Global Decant Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Decant Oil Market Foresight
Petroleum coke is realigning product economics across downstream refining as decant oil competes for residuum upgrading pathways. ExxonMobil leverages its integrated Gulf Coast refining network to sustain heavy feedstock processing flexibility. Royal Dutch Shell plc anchors European decant oil supply through its Pernis and Rheinland complex operations. Chevron Corporation differentiates via technology leadership in hydrocracking residuum into lighter, higher-value decant oil fractions.
Decant oil is a heavy petroleum distillate produced during fluid catalytic cracking, typically characterized by API gravity below 20 degrees and elevated aromatic content above 50 percent by weight. Refiners process it into carbon black feedstock, needle coke precursors, and fuel oil blending components for industrial combustion systems. Heavy Decant Oil and Vacuum Gas Oil occupy the dominant volume positions, reflecting their centrality to coker and hydrocracker feed slates. Chemical Feedstock applications represent the fastest-expanding demand segment, driven by carbon fiber precursor and synthetic graphite manufacturing requirements.
The EPA enforces fuel sulfur standards under the Clean Air Act that constrain high-sulfur decant oil combustion in US power generation and marine applications. REACH registration requirements in Europe govern aromatic hydrocarbon classifications, affecting decant oil import specifications and downstream chemical use approvals. China's MEE administers dual carbon goals that redirect refinery residuum processing toward lower-emission upgrading routes including decant oil hydrotreating. Stakeholders must monitor evolving carbon border adjustment mechanisms and marine fuel sulfur enforcement to anticipate regional price spreads and arbitrage opportunities.
Market Dynamics
IMO sulfur caps and carbon border mechanisms are forcing refiners to redirect residuum processing toward hydrotreated decant oil streams, compressing margins on high-sulfur fuel oil alternatives while opening premium pricing for compliant feedstock grades.
Growth Catalysts
- Marine fuel compliance:IMO 2020 sulfur regulations redirect ship operators toward low-sulfur bunker blends incorporating hydrotreated decant oil as a compliant base stock.
- Carbon fiber precursor demand:Synthetic graphite manufacturers expand needle coke offtake for lithium-ion battery anodes, pulling heavy aromatic decant oil fractions into chemical feedstock upgrading.
- China's refining integration:Sinopec and PetroChina operate residuum conversion complexes that upgrade vacuum resid into higher-value decant oil for domestic carbon black and electrode markets.
Market Restraints
- Crude sulfur volatility:Heavy sour crude differentials swing processing economics, forcing refiners to toggle between coker feed and fuel oil blending based on real-time margin capture.
- EPA combustion constraints:Clean Air Act sulfur standards block high-aromatic decant oil from US power generation, limiting outlet options for non-upgraded streams.
- Petroleum coke substitution:Sponge coke and fuel-grade petcoke compete for the same residuum feedstock pool, diverting volume from decant oil production during tight crude runs.
Strategic Opportunities
- India's delayed coker capacity:Reliance and Indian Oil expand residuum conversion units, creating import demand for heavy decant oil feedstock ahead of domestic supply ramp.
- EU carbon border adjustments:CBAM implementation favors low-carbon-intensity decant oil imports, rewarding hydrotreated streams with compliance premiums over conventional fuel oil.
- Battery anode convergence:Needle coke specifications tighten for EV-grade synthetic graphite, pulling ultra-low-sulfur decant oil into dedicated precursor processing contracts.
Industry Challenges
- Hydrotreater catalyst expertise:Residuum desulfurization requires specialized NiMo catalyst management that refiners struggle to staff amid retiring technical workforces.
- REACH aromatic registration:ECHA classification delays for high-PAH decant oil batches stall EU chemical feedstock approvals, extending inventory holding periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Decant Oil Market |
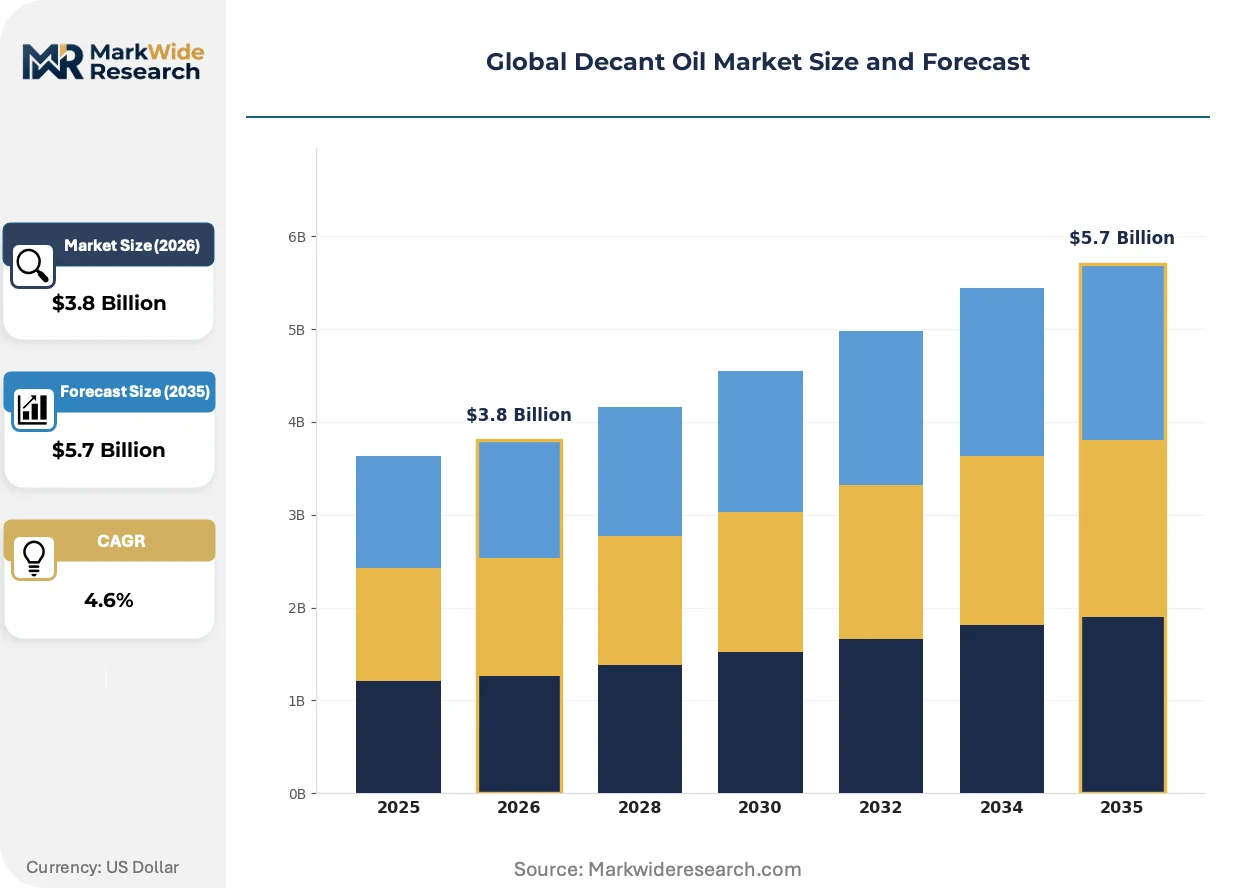
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Decant Oil, Medium Decant Oil, Heavy Decant Oil, Vacuum Gas Oil, Residual Oil Application: Fuel Blending, Industrial Lubricants, Asphalt Production, Paint Solvents, Chemical Feedstock End User Industry: Power Generation, Marine Vessels, Construction Machinery, Metal Fabrication, Mining Operations Packaging Type: Drums, IBC Totes, Bulk Tankers, Jerry Cans, Steel Barrels |
| Companies Covered | ExxonMobil Corporation, Royal Dutch Shell plc, Chevron Corporation, BP plc, TotalEnergies SE, Sinopec Corp., Saudi Arabian Oil Company, Reliance Industries Limited, PetroChina Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Decant Oil Market Shifts & Advancements
Processing flexibility and regulatory compliance are converging to reshape how refiners configure residuum upgrading trains, with technology investments clustering around sulfur removal and carbon intensity reduction.
Modular hydrotreating skids are decentralizing residuum processing economics by enabling smaller refiners to upgrade marginal decant oil streams without billion-dollar coker investments. Independent US Gulf Coast operators deploy these units to capture IMO-compliant bunker premiums. The technology is decentralizing supply concentration away from integrated majors toward mid-scale processors.
REACH aromatic hydrocarbon reclassification is tightening import specifications for European decant oil chemical feedstock applications. ECHA's updated substance evaluations extend registration timelines for high-PAH streams. Carbon black manufacturers in Germany and the Netherlands accelerate hydrotreater partnerships to secure compliant supply.
Long-term offtake contracting is displacing spot market exposure among needle coke producers seeking battery-grade feedstock security. Synthetic graphite manufacturers in Japan and South Korea lock in multi-year decant oil supply agreements. This pattern concentrates procurement leverage with integrated refiners possessing residuum conversion flexibility.
Global Decant Oil Market Segmentation
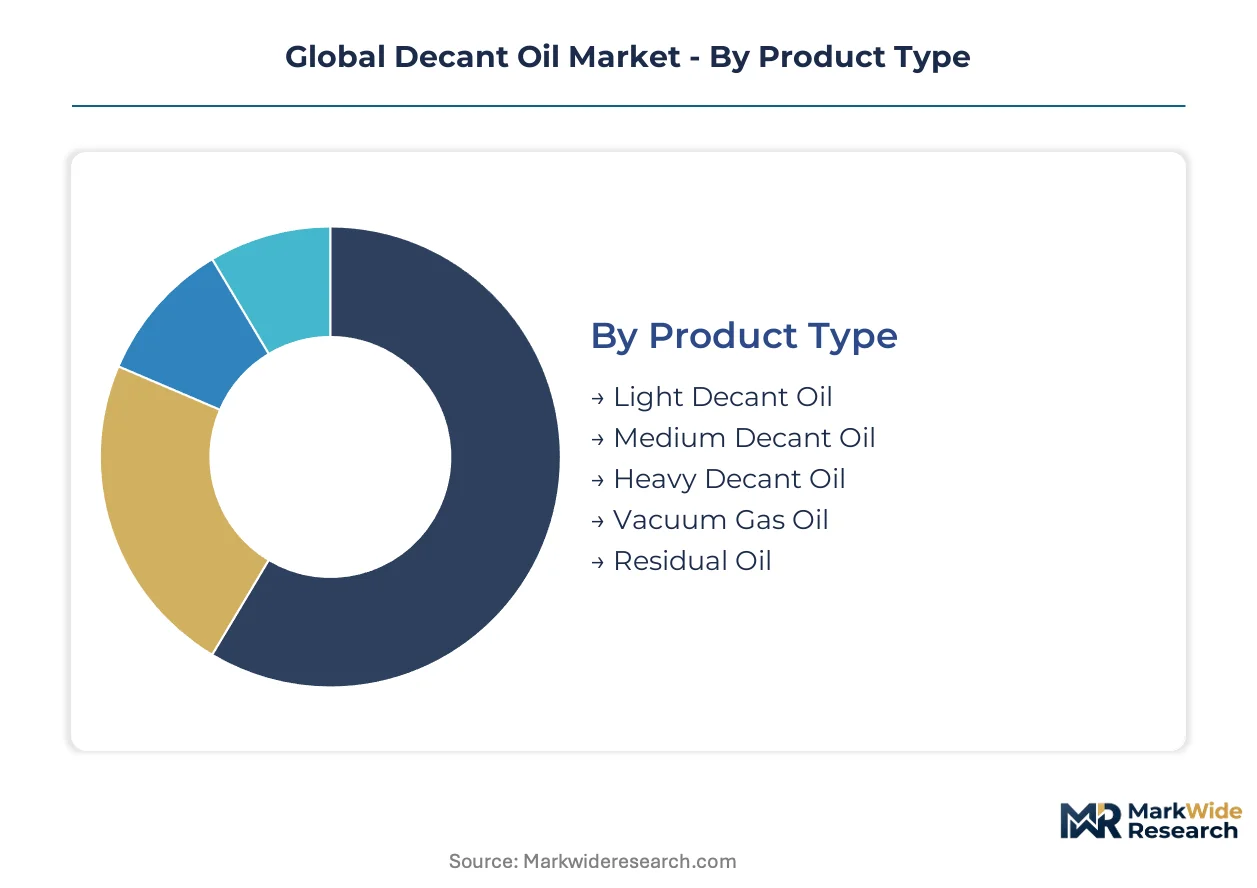
Decant oil market segmentation reveals how refinery output streams fragment across distinct value chains. Product viscosity and sulfur content determine upgrade economics, while end-use specifications dictate regional trade flows and processing investments.
Product Type:
Supply concentration in heavy residuum conversion capacity shapes competitive positioning across viscosity grades.
- Heavy Decant Oil:Dense aromatic fraction with API gravity below 15 degrees and sulfur content frequently exceeding 2.5 percent by weight. Demand concentrates in China's Shandong Province, where Sinopec's residuum conversion complexes feed domestic carbon black manufacturers facing tightening MEE emission standards.
- Vacuum Gas Oil:Intermediate distillate bridging atmospheric and vacuum residuum processing, characterized by 20-30 degree API gravity and moderate metals content. Hydrocracker feed demand in India's Gujarat cluster pulls imports ahead of Reliance's coker capacity expansion, creating premium pricing for low-sulfur VGO cargoes.
- Light Decant Oil:Higher API gravity stream suited to fuel oil blending without extensive hydrotreating.
- Medium Decant Oil:Mid-range viscosity fraction balancing upgrade economics against transport fuel yields.
- Residual Oil:Unconverted bottoms requiring coker or visbreaker processing for value recovery.
Today's leader: Heavy Decant Oil. Tomorrow's challenger: Vacuum Gas Oil.
Application:
Cost tier stratification separates commodity fuel blending from premium chemical feedstock conversion pathways.
- Chemical Feedstock:High-purity aromatic streams refined into needle coke precursors for synthetic graphite manufacturing. Battery anode specifications in Japan and South Korea lock in multi-year offtake contracts, pulling ultra-low-sulfur decant oil away from spot fuel markets.
- Fuel Blending:Marine bunker formulation represents the dominant volume outlet, with IMO 2020 compliance driving hydrotreater investments across US Gulf Coast independent refiners.
- Industrial Lubricants:Base oil extraction from lighter decant oil fractions.
- Asphalt Production:Residual binding agent applications in road construction.
- Paint Solvents:Niche aromatic solvent recovery for coatings manufacturing.
Chemical Feedstock commands margin premiums. Fuel Blending retains volume dominance.
End User Industry:
Customer type fragmentation distributes demand across regulated combustion markets and industrial manufacturing.
- Marine Vessels:IMO sulfur caps redirect ship operators toward low-sulfur bunker blends incorporating hydrotreated decant oil as compliant base stock. Singapore and Rotterdam bunkering hubs concentrate procurement leverage with integrated refiners possessing residuum flexibility.
- Power Generation:EPA Clean Air Act constraints block high-aromatic decant oil from US utility combustion, limiting outlet options to upgraded low-sulfur streams.
- Construction Machinery:Off-road diesel equipment fuel specifications.
- Metal Fabrication:Heat treatment and cutting fluid applications.
- Mining Operations:Remote power generation and heavy equipment fueling.
Marine compliance requirements reshape procurement. Power generation faces regulatory compression.
Packaging Type:
Volume scale and logistics infrastructure determine packaging economics across terminal and distributed delivery models.
- Bulk Tankers:Dedicated vessel and railcar shipments dominate inter-regional trade, with integrated refiners capturing economies of scale in long-haul supply to Asian carbon black clusters.
- IBC Totes:Intermediate bulk containers serve mid-scale chemical processors requiring flexible delivery schedules without terminal infrastructure investment.
- Drums:Standard 55-gallon containers for specialty chemical applications.
- Steel Barrels:Heavy-duty containment for high-viscosity residual grades.
- Jerry Cans:Small-format packaging for laboratory and pilot-scale consumption.
Bulk infrastructure anchors supply security. IBC flexibility captures specialty demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province's residuum conversion complexes anchor global decant oil supply concentration, with integrated refiners upgrading vacuum resid into higher-value aromatic streams for carbon black and electrode manufacturing clusters.
China
Sinopec and PetroChina operate integrated refining complexes that upgrade residual fractions into decant oil products for domestic chemical feedstock markets. The MEE administers dual carbon goals that redirect refinery residuum processing toward lower-emission upgrading routes including hydrotreating. Shandong Province concentrates carbon black manufacturing demand, pulling heavy aromatic decant oil into domestic electrode and synthetic graphite supply chains.
United States
Independent Gulf Coast refiners deploy modular hydrotreating skids to capture IMO-compliant bunker premiums from low-sulfur decant oil blending. The EPA enforces Clean Air Act sulfur standards that constrain high-aromatic decant oil combustion in power generation applications. Houston and Corpus Christi terminal infrastructure anchors inter-regional bulk shipments to Asian carbon black clusters.
India
Reliance Industries and Indian Oil expand residuum conversion capacity, creating import demand for heavy decant oil feedstock ahead of domestic supply ramp. The country's national petroleum regulator oversees fuel quality specifications affecting bunker blending formulations. Gujarat's refining cluster pulls low-sulfur VGO cargoes at premium pricing for hydrocracker feed demand.
Japan
Synthetic graphite manufacturers lock in multi-year decant oil offtake contracts for battery-grade needle coke precursor production. METI oversees industrial chemical standards affecting aromatic hydrocarbon import classifications. Osaka and Nagoya industrial corridors concentrate carbon fiber precursor demand, pulling ultra-low-sulfur decant oil away from spot fuel markets.
Germany
Carbon black manufacturers accelerate hydrotreater partnerships to secure REACH-compliant decant oil supply for chemical feedstock applications. ECHA classification delays for high-PAH batches stall import approvals, extending inventory holding periods. The Ruhr industrial region and Rotterdam-adjacent processing facilities concentrate European demand for low-aromatic decant oil streams.
Global Decant Oil Market Competitive Landscape
Global majors compete with regional champions across residuum conversion capacity and marine fuel compliance certification. The vendor base stratifies into integrated refining networks, national oil companies with captive feedstock access, and independent processors leveraging modular upgrading technology. Three archetypes dominate: scale-driven integrated majors, state-backed Asian refiners with domestic demand anchoring, and flexible Gulf Coast independents capturing spot premiums. Competitive positioning depends on backward integration into crude supply and forward control over carbon black and needle coke offtake relationships.
Within the integrated major tier, ExxonMobil Corporation and Royal Dutch Shell plc occupy positions exemplifying scale-driven residuum processing flexibility across multiple geographies. Chevron Corporation sits within the technology-differentiated archetype, while Sinopec Corp. and PetroChina Company Limited represent state-backed national champions with captive domestic demand anchoring. Saudi Arabian Oil Company exemplifies the crude-integrated model with upstream feedstock security. These named entities anchor market structure without implying specific strategic actions or market share positions beyond their visible industry roles.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Royal Dutch Shell plc |
| Chevron Corporation |
| BP plc |
| TotalEnergies SE |
| Sinopec Corp. |
| Saudi Arabian Oil Company |
| Reliance Industries Limited |
| PetroChina Company Limited |
| Others |
Supply & Pricing Matrix
Captive residuum conversion at integrated Gulf Coast and Shandong Province refineries anchors supply security and pricing leverage for needle coke precursor streams. This backward integration into vacuum resid upgrading insulates majors from crude sulfur volatility while compressing margins for merchant processors dependent on spot VGO cargoes.
Pricing Analysis
Crude sulfur differentials pass through directly to hydrotreated decant oil premiums, with heavy sour discounts widening processing spreads for coker-fed producers. Three-tier pricing structure across battery-grade, marine-compliant, and fuel oil blending levels separates ultra-low-sulfur needle coke feedstock from IMO 2020 bunker bases and unupgraded residual streams. Cost compression in fuel-grade blending is intensifying because independent refiners deploy modular hydrotreating skids to capture compliance premiums. Marine bunker operators exhibit highest price sensitivity, while synthetic graphite manufacturers lock in long-term offtake contracts at fixed premiums.
Supply Chain Analysis
Specialized NiMo catalyst technicians are scarce across US Gulf Coast and Gujarat refining corridors, constraining residuum desulfurization ramp rates and extending unit commissioning timelines. Supply concentrates in China, the United States, and India, with Shandong Province residuum conversion complexes, Texas modular hydrotreater deployments, and Reliance's Jamnagar expansion anchoring global capacity. Feedstock draws from Venezuelan heavy sour, Canadian oil sands, and Middle Eastern vacuum resid streams. Single-source vulnerability runs through catalyst manufacturing concentrated in Germany and Japan. Distribution runs through Rotterdam, Singapore, and Houston terminal hubs for inter-regional bulk shipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU carbon border adjustment compliance premiums and US Gulf Coast modular upgrading cost advantages. The spread between REACH-registered hydrotreated streams and high-PAH fuel-grade alternatives creates margin capture opportunities for processors with dual-certification flexibility.
For Market Incumbents: Hedge against petroleum coke substitution by securing long-term needle coke offtake contracts with Japanese and South Korean synthetic graphite manufacturers. Expand hydrotreater capacity in Texas and Louisiana to capture IMO-compliant bunker premiums before India's delayed coker capacity comes online. Backward integration into heavy sour crude term contracts insulates margin volatility from spot differentials.
For New Entrants and Emerging Players: Begin with India's import-dependent window ahead of Reliance and Indian Oil residuum conversion ramp, targeting Gujarat hydrocracker feed demand for low-sulfur VGO. Carbon black manufacturers in Germany and the Netherlands facing REACH registration delays represent penetrable chemical feedstock accounts. A go-to-market angle anchored on ECHA pre-registration compliance and expedited aromatic hydrocarbon classification offers differentiation against stalled incumbent shipments.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale Gulf Coast independents with modular hydrotreating assets because marine fuel sulfur enforcement fragments procurement toward flexible processors with IMO certification. The five-to-ten year viability window favors operators with residuum conversion flexibility and battery anode supply relationships. Acquisition targets should possess NiMo catalyst management expertise and established needle coke producer offtake. The signal to watch is EU carbon border adjustment mechanism implementation timing and scope expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heavy Sour Crude Supply | ExxonMobil's term contracts with Venezuelan and Canadian producers insulate margin volatility from spot differentials. |
| Modular Hydrotreating Capacity Expansion | Independent Gulf Coast operators capture IMO 2020 bunker premiums without billion-dollar coker investments. |
| Long-term Needle Coke Offtake Contracting | Synthetic graphite manufacturers in Osaka and Nagoya lock in battery-grade feedstock security against spot market exposure. |
| REACH Compliance Partnership with ECHA | German carbon black manufacturers accelerate hydrotreater investments to secure aromatic hydrocarbon registration. |
| Joint Venture for Residuum Conversion Technology | Reliance and Indian Oil collaborations address India's import demand ahead of domestic coker capacity ramp. |
Research Methodology
Multiple input streams — structured interviews with refinery operations managers and residuum conversion technical leads, customs and trade flow databases, and SEC 10-K filings from integrated majors — were reconciled against hydrocracker utilization rates and needle coke production disclosures. Primary fieldwork captured catalyst management practices and hydrotreater commissioning timelines from Gulf Coast and Gujarat processors. Secondary validation drew from EIA refinery capacity reports, IEA oil market analyses, and MEE emission standard filings. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Data-stream reconciliation across product viscosity grades, sulfur content tiers, and end-use applications — spanning chemical feedstock, marine fuel blending, and industrial combustion — structured the analytical framework across the projection horizon. CAGRs were derived from regression analysis of historical residuum conversion capacity additions and battery anode demand trajectories. Forecast inputs incorporated IMO sulfur cap enforcement stringency, EU carbon border adjustment implementation scope, and China's dual carbon goal refinery redirection.
Several conditions sit outside the modeled scope, including abrupt crude sulfur differential shocks, unanticipated ECHA aromatic reclassification delays, and geopolitical disruption to Venezuelan or Iranian heavy sour supply. Forecasts reflect documented assumptions regarding hydrotreater deployment rates and needle coke specification tightening timelines. Material deviation in marine fuel sulfur enforcement, carbon border adjustment scope expansion, or catalyst supply chain disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Squalane Market
Oleochemicals
US Esters Market
Oleochemicals
Global Hexyl Cinnamal Market
Oleochemicals
Ethylhexyl Pelargonate Market
Oleochemicals
Higher Olefins Market
Oleochemicals
Neodecanoyl Chloride Market
Oleochemicals
Glycerol Esters Market
Oleochemicals
Fatty Acid Ester Market
Oleochemicals
Paraffin Wax Market
Oleochemicals
Global Emollient Esters Market
Oleochemicals
Oxo-Octyl Acetate Market
Oleochemicals
Ethoxylates Market
Oleochemicals
Sodium Stearoyl Lactylate Market
Oleochemicals
Europe Arachidonic Acid Market
Oleochemicals
Global Oxidized Polyethylene Wax Market
Oleochemicals
Candelilla Wax Market