
 United Arab Emirates Real Time Payments Market | 2026-2036
United Arab Emirates Real Time Payments Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Real Time Payments Market Analytics
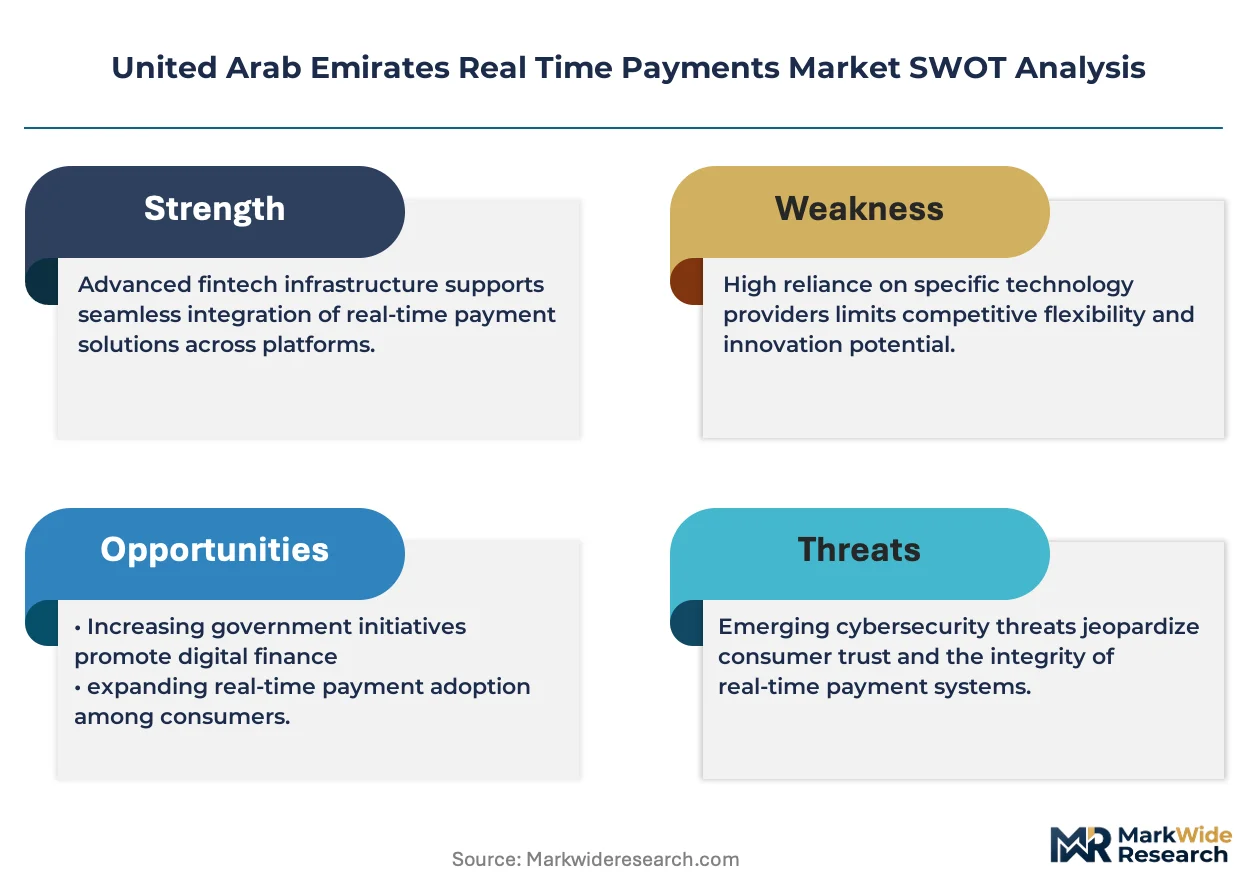
ISO 20022 messaging compliance is redrawing competitive thresholds across the UAE payments landscape. Emirates NBD leverages its universal banking license to anchor real-time corporate treasury services. Network International competes through merchant-acquiring scale spanning multiple GCC corridors. Mastercard differentiates via tokenization layers that secure NFC transaction flows.
Real time payments denote funds transfer systems that clear and settle transactions within seconds, typically operating on ISO 20022 protocols with 24/7 availability and irrevocable settlement finality. These systems eliminate float periods, reduce counterparty risk, and enable immediate liquidity positioning for commercial treasuries. Instant transfers command structural priority within the payment type dimension, as corporate treasurers prioritize working-capital velocity over cost-sensitive bill payment alternatives. Mobile payments lead the transaction method category, with QR code infrastructure expanding fastest among small merchants seeking low-friction onboarding. API integration dominates the technology layer, though blockchain pilots for cross-border corridors attract concentrated R&D investment from wholesale banking units.
The UAE Central Bank governs licensing and operational resilience standards for payment service providers, while the DFSA and VARA establish fintech-specific frameworks in Dubai's economic zones. These regulators mandate customer fund segregation, real-time fraud monitoring, and open-banking API standards that determine market access eligibility. Stakeholders must monitor how forthcoming stablecoin regulations and CBDC interoperability requirements reshape settlement architecture choices.
Market Dynamics
The UAE Central Bank's Aani instant payment platform is compressing settlement timelines from days to seconds, forcing banks and fintechs to re-architect treasury infrastructure around 24/7 liquidity management rather than batch processing windows.
Growth Catalysts
- VARA Licensing Framework:Dubai's virtual asset regulator streamlines fintech authorization, cutting time-to-market for real-time payment providers seeking operational permits in the emirate's free zones.
- Retail Merchant QR Adoption:Small merchants across Dubai's souks and Abu Dhabi's malls deploy low-cost QR infrastructure, bypassing expensive POS terminal investments while accessing instant settlement.
- Corporate Treasury Velocity:CFOs at UAE-headquartered conglomerates prioritize working-capital optimization, mandating ISO 20022-compliant instant rails for supplier payments and receivables concentration.
Market Restraints
- Interchange Cost Compression:Real-time rails eliminate float revenue that subsidized legacy payment infrastructure, squeezing issuer margins and forcing fee restructuring.
- Cross-Border Fragmentation:GCC corridor settlement lacks unified instant standards, requiring correspondent banking relationships that reintroduce latency for regional transactions.
- Fraud Monitoring Capex:Sub-second settlement windows demand real-time transaction screening engines, requiring substantial infrastructure investment from tier-two payment service providers.
Strategic Opportunities
- Ras Al Khaimah Fintech Cluster:The northern emirate's emerging digital economy zone offers untapped merchant density with lighter regulatory touchpoints than Dubai or Abu Dhabi.
- Stablecoin Settlement Rails:Forthcoming UAE Central Bank digital asset regulations may permit dirham-pegged tokens to settle on Aani infrastructure, bridging traditional and programmable money.
- API-First B2B Platforms:Convergence of open banking standards with ERP system integration enables embedded finance models where real-time payments trigger automatic reconciliation workflows.
Industry Challenges
- ISO 20022 Migration Complexity:Banks must reformat message structures across correspondent networks, testing environments, and client-facing APIs without disrupting live transaction flows.
- Talent Scarcity in Real-Time Risk:The UAE market lacks sufficient specialists in sub-second fraud pattern recognition and behavioral biometrics deployment.
- Legacy Core Modernization:Tier-one institutions operate on decades-old mainframe architectures that resist 24/7 availability requirements without expensive parallel system builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Real Time Payments Market |
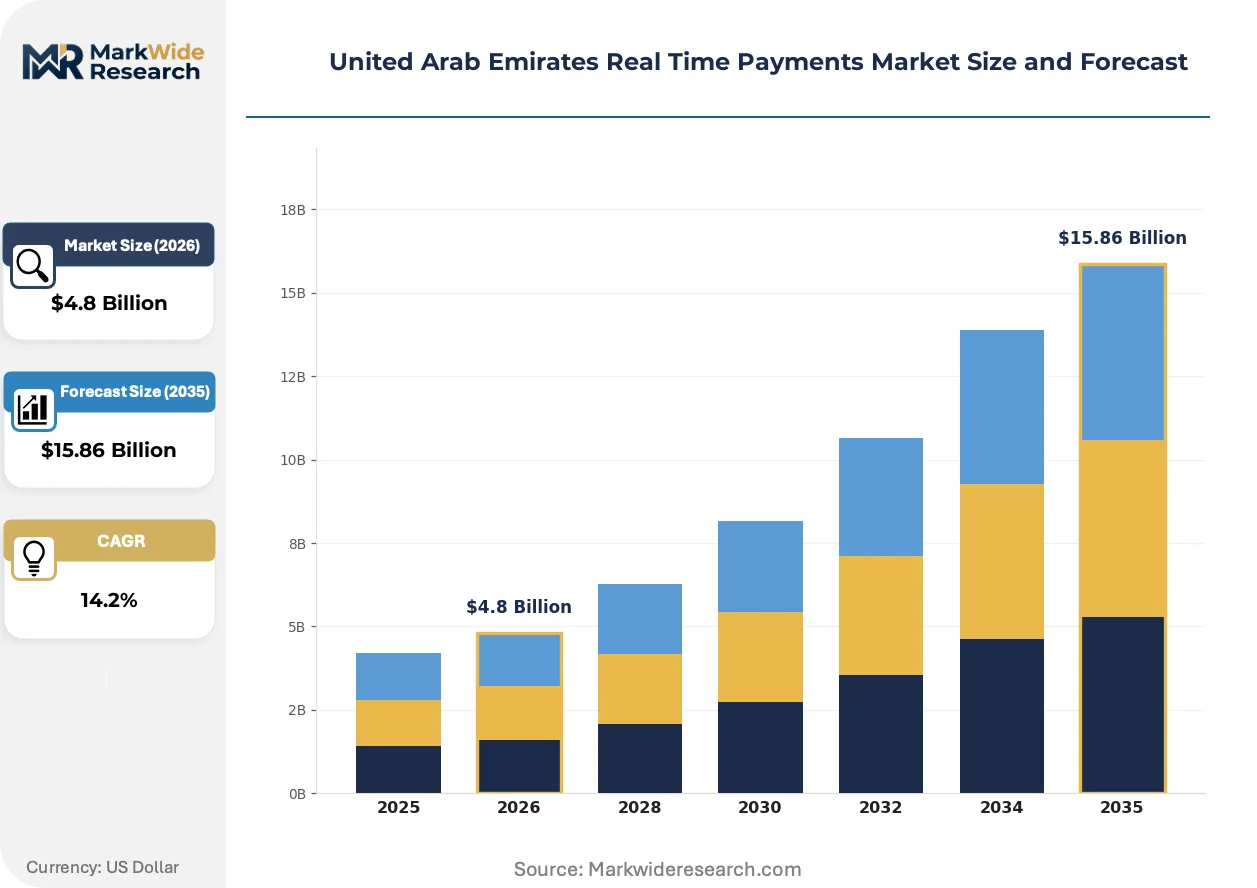
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: Instant Transfers, Bill Payments, Cross-Border Payments, Peer-to-Peer Payments Transaction Method: Mobile Payments, Online Banking, QR Code Payments, NFC Payments End User Sector: Retail, Government, Hospitality, Healthcare Integration Technology: API Integration, Blockchain, Cloud Solutions, Secure Messaging |
| Companies Covered | Abu Dhabi Commercial Bank, RAKBANK, Mashreq Bank, Stripe, Network International, Emirates NBD, Dubai Islamic Bank, Mastercard, First Abu Dhabi Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Real Time Payments Market Evolving Landscape
Payment infrastructure in the Emirates is fragmenting into specialized layers, with settlement finality, messaging protocols, and customer interfaces decoupling to enable faster iteration cycles and niche competitive positioning.
API orchestration layers are decomposing the traditional acquiring stack into modular components. Fintechs in DIFC deploy microservices for authorization, clearing, and settlement, allowing merchants to mix providers by function. This architecture compresses vendor switching costs and enables best-of-breed procurement for specific transaction types.
The UAE Central Bank's open banking mandates are hardening data-sharing requirements between licensed institutions. DFSA-regulated entities must expose standardized account information and payment initiation endpoints, eroding proprietary data advantages that incumbent banks historically exploited. Retail aggregators leverage these rails to offer consolidated multi-bank dashboards.
Merchant onboarding expectations have shifted from weeks to hours. Payment facilitators in Dubai South and Abu Dhabi Global Market compete on time-to-first-transaction, automating KYB checks through commercial registry integrations. This behavioral shift pressures traditional acquirers to dismantle manual underwriting queues or cede SME market share to API-native competitors.
United Arab Emirates Real Time Payments Market Segmentation
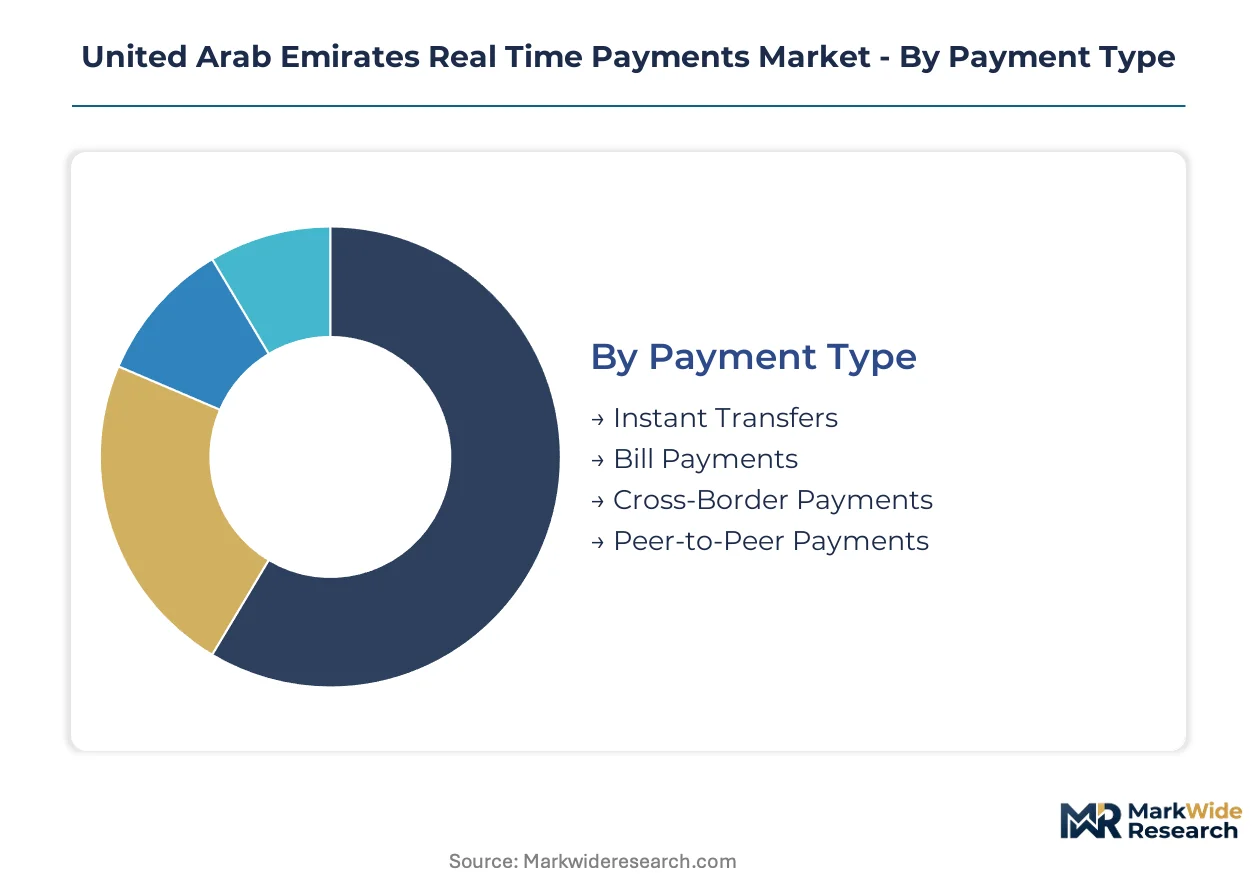
Segmentation in the UAE real-time payments market reveals how infrastructure investments and regulatory frameworks differentially serve transaction types, methods, and institutional contexts. Understanding these divides helps stakeholders allocate capital toward segments where Aani platform integration and VARA licensing create sustainable competitive moats.
Payment Type:
Channel-mix dynamics show instant transfers and bill payments flowing primarily through mobile-first retail channels, while cross-border and peer-to-peer segments concentrate in digital banking interfaces with heavier compliance overhead.
- Instant Transfers:These transactions clear and settle within seconds on ISO 20022 rails with irrevocable finality, eliminating float periods entirely. Demand concentrates in Dubai's financial free zones where corporate treasuries mandate 24/7 liquidity positioning for supplier settlements and receivables concentration.
- Bill Payments:Recurring utility and telecom settlements leverage Aani infrastructure for automated debit arrangements, with adoption deepest among UAE-headquartered conglomerates optimizing working-capital velocity. Regulatory pressure from the UAE Central Bank's open-banking mandates accelerates API-native deployment.
- Cross-Border Payments:GCC corridor settlements currently lack unified instant standards, requiring correspondent relationships that reintroduce latency.
- Peer-to-Peer Payments:Social remittances and informal transfers dominate this segment, with QR infrastructure expanding fastest among small merchants in Abu Dhabi's traditional souks.
By volume, Instant Transfers leads. By growth pace, Cross-Border Payments is ahead as regional harmonization efforts advance.
Transaction Method:
Cost-tier stratification separates premium NFC deployments in luxury retail from low-friction QR solutions serving price-sensitive SME merchants.
- Mobile Payments:Smartphone-native transactions dominate transaction volume through wallet applications integrated with Aani rails, with merchant adoption deepest in Dubai Mall corridors and Abu Dhabi Global Market food courts.
- QR Code Payments:Low-cost onboarding infrastructure bypasses expensive POS terminal investments, expanding fastest among small merchants in Ras Al Khaimah's emerging digital economy zone where regulatory touchpoints remain lighter than Dubai or Abu Dhabi.
- Online Banking:Corporate treasury platforms and high-value consumer transfers flow through authenticated web interfaces with enhanced fraud monitoring.
- NFC Payments:Tokenized contactless transactions secure premium retail environments, with deployment concentrated in Dubai's luxury hospitality sector.
By adoption breadth, QR Code Payments leads. By transaction value per user, NFC Payments commands the steepest expansion trajectory.
End User Sector:
Application-specific requirements drive divergent infrastructure demands, with retail prioritizing speed and government mandating audit trails.
- Retail:High-frequency, low-value transactions demand sub-second authorization with minimal friction, with merchant density greatest in Dubai's mall ecosystems and Abu Dhabi's convenience retail chains.
- Government:Public sector disbursements and tax collections require immutable record-keeping aligned with federal transparency mandates, with adoption accelerating through MOHAP and municipal payment integrations.
- Hospitality:Tourism-dependent venues in Dubai South and Yas Island prioritize multi-currency acceptance with instant dirham settlement.
- Healthcare:Insurance claim settlements and patient co-payments flow through specialized clearing arrangements with enhanced data privacy protections.
By transaction velocity, Retail leads. By regulatory tailwinds, Government is expanding most quickly.
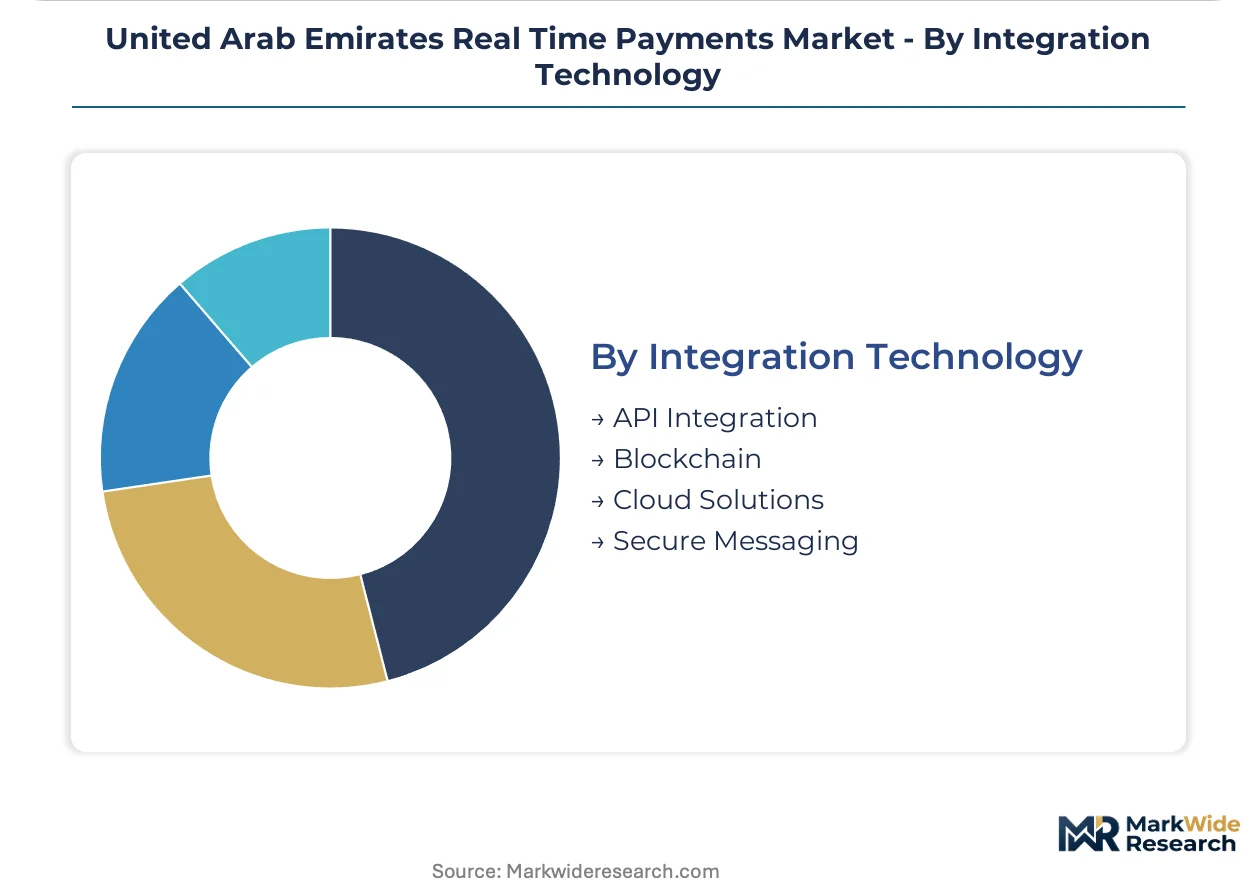
Integration Technology:
Customer-type differentiation separates API-first fintechs serving agile SMEs from blockchain pilots targeting wholesale banking units with concentrated R&D budgets.
- API Integration:Modular microservices decompose traditional acquiring stacks into authorization, clearing, and settlement components, with deployment concentrated among DFSA-licensed entities in DIFC offering best-of-breed procurement.
- Cloud Solutions:Elastic infrastructure enables tier-two payment service providers to achieve 24/7 availability without legacy mainframe investments, gaining share fastest among VARA-authorized fintechs in Dubai's free zones.
- Blockchain:Distributed ledger pilots target cross-border corridors with programmable settlement logic, attracting concentrated investment from wholesale banking units.
- Secure Messaging:ISO 20022-compliant message formatting underpins interoperability across correspondent networks, with migration complexity highest at tier-one institutions operating decades-old architectures.
By deployment scale, API Integration leads. By investment intensity, Blockchain is climbing the fastest despite regulatory uncertainty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payment infrastructure investment clusters in Dubai and Abu Dhabi, with tier-one banks and VARA-licensed fintechs anchoring real-time deployment. Northern emirates present whitespace for merchant-acquiring expansion.
Dubai
Corporate treasury demand from DIFC-headquartered conglomerates drives instant transfer volume. VARA licensing accelerates fintech authorization timelines for payment service providers. Dubai Mall corridors and Dubai South logistics zones host dense QR merchant networks accessing Aani settlement rails.
Abu Dhabi
Government disbursement mandates from MOHAP and municipal entities expand bill payment adoption. The UAE Central Bank's operational resilience standards enforce 24/7 availability requirements. Abu Dhabi Global Market food courts and Yas Island hospitality venues prioritize multi-currency acceptance with instant dirham settlement.
Sharjah
Mid-market retail chains and family-owned trading houses generate working-capital optimization demand. Federal transparency mandates accelerate public sector payment digitization. Industrial zones around Sharjah Airport Free Zone concentrate SME merchant density seeking low-friction onboarding.
Northern Emirates
Ras Al Khaimah's emerging digital economy zone offers lighter regulatory touchpoints than southern emirates. Small merchants in traditional souks deploy QR infrastructure bypassing POS terminal investments. Ajman and Fujairah present untapped corridors for payment facilitator expansion with compressed time-to-first-transaction competition.
United Arab Emirates Real Time Payments Market Competitive Landscape
Concentration sits with universal banks holding central bank clearing access and fintechs leveraging VARA licensing for agile deployment. The market exhibits tiered structure: tier-one institutions with legacy infrastructure dominance, VARA-authorized challengers with API-native stacks, and international payment networks with tokenization capabilities. Strategic moves center on ISO 20022 migration partnerships and merchant-acquiring scale builds in free zones.
Within the universal banking tier, Emirates NBD and First Abu Dhabi Bank anchor real-time corporate treasury services through universal license advantages. Among fintech infrastructure providers, Network International occupies a position exemplifying merchant-acquiring scale across GCC corridors. Mastercard represents the network archetype with tokenization layers securing NFC transaction flows.
| Leading Market Players |
|---|
| Abu Dhabi Commercial Bank |
| RAKBANK |
| Mashreq Bank |
| Stripe |
| Network International |
| Emirates NBD |
| Dubai Islamic Bank |
| Mastercard |
| First Abu Dhabi Bank |
| Others |
Value Network & Pricing Analysis
Capacity reservation agreements with Aani infrastructure providers lock in settlement access and price visibility for tier-one banks, compressing margins for payment service providers unable to secure preferential routing terms under UAE Central Bank operational resilience standards.
Pricing Analysis
UAE Central Bank operational resilience standards dictate the pricing tier structure across the real-time payments landscape. Per-unit transactional models dominate, with interchange compression eliminating float revenue that historically subsidized legacy infrastructure. Price differentiation rests on ISO 20022 compliance tier and fraud monitoring sophistication, where tier-one institutions with in-house engines command premium positioning. Cost compression in the merchant-acquiring layer is intensifying because API-native fintechs undercut traditional acquirers on onboarding fees. Small merchants in Ras Al Khaimah's emerging zones exhibit highest price sensitivity, while DIFC-headquartered corporate treasuries prioritize velocity over cost.
Supply Chain Analysis
Strait of Hormuz transit underwrites connectivity resilience for payment messaging infrastructure serving UAE corridors. Geographic supply concentration centers on domestic cloud infrastructure providers, Singapore-based data center operators, and European ISO 20022 messaging standard-setters. Raw material dependencies include semiconductor chips for POS terminals, cryptographic hardware security modules, and subsea fiber optic capacity. Single-source vulnerability sits with tier-one banks operating decades-old mainframe architectures that resist 24/7 availability without expensive parallel builds. Distribution runs through VARA-licensed fintech aggregators in Dubai's free zones, bypassing traditional correspondent banking hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE real-time payments market represents a high-growth disruption as Aani platform adoption compresses settlement timelines from days to seconds, forcing wholesale infrastructure replacement across banking and fintech sectors.
For Market Incumbents: Consolidate ISO 20022 migration partnerships with correspondent networks to defend against API-native challengers eroding corporate treasury market share. Prioritize backward integration into cloud infrastructure to escape third-party data center cost escalations. Lock in long-term capacity reservations with Aani settlement rails before VARA-licensed competitors capture preferred routing priority. For New Entrants and Emerging Players: Differentiate on sub-second fraud pattern recognition capabilities, where talent scarcity among tier-one institutions creates white-space opportunity. Target Ras Al Khaimah's merchant-acquiring corridor, where regulatory touchpoints remain lighter than Dubai or Abu Dhabi. Deploy QR infrastructure with automated KYB integration to compress time-to-first-transaction below traditional acquirer benchmarks. For Investors and Strategic Acquirers: Capital is best deployed toward API-first payment facilitators with demonstrated ERP integration traction and VARA licensing in hand. Long-term viability favors entities bridging open banking mandates with embedded finance workflows rather than pure infrastructure plays. Watch stablecoin regulatory clarity from the UAE Central Bank as the inflection signal for programmable money settlement rails.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20022 Migration Partnership | Emirates NBD and First Abu Dhabi Bank anchor corporate treasury services through compliance-first positioning. |
| VARA Licensing Acceleration | Fintechs in DIFC and Dubai South compress authorization timelines to capture merchant-acquiring scale. |
| QR Infrastructure Deployment | Network International expands low-friction onboarding across Ras Al Khaimah's untapped merchant corridors. |
| API-First Platform Integration | Mastercard tokenization layers secure NFC flows in Dubai's luxury hospitality vertical. |
| Cloud Infrastructure Transition | Tier-two payment service providers achieve 24/7 availability without legacy mainframe capital burden. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of UAE Central Bank regulatory filings, VARA authorization databases, and DFSA open banking implementation guidelines. Primary interviews engaged payment infrastructure executives at tier-one banks, fintech product leads holding VARA licenses, corporate treasury officers at DIFC-headquartered conglomerates, and merchant-acquiring specialists at payment facilitators. Secondary validation drew from UAE Central Bank annual reports, DFSA regulatory notices, SWIFT ISO 20022 migration tracking, and hyperscaler cloud infrastructure disclosures. Bottom-up transaction volume modeling triangulates against top-down market sizing from banking sector aggregate data.
Segmentation dimensions modeled span payment type, transaction method, end user sector, and integration technology across the projection horizon. Analytical framework deploys cohort-based adoption curves for Aani platform penetration, with CAGRs derived from regression against historical real-time payment infrastructure deployment patterns in comparable Gulf markets. Industry-specific forecast inputs include merchant QR adoption velocity in northern emirates and corporate treasury mandate penetration for ISO 20022-compliant instant rails.
Material uncertainties — forthcoming stablecoin regulations, CBDC interoperability requirements, and GCC corridor harmonization timelines — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory implementation pace and correspondent banking relationship stability. Practitioners should keep alternative scenarios live as UAE Central Bank digital asset frameworks and open banking mandate enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Slovakia POS Terminal Market
Payments
Fingerprint Payment Market
Payments
UAE POS Terminal Market
Payments
Germany Payment Gateway Market
Payments
Digital Payment Market
Payments
E-Commerce Payments Market
Payments
Mexico POS Terminals Market
Payments
Voice-Based Payments Market
Payments
South Africa Real Time Payments Market
Payments
Israel Credit Cards Market
Payments
Remote Mobile Payment Market
Payments
Asia-Pacific Payment Gateway Market
Payments
Money Transfer Agencies Market
Payments
Poland Payments Market
Payments
Transit Cards Market
Payments
POS Terminals Market