
 Argentina Payments Market | 2026-2036
Argentina Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Payments Market Analysis
Merchant buyer concentration is expanding as small businesses and informal vendors migrate from cash to digital acceptance, fragmenting the historic dominance of large retail chains. Mercado Pago leverages its e-commerce ecosystem to anchor in-store and online payment flows. Ualá competes through fee-transparent mobile wallets targeting underbanked segments. Visa Inc sustains network effects via contactless infrastructure partnerships with Argentine banks.
Argentina payments encompass electronic fund transfer systems, card networks, and digital wallets facilitating commercial transactions through encrypted authorization protocols and real-time settlement rails. The primary purpose is reducing cash dependency while accelerating transaction velocity for consumers and businesses. Mobile wallets represent the fastest-growing payment method as smartphone penetration deepens across provinces. Bank transfers occupy a mature position in B2B corridors where large transaction settlement requires institutional clearing. Cross-border payments concentrate margin pools as Argentine exporters seek dollar-denominated settlement alternatives.
BCRA, the national securities regulator CNV, and AFIP tax authority shape market access through fintech charter requirements, anti-money laundering protocols, and transaction reporting mandates. These frameworks elevate compliance costs for new entrants while privileging licensed operators with established risk infrastructure. Stakeholders must monitor regulatory treatment of dollar-linked payment instruments as macroeconomic volatility persists.
Market Dynamics
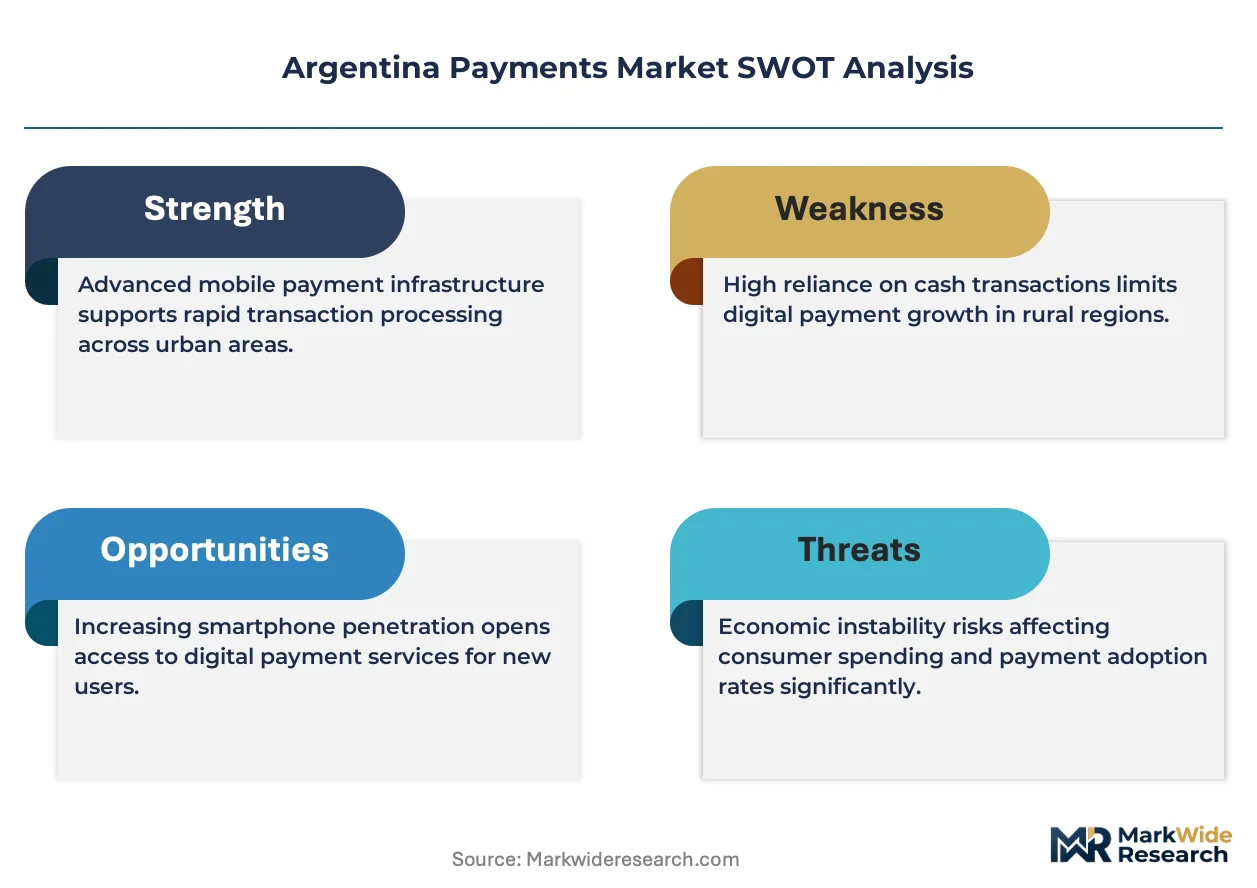
Argentina's payments sector faces acute currency instability that forces operators to engineer dual-currency settlement rails while BCRA licensing requirements filter out undercapitalized entrants. This structural pressure concentrates market power among licensed fintechs with established compliance infrastructure.
Growth Catalysts
- BCRA Fintech Charter Framework:The central bank's formal licensing regime creates a regulated pathway for digital wallet operators to access the financial system, accelerating institutional legitimacy for mobile payment providers.
- Small Merchant Digital Migration:Informal vendors and neighborhood retailers across Buenos Aires province are abandoning cash registers for smartphone-based acceptance, fragmenting historic concentration in large retail chains.
- Contactless Infrastructure Deployment:Argentine banks are retrofitting ATM and POS terminals with NFC capabilities, enabling tap-to-pay adoption among urban consumers with rising smartphone penetration.
Market Restraints
- Foreign Exchange Volatility:Peso-dollar instability forces payment processors to maintain dual-currency reserves, elevating working capital requirements and compressing margins on cross-border settlements.
- Compliance Cost Escalation:AFIP transaction reporting mandates and CNV anti-money laundering protocols require dedicated legal infrastructure that disadvantages smaller fintech entrants.
- Interoperability Fragmentation:Proprietary wallet ecosystems lack standardized APIs, forcing merchants to maintain multiple settlement accounts and increasing technical integration burdens.
Strategic Opportunities
- Provincial Underpenetration:Secondary cities in Córdoba, Mendoza, and Rosario exhibit sub-30% digital payment adoption relative to Buenos Aires, offering expansion corridors for mobile-first operators.
- Export-Oriented Dollar Settlement:Argentine agricultural and manufacturing exporters require dollar-denominated payment rails that bypass traditional correspondent banking delays and FX conversion losses.
- API-First B2B Platforms:Convergence of open banking protocols with ERP integration is enabling embedded payment workflows for enterprise treasury management, displacing manual bank transfer reconciliation.
Industry Challenges
- Regulatory Interpretation Talent Scarcity:The intersection of BCRA fintech norms, AFIP tax reporting, and CNV securities rules requires specialized compliance professionals in short supply across the domestic labor market.
- Legacy Core Banking Integration:Incumbent Argentine banks operate on decades-old mainframe architectures that resist real-time API connectivity, forcing payment innovators to build expensive middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Payments Market |
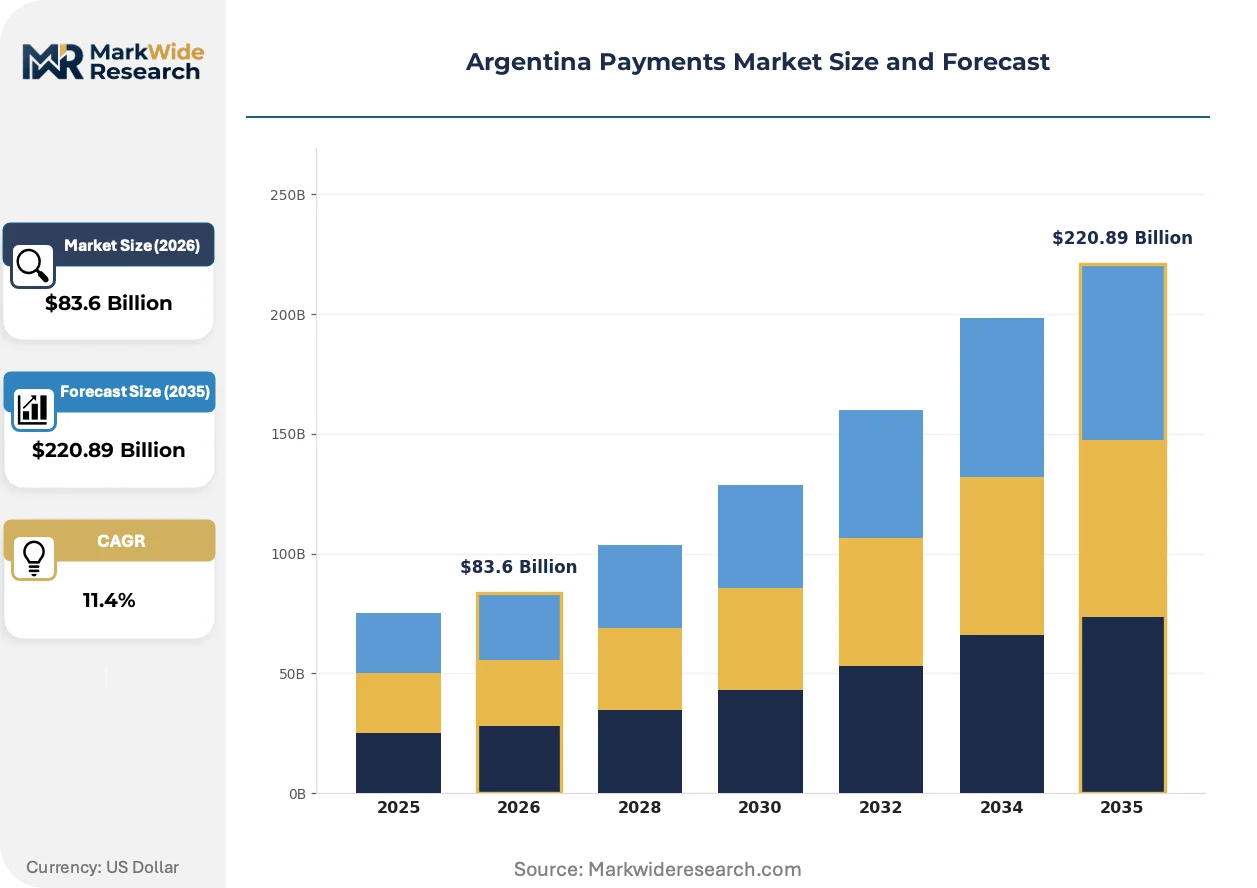
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $220.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Cards, Debit Cards, Mobile Wallets, Bank Transfers Customer Type: Consumers, Merchants, Corporates, Government Transaction Size: Micro Transactions, Small Transactions, Medium Transactions, Large Transactions Service Type: In-store Payments, Online Payments, Cross-border Payments, Subscription Services |
| Companies Covered | PagoFacil, Naranja X, Mercado Pago, Dlocal, Ualá, Visa Inc, Rapipago, PayU Argentina, Mastercard International Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Payments Market Emerging Trajectories
Argentina's payment infrastructure is fragmenting into specialized rails as operators architect around currency instability and regulatory complexity. Three convergent developments are compressing transaction costs while elevating compliance automation.
QR code-based payment orchestration is unifying merchant acceptance across competing wallet ecosystems. Neighborhood retailers in Greater Buenos Aires are adopting interoperable QR standards that route transactions through multiple settlement providers simultaneously. This technology is compressing merchant acquisition costs by eliminating proprietary terminal requirements and enabling instant fund availability.
BCRA's tightening of fintech licensing under Circulars A-6409 and A-7545 is mandating minimum capital reserves and operational risk frameworks for non-bank payment providers. The industrial consequence is a filtering of undercapitalized entrants while privileging established operators with compliance infrastructure. Digital wallet segments targeting underbanked populations are responding by consolidating through strategic partnerships to meet capital thresholds.
Behavioral payment patterns are rotating toward embedded finance models where transactions occur inside non-financial applications. Agricultural supply cooperatives in Santa Fe province are integrating harvest financing with input procurement payments, displacing traditional bank transfer workflows. This shift is most visible in commodity-exporting verticals where payment timing directly ties to production cycles.
Argentina Payments Market Segmentation
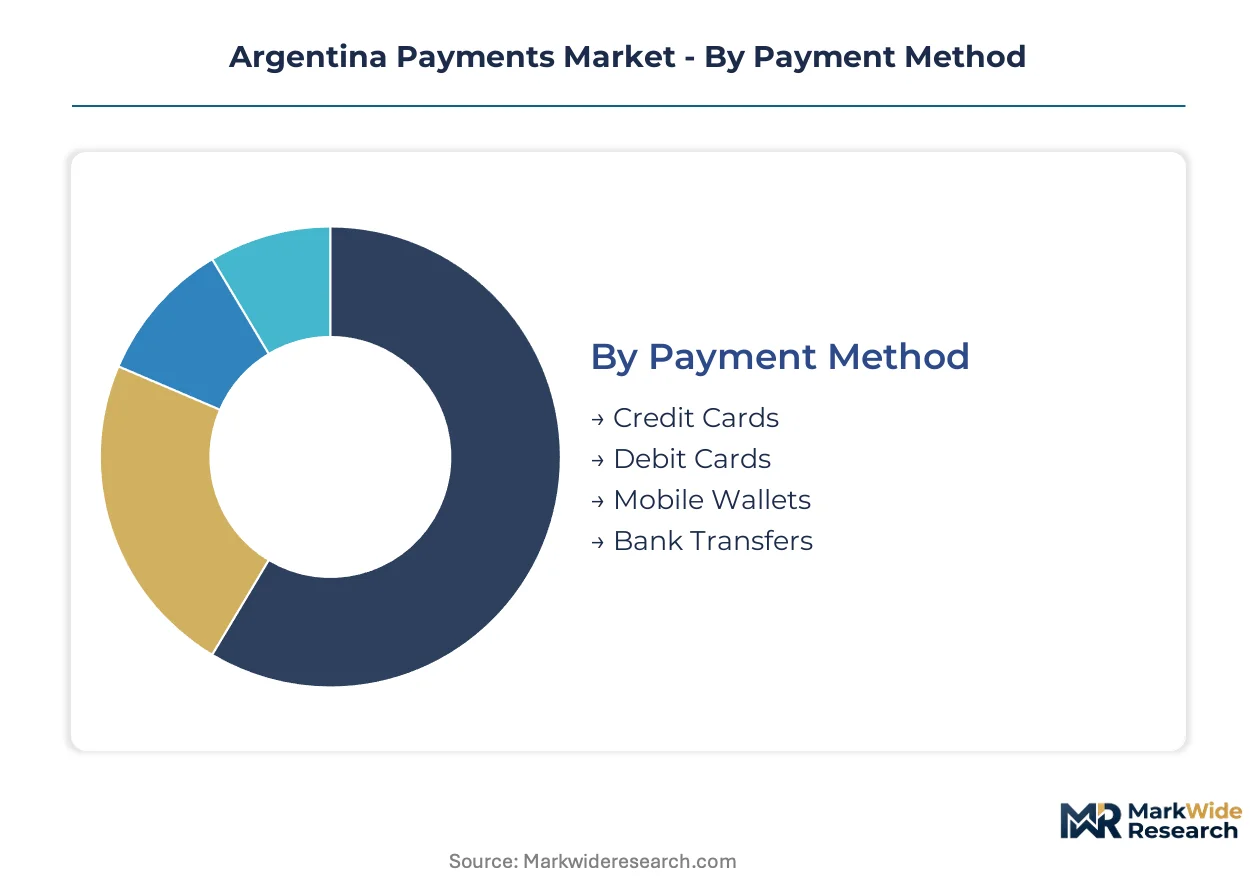
Payment method fragmentation in Argentina reflects divergent infrastructure maturity and user sophistication across consumer and commercial corridors. Segment boundaries blur as mobile wallets absorb card functionality and B2B platforms embed treasury workflows into ERP systems.
Payment Method:
Integration depth varies sharply—cards operate through standalone terminal infrastructure while mobile wallets embed directly into merchant smartphones and e-commerce checkouts.
- Credit Cards:Revolving credit instruments issued by Argentine banks under Visa and Mastercard networks, typically carrying 40-55 day grace periods. Buenos Aires metropolitan retailers anchor volume as inflation hedging drives consumer preference for deferred payment. BCRA interest rate caps constrain issuer margins while sustaining accessibility.
- Mobile Wallets:Smartphone-based stored-value applications enabling QR-code acceptance without proprietary hardware. Mercado Pago and Ualá dominate as underbanked segments in Greater Buenos Aires adopt fee-transparent alternatives to traditional banking. Dual-currency functionality addresses peso volatility.
- Debit Cards:Direct-linked instruments deducting from demand deposits in real-time. Provincial bank branches in Córdoba and Mendoza sustain mature infrastructure.
- Bank Transfers:Account-to-account settlement through CBU/Alias systems for B2B and high-value consumer transactions. Corporate treasury departments in agricultural export verticals favor this rail for traceability.
Volume placements concentrate in Credit Cards; the faster expansion belongs to Mobile Wallets.
Customer Type:
Cost tier stratification separates mass-market consumers from enterprise clients requiring customized integration and dedicated support infrastructure.
- Merchants:Businesses accepting digital payments through POS terminals, QR codes, or e-commerce gateways. Neighborhood retailers across Buenos Aires province migrate from cash to smartphone-based acceptance, fragmenting historic concentration in large retail chains. Integration complexity rises with multi-wallet reconciliation requirements.
- Consumers:Individual users executing purchases, peer-to-peer transfers, and bill payments. Smartphone penetration in secondary cities drives wallet adoption beyond traditional banking relationships.
- Corporates:Enterprise entities managing payroll disbursements, supplier payments, and treasury operations. Agricultural cooperatives in Santa Fe embed financing with procurement workflows.
- Government:Public sector entities distributing social benefits and collecting tax revenues. AFIP mandates shape reporting requirements for payment processors serving this segment.
Merchant acquisition commands the steepest investment; consumer wallets are climbing the fastest.
Transaction Size:
Application context determines rail selection—micro transactions favor instant settlement while large transactions require institutional clearing and documentation.
- Micro Transactions:Sub-peso payments for transit, vending, and digital content. Urban contactless infrastructure enables tap-to-pay adoption.
- Small Transactions:Everyday retail purchases under typical debit limits. Buenos Aires convenience stores anchor this tier.
- Medium Transactions:Monthly household expenditures and SME procurement. B2B platforms automate reconciliation for this range.
- Large Transactions:Real estate, vehicle purchases, and export settlements. Dollar-denominated alternatives bypass correspondent banking delays.
Small transactions dominate frequency counts; large transactions capture premium margin pools.
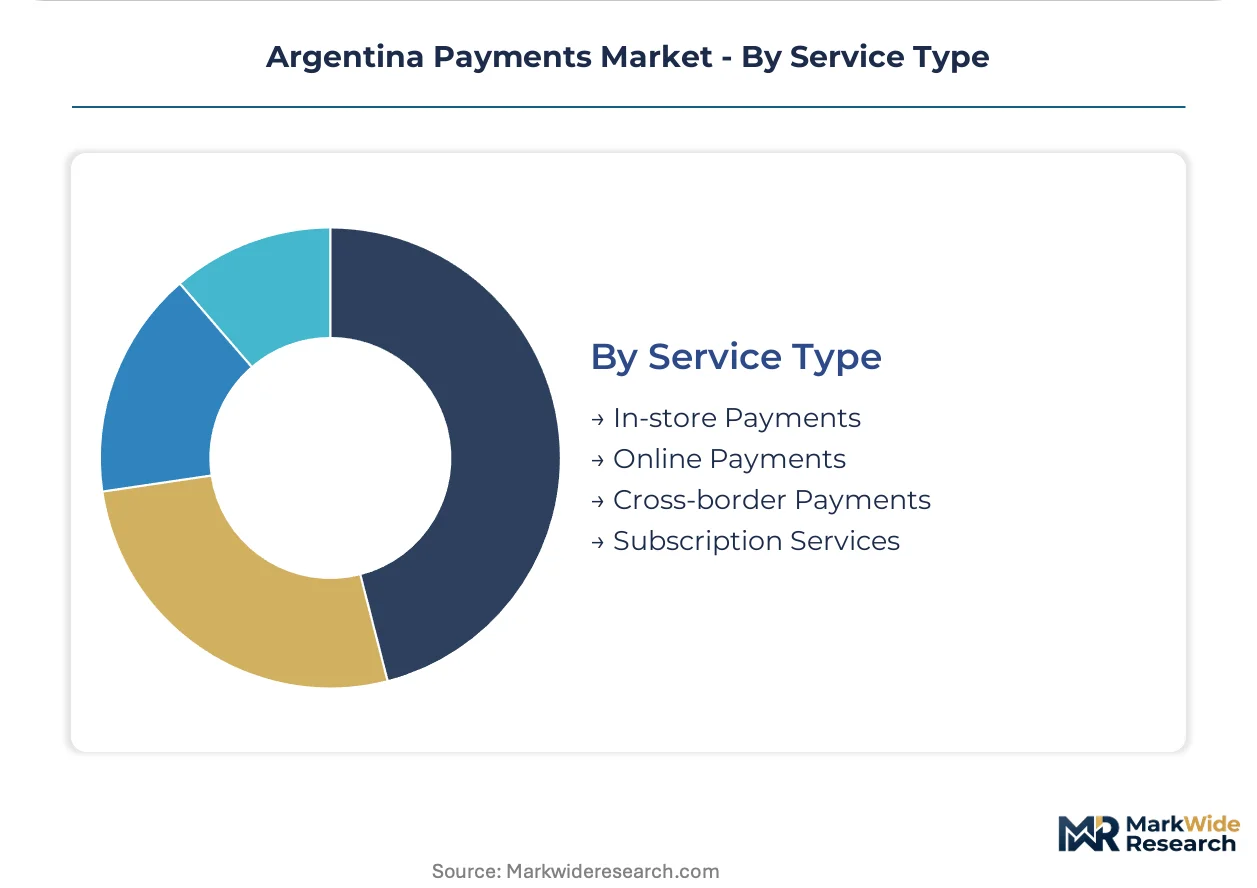
Service Type:
Geographic concentration separates Buenos Aires corridor density from provincial expansion corridors.
- In-store Payments:Physical merchant acceptance through cards, QR codes, or NFC terminals. Retrofit programs by Argentine banks accelerate contactless deployment.
- Online Payments:E-commerce checkout flows and digital service subscriptions. Mercado Libre ecosystem integration anchors this segment.
- Cross-border Payments:International remittances and export settlement rails. Agricultural exporters in Rosario corridor seek dollar-denominated alternatives.
- Subscription Services:Recurring billing for utilities, streaming, and SaaS platforms. Automated debit authorization reduces churn.
In-store placements retain volume leadership; cross-border services are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buenos Aires province anchors Argentina's payment infrastructure density, with the metropolitan corridor concentrating merchant acceptance networks and fintech headquarters. Provincial expansion corridors in Córdoba, Mendoza, and Rosario exhibit significant underpenetration relative to capital-region saturation.
Greater Buenos Aires
Neighborhood retailers and informal vendors across the metropolitan corridor accelerate smartphone-based payment acceptance, fragmenting historic concentration in large retail chains. BCRA Circular A-6409 mandates minimum capital reserves for digital wallet operators accessing this dense merchant base. The Palermo and Recoleta commercial districts concentrate contactless infrastructure deployment by Argentine banks retrofitting ATM and POS terminals with NFC capabilities.
Córdoba Province
Agricultural cooperatives and SME manufacturers in this central region drive B2B payment automation for supplier settlements and procurement workflows. AFIP transaction reporting mandates shape compliance infrastructure requirements for processors serving corporate treasury departments. The Córdoba capital city anchors sub-30% digital payment adoption relative to Buenos Aires, offering expansion corridors for mobile-first operators targeting underbanked segments.
Mendoza Province
Wine exporters and agricultural producers in this western region require dollar-denominated settlement rails bypassing traditional correspondent banking delays. The central bank's tightening of fintech licensing under Circular A-7545 filters undercapitalized entrants from serving this cross-border payment demand. The Mendoza capital and surrounding vineyard corridors concentrate merchant acquisition investment by established licensed operators.
Santa Fe Province
Rosario's agricultural commodity trading hub generates large transaction settlement volumes requiring institutional clearing and traceable documentation. CNV anti-money laundering protocols elevate compliance costs for payment processors serving export-oriented corporate clients. The Santa Fe capital and Rosario metropolitan area embed harvest financing with input procurement payments through cooperative-integrated platforms.
Secondary Provincial Corridors
Neuquén, Tucumán, and Entre Ríos provinces exhibit deepening smartphone penetration without proportional payment infrastructure deployment. Provincial bank branches sustain mature debit card infrastructure while mobile wallet adoption lags capital-region saturation. These corridors represent untapped expansion territory for QR-code-based payment orchestration eliminating proprietary terminal requirements.
Argentina Payments Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue embedded finance and provincial merchant acquisition. The market structure concentrates among licensed fintechs with BCRA-compliant risk infrastructure, filtering undercapitalized competitors through regulatory capital thresholds. Three archetypes dominate: e-commerce ecosystem anchors, mobile-first wallet specialists, and global network infrastructure providers. Competitive dynamics center on strategic partnerships for provincial expansion and API interoperability investments reducing merchant integration burdens.
Within the mobile wallet tier, Ualá and Mercado Pago exemplify divergent positioning strategies targeting underbanked segments versus e-commerce-anchored flows. Visa Inc and Mastercard International Incorporated occupy the network infrastructure tier, sustaining contactless acceptance through Argentine bank partnerships. Among established local processors, PagoFacil and Rapipago represent legacy payment collection archetypes adapting to digital wallet displacement through QR-code interoperability investments. Dlocal anchors the cross-border settlement tier serving agricultural exporters requiring dollar-denominated alternatives.
| Leading Market Players |
|---|
| PagoFacil |
| Naranja X |
| Mercado Pago |
| Dlocal |
| Ualá |
| Visa Inc |
| Rapipago |
| PayU Argentina |
| Mastercard International Incorporated |
| Others |
Supply Flow & Price Mechanics
Small merchant demand for fee-transparent, smartphone-based acceptance is forcing payment processors to unbundle hardware costs from transaction fees, compressing margins on terminal-dependent models while elevating software-only QR solutions. This procurement shift privileges operators with middleware-light architectures and punishes legacy POS distributors tethered to proprietary device ecosystems.
Pricing Analysis
Warranty and service bundling separates premium-tier payment processors from economy competitors, with established operators including dedicated compliance support and chargeback insurance while stripped-down entrants offer bare transaction rails. Three-tier pricing structure across premium, standard, and economy levels reflects BCRA charter status, AFIP reporting automation, and settlement speed guarantees. Pricing pressure stems from mobile wallet proliferation in Greater Buenos Aires, where Mercado Pago and Ualá compete on merchant acquisition subsidies. Small neighborhood retailers exhibit highest price sensitivity, while agricultural exporters in Rosario prioritize dollar-settlement reliability over transaction cost.
Supply Chain Analysis
Warehouse-distribution layers for payment hardware concentrate in São Paulo and Miami logistics hubs serving Argentine terminal deployment, with software infrastructure increasingly migrating to São Paulo and Santiago data centers. Semiconductor components for NFC terminals draw from Taiwan and South Korea, while server capacity rests on Chilean and Brazilian cloud regions. Single-source vulnerability runs through BCRA-sanctioned settlement rails, where licensed operator concentration creates systemic dependency. Distribution runs through Argentine bank partnerships for merchant acquisition, with direct API sales displacing traditional channel intermediaries for enterprise clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating rapidly as BCRA capital reserve requirements filter undercapitalized fintechs, forcing acquisition or exit for sub-scale wallet operators.
For Market Incumbents: Hedge currency exposure by deepening dollar-denominated settlement infrastructure for agricultural exporters in Santa Fe and Mendoza, while acquiring provincial merchant acquirers in Córdoba and Rosario to preempt mobile-first entrants. BCRA Circular A-7545 compliance costs favor scaled operators with dedicated legal infrastructure. For New Entrants and Emerging Players: BCRA's formal fintech charter framework in Argentina opens a window for capitalized regional operators to enter via Mendoza and Córdoba corridors where mobile wallet penetration lags Buenos Aires by 20-plus points. Target agricultural cooperatives with embedded harvest-financing payment workflows, bypassing saturated consumer wallet competition through B2B ERP integration. For Investors and Strategic Acquirers: The window for entry favors licensed fintechs with established AFIP reporting automation and BCRA-compliant risk frameworks over unlicensed technology plays. Long-term viability hinges on regulatory moat durability through charter renewal cycles. Watch BCRA treatment of dollar-linked payment instruments as the inflection signal for cross-border margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| API Interoperability Investment | Reduces merchant reconciliation burden across Mercado Pago, Ualá, and bank wallet ecosystems. |
| Provincial Merchant Acquisition | Captures underpenetrated Córdoba and Mendoza corridors before mobile wallet saturation. |
| Dollar-Settlement Rail Construction | Addresses Rosario agricultural exporter demand for bypassing correspondent banking delays. |
| Compliance Infrastructure Scale-Up | Meets BCRA Circular A-7545 capital thresholds filtering undercapitalized competitors. |
| Embedded Finance Partnership | Integrates harvest financing with input procurement for Santa Fe cooperatives. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, with BCRA circulars, CNV securities disclosures, and AFIP transaction reporting mandates providing official market parameters. Primary interviews with fintech compliance officers, merchant acquisition heads at Argentine banks, agricultural cooperative treasury managers, and POS terminal distributors validated operational assumptions. Bottom-up modeling of wallet transaction volumes triangulated against top-down Central Bank payment system statistics.
Granularity-level modeling segmented by payment method, customer type, transaction size, and service type, with provincial penetration rates and BCRA charter status as cross-cutting dimensions. CAGRs derived from trend extrapolation of mobile wallet adoption curves, contactless infrastructure deployment schedules, and export settlement volume patterns. Dual-currency settlement demand and embedded finance convergence served as Argentina-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for QR-code interoperability standards would alter the outlook if proprietary wallet ecosystems persist. Forecasts reflect assumptions on BCRA regulatory continuity, peso-dollar stability bands, and smartphone penetration trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
United Kingdom Payment Market
Payments
Digital Payment in Healthcare Market
Payments
Mobile POS Market
Payments
Hong Kong Payments Market
Payments
China POS Terminals Market
Payments
Mobile Wallet Market
Payments
Latin America Subscription and Billing Management Market
Payments
Asia Pacific Buy Now Pay Later Service Market
Payments
Netherlands POS Terminal Market
Payments
China Forex Cards Market
Payments
Subscription Billing Management Market
Payments
Hungary POS Terminal Market
Payments
LAMEA Payment Gateway Market
Payments
Contactless Payment Ring Market
Payments
US Virtual Cards Market
Payments
Convergent Billing Market