
 Global VR Game Engine Software Market | 2026-2036
Global VR Game Engine Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global VR Game Engine Software Market Foresight
Multi-source licensing for core rendering modules is restructuring how studios assemble their VR development stacks. Epic Games leverages its Unreal Engine ecosystem to dominate high-fidelity entertainment and simulation verticals. Unity Technologies anchors the mid-market with cross-platform deployment tools that sustain broad indie and mobile VR adoption. Crytek competes through proprietary photogrammetry pipelines that differentiate its offering for architectural visualization clients.
VR game engine software comprises integrated development environments that compile spatial computing code, manage real-time rendering pipelines, and output executables for head-mounted displays with sub-20-millisecond motion-to-photon latency. These platforms serve commercial purposes spanning interactive entertainment, workforce training, and digital twin visualization. Real-time ray tracing rendering technology leads premium product positioning as studios demand physically accurate lighting for simulation-grade applications. Indie studios within the developer type segment represent the fastest-expanding user base, while AAA developers still command the largest margin pools through long-term enterprise licensing agreements.
The Federal Communications Commission in the United States governs wireless spectrum allocation for untethered VR headsets, directly shaping hardware compatibility requirements that engine developers must support. The European Union's AI Act and GDPR impose algorithmic transparency and biometric data handling standards that constrain how engines process eye-tracking and facial capture inputs. China's Ministry of Industry and Information Technology enforces content review protocols through its GB standards framework, creating a distinct compliance layer for engines distributed domestically. Stakeholders must monitor how fragmented regulatory requirements across these jurisdictions fragment feature parity and complicate unified product roadmaps.
Market Dynamics
Real-time ray tracing rendering technology is compressing development timelines for simulation-grade VR applications while simultaneously elevating hardware requirements that segment the addressable developer base.
Growth Catalysts
- Healthcare training simulations:Surgical residency programs in the United States and Germany are mandating immersive competency modules, pulling enterprise licensing volumes upward for physics-accurate engines.
- EU AI Act compliance frameworks:Engine developers embedding biometric processing tools must now certify algorithmic transparency, creating a first-mover advantage for platforms with pre-built audit pipelines.
- Photogrammetry pipelines:Architectural visualization studios in China are demanding native support for reality-capture workflows, expanding the utility layer beyond entertainment use cases.
Market Restraints
- GPU supply concentration:Foundry capacity for high-performance graphics processors clusters in Taiwan, exposing engine developers to allocation volatility that distorts hardware-targeted feature roadmaps.
- GDPR biometric friction:Eye-tracking and facial capture inputs require explicit consent architectures that increase engineering overhead for European deployments.
- Untethered latency floors:FCC spectrum allocation constraints for wireless VR headsets enforce sub-20-millisecond motion-to-photon baselines that limit rendering complexity on standalone devices.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Domestic assembly incentives for head-mounted displays are seeding a captive developer ecosystem that favors localized engine distribution partnerships.
- Digital twin convergence:Industrial facility operators in Germany are merging VR visualization with IoT sensor feeds, opening subscription revenue streams outside traditional licensing models.
- Japan's METI immersive technology roadmap:Public procurement mandates for workforce reskilling platforms are directing public-sector RFPs toward engine vendors with training-vertical certification.
Industry Challenges
- Spatial computing talent scarcity:Pipeline engineering for sub-20-millisecond latency requires specialized shader optimization expertise that commands premium compensation and elongates hiring cycles.
- Fragmented certification timelines:China's GB standards content review protocols operate on unpredictable cadences that delay feature releases for domestic engine distributions.
- Legacy CAD integration complexity:Enterprise manufacturing clients demand native import from Siemens NX and Dassault CATIA formats, forcing engine developers to maintain expensive interoperability layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global VR Game Engine Software Market |
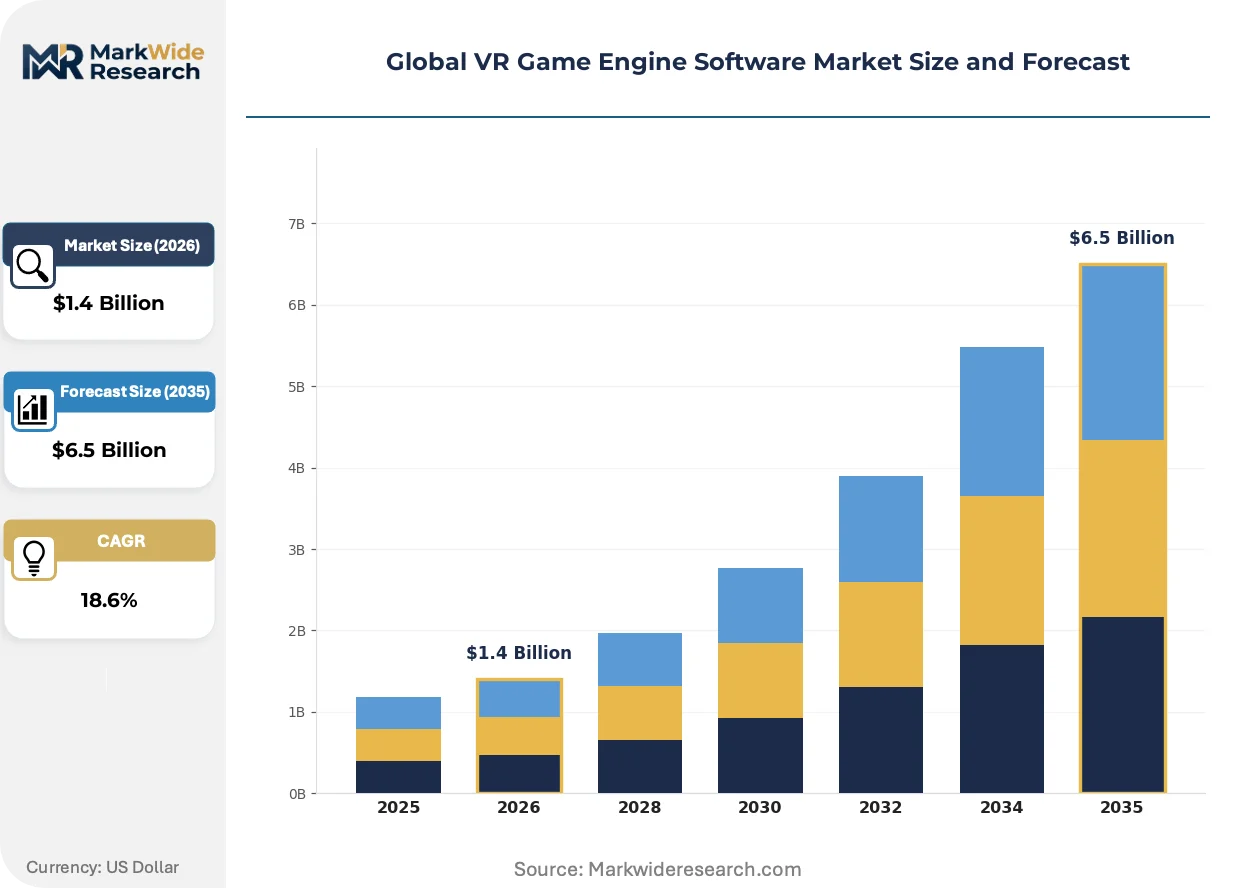
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform: Windows, macOS, Linux, Android, iOS, Others Rendering Technology: Real-Time Ray Tracing, Rasterization, Hybrid Rendering, Deferred Shading, Forward Rendering, Light Baking Application Sector: Entertainment, Education, Simulation, Training, Architectural Visualization, Virtual Tours Developer Type: Indie Studios, AAA Developers, Educational Institutions, Enterprise Developers, Freelancers, Agencies |
| Companies Covered | Unity Technologies, Epic Games, Autodesk, Crytek, Godot Engine, Cocos Creator, PlayCanvas, Amazon, O3DE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global VR Game Engine Software Market Shifts & Advancements
Neural rendering techniques and regulatory fragmentation around biometric data are simultaneously expanding creative possibility and compliance burden for engine architecture teams.
Neural radiance fields (NeRFs) are electrifying how volumetric scenes get reconstructed from sparse photographic inputs. Indie studios without dedicated photogrammetry hardware are adopting NeRF-based asset pipelines to compress production budgets. This democratization of high-fidelity environment creation is displacing traditional 3D scanning service bureaus and redistributing margin capture toward inference-optimized engine plugins.
The EU AI Act's algorithmic transparency mandates are forcing biometric processing modules into auditable sandbox architectures. Engine developers must now document decision pathways for eye-tracking calibration and facial expression inference. Simulation verticals serving European healthcare and defense clients are responding by segregating biometric features into optional, separately certified plugin tiers.
Enterprise procurement of VR training platforms is consolidating around multi-year outcome-based engagements rather than per-seat licensing. Industrial clients in Germany and the United States are unbundling content creation from runtime deployment, favoring engine vendors with managed service arms. This shift compresses upfront revenue recognition while extending customer lifetime value through mandatory update subscriptions.
Global VR Game Engine Software Market Segmentation
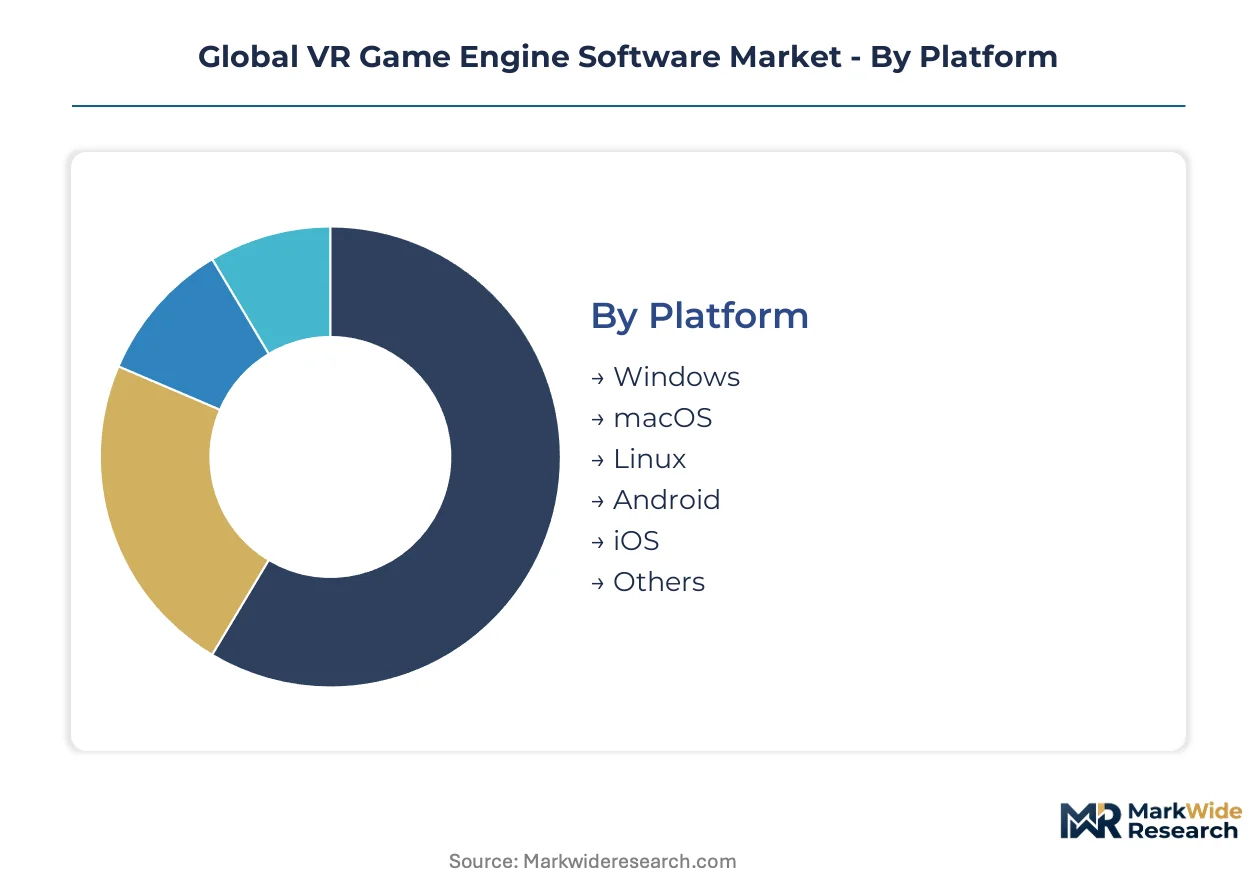
Segmentation in the VR game engine software market reveals how rendering architectures, platform targets, and developer economics fragment purchasing behavior across use cases. Understanding these divisions exposes where licensing revenue concentrates and which feature bundles command premium positioning.
Platform:
Operating system targeting determines hardware abstraction layers, SDK dependencies, and distribution channel access for engine deployments.
- Windows:Dominates desktop VR through native OpenXR and SteamVR integration. Enterprise simulation contracts in the United States and Germany default to Windows-targeted builds for HTC Vive and Varjo headset compatibility.
- Android:Powers standalone headsets from Meta and Pico, requiring aggressive optimization for thermal-constrained mobile SoCs. India's PLI scheme for electronics manufacturing is seeding domestic headset assembly that favors Android-native engine ports.
- macOS:Serves creative professionals in architectural visualization with Metal API pipelines, though headset hardware compatibility remains limited.
- Linux:Anchors research and defense applications requiring auditable source dependencies and air-gapped deployment environments.
- iOS:Supports phone-based VR viewers and ARKit-adjacent development, with engine support concentrated in lightweight visualization tools rather than immersive gaming.
- Others:Encompasses proprietary embedded systems for location-based entertainment and custom aerospace training hardware.
Mature deployment sits with Windows. Newer deployment is concentrated in Android.
Rendering Technology:
Pipeline architecture choices directly determine hardware requirements, content fidelity ceilings, and suitability for simulation-grade applications.
- Real-Time Ray Tracing:Simulates physically accurate light transport for surgical training and automotive design review. German industrial clients mandate ray-traced global illumination for digital twin visualization compliance.
- Rasterization:Retains dominance in mobile and standalone VR through predictable performance profiles. Chinese arcade VR operators rely on rasterization-optimized engines for high-throughput location-based entertainment.
- Hybrid Rendering:Combines ray-traced reflections with rasterized primary visibility, balancing quality and performance for mid-tier PC VR.
- Deferred Shading:Enables high dynamic range lighting with many dynamic sources, common in military simulation and night-training scenarios.
- Forward Rendering:Preserves multi-sample anti-aliasing quality for VR's high pixel density demands, preferred by flight simulator developers.
- Light Baking:Pre-computes static illumination for performance-constrained mobile deployments, standard in real estate virtual tours.
Established revenue pools center on rasterization. Steepest expansion trajectory belongs to real-time ray tracing.
Application Sector:
End-use verticals impose divergent certification requirements, content update cadences, and pricing model preferences on engine vendors.
- Entertainment:Interactive gaming and experiential media drive per-seat licensing volume. Japanese arcade chains and US theme park operators sustain demand for high-fidelity, low-latency rendering.
- Simulation:Physics-accurate environments for aviation, defense, and medical applications command enterprise-grade support contracts. EU AI Act compliance requirements are reshaping biometric data handling in European healthcare simulation deployments.
- Training:Workforce competency platforms in Germany and the United States are shifting toward outcome-based procurement, unbundling content creation from runtime licensing.
- Education:K-12 and university adoption concentrates on subscription tiers with curriculum-aligned asset libraries.
- Architectural Visualization:Reality-capture integration and CAD interoperability dominate purchasing criteria for Chinese and US real estate developers.
- Virtual Tours:Lightweight web-export and photogrammetry pipeline support define competitive positioning for hospitality and cultural heritage clients.
Margin concentration remains in entertainment. Fastest volume gains are appearing in training.
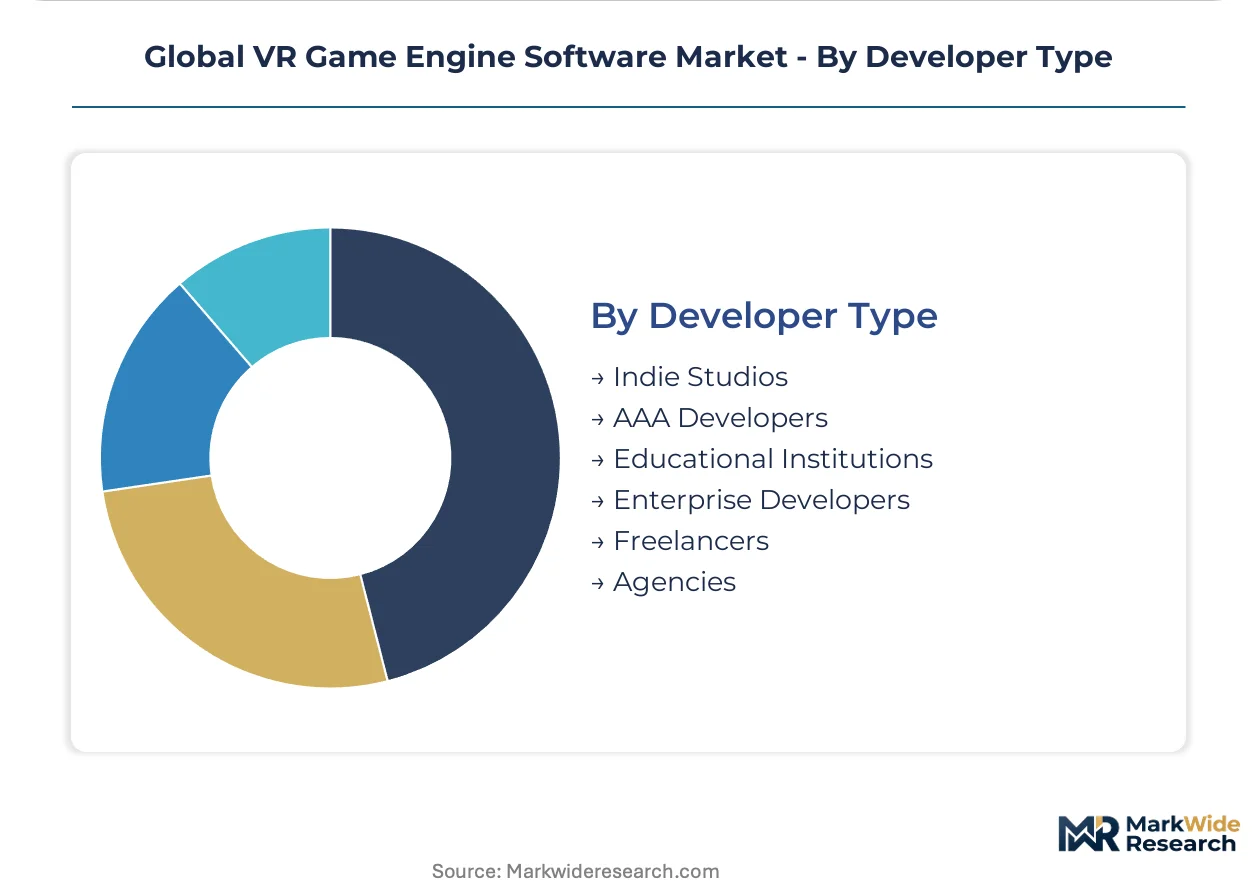
Developer Type:
Customer scale and technical sophistication determine support expectations, pricing tier selection, and platform loyalty patterns.
- AAA Developers:Maintain multi-year enterprise agreements with dedicated technical account management. Long-term licensing pools concentrate with simulation and entertainment studios in the United States and Germany.
- Indie Studios:Represent the expanding user base adopting cross-platform deployment tools and asset marketplace ecosystems. Revenue per seat is lower, but aggregate volume growth is climbing the fastest.
- Enterprise Developers:Internal IT and innovation teams at Fortune 500 manufacturers demand custom CAD importers and IoT sensor integration for digital twin applications.
- Educational Institutions:Qualify for academic pricing with restricted commercial use rights, serving as talent pipeline feeders rather than primary revenue contributors.
- Freelancers:Drive individual subscription tier adoption, particularly in architectural visualization and virtual tour production.
- Agencies:Service-based creative shops require project-based licensing flexibility and white-label runtime distribution rights.
Revenue depth sits with AAA developers. User base expansion is concentrated in indie studios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's venture concentration anchors North American engine development, while East Asian foundry capacity and European regulatory frameworks shape deployment patterns across three distinct innovation clusters.
United States
Surgical residency programs at Johns Hopkins and Mayo Clinic mandate immersive competency modules, pulling enterprise licensing volumes upward. The FCC governs wireless spectrum allocation for untethered headsets, enforcing sub-20-millisecond motion-to-photon baselines. Greater Boston hosts defense contractors integrating VR engines into air-gapped training environments for classified simulation work.
China
Architectural visualization studios in Shenzhen demand native photogrammetry pipelines for reality-capture workflows. The Ministry of Industry and Information Technology enforces content review protocols through GB standards, creating compliance delays for domestic engine distributions. Shanghai's Zhangjiang Hi-Tech Park clusters location-based entertainment operators optimizing rasterization engines for high-throughput arcade throughput.
Germany
Industrial facility operators in Stuttgart merge VR visualization with IoT sensor feeds for digital twin applications. The EU AI Act and GDPR impose algorithmic transparency and biometric data handling standards that constrain eye-tracking module architectures. Bavaria's Munich cluster anchors automotive design review contracts requiring ray-traced global illumination compliance.
India
Domestic assembly incentives under the PLI scheme for electronics manufacturing seed captive developer ecosystems favoring localized engine partnerships. The central bank's digital payment infrastructure supports subscription billing for indie studio tooling. Bangalore's Whitefield corridor concentrates mobile VR startups optimizing Android-native ports for thermally constrained chipsets.
Japan
Public procurement mandates from METI's immersive technology roadmap direct RFPs toward engine vendors with training-vertical certification. PMDA regulatory pathways shape healthcare simulation content approval timelines. Tokyo's Shibuya district hosts arcade chains sustaining demand for low-latency entertainment engines.
Global VR Game Engine Software Market Competitive Landscape
Global majors compete with regional champions across rendering fidelity tiers and compliance architecture depth. Market structure consolidates around three platform ecosystems with distinct vertical anchoring. Two strategic archetypes dominate: photorealistic simulation specialists and cross-platform deployment generalists. Competitive moves center on biometric audit pipeline certification and managed service arm construction for outcome-based procurement.
Within the ecosystem-platform tier, Unity Technologies and Epic Games occupy positions as archetype anchors for divergent developer economics. Unity exemplifies the mid-market generalist model with cross-platform deployment tools sustaining broad indie adoption. Epic represents the high-fidelity vertical specialist leveraging ecosystem depth for simulation-grade contracts. Crytek sits within the proprietary pipeline tier, differentiating through reality-capture workflows for architectural visualization clients.
| Leading Market Players |
|---|
| Unity Technologies |
| Epic Games |
| Autodesk |
| Crytek |
| Godot Engine |
| Cocos Creator |
| PlayCanvas |
| Amazon |
| O3DE |
| Others |
Supply & Pricing Matrix
Neural rendering plugin architectures are redistributing production economics toward inference-optimized compute tiers while compressing margins for traditional asset service bureaus. This technology transition simultaneously elevates cloud infrastructure dependencies and fragments pricing power across rendering pipeline layers.
Pricing Analysis
Extended technical support and biometric audit pipeline certification now anchor premium tier differentiation, with base subscriptions stripping out compliance modules to hit indie studio price points. Three-tier pricing structure across enterprise, professional, and indie levels reflects divergence in SLA guarantees and source code access rights. Cost compression in the professional tier is intensifying because Unity and Epic are racing to capture India's PLI-scheme developer ecosystem. Indie studios exhibit acute price sensitivity, while German automotive manufacturers accept substantial premiums for ray-traced global illumination guarantees.
Supply Chain Analysis
Regional distribution centers in Singapore, Frankfurt, and Los Angeles manage hub-and-spoke patterns for SDK delivery and headset compatibility certification kits. Foundry capacity for high-performance GPUs clusters in Taiwan and South Korea, with advanced packaging operations in the United States. The supply chain draws from specialized silicon, memory modules, and precision optics as core inputs. Single-source vulnerability around TSMC's leading-edge nodes exposes engine developers to allocation volatility that distorts hardware-targeted feature roadmaps. Distribution runs through direct enterprise sales teams for AAA contracts and digital marketplaces for indie tier adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global VR Game Engine Software Market is becoming a vertical-integration race as incumbents pursue captive control over biometric processing silicon and cloud inference infrastructure to defend margin pools.
For Market Incumbents: Lock in long-term enterprise agreements with dedicated technical account management before NeRF-based indie tools erode the mid-market. Acquire specialized shader optimization talent pools in Germany and the United States to compress hiring cycles for sub-20-millisecond latency engineering. Prioritize backward integration into cloud inference infrastructure to capture margin migrating from rendering software to compute services.
For New Entrants and Emerging Players: Launch via white-label runtime distribution partnerships targeting India's PLI-scheme headset manufacturers seeking localized engine alternatives. Exploit underpenetrated architectural visualization workflows in China where Crytek's proprietary photogrammetry leaves room for NeRF-native competitors. Target outcome-based procurement contracts in German industrial training verticals where incumbent managed service arms remain underdeveloped.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform ecosystem acquisitions by hyperscalers seeking spatial computing infrastructure. Five-to-ten-year viability hinges on biometric audit pipeline certification depth rather than rendering fidelity alone. Target acquisition archetypes are indie-focused engine shops with pre-built EU AI Act compliance modules. Watch for FCC spectrum allocation decisions on untethered VR as the inflection signal for standalone versus tethered hardware investment priority.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Audit Pipeline Certification | EU AI Act mandates algorithmic transparency for eye-tracking modules in European healthcare deployments. |
| Neural Rendering Plugin Development | NeRF-based asset pipelines displace traditional 3D scanning service bureaus and redistribute margin capture. |
| Managed Service Arm Construction | German industrial clients favor outcome-based procurement unbundling content creation from runtime licensing. |
| PLI Scheme Partnership Formation | India's domestic headset assembly incentives seed captive developer ecosystems favoring localized distribution. |
| Ray-Tracing Hardware Co-Design | Automotive design review contracts in Bavaria mandate physically accurate lighting compliance. |
Research Methodology
Independent corroboration across primary interviews with engine architecture leads, VR studio technical directors, and enterprise procurement officers underwrites the qualitative findings. Secondary validation draws from FCC spectrum allocation filings, EU AI Act implementation guidance, MIIT GB standards documentation, and PLI scheme administrative data. Bottom-up triangulation across developer type segments and top-down reconciliation against platform ecosystem revenue disclosures ensure methodological rigor.
Rate-of-change decomposition across the analysis window separates volume expansion in indie studios from value concentration in AAA enterprise agreements. Segmentation dimensions modeled include rendering technology tier, platform target, application vertical, and regional regulatory cluster. CAGRs were derived from growth driver elasticity estimates and hardware shipment correlation analysis. Industry-specific forecast inputs incorporate FCC wireless spectrum decisions and EU biometric processing compliance timelines.
GPU supply allocation shocks, regulatory certification delays under China's GB standards, and NeRF technology diffusion curves are the dominant revision risks. Forecasts reflect documented assumptions regarding headset hardware shipment trajectories and enterprise licensing contract renewal rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Android Emulator Market
Software & Services
Global Time Series Analysis Software Market
Software & Services
Global Voip Software Market
Software & Services
RIP Color Management Software Market
Software & Services
Enterprise Data Observability Software Market
Software & Services
Supply Chain Visibility (SCV) Software Market
Software & Services
Agile Application Life-Cycle Management Market
Software & Services
Deck Software Market
Software & Services
App Development Software Market
Software & Services
Computer Assisted Coding Software Market
Software & Services
Global Help Desk Software Market
Software & Services
Metal Recycling Software Market
Software & Services
Global Disk Imaging Software Market
Software & Services
Global Restaurant POS Software Market
Software & Services
Global Data Warehouse Software Market
Software & Services
Construction and Design Software Market