
 Global Restaurant POS Software Market | 2026-2036
Global Restaurant POS Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Restaurant POS Software Market Outlook
India's restaurant technology corridor is reconfiguring how vendors approach emerging market deployment. Toast Inc. leverages its integrated hardware-software stack to sustain dominance in North American full-service segments. Square Inc. anchors small-format merchant adoption through streamlined onboarding tools. NCR Corporation competes across legacy on-premise installations while navigating cloud transition pressures.
Restaurant POS software comprises digital transaction processing platforms that integrate order capture, payment authorization, kitchen display routing, and real-time sales analytics through local server or cloud-native architectures. These systems synchronize front-of-house operations with back-office inventory and labor scheduling to optimize throughput during peak service intervals. Cloud-based deployment leads system type adoption due to lower capital barriers and automatic feature updates, while on-premise installations retain share among operators with strict data sovereignty requirements. Quick service restaurants represent the fastest-growing end user category as drive-thru optimization and kiosk integration demand specialized throughput architecture. Feature set segmentation shows payment processing and inventory management modules capturing the deepest margin pools through recurring interchange and per-transaction fee structures.
The EU AI Act and GDPR impose algorithmic transparency and data localization requirements on European POS deployments, while India's RBI mandates tokenized payment storage standards for domestic foodservice operators. The US lacks unified federal POS regulation but PCI-DSS compliance and state-level biometric privacy laws in Illinois and Texas shape product development constraints. Stakeholders must monitor evolving AI disclosure mandates and cross-border data flow restrictions as these frameworks determine market access eligibility and vendor certification timelines.
Market Dynamics
Cloud-native architecture is collapsing the traditional on-premise deployment model across foodservice operations, compressing vendor margins while expanding addressable merchant bases through subscription economics.
Growth Catalysts
- EU AI Act compliance mandates:European operators face algorithmic transparency requirements for automated ordering systems. Vendors achieving early certification capture procurement preference from multinational chains.
- Quick service restaurant kiosk integration:Drive-thru throughput optimization demands specialized POS-to-kitchen display routing. Cloud platforms enable real-time menu synchronization across distributed locations.
- RBI tokenization standards in India:Domestic foodservice operators must adopt encrypted payment storage. Local vendors and global entrants compete on compliance velocity.
Market Restraints
- Semiconductor supply concentration:Dedicated payment terminal chipsets depend on Taiwan and South Korea fabrication capacity. Geopolitical friction threatens hardware delivery timelines.
- Legacy on-premise sunk costs:Full-service restaurants with depreciated server infrastructure delay cloud migration. Replacement cycles extend beyond typical SaaS conversion windows.
- GDPR data localization friction:Cross-border transaction processing requires EU-resident data storage. Multi-tenant cloud architectures face architectural reconfiguration costs.
Strategic Opportunities
- Brazilian foodservice modernization:Independent restaurant density exceeds installed POS penetration. Mobile-first platforms bypass traditional hardware distribution constraints.
- Voice-to-kitchen automation:Natural language processing converges with kitchen display systems. Early deployments reduce order entry labor during peak intervals.
- US state biometric privacy divergence:Illinois BIPA and Texas CUBI create compliance complexity. Vendors with modular identity verification architectures capture multi-state operators.
Industry Challenges
- PCI-DSS certification timeline compression:Annual assessment cycles strain engineering resources. Subcontractor auditor availability bottlenecks product release schedules.
- API fragmentation across legacy ERP:Inventory and labor scheduling systems lack standardized integration protocols. Custom connector development consumes professional services capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Restaurant POS Software Market |
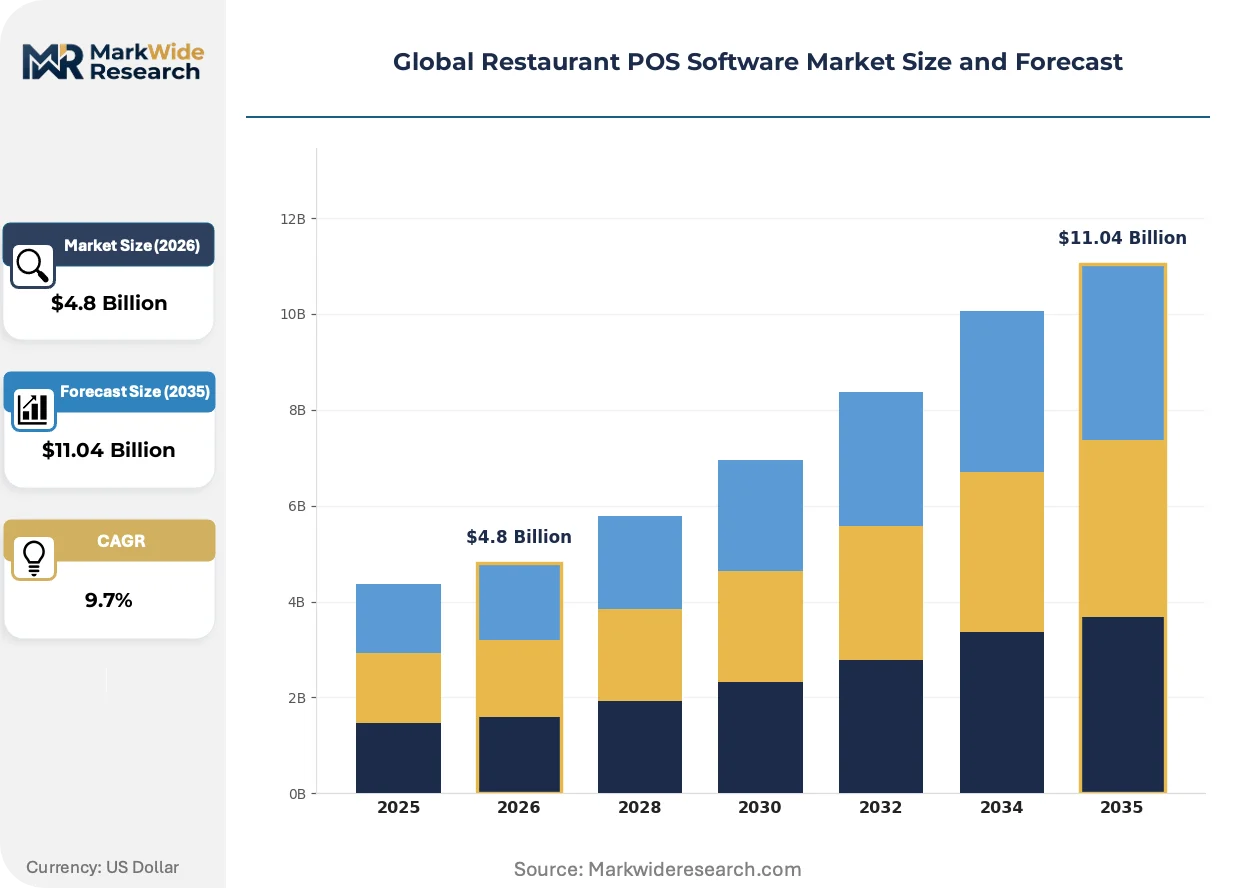
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Cloud-Based, On-Premise, Hybrid, Mobile Deployment Method: Web-Based, Local Server, Subscription, Custom End User Type: Quick Service Restaurants, Full-Service Restaurants, Cafes, Food Trucks Feature Set: Payment Processing, Inventory Management, Customer Relationship Management, Reporting Tools |
| Companies Covered | Toast Inc., Square Inc., NCR Corporation, Oracle Hospitality, Lightspeed Commerce, Clover Network Inc., Revel Systems, TouchBistro, Epos Now, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Restaurant POS Software Market Strategic Shifts
Artificial intelligence inference at the edge is reshaping how transaction data transforms into operational intelligence, compressing the latency between customer interaction and kitchen response.
Edge computing hardware is collapsing the distance between payment authorization and predictive analytics processing. Quick service operators in high-throughput environments deploy GPU-enabled terminals for real-time demand forecasting. This architecture eliminates round-trip latency to centralized cloud servers during peak service intervals.
GDPR Article 35 data protection impact assessments now extend to AI-enabled recommendation engines embedded in POS interfaces. European regulators scrutinize automated upselling algorithms for discriminatory patterning. Vendors serving EU markets reengineer transparency dashboards to satisfy supervisory authority documentation requirements.
Merchant acquisition through integrated software-hardware bundles is displacing standalone software licensing across North American full-service segments. Toast and Square anchor this model with subsidized terminal deployment recovered through payment processing spreads. Independent software vendors without captive hardware manufacturing face margin compression or partnership dependency.
Global Restaurant POS Software Market Segmentation
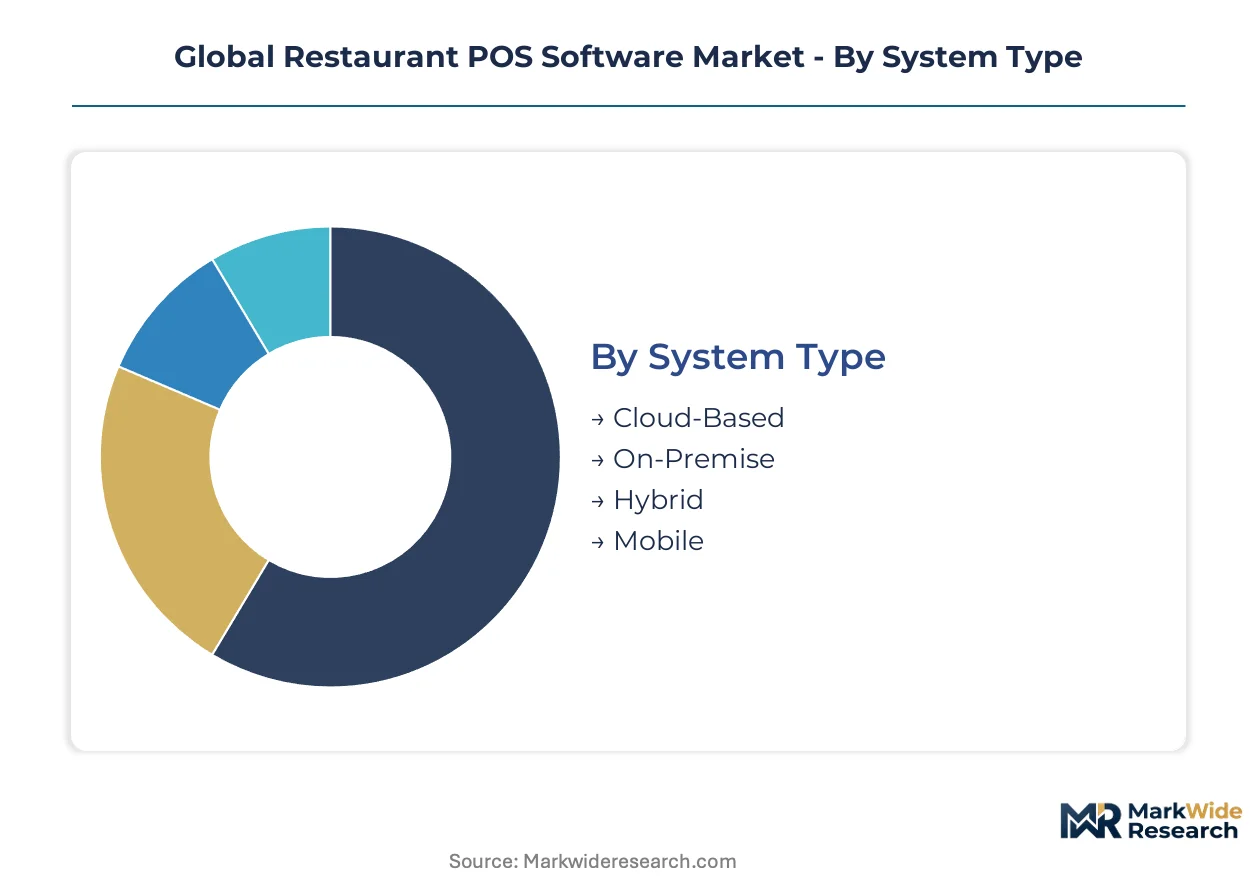
Restaurant POS software vendors architect product portfolios around four distinct segmentation axes. Each dimension captures different operational constraints, compliance burdens, and margin structures that determine competitive positioning.
System Type:
Cost tier differentiation separates capital-intensive installations from subscription-native alternatives.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server maintenance overhead. Quick service chains in the United States and India prioritize this model for distributed menu synchronization and automatic PCI-DSS patch deployment.
- On-Premise:Dedicated local servers retain data sovereignty for operators in jurisdictions with strict localization mandates. Full-service establishments in Germany and France maintain these installations to satisfy GDPR Article 44 cross-border transfer restrictions.
- Hybrid:Edge processing for payment authorization with cloud analytics aggregation. Brazil's independent restaurant sector adopts this middle-ground approach.
- Mobile:Smartphone-native transaction capture without dedicated terminal hardware. Food trucks in Texas and California leverage this for minimal equipment footprint.
Cloud-Based commands the established base. The steepest expansion runs through Mobile.
Deployment Method:
Application architecture determines integration depth with existing foodservice technology stacks.
- Web-Based:Browser-accessible interfaces running on standard tablets or PCs. Cafes in the United Kingdom favor this for minimal hardware procurement.
- Local Server:Dedicated on-site infrastructure with offline transaction capability. Japanese full-service restaurants maintain these for resilience during network outages.
- Subscription:Recurring licensing with bundled support and feature updates. Quick service operators in Mexico and Colombia prefer predictable operational expenditure.
- Custom:Bespoke development for enterprise chains with proprietary kitchen display protocols. Large casino-hospitality complexes in Nevada and Macau commission these builds.
Subscription licensing commands the established base. Web-Based deployment is climbing the fastest.
End User Type:
Customer type segmentation aligns feature depth with operational velocity requirements.
- Quick Service Restaurants:High-throughput environments demanding sub-second payment authorization and kitchen display routing. Drive-thru optimization in the United States and kiosk integration in India concentrate demand here.
- Full-Service Restaurants:Table-side ordering workflows with split-check complexity and tip distribution. Fine dining establishments in France and Italy require extensive wine inventory integration.
- Cafes:Simplified menu structures with loyalty program emphasis. Australia's independent coffee culture drives specialized loyalty module demand.
- Food Trucks:Mobility-first operations requiring offline transaction storage and cellular connectivity resilience. Street food vendors in Brazil and Thailand adopt ruggedized mobile terminals.
Full-Service Restaurants command the established base. Quick Service Restaurants are gaining share fastest.
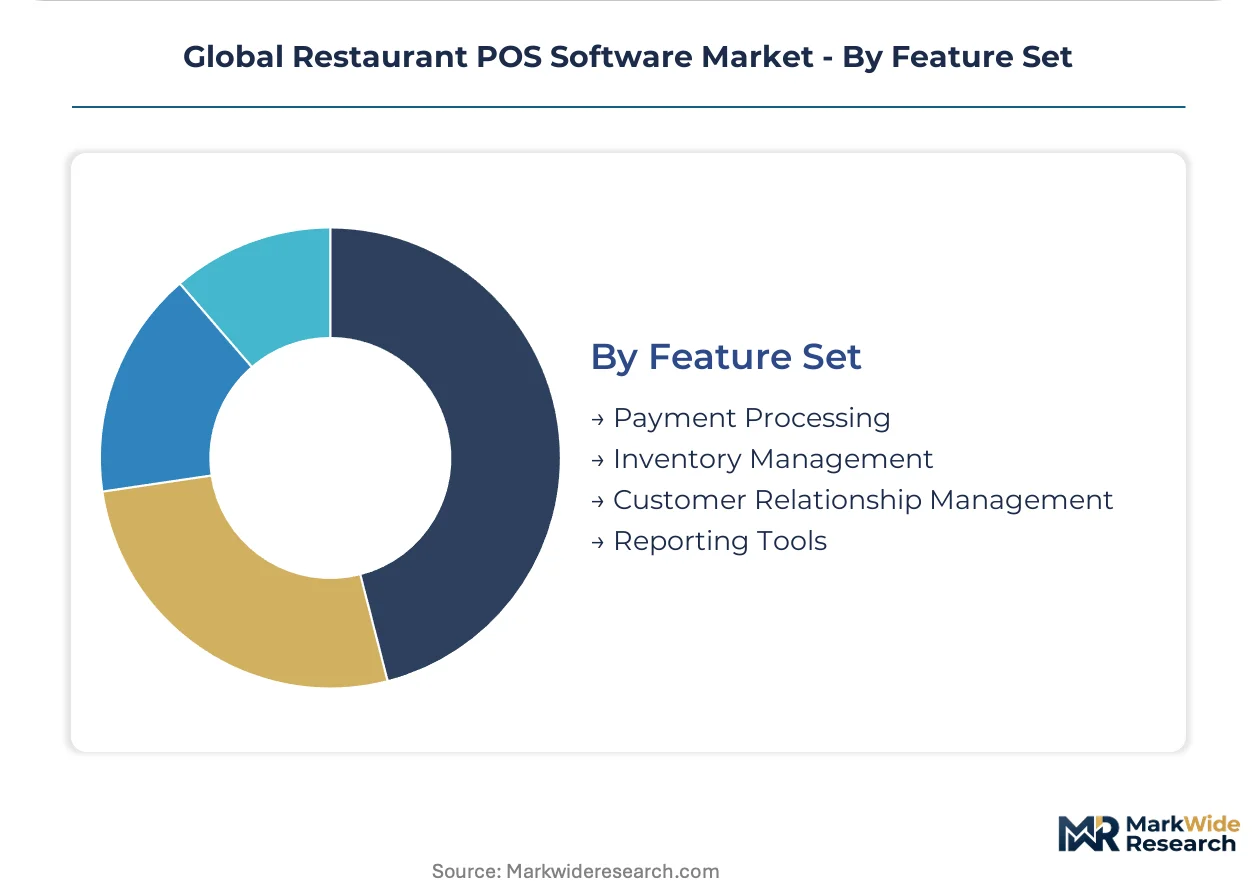
Feature Set:
Margin concentration varies sharply across functional modules based on recurring revenue potential.
- Payment Processing:Interchange fee participation and tokenized vault services generate the deepest recurring pools. RBI-mandated encryption standards in India and PCI-DSS Level 1 certification requirements in the United States create vendor qualification barriers.
- Inventory Management:Real-time stock depletion tied to POS transaction capture. Full-service chains in Spain and Italy leverage this for perishable ingredient optimization.
- Customer Relationship Management:Loyalty program administration with automated promotion targeting. Quick service operators in Canada use this for personalized upsell algorithms.
- Reporting Tools:Sales analytics with labor cost allocation and menu engineering insights. Independent restaurants in the United Kingdom prioritize these for owner-operator decision support.
Payment Processing commands the established base. Inventory Management shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor engineering resources concentrate disproportionately in the United States, India, and Brazil as these markets drive cloud-native POS architecture development. Taiwan and South Korea fabrication capacity constrains hardware delivery timelines for terminal deployments worldwide. Regulatory fragmentation across GDPR, RBI tokenization, and US state biometric laws forces multi-jurisdictional compliance engineering.
United States
Quick service chains drive cloud migration through drive-thru optimization and kiosk integration demands. Illinois BIPA and Texas CUBI impose modular identity verification requirements on multi-state operators. Silicon Valley engineering clusters and Atlanta payment processing hubs anchor vendor R&D concentration.
India
RBI-mandated tokenized payment storage accelerates domestic compliance engineering among foodservice operators. The central bank's encryption standards create vendor qualification barriers that favor early certifiers. Bangalore's restaurant technology corridor reconfigures emerging market deployment playbooks for global vendors.
Germany
Full-service establishments maintain on-premise installations to satisfy GDPR Article 44 cross-border transfer restrictions. The EU AI Act imposes algorithmic transparency requirements for automated ordering systems. Munich and Frankfurt banking infrastructure supports specialized POS financing for mid-market restaurant groups.
Brazil
Independent restaurant density exceeds installed POS penetration, creating mobile-first platform opportunities. ANVISA food safety traceability requirements intersect with payment data integration. São Paulo's foodservice modernization concentrates demand for hybrid cloud-edge architectures among street food vendors.
United Kingdom
Cafes favor web-based interfaces for minimal hardware procurement in high-rent urban locations. The Information Commissioner's Office enforces GDPR data protection impact assessments for AI-enabled recommendation engines. London fintech clusters supply embedded payment processing innovation to hospitality software vendors.
Global Restaurant POS Software Market Competitive Environment
Integrated hardware-software bundles and standalone SaaS platforms split the market into divergent margin structures. Toast and Square anchor the bundle model with subsidized terminal deployment recovered through payment spreads, while Lightspeed and TouchBistro occupy the software-native tier. Consolidation pressures intensify as merchant acquisition costs rise and processing margin compression forces scale economies. Strategic moves concentrate on API ecosystem expansion and vertical feature integration rather than pure geographic expansion.
Within the integrated bundle tier, Toast Inc. and Square Inc. exemplify the hardware-software convergence model that dominates North American full-service adoption. NCR Corporation occupies a transitional position spanning legacy on-premise maintenance and cloud migration services. These three anchors represent divergent responses to the collapse of traditional deployment economics: captive manufacturing integration, streamlined onboarding tooling, and installed base monetization respectively.
| Leading Market Players |
|---|
| Toast Inc. |
| Square Inc. |
| NCR Corporation |
| Oracle Hospitality |
| Lightspeed Commerce |
| Clover Network Inc. |
| Revel Systems |
| TouchBistro |
| Epos Now |
| Others |
Value Chain & Pricing Dynamics
The Shenzhen-Hong Kong logistics corridor's freight cost volatility compresses hardware margin pools while amplifying subscription-tier price differentiation between cloud-native and on-premise deployments. Taiwan Semiconductor Manufacturing Company's fabrication capacity constraints feed terminal chipset scarcity, forcing vendors to absorb upstream cost spikes or pass them through to quick service operators with limited substitution options.
Pricing Analysis
PCI-DSS Level 1 certification dictates the pricing tier structure across the vendor landscape. Three-tier pricing separates enterprise-grade tokenized vault services from mid-market SaaS bundles and basic mobile-only offerings. Price differentiation hinges on certification depth and geographic data residency compliance, with EU AI Act transparency modules commanding substantial premiums. Cost compression in the mid-market tier intensifies because Toast and Square subsidize terminal hardware through processing spread recovery. Independent restaurants exhibit the highest price sensitivity, while multinational quick service chains prioritize compliance velocity over unit economics.
Supply Chain Analysis
US Commerce Department export controls on advanced GPU chipsets limit edge-computing terminal flows to certain fabrication nodes. Hardware assembly concentrates in Taiwan, South Korea, and Mexico's Baja California corridor. Dedicated payment terminal production draws from Taiwan Semiconductor, Samsung Foundry, and specialty display manufacturers in Shenzhen. Single-source vulnerability pervades the GPU-enabled edge computing segment where NVIDIA's Jetson modules dominate kitchen display integration. Distribution runs through authorized hardware resellers and direct-to-merchant SaaS channels with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where switching costs lock merchants into integrated hardware-software bundles. Regulatory entrenchment through PCI-DSS certification timelines and GDPR compliance engineering creates asymmetric barriers for new entrants.
For Market Incumbents: Insulate core merchant relationships through captive hardware manufacturing integration and accelerated EU AI Act certification pipelines. Embedded payment processing spreads recover terminal subsidies while API ecosystem expansion deepens integration stickiness. Threats from modular API-first challengers require preemptive vertical integration into kitchen display manufacturing. Certification velocity in India's RBI tokenization framework represents the priority defensive lever.
For New Entrants and Emerging Players: Mid-market full-service restaurants in Brazil and Southeast Asia represent the most penetrable entry point for mobile-first platforms bypassing hardware distribution constraints. Voice-to-kitchen automation modules for high-throughput quick service environments offer specialized wedge opportunities. API-native architectures targeting legacy ERP fragmentation capture professional services revenue pools. Channel partnerships with existing payment processors accelerate merchant acquisition without captive terminal manufacturing.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy on-premise vendors with depreciated installed bases and cloud migration service capabilities. Long-term viability favors platforms with integrated hardware-software economics and regional compliance engineering depth. Acquisition archetypes include specialized kiosk integration vendors and GDPR-certified analytics modules. The signal to watch is RBI tokenization certification velocity as an inflection indicator for emerging market access eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Acceleration | Early certifiers capture procurement preference from McDonald's and Burger King European deployments. |
| Hardware-software Bundle Expansion | Subsidized terminal deployment recovers margin through interchange spreads and locks merchant switching costs. |
| API Ecosystem Deepening | Standardized connectors to Oracle Hospitality and legacy ERP systems reduce professional services drag. |
| Edge Computing Integration | GPU-enabled terminals for real-time demand forecasting eliminate cloud latency during peak service intervals. |
| Regional Compliance Engineering | Dedicated GDPR and RBI tokenization teams accelerate certification timelines and market access velocity. |
Study Parameters
Operator-level perspectives from quick service chain CTOs, full-service restaurant owners, payment processing integration specialists, and kitchen display system engineers anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings of publicly traded vendors, RBI circulars on tokenization standards, EU AI Act implementation guidance, and PCI-DSS certification databases. Bottom-up merchant adoption modeling triangulated against top-down cloud infrastructure spend analysis from hyperscaler disclosures.
Scenario-bracketing framed the analytical approach across the projection horizon. Segmentation dimensions modeled include system type, deployment method, end user category, and feature module penetration. CAGRs derived from installed base conversion rates, new merchant formation velocity, and average revenue per user expansion across subscription tiers. Forecast inputs incorporated RBI tokenization compliance timelines and EU AI Act enforcement phase transitions.
Practitioners should monitor semiconductor fabrication capacity allocation and geopolitical export control expansion for early signals. Forecasts reflect assumptions around cloud migration velocity and regulatory certification timeline compression. Material shifts in Taiwan Strait logistics disruption or GDPR Article 35 enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Online Whiteboard Software Market
Software & Services
Electronic Batch Records Market
Software & Services
Electromagnetic Simulation Software Market
Software & Services
Global Plumbing Software Market
Software & Services
Illustration Software Market
Software & Services
North America Equity Management Software Market
Software & Services
Global Gym Software Market
Software & Services
Europe Database Management Software Market
Software & Services
EDA Tools Market
Software & Services
Global Testing Software Market
Software & Services
Hackathon Management Software Market
Software & Services
Global Florist Software Market
Software & Services
Database Monitoring Software Market
Software & Services
Global Equity Management Software Market
Software & Services
Business Productivity Software Market
Software & Services
Global Video Streaming Software Market