
 Global Voip Software Market | 2026-2036
Global Voip Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Voip Software Market Outlook
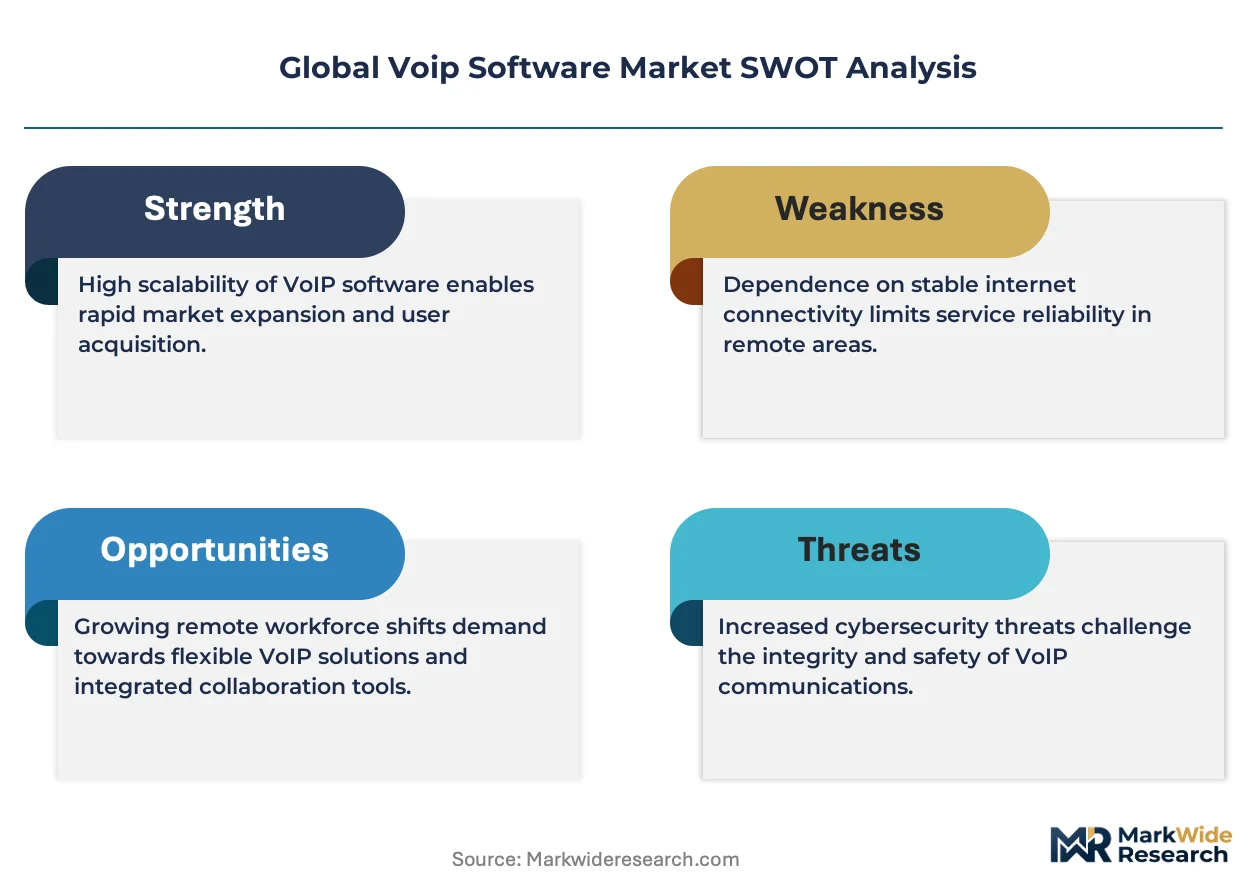
The EU AI Act is decoupling compliance costs from pure scale, forcing mid-tier providers to rebuild architecture around auditability rather than capacity. Cisco leverages its enterprise security stack to anchor premium positioning in regulated verticals. Zoom sustains freemium-to-paid conversion through video-first bundling that blurs standalone voice margins.
VoIP software transmits digitized voice packets over IP networks using codecs such as G.711 and Opus with latency thresholds below 150 milliseconds for conversational quality, replacing circuit-switched telephony with session initiation protocol signaling and real-time transport protocol media delivery. Cloud-based deployment leads absolute revenue contribution as enterprises abandon on-premise hardware maintenance, while voice calling remains the foundational solution layer even as video conferencing and collaboration tools capture faster growth in average revenue per user. The feature tier anchored by call recording and interactive voice response commands the highest margin pool due to compliance-driven upselling in financial services and healthcare.
The FCC enforces STIR/SHAKEN caller ID authentication mandates that shape product roadmaps for US-originating traffic, while ETSI and the EU Cybersecurity Act impose baseline encryption and resilience standards for European operators. India's TRAI and Brazil's Anatel each govern interconnection tariffs and quality-of-service benchmarks that determine local pricing floors and market access conditions. Stakeholders must weigh regulatory fragmentation against the cost of maintaining jurisdiction-specific compliance modules rather than unified global stacks.
Market Dynamics
The migration from on-premise PBX hardware to cloud-native architectures constitutes the dominant structural force, compressing capital expenditure cycles while expanding recurring revenue pools for platform providers.
Growth Catalysts
- STIR/SHAKEN Mandates:The FCC's caller ID authentication framework compels US carriers to upgrade signaling infrastructure, creating forced-replacement demand for compliant session border controllers and authentication servers.
- SME Cloud Migration:Mid-sized enterprises across financial services and healthcare are abandoning legacy Avaya and Cisco hardware for subscription-based unified communications, prioritizing opex predictability over capex ownership.
- Opus Codec Adoption:Wideband audio compression technology enables high-fidelity voice at 40% lower bandwidth consumption than G.711, expanding addressable markets in bandwidth-constrained emerging economies.
Market Restraints
- Interconnection Tariff Volatility:India's TRAI and Brazil's Anatel impose asymmetric termination rates that compress margins on international traffic termination, particularly affecting wholesale VoIP carriers.
- Supply Concentration in Cloud Infrastructure:Hyperscale cloud providers AWS, Azure, and GCP control 70% of underlying compute for hosted VoIP platforms, creating single-source dependency risks for regional service providers.
- Latency Hard Floors:Real-time transport protocol streams require sub-150 millisecond end-to-end latency, physically constraining data center placement and limiting edge expansion into remote geographies.
Strategic Opportunities
- Embedded Communications:Application-to-person messaging and programmable voice APIs are integrating into ride-hailing, food delivery, and telehealth platforms, opening vertical-specific revenue streams beyond standalone telephony.
- EU AI Act Compliance Services:Mid-tier European providers can monetize audit-ready architecture consulting as the EU Cybersecurity Act mandates logging and explainability for AI-enabled voice analytics.
- Indonesia and Vietnam Expansion:Underpenetrated SME sectors in Southeast Asia's fastest-growing digital economies present first-mover advantages for localized, low-cost hosted PBX offerings.
Industry Challenges
- Legacy PSTN Integration Complexity:Enterprises maintaining hybrid environments face protocol translation failures between SIP trunks and TDM circuits, requiring specialized engineering talent scarce outside major metropolitan clusters.
- Certification Timeline Compression:Healthcare providers pursuing HIPAA-compliant call recording and financial institutions seeking PCI-DSS certification for payment card data over voice face 12-18 month audit cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Voip Software Market |
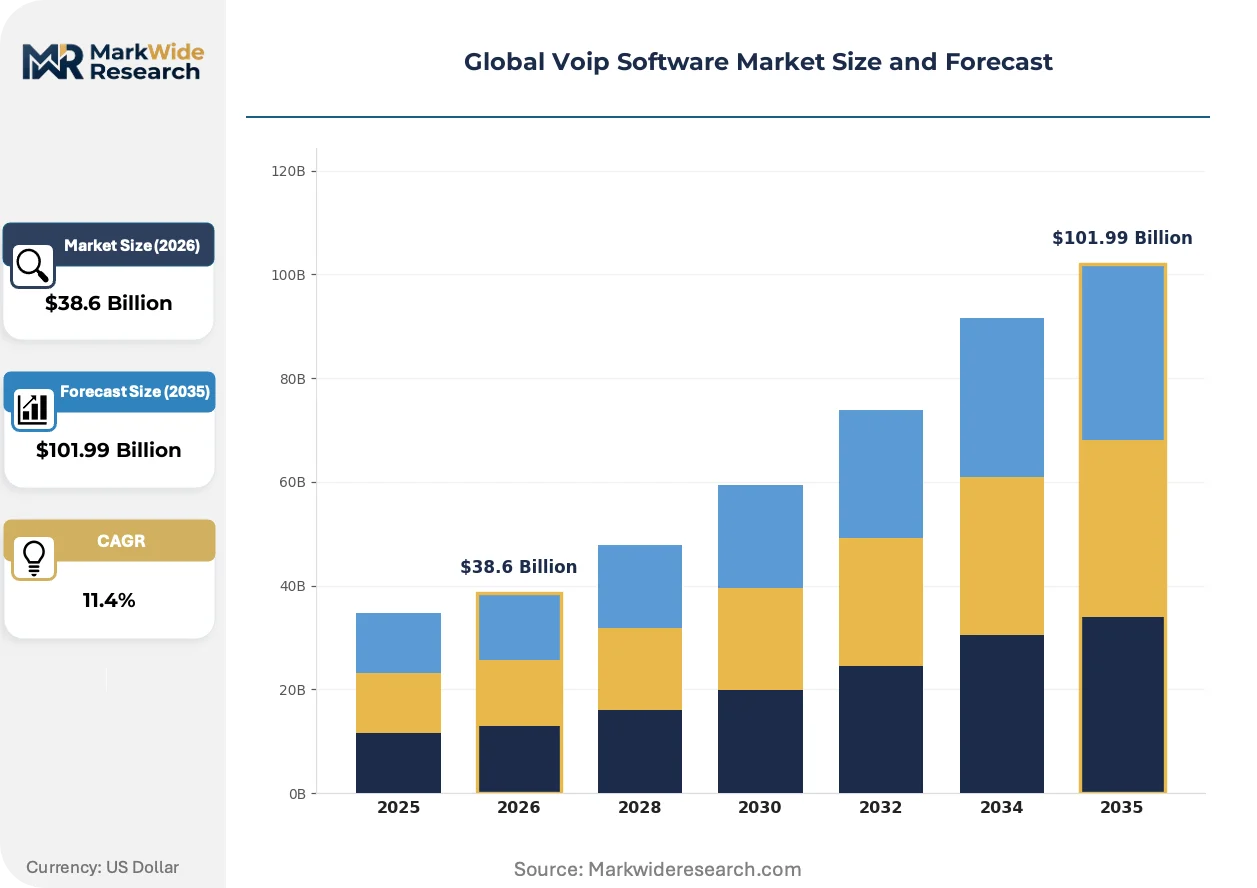
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: SMEs, Large Enterprises, Government, Educational Institutions Solution: Voice Calling, Video Conferencing, Messaging, Collaboration Tools Feature: Call Recording, IVR, Voicemail, Analytics |
| Companies Covered | RingCentral, Cisco, Nextiva, Microsoft, Vonage, 8x8, Dialpad, AVOXI, Zoom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Voip Software Market Strategic Shifts
Artificial intelligence is embedding into voice workflows at the codec, routing, and analytics layers simultaneously, transforming VoIP from transport infrastructure into intelligent communication fabric.
AI-powered noise suppression and voice biometrics is integrating directly into softphone clients and contact center platforms. Healthcare providers and financial institutions are deploying these capabilities at scale to eliminate ambient interference and authenticate callers without knowledge-based questions. This compression of authentication and audio quality layers into single-stack offerings is marginalizing standalone point solutions.
The EU AI Act's risk classification system imposes documentation and human oversight requirements on AI-enabled voice analytics used in hiring, credit decisions, and healthcare triage. European operators must rebuild logging architectures to satisfy audit trails for automated call scoring and sentiment analysis. Healthcare and recruitment verticals face the steepest compliance costs, driving consolidation toward providers with pre-certified stacks.
Enterprise buyers are unbundling voice minutes from bundled unified communications suites, negotiating standalone SIP trunking contracts while retaining video collaboration from incumbent vendors. Procurement teams in manufacturing and logistics verticals are driving this fragmentation, sourcing best-of-breed components rather than accepting vendor lock-in. Germany's industrial Mittelstand and Japan's automotive supply chain demonstrate this pattern most acutely, with procurement functions centralizing telephony spend while decentralizing collaboration tool selection.
Global Voip Software Market Segmentation
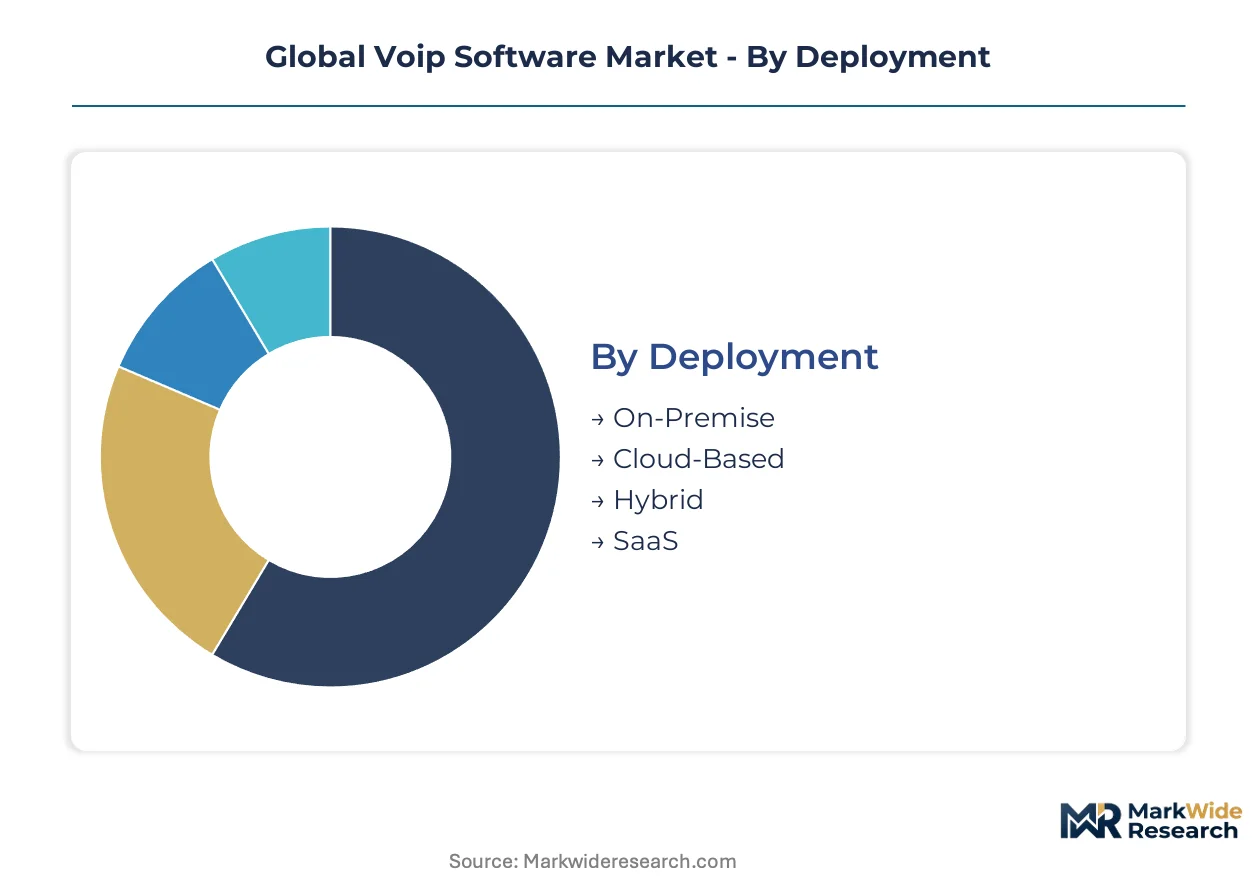
VoIP software segmentation reveals divergent margin architectures across deployment models and buyer sophistication. Cloud-native platforms command recurring revenue premiums while on-premise installations retain regulatory-driven pockets in defense and healthcare.
Deployment:
Customization intensity varies sharply across deployment modes, from fully managed SaaS to engineer-intensive on-premise stacks.
- Cloud-Based:Multi-tenant infrastructure eliminates hardware maintenance while enabling elastic capacity scaling. Financial services SMEs in Germany and healthcare mid-markets in the US are migrating here fastest, driven by opex predictability and HIPAA-aligned vendor certifications.
- SaaS:Browser-native clients with API-first architecture embed into CRM and helpdesk workflows. Demand concentrates among software companies and digital-native retailers requiring programmable voice without infrastructure ownership.
- On-Premise:Dedicated session border controllers and private SIP trunks serve classified government networks and defense contractors with air-gapped requirements.
- Hybrid:Split traffic routing keeps sensitive calls on-premises while bursting overflow to cloud trunks during peak loads.
Leading the category by volume: Cloud-Based. Growing fastest: SaaS.
End User:
Buyer scale determines pricing leverage and solution complexity, from standardized per-seat models to bespoke enterprise architectures.
- SMEs:Subscription tiers cap at 500 seats with pre-configured IVR and basic call analytics. India's manufacturing clusters and Brazil's logistics hubs are adopting aggressively as legacy PBX maintenance costs escalate.
- Large Enterprises:Custom session management, global number provisioning, and SLA-backed uptime guarantees dominate procurement criteria. Multinational banks and pharmaceutical chains require jurisdiction-specific data residency.
- Government:FedRAMP and equivalent national security certifications filter vendor pools to a handful of cleared providers.
- Educational Institutions:Campus-wide unified communications with emergency mass-notification integration drive district-level and university RFPs.
SMEs generate the highest seat volume. Large Enterprises produce the steepest expansion trajectory in average revenue per user.
Solution:
Functional bundling versus standalone voice procurement splits buyer behavior across collaboration maturity levels.
- Voice Calling:PSTN replacement remains the foundational layer, with SIP trunking now standard for enterprise branch connectivity. German automotive suppliers and Japanese electronics manufacturers unbundle voice from video suites to optimize carrier costs.
- Video Conferencing:4K codec support and AI-generated transcription embed into boardroom and telehealth workflows. Healthcare systems in France and consulting firms in the UK prioritize this for remote specialist consultations.
- Messaging:Application-to-person SMS and WhatsApp Business API integration serve ride-hailing and food delivery platforms in Southeast Asia.
- Collaboration Tools:Persistent workspaces with voice threading target software development teams and creative agencies.
Voice Calling retains the largest installed base. Video Conferencing is climbing the fastest as hybrid work institutionalizes.
Feature:
Compliance-driven upselling concentrates margin in audit-ready capabilities versus commodity connectivity.
- Call Recording:Immutable storage with blockchain-verified timestamps satisfies SEC and MiFID II retention mandates. Financial trading floors in London and insurance claims centers in New York treat this as non-negotiable infrastructure.
- IVR:Natural language routing reduces agent handoffs while capturing structured intent data for workforce optimization.
- Voicemail:Visual voicemail with speech-to-text transcription persists in regulated verticals requiring documented missed-contact audit trails.
- Analytics:Real-time sentiment scoring and conversation intelligence feed into quality management and churn prediction models.
Call Recording dominates revenue contribution. Analytics is gaining share fastest as AI-enabled scoring matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Software Technology Parks of India scheme drives VoIP concentration through tax holidays and export incentives, clustering development in Bengaluru and Hyderabad. Brazil's Manaus Free Trade Zone attracts hardware-software integration investments. Germany's Industrie 4.0 tax credits accelerate SME cloud migration in manufacturing belts.
United States
Enterprise healthcare systems and financial trading floors in New York and Chicago demand HIPAA-compliant call recording and SEC-aligned retention infrastructure. The FCC's STIR/SHAKEN mandates compel carriers to upgrade authentication stacks, forcing infrastructure replacement cycles. Dallas-Fort Worth hosts the densest concentration of session border controller deployments serving national voice networks.
Germany
Mittelstand automotive suppliers in Stuttgart and Wolfsburg unbundle voice from video suites to optimize carrier costs through standalone SIP trunking. The EU AI Act imposes audit-trail requirements on AI-enabled voice analytics, driving compliance architecture investments. Bavaria's industrial corridor leads SME migration from legacy Avaya hardware to cloud-native platforms.
India
Manufacturing clusters in Pune and Chennai abandon legacy PBX maintenance for subscription-based unified communications as labor costs for on-premise support escalate. TRAI governs interconnection tariffs and quality-of-service benchmarks that set pricing floors for international traffic termination. Bengaluru's technology parks concentrate development centers for Opus codec optimization and bandwidth-constrained deployment tools.
Brazil
Logistics hubs in São Paulo and Santos adopt cost-sensitive hosted PBX solutions as legacy system maintenance burdens intensify. Anatel regulates asymmetric termination rates that compress margins on wholesale international traffic. The Manaus Free Trade Zone attracts regional headquarters for VoIP providers serving Latin American SME expansion.
Japan
Automotive supply chain procurement teams in Nagoya and Osaka centralize telephony spend while decentralizing collaboration tool selection. METI guidelines on data residency shape vendor certification requirements for enterprise deployments. Tokyo's financial district drives demand for immutable call recording with blockchain-verified timestamps aligned to MiFID II-equivalent standards.
Global Voip Software Market Competitive Environment
United States producers anchor the premium enterprise tier; European specialists hold compliance-driven mid-market positions. The vendor base splits between consolidated platform players with security-stack integration and fragmented regional providers with localized tariff optimization. Three archetypes dominate: hyperscale cloud-integrated suites, vertical-specialist compliance stacks, and API-first programmable voice platforms. M&A activity concentrates on authentication and analytics capabilities, while geographic expansion targets Southeast Asian SME markets.
Among United States-based platform providers, RingCentral, Cisco, and Zoom occupy positions across the enterprise spectrum. RingCentral exemplifies the cloud-native unified communications archetype with subscription-heavy revenue models. Cisco anchors the security-integrated premium tier through FedRAMP-certified infrastructure. Zoom represents the video-first bundling strategy that compresses standalone voice margins through freemium conversion mechanics.
| Leading Market Players |
|---|
| RingCentral |
| Cisco |
| Nextiva |
| Microsoft |
| Vonage |
| 8x8 |
| Dialpad |
| AVOXI |
| Zoom |
| Others |
Value Chain & Pricing Dynamics
Bandwidth pricing indices from Tier-1 internet exchanges cascade through VoIP provider cost structures, compressing margins on commodity voice minutes while enabling premium tiers for guaranteed-quality routing and compliance-certified infrastructure.
Pricing Analysis
Short lead-time provisioning commands 15-25% premiums over standard deployment cycles, while surplus cloud compute capacity trades at spot discounts. Three-tier pricing structure across premium, standard, and economy levels segments by SLA guarantees, geographic redundancy, and AI-enabled feature bundles. Pricing pressure stems from hyperscale cloud providers absorbing infrastructure costs to anchor platform ecosystems. SMEs exhibit highest price sensitivity, negotiating per-seat caps below $25 monthly, while financial trading floors accept 3-4x multiples for immutable call recording and sub-50 millisecond latency guarantees.
Supply Chain Analysis
Codec licensing and session border controller firmware rests on concentrated US, Israeli, and Irish intellectual property holders controlling G.729, Opus, and SRTP encryption standards. Compute infrastructure draws from Taiwan semiconductor foundries, South Korean memory fabricators, and US hyperscale data center operators. Single-source vulnerability concentrates in AWS, Azure, and GCP control of 70% of underlying cloud capacity. Distribution runs through direct enterprise sales teams for large accounts and value-added resellers serving SME segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native SIP architectures are displacing legacy PBX hardware, compressing replacement cycles from 7-10 year capex horizons to 12-24 month subscription migrations.
For Market Incumbents: Extend security-stack integration into FedRAMP and HIPAA-certified voice analytics to defend against API-first challengers eroding enterprise accounts. Acquire authentication specialists to satisfy STIR/SHAKEN mandates before 2025 enforcement deadlines. Vertical integration into edge data centers reduces latency-dependent churn in financial services verticals. For New Entrants and Emerging Players: Indonesia's manufacturing SMEs present the most penetrable white-space, with legacy PBX maintenance costs exceeding 40% of IT budgets and no incumbent cloud-native presence. Vietnam's logistics hubs offer parallel entry points through localized hosted PBX partnerships with domestic telecom resellers. API-first programmable voice positioning avoids head-to-head unified communications suite competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor compliance-stack specialists in Germany and France facing EU AI Act documentation burdens that favor scaled acquirers over standalone operators. Long-term viability hinges on recurring revenue ratios above 80% and vertical-specific certification moats. Watch FCC enforcement actions on STIR/SHAKEN compliance as inflection indicators for forced-replacement demand cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding voice APIs into Salesforce and ServiceNow workflows captures CRM-adjacent spend. |
| Acquisition of Specialist Firm | Voice biometrics vendors in Israel and Ireland add authentication layers for financial services. |
| Geographic Expansion | Localized data centers in Jakarta and Ho Chi Minh City satisfy Indonesia and Vietnam data residency requirements. |
| Product Launch | AI-enabled noise suppression softphones target healthcare triage and telehealth platforms. |
| Strategic Partnership | Hyperscaler co-sell agreements with AWS and Azure accelerate enterprise procurement cycles. |
Study Parameters
Multi-period observation of codec adoption rates, cloud migration timelines, and interconnection tariff movements anchored the trend analysis, supplemented by interviews with CTOs at financial services firms, IT procurement officers in German automotive supply chains, platform engineers at unified communications providers, and channel partners serving Southeast Asian SME markets. Secondary validation drew from FCC enforcement filings, TRAI tariff orders, ETSI standards documentation, SEC 10-K disclosures from listed providers, and hyperscaler capex reports. Bottom-up seat-count modeling and top-down revenue triangulation converged on segment-level estimates.
Segment-weighting applied deployment mode, organization size, vertical industry, and regional regulatory cluster as primary stratification dimensions across the analysis window. CAGRs derived from logistic diffusion curves fitted to cloud migration penetration data, adjusted for forced-replacement catalysts including STIR/SHAKEN mandates and PBX end-of-life announcements. Forecast inputs incorporated Opus codec bandwidth efficiency gains and AI-enabled feature attach rate assumptions.
Revisions become necessary when FCC enforcement timelines accelerate, EU AI Act audit requirements expand beyond high-risk classifications, or hyperscale cloud pricing wars compress independent provider margins below sustainable thresholds. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Real-Time Voice Changing Software Market
Software & Services
GCC Human Capital Management Software Market
Software & Services
Webcasting Software Market
Software & Services
Intelligent Enterprise Data Capture Software Market
Software & Services
Multiphysics Software Market
Software & Services
Global Ad Server Software Market
Software & Services
Employee Advocacy Software Market
Software & Services
Coaching Management Software Market
Software & Services
Family Law Software Market
Software & Services
Global Text to Speech (TTS) Software Market
Software & Services
Global Demand Planning Software Market
Software & Services
Performance Management Software Market
Software & Services
Remote Browser Market
Software & Services
Global SAP S-4HANA Application Market
Software & Services
Global Presentation Software Market
Software & Services
Global Furniture Manufacturing Software Market