
 App Development Software Market | 2026-2036
App Development Software Market Size, Share, and Industry Trends Forecast 2026-2036
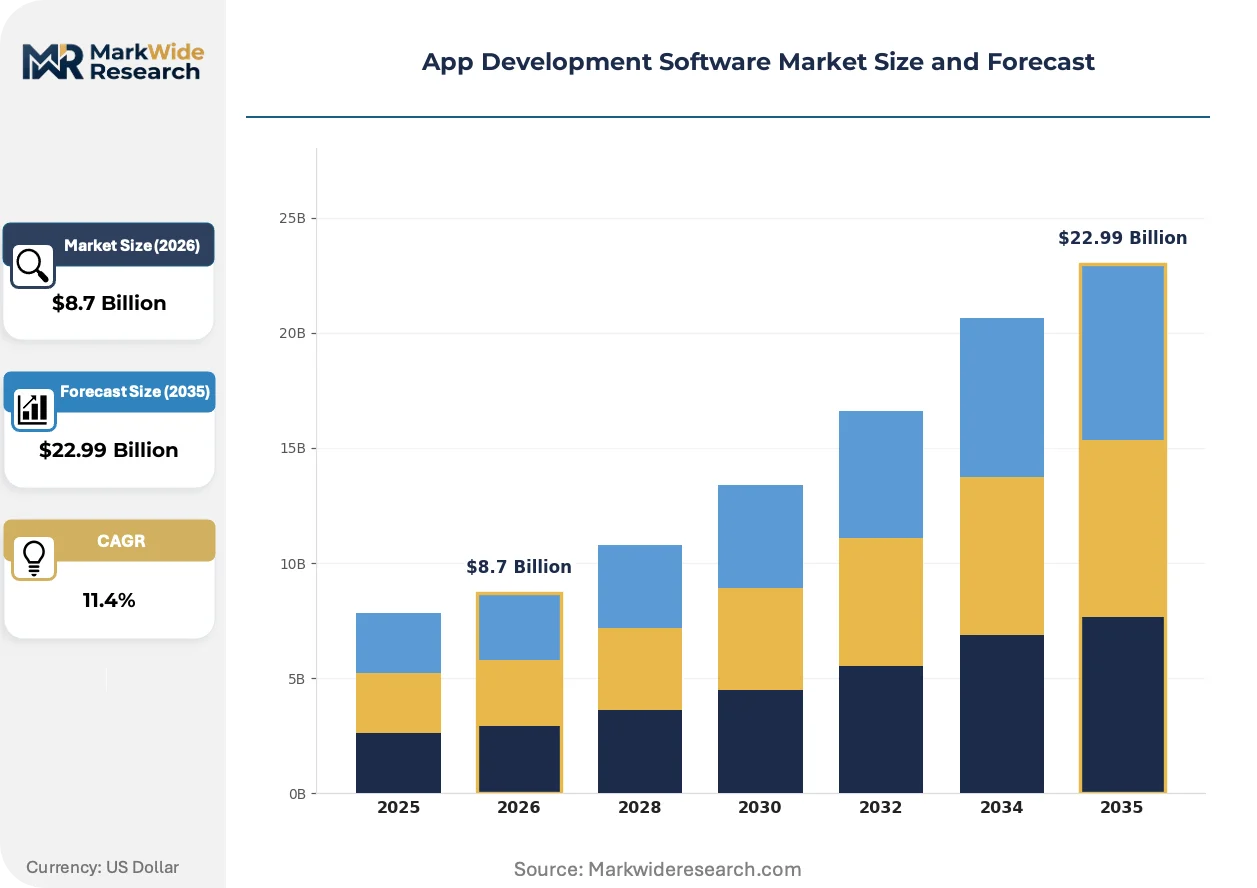
App Development Software Market Outlook
Developer talent scarcity is rotating enterprise priorities toward low-code and visual programming interfaces that reduce hand-coding requirements. Microsoft Corporation leverages its Azure ecosystem to anchor cloud-native development workflows across large organizations. Google LLC competes through Kubernetes-native tooling and progressive web app frameworks that simplify cross-platform delivery.
App development software encompasses integrated development environments, code editors, testing frameworks, and deployment pipelines that support the full software lifecycle from design to production release. These tools typically incorporate version control integration, automated testing protocols, and CI/CD orchestration to accelerate release velocity. Cloud-based deployment models now lead enterprise procurement decisions due to elastic scaling and reduced infrastructure overhead, while low-code technology segments attract the fastest expansion as business units bypass traditional IT gatekeeping. Native technology retains dominance in performance-sensitive applications such as gaming and financial trading platforms where direct hardware access remains non-negotiable.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements that constrain how development platforms process user information across borders. ISO 27001 and SOC 2 frameworks shape vendor qualification criteria for enterprises in regulated sectors such as healthcare and banking. Stakeholders must evaluate how emerging export controls on semiconductor design software and cloud infrastructure affect their toolchain portability before committing to platform-specific architectures.
Market Dynamics
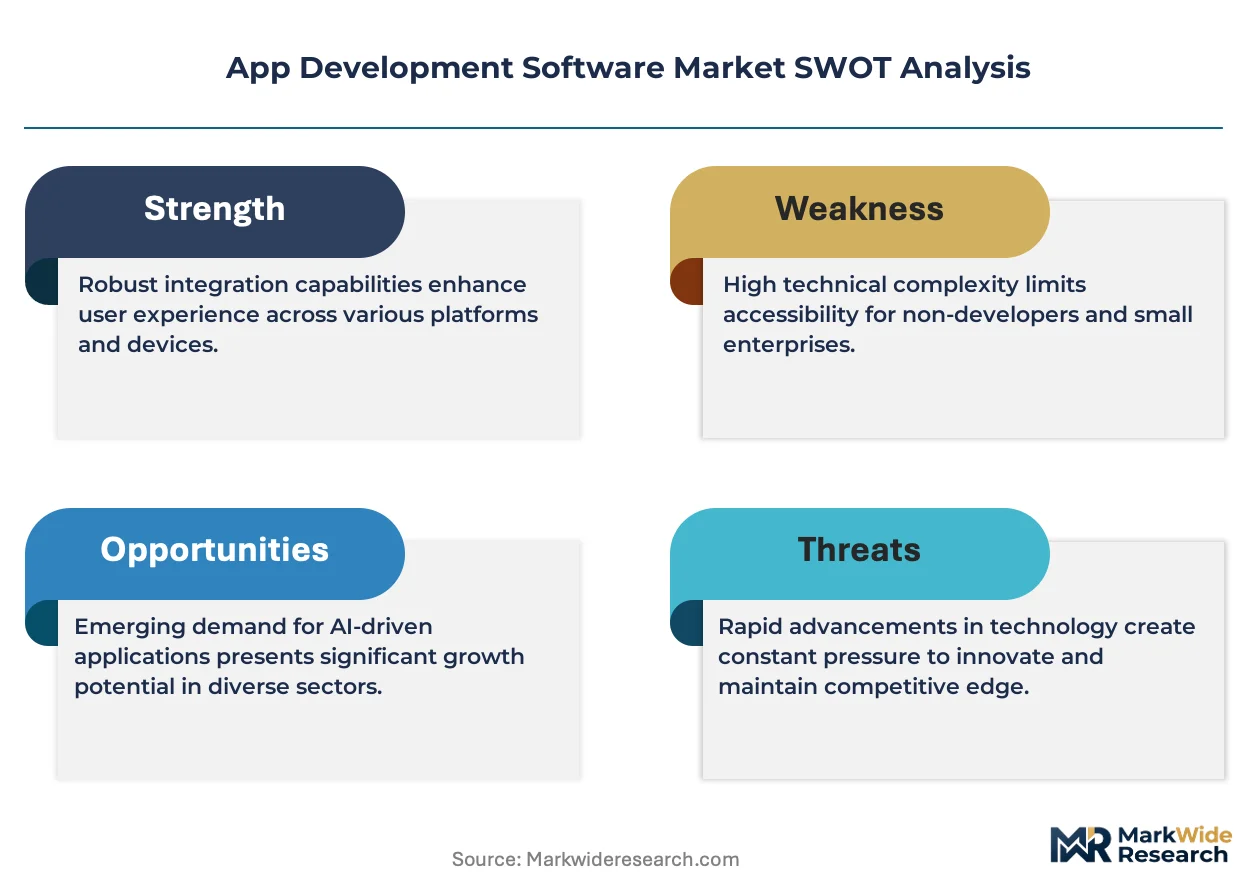
Low-code platforms are compressing traditional development cycles by abstracting hand-coding requirements, while GDPR and the EU AI Act impose data residency and algorithmic transparency mandates that reshape vendor qualification criteria across procurement workflows.
Growth Catalysts
- GDPR data residency mandates:European enterprises prioritize cloud-native platforms with EU-based data centers, accelerating regional infrastructure investments by hyperscale providers.
- Financial services automation:Banking and insurance sectors deploy low-code tools to accelerate compliance reporting and customer-facing application deployment.
- Kubernetes-native tooling convergence:Container orchestration standardization enables cross-platform portability that reduces vendor lock-in risks for enterprise IT departments.
Market Restraints
- Semiconductor export controls:Restrictions on advanced chip design software limit toolchain portability for organizations operating across US and Chinese jurisdictions.
- Cloud infrastructure concentration:Three hyperscale providers dominate compute availability, creating single-point-of-failure exposure for development pipeline continuity.
- Legacy system integration friction:Mainframe and on-premise ERP architectures resist API-native connectivity, forcing costly middleware layers.
Strategic Opportunities
- India's PLI scheme for IT hardware:Domestic manufacturing incentives attract development platform providers to establish localized cloud regions and support centers.
- Edge computing convergence with 5G:Low-latency application requirements drive demand for distributed development frameworks that compile to edge-native binaries.
- Healthcare interoperability mandates:HIPAA-adjacent certification requirements create premium positioning for platforms with pre-built compliance modules.
Industry Challenges
- Full-stack developer scarcity:Organizations struggle to hire personnel proficient in both legacy COBOL systems and modern microservices architectures.
- ISO 27001 certification timelines:Six-to-twelve month audit cycles delay market entry for SaaS development tools targeting regulated industries.
- Open-source license complexity:GPL and Apache license incompatibilities create legal exposure when integrating third-party libraries into commercial products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | App Development Software Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premises, Hybrid, SaaS Technology: Native, Cross-platform, Progressive Web App, Low-code End User: Startups, Enterprises, SMBs, Freelancers Service Type: Support, Maintenance, Consulting, Training |
| Companies Covered | Microsoft Corporation, IBM Corporation, Oracle Corporation, SAP SE, Google LLC, Salesforce, Inc., Zoho Corporation, HCL Technologies Ltd, Fujitsu Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
App Development Software Market Strategic Shifts
Artificial intelligence-assisted coding tools are rewriting productivity benchmarks across software engineering teams, compressing feature delivery timelines while introducing new governance requirements for generated code provenance and security validation.
Generative AI pair-programming assistants are supplanting traditional code completion and static analysis tools in enterprise development environments. Mid-market technology firms adopt these capabilities fastest, integrating them into CI/CD pipelines within three-to-six month procurement cycles. The technology is supplanting conventional quality assurance headcount ratios, enabling smaller engineering teams to maintain equivalent release velocity.
The EU AI Act's risk-based classification system imposes documentation and human oversight requirements on high-risk application categories including financial scoring and healthcare diagnostics. Development platforms must now embed explainability features and audit trail capabilities by default. Healthcare and banking sectors in Germany and France accelerate procurement of compliant toolchains ahead of enforcement deadlines.
Consumption-based pricing models displace traditional per-seat licensing across enterprise software procurement. IT departments negotiate usage-tier contracts that align costs with actual compilation and deployment activity rather than developer headcount. This shift is most visible among Series C and D technology companies in the United States optimizing burn rates against engineering team expansion.
App Development Software Market Segmentation
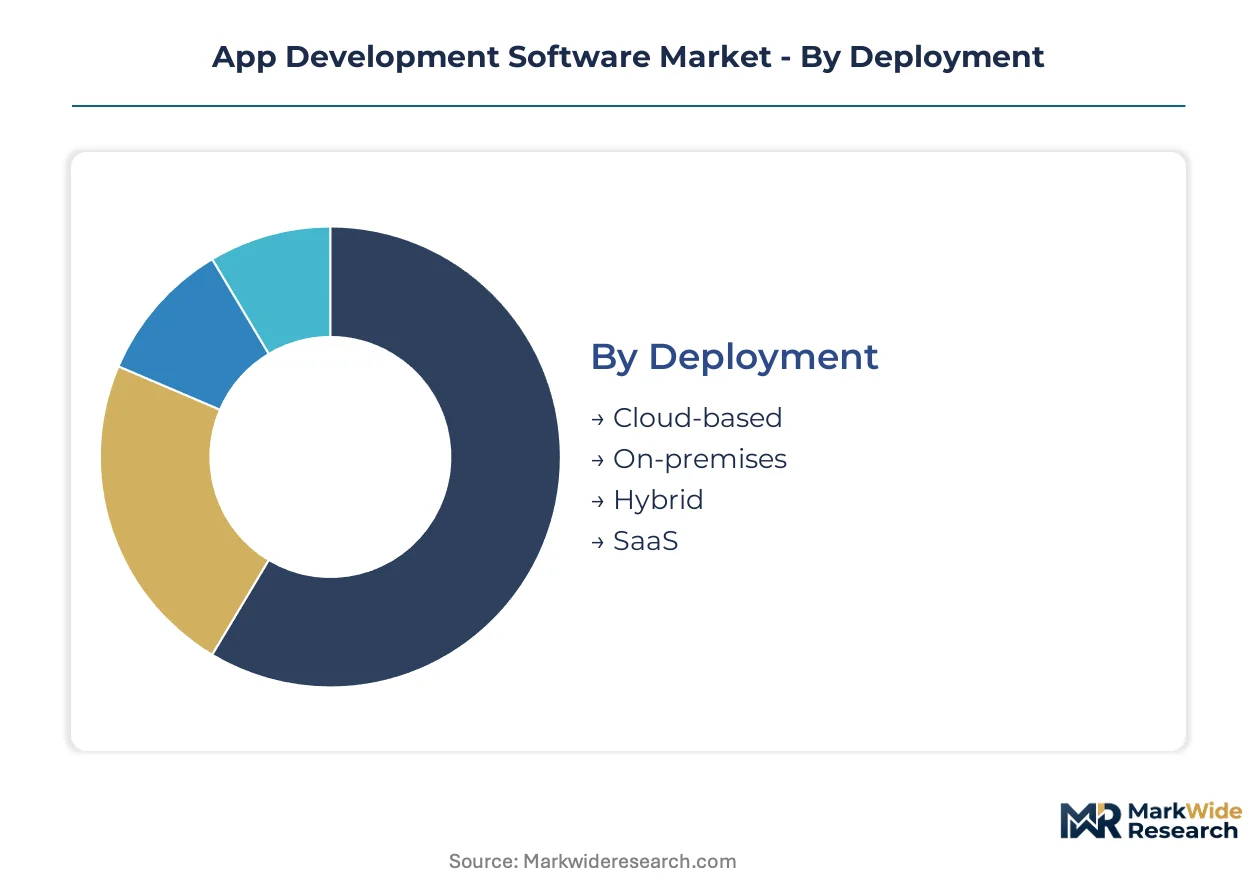
Segmentation in app development software reveals how procurement priorities diverge across infrastructure models, technical architectures, and buyer maturity levels. Understanding these fault lines enables vendors to align pricing structures with actual value delivery rather than generic seat-based models.
Deployment:
Substitution pressure intensifies as cloud-native platforms displace perpetual-license alternatives through consumption-based economics and elastic scaling capabilities.
- Cloud-based:Multi-tenant architectures with automatic scaling and pay-per-use metering dominate enterprise procurement cycles. United States technology firms concentrate demand here, driven by DevOps automation requirements and reduced capital expenditure burdens.
- SaaS:Browser-accessible development environments with zero local installation overhead attract mid-market buyers seeking immediate onboarding. European enterprises prioritize these deployments to satisfy GDPR data residency mandates through EU-region hosting options.
- Hybrid:Split architectures maintaining sensitive workloads on-premises while leveraging cloud burst capacity for compilation and testing pipelines.
- On-premises:Air-gapped installations serving defense contractors and financial institutions with strict data sovereignty requirements.
Cloud-based deployments retain volume leadership; SaaS holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium native tooling from mass-market abstraction layers that compress development labor requirements.
- Low-code:Visual drag-and-drop interfaces with pre-built connectors to enterprise systems. Banking and insurance sectors in Germany and France accelerate adoption ahead of EU AI Act compliance deadlines, using these platforms to embed audit trails and explainability features.
- Native:Platform-specific SDKs delivering direct hardware access for performance-critical applications. Gaming studios and high-frequency trading operations in the United States maintain demand here where microsecond latency remains non-negotiable.
- Cross-platform:Single-codebase compilation to multiple operating systems via frameworks like React Native and Flutter.
- Progressive Web App:Browser-based experiences with offline caching and push notification capabilities.
Native technology commands premium pricing; low-code is expanding most quickly across regulated industries.
End User:
Application complexity and procurement sophistication create distinct buyer archetypes with diverging support requirements and contract negotiation patterns.
- Enterprises:Fortune 500 technology departments with dedicated procurement teams negotiating enterprise-wide platform agreements. These buyers demand ISO 27001 certification, SOC 2 Type II attestation, and custom SLA terms spanning multiple geographic regions.
- Startups:Venture-backed technology companies prioritizing velocity over feature depth, typically adopting freemium tiers with rapid upgrade paths.
- SMBs:Regional businesses with limited IT staff seeking turnkey solutions with integrated hosting and maintenance.
- Freelancers:Individual contractors purchasing single-seat licenses for client project delivery.
Enterprises generate the highest contract values; startups show the fastest adoption velocity for emerging AI-assisted coding capabilities.
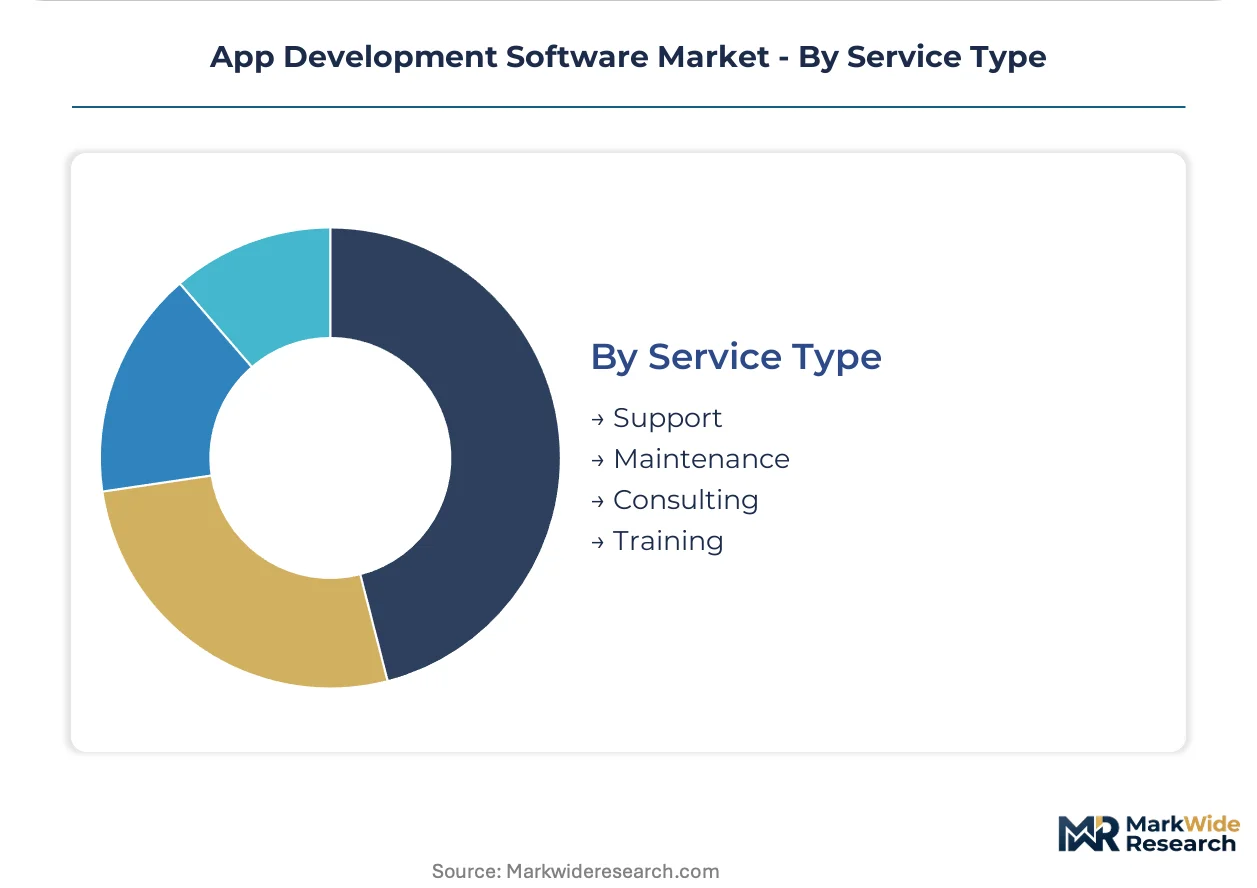
Service Type:
Margin structures vary dramatically between high-touch consulting engagements and automated support tiers with minimal human intervention.
- Consulting:Architecture design, migration planning, and custom integration development delivered by vendor professional services teams. Healthcare organizations in the United States concentrate demand here for HIPAA-aligned workflow implementations.
- Training:Certification programs and hands-on workshops accelerating platform proficiency. India's PLI scheme for IT hardware attracts vendors establishing localized training centers to support regional cloud region expansion.
- Support:Tiered response-time guarantees with escalating paths to engineering escalation.
- Maintenance:Patch management, security updates, and version migration services.
Consulting retains the highest margin contribution; training shows the strongest growth correlation with emerging market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement patterns diverge sharply by geography, with United States buyers prioritizing cloud-native velocity while European counterparts weight compliance architecture more heavily in vendor selection.
United States
Fortune 500 technology departments drive demand for Kubernetes-native tooling and AI-assisted coding platforms that compress release cycles. HIPAA and SEC cybersecurity disclosure rules shape vendor qualification for healthcare and financial services buyers. Silicon Valley and Seattle engineering clusters concentrate procurement authority for enterprise-wide platform agreements.
Germany
Automotive and industrial machinery sectors anchor demand for edge-native development frameworks supporting factory-floor deployment. GDPR and the EU AI Act impose documentation and human oversight requirements that filter vendor shortlists. Munich and Stuttgart industrial software clusters prioritize ISO 27001-certified platforms with embedded audit capabilities.
India
IT services exporters and domestic startups accelerate adoption of low-code platforms to bypass full-stack hiring bottlenecks. The PLI scheme for IT hardware attracts hyperscale providers to establish localized cloud regions and training infrastructure. Bangalore and Hyderabad technology corridors concentrate demand for SaaS development environments with zero on-premise footprint.
United Kingdom
Financial services and fintech sectors dominate procurement of compliance-embedded development tools ahead of EU AI Act alignment pressures. FCA operational resilience requirements extend to third-party software supply chains. London's Canary Wharf and Square Mile banking clusters drive premium-tier demand for SOC 2 Type II attested platforms.
Japan
Manufacturing conglomerates and automotive suppliers sustain demand for native SDKs delivering deterministic performance in embedded systems. METI data governance guidelines shape cross-border development workflow architectures. Tokyo and Nagoya industrial software clusters resist cloud-only deployment models for intellectual property-sensitive applications.
App Development Software Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with hyperscale cloud providers anchoring the upper layer through platform ecosystem lock-in. The middle tier fragments across vertical-specific low-code vendors and open-source tooling distributors. Two strategic archetypes dominate: ecosystem-integrated suites that bundle compute, storage, and development environments; and modular specialists selling point solutions for testing, deployment, or compliance automation. Competitive moves concentrate on M&A absorption of CI/CD tooling startups and geographic expansion through localized cloud region establishment.
Within the ecosystem-integrated tier, Microsoft Corporation and Google LLC occupy positions defined by their underlying infrastructure dominance, with Azure and Google Cloud anchoring development workflow gravity. Oracle Corporation represents the database-centric archetype extending into application lifecycle management. IBM Corporation sits within the enterprise services legacy, bridging mainframe integration requirements with modern container orchestration. Salesforce, Inc. exemplifies the SaaS-native platform model that bundles low-code capabilities with CRM data gravity. Zoho Corporation anchors the mid-market specialist position with integrated business application suites. These six entities collectively span the pricing and capability spectrum from freemium startup tiers to negotiated enterprise agreements exceeding eight figures annually.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Oracle Corporation |
| SAP SE |
| Google LLC |
| Salesforce, Inc. |
| Zoho Corporation |
| HCL Technologies Ltd |
| Fujitsu Ltd |
| Others |
Value Chain & Pricing Dynamics
Consumption-based metering contracts lock in multi-year platform access for United States enterprises while capping per-unit compilation costs, binding hyperscale providers to fixed infrastructure commitments that stabilize price visibility across volatile compute demand cycles.
Pricing Analysis
Long-term enterprise agreements with usage-tier floors dominate procurement for Fortune 500 technology departments, replacing per-seat licensing with metered consumption aligned to actual deployment activity. Price differentiation hinges on ISO 27001 certification tier and geographic hosting region, with EU data residency commanding premium positioning over standard multi-tenant deployments. Pricing pressure stems from mid-market buyers consolidating vendor relationships to reduce toolchain fragmentation. Startups exhibit highest price sensitivity, gravitating toward freemium tiers with rapid upgrade paths, while regulated healthcare and banking sectors absorb premium pricing for pre-built HIPAA and SOC 2 compliance modules.
Supply Chain Analysis
Just-in-time provisioning of cloud compute capacity dominates hyperscale operations, with strategic reserve commitments concentrated in United States, Germany, and India to satisfy data sovereignty requirements. The software supply chain draws from open-source repository ecosystems, proprietary API libraries, and third-party integration marketplaces. Single-source vulnerability concentrates around three hyperscale infrastructure providers controlling global compute availability. Distribution runs through direct enterprise sales teams for large accounts and self-service web portals for mid-market adoption, with channel partners handling localized implementation in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Professional services and training revenue layers expand faster than core platform licensing across the App Development Software Market, creating service-attach opportunities that deepen customer lifetime value beyond initial subscription contracts.
For Market Incumbents: Consolidate CI/CD tooling specialists through targeted acquisition to close feature gaps against modular competitors, while embedding explainability capabilities ahead of EU AI Act enforcement deadlines. Kubernetes-native workflow dominance represents the critical lever to defend against emerging low-code disruptors. Capacity expansion into India's PLI-supported cloud regions secures geographic diversification against concentration risk in United States and European data centers. For New Entrants and Emerging Players: ISO 27001 fast-track certification unlocks regulated industry procurement shortlists in Germany and France where audit timelines currently exclude smaller vendors. Healthcare interoperability mandates in the United States present the most penetrable white-space, with pre-built HIPAA compliance modules enabling rapid hospital system adoption. Channel partnerships with systems integrators accelerate enterprise credibility without direct sales infrastructure. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized compliance-automation platforms over generalist low-code providers. Long-term viability over the next decade hinges on AI-assisted coding differentiation and edge-native compilation capabilities. Acquisition targets should demonstrate embedded audit trail architectures and cross-cloud portability. The signal to watch is hyperscale provider M&A velocity in the CI/CD space as an inflection indicator for platform ecosystem lock-in intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure and Google Cloud ecosystem bundling anchors enterprise workflow gravity through unified billing. |
| Acquisition of Specialist Firm | CI/CD tooling absorption closes feature gaps against modular competitors in regulated verticals. |
| Geographic Expansion | India PLI scheme attracts localized cloud regions and training infrastructure to bypass talent scarcity. |
| Product Launch | Edge-native development frameworks capture 5G low-latency application demand in automotive sectors. |
| Strategic Partnership | Systems integrator alliances accelerate healthcare and banking procurement without direct sales overhead. |
Study Parameters
Desk research of hyperscaler capex disclosures, SEC filings, and EU regulatory databases preceded structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners across United States, Germany, and India technology corridors. Primary fieldwork captured deployment model preferences, compliance certification timelines, and vendor selection criteria in regulated industries. Secondary validation drew from open-source repository analytics, cloud infrastructure spend tracking, and enterprise software contract databases. Bottom-up segment sizing triangulated against top-down market boundary estimates.
Variance decomposition across deployment models, organization size tiers, vertical industry segments, integration complexity levels, and regional adoption patterns shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market boundary constraints. Forecast inputs incorporated low-code platform penetration curves in banking and insurance, Kubernetes-native tooling adoption velocity, and edge computing convergence timelines with 5G infrastructure rollout.
The analysis sits within stated boundaries; outcomes outside sustained hyperscale infrastructure investment levels, stable GDPR enforcement intensity, or continued venture capital availability for startup tooling vendors would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline adherence and enterprise cloud migration momentum. Revision becomes warranted when semiconductor export control expansion crosses thresholds that fragment cross-border development workflow architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Construction Suites Software Market
Software & Services
Programming Language Market
Software & Services
Photobooth Software Market
Software & Services
Global Neural Network Software Market
Software & Services
Feedback Management Software Market
Software & Services
Webcasting Software Market
Software & Services
Global Restaurant POS Software Market
Software & Services
Global Photogrammetry Software Market
Software & Services
Embedded Graphical User Interface (GUI) Development Software Market
Software & Services
North America Telecom Expense Management Services Software Market
Software & Services
Enterprise Resource Planning (ERP) Software Market
Software & Services
Bank Reconciliation Software Market
Software & Services
Lead-To-Account Matching and Routing Software Market
Software & Services
Car-Hailing Software Market
Software & Services
Global Membership Management Software Market
Software & Services
Global Desktop As a Service Market