
 Agile Application Life-Cycle Management Market | 2026-2036
Agile Application Life-Cycle Management Market Size, Share, and Industry Trends Forecast 2026-2036
Agile Application Life-Cycle Management Market Outlook
Modular unbundling of monolithic ALM suites into discrete DevOps tools, testing tools, and project management components is hardening buyer preference for best-of-breed procurement over single-vendor lock-in. Atlassian Corporation Plc leverages its Jira-Confluence integration layer to anchor team collaboration workflows across distributed engineering organizations. Microsoft Corporation competes through Azure DevOps and GitHub Enterprise, extending its cloud infrastructure dominance into the application delivery stack. IBM Corporation differentiates via Watsonx and hybrid cloud consulting, positioning its ALM services for regulated industries with complex compliance requirements.
Agile Application Life-Cycle Management encompasses the integrated tooling, processes, and governance frameworks that coordinate software planning, development, testing, deployment, and retirement in iterative release cycles, typically operating across containerized microservices architectures with automated CI/CD pipeline orchestration. Its primary commercial purpose is to compress release intervals while maintaining traceability, security auditability, and cross-functional alignment between product owners, developers, and operations teams. Cloud-based deployment now leads solution uptake among large enterprises seeking elastic infrastructure scaling, while DevOps tools capture the fastest expansion as organizations embed security scanning and compliance validation directly into build automation. Consulting services within the service type dimension command premium margins where implementation complexity involves legacy system migration and toolchain consolidation.
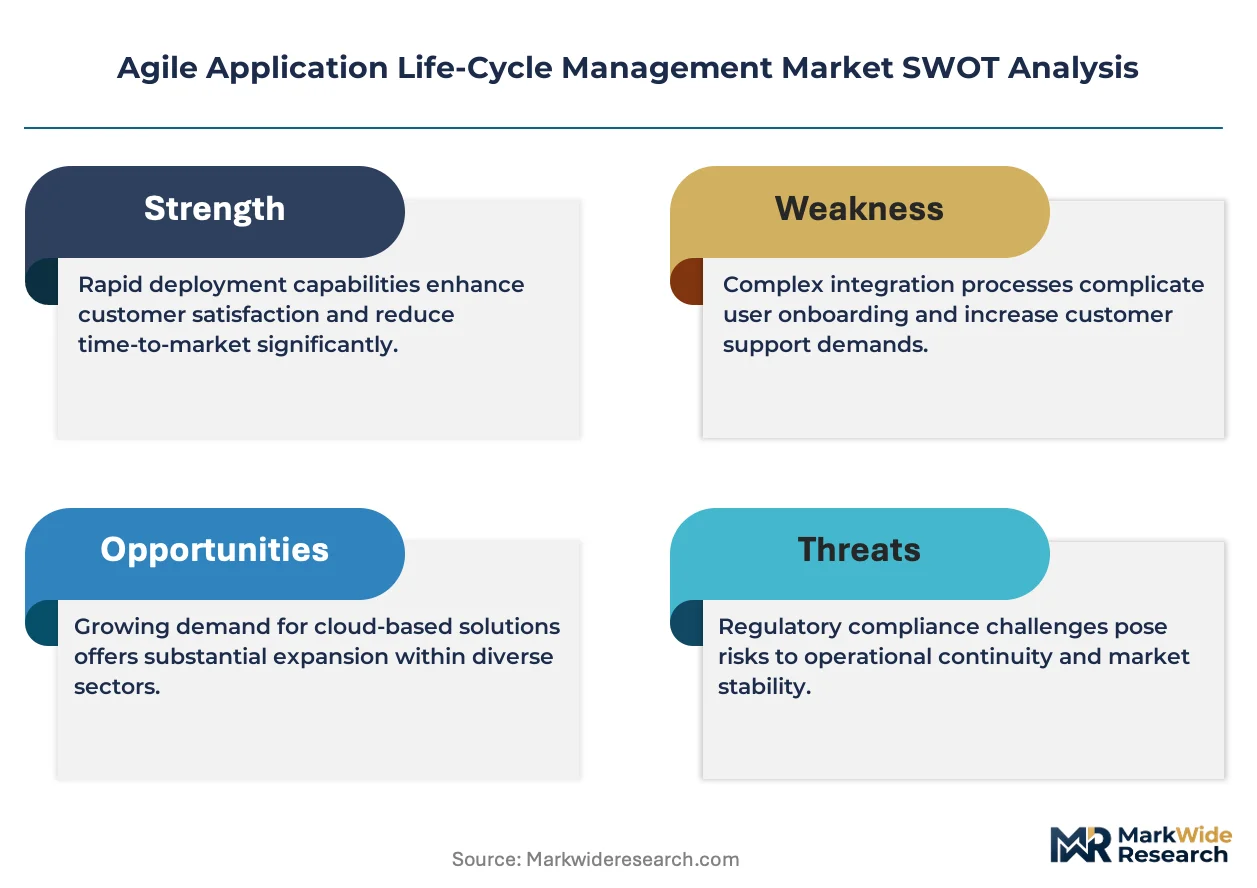
FDA 21 CFR Part 11 requirements for electronic records in medical device software, EU GDPR data protection impact assessments for citizen-facing applications, and SEC cybersecurity disclosure rules for publicly traded firms collectively shape ALM vendor roadmaps toward built-in audit trails and automated compliance documentation. ISO/IEC 27001 and NIST SP 800-53 further tighten security control expectations for government and educational institution procurement. Stakeholders must monitor how generative AI coding assistants integrate with existing ALM governance structures without fragmenting accountability or introducing unvetted dependency risks into production pipelines.
Market Dynamics
DevSecOps mandates from the EU AI Act and GDPR compliance requirements are pushing European enterprises toward automated governance tooling, compressing procurement cycles for integrated ALM platforms that embed security validation directly into CI/CD pipelines.
Growth Catalysts
- EU AI Act DevSecOps mandates:Automated governance tooling demand accelerates as European enterprises retrofit legacy stacks with compliance-embedded CI/CD pipelines.
- Containerized microservices architectures:Automotive OEMs in Germany and industrial conglomerates drive replacement demand for cloud-native ALM alternatives.
- Continuous integration pipeline expansion:Financial services firms compress software delivery cycles through embedded security scanning and automated compliance documentation.
Market Restraints
- Legacy system migration costs:Technical debt in mainframe-dependent enterprises creates prohibitive switching costs for full-stack ALM replacement.
- Toolchain fragmentation:Modular unbundling of monolithic suites into discrete DevOps, testing, and project management components complicates vendor consolidation.
- Skills scarcity in hybrid cloud DevOps:Shortage of engineers proficient in both legacy COBOL environments and Kubernetes orchestration slows implementation timelines.
Strategic Opportunities
- Generative AI coding assistant integration:ALM vendors can capture value by embedding governance structures around GitHub Copilot and Amazon CodeWhisperer outputs without fragmenting accountability.
- FDA 21 CFR Part 11 compliance automation:Medical device software manufacturers require built-in electronic records audit trails, creating premium-margin consulting services.
- SEC cybersecurity disclosure rules:Publicly traded firms in the United States need automated compliance documentation for material incident reporting, driving demand for traceability tooling.
Industry Challenges
- Dependency risk vetting in AI-assisted code:Generative AI outputs introduce unvetted open-source dependencies into production pipelines, requiring new governance checkpoints.
- Cross-functional alignment friction:Product owners, developers, and operations teams operate with misaligned incentive structures that iterative release cycles expose.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agile Application Life-Cycle Management Market |
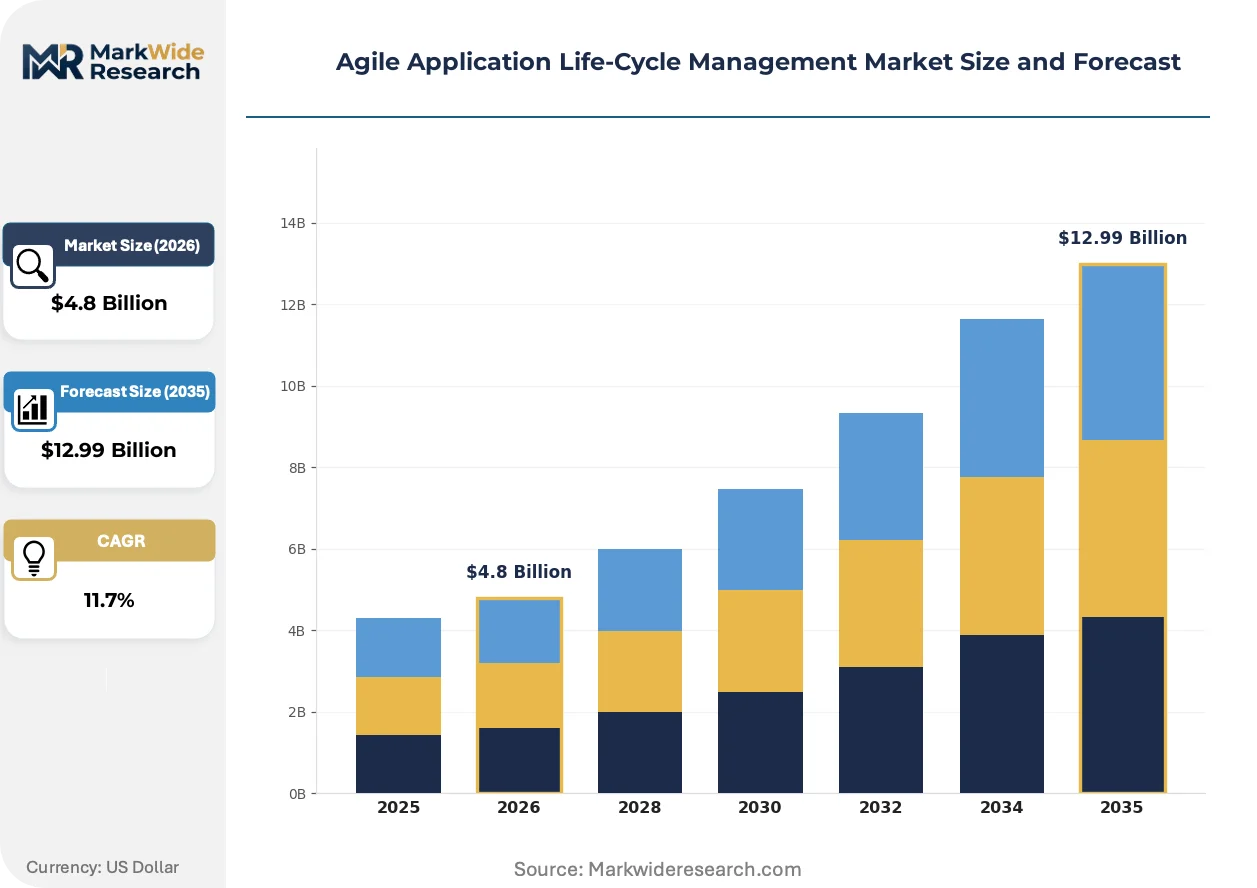
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services End User: SMEs, Large Enterprises, Government, Educational Institutions Solution: DevOps Tools, Testing Tools, Continuous Integration, Project Management Service Type: Consulting, Implementation, Support, Training |
| Companies Covered | Atlassian Corporation Plc, IBM Corporation, Microsoft Corporation, OpenText Corporation, Broadcom Inc., SAP SE, Oracle Corporation, Digital.ai Software, Inc., PTC Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agile Application Life-Cycle Management Market Strategic Shifts
Generative AI coding assistants are forcing ALM vendors to rearchitect governance layers, while regulatory mandates harden requirements for automated audit trails across regulated industries.
GitOps-based deployment automation is overtaking traditional imperative configuration management in enterprise Kubernetes environments. Platform engineering teams at financial services and automotive manufacturers are adopting declarative infrastructure-as-code at scale. This shift is overtaking ticket-driven change management by embedding approval workflows directly into version-controlled repository structures, compressing deployment intervals from days to minutes.
The EU AI Act's risk-based classification system for high-risk AI applications imposes mandatory logging and human oversight requirements on software supply chains. European medical device and automotive manufacturers must now maintain complete traceability from training data to production inference. Germany's automotive OEMs are responding by mandating MLOps pipeline certification from all tier-one software suppliers.
Outcome-based vendor engagement models are displacing perpetual license structures in enterprise ALM procurement. Large enterprises now demand consumption-aligned pricing tied to deployed application counts or pipeline execution volumes. This restructuring is most visible in the United States, where Fortune 500 technology procurement teams negotiate annual minimum commitments with burst capacity allowances rather than upfront capital commitments.
Agile Application Life-Cycle Management Market Segmentation
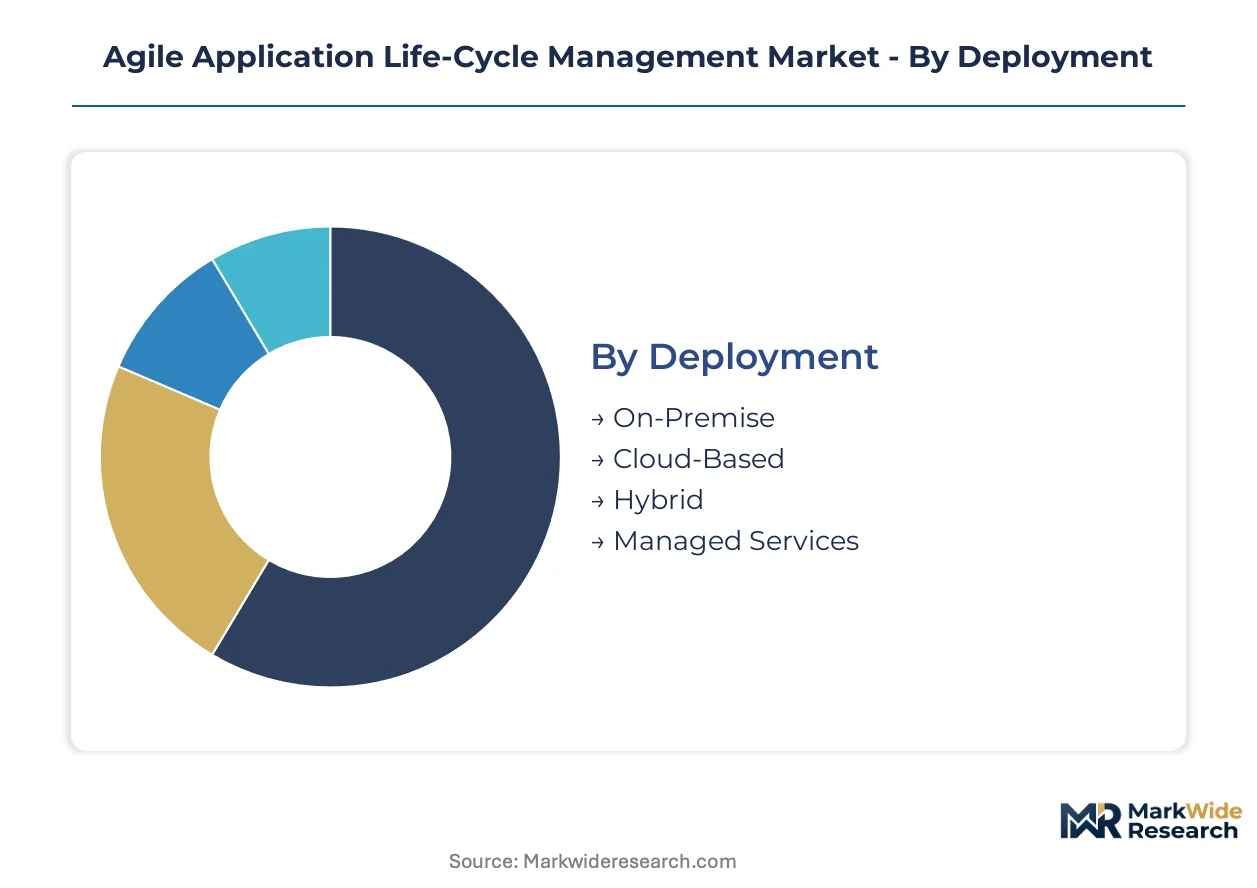
ALM procurement patterns diverge sharply across deployment topologies, organizational scale, and solution maturity. Vendors must align packaging and pricing to distinct technical debt profiles and compliance postures rather than pursuing uniform platform sales.
Deployment:
Supply concentration in cloud infrastructure is compressing delivery economics for elastic deployment options while legacy-bound sectors sustain on-premise demand.
- On-Premise:Air-gapped installations serve defense contractors and classified government facilities requiring physical data sovereignty. Financial services firms in Germany and Switzerland maintain on-premise ALM cores for GDPR data residency mandates despite higher operational overhead.
- Cloud-Based:Multi-tenant SaaS architectures dominate new procurement among mid-market enterprises seeking zero-infrastructure onboarding. Containerized delivery enables automotive OEMs in Stuttgart and Wolfsburg to scale CI/CD capacity elastically during model-year software pushes.
- Hybrid:Split configurations anchor sensitive code repositories on-premise while pushing build automation to public cloud. Industrial conglomerates retrofitting legacy ALM stacks favor this topology to phase migration risk.
- Managed Services:Third-party operated ALM stacks absorb operational burden for organizations lacking internal platform engineering depth. European healthcare providers under EU AI Act timelines increasingly outsource governance tooling maintenance.
Cloud-Based absorbs the bulk of installed capacity; Managed Services is expanding most quickly.
End User:
Procurement scale and compliance complexity stratify sharply across organizational types, with regulated enterprises paying premium multiples for audit-ready configurations.
- SMEs:Lean teams prioritize low-code ALM entry points with pre-integrated security scanning. German Mittelstand manufacturers adopt modular DevOps tools to avoid monolithic suite lock-in.
- Large Enterprises:Distributed engineering organizations demand federated governance across hundreds of microservices pipelines. Fortune 500 technology procurement teams negotiate consumption-aligned pricing with burst capacity allowances.
- Government:Federal agencies require FedRAMP-authorized or equivalent national security certifications. ISO/IEC 27001 and NIST SP 800-53 compliance gates dominate vendor selection.
- Educational Institutions:Research universities and technical colleges seek discounted academic licensing for software engineering curricula. Cloud-native ALM platforms enable remote collaboration across distributed campus networks.
Large Enterprises command the deepest vendor engagement; Government procurement is climbing the fastest amid cybersecurity disclosure mandates.
Solution:
Functional unbundling of monolithic suites is hardening buyer preference for discrete, interoperable components over single-vendor dependency.
- DevOps Tools:Pipeline orchestration, artifact management, and infrastructure-as-code automation form the technical backbone of modern ALM. Financial services firms embed security scanning directly into CI/CD workflows to compress delivery cycles.
- Testing Tools:Automated unit, integration, and performance validation suites reduce manual QA bottlenecks. Medical device manufacturers require FDA 21 CFR Part 11 compliant electronic records for all test execution logs.
- Continuous Integration:Build automation servers trigger compilation, static analysis, and artifact generation on every commit. GitOps-based deployment is overtaking imperative configuration management in Kubernetes environments.
- Project Management:Agile planning, backlog grooming, and sprint tracking coordinate cross-functional alignment. Jira-Confluence integration layers anchor team collaboration workflows across distributed engineering organizations.
DevOps Tools absorb the bulk of installed capacity; Continuous Integration is gaining share fastest as GitOps adoption accelerates.
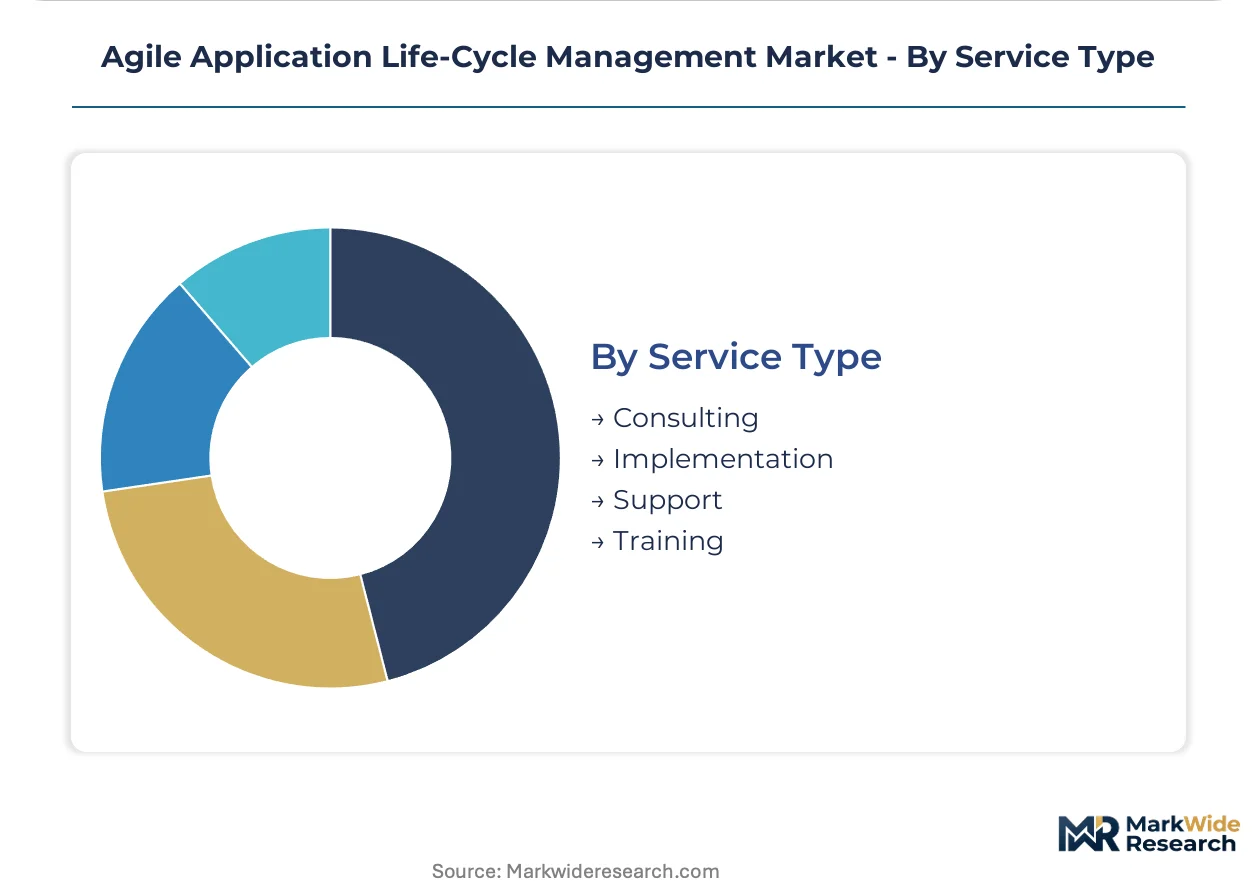
Service Type:
Margin concentration shifts toward high-touch consulting where implementation complexity involves toolchain consolidation and legacy migration.
- Consulting:Architecture assessment, vendor selection, and compliance roadmap development command premium day rates. IBM Corporation and similar firms position hybrid cloud consulting for regulated industries with complex requirements.
- Implementation:Technical deployment, data migration, and pipeline configuration absorb the bulk of professional services headcount. Mainframe-dependent enterprises face prohibitive switching costs for full-stack ALM replacement.
- Support:Tiered response commitments and dedicated technical account management sustain production operations. 24/7 coverage requirements from automotive OEMs drive premium pricing for mission-critical SLAs.
- Training:Certification programs and enablement workshops address skills scarcity in hybrid cloud DevOps. Kubernetes orchestration proficiency gaps slow implementation timelines for legacy COBOL environments.
Implementation absorbs the bulk of professional services capacity; Consulting is expanding most quickly amid compliance automation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software technology parks and innovation corridors concentrate Agile ALM demand in jurisdictions offering R&D tax credits and digital infrastructure subsidies. Regulatory pressure from data sovereignty laws and AI governance frameworks accelerates procurement in specific national markets. Vendor deployment strategies now calibrate to these geographic compliance gradients.
United States
SEC cybersecurity disclosure rules and FDA 21 CFR Part 11 mandates drive automated governance tooling procurement among publicly traded firms and medical device manufacturers. Federal agencies require FedRAMP-authorized ALM stacks for cloud migration timelines. Silicon Valley and Boston-Washington corridor enterprises anchor consumption-aligned pricing negotiations for DevOps platforms.
Germany
Automotive OEMs in Stuttgart and Wolfsburg retrofit legacy ALM stacks with cloud-native alternatives under EU AI Act risk-classification requirements. KBA safety standards and GDPR data residency mandates sustain hybrid deployment preferences. Industrial conglomerates in Bavaria and North Rhine-Westphalia phase migration risk through managed services absorption.
United Kingdom
Financial services firms in London's Square Mile embed continuous integration pipelines to compress software delivery cycles under FCA operational resilience requirements. ISO/IEC 27001 certification gates dominate vendor selection for government and educational procurement. Cambridge-Oxford tech corridor startups drive modular DevOps tool adoption over monolithic suite lock-in.
India
IT services exporters in Bangalore and Hyderabad scale platform engineering teams to serve North American and European compliance mandates. SEZ tax incentives and STPI infrastructure support concentrate ALM implementation capacity. Mumbai-Pune financial services hubs demand 24/7 mission-critical SLA coverage for distributed microservices orchestration.
Japan
Automotive and electronics manufacturers in Nagoya and Osaka prefectures adopt GitOps-based deployment automation for Kubernetes environments. METI digital transformation subsidies accelerate legacy mainframe migration timelines. Tokyo-based enterprises negotiate consumption-aligned pricing with burst capacity allowances for model-year software pushes.
Agile Application Life-Cycle Management Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered procurement segments. The vendor base clusters around three strategic archetypes: cloud infrastructure incumbents extending platform dominance, enterprise software legacy holders retrofitting compliance layers, and collaboration-tooling specialists anchoring team workflows. Consolidation pressure intensifies as outcome-based pricing models displace perpetual licenses. M&A activity targets CI/CD pipeline orchestration capabilities while strategic partnerships address hybrid cloud implementation complexity.
Within the cloud-platform tier, Microsoft Corporation and IBM Corporation exemplify infrastructure-to-application stack extension strategies. Atlassian Corporation Plc anchors the collaboration-centric archetype through workflow integration layers. These three entities represent distinct competitive vectors: cloud-native delivery, regulated-industry consulting depth, and distributed-team coordination tooling. Each occupies a position calibrated to specific buyer technical debt profiles and compliance postures rather than pursuing uniform platform dominance.
| Leading Market Players |
|---|
| Atlassian Corporation Plc |
| IBM Corporation |
| Microsoft Corporation |
| OpenText Corporation |
| Broadcom Inc. |
| SAP SE |
| Oracle Corporation |
| Digital.ai Software, Inc. |
| PTC Inc. |
| Others |
Value Chain & Pricing Dynamics
Kubernetes-certified platform engineers concentrated in Bangalore and Hyderabad feed labor-cost differentials into pricing-tier spreads, compressing margins for managed services while inflating premiums for EU AI Act-compliant configurations.
Pricing Analysis
Short lead-time premiums dominate ALM procurement, with automotive OEMs in Stuttgart paying surcharges for 48-hour CI/CD pipeline deployment against standard 30-day onboarding cycles. Subscription-based SaaS tiers anchor the dominant pricing model, with ISO 27001 certification grade and embedded security scanning modules driving price differentiation. Pricing pressure stems from outcome-based consumption models displacing perpetual licenses, compressing upfront revenue recognition. SMEs exhibit highest price sensitivity, while regulated healthcare manufacturers absorb premium multiples for FDA 21 CFR Part 11 audit-ready stacks.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscaler concentration in the United States, Germany, and India, with compute and storage capacity drawing from AWS, Azure, and GCP regional availability zones. Container orchestration components, security scanning engines, and compliance documentation APIs constitute critical input dependencies. Single-source vulnerability in GitHub Enterprise repository hosting creates systemic risk for distributed engineering organizations. Distribution runs through direct enterprise sales teams and systems integrator partnerships, with Accenture and similar firms absorbing implementation complexity for Fortune 500 accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Agile ALM market operates as a cost-of-compliance story, where EU AI Act DevSecOps mandates erect barrier-to-entry moats favoring vendors with pre-certified governance automation.
For Market Incumbents: Deepen hybrid cloud consulting capabilities to capture legacy migration spend from mainframe-dependent European manufacturers facing GDPR data residency requirements. Fortify against modular DevOps tool unbundling by embedding Jira-Confluence workflow layers into customer operating procedures. Prioritize FedRAMP authorization investment to defend federal agency procurement share against emerging cloud-native challengers. For New Entrants and Emerging Players: Begin with GitOps-based deployment automation for mid-market Kubernetes environments, where platform engineering skills scarcity slows incumbent response times. Target German Mittelstand manufacturers seeking modular alternatives to monolithic ALM suites, penetrating through channel partnerships with regional systems integrators. Lead with consumption-aligned pricing tied to pipeline execution volumes rather than seat-based licensing. For Investors and Strategic Acquirers: The window for entry favors CI/CD pipeline orchestration specialists with embedded security scanning capabilities, as regulatory mandates harden demand for automated governance. Long-term viability hinges on MLOps certification traction among automotive tier-one suppliers under EU AI Act timelines. Watch for FDA 21 CFR Part 11 compliance automation adoption rates in medical device software as inflection signal for premium-margin consulting services.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Atlassian's Jira-Confluence workflow layer anchors distributed engineering team coordination across automotive OEMs. |
| Acquisition of Specialist Firm | CI/CD pipeline orchestration capabilities command premium multiples as DevSecOps mandates compress procurement cycles. |
| Strategic Partnership | Microsoft Azure DevOps extends cloud infrastructure dominance into regulated healthcare via FDA-compliant audit trails. |
| Geographic Expansion | IBM Watsonx consulting penetration in Stuttgart automotive clusters captures EU AI Act implementation spend. |
| Product Launch | Generative AI governance layers around GitHub Copilot outputs address unvetted dependency risks in production pipelines. |
Study Parameters
SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory impact assessments formed the secondary backbone, cross-referenced with primary interviews involving platform engineering directors, IT procurement officers, compliance automation specialists, and channel integration partners. Bottom-up and top-down triangulation validated segment sizing across deployment topologies and solution maturity tiers.
Bottom-up modeling anchored volume estimates to pipeline execution metrics and seat-count expansions, while top-down analysis calibrated aggregate market boundaries against enterprise software spending patterns across the projection horizon. Segmentation dimensions included deployment model, organizational scale, vertical compliance posture, and regional regulatory framework intensity. CAGRs derived from historical adoption velocity and mandate-driven procurement acceleration, with GitOps penetration rates and MLOps certification timelines serving as industry-specific forecast inputs.
Underlying measurement precision varies by segment; cloud-based deployment and DevOps tools carry tighter precision than emerging managed services categories. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and hyperscaler capacity expansion. EU AI Act implementation delays, generative AI governance fragmentation, and legacy COBOL migration failures constitute specific risk factors warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
PCB Design Software Market
Software & Services
Global Handyman Software Market
Software & Services
Media Planning Software Market
Software & Services
Adaptive Learning Software Market
Software & Services
Global Script Writing Software Market
Software & Services
Global Demand Planning Software Market
Software & Services
Application Lifecycle Management (ALM) Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
Global Custom Software Development Services Market
Software & Services
Worldwide Persuasive Content Management Software Market
Software & Services
Engineering Software Market
Software & Services
Team Collaboration Tools Market
Software & Services
Global Product Management and Road Mapping Tool Market
Software & Services
Europe HR Payroll Software Market
Software & Services
Document-Centric Collaboration Software Market
Software & Services
Vending Software Market