
 Global Disk Imaging Software Market | 2026-2036
Global Disk Imaging Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Disk Imaging Software Market Foresight
North America is fragmenting as cloud infrastructure investments in the United States and Canada multiply data protection endpoints. Acronis leverages its hybrid cloud architecture to serve enterprises with cross-platform imaging needs. Veeam Software anchors its position through deep integration with VMware and Microsoft virtualization stacks. EaseUS competes aggressively on price in the small and medium business segment across Asia-Pacific markets.
Disk imaging software creates byte-for-byte copies of storage volumes, capturing operating systems, applications, and file structures into mountable image files typically compressed to 40-60% of original size for efficient transfer and restoration. The technology serves primary commercial purposes including bare-metal recovery, mass system deployment, and forensic preservation of digital evidence. Cloud-based deployment is capturing the fastest expansion as organizations abandon tape rotation and local vault maintenance. Disaster recovery solutions command premium pricing due to stringent recovery time objective requirements in financial services and healthcare. Managed service providers represent a concentrated demand pool, often bundling disk imaging with remote monitoring and patch management under recurring revenue contracts.
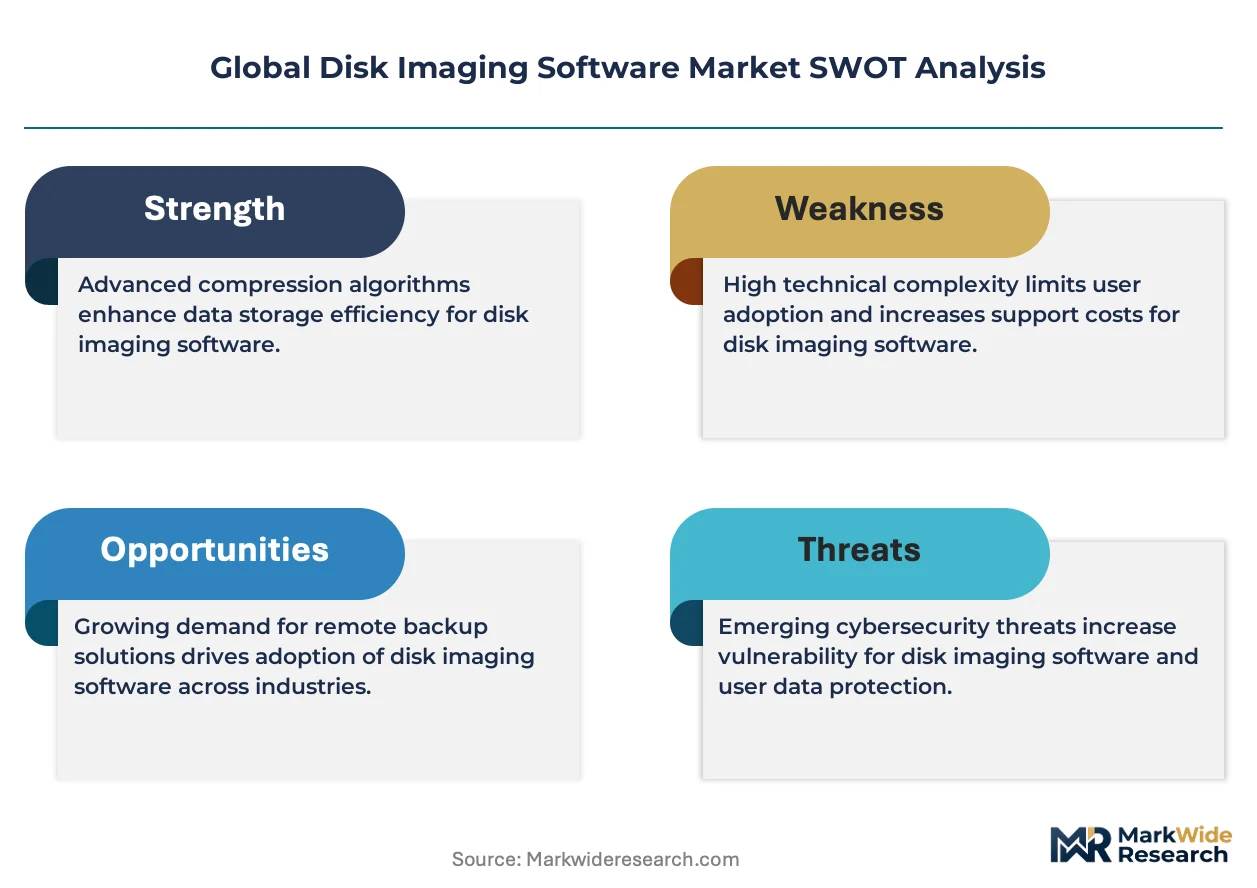
FDA 21 CFR Part 11 guidelines shape validation requirements for disk imaging used in pharmaceutical manufacturing environments, while HIPAA mandates encrypted backup procedures for healthcare entities handling protected health information. The EU GDPR's right to erasure creates tension with immutable backup policies, forcing vendors to engineer selective exclusion capabilities. Stakeholders must weigh the trade-off between cloud storage economics and data sovereignty obligations as jurisdictional fragmentation of privacy law intensifies.
Market Dynamics
Cloud-native immutable storage architectures are compressing traditional backup windows and forcing incumbents to rebuild core engines for object-store compatibility rather than file-system hierarchies.
Growth Catalysts
- Ransomware resilience mandates:Financial regulators in the United States and Germany now require demonstrable recovery capabilities, pushing banks and insurers toward immutable disk imaging with air-gapped verification.
- Edge computing proliferation:Manufacturing facilities in Japan and South Korea deploy disk imaging at plant-floor gateways to enable rapid restoration of industrial control systems without centralized IT intervention.
- GDPR Article 32:The EU's security of processing requirements compel organizations to maintain restorable copies with documented integrity checks, directly expanding encrypted imaging deployments across healthcare and legal sectors.
Market Restraints
- Cloud egress cost volatility:Amazon S3 and Azure Blob storage retrieval fees create unpredictable total cost of ownership for organizations maintaining multi-terabyte image repositories.
- Specialized engineering concentration:Advanced deduplication and compression algorithm development clusters in Israel and Estonia, creating acquisition risk and talent scarcity for vendors outside these hubs.
- Blockchain-based distributed storage:Decentralized alternatives threaten long-term growth of centralized disk imaging for archival use cases in cryptocurrency-adjacent enterprises.
Strategic Opportunities
- Brazilian healthcare digitization:ANVISA's electronic medical record requirements are expanding addressable market for HIPAA-compliant imaging solutions among private hospital networks.
- Container-native imaging:Kubernetes persistent volume snapshotting converges with traditional disk imaging, opening unified data protection platforms for DevOps-centric enterprises.
- India's data localization:The Reserve Bank of India's storage location mandates create captive demand for domestic cloud imaging infrastructure among payment processors and insurers.
Industry Challenges
- Immutable-recovery expertise gap:Enterprise IT teams lack personnel trained in forensic-grade image verification and chain-of-custody documentation required for regulatory audits.
- Legacy tape integration complexity:Hybrid environments force vendors to maintain parallel codebases for sequential media and random-access storage, fragmenting R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Disk Imaging Software Market |
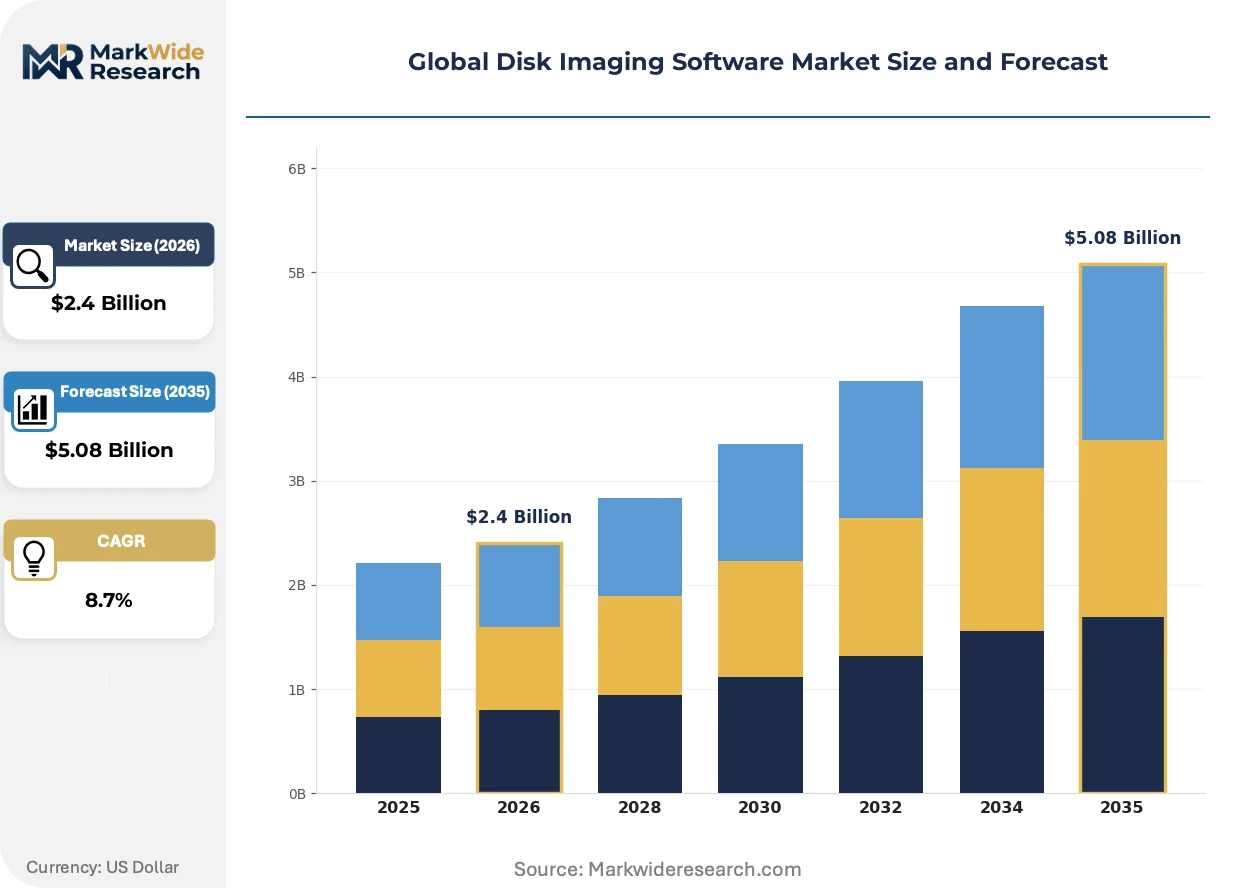
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Solution Type: Backup & Recovery, Cloning, Migration, Disaster Recovery, System Deployment Application: Enterprise Backup, Data Center Management, Endpoint Protection, IT Asset Management, Virtualization Support End User: IT Service Providers, Small & Medium Businesses, Large Enterprises, Managed Service Providers |
| Companies Covered | Symantec, AOMEI Technology, EaseUS, Macrium Software, Veeam Software, Acronis, Paragon Software Group, Clonezilla, LSoft Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Disk Imaging Software Market Shifts & Advancements
Artificial intelligence is penetrating backup operations through predictive failure detection and autonomous recovery orchestration, compressing the window between incident identification and system restoration.
Synthetic full imaging is rendering obsolete traditional incremental backup chains. This technology generates complete recovery points from existing image metadata without touching source systems. Managed service providers in Australia and Canada are adopting synthetic fulls to meet sub-hour recovery time objectives for SaaS-dependent clients. The approach is rendering obsolete weekly full backup windows that previously disrupted production environments.
The EU AI Act's risk classification framework is reshaping validation requirements for imaging software used in high-stakes automation. Vendors must now document algorithmic decision-making in recovery orchestration tools. Medical device manufacturers in Germany and pharmaceutical producers in Ireland face the steepest compliance burden, driving procurement toward vendors with pre-validated quality management systems.
Consumption-based licensing is displacing perpetual seat models across mid-market buyers. Channel partners in the United Kingdom and Netherlands now lead with metered storage pricing tied to actual protected terabytes rather than installed agent counts. This shift is most visible among professional services firms with seasonal workforce fluctuations, who resist upfront capital commitments for variable protection needs.
Global Disk Imaging Software Market Segmentation
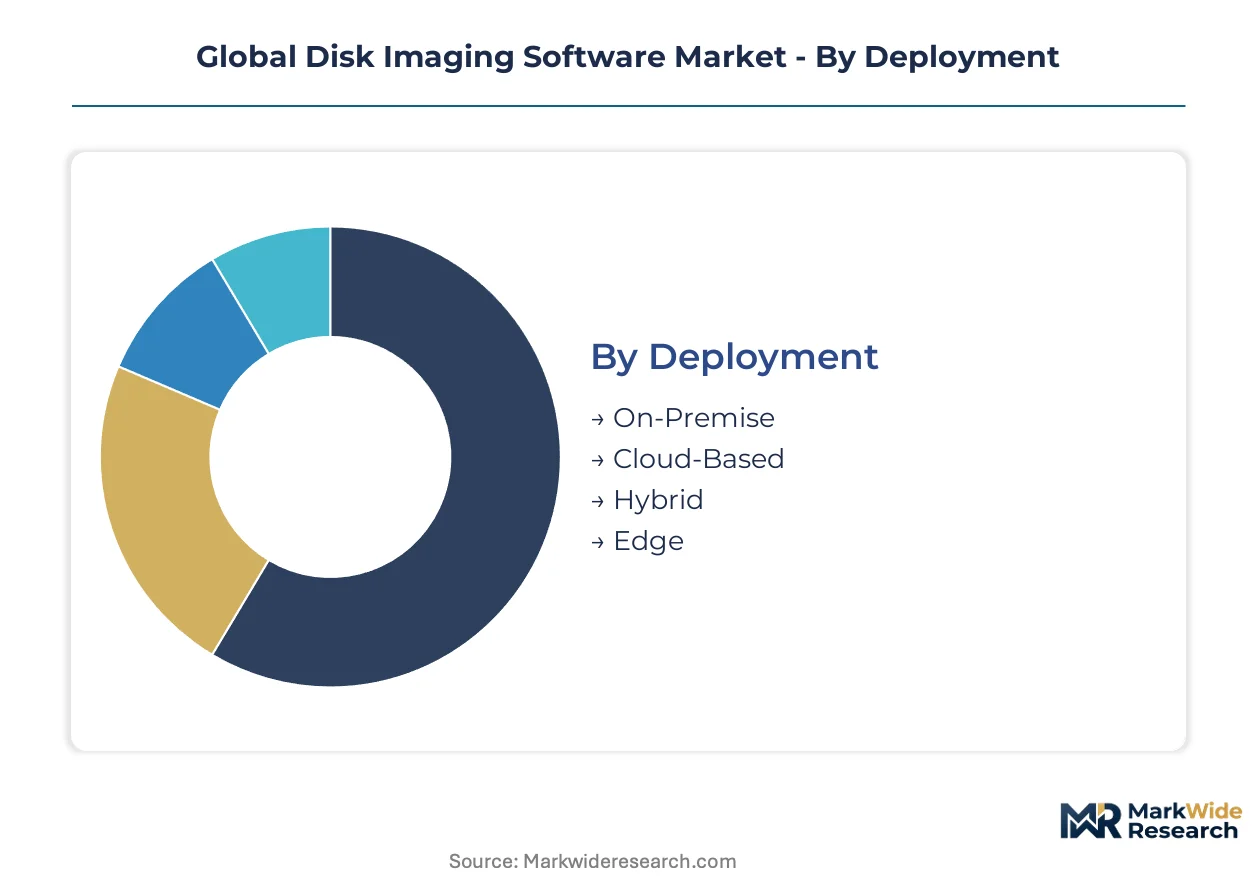
Disk imaging software serves heterogeneous operational contexts requiring distinct technical architectures and commercial models. Deployment patterns, solution configurations, application environments, and buyer categories each impose unique constraints on vendor product development and go-to-market strategy.
Deployment:
Cost tier determines infrastructure ownership obligations and ongoing operational overhead for disk imaging operations.
- Cloud-Based:Object-store architectures eliminate local vault maintenance and enable consumption-based scaling. Financial services firms in Singapore and healthcare networks in Germany prioritize this model to satisfy GDPR and MAS TRM guidelines without capital expenditure.
- Hybrid:Combines on-premise image generation with cloud tiering for long-term retention. Manufacturing conglomerates in Japan deploy hybrid configurations to protect industrial control systems while maintaining air-gapped verification copies.
- On-Premise:Retains full data sovereignty through dedicated hardware infrastructure. Defense contractors and classified government facilities mandate on-premise deployment for security clearance compliance.
- Edge:Distributes imaging capabilities to remote operational nodes with intermittent connectivity. Automotive test facilities and offshore energy platforms utilize edge deployment for autonomous recovery without centralized IT dependency.
On-Premise commands the established base. The steepest expansion runs through Cloud-Based.
Solution Type:
Application scope defines functional depth and integration complexity across disk imaging offerings.
- Disaster Recovery:Orchestrates complete system restoration with predefined recovery time objectives. Banks in the United States and insurers in Germany procure disaster recovery solutions to satisfy regulatory mandates for demonstrable business continuity capabilities.
- Backup & Recovery:Captures incremental changes with deduplication and compression for storage efficiency. Healthcare IT departments across France and the Netherlands deploy backup solutions to protect electronic patient records under GDPR Article 32 requirements.
- Cloning:Generates identical system replicas for hardware standardization and rapid provisioning. Educational institutions and call center operators leverage cloning for mass endpoint deployment.
- Migration:Facilitates cross-platform transfers between physical, virtual, and cloud environments. Enterprises undergoing data center consolidation utilize migration tools for workload portability.
- System Deployment:Automates operating system and application provisioning across bare-metal infrastructure. Retail chains and hospitality groups deploy system imaging for consistent point-of-sale configurations.
Backup & Recovery commands the established base. Disaster Recovery is climbing the fastest.
Application:
Customer maturity and operational criticality shape procurement specifications within each application domain.
- Enterprise Backup:Centralized protection for heterogeneous server and storage infrastructure. Multinational corporations in Switzerland and pharmaceutical manufacturers in Ireland implement enterprise backup to satisfy FDA 21 CFR Part 11 validation requirements.
- Endpoint Protection:Secures distributed laptops, workstations, and mobile devices against data loss. Professional services firms with remote workforces prioritize endpoint imaging for ransomware resilience.
- Data Center Management:Integrates imaging with infrastructure orchestration for virtualized environments. Hyperscale operators and colocation providers embed imaging within automated provisioning pipelines.
- IT Asset Management:Tracks hardware lifecycles and standardizes system configurations across equipment fleets. Government agencies and regulated utilities utilize imaging for compliance documentation.
- Virtualization Support:Optimizes image capture and restoration for VMware, Hyper-V, and KVM environments. Cloud service providers build virtualization-agnostic imaging into managed infrastructure offerings.
Enterprise Backup commands the established base. Endpoint Protection is gaining share fastest.
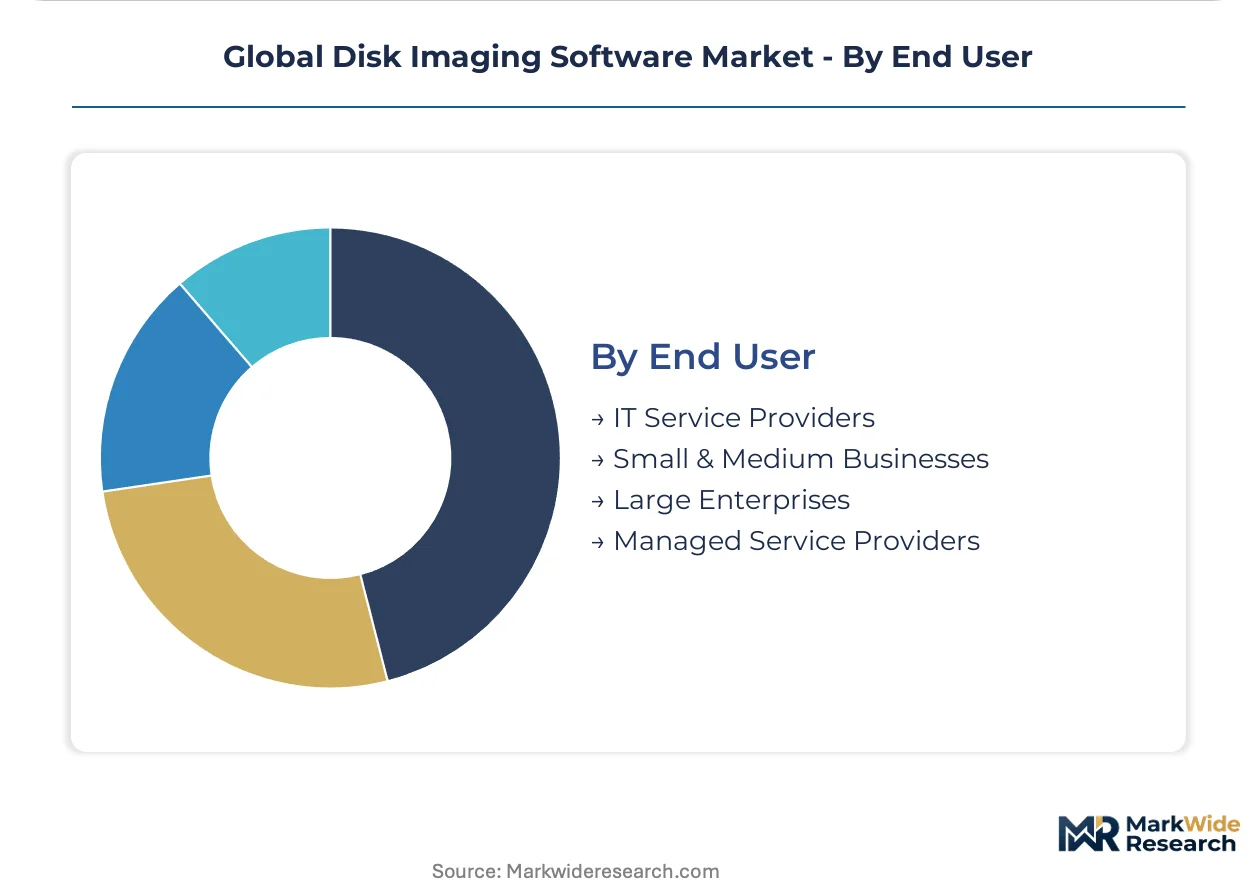
End User:
Organizational scale dictates pricing sensitivity, support requirements, and deployment complexity preferences.
- Large Enterprises:Demand centralized management, API integration, and dedicated account engineering. Automotive manufacturers in Germany and semiconductor fabricators in South Korea operate global imaging deployments across multi-site production networks.
- Managed Service Providers:Bundle imaging with remote monitoring under recurring revenue contracts. MSPs in Australia and Canada leverage white-label platforms to deliver differentiated data protection services.
- IT Service Providers:Resell and implement imaging solutions for client technology transformations. Systems integrators in the United Kingdom partner with vendors for project-based deployment revenue.
- Small & Medium Businesses:Prioritize simplified deployment and predictable subscription pricing. Professional services firms and regional healthcare clinics select cloud-native solutions minimizing internal IT overhead.
Large Enterprises commands the established base. Managed Service Providers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber optic cable systems landing at Virginia Beach and Bude anchor North America's data sovereignty calculus, while subsea routes through Singapore and Japan underpin Asia-Pacific cloud expansion. These infrastructure backbones determine where disk imaging workloads localize and how compliance architectures deploy.
United States
Financial services firms in New York and Chicago drive immutable backup procurement under SEC and state-level insurance commissioner mandates. HIPAA enforcement actions against hospital networks in Texas and Florida accelerate encrypted imaging adoption. The San Francisco Bay Area hyperscaler cluster shapes cloud-native architecture standards that propagate downstream.
Germany
Automotive manufacturers in Stuttgart and Munich operate multi-site production networks requiring forensic-grade system restoration. The EU AI Act and GDPR Article 32 compel pharmaceutical producers in Frankfurt-Rhine-Main to maintain auditable image chains. Industrial automation clusters in Bavaria deploy edge imaging at plant-floor gateways.
Japan
Semiconductor fabricators in Kyushu and automotive electronics suppliers in Nagoya mandate sub-hour recovery objectives for cleanroom control systems. METI guidelines on critical infrastructure protection shape imaging specifications. Manufacturing facilities in Osaka deploy autonomous restoration capabilities without centralized IT dependency.
India
Payment processors in Mumbai and Bengaluru face RBI data localization mandates requiring domestic cloud imaging infrastructure. IT service providers in Hyderabad and Pune bundle imaging within managed services contracts for global clients. Hospital networks in Delhi-NCR expand digitization under Ayushman Bharat requirements.
Brazil
Private hospital networks in São Paulo and Rio de Janeiro scale imaging deployments under ANVISA electronic medical record requirements. Financial institutions in São Paulo's Faria Lima district address central bank operational resilience guidelines. Manufacturing conglomerates in Minas Gerais protect industrial automation systems.
Global Disk Imaging Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with discrete imaging engines and compression algorithms. The vendor base separates into three functional layers: full-stack data protection platforms, virtualization-optimized tools, and open-source imaging utilities. Consolidation pressure runs through the middle tier as VMware and Microsoft deepen native snapshot capabilities. Strategic moves concentrate on API ecosystem expansion and consumption-based licensing transitions.
Among established platform vendors, Acronis and Veeam Software occupy positions spanning hybrid cloud deployment, while EaseUS exemplifies price-competitive positioning in small business segments. These three anchors represent divergent go-to-market architectures: Acronis with its Swiss-originated cross-platform emphasis, Veeam Software through deep Microsoft and VMware integration, and EaseUS competing on simplified deployment across Asia-Pacific markets. Specialist vendors including Macrium Software and AOMEI Technology sit within focused imaging-tool categories, with Paragon Software Group representing European-rooted partitioning and migration expertise.
| Leading Market Players |
|---|
| Symantec |
| AOMEI Technology |
| EaseUS |
| Macrium Software |
| Veeam Software |
| Acronis |
| Paragon Software Group |
| Clonezilla |
| LSoft Technologies |
| Others |
Supply & Pricing Matrix
Overcapacity in Eastern European development centers is compressing engineering labor rates and enabling aggressive SaaS pricing from vendors headquartered in Estonia and Poland. This utilization slack simultaneously drives cloud-native vendors toward consumption-based models while forcing traditional on-premise incumbents to absorb margin erosion or cede mid-market share.
Pricing Analysis
Volume-discount tiering structures separate enterprise MSP contracts from per-seat SMB subscriptions. Pricing stratifies across premium, standard, and economy tiers based on API integration depth and GDPR compliance certification. Cost compression in the standard tier is intensifying because EaseUS and AOMEI Technology are flooding Asia-Pacific markets with sub-dollar-per-agent offerings. Managed service providers demonstrate the lowest price sensitivity due to bundled margin recovery, while independent dental clinics and legal partnerships exhibit acute sensitivity to per-terabyte storage fees.
Supply Chain Analysis
Tariff exposure between the United States and China dominates component sourcing decisions for hardware-dependent imaging appliances. Algorithm development clusters in Israel, Estonia, and Ukraine supply core compression engines, while Taiwan and South Korea manufacture the NAND flash underlying immutable storage arrays. Supply chain risk centers on single-source vulnerability for advanced deduplication libraries. Distribution runs through hyperscaler marketplaces and direct vendor portals rather than traditional value-added reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Disk Imaging Software Market functions as a service-attach opportunity where recurring revenue from managed disaster recovery orchestration expands faster than perpetual license transactions. After-sales layers including forensic verification services and compliance audit documentation capture disproportionate margin expansion.
For Market Incumbents: Build switching-cost moats through deep API integration with VMware vSphere and Microsoft Azure Stack. Incumbents should acquire container-native snapshot specialists to neutralize Kubernetes-based substitution threats. Channel control through exclusive MSP certification programs anchors retention against price-aggressive challengers. For New Entrants and Emerging Players: Build out white-label platforms for Australian and Canadian managed service providers seeking differentiated data protection offerings. Underpenetrated Brazilian hospital networks under ANVISA digitization mandates represent the most accessible expansion corridor. A compliance-first go-to-market angle targeting GDPR Article 32 documentation gaps accelerates initial traction. For Investors and Strategic Acquirers: Capital is best deployed toward Israeli and Estonian algorithm shops with captive deduplication IP and demonstrated pharmaceutical validation workflows. Long-term viability hinges on object-store architecture migration completion before VMware and Microsoft fully internalize snapshot capabilities. The signal to watch is hyperscaler marketplace commission rate adjustments that would compress vendor economics.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep VMware and Microsoft embedding neutralizes hyperscaler substitution threats. |
| Acquisition of Specialist Firm | Container-native snapshot targets enable unified DevOps data protection platforms. |
| Geographic Expansion | Brazilian healthcare digitization under ANVISA creates captive demand for HIPAA-compliant solutions. |
| Product Launch | Synthetic full imaging renders weekly backup windows obsolete for MSP clients. |
| Strategic Partnership | Hyperscaler marketplace listings unlock consumption-based scaling for mid-market buyers. |
Research Methodology
Desk research of SEC filings, hyperscaler capex disclosures, and EU regulatory databases preceded structured interviews with CTOs, IT procurement officers, MSP platform engineers, and healthcare compliance leads. Primary fieldwork with channel partners and integration specialists validated secondary estimates of deployment model preferences. Bottom-up segment sizing triangulated against top-down IT spending forecasts across the analysis window.
Assumptions held fixed include prevailing GDPR enforcement intensity and VMware's continued third-party ecosystem openness, while cloud egress fee trajectories and ransomware incident frequency were varied across scenarios. The analytical framework modeled deployment model, organization size, vertical industry, and regional regulatory cluster dimensions. CAGRs derived from fitted adoption curves incorporating synthetic full imaging penetration and MSP contract renewal rates.
Practitioners should monitor EU AI Act implementation timelines and hyperscaler storage pricing volatility for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Virtual Data Room (VDR) Market
Software & Services
MEP Software Market
Software & Services
Web Development Market
Software & Services
Global Employee Engagement Software Market
Software & Services
Indonesia IT Services Market
Software & Services
Embedded Hypervisor Market
Software & Services
PCB Design Software Market
Software & Services
Telecom IT Services Market
Software & Services
Courier Software Market
Software & Services
Global User Interface Service Market
Software & Services
Software Market
Software & Services
Global Data Extraction Software Market
Software & Services
Global Software Quality Assurance Market
Software & Services
Global Product Lifecycle Management Software Market
Software & Services
Asia-Pacific IT Services Market
Software & Services
Know Your Customer Software Market