
 Global Data Warehouse Software Market | 2026-2036
Global Data Warehouse Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Warehouse Software Market Foresight
Consumption-based pricing and serverless leasing is fragmenting the competitive landscape for enterprise data infrastructure. Snowflake leverages its asset-light SaaS architecture to reduce upfront capital barriers for mid-market buyers. Amazon Redshift anchors its position through deep integration with AWS compute and storage services. Google BigQuery sustains competitive pressure with pay-per-query economics that shift cost risk from buyers to the vendor.
Data warehouse software comprises database management systems engineered for analytical query processing across petabyte-scale structured and semi-structured datasets, utilizing massively parallel processing architectures and columnar storage formats to deliver sub-second response times for complex business intelligence workloads. Cloud deployment now leads solution offering adoption as enterprises prioritize elastic scalability over fixed on-premises capacity, while data lake integration represents the fastest-growing segment as organizations seek unified analytics across warehouse and lakehouse environments. Real-time data processing commands premium margins due to specialized stream ingestion requirements and low-latency query demands from financial services and telecommunications sectors.
FCC guidelines on data localization and SEC record-keeping rules shape US demand for compliant retention architectures, while GDPR and the EU AI Act in Europe mandate explainability and audit trails that favor governed warehouse platforms with native lineage tracking. ISO 27001 and SOC 2 Type II certifications function as baseline market access requirements for vendor selection in regulated industries. Stakeholders must evaluate whether their current architecture supports emerging federated governance models before committing to multi-year platform contracts.
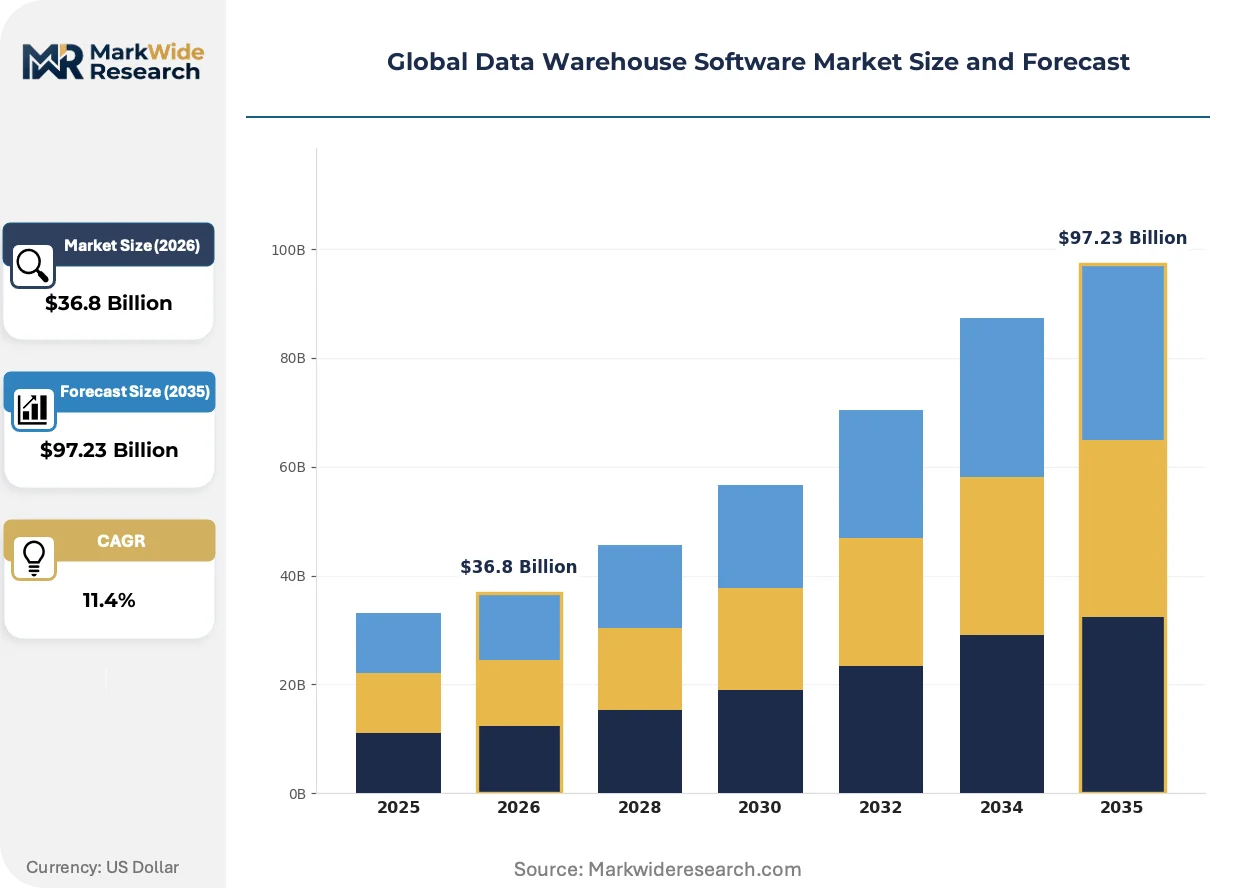
Market Dynamics
Consumption-based pricing models and serverless architectures are compressing procurement cycles for enterprise data infrastructure, forcing vendors to absorb capital risk while buyers prioritize elastic scalability over fixed capacity commitments.
Growth Catalysts
- EU AI Act explainability mandates:Financial services firms in Germany and France must maintain audit-ready data lineage, accelerating migration from on-premises systems to governed cloud warehouses with native provenance tracking.
- Real-time risk analytics:Securities trading desks require sub-second query response times for regulatory stress testing, driving premium adoption of stream-processing data warehouses.
- Hyperscaler infrastructure concentration:The United States hosts the densest concentration of cloud availability zones, reducing latency barriers for latency-sensitive analytical workloads.
Market Restraints
- Egress cost volatility:Cross-region data transfer fees from hyperscalers impose unpredictable operational expenditures that erode consumption-based pricing advantages.
- Specialized talent scarcity:Shortage of engineers proficient in massively parallel query optimization limits enterprise ability to extract value from petabyte-scale deployments.
- Hybrid integration friction:Legacy mainframe systems in banking retain decades of transactional history that resist seamless federation with cloud-native warehouse architectures.
Strategic Opportunities
- Lakehouse convergence:Unified analytics platforms that merge data warehouse governance with data lake flexibility are capturing workloads previously split across separate systems.
- India's digital public infrastructure:The country's account aggregator framework and open credit networks generate demand for compliant, scalable data repositories.
- ISO 27701 privacy extensions:Certification against this emerging standard opens regulated healthcare and insurance segments previously blocked by HIPAA and GDPR compliance gaps.
Industry Challenges
- Multi-cloud governance complexity:Enterprises operating across AWS, Azure, and GCP struggle to maintain consistent access controls and metadata synchronization without vendor lock-in.
- Stream-query optimization skill gaps:Shortage of practitioners capable of tuning low-latency analytical pipelines delays production deployment of real-time capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Warehouse Software Market |
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $97.23 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Multi-Cloud Solution Offering: Enterprise Data Warehouse, Cloud Data Warehouse, Data Lake Integration, Real-Time Data Processing Application: Customer Analytics, Risk Management, Supply Chain Optimization, Fraud Detection, Market Intelligence End User Industry: Telecommunications, Manufacturing, Energy & Utilities, Media & Entertainment, Government Agencies |
| Companies Covered | Snowflake, Amazon Redshift, Google BigQuery, Microsoft Azure Synapse Analytics, Databricks, Oracle Autonomous Data Warehouse, IBM Db2 Warehouse, Teradata, SAP Datasphere, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Warehouse Software Market Shifts & Advancements
Automated query optimization and separation of compute from storage architectures are compressing the traditional trade-off between analytical performance and infrastructure cost, enabling new consumption patterns previously economically infeasible.
Vectorized query execution engines leveraging SIMD instruction sets are rendering obsolete row-oriented processing architectures that dominated legacy data warehouse deployments. Telecommunications carriers processing call detail records at terabyte-per-hour velocities have adopted columnar formats universally. The structural consequence is collapsing price-performance ratios for complex analytical workloads.
The EU AI Act's risk-based classification system mandates that high-risk algorithmic decision systems maintain complete data provenance records. Deployments in automated credit scoring and insurance underwriting now require immutable audit trails from ingestion through model training. European financial institutions are prioritizing warehouse platforms with built-in lineage tracking over best-of-breed composable stacks.
Buyers are consolidating vendor relationships and demanding unified contracts spanning storage, compute, and governance layers rather than assembling point solutions. Systems integrators that previously specialized in ETL pipeline construction are repositioning as managed service providers for end-to-end warehouse operations. This consolidation pattern is most pronounced in United States federal contracting, where FedRAMP authorization requirements favor integrated platform bids over multi-vendor proposals.
Global Data Warehouse Software Market Segmentation
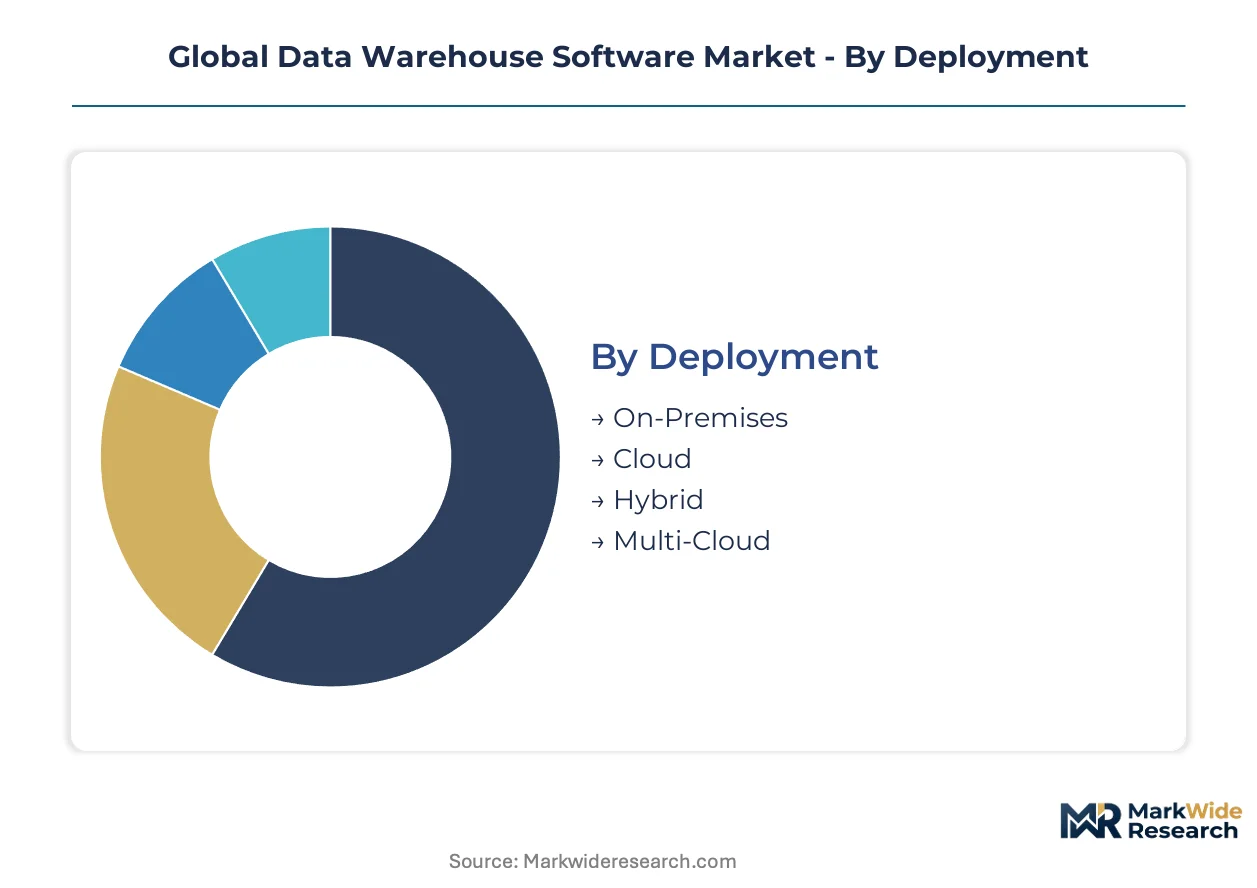
Segmentation reveals how procurement cycles, compliance burdens, and technical requirements fragment demand across deployment modes, solution architectures, and industry verticals. Understanding these divisions exposes where vendors absorb capital risk versus where buyers retain infrastructure control.
Deployment:
Replacement cycles vary dramatically: cloud deployments turn over in 18-24 month optimization sprints while on-premises systems persist for 7-10 year amortization horizons.
- Cloud:Fully managed SaaS architectures eliminate capital expenditure barriers through consumption-based metering. Financial services firms in the United States favor this model for elastic scaling around quarterly regulatory reporting spikes.
- On-Premises:Legacy installations retain sensitive workloads in controlled facilities with dedicated hardware stacks. German automotive manufacturers maintain these deployments for proprietary design data subject to strict domestic data residency statutes.
- Hybrid:Split architectures federate historical archives on-premises with burst compute in cloud environments. Energy utilities leverage this pattern for seasonal demand forecasting that spikes during extreme weather events.
- Multi-Cloud:Portability-focused deployments distribute workloads across AWS, Azure, and GCP to mitigate vendor concentration risk. Telecommunications carriers adopt this posture to satisfy divergent national data localization mandates across operating jurisdictions.
On-Premises deployments anchor the volume base while Cloud configurations gain share at the steepest rate.
Solution Offering:
Margin structures diverge sharply: integrated platforms command premium pricing while modular components compete on unit economics.
- Enterprise Data Warehouse:Monolithic systems deliver governed analytics through centralized schema management and batch-optimized processing. Japanese automotive suppliers rely on these platforms for consolidated financial reporting across global manufacturing footprints.
- Cloud Data Warehouse:Serverless architectures separate compute from storage to enable independent scaling of query concurrency and data volume. French insurance groups migrated to these solutions following EU AI Act audit trail requirements.
- Data Lake Integration:Unified lakehouse platforms merge structured warehouse governance with semi-structured data lake flexibility. Healthcare networks in the United States deploy these for longitudinal patient records spanning imaging archives and clinical trial databases.
- Real-Time Data Processing:Stream-native ingestion engines with sub-second query latency support continuous analytical pipelines. Securities exchanges in Singapore and Hong Kong require these capabilities for intraday risk monitoring and automated market surveillance.
Enterprise Data Warehouse retains the largest installed base though Real-Time Data Processing exhibits the steepest expansion trajectory.
Application:
Use case maturity determines implementation complexity: descriptive analytics deploy rapidly while predictive systems demand extended calibration periods.
- Customer Analytics:Behavioral segmentation and lifetime value modeling drive personalization engines across digital commerce platforms. Retail conglomerates in India leverage these tools for tiered loyalty program optimization.
- Risk Management:Regulatory stress testing and portfolio concentration analysis require immutable data lineage for audit defense. Basel III compliance deadlines in the European Union accelerate procurement of governed warehouse platforms.
- Supply Chain Optimization:Demand sensing and inventory positioning algorithms ingest external signals from weather patterns to shipping lane disruptions. German chemical manufacturers deploy these capabilities for raw material procurement hedging.
- Fraud Detection:Anomaly scoring across transaction streams demands millisecond-latency pattern recognition. Brazilian payment processors integrate these functions with central bank real-time settlement infrastructure.
- Market Intelligence:Competitive monitoring and pricing optimization synthesize external data feeds with internal sales records. South Korean consumer electronics firms operationalize these insights for product launch timing decisions.
Risk Management applications absorb the largest technology budgets while Fraud Detection climbs fastest among emerging use cases.
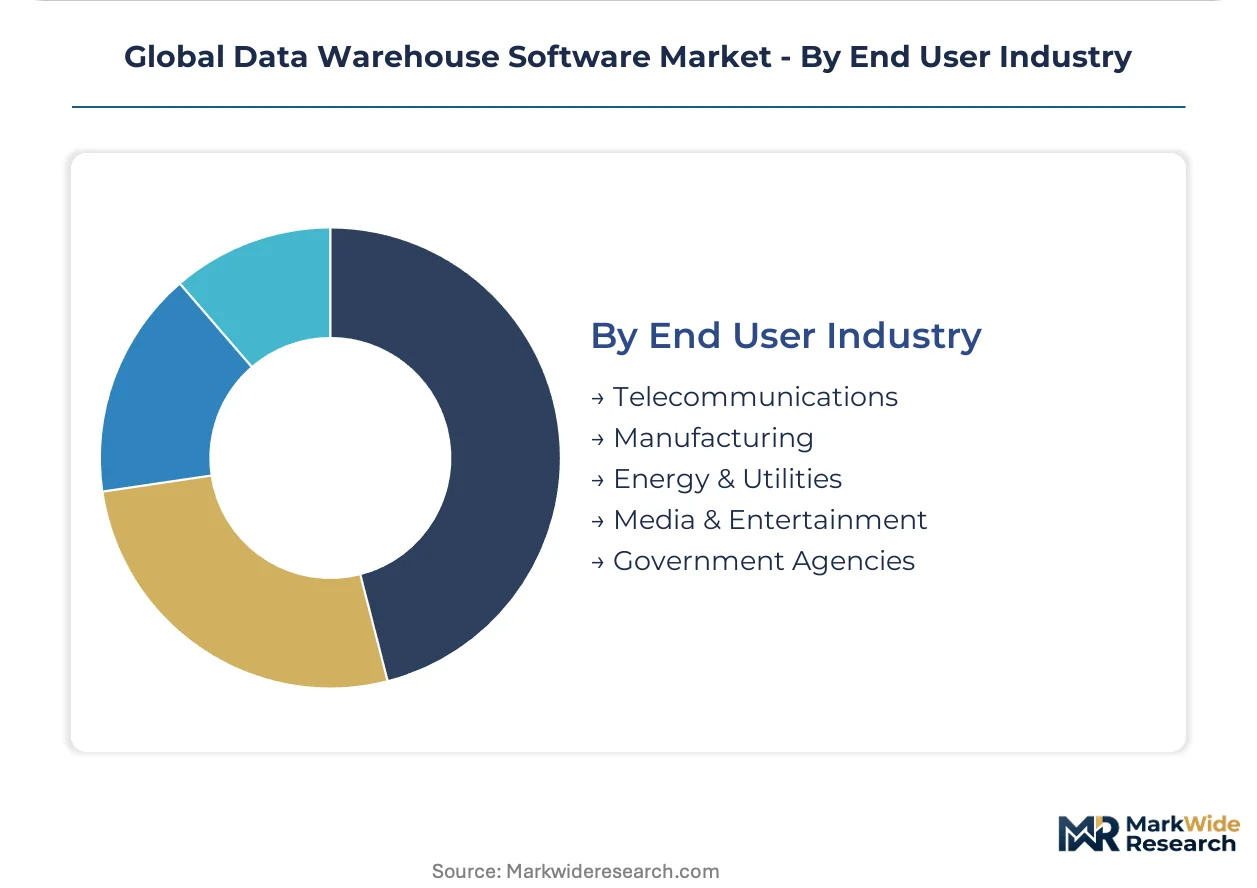
End User Industry:
Data gravity and regulatory exposure shape sector-specific requirements: regulated industries prioritize auditability while competitive sectors emphasize speed-to-insight.
- Telecommunications:Call detail record processing at terabyte-per-hour velocities demands columnar storage with vectorized execution. Network operators in the United States deploy these systems for Federal Communications Commission compliance reporting.
- Manufacturing:Industrial IoT sensor fusion and predictive maintenance analytics integrate operational technology with enterprise data. Japanese precision equipment makers use these platforms for quality defect root-cause analysis.
- Energy & Utilities:Smart meter data aggregation and grid stability forecasting require temporal database extensions. French nuclear operators maintain specialized deployments for reactor performance monitoring under ASN oversight.
- Media & Entertainment:Content recommendation engines and advertising yield optimization process high-velocity user interaction streams. Streaming platforms in South Korea and India scale these workloads during live sporting event broadcasts.
- Government Agencies:Citizen service analytics and fraud prevention across benefit programs demand FedRAMP-authorized cloud environments. United States federal agencies consolidate these procurements through GSA schedule vehicles.
Telecommunications carries the heaviest data volume while Government Agencies represent the most regulated procurement channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal data governance mandates and hyperscaler infrastructure density concentrate procurement cycles in the United States, while EU AI Act explainability requirements accelerate migration timelines across European financial centers. India's digital public infrastructure generates demand for compliant, scalable repositories.
United States
SEC record-keeping rules and FCC data localization guidelines shape demand for compliant retention architectures. FedRAMP authorization requirements favor integrated platform bids over multi-vendor proposals in federal contracting. Financial services firms in New York and Chicago deploy elastic cloud warehouses for quarterly regulatory reporting spikes.
Germany
Automotive manufacturers maintain on-premises deployments for proprietary design data subject to strict domestic data residency statutes. The EU AI Act mandates audit-ready data lineage for automated credit scoring systems. Frankfurt's financial district drives premium adoption of stream-processing warehouses for real-time risk analytics.
India
The account aggregator framework and open credit networks generate demand for compliant, scalable data repositories. RBI guidelines on data localization influence deployment architecture decisions. Mumbai and Bengaluru clusters concentrate fintech procurement of serverless warehouse platforms.
France
Insurance groups migrated to cloud data warehouses following EU AI Act audit trail requirements for algorithmic decision systems. ASN oversight of nuclear operators maintains specialized deployments for reactor performance monitoring. Paris-based banking groups prioritize platforms with built-in lineage tracking.
Singapore
Securities exchanges require sub-second query latency for intraday risk monitoring and automated market surveillance. The Monetary Authority of Singapore's technology risk management guidelines shape vendor selection criteria. Marina Bay financial district anchors regional procurement of real-time data processing capabilities.
Global Data Warehouse Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment modes and solution architectures. Hyperscaler-backed platforms leverage infrastructure integration to anchor enterprise relationships, while independent SaaS vendors reduce upfront capital barriers through consumption-based metering. Three archetypes dominate: hyperscaler-integrated suites, asset-light pure-plays, and legacy database incumbents repositioning toward cloud-native delivery. Competitive moves concentrate on strategic partnerships with systems integrators and portfolio diversification into lakehouse convergence.
Within the independent SaaS tier, Snowflake exemplifies the asset-light architecture reducing procurement friction for mid-market buyers. Among hyperscaler-integrated offerings, Amazon Web Services and Google Cloud anchor positions through compute-storage bundling and pay-per-query economics respectively. Microsoft occupies a position bridging enterprise software relationships with cloud infrastructure scale.
| Leading Market Players |
|---|
| Snowflake |
| Amazon Redshift |
| Google BigQuery |
| Microsoft Azure Synapse Analytics |
| Databricks |
| Oracle Autonomous Data Warehouse |
| IBM Db2 Warehouse |
| Teradata |
| SAP Datasphere |
| Others |
Supply & Pricing Matrix
Seattle's hyperscaler infrastructure cluster anchors global capacity for cloud data warehouse platforms, concentrating compute-storage bundling power among three dominant providers and compressing margins for independent SaaS vendors competing on consumption-based metering.
Pricing Analysis
Certification level creates the primary spread between FedRAMP-authorized federal tiers and standard commercial deployments, with SOC 2 Type II and ISO 27701 privacy extensions commanding substantial premiums in regulated healthcare and insurance segments. Consumption-based SaaS metering dominates enterprise procurement, though egress cost volatility from cross-region data transfers erodes the consumption model's predictability. Mid-market buyers exhibit acute price sensitivity to upfront capital barriers, while financial services firms prioritize audit-ready lineage over unit economics.
Supply Chain Analysis
Export-control restrictions on advanced semiconductors and AI training hardware limit flows from Taiwan and South Korea to Chinese cloud providers, reshaping regional capacity deployment strategies. The software supply chain draws from concentrated engineering talent pools in the United States, India, and Ireland, with specialized query optimization expertise remaining scarce. Single-source vulnerability in vectorized execution engine licensing creates dependency risk. Distribution runs through hyperscaler marketplaces and systems integrator channels, with GSA schedule vehicles dominating United States federal procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data warehouse software exhibits durable defensive moats rooted in switching costs, as petabyte-scale data gravity and query optimization investments embed enterprise customers in multi-year platform commitments that resist displacement.
For Market Incumbents: Build switching-cost moats through deeper integration with legacy mainframe systems in banking, where decades of transactional history resist cloud-native federation. Expand FedRAMP authorization coverage to capture United States federal consolidation trends. Invest in stream-query optimization tooling to address the talent scarcity limiting real-time deployment velocity.
For New Entrants and Emerging Players: India's account aggregator framework and open credit networks represent the most penetrable entry point for compliant, scalable repository deployments. Target mid-market fintech clusters in Mumbai and Bengaluru with serverless architectures that reduce upfront capital barriers. Pursue ISO 27701 certification to unlock healthcare and insurance segments blocked by HIPAA and GDPR compliance gaps.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors lakehouse convergence platforms that merge warehouse governance with data lake flexibility. Five-to-ten year viability hinges on federated governance capabilities across multi-cloud deployments. Monitor EU AI Act enforcement patterns as the inflection signal for explainability-mandated procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep AWS compute-storage bundling anchors Amazon Redshift's enterprise relationships against independent SaaS competitors. |
| Strategic Partnership | Snowflake's systems integrator alliances reposition channel partners as managed service providers for end-to-end operations. |
| Geographic Expansion | India's digital public infrastructure generates demand for RBI-compliant, scalable data repositories in Mumbai fintech clusters. |
| Product Launch | Real-time stream-native ingestion engines capture securities exchange workloads in Singapore's Marina Bay financial district. |
| Acquisition of Specialist Firm | Vectorized query execution capabilities address the skill gaps delaying production deployment of low-latency analytical pipelines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CTOs, IT procurement officers, platform engineers, and systems integrator channel partners. Secondary validation drew from SEC filings, hyperscaler capex disclosures, FedRAMP authorization databases, and EU regulatory implementation guidance. Bottom-up deployment estimates triangulated against top-down infrastructure spending patterns across cloud availability zones.
Calibration anchored historical adoption curves against elastic scaling behavior during quarterly regulatory reporting spikes. Segmentation dimensions spanned deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating EU AI Act compliance deadlines and India's account aggregator framework expansion. Model inputs included hyperscaler infrastructure buildout schedules and financial services real-time analytics procurement velocity.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting enterprise capital expenditure cycles would shift the trajectory. Forecasts reflect assumptions on regulatory enforcement intensity and talent pipeline expansion. Material shifts in export-control regimes governing semiconductor hardware flows would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Labeling Software Market
Software & Services
Customer Advocacy Software Market
Software & Services
General Ledger Accounting Software Market
Software & Services
United States Donation Management Software Market
Software & Services
3D Animation Software Market
Software & Services
Exploration and Production (E&P) Software Market
Software & Services
Resonator Design Software Market
Software & Services
Geophysical Software Service Market
Software & Services
Lighting Control Software Market
Software & Services
Shift Planning Software Market
Software & Services
APAC Interior Design Software Market
Software & Services
Global Catalog Management Systems Market
Software & Services
LTFS Copy Software Market
Software & Services
Global Affiliate Software Market
Software & Services
Cloud Backup and Recovery Software Market
Software & Services
Vending Software Market