
 Virtual Reality (VR) Simulator Market | 2026-2036
Virtual Reality (VR) Simulator Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Reality (VR) Simulator Market Analytics
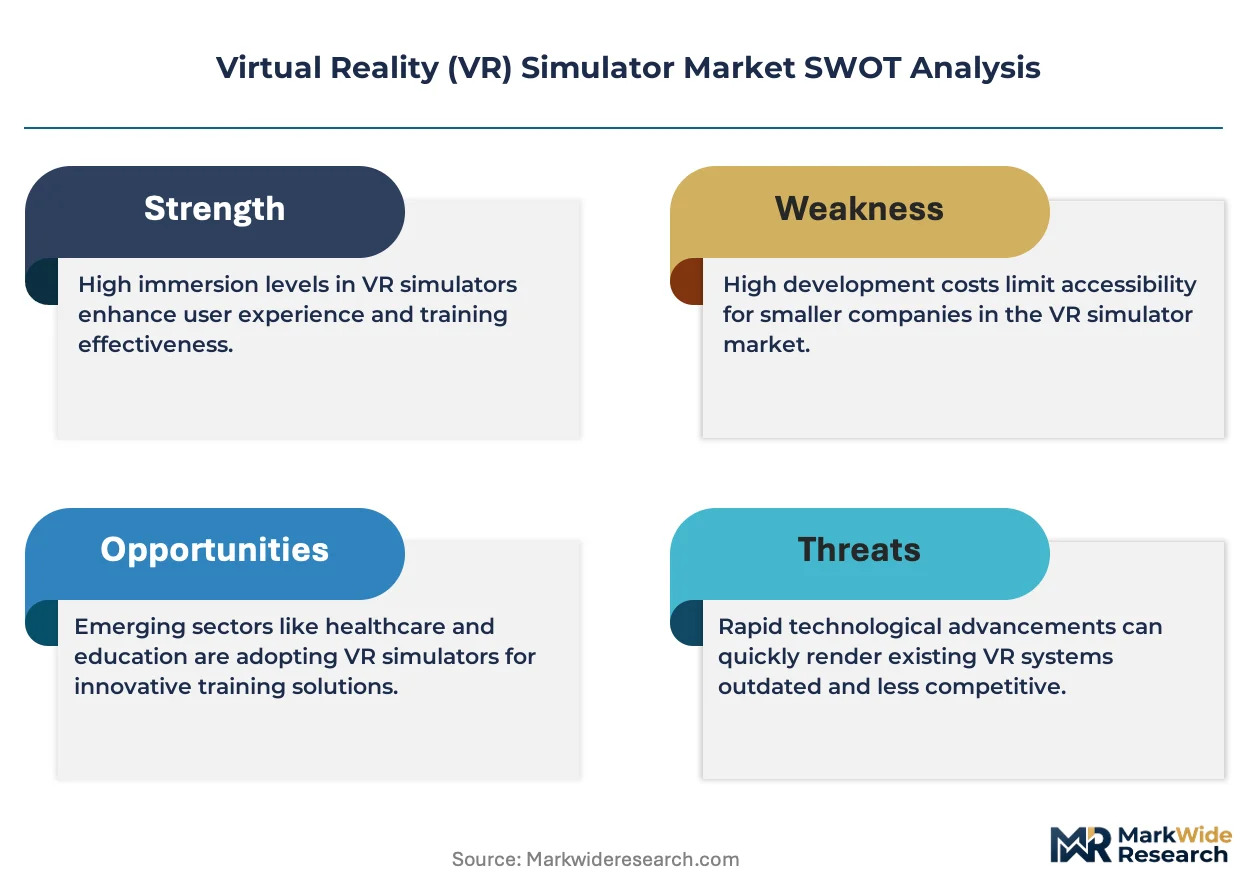
Modular hardware-software bundles is expanding as the dominant procurement pattern, letting enterprise buyers mix headset tiers with subscription-based simulation platforms rather than committing to monolithic systems. Meta leverages its captive content ecosystem to anchor premium enterprise contracts. HTC Corporation specializes in location-based entertainment configurations with high-fidelity motion tracking. Sony Group Corporation competes through cinematic display fidelity in consumer and prosumer segments.
Virtual Reality simulators integrate head-mounted displays with spatial computing architectures to render interactive three-dimensional environments for skill acquisition, procedural rehearsal, and sensory immersion. These systems typically achieve sub-20 millisecond motion-to-photon latency to prevent simulator sickness during extended training protocols. Standalone headsets now capture the largest addressable base by eliminating PC dependency and reducing total cost of ownership for education and healthcare deployments. Haptic Feedback technology represents the fastest-expanding capability layer, as force-feedback gloves and full-body suits deepen kinesthetic fidelity in military and surgical training applications.
The Federal Aviation Administration governs VR flight simulator certification under Part 60 standards, while the EU AI Act imposes risk-classification obligations on autonomous training algorithms deployed in European healthcare and defense contexts. FDA guidance on VR-based therapeutic devices shapes clinical trial design and reimbursement pathways for digital health applications. Stakeholders must weigh regulatory pre-certification investments against the margin compression from fragmented national standards for data privacy and biometric consent in immersive environments.
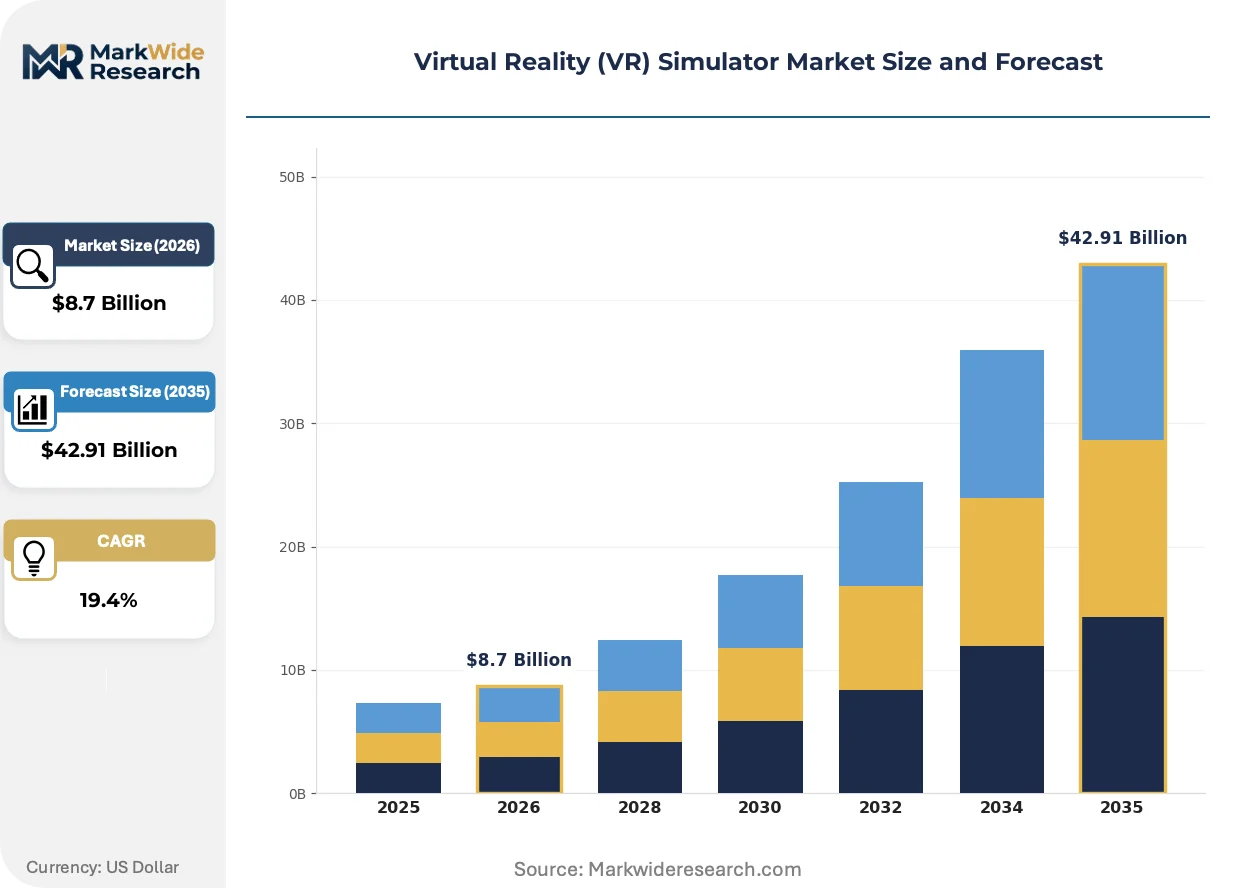
Market Dynamics
Defense procurement agencies across NATO member states are accelerating simulator deployment as military readiness mandates intensify, while modular hardware-software bundles displace monolithic system purchases in enterprise training budgets.
Growth Catalysts
- EU AI Act risk-classification mandates:European healthcare and defense training providers must upgrade legacy systems to compliant architectures, forcing replacement cycles and certified vendor consolidation.
- Haptic Feedback integration:Force-feedback gloves and full-body suits deepen kinesthetic fidelity, expanding addressable use cases in surgical rehearsal and combat scenario training beyond visual immersion.
- Germany's industrial automation corridor:Automotive OEMs deploy VR assembly line simulators for workforce certification, creating concentrated demand for high-precision motion tracking systems.
Market Restraints
- Display panel supply concentration:Micro-OLED and pancake lens manufacturing clusters in East Asian foundries create input cost volatility and allocation risk for headset producers.
- CE marking and MDR compliance costs:European medical device regulations impose pre-certification investments that compress margins for therapeutic VR device developers.
- Simulator sickness latency thresholds:Sub-20 millisecond motion-to-photon requirements demand specialized rendering hardware, elevating baseline system costs above education-sector budgets.
Strategic Opportunities
- Standalone headset penetration in India:Elimination of PC dependency reduces total cost of ownership, opening healthcare and vocational training deployments in price-sensitive institutional markets.
- FAA Part 60 certification expansion:Regulatory pathway clarity for VR flight simulators enables commercial aviation training providers to substitute immersive systems for full-motion platforms.
- Spatial computing and 5G convergence:Edge-rendered immersive environments delivered over low-latency networks enable lightweight headsets for location-based entertainment venues.
Industry Challenges
- Biometric data governance fragmentation:National standards for eye-tracking and physiological monitoring consent in immersive environments complicate multi-jurisdictional deployment architectures.
- Motion-to-photon engineering talent scarcity:Specialized latency optimization skills required for nausea prevention remain concentrated among a small pool of rendering engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Reality (VR) Simulator Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Tethered, Mobile, PC-based End User: Education, Healthcare, Entertainment, Military Technology: Optical Tracking, Motion Tracking, Haptic Feedback, 3D Audio Application: Training Simulations, Virtual Tours, Gaming, Therapy |
| Companies Covered | Meta, Sony Group Corporation, Apple Inc., Microsoft Corporation, Samsung Electronics Co., Ltd., HTC Corporation, ByteDance, Unity Technologies, Google, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Reality (VR) Simulator Market Evolving Landscape
Rendering architectures and procurement models are undergoing parallel transformation as latency engineering converges with cloud distribution and enterprise buyers abandon capital-intensive ownership structures.
Standalone VR headsets are consolidating market position by eliminating tethered PC dependencies and reducing facility infrastructure requirements. Healthcare systems and educational institutions in North America and Europe are adopting these platforms at accelerating pace. This consolidation is compressing addressable market share for high-end tethered systems outside specialized military and surgical applications.
EU AI Act risk-classification obligations are reshaping product development roadmaps for autonomous training algorithms deployed in European healthcare and defense contexts. Developers must document decision pathways and human oversight mechanisms before market entry. Medical device manufacturers are responding by restructuring AI governance teams and pre-submission engagement with notified bodies.
Enterprise training buyers are fragmenting vendor relationships across hardware tiers and software subscriptions rather than consolidating with single-source providers. Automotive and aerospace certification programs in Germany and the United States are unbundling headset procurement from simulation content licensing. This pattern is most visible in German industrial corridors where workforce certification volumes justify platform-agnostic content investments.
Virtual Reality (VR) Simulator Market Segmentation
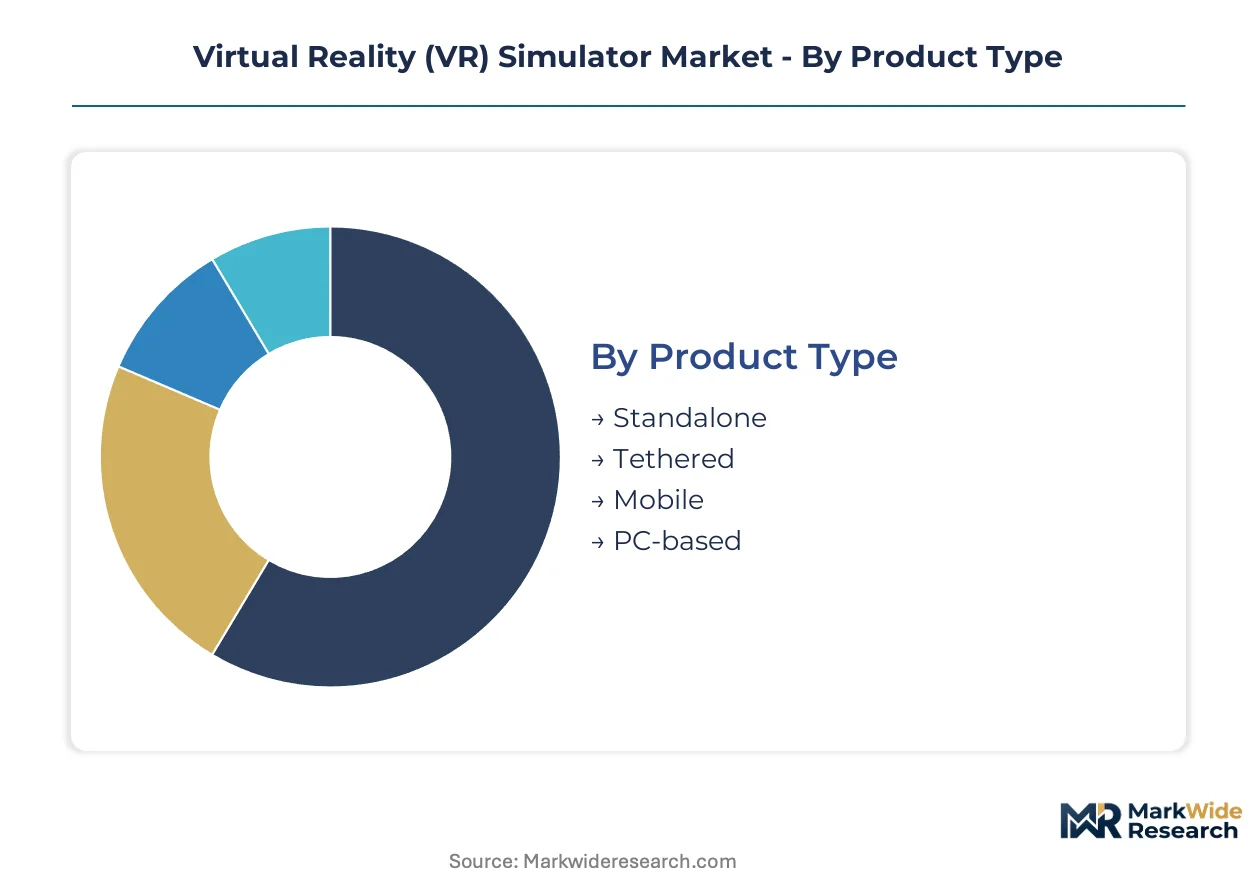
VR simulator procurement patterns diverge sharply across hardware configurations, end-use requirements, and sensory fidelity specifications. Buyers optimize total cost of ownership against latency thresholds and content ecosystem depth. Segment boundaries blur as standalone headsets encroach on tethered performance tiers and haptic layers become standard in military and surgical deployments.
Product Type:
Processing architecture and PC dependency define the hardware hierarchy, with thermal constraints and battery chemistry governing mobility trade-offs.
- Standalone:Integrated SoC architectures with onboard rendering eliminate facility infrastructure requirements. German automotive OEMs deploy these for assembly line certification programs, prioritizing rapid facility reconfiguration over absolute fidelity.
- Tethered:External GPU dependency delivers sub-20ms motion-to-photon latency through dedicated rendering pipelines. Flight training centers under FAA Part 60 jurisdiction retain these for instrument-rated simulator certification where regulatory precision mandates stationary installations.
- Mobile:Smartphone-dependent optics leverage existing device penetration for entry-level education deployments. India's vocational training institutes adopt these for cost-constrained skills programs.
- PC-based:Modular component architectures allow GPU upgrade cycles without full headset replacement. Location-based entertainment venues in Japan favor these for refresh flexibility.
Leading the category by volume: Standalone. Growing fastest: Standalone, as healthcare systems eliminate PC management overhead.
End User:
Budget authority and certification requirements reshape vendor selection, with procurement cycles spanning months for defense contracts versus weeks for entertainment rollouts.
- Education:Institutional procurement favors multi-seat licensing and content curation tools. North American universities prioritize standalone deployments for campus-wide accessibility.
- Healthcare:FDA and EMA regulatory pathways demand clinical validation documentation. Surgical rehearsal applications drive haptic integration requirements.
- Entertainment:Location-based venues require high-throughput motion tracking for multiplayer synchronization. Operators in Dubai and Singapore invest in warehouse-scale installations.
- Military:NATO procurement specifications mandate encrypted data handling and electromagnetic hardening. Combat scenario training absorbs the highest per-seat haptic expenditure.
Dominant procurement volume sits with Military. Steepest expansion trajectory belongs to Healthcare, as reimbursement pathways for therapeutic VR solidify.
Technology:
Sensory fidelity layers stack from positional awareness through force feedback, with integration complexity rising nonlinearly.
- Optical Tracking:Inside-out camera arrays map environment geometry without external base stations. Consumer and prosumer headsets standardize this approach for setup simplicity.
- Motion Tracking:External lighthouse or marker-based systems achieve millimeter precision for industrial metrology and surgical navigation. Germany's automation corridor specifies these for assembly verification.
- Haptic Feedback:Force-feedback gloves and exoskeleton suits render texture, resistance, and impact. Military and surgical training represent the primary demand concentration as kinesthetic fidelity becomes competitive differentiator.
- 3D Audio:Spatial audio engines with head-related transfer function modeling enhance immersion without hardware cost escalation. Entertainment and therapy applications lead adoption.
Optical Tracking commands installed base leadership. Haptic Feedback climbs fastest as training protocols deepen beyond visual immersion.
Application:
Use case maturity determines content ecosystem depth and regulatory scrutiny intensity.
- Training Simulations:Structured skill acquisition with performance analytics and competency verification. Aviation, healthcare, and defense procurement dominate this segment.
- Virtual Tours:Real estate, tourism, and cultural heritage visualization with limited interactivity. Commercial deployment concentrates in hospitality and property marketing.
- Gaming:Consumer entertainment with the deepest content libraries and shortest hardware replacement cycles. Meta and Sony anchor platform competition here.
- Therapy:Clinical interventions for anxiety, PTSD, and pain management requiring FDA or national health regulator clearance. Reimbursement pathway development lags hardware capability.
Training Simulations generate largest contract value. Therapy expands most quickly as digital health reimbursement frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware fabrication clusters in East Asia supply display panels and optical components, while Western defense and healthcare systems absorb the highest-value deployments. Consumption concentrates in NATO-aligned defense procurement corridors and German industrial automation zones.
United States
The FAA governs VR flight simulator certification under Part 60 standards, driving commercial aviation training substitution toward immersive platforms. Defense procurement agencies accelerate combat scenario simulator budgets under intensified military readiness mandates. Greater Boston anchors surgical rehearsal application development with FDA-cleared therapeutic VR trials.
Germany
The EU AI Act imposes risk-classification obligations on autonomous training algorithms deployed in healthcare and defense contexts. Automotive OEMs in Baden-Württemberg deploy VR assembly line simulators for workforce certification, creating concentrated demand for high-precision motion tracking. KBA influences industrial safety standards for immersive manufacturing training environments.
China
MIIT standards govern immersive technology product compliance for domestic headset manufacturers. Location-based entertainment venues in Shanghai and Shenzhen invest in warehouse-scale multiplayer installations. The Yangtze River Delta hosts micro-OLED foundry clusters supplying display panels to global headset producers.
United Kingdom
GDPR and emerging biometric consent frameworks complicate eye-tracking data governance for multi-jurisdictional VR deployments. Defense procurement through the Ministry of Defence prioritizes encrypted data handling specifications for combat training systems. London anchors financial services VR applications for trader simulation and client onboarding protocols.
India
Standalone headset penetration accelerates as elimination of PC dependency reduces total cost of ownership for healthcare and vocational training. BIS standards shape product compliance pathways for imported immersive devices. Karnataka's vocational training institutes adopt mobile-dependent VR optics for cost-constrained skills programs.
Virtual Reality (VR) Simulator Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware fabrication, content platforms, and enterprise software integration. Market structure tilts toward platform consolidation as content ecosystem depth determines contract retention. Three archetypes dominate: captive hardware-content integrators, component-specialist fabricators, and cross-platform software enablers. M&A activity concentrates on haptic technology acquisitions and spatial computing talent, while geographic expansion targets price-sensitive institutional markets in South Asia and Southeast Asia.
Among diversified technology conglomerates, Meta and Sony Group Corporation occupy positions as captive ecosystem anchors, each leveraging content libraries to retain enterprise and consumer segments. HTC Corporation exemplifies the component-specialist archetype with concentrated focus on location-based entertainment configurations. Microsoft Corporation sits within the enterprise software integration tier, bridging cloud infrastructure with immersive training deployment architectures.
| Leading Market Players |
|---|
| Meta |
| Sony Group Corporation |
| Apple Inc. |
| Microsoft Corporation |
| Samsung Electronics Co., Ltd. |
| HTC Corporation |
| ByteDance |
| Unity Technologies |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialists in European haptic hardware have consolidated component suppliers across Germany and the Netherlands, compressing procurement leverage for standalone headset assemblers while forcing three-tier pricing stratification across premium FAA-certified, standard enterprise, and economy education tiers.
Pricing Analysis
Margin tightening in economy-tier education hardware traces to India's vocational training institutes demanding sub-$300 unit costs for mobile-dependent optics. Pricing stratifies across premium tethered systems with sub-20ms latency guarantees, standard standalone bundles for automotive certification, and economy smartphone-dependent configurations. CE marking and MDR pre-certification investments compress therapeutic device margins, while defense procurement absorbs least price sensitivity through encrypted, electromagnetic-hardened specifications.
Supply Chain Analysis
Ocean freight cost volatility from East Asian display panel foundries to European assembly plants has elevated inventory carrying costs for micro-OLED and pancake lens inputs. Manufacturing clusters center on China's Yangtze River Delta for display fabrication, South Korea for advanced semiconductor packaging, and Taiwan for optical component precision. Single-source vulnerability concentrates in micro-OLED etching equipment, where German automation corridor demand competes with global headset allocation. Distribution runs through authorized enterprise integrators for defense and healthcare, direct OEM relationships for automotive, and mass retail for education.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum favors haptic technology and spatial computing talent acquisition as the decisive upstream lever, with downstream platform consolidation determining contract retention across NATO defense procurement and German automotive certification programs.
For Market Incumbents: Anchor enterprise contract retention through captive content ecosystem depth, prioritizing FAA Part 60 certification maintenance and EU AI Act compliance documentation as defensive moats. Acquire specialized haptic engineering teams to deepen kinesthetic fidelity differentiation against modular hardware-software bundlers. Expand encrypted data handling capabilities to defend military procurement share from emerging sovereign-backed Asian competitors. For New Entrants and Emerging Players: Cloud-rendered SaaS distribution channels enable rapid penetration of India's price-sensitive healthcare and vocational training markets without hardware manufacturing overhead. Target standalone headset deployments in Karnataka's skills institutes and North American university multi-seat licensing as the most penetrable white-space. Pursue platform-agnostic content licensing to German automotive OEMs unbundling hardware from simulation software procurement. For Investors and Strategic Acquirers: Distressed-cycle entries favor haptic feedback specialists with FDA-cleared therapeutic applications in Greater Boston and Baden-Württemberg. Long-term viability hinges on reimbursement pathway maturation for digital health VR and defense budget continuity through NATO readiness mandates. Watch for FAA Part 60 certification expansion signals as inflection indicators for commercial aviation training substitution toward immersive platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Haptic Technology Acquisition | Force-feedback glove developers deepen kinesthetic fidelity for surgical and combat training protocols. |
| EU AI Act Compliance Investment | Documented decision pathways satisfy risk-classification mandates for autonomous healthcare algorithms. |
| Standalone Headset Platform Launch | Elimination of PC dependency opens India's vocational training and healthcare institutional markets. |
| FAA Part 60 Certification Pathway | Regulatory clarity enables commercial aviation providers to substitute immersive systems for full-motion platforms. |
| Spatial Computing Talent Acquisition | Latency optimization engineers remain scarce for sub-20ms motion-to-photon rendering pipelines. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across headset hardware engineers, simulation platform product managers, defense procurement officers, and healthcare reimbursement specialists. FDA 510(k) submissions, EMA medical device registrations, FAA Part 60 certification databases, and EU notified body pre-submission filings provided regulatory trajectory validation. Bottom-up unit shipment estimates by hardware tier converged with top-down defense budget allocation analysis across NATO member states.
Segment-level modeling tracked standalone, tethered, mobile, and PC-based hardware configurations against education, healthcare, entertainment, and military end-use requirements. Deployment model, certification tier, motion-to-photon latency specification, and regional procurement pattern dimensions structured volume and value projections across the analysis window. CAGRs derived from replacement cycle analysis of EU AI Act-mandated system upgrades and haptic integration adoption curves in surgical rehearsal applications.
The model holds under sustained defense procurement budgets and reimbursement pathway expansion for therapeutic VR; deviation in micro-OLED supply allocation or biometric data governance fragmentation would shift trajectory. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Spatial Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Visor Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Construction Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Mobile Infrastructure Market
Virtual Reality (VR) and Augmented Reality (AR)
India Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
5G and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality in Therapy Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) in Healthcare Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Software Market