
 Holographic AR Display Market | 2026-2036
Holographic AR Display Market Size, Share, and Industry Trends Forecast 2026-2036
Holographic AR Display Market Foresight
Platform licensing revenue from holographic software ecosystems is reshaping profit distribution across the value chain. Looking Glass Factory, Inc. leverages its volumetric display architecture to dominate creative production workflows. Qualcomm Incorporated anchors the semiconductor layer with specialized spatial computing chipsets. HYPERVSN competes in large-format holographic projection for retail and events, while Leia, Inc. specializes in light-field displays for mobile integration.
Holographic AR display systems generate three-dimensional imagery through light-field modulation or laser interference patterns, typically operating at refresh rates exceeding 60 Hz to prevent perceptual flicker during immersive visualization. These systems serve medical imaging, automotive prototyping, and remote collaboration by rendering depth-correct volumetric content without head-worn optics. Head-Mounted Displays and Smart Glasses capture premium positioning in enterprise training and surgical navigation, where margin pools concentrate on optical waveguide subsystems. Projection Systems lead in retail and entertainment deployments due to lower per-unit hardware costs, while Desktop Monitors are gaining traction in design studios that require collaborative holographic review without individual wearables.
FDA device classification rules govern clinical holographic AR systems intended for diagnostic or surgical guidance, while the EU AI Act imposes conformity requirements on automated decision-support overlays in medical and automotive applications. ISO standards for near-eye display metrology shape interoperability benchmarks across hardware vendors. Stakeholders must monitor regulatory divergence between FDA premarket pathways and EMA notified body expectations as both jurisdictions develop specialized frameworks for spatial computing medical devices.
Market Dynamics
Platform licensing revenue from holographic software ecosystems is redistributing value capture away from hardware manufacturers toward middleware developers and spatial computing engines. This structural shift concentrates margin pools in volumetric content pipelines and developer toolchains.
Growth Catalysts
- FDA device classification rules:The tightening premarket pathway for clinical AR systems is accelerating hospital procurement cycles for validated surgical visualization platforms in the United States.
- Precision engineering clusters in Germany:Stuttgart and Munich manufacturing corridors are driving enterprise adoption for automotive holographic prototyping and digital twin validation workflows.
- Light-field modulation:Advances in real-time parallax correction are eliminating vergence-accommodation conflict in medical imaging, expanding addressable use cases in radiology departments.
Market Restraints
- Optical waveguide substrate concentration:German and Japanese specialty glass suppliers control critical photonic material supply, creating input bottleneck vulnerability for head-mounted display manufacturers.
- EU AI Act conformity costs:Automated decision-support overlay requirements impose documentation burdens that extend product development timelines for clinical AR vendors targeting European healthcare systems.
- Conventional 2D display substitution:High-resolution flat panels with eye-tracking foveated rendering satisfy price-sensitive enterprise training segments without holographic depth cues.
Strategic Opportunities
- South Korea consumer electronics manufacturing:Seoul and Suwon production corridors offer contract assembly scale for mobile-integrated light-field displays targeting smartphone ecosystem integration.
- Remote surgical collaboration:Telementoring applications for complex procedures create demand for shared volumetric visualization without geographic latency constraints.
- ISO near-eye display metrology standards:Emerging interoperability benchmarks create certification service revenue streams for optical testing laboratories and quality assurance providers.
Industry Challenges
- Computational optics talent scarcity:Waveguide design and holographic algorithm development require specialized photonics expertise concentrated in academic institutions with limited industry pipeline capacity.
- Legacy PACS integration complexity:Hospital IT infrastructure built on DICOM-standard 2D imaging creates middleware development burdens for real-time volumetric data streaming.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Holographic AR Display Market |
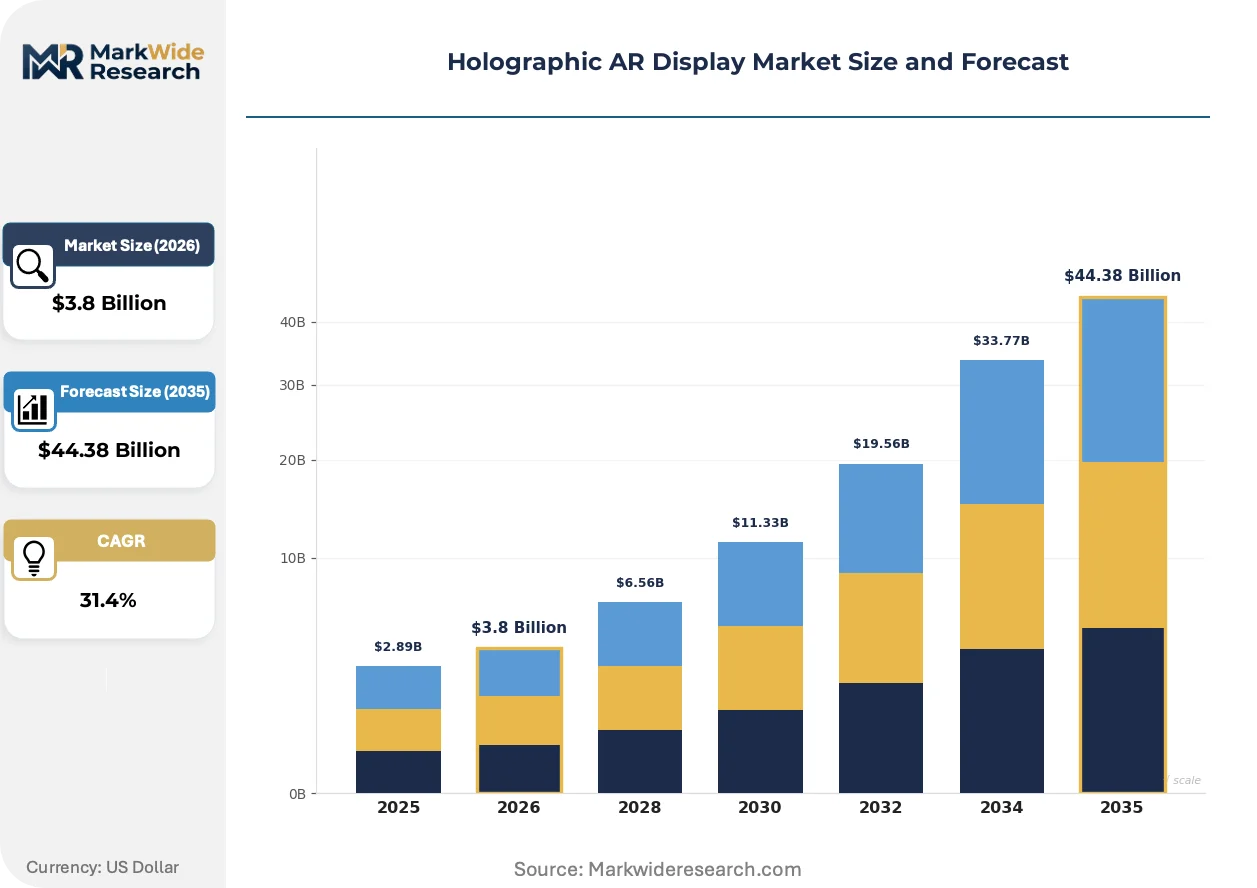
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $44.38 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head-Mounted Displays, Smart Glasses, Projection Systems, Desktop Monitors Application: Healthcare, Education, Automotive Design, Remote Collaboration End User: Enterprise, Consumer, Defense, Retail Technology: Laser-Based, Computer Vision, Light Field, Digital Light Processing |
| Companies Covered | Looking Glass Factory, Inc., HYPERVSN, Leia, Inc., Qualcomm Incorporated, EON Reality, Inc., RealView Imaging Ltd., Axiom Holographics, Realfiction Holding AB, Holoconnects, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Holographic AR Display Market Shifts & Advancements
Real-time volumetric capture pipelines are compressing content production cycles from weeks to hours. This acceleration is reshaping competitive advantage toward software-defined display architectures.
Laser interference-based holographic projection is rendering obsolete lamp-based volumetric displays in retail and entertainment deployments. Theme park operators and flagship retail brands are adopting solid-state illumination systems for 24/7 operational reliability. The technology is rendering obsolete maintenance-intensive legacy projection hardware and associated service contracts.
The EU AI Act conformity assessment framework is mandating algorithmic transparency documentation for clinical decision-support overlays. Medical device manufacturers must submit training data provenance and bias audit reports to notified bodies. Surgical navigation vendors targeting European hospitals are restructuring product development organizations to embed regulatory affairs earlier in design cycles.
Hospital procurement committees are consolidating vendor relationships around integrated hardware-software-service bundles. Standalone display hardware vendors face margin compression as radiology departments favor multi-year performance contracts with guaranteed uptime and content update provisions. This bundling preference is most pronounced in German university hospital systems and South Korean national health service tenders.
Holographic AR Display Market Segmentation
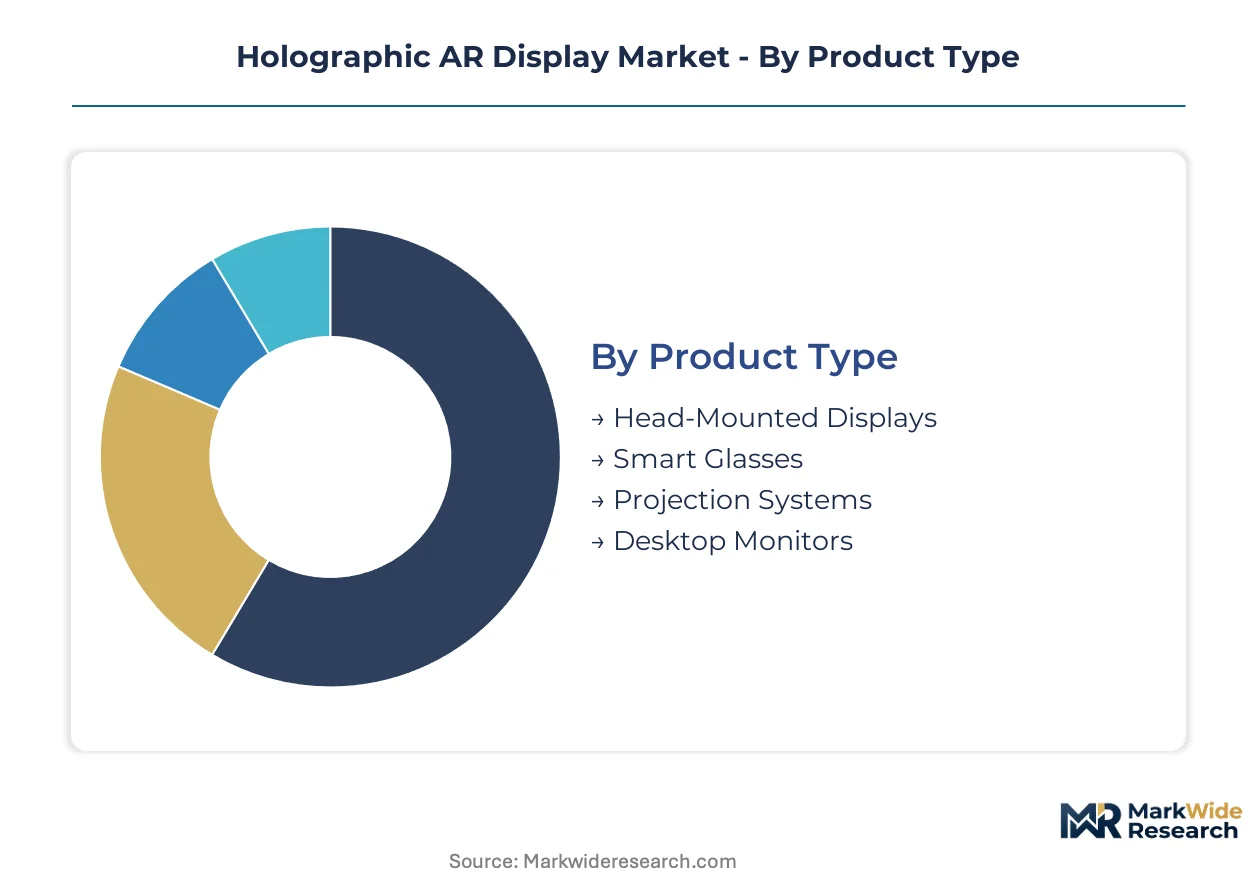
Holographic AR display segmentation reveals divergent service intensity profiles across hardware categories. After-sales support obligations vary dramatically between clinical-grade head-mounted systems and retail projection installations. Understanding these structural differences shapes vendor profitability models and channel investment priorities.
Product Type:
After-sales service intensity peaks in wearable categories requiring optical calibration and firmware maintenance cycles.
- Head-Mounted Displays:Optical waveguide subsystems demand periodic alignment verification and prescription lens integration support. Hospital surgical navigation suites in Germany and the United States drive premium service contract attachment rates exceeding hardware margins. FDA device classification rules mandate traceable maintenance logs for clinical deployments.
- Smart Glasses:Enterprise training programs require fleet management platforms with remote diagnostics and prescription accommodation workflows. Stuttgart automotive prototyping clusters favor multi-year performance guarantees with guaranteed uptime provisions.
- Projection Systems:Retail and entertainment venues prioritize 24/7 operational reliability with solid-state laser illumination reducing maintenance intervals versus lamp-based predecessors.
- Desktop Monitors:Design studios require collaborative holographic review capabilities without individual wearable logistics, concentrating demand in South Korean content production corridors.
By volume, Projection Systems lead. By growth pace, Head-Mounted Displays are expanding most quickly.
Application:
Cost tier stratification separates regulated clinical applications from price-sensitive education deployments.
- Healthcare:Surgical planning and radiology visualization command highest price points with FDA premarket validation requirements. German university hospital systems consolidate procurement around integrated hardware-software-service bundles with guaranteed content update provisions.
- Automotive Design:Digital twin validation workflows in Munich manufacturing corridors drive holographic prototyping adoption with precision engineering tolerances.
- Education:Price-sensitive institutional budgets favor conventional 2D displays with eye-tracking foveated rendering over holographic depth cues in basic training modules.
- Remote Collaboration:Telementoring applications for complex procedures create demand for shared volumetric visualization without geographic latency constraints, particularly in distributed surgical education networks.
Healthcare captures the steepest expansion trajectory. Education remains the largest addressable volume pool.
End User:
Customer type determines procurement authority structures and contract duration preferences.
- Enterprise:Automotive and aerospace manufacturers in Germany's precision engineering clusters drive automotive holographic prototyping with multi-year digital twin validation contracts.
- Consumer:Seoul and Suwon production corridors offer contract assembly scale for mobile-integrated light-field displays targeting smartphone ecosystem integration.
- Defense:Mission-critical simulation requirements prioritize optical reliability and secure supply chains over unit cost optimization.
- Retail:Flagship brand deployments favor large-format holographic projection with 24/7 operational specifications and minimal maintenance downtime.
Enterprise dominates current revenue concentration. Consumer segments are climbing the fastest as mobile integration matures.
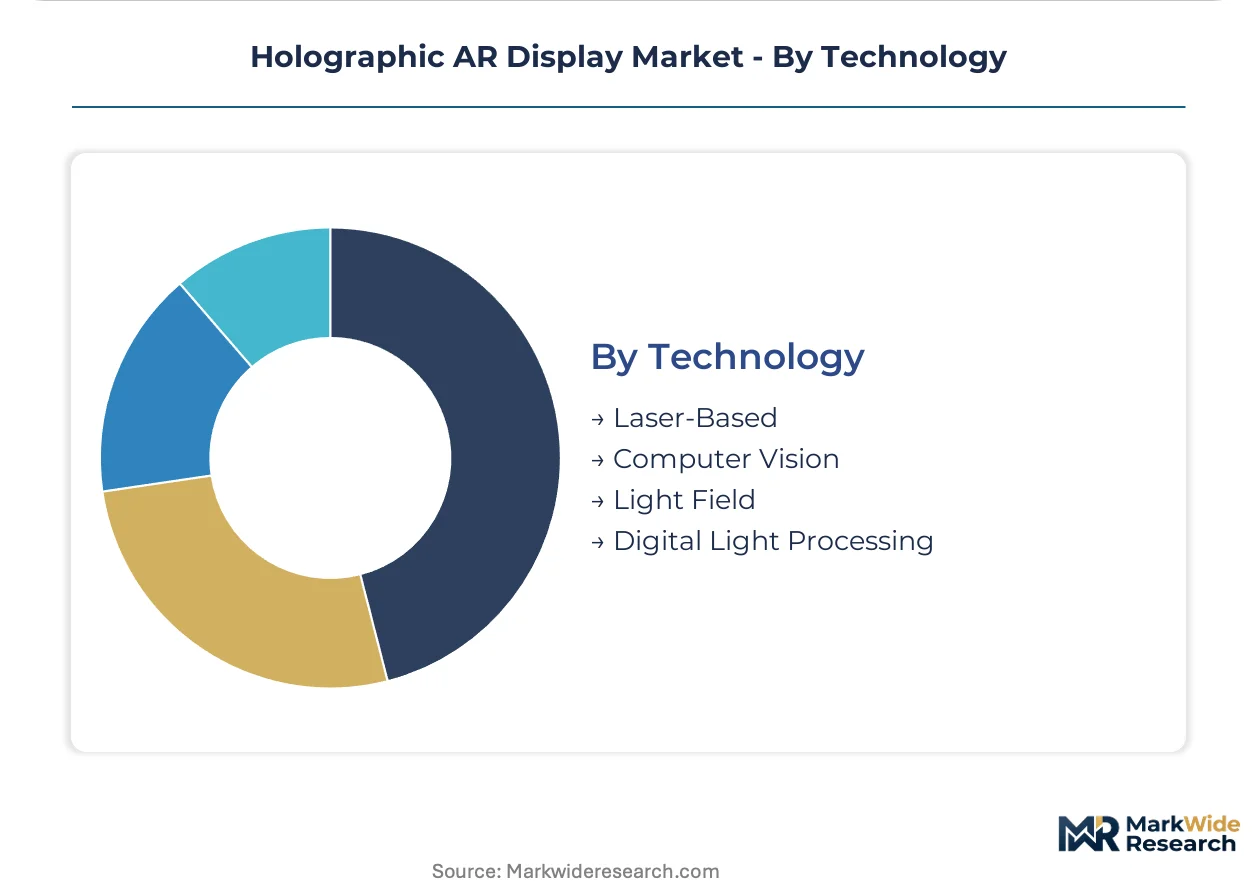
Technology:
Supply concentration in photonic materials shapes technology adoption barriers and vendor differentiation.
- Laser-Based:Solid-state illumination systems eliminate maintenance-intensive legacy projection hardware. Theme park operators and flagship retail brands adopt these for continuous operational reliability.
- Light Field:Real-time parallax correction eliminates vergence-accommodation conflict in medical imaging, expanding radiology department adoption. Advances here depend on German and Japanese specialty glass substrate availability.
- Computer Vision:Algorithmic transparency documentation requirements under EU AI Act impose development timeline extensions for clinical decision-support overlays in European healthcare systems.
- Digital Light Processing:Mature micro-mirror architectures serve cost-sensitive enterprise training segments with established supply chains and reduced optical complexity.
Laser-Based systems lead by installed volume. Light Field technology is gaining share fastest in premium medical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospitals deploy holographic AR primarily for FDA-cleared surgical navigation, while German automotive engineers use identical hardware for digital twin validation. South Korean consumer electronics corridors pursue mobile-integrated light-field displays at mass-market price points.
United States
FDA premarket pathway requirements accelerate hospital procurement cycles for validated surgical visualization platforms. The FDA device classification rules mandate traceable maintenance logs and clinical performance documentation for diagnostic AR systems. Pittsburgh and Boston medical technology corridors concentrate radiology department adoption with integrated hardware-software-service bundles.
Germany
Stuttgart and Munich precision engineering clusters drive enterprise demand for automotive holographic prototyping workflows. The EU AI Act conformity assessment framework imposes algorithmic transparency documentation burdens on clinical decision-support vendors. Bavarian university hospital systems consolidate procurement around multi-year performance contracts with guaranteed uptime provisions.
South Korea
Seoul and Suwon production corridors offer contract assembly scale for smartphone-integrated light-field displays. The MFDS medical device regulations shape performance validation requirements for clinical AR systems targeting domestic healthcare networks. Gyeonggi-do manufacturing belts concentrate mobile holographic display module production for consumer ecosystem integration.
China
Shanghai and Shenzhen technology hubs expand domestic production capacity for laser-based holographic projection systems. The NMPA medical device registration pathway governs clinical AR system commercialization with localization requirements for data handling. Yangtze River Delta industrial zones concentrate volumetric display component manufacturing for retail and entertainment deployments.
Japan
Tokyo and Osaka metropolitan areas sustain demand for precision optical waveguide substrates in head-mounted display manufacturing. The PMDA regulatory framework aligns with international standards for near-eye display metrology and clinical safety validation. Chubu region specialty glass suppliers control critical photonic material inputs for global HMD manufacturers.
Holographic AR Display Market Competitive Landscape
Capability concentration sits with specialized volumetric display architects; scale advantage sits with semiconductor platform licensors. The vendor base organizes around three strategic archetypes: volumetric hardware specialists, spatial computing chipset providers, and holographic software ecosystem developers. Consolidation pressure concentrates in the middleware layer where platform licensing revenue redistributes value capture. Dominant competitive moves include technology licensing partnerships and backward integration into optical waveguide substrate supply.
Within the volumetric display specialist tier, Looking Glass Factory, Inc. and HYPERVSN occupy positions representing divergent hardware philosophies. Qualcomm Incorporated anchors the semiconductor layer as a spatial computing chipset licensor. Leia, Inc. exemplifies the mobile-integrated light-field archetype targeting consumer electronics ecosystem penetration.
| Leading Market Players |
|---|
| Looking Glass Factory, Inc. |
| HYPERVSN |
| Leia, Inc. |
| Qualcomm Incorporated |
| EON Reality, Inc. |
| RealView Imaging Ltd. |
| Axiom Holographics |
| Realfiction Holding AB |
| Holoconnects |
| Others |
Supply & Pricing Matrix
Seoul and Suwon production corridors anchor global capacity for smartphone-integrated light-field display modules, concentrating downstream pricing power with contract manufacturers who dictate terms to hardware assemblers. This geographic clustering enables volume-driven cost compression in consumer-tier holographic components while clinical-grade optical waveguide subsystems command premium positioning through German and Japanese specialty glass scarcity.
Pricing Analysis
Long-term offtake agreements dominate hospital procurement for FDA-cleared surgical navigation systems, locking in multi-year hardware-software-service bundles with guaranteed uptime provisions. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade head-mounted displays with optical calibration support from retail projection systems and cost-sensitive desktop monitors. Cost compression in enterprise training segments intensifies as conventional 2D displays with eye-tracking foveated rendering satisfy basic depth visualization needs. Education buyers exhibit highest price sensitivity, while German automotive prototyping clusters demonstrate lowest sensitivity due to precision engineering tolerance requirements.
Supply Chain Analysis
Tariff exposure between German specialty glass suppliers and Chinese volumetric display assemblers dominates supply chain risk planning for head-mounted display manufacturers. Production gravity centers on Japan, Germany, and South Korea for optical waveguide substrates, laser illumination modules, and mobile-integrated light-field panels respectively. Critical photonic material inputs draw from Chubu region specialty glass foundries and Stuttgart precision optics workshops. Single-source vulnerability concentrates in germanium-doped waveguide substrates essential for near-eye display metrology. Distribution runs through hospital GPO contracts, automotive Tier 1 supplier networks, and consumer electronics OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Holographic AR display incumbents face substitution pressure from high-resolution flat panels with eye-tracking foveated rendering that replicate depth cues at lower cost points in price-sensitive training segments.
For Market Incumbents: Build regulatory certification moats through early FDA premarket pathway engagement and EU AI Act conformity documentation. Deepen backward integration into optical waveguide substrate supply through partnerships with Chubu region specialty glass suppliers. Capture margin pools in volumetric content pipelines by licensing spatial computing engines to middleware developers. Counter conventional 2D display substitution with bundled performance guarantees that flat panels cannot match. For New Entrants and Emerging Players: Establish a beachhead in remote surgical collaboration applications where telementoring demand outpaces incumbent supply capacity. Target South Korean consumer electronics manufacturing corridors for contract assembly partnerships that bypass German-Japanese photonic material bottlenecks. Penetrate education sector white space through smartphone-integrated light-field displays that undercut desktop monitor price points. Pursue ISO near-eye display metrology certification services as a revenue-generating entry vector. For Investors and Strategic Acquirers: Long-term, this sits as a platform licensing play because software-defined display architectures are redistributing value capture from hardware manufacturers toward middleware developers. Acquisition candidates should demonstrate volumetric content pipeline control or spatial computing chipset licensing leverage. Monitor FDA device classification rule expansions and EU AI Act implementation timelines as inflection indicators for clinical AR system commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Licensing Partnership | Qualcomm's spatial computing chipset ecosystem anchors downstream hardware compatibility standards. |
| Backward Integration into Waveguide Supply | Captive specialty glass sourcing insulates against Chubu region supplier concentration risk. |
| FDA Premarket Pathway Investment | Early validation documentation accelerates hospital procurement cycles for surgical navigation suites. |
| EU AI Act Conformity Embedding | Algorithmic transparency documentation restructures product development timelines for European market access. |
| Remote Collaboration Capability Development | Telementoring applications create demand for shared volumetric visualization without geographic latency constraints. |
Research Methodology
A spread of perspectives from hospital surgical navigation directors, automotive digital twin validation engineers, consumer electronics procurement leads, and optical waveguide substrate suppliers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR technical documentation, SEC semiconductor capex disclosures, and German precision engineering cluster trade data. Bottom-up demand modeling across product type, application, end user, and technology dimensions triangulated with top-down market sizing from spatial computing platform licensors.
Demand-supply-balance framing shaped the analytical framework across the analysis window, with segmentation modeling across head-mounted displays, smart glasses, projection systems, and desktop monitors by healthcare, automotive, education, and remote collaboration applications. CAGRs were derived from installed base growth curves and replacement cycle dynamics in clinical versus consumer deployment contexts. Forecast inputs incorporated optical waveguide yield rates, laser illumination cost curves, and volumetric content production pipeline expansion trajectories.
Sensitivities concentrate around FDA device classification rule expansions, EU AI Act notified body interpretation variance, and specialty glass substrate supply disruptions from Chubu region production constraints. Forecasts reflect assumptions regarding hospital procurement committee bundling preferences and automotive prototyping cluster digital twin adoption velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Telepresence Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Mobile Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Visor Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Para-Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Amusement Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
China Metaverse Market