
 Smart Home As a Service Market | 2026-2036
Smart Home As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home As a Service Market Outlook
The shift from device purchase to recurring subscription is hardening across residential technology procurement. ADT Inc. leverages its professional monitoring infrastructure to anchor managed security services within broader home automation bundles. Vivint Smart Home, Inc. competes through vertically integrated installation and support networks that reduce third-party dependency. Comcast Corporation extends its broadband subscriber base into home automation through platform-agnostic service layering.
Smart Home As a Service denotes a recurring-revenue operational model where providers remotely manage, monitor, and update connected residential devices through cloud-based platforms, typically requiring minimum bandwidth thresholds of 25 Mbps for real-time video analytics and over-the-air firmware distribution. The architecture eliminates upfront capital burdens for consumers while generating predictable lifetime value for service operators. Security Monitoring commands the largest current revenue share within service type segmentation, though Energy Management registers the fastest expansion as utility dynamic pricing programs proliferate. Smart Thermostats dominate device type attachment rates due to their quantifiable return on investment, while Smart Cameras concentrate margin pools through tiered storage and AI-enhanced analytics upsells.
The FCC governs spectrum allocation for Z-Wave and Zigbee protocols that underpin low-power device mesh networks, while the FTC monitors subscription billing transparency and automatic renewal disclosures that shape consumer trust in recurring contracts. State-level public utility commissions in California and New York mandate interoperable energy data standards that determine which platforms qualify for demand-response program participation. Stakeholders must track evolving cybersecurity certification requirements from NIST as breach liability increasingly shifts from device manufacturers to managed service providers.
Market Dynamics
The subscription pivot in residential technology procurement is compressing capital cycles and transferring device lifecycle risk from consumers to service operators, fundamentally restructuring vendor economics around recurring revenue capture rather than transactional hardware margins.
Growth Catalysts
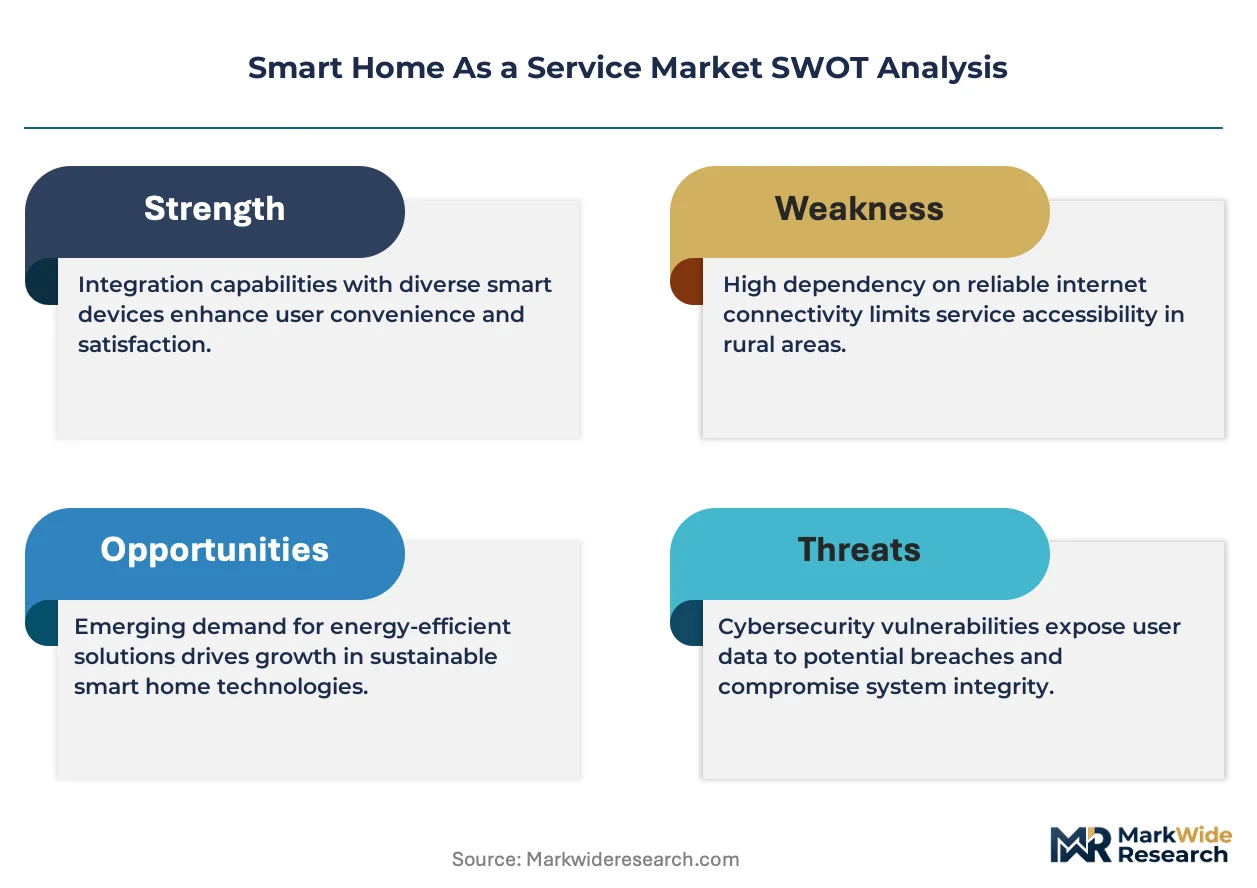
- Utility dynamic pricing programs:State public utility commissions in California and New York mandate interoperable energy data standards, qualifying managed service platforms for demand-response participation and accelerating thermostats-as-a-service attachment.
- FCC broadband infrastructure investments:Federal Communications Commission funding expands minimum 25 Mbps connectivity to underserved census tracts, enabling real-time video analytics and over-the-air firmware distribution for cloud-managed device networks.
- Insurance premium discount frameworks:Property and casualty underwriters in Texas and Florida now bundle professionally monitored security services into homeowners policies, converting risk-averse households to subscription models.
Market Restraints
- Cloud infrastructure concentration:Amazon Web Services and Microsoft Azure host over 70 percent of residential IoT backend workloads, creating single-point-of-failure exposure for tier-two service operators.
- Cybersecurity liability migration:NIST cybersecurity certification requirements shift breach accountability from device manufacturers to managed service providers, inflating insurance premiums and compliance overhead.
- Silicon supply bottlenecks:Taiwan Semiconductor Manufacturing Company capacity constraints for 28nm and 40nm process nodes delay smart camera and sensor production, extending procurement lead times for hardware-dependent service rollouts.
Strategic Opportunities
- Multifamily developer channel penetration:Property technology platforms like Yardi and RealPage enable lease-embedded automation bundles, converting apartment dwellers to service subscribers without individual sales friction.
- Age-in-place healthcare integration:Fall detection and medication adherence sensors converge with Medicare Advantage supplemental benefit structures, opening reimbursement-funded service categories.
- EU Energy Performance of Buildings Directive:Mandatory smart readiness indicators for residential construction create regulatory pull for pre-installed energy management services in new German and French housing stock.
Industry Challenges
- Interoperability protocol fragmentation:Z-Wave, Zigbee, Thread, and Matter standards operate in parallel, forcing service operators to maintain multi-radio gateways and complicating seamless device onboarding.
- Technical workforce scarcity:Low-voltage installation technicians with cloud platform certification command wage premiums exceeding 35 percent above residential electrical trades, constraining field service scaling.
- Subscription fatigue management:FTC automatic renewal disclosure requirements and state-level subscription cancellation mandates increase customer acquisition cost recovery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home As a Service Market |
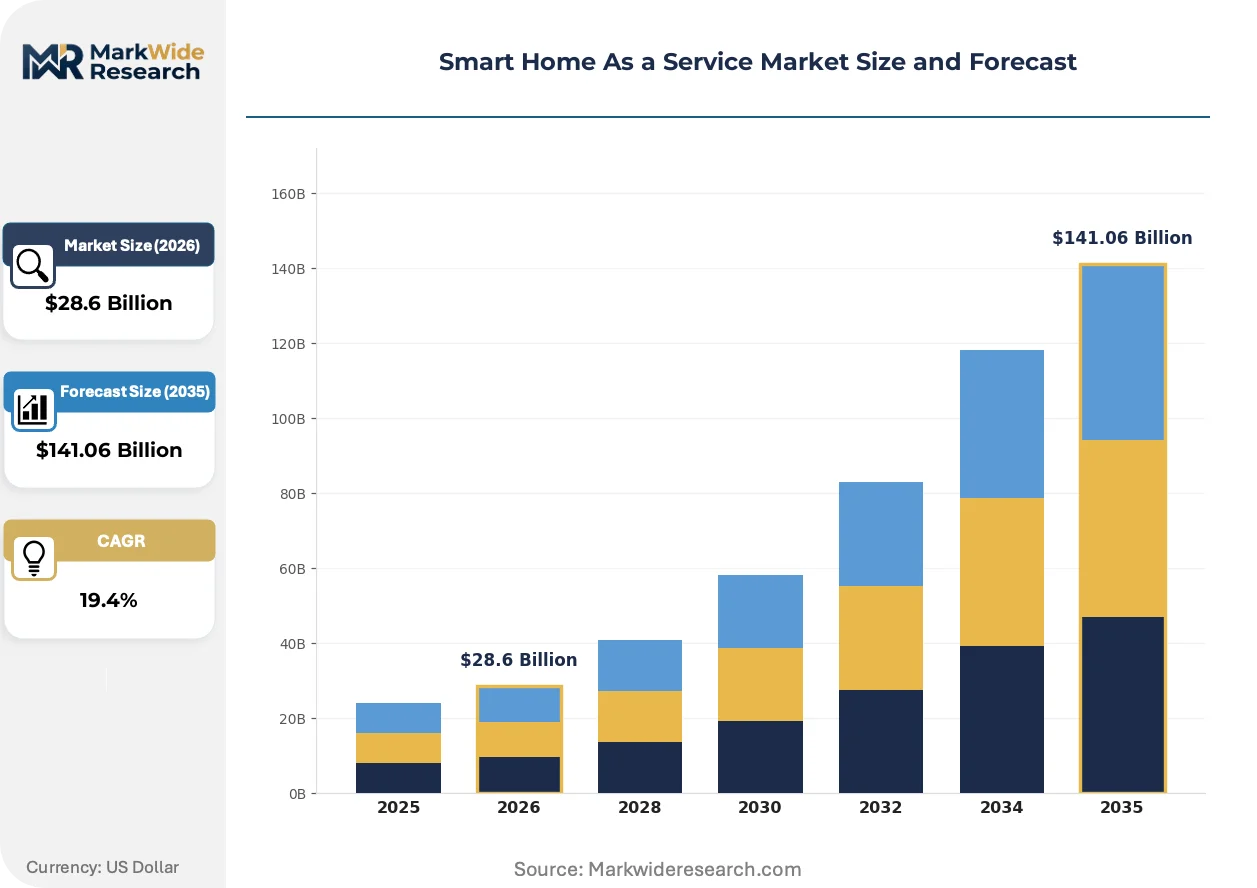
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $141.06 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Home Automation, Energy Management, Security Monitoring, Voice Control Device Type: Smart Lights, Smart Thermostats, Smart Locks, Smart Cameras Consumer Segment: Residential, Rental, Hospitality, Senior Living Connectivity Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth |
| Companies Covered | ADT Inc., Vivint Smart Home, Inc., Comcast Corporation, Alarm.com Holdings, Inc., Johnson Controls International PLC, Control4 Corp., Charter Communications, Inc., Telus International, Lumen Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home As a Service Market Strategic Shifts
Edge AI inference is migrating from cloud data centers to residential gateways, compressing latency for real-time anomaly detection while reducing bandwidth consumption and recurring cloud compute costs for service operators.
Matter protocol standardization is rewriting competitive positioning for device-agnostic service platforms. Multifamily property managers and retail channel partners are accelerating procurement of cross-ecosystem compatible hardware, collapsing the proprietary lock-in strategies that previously protected vertically integrated incumbents. This interoperability pressure is compressing margin capture for closed-platform specialists.
The FTC's updated Click-to-Cancel rule mandates one-click subscription termination mechanisms, reshaping customer lifetime value calculations. Service operators must now front-load profitability within shorter average tenures, driving investment into predictive churn algorithms and proactive retention outreach. California and New York public utility commissions are responding with accelerated rebate qualification for platforms demonstrating sustained subscriber engagement.
Procurement authority is consolidating among property technology procurement officers at institutional multifamily owners, displacing individual resident decision-making. Greystar, AvalonBay, and Equity Residential now mandate standardized automation stacks across portfolios, forcing device vendors to restructure sales organizations around enterprise account teams rather than retail channel support. This concentration is most visible in Sun Belt metropolitan construction pipelines.
Smart Home As a Service Market Segmentation
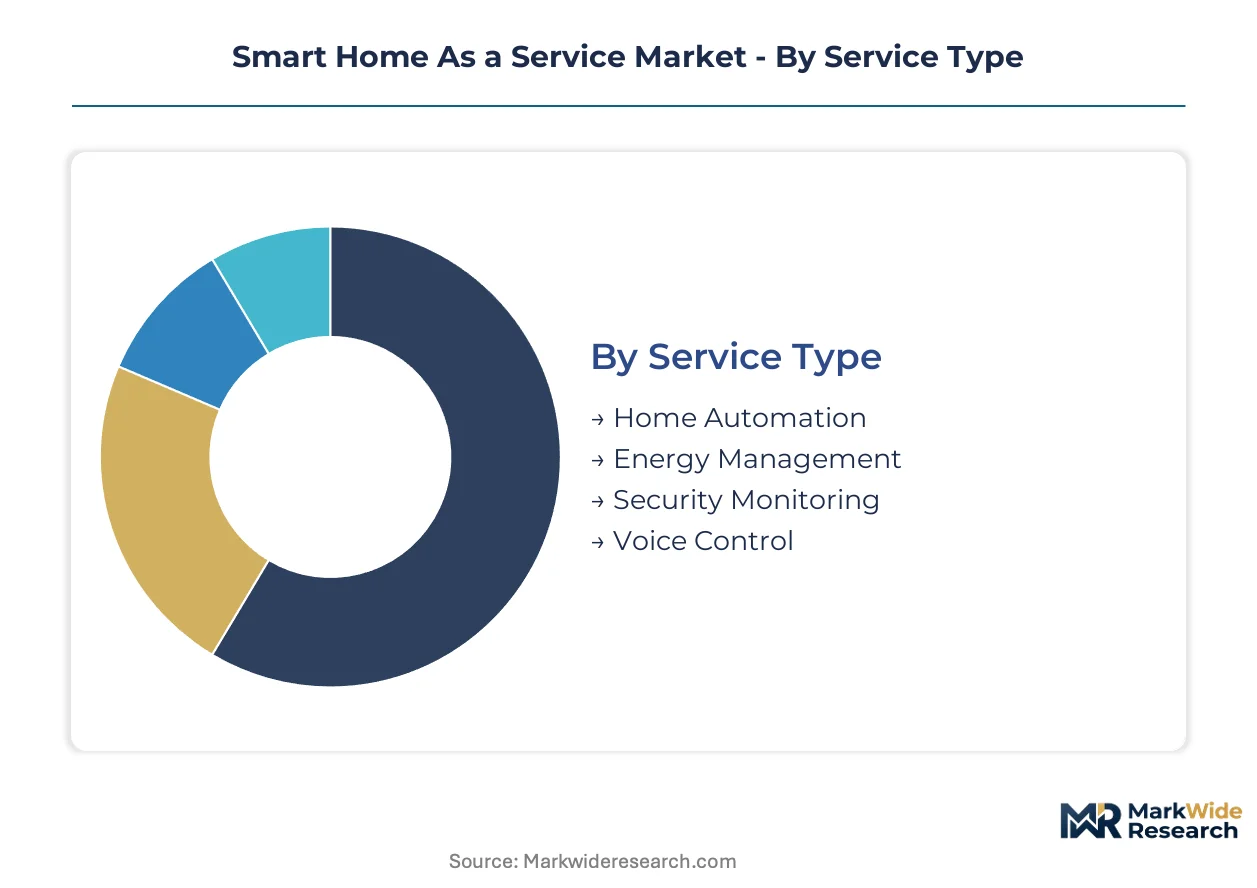
Smart Home As a Service providers structure pricing tiers and deployment economics around distinct operational bundles. Each segment carries different hardware refresh cycles, cloud compute intensity, and subscriber lifetime value profiles that reshape go-to-market priorities.
Service Type:
Capital intensity varies sharply across service bundles, with cloud infrastructure and professional monitoring networks demanding the heaviest upfront platform investment.
- Security Monitoring:Continuous video verification and emergency dispatch coordination require redundant data centers and UL-certified monitoring stations. Property and casualty underwriters in Texas and Florida now mandate professional monitoring for premium discounts, concentrating demand among risk-averse suburban homeowners.
- Energy Management:Dynamic pricing integration and utility backhaul connections demand API development and regulatory certification. California and New York public utility commissions qualify only interoperable platforms for demand-response rebates, accelerating thermostats-as-a-service attachment in deregulated electricity markets.
- Home Automation:Scene programming and cross-device orchestration rely on cloud-native middleware with lower fixed-cost thresholds.
- Voice Control:Natural language processing licenses and wake-word detection modules add per-subscriber variable costs rather than capital intensity.
Security Monitoring absorbs the bulk of installed capacity; Energy Management is expanding most quickly.
Device Type:
Margin capture diverges based on data monetization potential and replacement frequency rather than unit economics alone.
- Smart Cameras:Tiered cloud storage subscriptions and AI-enhanced analytics upsells generate recurring revenue multiples exceeding hardware cost. Multifamily developers in Sun Belt metropolitan pipelines now mandate pre-installed camera networks as lease differentiation tools.
- Smart Thermostats:Quantifiable utility bill reductions drive the shortest payback periods and highest standalone attachment rates. State rebate programs in California and New York accelerate procurement through point-of-sale incentives.
- Smart Locks:Access credential management and temporary key generation serve property manager workflows more than resident convenience.
- Smart Lights:Color tuning and circadian scheduling add marginal utility with limited standalone pricing power.
Smart Cameras command the deepest recurring revenue pools; Smart Thermostats show the steepest expansion trajectory.
Consumer Segment:
Procurement authority concentration determines sales cycle length and contract structure complexity across end-use environments.
- Residential:Individual homeowner decision-making demands retail channel support and consumer financing partnerships. Insurance premium discount frameworks in Texas and Florida accelerate conversion from device ownership to managed service models.
- Rental:Lease-embedded automation bundles eliminate individual sales friction through property technology platforms. Greystar, AvalonBay, and Equity Residential now mandate standardized automation stacks across portfolios, consolidating procurement authority among institutional multifamily owners.
- Hospitality:Guest experience standardization and operational efficiency drive brand-level technology mandates.
- Senior Living:Fall detection and medication adherence sensors converge with Medicare Advantage supplemental benefit structures.
Rental channels absorb the bulk of net new subscriber additions; Senior Living is climbing the fastest as reimbursement-funded categories mature.
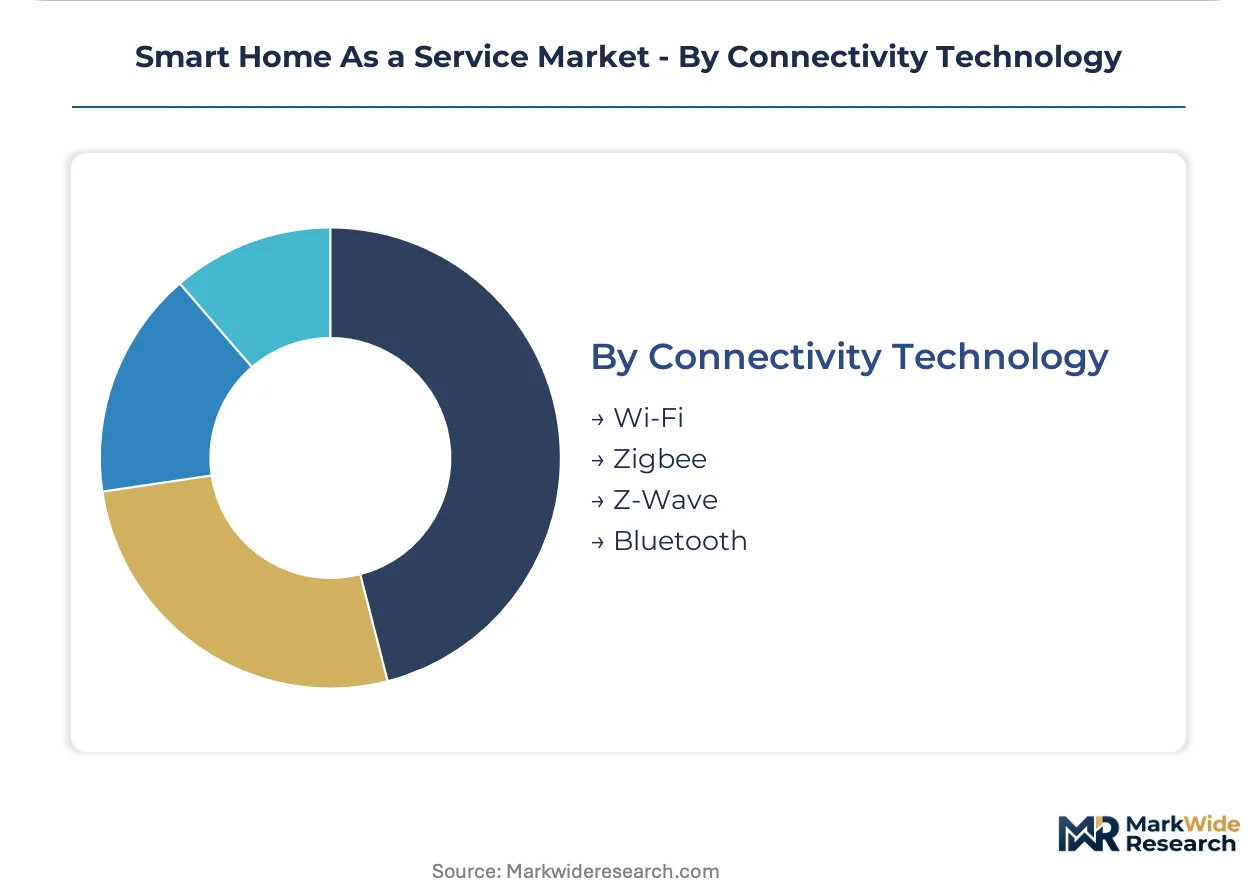
Connectivity Technology:
Spectrum licensing and gateway hardware requirements shape operator margin structures and interoperability investments.
- Z-Wave:Sub-GHz mesh networking penetrates building materials with minimal power draw, extending battery life for door and window sensors. FCC spectrum allocation governs protocol deployment across United States residential installations.
- Zigbee:2.4 GHz global standardization reduces regional SKU complexity for hardware vendors. Thread protocol convergence through Matter certification is collapsing proprietary gateway requirements.
- Wi-Fi:Ubiquitous infrastructure availability eliminates dedicated gateway costs but increases power consumption and congestion exposure.
- Bluetooth:Proximity-based commissioning and temporary device pairing serve onboarding workflows rather than persistent connectivity.
Z-Wave carries the bulk of legacy installed base; Zigbee is gaining share fastest through Matter protocol standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Broadband infrastructure density anchors geographic penetration patterns for managed home automation services. Utility rebate programs and insurance regulatory frameworks concentrate demand in markets with deregulated energy pricing and mature property-casualty underwriting.
United States
FCC broadband infrastructure investments expand minimum 25 Mbps connectivity to underserved census tracts, enabling cloud-managed device networks. State public utility commissions in California and New York mandate interoperable energy data standards for demand-response program participation. Sun Belt metropolitan construction pipelines concentrate multifamily developer procurement authority among institutional owners like Greystar and AvalonBay.
Germany
The EU Energy Performance of Buildings Directive mandates smart readiness indicators for residential construction, creating regulatory pull for pre-installed energy management services. Federal Network Agency spectrum allocation governs Z-Wave and Zigbee protocol deployment across residential installations. Industrial clusters in Bavaria and Baden-Württemberg host hardware manufacturing and systems integration capabilities for European market supply.
United Kingdom
Ofcom broadband universal service obligations accelerate connectivity-dependent service penetration in suburban and rural postcodes. The Financial Conduct Authority monitors subscription billing transparency for recurring home automation contracts. Greater London and Southeast England concentrate property technology procurement officers at institutional build-to-rent operators.
Japan
METI energy efficiency standards for residential buildings accelerate thermostats-as-a-service attachment through utility partnership programs. Ministry of Internal Affairs and Communications spectrum licensing governs low-power wide-area network deployment for sensor mesh networks. Kanto and Kansai metropolitan areas concentrate aging-population demand for fall detection and medication adherence sensor integration with healthcare reimbursement structures.
Australia
ACCC broadband performance monitoring and regional connectivity programs expand addressable market for bandwidth-intensive video analytics services. State-level energy efficiency schemes in New South Wales and Victoria qualify managed platforms for demand-response rebates. Sydney and Melbourne metropolitan construction pipelines concentrate multifamily developer activity for lease-embedded automation bundles.
Smart Home As a Service Market Competitive Environment
Strategic partnership formation dominates the current landscape as service operators seek to reduce third-party dependency and expand addressable channels. The vendor base clusters around three tiers: vertically integrated installation networks, broadband-centric platform layers, and security-monitoring infrastructure operators. Two strategic archetypes have emerged: providers bundling professional monitoring into broader automation stacks, and telecommunications incumbents extending subscriber relationships into home technology management. Dominant competitive moves include multifamily developer channel penetration and edge AI inference migration to residential gateways.
Within the security-monitoring tier, ADT Inc. and Vivint Smart Home, Inc. exemplify vertically integrated service models that combine professional installation with recurring revenue capture. Comcast Corporation occupies a position among broadband-centric platform operators, leveraging existing subscriber relationships to layer automation services without dedicated hardware sales friction. These three entities represent contrasting approaches to customer acquisition economics and device lifecycle risk transfer.
| Leading Market Players |
|---|
| ADT Inc. |
| Vivint Smart Home, Inc. |
| Comcast Corporation |
| Alarm.com Holdings, Inc. |
| Johnson Controls International PLC |
| Control4 Corp. |
| Charter Communications, Inc. |
| Telus International |
| Lumen Technologies, Inc. |
| Others |
Value Chain & Pricing Dynamics
Memory chip spot prices and silicon wafer contract indices cascade through gateway hardware costs into subscription tiering, compressing margins for operators without captive semiconductor sourcing while rewarding vertically integrated platforms with pricing flexibility across premium monitoring bundles.
Pricing Analysis
Warranty and professional monitoring bundling separates premium tiers from unbundled economy offerings, with UL-certified dispatch services and extended hardware replacement guarantees commanding substantial subscription uplifts. Three-tier pricing structure across premium, standard, and economy levels reflects installation complexity, cloud storage allocation, and AI analytics depth. Cost compression in the economy segment is intensifying because Matter protocol standardization collapses proprietary gateway lock-in. Individual homeowners exhibit highest price sensitivity, while institutional multifamily developers prioritize standardized stack compliance over per-unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Greystar and AvalonBay, bypassing retail distribution entirely for pre-installed automation stacks. Taiwan, South Korea, and China anchor semiconductor fabrication for 28nm and 40nm process nodes feeding camera and sensor production. Taiwan Semiconductor Manufacturing Company capacity constraints and Z-Wave silicon module shortages create single-source vulnerability for tier-two operators. Distribution runs through property technology platforms like Yardi and RealPage for multifamily channel penetration, with broadband carriers handling residential direct acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around recurring revenue capture, with FTC automatic renewal disclosure requirements and one-click cancellation mandates forcing weaker operators out through elevated customer acquisition cost recovery timelines.
For Market Incumbents: Cement gateway hardware control through backward integration into edge AI chip design, insulating against cloud infrastructure concentration risk from Amazon Web Services and Microsoft Azure. Expand enterprise account teams targeting Greystar and Equity Residential procurement officers before multifamily standardization locks out secondary vendors. Prioritize predictive churn algorithm investment to front-load profitability within shortened subscriber tenures mandated by Click-to-Cancel compliance.
For New Entrants and Emerging Players: Property technology platform partnerships offer the lowest-friction digital-channel route for bypassing individual sales cycles in the rental segment. Target senior living reimbursement-funded categories where Medicare Advantage supplemental benefit structures create white-space demand for fall detection and medication adherence sensors. Pursue utility backhaul certification in California and New York demand-response programs to qualify for point-of-sale rebate acceleration.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated installation networks with UL-certified monitoring stations and captive low-voltage technician workforces. Platforms combining professional monitoring infrastructure with broadband subscriber relationships demonstrate superior lifetime value economics over pure-play device vendors. Monitor NIST cybersecurity certification requirement evolution as the inflection indicator for liability migration from manufacturers to service operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Gateway Development | Residential inference migration reduces Amazon Web Services bandwidth dependency and cloud compute costs. |
| Matter Protocol Certification | Cross-ecosystem compatibility collapses proprietary lock-in protecting vertically integrated incumbents. |
| Multifamily Developer Partnership | Lease-embedded bundles through Yardi and RealPage convert apartment dwellers without individual sales friction. |
| Utility Backhaul Integration | California and New York demand-response qualification unlocks rebate-funded subscriber acquisition. |
| Cybersecurity Certification Investment | NIST compliance shifts breach liability protection from device manufacturers to managed service providers. |
Study Parameters
SEC 10-K filings, FCC broadband deployment reports, and utility commission regulatory dockets formed the secondary backbone, cross-referenced with primary interviews across smart home service operators, property technology procurement officers, low-voltage installation contractors, and cybersecurity compliance consultants. Bottom-up subscriber aggregation across service tiers and top-down addressable household penetration estimates were triangulated against broadband infrastructure density maps and multifamily construction pipeline data.
Bottom-up modeling tracked individual service provider subscriber disclosures and average revenue per user by tier, while top-down analysis calibrated against FCC connectivity thresholds and state-level utility rebate program qualification rates. Segmentation across service type, device attachment, consumer segment, and connectivity technology shaped volume and value outputs across the projection horizon. CAGRs were derived from installed base growth, churn-adjusted lifetime value, and hardware refresh cycle compression.
The model holds under stable broadband infrastructure investment continuity and regulatory rebate program persistence; deviation in semiconductor supply availability or FTC subscription enforcement intensity would shift forecast trajectories. Practitioners should monitor Taiwan Semiconductor Manufacturing Company capacity allocation and Matter protocol adoption curves for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
LED Packaging Market
Others
Water and Waste Water Treatment Chemicals Market
Others
Metal Ore Mining Market
Others
Hotel Wardrobe Market
Others
Brazil Lime Market
Others
Dandelion Market
Others
Brazil Cane Sugar Market
Others
Bird Food Market
Others
Ultra Mobile Devices (UMD) Market
Others
Global Application Testing Services Market
Others
Asia-Pacific Agricultural Enzymes Market
Others
Thermal Energy Flow Metering Solutions Market
Others
Fiber to the X (Fttx) Tester Market
Others
Cloud Digital Video Recorder Market
Others
Paper Shredder Market
Others
Smart TV Platforms Market