
 Global Laser Defense Eyewear Market | 2026-2036
Global Laser Defense Eyewear Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laser Defense Eyewear Market Foresight
The gap between premium military-grade systems and commoditized industrial eyewear is realigning procurement strategies across defense agencies. Gentex leverages its integrated helmet platform to sustain long-term contracts with North American armed forces. Honeywell International anchors its position through backward integration into optical coating supply chains. Metamaterial Technologies differentiates via advanced nano-structured filters that compete with legacy dye-based absorption lenses.
Laser defense eyewear comprises specialized optical systems engineered to attenuate coherent light across specific wavelength bands, typically achieving optical densities of OD 4 to OD 7 through multi-layer thin-film deposition or absorptive glass matrices. These devices protect ocular tissue from permanent retinal damage during directed-energy exposure in combat, industrial, or research environments. Helmet visors command the dominant share of military procurement value due to their integration with existing soldier modernization programs, while photochromic technologies represent the fastest-expanding segment as adaptive response times improve for variable threat environments. Anti-laser goggles retain mature demand within scientific research facilities where fixed-wavelength laboratory lasers dominate operational hazards.
ANSI Z136 standards in the United States, CE marking requirements under the EU MDR framework, and ISO 12312-1 specifications collectively shape product certification pathways and market access conditions for manufacturers. The U.S. FDA regulates medical claims for laser protective devices, while NATO standardization agreements harmonize military procurement specifications across allied defense ministries. Stakeholders must monitor evolving directed-energy weapon proliferation patterns to calibrate R&D investments against emerging wavelength threats rather than legacy laser profiles.
Market Dynamics
Directed-energy weapon proliferation across NATO member states is compressing procurement cycles for multi-wavelength protective systems while simultaneously tightening optical density certification thresholds.
Growth Catalysts
- ANSI Z136 Standard Revision:Tighter optical density certification requirements in the United States are forcing rapid filter technology upgrades across defense contractor supply chains.
- Helmet Platform Integration:NATO standardization agreements are mandating interoperable visor-helmet interfaces, driving bundled procurement of soldier modernization systems.
- Photochromic Response Acceleration:Sub-100 millisecond adaptive switching speeds in nano-structured metamaterials are opening variable-threat environment applications previously closed to fixed-filter designs.
Market Restraints
- Rare Earth Element Concentration:Chinese control over dysprosium and terbium supply chains creates input cost volatility for high-performance optical coating deposition.
- Dual-Use Export Control Friction:ITAR restrictions and EU dual-use regulations impose licensing delays on cross-border shipments of military-grade filtering systems.
- Absorptive Glass Substitution Ceiling:Legacy dye-impregnated glass matrices retain cost advantages in fixed-wavelength laboratory settings, limiting premium filter penetration in scientific research verticals.
Strategic Opportunities
- Japan Maritime Self-Defense Force Modernization:Underpenetrated procurement channels in Tokyo's directed-energy defense programs offer first-mover positioning for compliant suppliers.
- AI-Integrated Threat Detection:Convergence of spectroscopic sensors with adaptive eyewear is creating autonomous wavelength-switching systems for unpredictable combat environments.
- EU MDR Streamlined Pathway:CE marking harmonization for personal protective equipment is reducing certification duplication costs across European defense and industrial markets.
Industry Challenges
- Thin-Film Deposition Talent Scarcity:Specialized vacuum coating engineers command premium compensation, constraining production scale-up for multi-layer optical stack manufacturers.
- NATO Standardization Agreement Lag:STANAG harmonization timelines for laser threat wavelength profiles trail actual directed-energy weapon deployment, creating specification mismatches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laser Defense Eyewear Market |
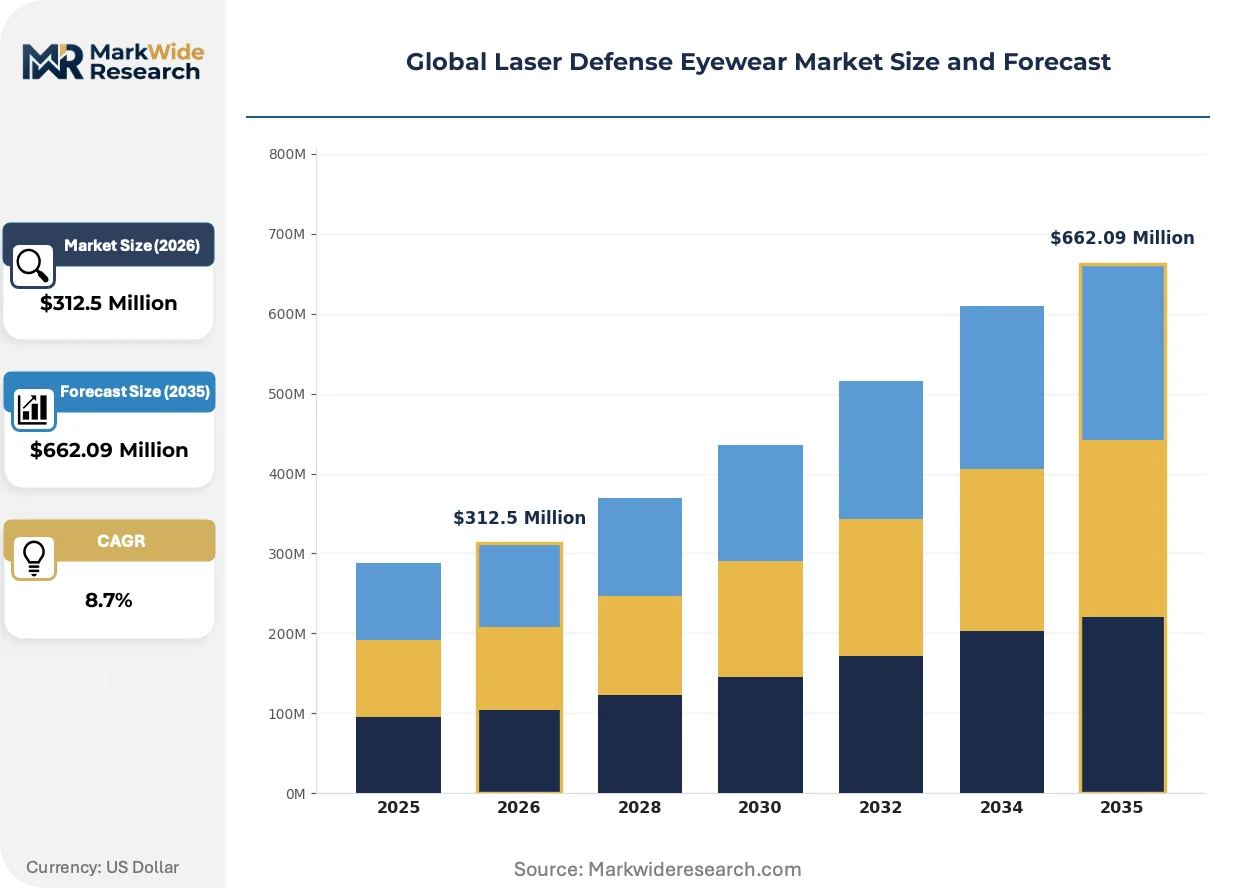
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-laser Goggles, Protective Spectacles, Helmet Visors, Overlays, Face Shields Technology: Optical Filtering, Photochromic, Anti-reflective Coating, Polarized Lenses, Multi-layer Coating Application: Military Combat, Security Operations, Industrial Safety, Scientific Research, Aerospace Maintenance End User: Armed Forces, Law Enforcement, Manufacturing Plants, Research Facilities, Aviation Crew |
| Companies Covered | Honeywell International, Gentex, ESS, Revision Military, Laser Safety Industries, NoIR LaserShields, PerriQuest, Metamaterial Technologies, uvex group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laser Defense Eyewear Market Shifts & Advancements
Active materials science breakthroughs are compressing the performance gap between fixed and adaptive optical protection, while regulatory convergence across defense procurement blocs is reshaping certification economics.
Metamaterial nano-structured filters is consolidating competitive positioning in the premium military segment. These engineered surfaces achieve wavelength-selective attenuation through subwavelength resonant elements rather than bulk absorption. United States Army and Marine Corps procurement offices are prioritizing metamaterial-enabled visors for next-generation soldier protection suites. The technology is consolidating supplier margins by eliminating dye-batch variability and enabling precise optical density tuning across threat bands.
EU MDR framework expansion into military-adjacent protective equipment is compressing certification timelines for dual-use optical products. The regulation's Annex XVI classification criteria now capture certain laser defense eyewear categories previously exempt from medical device scrutiny. German and French defense ministries are responding by pre-qualifying suppliers against harmonized EN standards, reducing per-contract compliance overhead. This shift most affects mid-tier industrial eyewear manufacturers seeking military contract diversification.
Integrated platform procurement is displacing standalone eyewear purchasing across NATO defense ministries. Buyers now specify helmet-visor-communications bundles rather than discrete protective devices, collapsing traditional supplier tiers. Tier-one integrators in the United States and United Kingdom are capturing value previously distributed across optical specialists. This pattern concentrates contract awards on firms with captive helmet platform capabilities, compressing opportunities for pure-play filter manufacturers.
Global Laser Defense Eyewear Market Segmentation
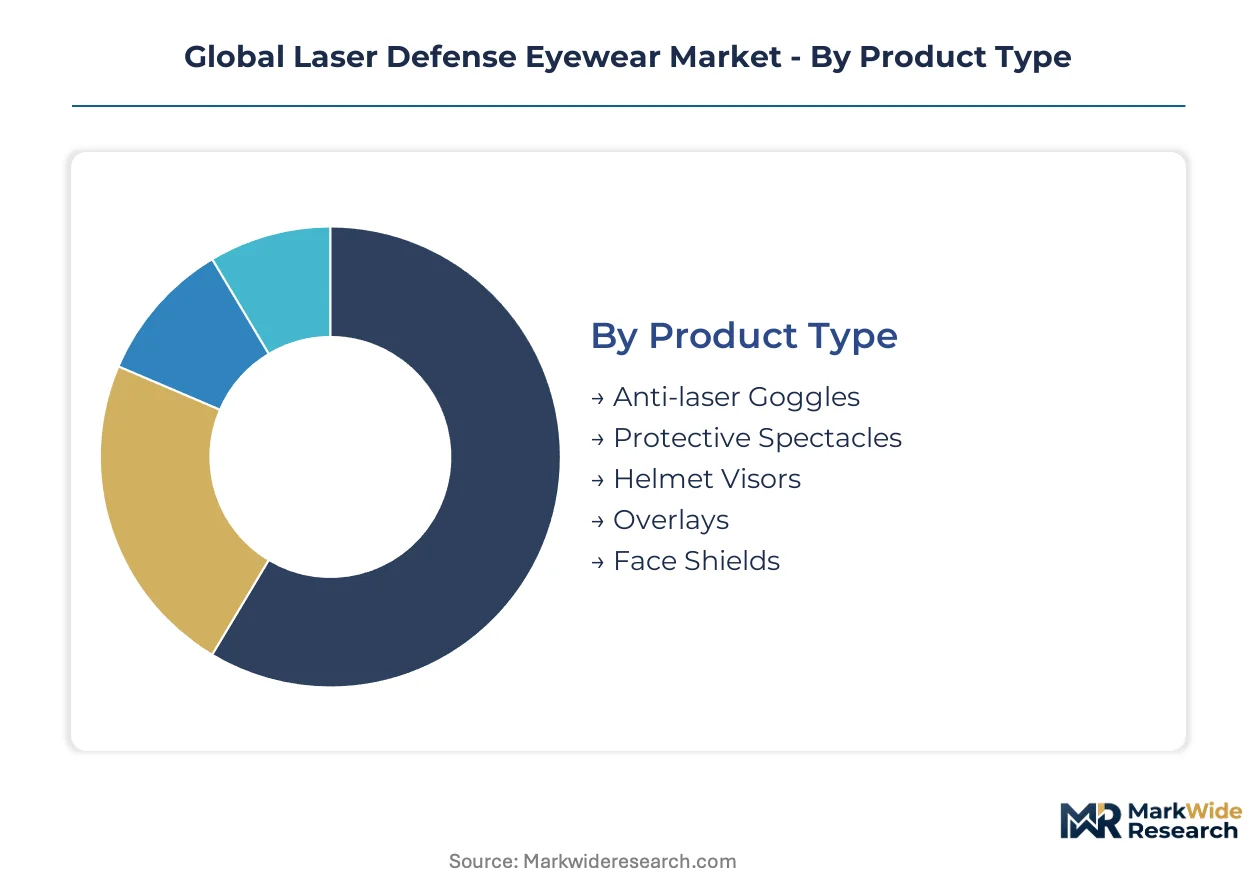
Laser defense eyewear procurement decisions hinge on threat wavelength specificity, platform integration requirements, and operational mobility constraints. Segmentation reveals how military modernization programs concentrate value in integrated helmet systems while industrial and research verticals sustain demand for discrete protective devices.
Product Type:
Military procurement officers prioritize platform compatibility over unit cost when selecting protective form factors.
- Helmet Visors:Multi-layer thin-film deposition systems achieving OD 6+ optical density across 400-1400nm threat bands. United States Army and Marine Corps modernization programs bundle these with communications suites, capturing the dominant procurement value share in North American defense budgets.
- Anti-laser Goggles:Self-contained absorptive glass or dye-impregnated polymer matrices delivering fixed-wavelength protection. German and French research facilities sustain mature demand for laboratory-grade units where laser wavelengths are predetermined and mobility requirements are minimal.
- Protective Spectacles:Lightweight polycarbonate frames with clip-on filter inserts for industrial maintenance crews.
- Overlays:Adhesive film layers applied to existing prescription eyewear for secondary protection.
- Face Shields:Full-coverage polycarbonate systems for high-power industrial laser cutting operations.
Volume sits with Anti-laser Goggles; growth tilts toward Helmet Visors.
Technology:
Adaptive response capabilities now determine premium positioning against legacy fixed-filter alternatives.
- Photochromic:Nano-structured metamaterials achieving sub-100 millisecond switching speeds between transparent and protective states. Japan Maritime Self-Defense Force evaluation programs are testing these for variable-threat maritime environments where laser sources remain unidentified until engagement.
- Optical Filtering:Discrete wavelength-selective coatings deposited via electron-beam evaporation onto glass or ceramic substrates. NATO standardization agreements mandate specific optical density thresholds that favor established suppliers with certified deposition chambers.
- Multi-layer Coating:Alternating high-low index dielectric stacks for broadband attenuation.
- Anti-reflective Coating:Surface treatments reducing glare-induced visual fatigue during extended wear.
- Polarized Lenses:Orientation-dependent filtering for specific coherent light polarization states.
Optical Filtering commands current procurement volume; Photochromic systems are climbing the fastest as threat detection latency compresses.
Application:
Operational environment severity dictates certification grade and corresponding price tier acceptance.
- Military Combat:Integrated soldier protection systems requiring STANAG-compliant interoperability across NATO allied forces. United Kingdom Ministry of Defence procurement bundles specify helmet-visor-communications integration, collapsing standalone eyewear purchasing channels.
- Industrial Safety:ANSI Z136.1-certified devices for manufacturing environments with fixed or scanning laser equipment. OSHA enforcement patterns in United States metal fabrication plants drive replacement cycles for damaged or outdated protective equipment.
- Security Operations:Covert-wearable designs for law enforcement laser threat scenarios.
- Scientific Research:Laboratory-specific filtering matched to institutional laser inventory.
- Aerospace Maintenance:Ground crew protection during aircraft rangefinder and targeting system testing.
Military Combat absorbs the premium pricing tier; Industrial Safety generates the highest unit volume through recurring replacement schedules.
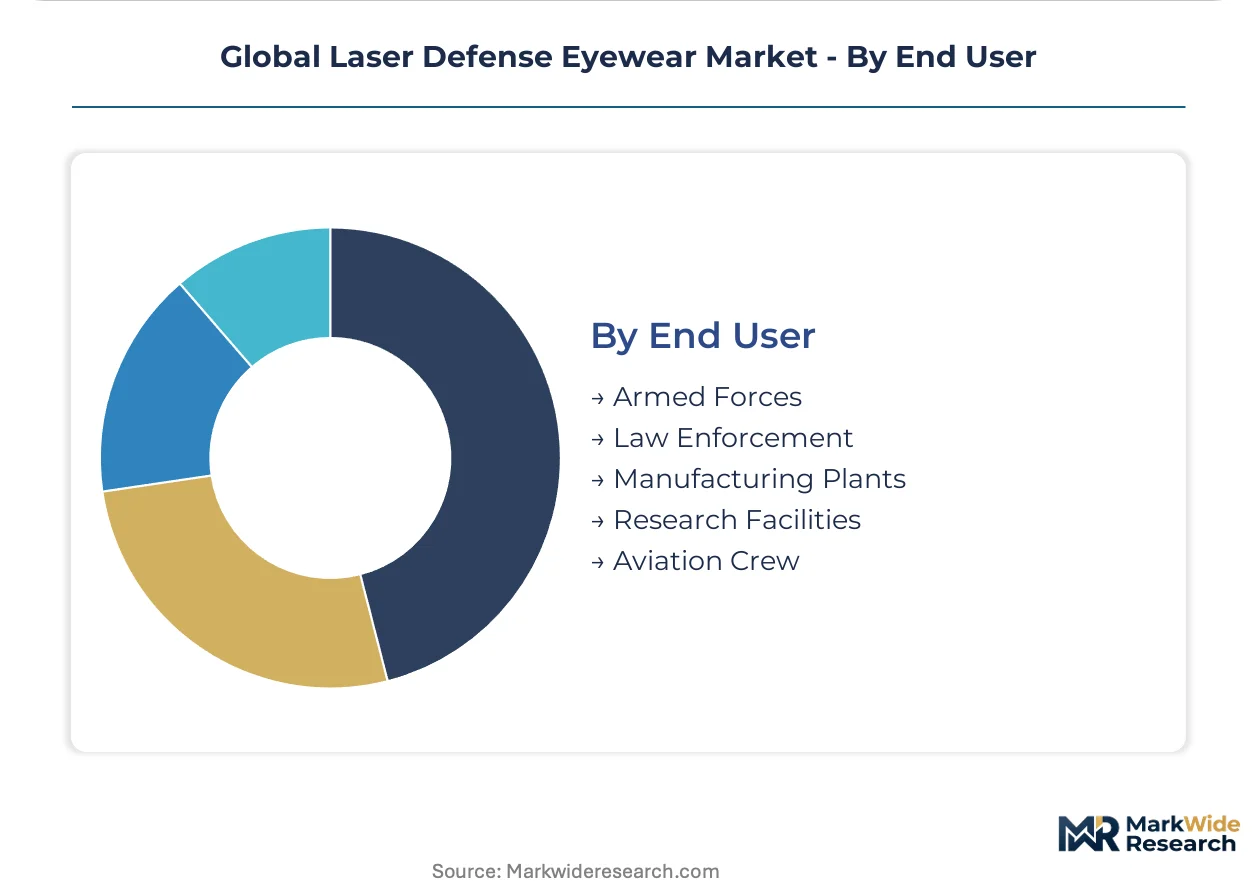
End User:
Budget authority centralization versus distributed purchasing determines supplier access and contract structure.
- Armed Forces:Centralized defense ministry procurement with multi-year framework agreements and technical qualification requirements. United States Department of Defense primes negotiate sole-source or limited-competition awards for helmet platform integration.
- Law Enforcement:Agency-level purchasing with municipal budget constraints favoring mid-tier certified products. German federal police procurement offices balance cost controls against CE marking requirements under EU MDR expansion.
- Manufacturing Plants:Facility safety managers with discretionary procurement authority.
- Research Facilities:Principal investigator-driven purchasing for laboratory-specific wavelength matching.
- Aviation Crew:Airline and military aviation ground operations with mixed threat exposure profiles.
Armed Forces concentrate contract value; Manufacturing Plants distribute demand across fragmented supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Washington D.C. anchors defense procurement concentration for laser protective systems, with Pentagon modernization budgets directing helmet-visor integration contracts toward integrated platform suppliers. Military R&D corridors in Boston and San Diego sustain adjacent innovation ecosystems for optical coating deposition and metamaterial filter development.
United States
Department of Defense sole-source awards for soldier protection systems concentrate contract value with helmet platform integrators. FDA oversight of medical device claims intersects with ITAR restrictions on military-grade optical exports, creating dual compliance burdens for suppliers. Boston's Route 128 technology corridor hosts thin-film deposition specialists serving prime defense contractors with certified optical stack production.
Germany
Bundeswehr modernization programs under NATO standardization agreements drive demand for STANAG-compliant visor-helmet interfaces. EU MDR Annex XVI classification for military-adjacent protective equipment compresses certification timelines through harmonized EN standards. Munich's precision optics cluster supplies electron-beam evaporation chambers to defense contractors across European allied forces.
Japan
Japan Maritime Self-Defense Force directed-energy defense programs are evaluating photochromic metamaterials for variable-threat maritime environments. METI industrial technology grants support domestic nano-structured filter development to reduce rare earth element import dependency. Yokohama's materials science corridor hosts research consortia testing sub-100 millisecond adaptive switching speeds.
United Kingdom
Ministry of Defence procurement bundles specify helmet-visor-communications integration, eliminating standalone eyewear purchasing channels. UK defense industrial strategy prioritizes sovereign capability in optical coating supply chains through strategic supplier partnerships. Bristol's aerospace and defense cluster concentrates systems integration expertise for NATO interoperability compliance.
France
Direction Générale de l'Armement pre-qualifies suppliers against harmonized EN standards to reduce per-contract compliance overhead. ANSM oversight of medical device claims affects dual-use products crossing into civilian laboratory markets. Paris-Saclay research cluster advances nano-structured filter architectures for next-generation soldier protection suites.
Global Laser Defense Eyewear Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification grade and platform integration depth, with contract structure favoring captive helmet system suppliers over standalone filter manufacturers. The vendor base organizes into three tiers: integrated platform providers with sole-source defense relationships, optical coating specialists with certified deposition capabilities, and industrial safety distributors serving fragmented manufacturing demand. Dominant competitive moves include backward integration into rare earth supply chains and strategic partnerships with helmet system primes to secure bundled procurement positions.
Within the integrated platform tier, Gentex and Honeywell International exemplify archetype positioning through captive helmet system capabilities and long-term defense ministry relationships. Metamaterial Technologies occupies a position among advanced materials specialists competing on nano-structured filter differentiation against legacy dye-based alternatives. These three anchors illustrate how supplier margins concentrate with platform integration depth and optical density certification thresholds.
| Leading Market Players |
|---|
| Honeywell International |
| Gentex |
| ESS |
| Revision Military |
| Laser Safety Industries |
| NoIR LaserShields |
| PerriQuest |
| Metamaterial Technologies |
| uvex group |
| Others |
Supply & Pricing Matrix
Rare earth element feedstocks—particularly dysprosium and terbium for high-index optical coatings—flow from Chinese mining operations through Japanese refining corridors before reaching thin-film deposition chambers in United States and German defense contractor facilities. This upstream concentration translates into tiered pricing structures downstream, where helmet-integrated visor systems command substantial premiums over discrete protective eyewear for industrial buyers.
Pricing Analysis
Value-based pricing anchored to optical density certification thresholds separates military-grade OD 6+ systems from ANSI Z136.1-compliant industrial alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and platform integration depth. Cost compression in the industrial tier is intensifying because legacy dye-impregnated glass matrices retain cost advantages for fixed-wavelength laboratory settings. Manufacturing plant safety managers exhibit highest price sensitivity, while United States Department of Defense procurement officers prioritize performance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale defense ministry demand, while industrial distributors serve fragmented manufacturing plant procurement. Geographic supply concentration centers on China for rare earth element extraction, Japan for precision optical substrate fabrication, and the United States for thin-film deposition equipment. Raw material dependencies include dysprosium oxide, terbium metal, and electron-beam evaporation chamber components. Single-source vulnerability in Chinese rare earth processing creates structural risk for coating cost stability. Distribution runs through defense prime contractors for military segments and safety equipment distributors for industrial verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-film deposition engineer scarcity props pricing for certified optical stack production, constraining scale-up capacity across multi-layer filter manufacturers. This supply-constrained dynamic favors incumbents with captive talent pipelines and certified deposition infrastructure.
For Market Incumbents: Deploy backward integration into rare earth supply chains to dampen input cost volatility from Chinese concentrate markets. Incumbents should deepen certification investments against tightening ANSI Z136 optical density thresholds to maintain sole-source positioning with United States Army and Marine Corps procurement offices. Absorptive glass substitution in scientific research verticals poses margin pressure for premium filter portfolios. For New Entrants and Emerging Players: Begin with Japan Maritime Self-Defense Force photochromic metamaterial evaluation programs, where first-mover positioning remains available for compliant suppliers. White-space targets include AI-integrated threat detection convergence and EU MDR streamlined CE marking pathways for dual-use products. A direct engagement model with Tokyo's defense procurement channels offers the most penetrable entry vector. For Investors and Strategic Acquirers: Sub-100 millisecond photochromic switching speed demonstrations in Yokohama materials science consortia are the leading indicator that adaptive filter technologies will displace fixed-filter architectures in next-generation soldier protection suites. Long-term viability rests on platform integration capabilities rather than standalone filter manufacturing. Acquisition targets should emphasize helmet system integrators with NATO STANAG-compliant visor interfaces. Thin-film deposition talent scarcity signals capacity-constrained pricing power for certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Supply | Reduces dysprosium cost volatility for United States defense contractors. |
| Photochromic Metamaterial Scale-Up | Captures Japan Maritime Self-Defense Force variable-threat environment contracts. |
| Helmet Platform Integration Partnership | Locks in NATO bundled procurement through visor-helmet interoperability. |
| EU MDR CE Marking Pre-Qualification | Compresses German and French defense ministry compliance timelines. |
| AI-Integrated Threat Detection R&D | Opens autonomous wavelength-switching applications for unpredictable combat environments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with thin-film deposition engineers, defense procurement officers, optical coating R&D directors, and industrial safety equipment distributors combined with secondary validation from FDA 510(k) filings, NATO standardization agreement documents, and EU MDR Annex XVI classification records. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume estimates across the analysis window.
Product type, technology, application, and end-user dimensions were modeled at granular levels to capture procurement pattern variation between military and industrial verticals. CAGRs were derived from segment-level growth trajectory analysis. Forecast inputs incorporated directed-energy weapon proliferation timelines, ANSI Z136 standard revision schedules, and rare earth element supply chain stability indicators throughout the projection horizon.
Underlying measurement precision varies by segment; military combat and helmet visor categories carry tighter precision than scientific research and protective spectacles due to consolidated procurement data availability. Forecasts reflect documented assumptions regarding NATO modernization budget trajectories and photochromic technology maturation curves. Periodic stress-testing of base assumptions is recommended against directed-energy weapon deployment patterns and rare earth export restriction scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
North America Printed Signage Market
Others
Japan Smart Home Market
Others
Rugged Devices Market
Others
Coconut Activated Carbon Market
Others
Gesture Recognition for Smart TV Market
Others
Global Emergency Spill Response Market
Others
Architectural Fabrics Market
Others
Global Digital Caliper Market
Others
Free Space Optics (FSO) Market
Others
Mexico 3D Printing Construction Market
Others
Dried Egg Market
Others
Cloud DVR Market
Others
Hypermarket Market
Others
United States Smart Homes Market
Others
Telecom Transformers Market
Others
Bitcoin Mining Hardware Market