
 Foam Engraving Machines Market | 2026-2036
Foam Engraving Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Engraving Machines Market Insights
The EU Green Deal is realigning foam processing standards across European manufacturing, compelling machinery upgrades that reduce chemical waste and energy intensity. Universal Laser Systems leverages its laser platform specialization to serve high-precision signage and prototyping workflows. AXYZ anchors its position through integrated CNC routing systems that span furniture and packaging applications. MultiCam competes with configurable gantry systems that handle diverse foam densities across industrial and commercial end uses.
Foam engraving machines employ computer-controlled cutting heads—laser, mechanical, or ultrasonic—to shape expanded polystyrene, polyurethane, and polyethylene foam blocks with dimensional tolerances often below 0.1 millimeters, serving applications from protective packaging inserts to architectural display models. CNC Foam Engraving dominates current equipment installations due to proven reliability in high-volume manufacturing environments, while Laser Foam Engraving captures expanding share in design studios and model-making workshops where edge quality and detail resolution command premium positioning. Ultrasonic Foam Engraving remains nascent but attracts R&D investment for specialized medical and electronics packaging where thermal damage must be eliminated.
REACH and RoHS frameworks in Europe restrict hazardous substances in foam substrates and mandate material traceability, directly influencing machine design for fume extraction and waste containment. The EPA regulates volatile organic compound emissions from laser and hot-wire processes in US manufacturing facilities, shaping local equipment specification standards. OSHA workplace exposure limits for respirable foam particulate drive dust collection integration requirements across industrial installations. Stakeholders must monitor evolving chemical compliance timelines and evaluate whether ultrasonic or mechanical platforms offer durable regulatory hedge against tightening emission controls.
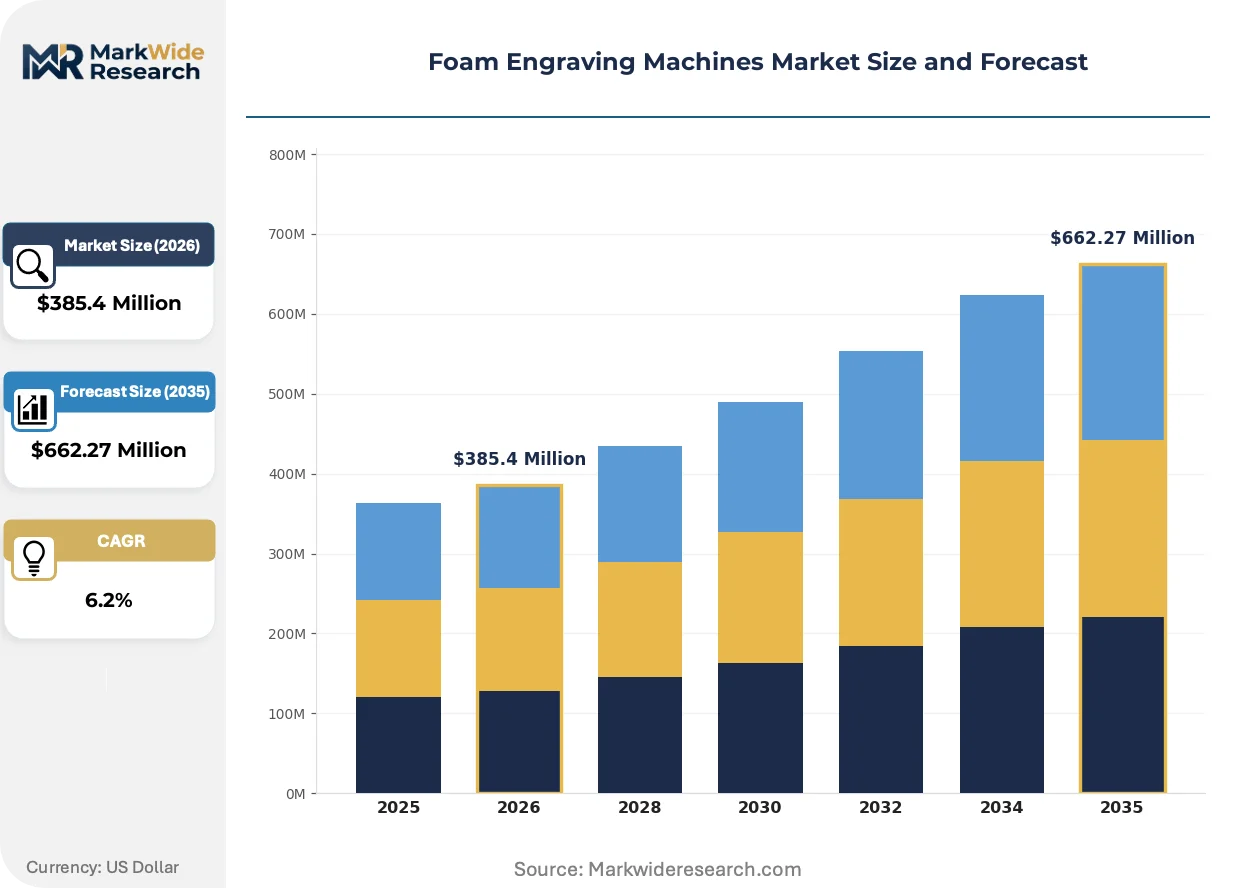
Market Dynamics
Packaging automation mandates across German automotive suppliers and Chinese electronics exporters are forcing simultaneous equipment replacement cycles, compressing traditional seven-year machine lifecycles into four-year upgrade windows and reshaping vendor financing structures.
Growth Catalysts
- REACH chemical compliance:European ECHA enforcement of substrate traceability rules elevates specification requirements for fume extraction systems, compelling machinery upgrades across French and Italian packaging facilities.
- Protective packaging densification:Semiconductor logistics hubs in Taiwan and South Korea demand higher-precision foam inserts for wafer transport, pulling ultrasonic engraving R&D investment from medical device specialists.
- Laser platform maturation:Fiber laser reliability improvements above 10,000-hour maintenance intervals reduce total cost of ownership calculations for US signage studios and architectural model shops.
Market Restraints
- Copper and rare-earth magnet volatility:Servo motor and laser source input costs fluctuate with Chinese export quota adjustments, pressuring mid-tier machine builder margins.
- Technical limitation in closed-cell foams:Polyethylene density above 45 kg/m³ produces inconsistent kerf quality across mechanical routing platforms, restricting addressable substrate range.
- Substitution threat from molded pulp:Amazon and IKEA packaging mandates favor fiber-based protective formats in e-commerce fulfillment, eroding expandable polystyrene insert volumes.
Strategic Opportunities
- Underpenetrated Mexican automotive cluster:Querétaro and Guanajuato seat manufacturing expansion lacks localized foam engraving service infrastructure, creating equipment placement openings for integrated CNC-laser hybrid systems.
- EU Green Deal retrofit mandates:Energy intensity thresholds for industrial machinery qualify foam engraving equipment upgrades for subsidized financing through national recovery funds in Spain and Poland.
- Technology convergence of AI vision and ultrasonic cutting:Real-time density mapping enables adaptive amplitude control for medical packaging applications requiring zero thermal damage zones.
Industry Challenges
- Multi-axis programming skill scarcity:CAM software proficiency for simultaneous five-axis foam machining concentrates in German and Japanese technical institutes, constraining workforce expansion in emerging manufacturing hubs.
- CE-MDR dual certification timelines:Medical device packaging equipment requires parallel machinery directive and medical device regulation approvals, extending time-to-revenue for European market entry by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Engraving Machines Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CNC Foam Engraving, Laser Foam Engraving, Ultrasonic Foam Engraving, Mechanical Foam Engraving Technology: Laser Beam, Ultrasonic Wave, Mechanical Cutting, Computer Numerical Control Application: Packaging Industry, Furniture Manufacturing, Prototype Modeling, Signage Crafting, Custom Decorations End User: Manufacturing Facilities, Design Studios, Advertising Agencies, Educational Institutions, Model Makers |
| Companies Covered | Universal Laser Systems, AXYZ, MultiCam, Hotwire Direct, Techno CNC, Foamlinx, Jinan Style Machinery, Gravotech, Trotec Laser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Engraving Machines Market Trends and Innovations
Equipment architecture is bifurcating between high-throughput gantry systems for automotive and appliance packaging and compact benchtop units for design studios, with software-defined toolpath optimization becoming the primary differentiation vector.
Hybrid laser-mechanical platforms are consolidating control architectures across previously separate workflow stages. Signage producers in California and Texas adopt these systems to collapse prototyping-to-production handoffs from three machines to one. The resulting footprint reduction is consolidating supplier relationships toward single-vendor service agreements.
EPA volatile organic compound enforcement under Clean Air Act Title V is tightening emission permits for hot-wire and laser foam cutting in Ohio and Michigan manufacturing corridors. Facility operators face quarterly stack testing requirements, accelerating migration to enclosed fume extraction systems with activated carbon filtration. Machine specification standards in these states now prioritize containment over raw cutting speed.
Equipment-as-a-service contracting is displacing capital purchase models among mid-volume packaging converters. Monthly per-hour fees bundle maintenance, software updates, and consumable provisioning, transferring obsolescence risk to OEMs. This restructuring concentrates most visibly in German Mittelstand firms and US contract packaging networks serving pharmaceutical distributors.
Foam Engraving Machines Market Segmentation
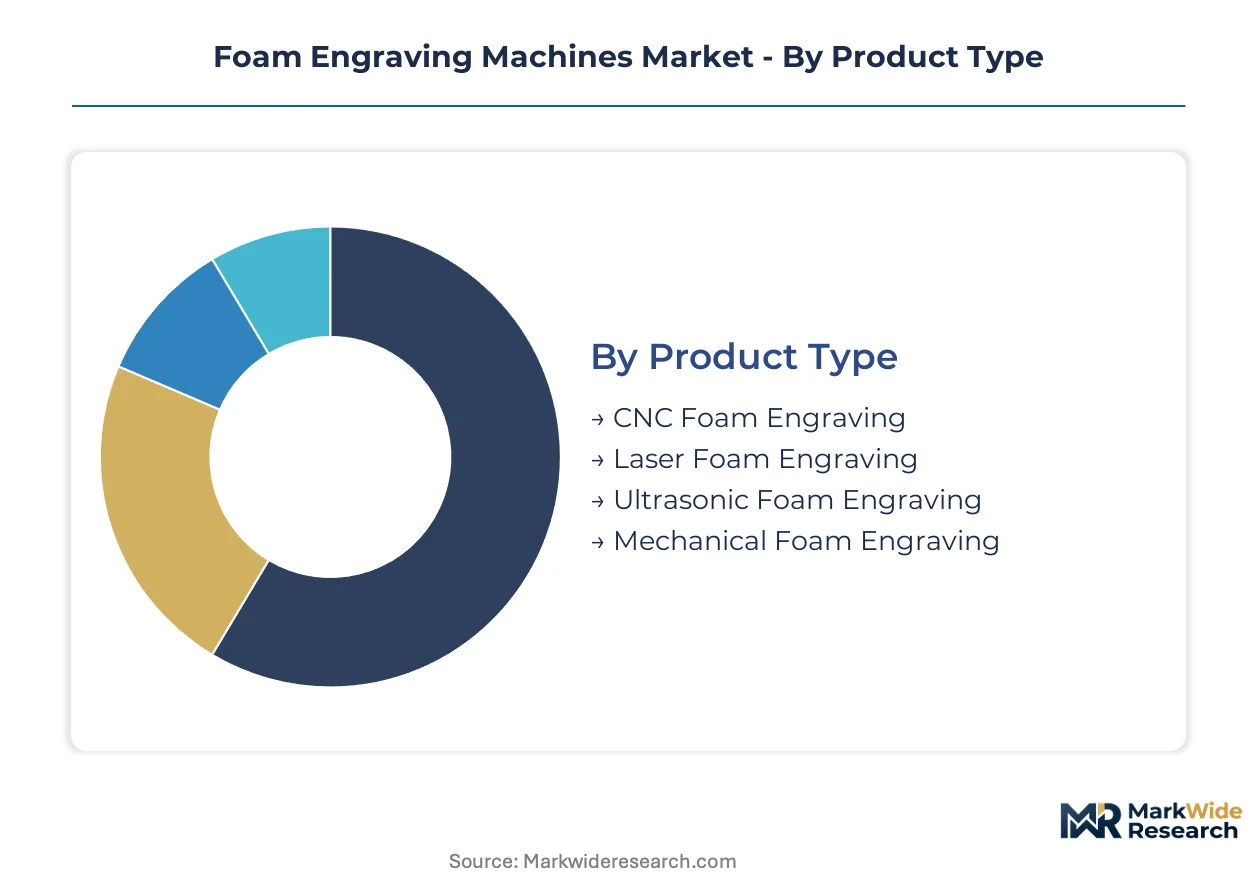
Segmentation reveals how equipment specification requirements diverge across foam density ranges, precision tolerances, and regulatory compliance tiers. Upgrade cycles compress from seven years to four years where automation mandates intersect with chemical compliance deadlines. Understanding these divides enables targeted positioning against replacement demand rather than greenfield installations.
Product Type:
Replacement cycles accelerate fastest where REACH substrate traceability and EPA emission enforcement overlap, forcing simultaneous hardware and extraction system upgrades.
- CNC Foam Engraving:Proven reliability in high-volume manufacturing environments with dimensional tolerances below 0.1 millimeters. German automotive suppliers and Chinese electronics exporters concentrate demand here as packaging automation mandates compress traditional machine lifecycles.
- Laser Foam Engraving:Fiber laser platforms now achieve maintenance intervals exceeding 10,000 hours, reducing total cost of ownership calculations. US signage studios in California and Texas adopt these systems where edge quality commands premium positioning in architectural model workflows.
- Ultrasonic Foam Engraving:Eliminates thermal damage for medical and electronics packaging applications. R&D investment pulls from Taiwanese semiconductor logistics hubs requiring zero-damage wafer transport inserts.
- Mechanical Foam Engraving:Routing platforms face kerf quality limitations above 45 kg/m³ polyethylene density. Mid-tier furniture manufacturers retain these systems where substrate range restrictions prove acceptable.
Volume placements concentrate in CNC Foam Engraving; the faster expansion belongs to Laser Foam Engraving.
Technology:
Cost tier stratification separates premium fiber laser sources from standardized mechanical cutting heads, with ultrasonic transducers occupying a narrow medical-specialist niche.
- Laser Beam:CO2 and fiber architectures dominate where fume extraction integration determines permit compliance. EPA Title V enforcement in Ohio and Michigan manufacturing corridors accelerates migration to enclosed carbon filtration systems.
- Computer Numerical Control:Multi-axis programming proficiency concentrates in German and Japanese technical institutes, constraining workforce expansion in emerging manufacturing hubs. CAM software capability gaps extend time-to-production for complex geometries.
- Ultrasonic Wave:Real-time density mapping enables adaptive amplitude control. Medical device packaging applications in South Korea and Taiwan drive convergence with AI vision systems.
- Mechanical Cutting:Hot-wire and routing platforms face volatile copper and rare-earth magnet input costs. Chinese export quota adjustments pressure mid-tier machine builder margins.
Customer procurement concentrates at the CNC-laser boundary; ultrasonic platforms are climbing the fastest as semiconductor logistics requirements tighten.
Application:
Application maturity separates established packaging automation from emerging prototype-to-production consolidation in design workflows.
- Packaging Industry:Protective insert demand from semiconductor logistics hubs in Taiwan and South Korea pulls precision requirements upward. Amazon and IKEA fiber-based mandates erode expandable polystyrene volumes in e-commerce fulfillment.
- Signage Crafting:Hybrid laser-mechanical platforms collapse prototyping-to-production handoffs from three machines to one. California and Texas producers consolidate supplier relationships toward single-vendor service agreements.
- Furniture Manufacturing:Integrated CNC routing systems span upholstery framing and decorative component production. Mexican automotive seat manufacturing expansion in Querétaro and Guanajuato lacks localized service infrastructure.
- Prototype Modeling:Architectural model shops prioritize edge resolution over throughput. Benchtop unit footprints suit studio environments where space constraints dominate.
- Custom Decorations:Niche demand from event production and retail display sectors. Seasonal volume fluctuations complicate equipment utilization planning.
Equipment-as-a-service contracting concentrates in Packaging Industry; Signage Crafting applications show steepest technology convergence trajectory.
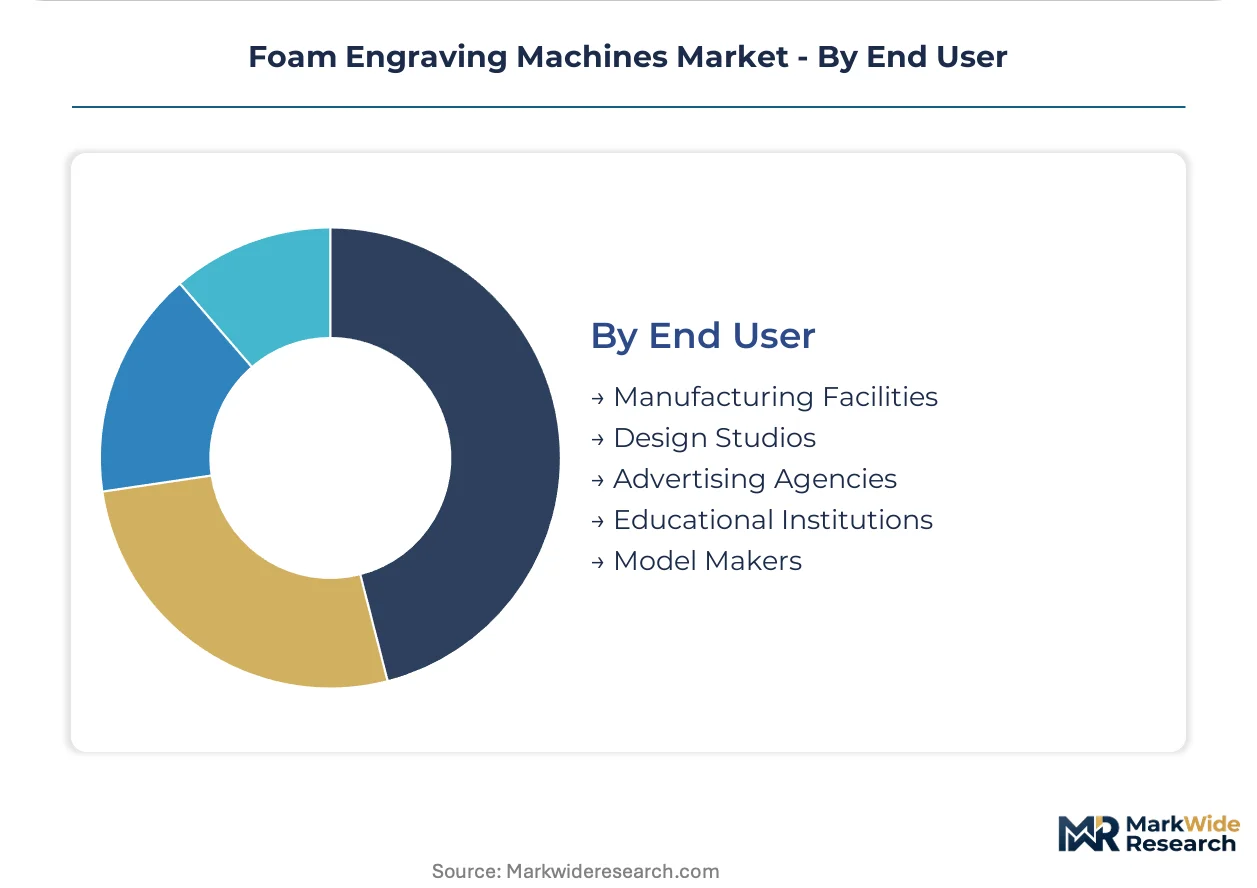
End User:
Customer type determines financing structure preference, with manufacturing facilities favoring capital purchase and creative studios accepting per-hour service fees.
- Manufacturing Facilities:German Mittelstand firms and US pharmaceutical contract packaging networks drive equipment-as-a-service adoption. Monthly bundles transfer obsolescence risk to OEMs while securing maintenance and consumable provisioning.
- Design Studios:Compact benchtop units with software-defined toolpath optimization serve prototyping workflows. California and Texas signage producers demand single-vendor relationships spanning hardware and control architecture.
- Model Makers:Precision tolerances for architectural and medical device prototypes command premium positioning. CE-MDR dual certification timelines extend European market entry by 14-18 months.
- Advertising Agencies:Campaign-driven demand cycles create utilization challenges. Equipment rental models suit project-based workflows.
- Educational Institutions:Training equipment purchases lag industrial specification curves. Curriculum alignment with CAM software proficiency gaps constrains graduate workforce readiness.
Service contract penetration concentrates in Manufacturing Facilities; Design Studios are expanding most quickly as hybrid platforms consolidate previously separate workflow stages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Machine builders in Germany and China supply the bulk of installed capacity, while demand concentrates in automotive clusters across the United States, Mexico, and Taiwan where packaging automation mandates drive replacement cycles.
United States
Signage studios in California and Texas consolidate supplier relationships around hybrid laser-mechanical platforms. EPA Clean Air Act Title V enforcement mandates quarterly stack testing for hot-wire and laser cutting in Ohio and Michigan manufacturing corridors. Equipment specification standards now prioritize enclosed fume extraction with activated carbon filtration over raw cutting speed.
Germany
Automotive suppliers compress traditional seven-year machine lifecycles into four-year upgrade windows under packaging automation mandates. EU Green Deal energy intensity thresholds qualify foam engraving equipment upgrades for subsidized financing through national recovery funds. Bavarian Mittelstand firms drive equipment-as-a-service contracting to transfer obsolescence risk to OEMs.
China
Electronics exporters in the Yangtze River Delta and Pearl River Delta demand simultaneous equipment replacement cycles. MIIT industrial upgrading programs accelerate CNC platform adoption in packaging facilities. Shenzhen and Dongguan logistics hubs pull precision foam insert demand from semiconductor wafer transport applications.
Mexico
Automotive seat manufacturing expansion in Querétaro and Guanajuato lacks localized foam engraving service infrastructure. Mexican federal manufacturing incentives support equipment placement for integrated CNC-laser hybrid systems. Monterrey and Tijuana industrial corridors attract vendor financing structures adapted from German and US contract packaging networks.
Taiwan
Semiconductor logistics hubs in Hsinchu and Tainan demand higher-precision foam inserts for wafer transport. Taiwanese environmental regulations align with REACH substrate traceability frameworks for medical device packaging applications. Kaohsiung packaging facilities pull ultrasonic engraving R&D investment to eliminate thermal damage zones.
Foam Engraving Machines Market Competitive Landscape
The competitive structure tilts toward technology-specialist archetypes with deep platform expertise rather than diversified industrial conglomerates. Vendor relationships concentrate around three strategic groupings: laser platform specialists, integrated CNC routing system providers, and configurable gantry system builders. Dominant competitive moves include hybrid technology convergence collapsing multi-machine workflows into single-platform solutions, and equipment-as-a-service contracting displacing capital purchase models among mid-volume packaging converters.
Among US-based laser platform specialists, Universal Laser Systems exemplifies the precision-signage and prototyping workflow archetype. AXYZ, a Canadian Co., Ltd. structure, anchors the integrated CNC routing tier spanning furniture and packaging applications. MultiCam occupies a position within the configurable gantry system segment, serving diverse foam densities across industrial and commercial end uses. These three represent distinct technology-commitment strategies rather than overlapping market positions.
| Leading Market Players |
|---|
| Universal Laser Systems |
| AXYZ |
| MultiCam |
| Hotwire Direct |
| Techno CNC |
| Foamlinx |
| Jinan Style Machinery |
| Gravotech |
| Trotec Laser |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in Germany and China anchor supply-side discipline through conservative capacity expansion and selective financing partnerships, translating into pricing power that resists commoditization even as input costs fluctuate. Their ownership structure limits private-equity-style margin extraction, preserving reinvestment capacity for extraction-system upgrades demanded by REACH and EPA enforcement.
Pricing Analysis
Cost-down pressure on mid-tier mechanical platforms accelerates because Chinese rare-earth export quotas inflate servo motor input costs, compressing builder margins unless passed through. Pricing stratifies across fiber-laser premium tiers, CNC-mid tiers with bundled maintenance, and economy mechanical routing systems with limited fume extraction. Price differentiation hinges on CE-MDR dual certification status and after-sales service bundling. Packaging converters in German Mittelstand firms show highest price sensitivity through equipment-as-a-service contracting, while US signage studios absorbing hybrid laser-mechanical platforms prove least sensitive where edge quality commands premium positioning.
Supply Chain Analysis
Multi-axis CAM programming proficiency concentrates in German and Japanese technical institutes, constraining workforce expansion in emerging Mexican and Taiwanese manufacturing hubs. Component sourcing draws from China for rare-earth magnets and fiber laser sources, Germany for precision motion control systems, and Japan for ultrasonic transducer assemblies. Single-source vulnerability sits with Chinese export quota adjustments for neodymium and dysprosium. Distribution runs through OEM-direct sales for large packaging converters, regional distributor networks for mid-volume furniture manufacturers, and equipment-as-a-service platforms for pharmaceutical contract packaging networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-side constraints from multi-axis programming skill scarcity prop pricing discipline, as workforce bottlenecks limit rapid capacity scaling regardless of demand acceleration from semiconductor logistics hubs.
For Market Incumbents: Lock in service contract penetration among German Mittelstand packaging converters before ultrasonic platforms mature, while deepening backward integration into fume extraction system manufacturing to capture REACH-driven upgrade cycles. Vertical control over carbon filtration component supply hedges against EPA Title V enforcement tightening in Ohio and Michigan manufacturing corridors. For New Entrants and Emerging Players: EU Green Deal energy intensity thresholds in Spain and Poland open a window for subsidized equipment placement through national recovery funds, targeting underpenetrated Polish automotive packaging facilities lacking localized CNC-laser hybrid infrastructure. A go-to-market angle anchored in equipment-as-a-service financing structures adapted from US pharmaceutical contract packaging networks collapses capital barriers for mid-volume converters. For Investors and Strategic Acquirers: CE-MDR dual certification timeline extensions stretching European market entry to 14-18 months is the leading indicator that medical-device packaging specialization will consolidate around incumbent platforms with regulatory infrastructure already deployed. Acquisition target archetype: ultrasonic engraving specialists with AI vision convergence patents and existing South Korean or Taiwanese semiconductor logistics relationships. Long-term viability favors platforms with regulatory hedge positioning across REACH, RoHS, and EPA emission frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Platform Convergence | Collapsing prototyping-to-production handoffs from three machines to one consolidates California and Texas signage producer relationships. |
| Equipment-as-a-Service Expansion | Monthly per-hour fee structures transfer obsolescence risk to OEMs while securing German Mittelstand maintenance contracts. |
| Ultrasonic-AI Vision Integration | Real-time density mapping for zero-thermal-damage medical packaging captures Taiwanese semiconductor logistics demand. |
| Backward Integration into Filtration | In-house production of activated carbon extraction systems captures REACH and EPA-driven upgrade cycles. |
| Mexican Automotive Cluster Entry | Querétaro and Guanajuato seat manufacturing expansion lacks localized foam engraving service infrastructure. |
Research Methodology
Document review covered SEC 10-K filings from industrial equipment manufacturers, ECHA REACH enforcement documentation, EPA Clean Air Act Title V permit databases, and customs trade records for laser source and servo motor imports, complemented by interviews with plant engineers at German automotive suppliers, packaging procurement leads at Taiwanese semiconductor logistics hubs, aftermarket service heads at US signage studios, and CAM software training directors at Japanese technical institutes. Bottom-up equipment shipment data triangulated against top-down manufacturing value-add estimates across the analysis window.
Cross-referencing historical replacement cycle patterns with panel input from machinery OEMs and packaging automation consultants shaped the analytical framework. Segmentation modeling spanned product type, technology architecture, application maturity, and end-user financing preference dimensions. CAGRs derived from installed base depreciation curves intersecting with regulatory compliance deadline clustering, with specific inputs including Chinese MIIT industrial upgrading program acceleration rates and EU Green Deal retrofit subsidy uptake trajectories.
The model assumes a particular technology adoption path; alternative pathways for ultrasonic engraving displacing laser platforms in medical packaging would alter the outlook. Forecasts reflect assumptions regarding REACH enforcement consistency, rare-earth export quota stability, and semiconductor logistics hub expansion continuity. Material deviation in EPA Title V stack testing requirements, ECHA substrate traceability timeline extensions, or Amazon-IKEA molded pulp substitution velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
DIY Ball Mill Market
Tools
Bandsaw Machines Market
Tools
Asia Pacific Power Tools Market
Tools
CNC Leather Cutting Machine Market
Tools
Woodworking Power Tools Market
Tools
Air Hammer Market
Tools
Welding Products Market
Tools
Global Scarifiers Market
Tools
Collated Screws Market
Tools
Cordless Fillet Weld Grinder Market
Tools
Diamond Hole Saw Market
Tools
Power Tool Accessories Market
Tools
Cutting Tool Inserts Market
Tools
US Power Tools Market
Tools
Hand Saw Market
Tools
Rotary Tools Market