
 North America PVC Pipes Market | 2026-2036
North America PVC Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
North America PVC Pipes Market Intelligence
Asset-light leasing arrangements for extrusion equipment are reshaping competitive entry in the North America PVC Pipes Market, enabling regional distributors to scale capacity without balance-sheet heavy capital commitments. JM Eagle Inc. leverages vertical integration from resin compounding through finished pipe to sustain margin control across volatile feedstock cycles. Westlake Corporation anchors its position through chlor-alkali and vinyl chloride monomer captive supply, while Orbia competes via geographic breadth spanning Mexican manufacturing and U.S. distribution networks.
North America PVC pipes are rigid thermoplastic conduits manufactured from polyvinyl chloride resin compounded with stabilizers, lubricants, and impact modifiers, typically extruded in diameters from half-inch to sixty-inch and pressure-rated per ASTM D1784 cell classifications for tensile strength and modulus. These pipes convey potable water, stormwater, sewage, and process fluids across municipal, agricultural, and industrial infrastructure systems. Schedule 40 dominates unit volume in residential plumbing and light commercial drainage due to established contractor familiarity and lower installed cost, while SDR 17 and SDR 26 variants capture expanding share in trenchless municipal rehabilitation where flexibility and joint integrity reduce excavation requirements. The irrigation application segment leads growth velocity, propelled by precision agriculture adoption and aquifer depletion constraints across the Great Plains and Central Valley.
EPA Safe Drinking Water Act standards and NSF/ANSI 61 certification requirements govern potable water contact surfaces, compelling compound reformulation to exclude legacy heavy-metal stabilizers and accelerating transition to calcium-zinc and organotin systems. ASTM D2241 and AWWA C900 standards define dimension ratios, hydrostatic design basis, and quality assurance protocols that determine product eligibility for municipal procurement specifications. State-level environmental agency enforcement of stormwater management mandates under EPA NPDES permits is expanding specification of corrugated PVC drainage in commercial and highway construction. Stakeholders must monitor evolving per- and polyfluoroalkyl substance scrutiny, as regulatory pressure on fluoropolymer alternatives could redirect specification toward PVC in certain chemical resistance applications.
Market Dynamics
EPA lead-and-copper rule revisions are compelling water utilities across the United States to replace aging metallic distribution networks with corrosion-resistant thermoplastic alternatives, accelerating capital deployment toward large-diameter pressure pipe procurement.
Growth Catalysts
- Safe Drinking Water Act mandates:NSF/ANSI 61 certification requirements exclude legacy heavy-metal stabilizers, forcing compound reformulation toward calcium-zinc and organotin systems that favor established PVC processors.
- Precision agriculture expansion:Aquifer depletion constraints across the Great Plains and Central Valley are driving specification of SDR 17 and SDR 26 variants for pressurized irrigation conveyance.
- Texas-California corridor demand:Population growth and drought-driven infrastructure strain concentrate procurement activity for municipal water and stormwater rehabilitation projects.
Market Restraints
- Chlor-alkali supply concentration:Captive vinyl chloride monomer production anchors competitive positioning to integrated chemical conglomerates, limiting independent extruder margin flexibility during ethylene price spikes.
- Per- and polyfluoroalkyl substance scrutiny:Regulatory pressure on fluoropolymer alternatives creates specification uncertainty that could redirect demand unpredictably across chemical resistance applications.
- HDPE substitution in trenchless:High-density polyethylene pipe captures share in horizontal directional drilling rehabilitation where flexibility and fused joints outperform PVC bell-and-spigot configurations.
Strategic Opportunities
- Asset-light leasing models:Equipment finance arrangements enable regional distributors to scale extrusion capacity without balance-sheet heavy capital commitments.
- Stormwater management mandates:EPA NPDES permit enforcement at state environmental agencies expands specification of corrugated PVC drainage in commercial and highway construction across the United States.
- Mexican manufacturing integration:Cross-border production networks offer tariff-advantaged supply positioning for Southwest and Gulf Coast municipal procurement.
Industry Challenges
- ASTM D2241 certification timelines:Hydrostatic design basis testing and quality assurance protocol verification compress bid windows for large-diameter municipal contracts.
- Contractor specification inertia:Established familiarity with Schedule 40 dimensions in residential plumbing slows adoption of optimized SDR alternatives despite superior trenchless performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America PVC Pipes Market |
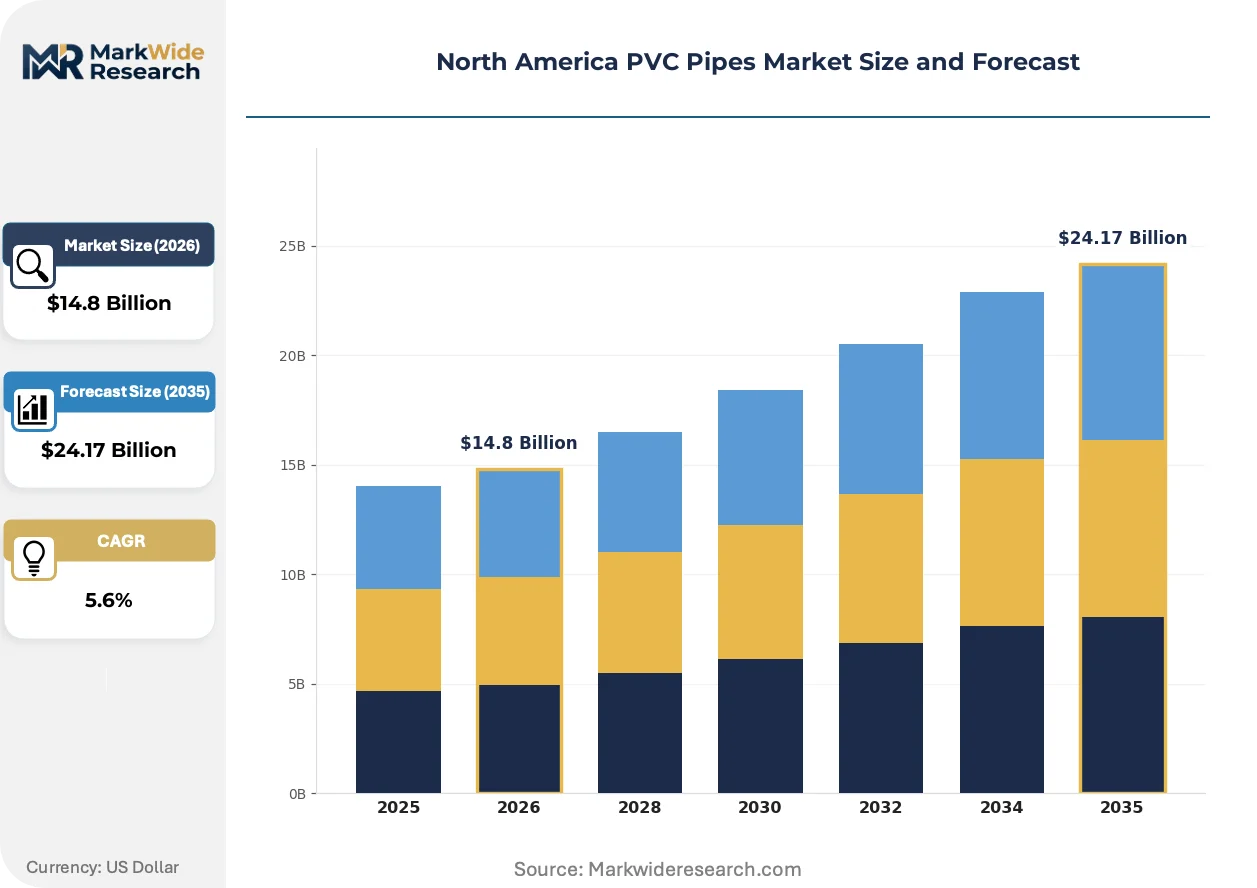
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Schedule 40, Schedule 80, SDR 17, SDR 26 End User: Construction, Agriculture, Automotive, Plumbing Application: Drainage, Irrigation, Water Supply, HVAC Size: 2 inch, 4 inch, 6 inch, 8 inch |
| Companies Covered | JM Eagle Inc., Westlake Corporation, Orbia, Formosa Plastics Corporation, Charlotte Pipe and Foundry Company, IPEX Inc., Aliaxis Holdings SA, Advanced Drainage Systems, Cresline Plastic Pipe Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America PVC Pipes Market Strategic Shifts & Innovations
Extrusion process control systems and compound formulation analytics are compressing quality variance and enabling just-in-time production scheduling for project-specific dimension ratios.
Machine vision inspection integrated with real-time wall-thickness telemetry is digitizing quality assurance workflows for large-diameter pressure pipe production. Municipal procurement offices in California and Texas are mandating digital certification traceability for NSF/ANSI 61 compliance. This convergence is compressing batch rejection rates and accelerating specification approval timelines for trenchless rehabilitation projects.
EPA enforcement discretion under revised lead-and-copper rules is tightening allowable lead service line replacement timelines across Midwest and Northeast water systems. Utilities must document corrosion-resistant alternative materials in capital improvement plans submitted to state revolving fund administrators. PVC pipe specification is capturing share previously held by ductile iron in Chicago, Detroit, and Cleveland distribution network rebuilds.
Consolidated distributor purchasing cooperatives are compressing manufacturer-direct relationships in municipal procurement channels. Independent waterworks distributors across the Sun Belt are aggregating volume commitments to extract price transparency and extended payment terms from resin-integrated producers. This concentration is most visible in Arizona, Nevada, and Colorado where regional distributor networks have consolidated under private-equity ownership since 2022.
North America PVC Pipes Market Segmentation
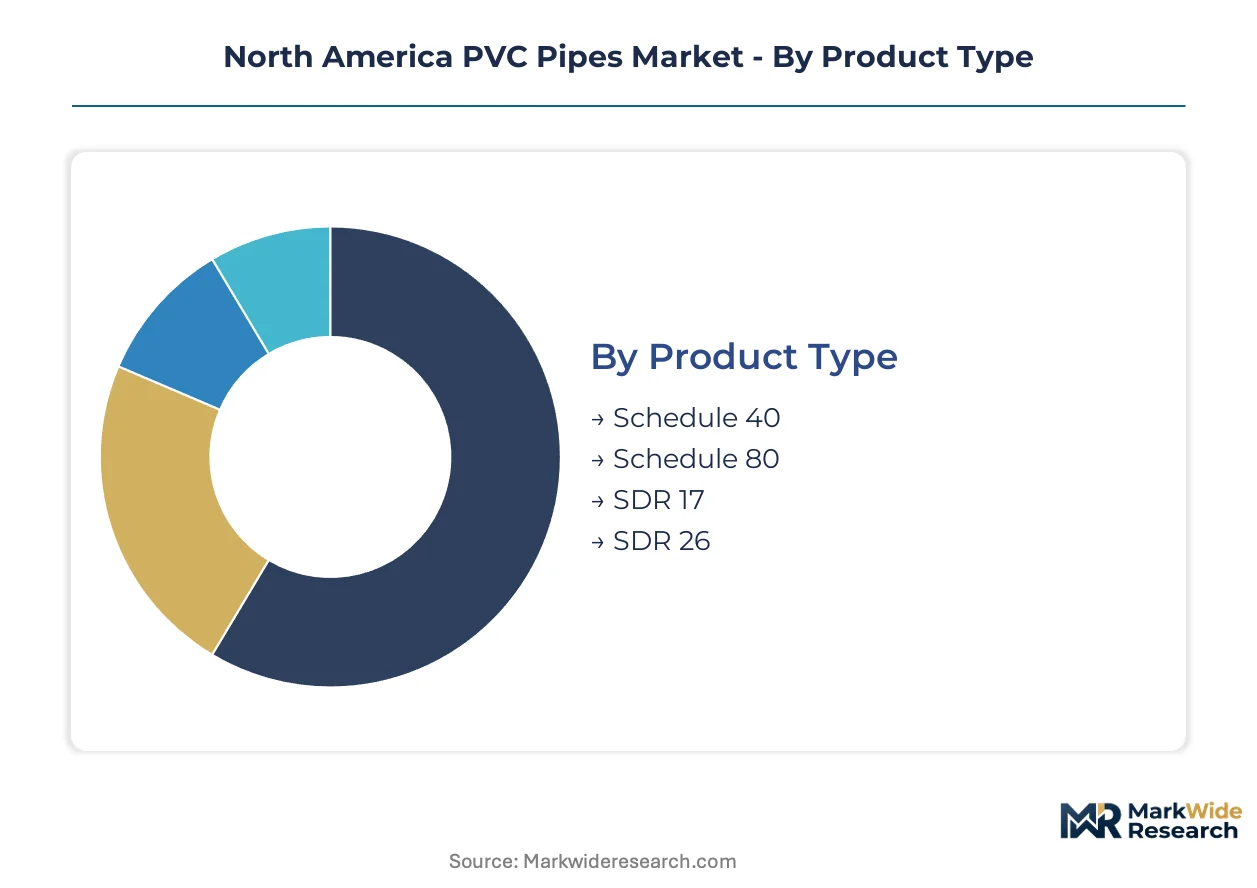
Segmentation in the North America PVC Pipes Market reveals how specification standards, installation practices, and regulatory compliance create distinct commercial pockets with varying margin profiles and service intensity requirements. Understanding these divisions enables targeted capacity planning and compound formulation investments.
Product Type:
After-sales-service intensity varies sharply across product categories, with pressure-rated variants demanding technical support for joint installation and hydrostatic testing that commodity schedules rarely require.
- Schedule 40:Thin-walled conduit specified for gravity-flow drainage and residential plumbing where contractor familiarity minimizes field support needs. Demand concentrates in single-family residential construction across the Sun Belt, where builder preference for established dimensions limits SDR conversion despite price premiums.
- SDR 17:Dimension ratio pipe engineered for municipal water distribution with thicker walls and higher hydrostatic design basis. Procurement clusters in California and Texas infrastructure rehabilitation, driven by EPA lead-and-copper rule compliance timelines that favor corrosion-resistant thermoplastic over metallic alternatives.
- Schedule 80:Heavy-wall variant for industrial process applications requiring elevated pressure ratings and chemical resistance.
- SDR 26:Flexible profile optimized for trenchless installation methods where joint integrity and soil loading tolerance reduce excavation costs.
By volume, Schedule 40 leads. By growth pace, SDR 17 is ahead.
End User:
Customer concentration patterns determine pricing power and contract duration, with fragmented residential builders negotiating spot terms while consolidated utilities lock multi-year supply agreements.
- Construction:Commercial and residential builders specifying PVC for stormwater, sanitary sewer, and foundation drainage systems. Activity concentrates in the Texas-California corridor where population growth and drought-driven code revisions expand conveyance infrastructure requirements.
- Agriculture:Irrigation districts and individual growers deploying pressure-rated pipe for center-pivot and drip systems. Demand clusters in the Central Valley and Great Plains, where aquifer depletion constraints and precision agriculture adoption accelerate pressurized conveyance replacement cycles.
- Plumbing:Residential and light commercial potable water distribution contractors operating under established mechanical codes.
- Automotive:Manufacturing facilities specifying corrosion-resistant process piping for coolant and chemical handling systems.
Construction commands the largest revenue pool. Agriculture is expanding most quickly.
Application:
Functional use cases dictate compound formulation requirements, with potable water contact surfaces facing NSF/ANSI 61 certification barriers that drainage applications bypass.
- Irrigation:Pressurized conveyance for agricultural water distribution requiring UV stabilizers and impact modifiers for outdoor exposure. Specification concentrates in California's Central Valley and Texas High Plains, where groundwater pumping restrictions and surface water allocation scarcity drive efficiency investments.
- Drainage:Stormwater and sanitary sewer systems where corrugated profiles and perforated configurations address infiltration and exfiltration control. Municipal procurement across the Midwest and Southeast favors PVC for highway and commercial construction under EPA NPDES permit enforcement.
- Water Supply:Potable distribution networks subject to Safe Drinking Water Act standards and state revolving fund compliance documentation.
- HVAC:Condensate drainage and process cooling circuits in commercial and industrial mechanical systems.
Drainage dominates unit shipments. Irrigation posts the steepest expansion trajectory.
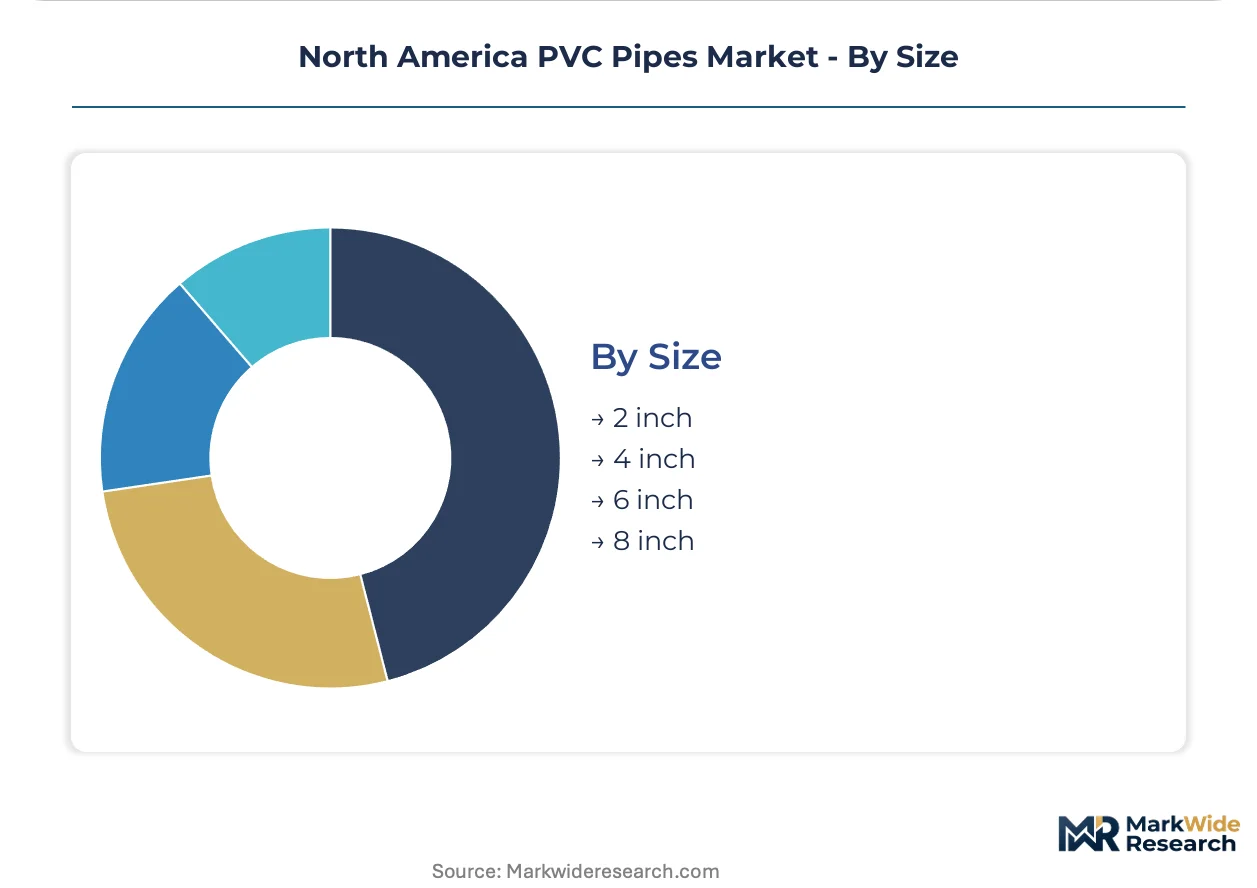
Size:
Diameter selection correlates directly with end-use economics, with small-diameter commodity production competing on cycle time and large-diameter custom extrusion competing on technical capability.
- 6 inch:Municipal water distribution and agricultural mainline standard where trenchless rehabilitation methods require sufficient wall thickness for directional drilling pull-through. Procurement concentrates in California and Texas utility contracts, with ASTM D2241 certification timelines compressing bid windows for integrated producers.
- 4 inch:Residential sewer lateral and commercial drainage workhorse dimension with established contractor tooling and joint familiarity. Demand clusters in single-family construction across Arizona, Nevada, and Colorado where regional distributor consolidation since 2022 has shifted purchasing leverage toward cooperative buying arrangements.
- 2 inch:Residential plumbing branch lines and irrigation laterals with highest unit volume and lowest margin per pound.
- 8 inch:Large-diameter pressure pipe for municipal transmission mains and industrial process headers requiring specialized extrusion equipment and extended quality assurance protocols.
Four-inch diameter leads in unit volume. Six-inch diameter is gaining share fastest in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration among municipal water utilities and agricultural irrigation districts shapes procurement patterns across North America, with specification authority clustering in state revolving fund administrators and regional distributor cooperatives.
United States
EPA lead-and-copper rule revisions are compelling water utilities in Chicago, Detroit, and Cleveland to replace metallic distribution networks with corrosion-resistant thermoplastic alternatives. Municipal procurement offices in California and Texas now mandate digital certification traceability for NSF/ANSI 61 compliance. The Texas-California corridor concentrates demand for large-diameter pressure pipe as population growth and drought-driven irrigation expansion strain existing conveyance systems.
Canada
Provincial infrastructure stimulus programs in Ontario and Quebec are accelerating stormwater and sanitary sewer rehabilitation projects. Health Canada guidelines for potable water contact materials align with NSF/ANSI 61 standards, simplifying cross-border specification for integrated producers. The Greater Toronto Area and Vancouver Metro anchor procurement volume for SDR-rated pressure pipe in municipal transmission applications.
Mexico
Cross-border production networks offer tariff-advantaged supply positioning for Southwest and Gulf Coast municipal procurement in the United States. Mexican manufacturing integration supports just-in-time production scheduling for project-specific dimension ratios demanded by Texas utilities. Nuevo León and the Bajío Region concentrate extrusion capacity serving binational distributor networks.
North America PVC Pipes Market Key Industry Players
Channel-controlling players compete with product-specialist players for specification authority in municipal procurement channels. The vendor base organizes around three strategic archetypes: resin-integrated chemical conglomerates with captive vinyl chloride monomer supply, regional extruders leveraging asset-light equipment leasing, and distributor-owned fabricators with cooperative purchasing leverage. Dominant competitive moves include backward integration into chlor-alkali production and geographic expansion through cross-border manufacturing networks.
Within the resin-integrated tier, JM Eagle Inc., Westlake Corporation, and Orbia exemplify archetypes that anchor competitive positioning through upstream control over feedstock cycles. JM Eagle represents vertical integration from resin compounding through finished pipe. Westlake Corporation occupies a position secured by captive chlor-alkali and vinyl chloride monomer supply. Orbia sits within a geographic breadth archetype spanning Mexican manufacturing and U.S. distribution networks.
| Leading Market Players |
|---|
| JM Eagle Inc. |
| Westlake Corporation |
| Orbia |
| Formosa Plastics Corporation |
| Charlotte Pipe and Foundry Company |
| IPEX Inc. |
| Aliaxis Holdings SA |
| Advanced Drainage Systems |
| Cresline Plastic Pipe Co., Inc. |
| Others |
Cost & Logistics Intelligence
Tariff exposure on Mexican-origin resin and finished pipe determines both pricing tier spreads and supply chain shape across the North America PVC Pipes Market. The USMCA rules-of-origin provisions create divergent landed costs for integrated producers versus cross-border distributors, compressing margins on commodity schedules while preserving premium capture for NSF/ANSI 61-certified pressure pipe.
Pricing Analysis
Cost-plus contracts indexed to ethylene and chlorine spot benchmarks dominate municipal procurement, with quarterly adjustments passing through feedstock volatility to utility buyers. Price differentiation separates resin-integrated producers from regional extruders, as captive vinyl chloride monomer supply insulates JM Eagle and Westlake from margin compression during ethylene spikes. Pricing pressure stems from distributor cooperative consolidation across Arizona, Nevada, and Colorado, where aggregated volume commitments extract transparency concessions. Residential construction contractors exhibit highest price sensitivity, while municipal utilities lock multi-year agreements prioritizing certification compliance over unit cost.
Supply Chain Analysis
Upstream ethylene and chlorine feedstock production concentrates in Texas and Louisiana, with vinyl chloride monomer capacity anchored along the Gulf Coast petrochemical corridor. The supply chain draws from salt brine electrolysis and ethane cracking, with EDC/VCM integration determining cost position. Single-source vulnerability runs through chlor-alkali supply concentration among integrated chemical conglomerates. Distribution runs through consolidated waterworks distributors and cooperative purchasing networks, with private-equity-owned regional networks gaining leverage since 2022.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America PVC Pipes Market sits at a regulatory-inflection disruption, as EPA lead-and-copper rule enforcement accelerates metallic replacement cycles and reshapes specification authority toward corrosion-resistant thermoplastics.
For Market Incumbents: Harden margin position through captive chlor-alkali capacity expansion and digital certification traceability investments that compress ASTM D2241 approval timelines. Defend against HDPE substitution in trenchless applications by embedding SDR 26 variants in municipal engineering standards. Prioritize joint integrity testing protocols that differentiate PVC bell-and-spigot performance from fused polyethylene alternatives. For New Entrants and Emerging Players: Underpenetration in Canadian prairie provinces and Mexican industrial corridors offers white-space expansion without direct confrontation with resin-integrated giants. Target Ontario and Quebec stormwater rehabilitation programs fueled by provincial infrastructure stimulus. Enter through asset-light extrusion equipment leasing that bypasses balance-sheet-heavy capital requirements, partnering with regional distributors for specification access. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap extruders with ASTM certification depth and geographic positioning in the Texas-California corridor. Long-term viability hinges on regulatory tailwinds from Safe Drinking Water Act enforcement and drought-driven irrigation infrastructure replacement. Watch for signals in state revolving fund disbursement velocity as inflection indicators for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali | Captive VCM supply insulates margin during ethylene price volatility cycles. |
| Digital Certification Traceability | California and Texas procurement offices now mandate NSF/ANSI 61 compliance documentation. |
| Asset-Light Equipment Leasing | Regional distributors scale extrusion capacity without heavy balance-sheet commitments. |
| Mexican Manufacturing Integration | Tariff-advantaged supply positioning serves Southwest and Gulf Coast municipal contracts. |
| SDR Variant Specification Embedding | Trenchless rehabilitation standards favor flexible profiles with superior joint integrity. |
Research Approach
Initial hypotheses were tested against primary input from municipal procurement officers, water utility engineers, chlor-alkali plant managers, and regional distributor executives and refined through secondary validation. Bottom-up triangulation combined structured interviews with downstream specification authorities and top-down reconciliation against customs trade data, EPA enforcement disclosures, state revolving fund allocation records, and SEC filings from resin-integrated producers. Cross-referencing ASTM certification databases with municipal bid archives verified product penetration patterns across pressure-rated and drainage categories.
Demand-supply balance modeling segmented volume projections across Schedule 40, SDR 17, SDR 26, and Schedule 80 product tiers, irrigation, drainage, water supply, and HVAC applications, and construction, agriculture, plumbing, and automotive end-use sectors. CAGRs were derived from regression analysis of historical procurement cycles against regulatory compliance timelines and population-driven infrastructure strain indices. Feedstock cost pass-through elasticity and distributor cooperative purchasing leverage were incorporated as industry-specific demand shapers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-equity-backed distributor consolidators or resin-integrated capacity expansions would shift outcomes. Material shifts in EPA enforcement discretion, USMCA tariff classifications, or chlor-alkali supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
PVC Pipes and Fittings Market
Pipes and Tubes
Multiflex Tubes Market
Pipes and Tubes
Stainless Steel Plumbing Pipes Market
Pipes and Tubes
Qatar PVC Pipe Market
Pipes and Tubes
Drum Funnel Market
Pipes and Tubes
Stainless Steel Tank Container Market
Pipes and Tubes
Duplex Stainless Steel Pipe Market
Pipes and Tubes
Global Cured-In-Place Pipe Market
Pipes and Tubes
Pipeline Processing and Pipeline Services Market
Pipes and Tubes
Steel Pipe Market
Pipes and Tubes
Global PEX (Cross-Linked Polyethylene) Market
Pipes and Tubes
HDPE Pipes Market
Pipes and Tubes
FRP Pipe Market
Pipes and Tubes
Saudi Arabia Copper Pipes and Tubes Market
Pipes and Tubes
Tapping Sleeves Market
Pipes and Tubes
Coiled Tubing Manufacturing Market