
 Gan and Sic Power Semiconductor Market | 2026-2036
Gan and Sic Power Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
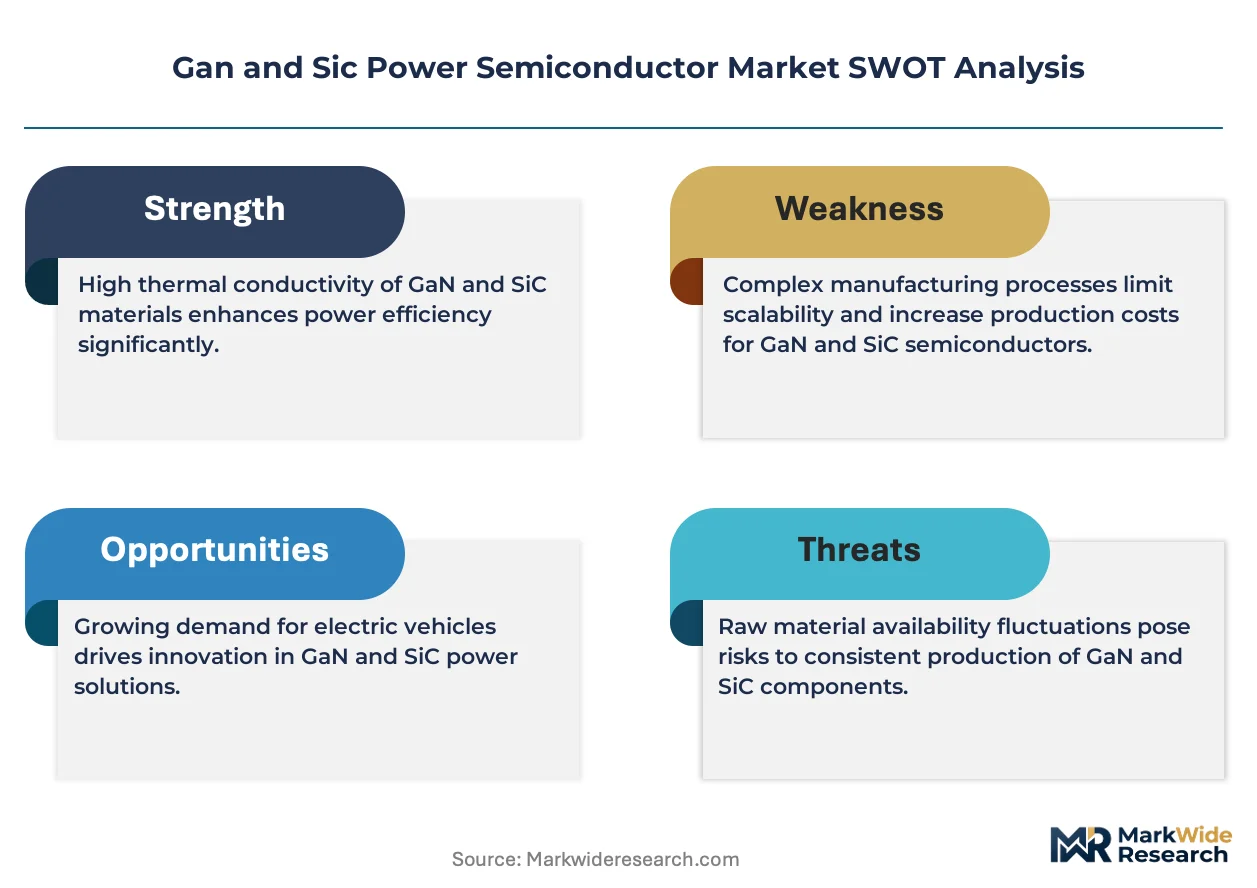
Gan and Sic Power Semiconductor Market Analysis
The EU Green Deal is consolidating demand for silicon carbide and gallium nitride components across European automotive supply chains. Infineon Technologies AG leverages its Dresden manufacturing complex to sustain captive wafer supply for power modules. Wolfspeed anchors North American SiC substrate production through its Mohawk Valley fabrication facility. STMicroelectronics competes via integrated GaN-on-Si R&D pipelines serving consumer power adapter markets.
GaN and SiC power semiconductors are wide-bandgap devices engineered from gallium nitride or silicon carbide crystal structures, delivering breakdown voltages above 600V with switching frequencies that exceed silicon limits by an order of magnitude. These properties enable compact, efficient power conversion in electric drivetrains, data center servers, and grid-tied inverters. Discrete Devices command the largest revenue share due to their flexibility across voltage classes and ease of integration into existing circuit designs. Electric Vehicles within the Application dimension represent the fastest structural expansion as OEMs redesign traction inverters around SiC MOSFETs to extend range. Power Modules concentrate margin pools because thermal management complexity and qualification cycles create barriers that protect incumbent suppliers.
REACH restrictions on hazardous substances and the EU AI Act's energy efficiency reporting requirements shape component qualification timelines and material disclosure obligations for vendors serving European industrial buyers. EPA vehicle emission standards and NHTSA fuel economy rules in the United States directly mandate the power density improvements that only wide-bandgap semiconductors can deliver at system level. Stakeholders must monitor how EMA, ECHA, and EPA coordinate emerging substance restrictions with performance standards to anticipate which technology pathways secure regulatory preference.
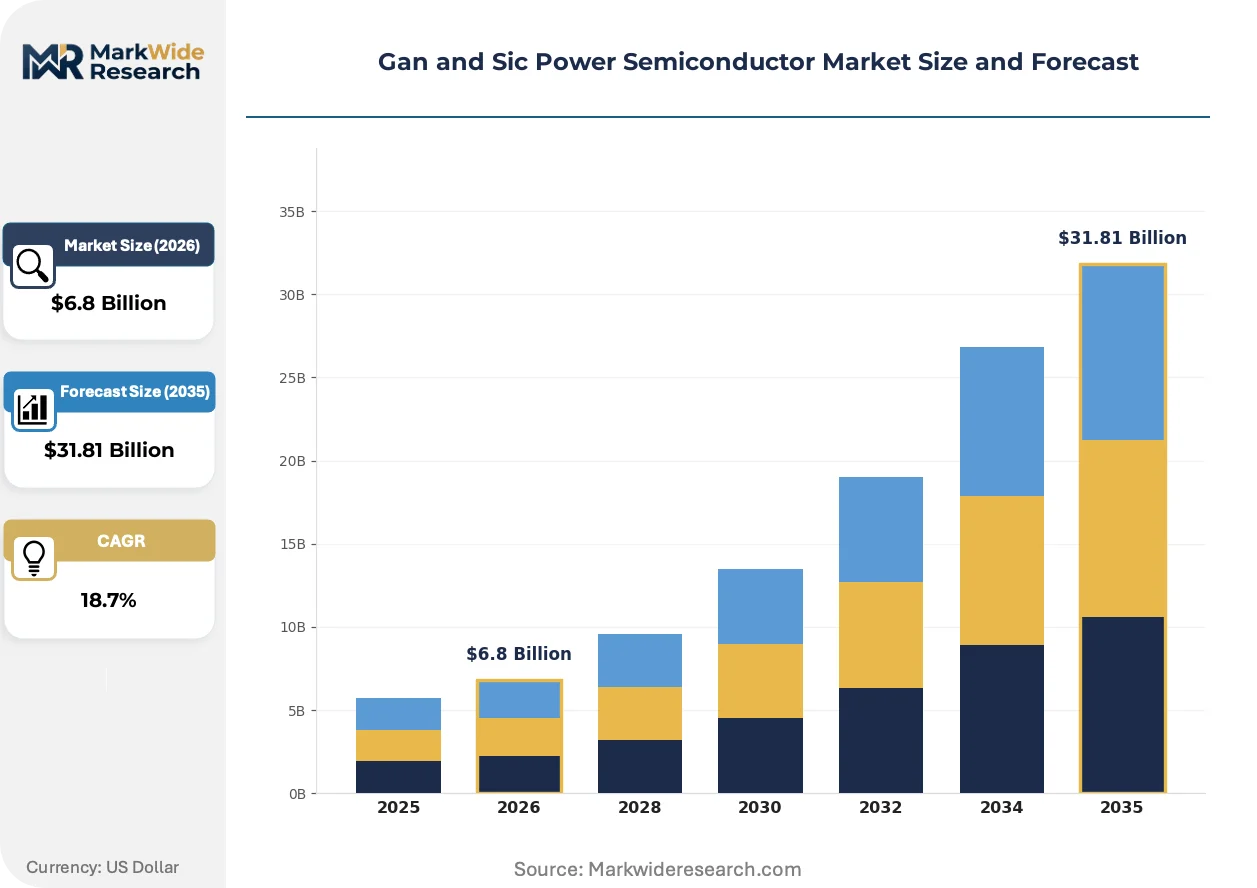
Market Dynamics
OEM electrification roadmaps are compressing SiC MOSFET qualification timelines as EPA tailpipe rules tighten. Wafer fabrication concentration across China, Japan, and Germany is forcing supply security redesigns among tier-one automotive suppliers.
Growth Catalysts
- EPA Vehicle Emission Standards:United States fuel economy mandates require power density improvements that silicon MOSFETs cannot deliver, pulling SiC into traction inverters.
- Data Center Load Growth:Hyperscale server farms in Northern Virginia and Frankfurt are retrofitting power supplies with GaN HEMTs to cut thermal overhead.
- EU Green Deal Consolidation:European automotive supply chains are locking in multi-year SiC module contracts ahead of 2035 ICE phase-out deadlines.
Market Restraints
- Substrate Cost Volatility:6-inch SiC boule supply from Wolfspeed and Coherent remains insufficient for projected EV ramp volumes.
- China Wafer Concentration:Sanan Optoelectronics and SICC control over 60% of global SiC substrate growth capacity.
- Defect Density Limitations:Basal plane dislocations in SiC epilayers above 650V ratings constrain yield rates at 150mm wafer transitions.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for semiconductor fabrication are attracting GaN-on-Si pilot lines serving domestic solar inverter demand.
- Grid-Scale Storage Integration:Battery energy storage systems in Texas and California are specifying SiC IGBTs for 1500V DC bus architectures.
- EU AI Act Energy Reporting:Mandatory disclosure of data center PUE metrics is accelerating GaN adoption in server power supplies.
Industry Challenges
- Power Electronics Talent Gap:Shortage of engineers experienced in wide-bandgap device characterization and gate driver design is extending product development cycles.
- AEC-Q101 Qualification Burden:Automotive-grade SiC MOSFETs require 1000-hour HTRB testing that adds months to production timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gan and Sic Power Semiconductor Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.81 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Modules, Power ICs, Discrete Devices, Power Boards Technology: GaN, SiC, Hybrid, CMOS End User: Consumer Electronics, Automotive, Industrial, Telecommunications Application: Power Supply, RF Amplifiers, Electric Vehicles, Renewable Energy |
| Companies Covered | Infineon Technologies AG, Wolfspeed, STMicroelectronics, onsemi, ROHM Semiconductor, Mitsubishi Electric Corporation, Renesas Electronics Corporation, Alpha and Omega Semiconductor, Fuji Electric Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gan and Sic Power Semiconductor Market Emerging Trajectories
GaN-on-silicon epitaxy is absorbing capital and engineering resources previously directed at silicon superjunction MOSFETs. This substrate transition is compressing cost curves and redrawing competitive boundaries across consumer and automotive power electronics.
GaN HEMT technology is absorbing switching frequency loads that silicon devices cannot sustain above 100kHz. Smartphone charger OEMs in Dongguan and Shenzhen are transitioning entire adapter portfolios to GaN-on-Si platforms within 18-month product cycles. This absorption is collapsing magnetic component sizes and enabling sub-100cc 65W adapter form factors.
REACH substance restrictions on hexavalent chromium plating are forcing automotive module suppliers to redesign baseplate metallization. ECHA hazard classifications for certain die-attach materials are triggering material disclosure audits across European industrial buyer procurement teams. Power module vendors with pre-qualified RoHS-compliant solder schemes are securing preferred supplier status.
Automotive tier-ones are consolidating power semiconductor procurement under direct OEM relationships, bypassing traditional distributor channels. Bosch and Continental are negotiating multi-year SiC wafer supply agreements directly with substrate growers. This disintermediation is most visible in Germany and Japan, where just-in-time module assembly lines require bonded inventory commitments.
Gan and Sic Power Semiconductor Market Segmentation
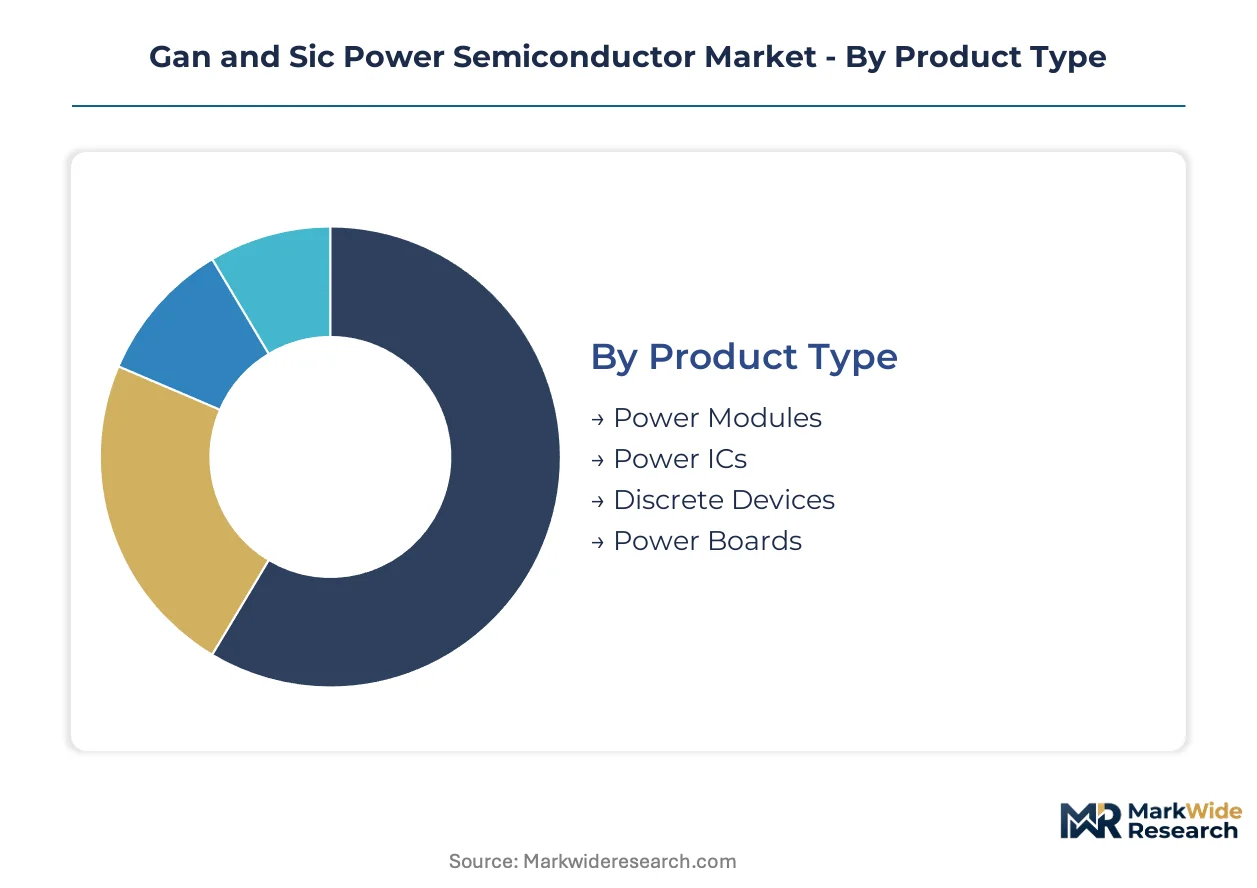
Wide-bandgap semiconductor procurement patterns diverge sharply across voltage classes, switching frequency demands, and qualification rigor. Each segmentation dimension reveals distinct buyer priorities that reshape supplier R&D roadmaps and capacity allocation decisions.
Product Type:
Cost tier differentiation separates mass-market buyers seeking drop-in replacements from system integrators demanding thermal-optimized assemblies.
- Discrete Devices:Individual transistors and diodes rated from 650V to 1700V deliver flexible circuit design options. Automotive tier-ones in Germany and Japan source discretes for traction inverter prototyping and aftermarket retrofit programs where module costs prove prohibitive.
- Power Modules:Pre-assembled half-bridge and six-pack configurations integrate SiC MOSFETs with ceramic substrates and advanced thermal interface materials. OEM electrification programs in the United States and China are locking in multi-year module supply agreements as EPA tailpipe rules tighten.
- Power ICs:Monolithic GaN gate drivers and controllers from foundries in Taiwan and South Korea serve high-frequency consumer adapter markets.
- Power Boards:Subsystem-level assemblies combining wide-bandgap devices with magnetics and capacitors address data center and industrial inverter demand.
Volume sits with Discrete Devices; growth tilts toward Power Modules.
Technology:
Application switching frequency requirements and breakdown voltage thresholds determine technology selection across end-use segments.
- SiC:Silicon carbide crystal structures deliver 1200V-3300V breakdown ratings with thermal conductivity three times silicon's capability. Electric vehicle traction inverters from Detroit to Shanghai specify SiC MOSFETs for 800V architectures that extend range and enable faster DC charging.
- GaN:Gallium nitride HEMTs sustain switching above 1MHz with sub-50 milliohm on-resistance. Smartphone charger OEMs in Dongguan and Shenzhen have transitioned entire adapter portfolios to GaN-on-Si platforms within compressed product cycles.
- Hybrid:Cascode configurations pairing SiC diodes with silicon IGBTs bridge cost-performance gaps in industrial motor drives.
- CMOS:Silicon-based power management ICs retain share in sub-100V applications where wide-bandgap premiums outweigh efficiency gains.
Revenue concentrates in SiC; GaN claims the steepest expansion trajectory as consumer electronics absorption accelerates.
End User:
Customer qualification timelines and volume predictability create divergent supplier engagement models across buyer categories.
- Automotive:AEC-Q101 qualification mandates and functional safety requirements under ISO 26262 extend development cycles to 36-48 months. Direct OEM-supplier relationships are displacing distributor channels as Bosch and Continental negotiate bonded inventory commitments with wafer growers.
- Industrial:Variable frequency drives, welding equipment, and uninterruptible power supplies demand 600V-1700V ratings with decade-long service life guarantees. European machine builders face REACH substance disclosure audits that favor pre-qualified RoHS-compliant module vendors.
- Consumer Electronics:Rapid product refresh cycles and cost-sensitive procurement favor GaN-on-Si discretes from merchant suppliers.
- Telecommunications:Base station power amplifiers and server power supplies require RF-optimized GaN HEMTs with linearity specifications.
Procurement volume clusters in Automotive; margin expansion favors Industrial buyers accepting premium pricing for extended reliability guarantees.
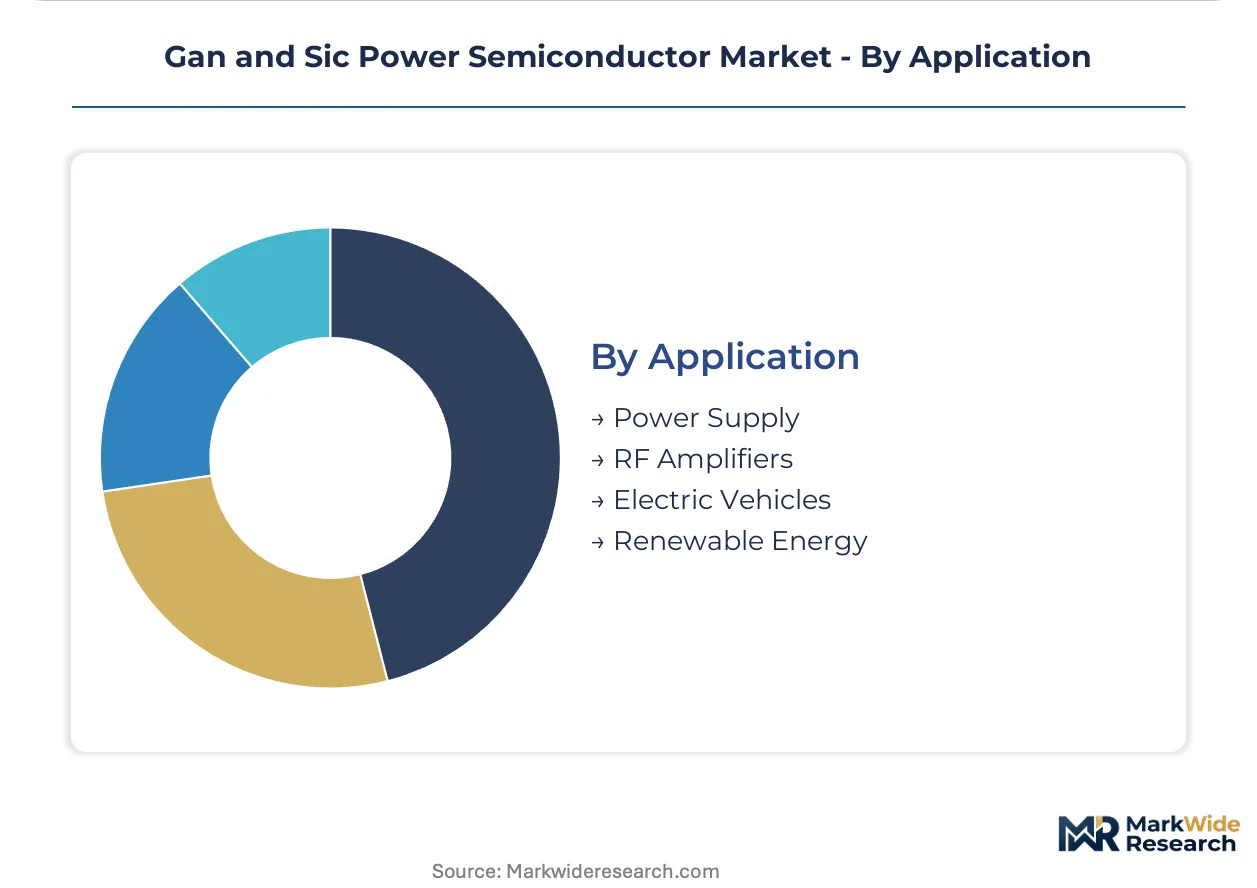
Application:
System-level efficiency mandates and power density targets reshape component specifications across deployment contexts.
- Electric Vehicles:Traction inverters, onboard chargers, and DC-DC converters absorb the majority of automotive-qualified SiC output. United States EPA fuel economy rules directly mandate the power density improvements that silicon MOSFETs cannot deliver at system level.
- Power Supply:Data center server farms in Northern Virginia and Frankfurt are retrofitting AC-DC front ends with GaN HEMTs to cut thermal overhead and improve PUE metrics under EU AI Act disclosure requirements.
- Renewable Energy:Solar inverters and wind turbine converters specify 1500V DC bus architectures that SiC IGBTs address with reduced switching losses.
- RF Amplifiers:5G macro base stations and radar systems exploit GaN's high electron mobility for microwave frequency operation.
Installed base dominates Power Supply; Electric Vehicles capture the fastest share gain as OEM electrification roadmaps compress qualification timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dresden anchors European wafer fabrication capacity, while Mohawk Valley and Xining concentrate substrate growth investments. Regulatory pressure from EPA tailpipe rules and EU Green Deal deadlines is redrawing procurement geography across automotive supply chains.
United States
EPA vehicle emission standards and NHTSA fuel economy rules mandate power density improvements that silicon MOSFETs cannot deliver. The IRA production tax credits accelerate domestic module assembly investments. Mohawk Valley in New York State hosts North America's largest SiC substrate fabrication complex, with tier-one automotive suppliers negotiating direct wafer supply agreements.
Germany
Bosch and Continental compress SiC MOSFET qualification timelines as OEM electrification roadmaps advance. REACH restrictions on hazardous substances and ECHA hazard classifications trigger material disclosure audits across procurement teams. Dresden's manufacturing complex sustains captive wafer supply for automotive power modules serving European EV programs.
China
Sanan Optoelectronics and SICC control over 60% of global SiC substrate growth capacity, forcing supply security redesigns among international tier-ones. MIIT dual carbon goals and GB standards accelerate wide-bandgap adoption in domestic EV traction inverters. Xining and Shanghai concentrate boule growth and epitaxial wafer processing for export and domestic module assembly.
Japan
METI technology roadmaps prioritize 150mm SiC wafer transitions to address defect density limitations in high-voltage epilayers. Automotive tier-ones in Nagoya and Tokyo lock in multi-year module contracts as AEC-Q101 qualification mandates extend development cycles. Yokohama hosts concentrated R&D pipelines for GaN-on-Si consumer power adapters.
India
The PLI scheme for semiconductor fabrication attracts GaN-on-Si pilot lines targeting domestic solar inverter demand. CEA grid codes and BIS standards shape component qualification timelines for industrial power electronics. Gujarat and Karnataka emerge as assembly hubs for wide-bandgap modules serving renewable energy and EV charger deployments.
Gan and Sic Power Semiconductor Market Vendor Landscape
The competitive structure tilts toward integrated device manufacturers with captive substrate supply. Wafer fabrication concentration across three countries creates tiered supplier access based on bonded inventory commitments. Two archetypes dominate: vertically integrated substrate-to-module players and fabless designers relying on merchant foundry capacity. Capacity expansion and direct OEM-supplier partnerships constitute the primary competitive moves, displacing traditional distributor channels.
Among European integrated manufacturers, Infineon Technologies AG and STMicroelectronics exemplify the captive wafer supply archetype. Wolfspeed anchors North American substrate production. These three occupy positions where thermal management complexity and qualification cycles protect margin pools against merchant competition.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Wolfspeed |
| STMicroelectronics |
| onsemi |
| ROHM Semiconductor |
| Mitsubishi Electric Corporation |
| Renesas Electronics Corporation |
| Alpha and Omega Semiconductor |
| Fuji Electric Co., Ltd |
| Others |
Supply Flow & Price Mechanics
6-inch SiC boule costs cascade from Xining and Mohawk Valley growth facilities through three pricing strata that separate automotive module contracts from consumer adapter spot purchases. Wafer fabrication concentration across China, Japan, and Germany feeds tiered procurement power where bonded inventory commitments unlock preferential unit economics.
Pricing Analysis
Yield-normalized cost-per-ampere anchors value-based pricing for automotive-qualified SiC MOSFETs against silicon alternatives. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels separates AEC-Q101 qualified modules from merchant discretes. Cost compression in consumer GaN adapters intensifies as Dongguan OEMs absorb merchant foundry capacity. Automotive buyers exhibit lowest price sensitivity due to range-extension mandates under EPA tailpipe rules.
Supply Chain Analysis
Freight costs for SiC substrates from Xining to Dresden module assembly lines compound with bonded inventory carrying charges under just-in-time OEM contracts. Raw material dependencies on high-purity silicon carbide powder, ceramic substrate alumina, and RoHS-compliant die-attach solder pastes draw from concentrated specialty chemical suppliers. Single-source vulnerability in 150mm SiC wafer transitions threatens supply security for 800V traction inverter programs. Distribution runs through direct OEM-supplier agreements that displace traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where REACH substance restrictions and AEC-Q101 qualification mandates erect barrier-to-entry moats for pre-certified incumbents.
For Market Incumbents: Cement captive wafer supply through multi-year substrate growth agreements with Xining and Mohawk Valley facilities before 150mm transition bottlenecks harden. Deepen backward integration into ceramic substrate manufacturing to defend margin pools against merchant module competition. Lock in bonded inventory commitments with Bosch and Continental as tier-one procurement consolidates under direct OEM relationships. For New Entrants and Emerging Players: Enter via GaN-on-Si consumer adapter white space where 18-month product cycles and merchant foundry access lower qualification barriers compared to automotive SiC. Target data center power supply retrofit demand under EU AI Act energy disclosure requirements. Pursue fabless design partnerships with Taiwan foundries to bypass substrate fabrication capital intensity. For Investors and Strategic Acquirers: Direct OEM-supplier contract announcements from tier-one automotive module vendors are the leading indicator that supply security premiums are crystallizing into sustainable margin structures. Position for 5-10 year holding periods around vertically integrated substrate-to-module players with proven 150mm wafer yield trajectories. Monitor EPA tailpipe rule stringency adjustments as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| 150mm SiC Wafer Transition | METI roadmaps and automotive OEM roadmaps converge on defect density thresholds for 800V architectures. |
| Backward Integration into Substrate Growth | Mohawk Valley and Dresden facilities anchor regional supply security against China wafer concentration. |
| AEC-Q101 Pre-Qualification Investment | 1000-hour HTRB testing completion unlocks tier-one automotive procurement channel access. |
| GaN-on-Si Foundry Partnership | Taiwan foundry capacity secures consumer adapter market share without substrate fabrication capital. |
| REACH-Compliant Material Redesign | RoHS-compliant solder schemes secure preferred supplier status under ECHA disclosure audits. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs that combined with primary interviews across SiC substrate growth engineers, automotive tier-one procurement directors, power module thermal design leads, and foundry process integration specialists. SEC 10-K disclosures, EPA emission standard dockets, ECHA REACH registration databases, and MIIT industry bulletins supplied quantitative benchmarks. Bottom-up wafer capacity modeling and top-down EV adoption scenario triangulation validated segment-level outputs.
Data-stream reconciliation across unit shipment tracking, fab utilization reporting, and OEM contract disclosure patterns shaped the analytical framework. Segmentation dimensions spanned product type, technology node, voltage class, end-user qualification tier, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and technology substitution elasticity parameters. Defect density trajectories in 150mm SiC epilayers and GaN HEMT switching frequency benchmarks informed technology-specific growth assumptions across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under substrate supply disruption or EPA rule relaxation scenarios. Forecasts reflect documented assumptions about wafer yield improvement rates and automotive electrification penetration curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Chip Equalizers Market
Semiconductor Devices
Programmable Logic Device (PLD) Market
Semiconductor Devices
APAC Semiconductor Device in Aerospace and Defense Market
Semiconductor Devices
Global 8 - Bit Microcontroller Market
Semiconductor Devices
Epi Wafer Market
Semiconductor Devices
Japan Semiconductor Diode Market
Semiconductor Devices
SLD Market
Semiconductor Devices
Fin Field Effect Transistor (Finfet) Market
Semiconductor Devices
Temperature-Controlled Semiconductor Market
Semiconductor Devices
IGBT and Super Junction MOSFET Market
Semiconductor Devices
Spintronic Logic Devices Market
Semiconductor Devices
Thick Film Devices Market
Semiconductor Devices
High Speed Data Converters Market
Semiconductor Devices
AMD Motherboards Market
Semiconductor Devices
Analog and Mixed Signal Device Market
Semiconductor Devices
Taiwan Discrete Semiconductor Market