
 Global Gel Stent Market | 2026-2036
Global Gel Stent Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gel Stent Market Foresight
CE marking under the EU Medical Device Regulation is reorganizing competitive access for gel stent manufacturers seeking European commercialization. Glaukos Corporation leverages its proprietary trabecular meshwork bypass platform to sustain technology leadership in ophthalmic micro-invasive surgery. Alcon Inc anchors its position through extensive surgeon training networks and direct distribution across major eye care markets. Johnson & Johnson Vision competes on integrated cataract-glaucoma combination workflows that streamline operating room efficiency.
A gel stent is a biocompatible, flexible tubular implant typically composed of cross-linked hydrogel or silicone matrices, designed to create a permanent drainage channel for aqueous humor in glaucoma therapy or to maintain patency in vascular and urological applications. The device relies on controlled porosity and swelling properties to minimize foreign body response while ensuring sustained flow rates. Hydrogel formulations currently dominate product type discussions due to their tunable mechanical properties and established biocompatibility profiles, though biodegradable gel variants are gaining fastest attention as surgeons prioritize resorbable options that eliminate explantation risks. Drug-eluting technology segments command premium positioning through localized pharmacologic delivery that suppresses fibrotic encapsulation and extends device patency duration.
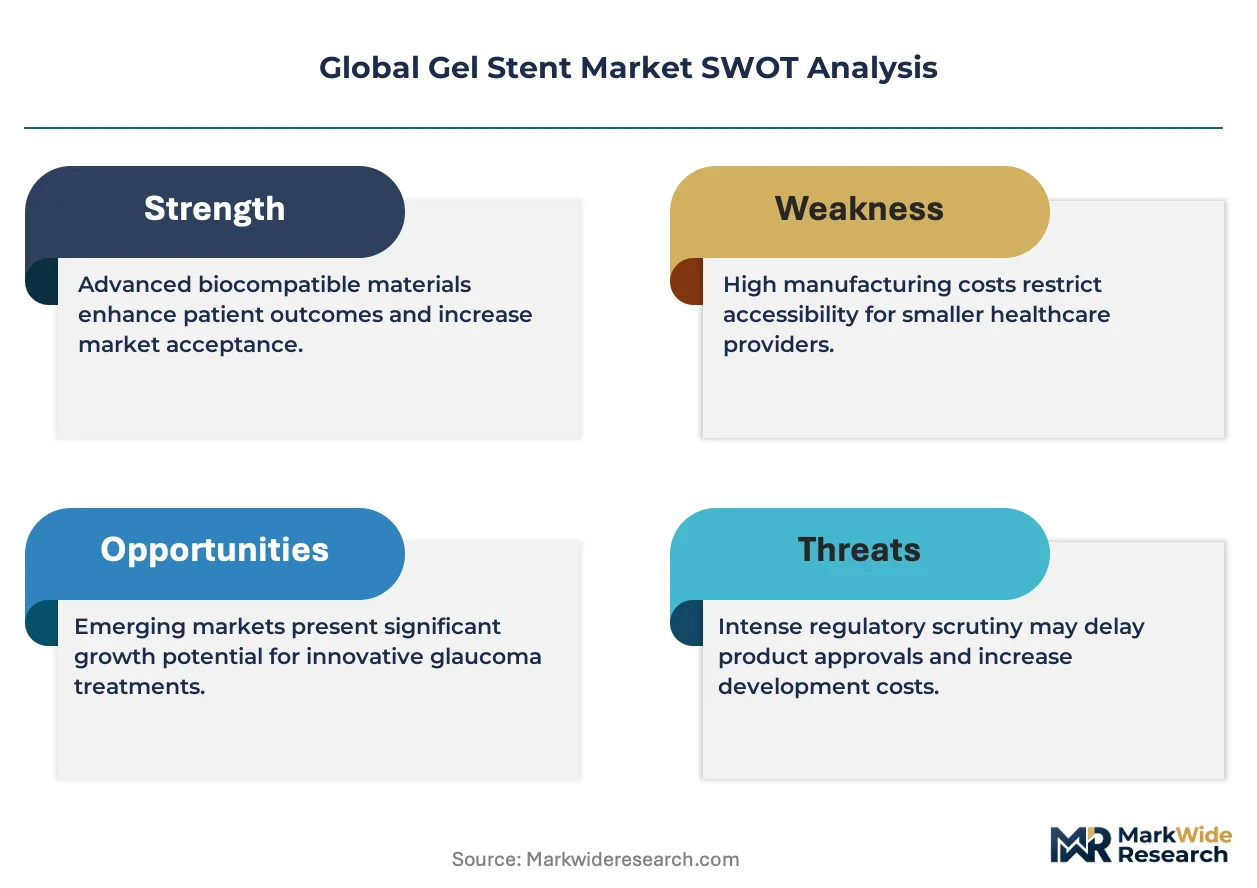
The FDA's premarket approval process and the EU MDR's enhanced clinical evidence requirements collectively extend development timelines and raise capital barriers for new gel stent entrants. Japan's PMDA maintains distinct biocompatibility testing protocols that necessitate separate validation studies for manufacturers targeting that market. Stakeholders must monitor evolving reimbursement decisions by national health technology assessment bodies, as these determinations will shape which gel stent technologies achieve sustainable commercial scale across priority ophthalmology markets.
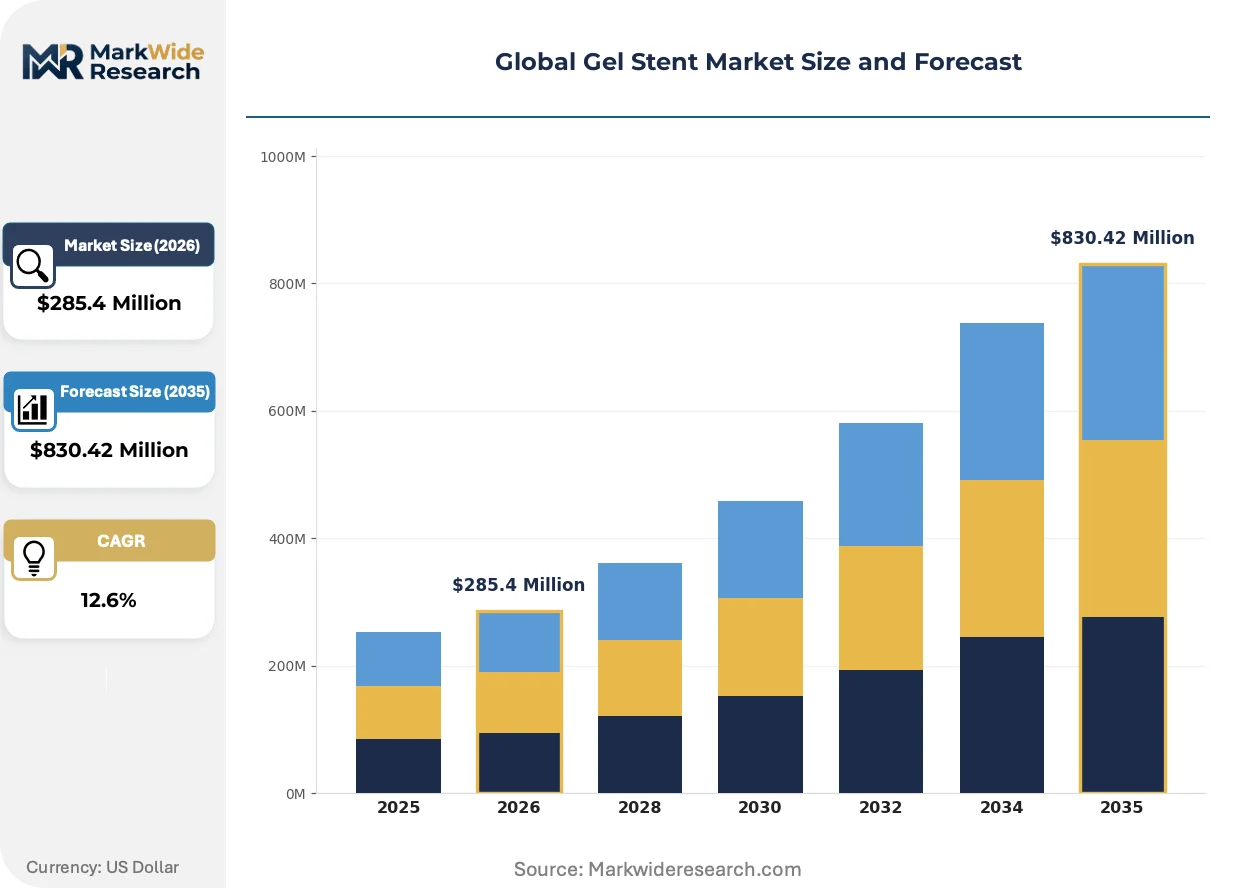
Market Dynamics
CE marking under the EU MDR is reorganizing competitive access for gel stent manufacturers, forcing portfolio rationalization and clinical evidence investments that favor established players with deep regulatory capabilities over emerging entrants.
Growth Catalysts
- Japan's PMDA pathway modernization:Streamlined biocompatibility validation protocols for hydrogel implants accelerate commercial entry timelines for compliant manufacturers targeting Japanese ophthalmology centers.
- Minimally invasive glaucoma surgery (MIGS) procedural expansion:Ophthalmic clinics across Germany and the United States are converting trabeculectomy volumes to gel stent-based drainage procedures, driven by shorter recovery protocols and reduced complication profiles.
- Drug-eluting hydrogel formulations:Localized antimetabolite delivery directly from the stent matrix suppresses fibrotic encapsulation, extending functional patency duration and reducing revision surgery rates.
Market Restraints
- Silicone raw material concentration:Medical-grade silicone supply chains cluster in Northeast Asian specialty chemical producers, creating input vulnerability for Western stent manufacturers during logistics disruptions.
- FDA premarket approval timeline friction:Novel intraocular devices face extended clinical trial requirements and iterative review cycles that compress early-mover advantage windows for breakthrough technologies.
- Trabecular micro-bypass shunt substitution:Alternative MIGS devices using iStent and Hydrus platforms compete for identical patient populations and reimbursement codes, limiting gel stent volume expansion in price-sensitive accounts.
Strategic Opportunities
- Brazil's ANVISA regulatory harmonization:Convergence toward FDA-recognized standards creates pathway efficiency for manufacturers holding US approvals, opening Latin America's largest ophthalmology market with reduced duplicate testing burden.
- Biodegradable resorbable stent platforms:Elimination of permanent foreign body and explantation risk aligns with surgeon preference evolution in academic medical centers, creating premium positioning for first movers.
- Teleophthalmology screening integration:Remote diagnostic workflows in rural United States markets expand glaucoma detection reach, funnelling previously undiagnosed patients into surgical intervention pipelines.
Industry Challenges
- Microsurgical technique standardization:Gel stent implantation demands precise anterior chamber angle navigation that exceeds conventional trabeculectomy training, requiring substantial proctor investment and hands-on laboratory curriculum development.
- EU MDR technical documentation burden:Enhanced clinical evidence requirements for Class III devices force retrospective data collection and post-market surveillance infrastructure that smaller manufacturers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gel Stent Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $830.42 Million |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrophilic Gel, Silicone Gel, Polyurethane Gel, Hydrogel, Biodegradable Gel Technology: Drug-Eluting, Microfluidic, Nanocoated, Shape Memory, Biocompatible Surface Application: Glaucoma Treatment, Cardiovascular Support, Urological Use, Neurovascular Intervention, Cosmetic Procedures End User: Ophthalmic Clinics, Cardiac Centers, Urology Hospitals, Neurology Institutes, Aesthetic Clinics |
| Companies Covered | AqueSys Inc, Allergan, Glaukos Corporation, Alcon Inc, Johnson & Johnson Vision, AbbVie Inc, Innfocus, Innovative Medical Devices, Ophthalmic Solutions Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gel Stent Market Shifts & Advancements
Active materials science and regulatory convergence are compressing product development cycles while fragmenting competitive positioning between permanent and resorbable platform philosophies.
Cross-linked polyethylene glycol-based hydrogels with tunable porosity gradients are bifurcating the product landscape. Academic medical centers in Germany and Japan are piloting these formulations for their swelling-controlled flow dynamics and reduced foreign body response. The technology is bifurcating procurement patterns, as hospitals with established MIGS programs separate premium resorbable contracts from standard permanent implant purchasing.
EU MDR Article 54 clinical evaluation consultation procedures are extending review timelines for novel intraocular devices. Manufacturers must now demonstrate equivalence to established predicate devices or conduct prospective trials, raising capital requirements for European market entry. Smaller technology developers are responding by prioritizing US FDA approval first, deferring CE marking investments until commercial traction justifies the documentation burden.
Surgeon training networks are consolidating purchasing influence in the United States and Japan. Large ophthalmology group practices and hospital systems are centralizing device selection through exclusive MIGS platform contracts, displacing individual surgeon preference as the primary decision driver. This concentration is most visible in metropolitan markets where vertically integrated eye care chains negotiate system-wide pricing for combination cataract-glaucoma workflows.
Global Gel Stent Market Segmentation
Gel stent procurement channels diverge sharply by clinical setting, with ophthalmic clinics driving volume through direct manufacturer contracts while cardiac and urology facilities rely on specialized distributors. Understanding these pathway distinctions enables targeted commercial resource allocation across the five core segmentation dimensions.
Product Type:
Channel distribution varies by material properties, with hydrophilic and hydrogel formulations flowing through high-volume ophthalmic distributors while silicone and biodegradable variants concentrate in academic medical center direct purchasing.
- Hydrogel:Cross-linked polymer matrices dominate current procurement volumes due to established biocompatibility profiles and tunable mechanical properties. United States ophthalmic clinics prioritize these formulations for MIGS procedures, though supply concentration in Northeast Asian specialty chemical producers creates input vulnerability.
- Biodegradable Gel:Resorbable platforms eliminate explantation risk and align with surgeon preference evolution in German and Japanese academic centers. Demand concentrates where permanent foreign body concerns drive premium positioning, though manufacturing complexity limits current channel penetration.
- Hydrophilic Gel:Water-absorbing formulations reduce foreign body response in anterior chamber applications.
- Silicone Gel:Medical-grade elastomers serve cardiovascular and urological drainage applications requiring sustained patency.
- Polyurethane Gel:Segmented block copolymers offer abrasion resistance in neurovascular intervention settings.
By volume, hydrogel leads procurement contracts. By expansion trajectory, biodegradable gel is climbing fastest.
Technology:
Cost tier stratification separates premium drug-eluting and nanocoated platforms from standard biocompatible surface offerings, with microfluidic and shape memory technologies occupying mid-tier positioning.
- Drug-Eluting:Localized antimetabolite delivery directly from the stent matrix suppresses fibrotic encapsulation and extends functional patency duration. Japan's PMDA pathway modernization accelerates commercial entry for compliant manufacturers targeting ophthalmology centers with these premium formulations.
- Nanocoated:Surface modification technologies reduce protein adhesion and thrombogenicity in cardiovascular applications. German cardiac centers pilot these platforms for their hemocompatibility advantages, though coating durability concerns constrain reimbursement negotiations.
- Microfluidic:Precision-engineered flow channels enable controlled aqueous humor drainage rates.
- Shape Memory:Temperature-responsive polymers facilitate minimally invasive deployment through micro-incisions.
- Biocompatible Surface:Standard surface treatments without active pharmaceutical components serve cost-sensitive accounts.
By installed base, biocompatible surface dominates. By revenue per unit, drug-eluting commands premium positioning.
Application:
Customer type fragmentation separates high-volume glaucoma treatment demand from specialized cardiovascular, urological, and neurovascular interventions requiring procedure-specific training infrastructure.
- Glaucoma Treatment:Minimally invasive drainage procedures convert trabeculectomy volumes across United States and German ophthalmic clinics. The FDA's premarket approval pathway shapes commercial timelines for novel intraocular devices in this largest addressable segment.
- Cardiovascular Support:Vascular patency maintenance applications concentrate in cardiac centers with established interventional cardiology programs. Japan's aging population drives procedural volumes for peripheral and coronary indications.
- Urological Use:Ureteral and prostatic stenting applications serve urology hospitals with dedicated endourology suites.
- Neurovascular Intervention:Cerebrospinal fluid shunting and aneurysm treatment applications demand specialized neurosurgical expertise.
- Cosmetic Procedures:Aesthetic tissue augmentation applications occupy niche positioning in premium aesthetic clinics.
By procedure volume, glaucoma treatment leads. By complexity premium, neurovascular intervention commands highest unit economics.
End User:
Geographic concentration patterns concentrate ophthalmic clinic demand in United States metropolitan markets and Japanese urban centers, while cardiac and neurology institutes cluster in German academic medical regions.
- Ophthalmic Clinics:Vertically integrated eye care chains in the United States negotiate system-wide pricing for combination cataract-glaucoma workflows. Surgeon training networks consolidate purchasing influence through exclusive MIGS platform contracts.
- Cardiac Centers:Interventional cardiology departments in Germany and Japan drive cardiovascular gel stent adoption through established structural heart programs.
- Urology Hospitals:Endourology-focused facilities in Brazil's ANVISA-harmonized regulatory environment expand Latin American access.
- Neurology Institutes:Academic medical centers in Japan pilot advanced formulations for cerebrospinal fluid applications.
- Aesthetic Clinics:Cosmetic-focused practices in United States metropolitan markets serve elective procedure demand.
By contract value concentration, ophthalmic clinics lead. By growth pace in emerging markets, urology hospitals are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in the United States, Germany, and Japan concentrate gel stent purchasing decisions through exclusive MIGS platform contracts. These three markets collectively shape reimbursement benchmarks and regulatory precedents that cascade into secondary ophthalmology markets.
United States
Ophthalmic clinic chains in metropolitan markets convert trabeculectomy volumes to gel stent procedures at accelerating rates. The FDA's premarket approval pathway for novel intraocular devices extends clinical trial timelines but establishes commercial credibility for compliant manufacturers. Vertically integrated eye care networks in California and Texas negotiate system-wide pricing for combination cataract-glaucoma workflows.
Germany
Academic medical centers in Bavaria and Baden-Württemberg pilot biodegradable resorbable stent platforms for their elimination of permanent foreign body risk. CE marking under the EU MDR forces retrospective data collection investments that favor established players with deep regulatory capabilities. Stuttgart and Munich clusters concentrate surgeon training infrastructure for anterior chamber angle navigation techniques.
Japan
Aging demographics in Tokyo and Osaka metropolitan areas drive procedural volumes for minimally invasive glaucoma interventions. The PMDA maintains distinct biocompatibility testing protocols that necessitate separate validation studies for hydrogel implant manufacturers. Kanto region ophthalmology centers prioritize drug-eluting formulations for their localized antimetabolite delivery advantages.
Brazil
ANVISA regulatory harmonization toward FDA-recognized standards reduces duplicate testing burden for manufacturers holding US approvals. São Paulo and Rio de Janeiro ophthalmology clinics expand adoption of MIGS procedures as reimbursement frameworks mature. Endourology-focused facilities in Minas Gerais simultaneously drive urological gel stent demand through established interventional suites.
United Kingdom
London and Southeast England hospital systems centralize device selection through exclusive platform contracts that displace individual surgeon preference. NICE technology appraisals determine which gel stent innovations achieve sustainable NHS reimbursement. Midlands and North England regions trail in procedural adoption due to slower commissioning cycle timelines for novel intraocular devices.
Global Gel Stent Market Competitive Landscape
Player mix skews toward diversified ophthalmic conglomerates with established surgeon training networks and direct distribution infrastructure. Market structure concentrates around three to five entities with regulatory approval breadth across FDA, CE marking, and PMDA jurisdictions. Strategic archetypes include integrated cataract-glaucoma workflow providers, standalone MIGS platform specialists, and diversified medical device conglomerates with ophthalmic divisions. Dominant competitive moves encompass exclusive MIGS platform contracting with hospital systems and backward integration into medical-grade silicone supply chains.
Within the integrated workflow tier, Glaukos Corporation and Alcon Inc exemplify contrasting scale approaches to market development. Glaukos represents the standalone MIGS specialist archetype with concentrated expertise in trabecular meshwork bypass platforms. Alcon anchors the diversified conglomerate position through extensive surgeon training networks spanning major eye care markets. Johnson & Johnson Vision occupies a hybrid position combining medical device scale with ophthalmic-specific portfolio depth. Among regulatory-capable manufacturers, Allergan and AbbVie Inc demonstrate how pharmaceutical heritage translates into drug-eluting device development priorities.
| Leading Market Players |
|---|
| AqueSys Inc |
| Allergan |
| Glaukos Corporation |
| Alcon Inc |
| Johnson & Johnson Vision |
| AbbVie Inc |
| Innfocus |
| Innovative Medical Devices |
| Ophthalmic Solutions Inc |
| Others |
Supply & Pricing Matrix
Medical-grade silicone polymerization capacity utilization above eighty percent in Northeast Asian specialty chemical producers creates asymmetric pricing power for hydrogel raw material suppliers, compressing margin buffers for Western stent manufacturers while elevating floor prices for drug-eluting formulations.
Pricing Analysis
Cost-plus contracts with medical-grade silicone indexation dominate procurement agreements between stent manufacturers and specialty chemical suppliers. Three-tier pricing structure across premium drug-eluting, standard hydrogel, and economy biocompatible surface tiers separates reimbursement-eligible formulations from cash-pay alternatives. Pricing pressure stems from trabecular micro-bypass shunt substitution in United States ophthalmic clinics, where iStent and Hydrus platforms compete for identical procedural codes. Academic medical centers exhibit lowest price sensitivity due to bundled payment structures, while independent ophthalmic clinics in price-sensitive accounts drive hardest negotiation.
Supply Chain Analysis
Inbound logistics costs from Northeast Asian ports through Los Angeles and Rotterdam gateways fluctuate with container availability and trans-Pacific lane congestion, adding unpredictability to medical-grade silicone delivery schedules. Raw material concentration in China, South Korea, and Japan for cross-linked polyethylene glycol precursors and silicone elastomers draws from single-source vulnerabilities for Western manufacturers. Distribution runs through high-volume ophthalmic distributors in the United States, direct hospital contracts in Germany, and specialized interventional cardiology channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gel stent market constitutes a high-growth disruption propelled by FDA premarket approval pathway maturation for novel intraocular devices, which simultaneously extends development timelines and elevates commercial credibility barriers for compliant manufacturers.
For Market Incumbents: Consolidate surgeon training network control through exclusive MIGS platform contracting with vertically integrated eye care chains, neutralizing substitution threat from trabecular micro-bypass shunts. Deepen backward integration into medical-grade silicone supply chains through captive production or long-term offtake agreements with Northeast Asian specialty chemical producers, insulating margin compression from raw material concentration.
For New Entrants and Emerging Players: Surgeon education infrastructure gaps in Brazil's ANVISA-harmonized regulatory environment present white-space entry points for manufacturers holding FDA approvals, leveraging reduced duplicate testing burden to accelerate commercial timelines. Target biodegradable resorbable stent platforms in German and Japanese academic medical centers, where permanent foreign body elimination aligns with preference evolution and incumbent coverage remains thin. Deploy teleophthalmology screening integration as go-to-market channel to funnel rural United States undiagnosed patients into surgical intervention pipelines.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among drug-eluting technology developers with established reimbursement codes and hospital system purchasing committee relationships, positioning these archetypes for durable cash flow quality across extended holding periods. Prioritize acquisition targets with regulatory approval breadth across FDA, CE marking, and PMDA jurisdictions, as this triad credentialing compresses commercial friction in priority ophthalmology markets. Monitor Japan's PMDA pathway modernization implementation as inflection signal for accelerated biocompatibility validation timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR Article 54 compliance opens European commercial access for Class III intraocular devices. |
| Hospital System Partnership | Exclusive MIGS platform contracts with vertically integrated chains consolidate purchasing influence. |
| Backward Integration into Silicone Supply | Captive medical-grade elastomer production insulates margin compression from Northeast Asian concentration. |
| Reimbursement Strategy Development | NICE technology appraisals and CMS coding determinations shape sustainable commercial scale. |
| Software Companion Development | Teleophthalmology screening integration expands glaucoma detection reach in rural United States markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with ophthalmic surgeons, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs leads at stent manufacturers. Secondary validation drew from FDA premarket approval filings, PMDA submission databases, EU MDR technical documentation, hospital procurement contract repositories, and CMS Medicare reimbursement schedules. Bottom-up procedure volume estimates triangulated against top-down market value reconstructions across hydrogel, biodegradable, and drug-eluting technology segments.
Across the analysis window, volume and value outputs reflect segmentation modeling by product type, technology tier, application indication, end-user facility category, and geographic regulatory cluster. CAGRs were derived from procedure volume trajectories, pricing trend extrapolation, and reimbursement pathway maturation curves. Forecast inputs incorporated aging demographic projections for United States, German, and Japanese ophthalmology markets, alongside MIGS procedural conversion rates from trabeculectomy volumes.
Forecasts assume regulatory continuity in FDA premarket approval, EU MDR CE marking, and Japan PMDA biocompatibility testing regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Minimally Invasive Neurosurgical Devices Market
Medical Devices
Global Mobile ECG Devices Market
Medical Devices
Drug Delivery Devices Market
Medical Devices
Transcatheter Mitral Valve Market
Medical Devices
Electroencephalogram (EEG) Caps Market
Medical Devices
Ventricular Restoration Systems Market
Medical Devices
Global Interspinous Spacers Market
Medical Devices
Drug and Gene Delivery Devices Market
Medical Devices
Americas Wearable Medical Device Market
Medical Devices
Global Transcranial Magnetic Stimulators Market
Medical Devices
North America Vagus Nerve Stimulation Market
Medical Devices
Transcranial Magnetic Stimulator for Depression Requisition Market
Medical Devices
Brachytherapy Market
Medical Devices
Europe Medical Devices Market
Medical Devices
Global Micro Injection Molding Medical Devices Market
Medical Devices
Superficial Radiation Therapy System Market