
 Cyprosin Market | 2026-2036
Cyprosin Market Size, Share, and Industry Trends Forecast 2026-2036
Cyprosin Market Outlook
Enzymatic extraction at ambient temperature is tilting manufacturing economics away from traditional solvent-intensive processes. Jupiter Pharmaceuticals Limited leverages captive fermentation capacity to secure raw material throughput. Fytozimus Biotech Inc anchors its position through specialized downstream purification protocols. Chr. Hansen Holding competes on biosafety certification depth across multiple pharmacopeias.
Cyprosin is a proteolytic enzyme complex derived from Cynara carduncus flower extracts, functioning at optimal activity between pH 4.5 and 6.0 with casein-specific cleavage patterns that enable milk coagulation without animal rennet contamination. Its primary commercial purpose centers on pharmaceutical-grade enzyme production for vegetarian drug formulations and specialized dairy processing where religious or dietary restrictions prohibit animal-derived rennets. Powder formulations lead volume throughput due to extended shelf stability and freight efficiency, while liquid concentrates command premium positioning in pharmaceutical applications where dosing precision outweighs logistics costs. Food Additives applications show the steepest trajectory as clean-label vegetarian certification expands across European and North American retail channels.
India's CDSCO mandates batch-level enzyme activity documentation for pharmaceutical-grade cyprosin, while the US FDA enforces dietary supplement GMP standards that extend to enzyme-based nutraceuticals. The EU EFSA novel food approval pathway creates entry friction for non-traditional plant enzyme sources. Stakeholders must monitor regulatory divergence between pharmaceutical and food-grade classification thresholds.
Market Dynamics
Enzymatic extraction at ambient temperature is collapsing the cost differential between solvent-based and biological manufacturing routes, forcing pharmaceutical formulators in India and Southeast Asia to reconfigure their capital deployment toward captive fermentation infrastructure.
Growth Catalysts
- CDSCO batch documentation mandates:India's pharmaceutical regulator now requires enzyme activity certification at the batch level, elevating demand for standardized cyprosin production.
- Vegetarian drug formulation protocols:Religious dietary restrictions across Hindu and Jain patient populations drive substitution of animal rennet in pharmaceutical-grade enzyme applications.
- Maharashtra biotech corridor expansion:State-level biotechnology incentives concentrate manufacturing capacity near Mumbai-Pune industrial zones.
Market Restraints
- Cynara carduncus supply volatility:Mediterranean climate dependency for cardoon flower harvests creates input cost instability.
- EFSA novel food approval friction:European regulatory pathways for non-traditional plant enzyme sources extend commercialization timelines.
- Fungal protease substitution:Aspergillus-derived recombinant enzymes compete on cost in non-pharmaceutical dairy applications.
Strategic Opportunities
- US FDA dietary supplement GMP extension:Enzyme-based nutraceutical classification creates parallel revenue streams beyond pharmaceutical grade.
- Clean-label retail certification:European and North American retail channels expand vegetarian enzyme labeling requirements.
- Downstream purification protocol convergence:Membrane filtration and chromatography integration enables single-facility multi-grade output.
Industry Challenges
- Fermentation scale-up expertise scarcity:Qualified bioprocess engineers capable of pH 4.5-6.0 optimization remain concentrated in legacy antibiotic production hubs.
- Dual-grade facility certification complexity:Simultaneous pharmaceutical and food-grade production requires segregated downstream processing lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyprosin Market |
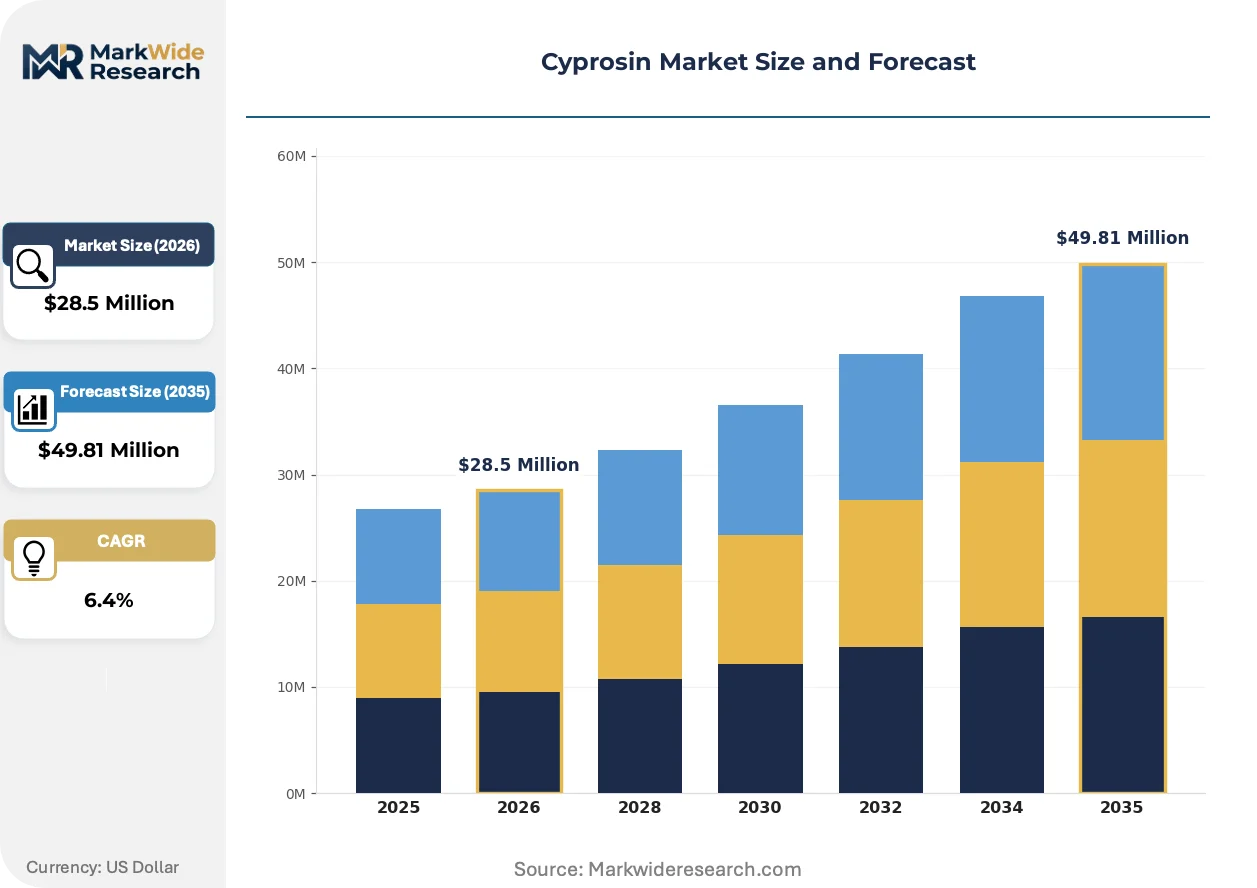
| Market Size in 2026 | $28.5 Million |
| Market Size in 2035 | $49.81 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granules, Concentrate Application: Agriculture, Pharmaceuticals, Veterinary, Food Additives End User: Manufacturers, Distributors, Research Institutions, Farmers Distribution Channel: Online Sales, Retail, Wholesalers, Direct Sales |
| Companies Covered | Jupiter Pharmaceuticals Limited, Fytozimus Biotech Inc, Zenon Healthcare Limited, Caplet India Pvt, Intas Pharmaceuticals Ltd, Torque Pharmaceuticals Pvt, Radico Remedies, Geno Pharmaceuticals Ltd, Chr. Hansen Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyprosin Market Strategic Shifts
Bioprocess intensification and regulatory harmonization pressures are compressing the traditional boundary between food-grade and pharmaceutical-grade enzyme production, forcing facility designs that accommodate dual-certification pathways.
Continuous perfusion fermentation with real-time pH monitoring is collapsing the batch-to-batch variability that has historically plagued plant-derived enzyme production. Gujarat's bulk drug manufacturers are adopting this technology to meet CDSCO documentation requirements. The structural consequence is collapsing quality control overhead as in-process analytics replace end-point testing.
REACH registration requirements for novel enzyme preparations are tightening substance characterization obligations across European manufacturing sites. Industrial consequence includes mandatory proteomic fingerprinting for cyprosin batches entering EU pharmaceutical supply chains. Specialty dairy processors in France and Italy face the steepest compliance burden as traditional extraction methods lack the traceability documentation now required.
Buyer concentration among contract manufacturing organizations is compressing supplier qualification timelines. Large pharmaceutical formulators in India now demand 18-month stability data before vendor onboarding, displacing the previous 6-month pilot-phase norm. Maharashtra's CDMO clusters exhibit the most aggressive procurement compression as they compete for multinational outsourcing contracts.
Cyprosin Market Segmentation
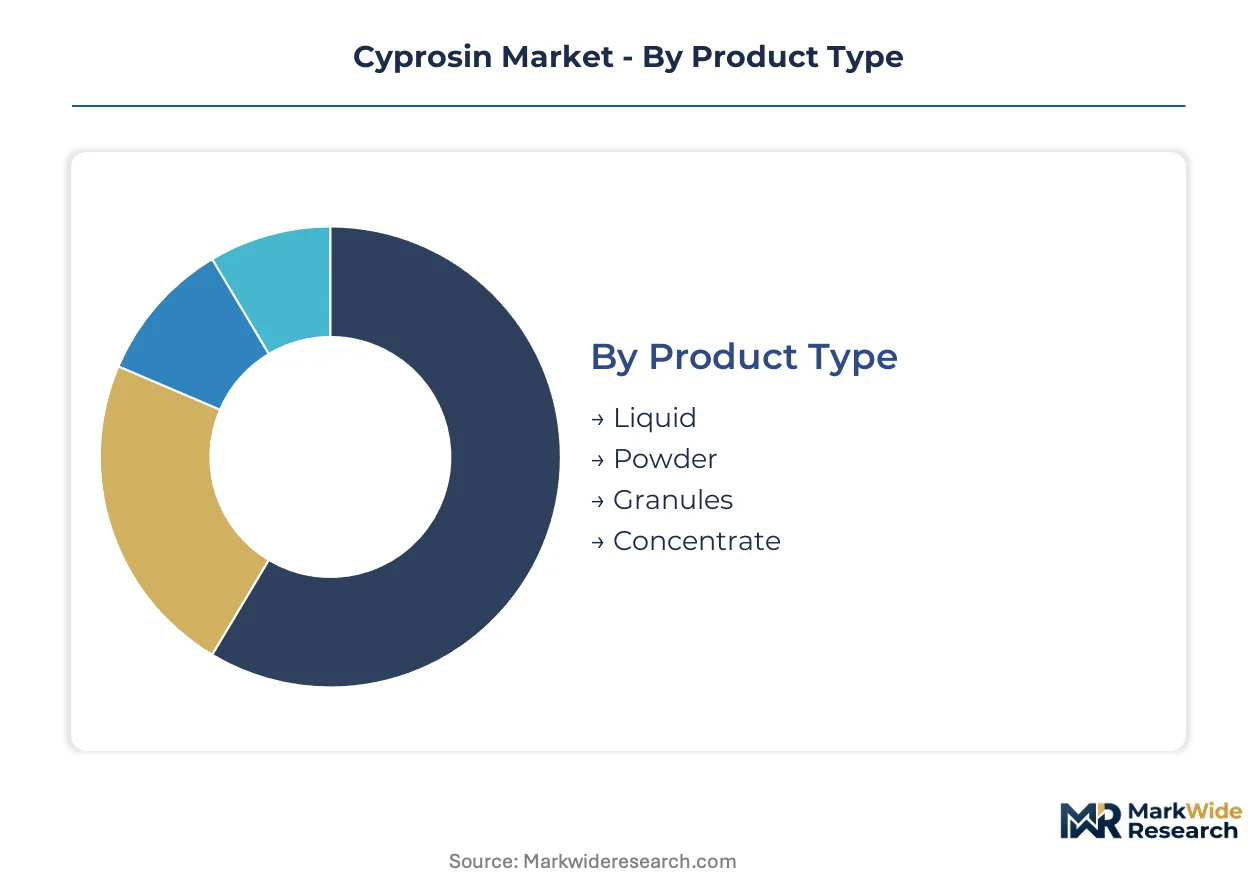
Enzyme form factor and regulatory classification tier determine manufacturing facility investment, freight economics, and customer procurement cycles. Pharmaceutical-grade purity thresholds split the addressable market from commodity dairy applications, while distribution channel selection governs margin capture and technical service depth.
Product Type:
Cost tier stratification across physical forms governs capital allocation between spray-drying infrastructure and aseptic liquid filling lines.
- Powder:Spray-dried enzyme preparations with moisture content below 5% achieve 24-month stability at ambient storage conditions. Maharashtra's bulk drug manufacturers prioritize powder procurement for interstate distribution to Gujarat's dairy processing zones, where extended shelf life offsets higher unit dosing costs.
- Liquid:Aqueous concentrates maintain proteolytic activity within pH-buffered matrices requiring cold chain logistics. Pharmaceutical formulators in Mumbai-Pune corridor specify liquid formats for parenteral enzyme applications where precise activity titration outweighs per-kilogram freight premiums.
- Granules:Fluid-bed agglomerated particles reduce dust exposure during handling. Feed enzyme applications in Southeast Asian poultry operations specify granule formats for mixer uniformity.
- Concentrate:High-activity extracts for downstream dilution by formulators. Captive use by integrated manufacturers limits third-party market penetration.
Powder holds installed capacity. Liquid is rotating up the share rankings.
Application:
Application maturity determines whether CDSCO pharmaceutical documentation or FSSAI food additive registration governs market access.
- Food Additives:Clean-label vegetarian certification requirements across European retail channels specify cardoon-derived coagulants for specialty cheese production. Italian PDO producers and French artisan dairies command premium positioning through EFSA-traceable enzyme sourcing.
- Pharmaceuticals:Batch-level enzyme activity documentation mandated by India's CDSCO restricts supply base to fermentation-capable manufacturers. Vegetarian drug formulation protocols for Hindu and Jain patient populations drive substitution away from animal rennet in digestive enzyme preparations.
- Agriculture:Silage inoculation and crop residue processing applications compete with fungal cellulase complexes on cost.
- Veterinary:Ruminant feed enzyme supplementation remains experimental with limited commercial scale.
Food Additives is climbing the fastest. Pharmaceuticals holds formulation complexity premiums.
End User:
Customer type dictates technical service intensity and contract structure, from spot procurement to multi-year supply agreements.
- Manufacturers:Integrated pharmaceutical and dairy processors with captive formulation capacity. CDSCO compliance documentation requirements favor long-term vendor relationships over spot market sourcing.
- Distributors:Regional stockists serving fragmented dairy cooperative networks. Maharashtra and Gujarat distribution hubs consolidate procurement for smaller cheese producers lacking direct import licenses.
- Research Institutions:Academic and government laboratories evaluating novel enzyme applications. Purchase volumes remain below commercial thresholds.
- Farmers:Direct procurement limited to organized cooperative structures with collective bargaining power.
Manufacturers dominate volume throughput. Distributors are gaining intermediary leverage.
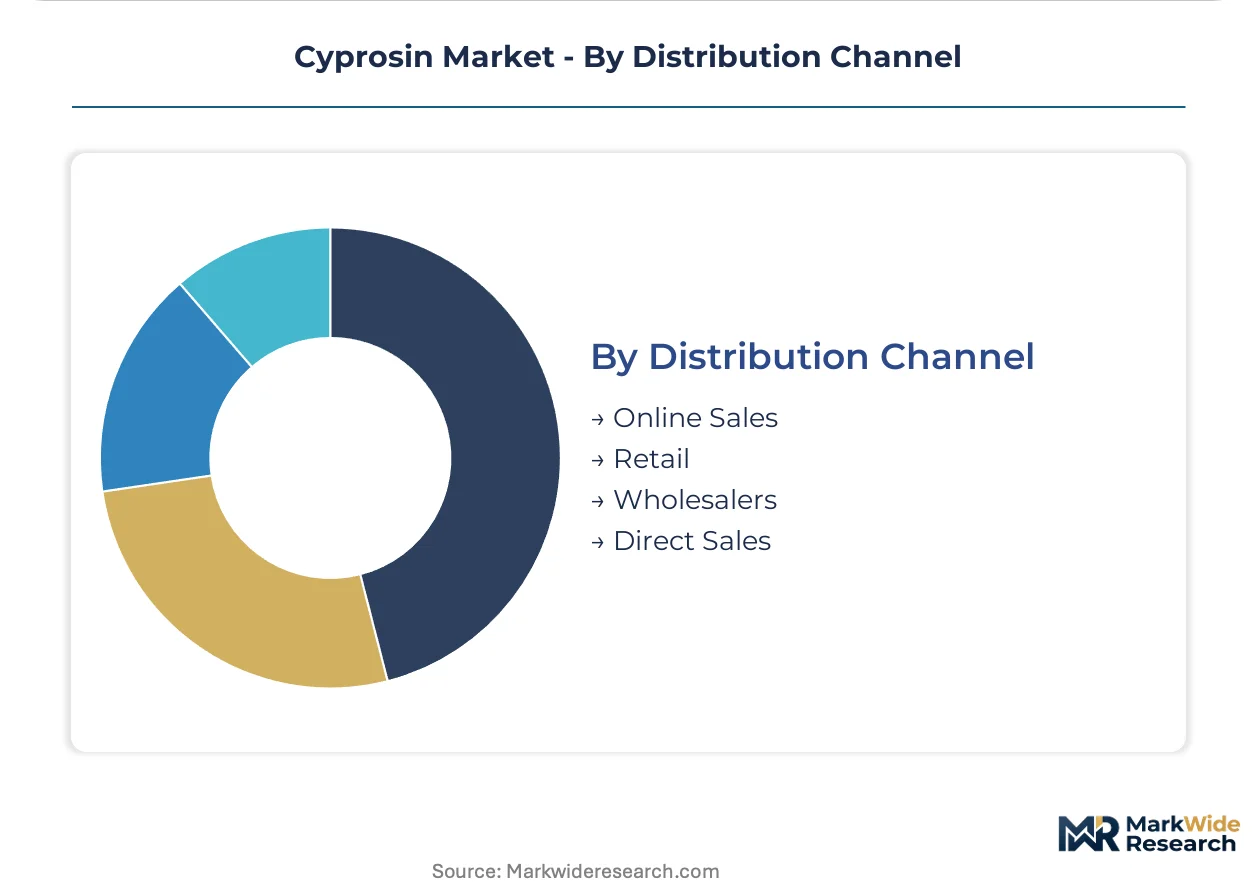
Distribution Channel:
Channel selection determines documentation custody and cold chain integrity through final delivery.
- Direct Sales:Manufacturer-to-formulator relationships preserve batch traceability for pharmaceutical-grade enzyme supply. CDSCO audit requirements favor direct channels where certificate of analysis custody remains unbroken.
- Wholesalers:Regional inventory consolidation for food-grade applications with less stringent documentation requirements. Gujarat's bulk drug wholesale clusters serve secondary dairy processors.
- Online Sales:Emerging channel for research-grade quantities and specialty food enzyme samples. Regulatory ambiguity surrounds pharmaceutical-grade enzyme e-commerce.
- Retail:Limited to consumer-facing enzyme supplements under FSSAI dietary product classification.
Direct Sales holds pharmaceutical compliance advantages. Wholesalers is expanding food-grade reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical formulators in India and Southeast Asia anchor procurement volumes, while European specialty dairy processors and North American nutraceutical manufacturers concentrate demand for high-purity grades.
India
Maharashtra's biotech corridor and Gujarat's bulk drug zones drive fermentation capacity expansion for CDSCO-compliant cyprosin batches. India's pharmaceutical regulator mandates batch-level enzyme activity documentation, elevating demand for standardized production. Mumbai-Pune industrial clusters concentrate manufacturing as formulators reconfigure toward captive infrastructure.
United States
Nutraceutical manufacturers in New Jersey and California seek FDA dietary supplement GMP-compliant enzyme sources for vegetarian capsule formulations. The US FDA enforces quality standards extending to enzyme-based nutraceuticals, creating parallel revenue streams. Direct sales channels dominate pharmaceutical-grade supply to preserve batch traceability.
Italy
PDO cheese producers in Emilia-Romagna and Lombardy specify cardoon-derived coagulants for traditional vegetarian certification. EFSA novel food approval pathways create entry friction for non-traditional plant enzyme sources. Artisan dairies in Parma and Cremona face compliance burden as traceability documentation requirements tighten.
France
Specialty dairy processors in Auvergne-Rhône-Alpes command premium positioning through EFSA-traceable enzyme sourcing for clean-label retail channels. REACH registration requirements mandate proteomic fingerprinting for cyprosin batches entering pharmaceutical supply chains. Lyon-based formulators adopt membrane filtration integration for multi-grade output.
Germany
Industrial enzyme distributors in North Rhine-Westphalia consolidate procurement for European dairy cooperative networks. ECHA substance characterization obligations tighten across manufacturing sites handling novel enzyme preparations. Düsseldorf-Cologne logistics hubs manage regional inventory for food-grade applications with reduced documentation requirements.
Cyprosin Market Competitive Environment
Channel-controlling players compete with product-specialist players across a fragmented vendor base where fermentation scale-up expertise remains scarce. The market structure separates integrated pharmaceutical manufacturers from dedicated enzyme suppliers and regional distributors. Three archetypes dominate: captive fermentation operators, downstream purification specialists, and biosafety certification leaders. Capacity expansion and downstream protocol convergence represent the primary competitive vectors as stakeholders seek dual-grade facility qualification.
Within the captive fermentation tier, Jupiter Pharmaceuticals Limited and Intas Pharmaceuticals Ltd occupy positions exemplifying integrated pharmaceutical manufacturing. Fytozimus Biotech Inc anchors the specialist purification segment. These entities represent contrasting strategic postures—vertically integrated drug formulators versus focused enzyme technology developers—within a competitive set where CDSCO compliance documentation and EFSA traceability standards determine vendor selection criteria.
| Leading Market Players |
|---|
| Jupiter Pharmaceuticals Limited |
| Fytozimus Biotech Inc |
| Zenon Healthcare Limited |
| Caplet India Pvt |
| Intas Pharmaceuticals Ltd |
| Torque Pharmaceuticals Pvt |
| Radico Remedies |
| Geno Pharmaceuticals Ltd |
| Chr. Hansen Holding |
| Others |
Value Chain & Pricing Dynamics
Maharashtra's biotech corridor concentrates pharmaceutical-grade cyprosin fermentation capacity, anchoring margin capture downstream among CDSCO-compliant formulators who command premium positioning over commodity dairy enzyme suppliers. This geographic concentration of captive production infrastructure creates asymmetric pricing power where batch-level documentation capabilities separate certified pharmaceutical supply from food-grade alternatives.
Pricing Analysis
Cost-plus contracts with cardoon flower harvest indexation dominate long-term pharmaceutical supply agreements, insulating manufacturers from Mediterranean climate volatility. Price differentiation rests on CDSCO certification tier and EFSA traceability documentation, with pharmaceutical-grade batches commanding substantial premiums over food-additive alternatives. Pricing pressure stems from fungal protease substitution in non-pharmaceutical dairy applications, compressing margins at the standard tier. Small-scale cheese cooperatives in Gujarat exhibit highest price sensitivity, while Mumbai-Pune pharmaceutical formulators prioritize documentation integrity over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard among Maharashtra fermentation operators seeking to lock in cardoon flower offtake commitments from Mediterranean agricultural cooperatives. Raw material sourcing draws from Spain, Portugal, and Morocco, with downstream processing concentrated in India's biotech corridor and European specialty dairy zones. Single-source vulnerability runs through Cynara carduncus cultivar dependency, as alternative plant protease sources require lengthy EFSA novel food approval. Distribution runs through direct manufacturer-to-formulator channels for pharmaceutical grade, with regional wholesalers consolidating food-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cyprosin demand tracks pharmaceutical capital expenditure cycles, with CDSCO compliance investment waves driving procurement spikes as Indian formulators upgrade captive fermentation infrastructure.
For Market Incumbents: Insulate pharmaceutical-grade positioning by deepening backward integration into cardoon cultivar development partnerships and securing dual-grade facility certification ahead of regulatory harmonization pressures. Fungal protease substitution in commodity dairy applications threatens standard-tier margins, making CDSCO documentation depth the priority defensive lever. For New Entrants and Emerging Players: Build out downstream purification protocol specialization rather than competing on fermentation scale, targeting the contract manufacturing white space among Maharashtra CDMO clusters seeking qualified enzyme suppliers. The most penetrable entry point lies in EFSA-traceable food-grade supply to European artisan dairies, with membrane filtration integration as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward downstream purification specialists with established multi-pharmacopeia biosafety certification, as fermentation scale-up expertise scarcity creates durable competitive moats. Long-term viability over a five-to-ten-year window favors entities with demonstrated CDSCO audit compliance and EFSA novel food pathway experience. The signal to watch is regulatory divergence between pharmaceutical and food-grade classification thresholds, which would accelerate consolidation among dual-capability operators.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Dual-Grade Facility Certification | Enables single-site output of pharmaceutical and food-grade cyprosin, collapsing quality control overhead. |
| Backward Integration into Cardoon Cultivation | Secures Cynara carduncus supply against Mediterranean climate volatility and harvest price spikes. |
| Membrane Filtration Protocol Convergence | Integrates chromatography and filtration for multi-grade output from shared downstream infrastructure. |
| EFSA Novel Food Approval Pathway Investment | Unlocks European specialty dairy market access for non-traditional plant enzyme sources. |
| Continuous Perfusion Fermentation Adoption | Collapses batch-to-batch variability through real-time pH monitoring in pH 4.5-6.0 optimization. |
Study Parameters
Desk research of CDSCO regulatory filings, EFSA novel food approval databases, and Indian pharmaceutical customs records preceded structured interviews with fermentation plant managers, CDSCO regulatory affairs leads, pharmaceutical procurement directors, and specialty dairy technical buyers. Primary fieldwork combined with secondary validation against US FDA dietary supplement GMP guidance and REACH substance characterization requirements. Bottom-up capacity modeling and top-down demand triangulation from end-use application forecasts were cross-referenced for convergence.
Assumptions held fixed include current CDSCO batch documentation mandates, EFSA traceability requirements, and existing Cynara carduncus cultivation geography; variables tested included regulatory harmonization scenarios and fungal protease substitution rates across the analysis window. Segmentation modeling incorporated enzyme form factor, application tier, end-user type, and distribution channel, with CAGRs derived from intensity-of-use projections by pharmaceutical formulation and specialty dairy processing. Forecast inputs included Maharashtra biotech corridor capacity expansion timelines and European clean-label certification adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by integrated pharmaceutical manufacturers or sudden EFSA regulatory relaxation would shift outcomes. Macroeconomic deviation in pharmaceutical capital expenditure, regulatory reclassification of enzyme grades, or breakthrough recombinant enzyme technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
United Kingdom Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Global Dexamethasone Market
Pharmaceutical Ingredients
Kitasamycin Market
Pharmaceutical Ingredients
France Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Immunosuppressants Market
Pharmaceutical Ingredients
Acetaminophen API Market
Pharmaceutical Ingredients
Oral Doxycycline Hyclate Market
Pharmaceutical Ingredients
Encapsulated Salicylic Acid Market
Pharmaceutical Ingredients
Calcium Gluconate Market
Pharmaceutical Ingredients
Lidocaine Hydrochloride Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients CDMO Market
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market
Pharmaceutical Ingredients
Epcam Antagonists Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
Global Glycine Supplement Market
Pharmaceutical Ingredients
Silver Sulfadiazine Market